

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
DX Strategy and Consulting Market: Why the 12.5% CAGR Through 2032 Reshapes Enterprise Spending

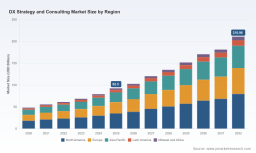
Navigating the DX Strategy and Consulting Market: Strategic Trends and Commercial Opportunities Through 2032
The Digital Transformation (DX) strategy and consulting market has matured beyond the early adoption hype cycle into a structural growth phase. Over the past five years, the sector has expanded from a niche advisory service into a core operational imperative for enterprises worldwide. Current market valuations place the overall industry at approximately $92.5 billion as of 2025, with a projected compound annual growth rate of 12.5% extending through 2032. This trajectory points to a market that will nearly double in size over the forecast period, reaching levels that reflect not only increased spending but also a fundamental shift in how organizations approach technology integration, operational redesign, and workforce transformation.
Worldwide Digital Business Transformation Market
Behind these headline figures lies a more complex reality. The market is no longer driven solely by technology adoption for its own sake. Enterprises are grappling with a series of interconnected challenges that define the current inflection point. First, the gap between investment and outcomes has widened. A significant majority of operations leaders report that technology investments in digital transformation have not fully delivered expected results, signaling a breakdown in execution rather than a lack of funding. This execution shortfall is compounded by fragmented operating models, where strategy, implementation, and change management often operate in silos. Second, the talent landscape has become increasingly constrained. Organizations face persistent shortages in digital skills and AI expertise, driving premium compensation costs and making it difficult to build digital-ready workforces internally. Third, regulatory and policy volatility has introduced new layers of complexity. Data privacy requirements, evolving compliance standards, and shifting trade regulations are forcing companies to rethink DX roadmaps that were designed under more stable conditions.
These challenges are not isolated friction points. They represent structural shifts that are reshaping how value is created in the DX consulting space. The market is moving away from generic transformation playbooks toward more targeted, outcome-driven engagements that account for organizational readiness, regulatory constraints, and measurable performance indicators. Enterprises that recognize this shift early are repositioning their consulting budgets accordingly, while those that continue to treat DX as a technology procurement exercise risk compounding inefficiencies.
Key Drivers Shaping the Market Trajectory
Several interconnected forces are accelerating demand for DX strategy and consulting services. Understanding these drivers is essential for executives and investors evaluating where the market is heading and which segments will capture disproportionate value.
Technology Innovation and the AI Inflection Point
The rapid maturation of artificial intelligence, particularly generative and agent-based systems, has altered the baseline expectations for digital transformation. AI is no longer a standalone initiative; it is becoming embedded in operating models, decision workflows, and customer engagement layers. This shift has created a new category of consulting demand focused on AI integration, data architecture, and organizational rewiring. Enterprises are increasingly seeking partners who can translate AI capabilities into measurable business outcomes rather than experimental pilots. The pressure to move from proof-of-concept to production-scale deployment is driving firms to engage strategic advisors who can align technology roadmaps with operational realities, governance frameworks, and change management requirements.
Worldwide Analytical and Technical Consulting Service Market
At the same time, cloud modernization and hybrid infrastructure strategies continue to serve as foundational enablers. Organizations are restructuring legacy systems to support more agile, data-driven operations, and this process requires coordinated strategy across technology, process design, and workforce capabilities. The convergence of AI and cloud transformation is creating integrated consulting engagements that span strategy, implementation, and ongoing managed services, blurring the lines between traditional advisory work and long-term delivery partnerships.
Regulatory and Compliance Pressures
Regulatory complexity is emerging as a significant catalyst for DX consulting demand. Data privacy frameworks, evolving compliance requirements, and cross-border regulatory standards are increasing the cost and risk of transformation initiatives. Organizations operating in multiple jurisdictions must navigate overlapping legal standards while modernizing their digital infrastructure, a task that requires specialized advisory support. Regulatory and policy volatility is already impacting a majority of operations leaders, particularly in areas related to resilience and trade compliance, prompting adjustments to DX strategies that were designed under more predictable conditions.
This dynamic is pushing consulting engagements toward more compliance-aware transformation models. Firms that can integrate regulatory navigation, data governance, and risk management into their DX strategy offerings are gaining traction with enterprises that view compliance not as a constraint but as a design parameter for transformation. The demand for specialized consulting to manage these complexities is growing as regulatory environments become more fragmented and enforcement more rigorous.
Workforce Transformation and Talent Economics
Demographic shifts and AI adoption are reshaping workforce needs at a pace that many organizations are struggling to match. The need for upskilling, new talent strategies, and digital-ready organizational designs is becoming a central component of DX strategy. Labor cost pressures are intensifying as demand for digital skills and AI expertise outpaces supply, and companies are increasingly turning to external partners to help design workforce transformation plans, training programs, and operating models that can absorb new technologies effectively.
This driver is particularly relevant for mid-sized enterprises and regional players that lack the internal capacity to build comprehensive digital talent pipelines. Consulting engagements are expanding beyond technology strategy to include human capital integration, change management, and capability-building frameworks. The organizations that succeed in this environment are those that treat workforce transformation as a core pillar of DX rather than a secondary implementation concern.
Demand-Side Shifts in Enterprise Behavior
Enterprise buyers are becoming more sophisticated in how they evaluate and procure DX consulting services. The earlier pattern of large, undifferentiated transformation programs is giving way to more modular, outcome-focused engagements. Companies are prioritizing measurable business outcomes, shorter time-to-value, and clearer accountability structures. This shift is reflected in the growing emphasis on performance-driven digital transformations, where strategy consulting is tied closely to execution metrics, operating model redesign, and continuous improvement frameworks.
At the same time, private equity and growth-focused investors are driving demand for DX strategy services that can accelerate value creation in portfolio companies. The focus on results, operational efficiency, and scalable growth models is pushing consulting firms to develop frameworks that can be deployed rapidly across multiple entities while maintaining consistency in execution quality. This investor-driven demand is adding a new dimension to the market, particularly in sectors where digital maturity varies widely across portfolio assets.
Competitive Landscape and Strategic Positioning
The DX strategy and consulting market is characterized by a mix of global integrators, strategy-focused consultancies, and specialized technology implementation firms. Market concentration remains moderate, with the top players holding a combined share that leaves substantial room for regional specialists, niche providers, and new entrants. This fragmentation is both a challenge and an opportunity, as enterprises increasingly seek partners with specific industry expertise, regional capabilities, or differentiated delivery models.
Strategic Positioning of Leading Players
Several firms have established distinct positioning within the market, reflecting different approaches to DX strategy and delivery:
- Accenture has built a comprehensive end-to-end model that spans DX strategy, technology transformation, AI, cloud, and digital operating model design. Its strength lies in scale, industry coverage, and the ability to integrate strategy with large-scale implementation. Recent partnerships, such as its selection as a business and technology consulting partner for major global sports organizations, illustrate its focus on multi-year digital transformation engagements that combine AI, data insights, and infrastructure upgrades.
- Deloitte emphasizes comprehensive DX strategy consulting with strong integration of human capital, technology implementation, and measurable business outcomes. Its approach reflects an understanding that transformation success depends as much on organizational readiness and people integration as on technology selection.
- McKinsey & Company positions itself in the high-end strategy segment, with emphasis on AI integration, organizational rewiring, and performance-driven transformations. Its model targets enterprises seeking strategic clarity and executive alignment before scaling execution.
- Boston Consulting Group (BCG) blends technology strategy with human capabilities, innovation frameworks, and industry-specific roadmaps. Its differentiation centers on aligning digital transformation with broader business strategy and innovation agendas.
- Capgemini focuses on DX consulting across cloud transformation, AI, cybersecurity, and intelligent industry solutions. Its positioning appeals to enterprises looking for technology-heavy transformation with strong implementation depth.
- IBM Consulting leverages its background in hybrid cloud, AI, and enterprise systems modernization to offer DX strategy and implementation services. Its value proposition is strongest for organizations modernizing complex legacy environments.
- PwC delivers DX strategy with emphasis on operations, AI-driven performance, and regulatory compliance. Its approach integrates transformation with risk management and operational execution.
- ABeam Consulting has strengthened its technology consulting delivery capabilities in India and expanded support for the establishment, operation, and advancement of Global Capability Centers (GCCs). Recent recognition, including regional SAP Partner Awards, highlights its focus on execution frameworks, SAP integration, and Asia-Pacific market expertise. The firm has also highlighted the persistent challenge of turning AI investments into measurable business value, reflecting a broader industry concern.
- Bain & Company provides strategy-led digital transformation consulting focused on results, private equity, and growth acceleration. Its positioning is particularly relevant for investors and enterprises seeking outcome-driven engagements with clear value creation metrics.
- Cognizant specializes in digital experience, application modernization, and cloud-enabled DX strategy services. Its strength lies in bridging digital front-end experiences with backend modernization.
- Infosys Consulting delivers AI-first cloud and digital transformation strategy and implementation services, positioning around integrated technology and strategy delivery.
- Tata Consultancy Services (TCS) provides comprehensive DX strategy, consulting, and large-scale technology transformation services globally, with scale and breadth across industries and regions.
Market Evolution and Structural Shifts
The competitive landscape is evolving along several dimensions. Integration is occurring as large firms expand their capabilities across strategy, implementation, and managed services to capture more of the transformation value chain. At the same time, specialization is increasing as enterprises seek partners with deep industry expertise, regional delivery capabilities, or focused technology competencies. The growth of Global Capability Centers is reshaping delivery models, with firms like ABeam expanding support for GCC establishment and operation, reflecting a broader trend toward distributed talent and cost-optimized delivery structures.
New entrants and regional players are gaining traction by offering niche expertise, faster engagement models, or stronger local market knowledge. The market is not consolidating into a single dominant model; rather, it is differentiating into layers of strategy advisors, implementation partners, managed services providers, and capability builders. Enterprises are increasingly combining multiple partners to address different aspects of transformation, which is pushing consulting firms to clarify their value propositions and avoid overlap.
Future Trends and Commercial Opportunities (2026–2032)
Looking ahead, several trends are likely to define the next phase of growth in the DX strategy and consulting market. These trends carry direct implications for commercial strategy, partnership models, and investment allocation.
From Strategy to Outcome Accountability
The gap between DX investment and realized outcomes will drive demand for more accountable consulting models. Enterprises are increasingly expecting strategy engagements to include clear execution pathways, performance metrics, and governance structures. Consulting firms that can bridge strategy and measurable results will capture greater share of wallet, while those that remain confined to advisory-only models may face pricing pressure and reduced differentiation. This trend creates opportunities for firms that integrate strategy, implementation oversight, and change management into cohesive delivery frameworks.
AI-Embedded Transformation as a Standard Engagement Layer
AI integration will become a baseline component of DX strategy rather than a separate workstream. Consulting engagements will increasingly address data readiness, AI governance, workflow redesign, and workforce adaptation as interconnected elements of transformation. Firms that can offer structured approaches to AI adoption, including risk management, compliance alignment, and value measurement, will be better positioned to serve enterprises navigating the transition from pilot activity to scaled deployment. The commercial opportunity lies in helping organizations convert AI investment into operational impact, a challenge that remains broadly unmet across industries.
Regional Capability Centers and Distributed Delivery Models
The expansion of Global Capability Centers and distributed delivery models is reshaping how DX services are structured and priced. Organizations are seeking partners who can support the establishment, operation, and advancement of capability centers that combine cost efficiency with local market knowledge and technology expertise. This trend is creating opportunities for consulting firms with strong regional footprints, talent development capabilities, and experience in setting up sustainable delivery structures. The firms that can help clients build long-term internal capacity, rather than relying solely on external delivery, will benefit from deeper relationships and recurring engagement potential.
Risk and Uncertainty Factors
Several variables could shape the pace and direction of market growth. Regulatory fragmentation may increase compliance costs and slow certain transformation initiatives, particularly in sectors with heavy data and privacy requirements. Talent shortages could constrain execution capacity, forcing firms to invest more heavily in training, automation, and delivery innovation. Economic volatility may lead some enterprises to delay large-scale transformation programs, shifting demand toward smaller, faster engagements with clearer near-term returns. Finally, the risk of AI investment failing to produce measurable value remains a persistent concern, and organizations that cannot demonstrate tangible outcomes may reduce spending or reallocate budgets to alternative priorities.
PW Consulting Information & Electronics Research Center
Strategic Implications for Decision-Makers
The DX strategy and consulting market is entering a phase where differentiation depends on execution clarity, outcome accountability, and the ability to navigate regulatory and workforce complexities. Decision-makers across different roles should consider the following priorities:
- For enterprises and manufacturers : Treat DX strategy as an operating model redesign effort rather than a technology procurement exercise. Prioritize engagements that link AI, cloud, and process transformation to measurable performance indicators, and ensure that change management and workforce upskilling are embedded from the outset. Evaluate partners based on their ability to connect strategy to execution accountability, not just advisory breadth.
- For investors and private equity stakeholders : Focus on DX consulting providers and portfolio companies that demonstrate clear value creation frameworks, scalable execution models, and alignment between strategy and operational outcomes. The growing emphasis on results-driven transformation and GCC-enabled delivery models offers opportunities to identify assets with stronger long-term transformation capacity.
- For procurement and sourcing leaders : Move beyond price-based selection toward capability-based evaluation. Assess consulting partners on their proficiency in regulatory navigation, AI integration, workforce transformation, and regional delivery infrastructure. Structured sourcing that accounts for compliance, talent availability, and execution track record will reduce the risk of transformation underperformance.
The dynamics shaping this market are evolving quickly, and the window for strategic positioning is narrowing. Enterprises and investors that deepen their understanding of segment-level demand, regional capability shifts, and emerging engagement models will be better equipped to allocate resources, select partners, and capture value as the market expands. For those seeking a more detailed view of segmentation patterns, regional breakdowns, and customized strategic guidance, the full research report provides a comprehensive foundation for planning and execution decisions.
For detailed analysis of this topic, please visit the official page: DX Strategy and Consulting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com