

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Integrated Workforce Mobility Market: Why the 10.25% CAGR Reshapes Global Strategy

The Integrated Workforce Mobility Market: Strategic Trends and Commercial Opportunities in a Hyperconnected Era
The integrated workforce mobility market has evolved from a niche compliance function into a central pillar of global talent strategy. Valued at 14.5 billion USD in 2025, the market has expanded consistently over the past five years, reflecting a fundamental shift in how organizations deploy, manage, and retain international talent. Looking ahead to 2032, the trajectory points toward sustained expansion, with a compound annual growth rate of 10.25 percent positioning the sector well above many legacy enterprise software categories. This growth is not merely a function of rising cross-border assignments; it signals a deeper restructuring of work itself, where mobility platforms, compliance infrastructure, and digital work environments converge to support distributed, hybrid, and remotely hosted teams.
PW Consulting Information & Electronics Research Center
Yet the market operates at a structural inflection point. Organizations are increasingly caught between the operational imperative to move talent quickly and the regulatory reality of tightening border controls, data privacy mandates, and social security scrutiny. At the same time, the technology stack supporting workforce mobility is fragmenting across device management, application governance, content security, and identity controls, forcing enterprises to reconcile point solutions with integrated platforms. A third tension lies in talent economics: companies must balance cost discipline with the need to offer seamless relocation, cultural integration, and digital onboarding experiences that actually retain high-value assignees. These challenges do not signal market weakness; rather, they define where value will concentrate over the next cycle.
Market Definition and Structural Realities
The integrated workforce mobility market encompasses the technologies, advisory services, and managed programs that enable organizations to deploy employees across borders, manage remote workforces, and comply with immigration, tax, and data security requirements. Historically anchored by global assignment administration, the category has broadened to include digital platforms that orchestrate compliance workflows, payroll alignment, device provisioning, and employee experience touchpoints. The revenue base of 14.5 billion USD in 2025 reflects a market that has moved beyond cyclical assignment volumes and now captures recurring platform usage, managed services, and enterprise-grade security tooling that supports distributed work.
North America remains the largest demand center, reflecting the depth of multinational headquarters, the scale of technology-driven talent strategies, and the maturity of compliance and mobility service ecosystems. Europe follows as a substantial market, shaped by cross-border labor frameworks, high assignment density, and increasingly complex social security coordination. Asia Pacific has emerged as a fast-growing region, driven by intra-Asia talent flows, expanding shared services hubs, and the rapid digitization of HR and mobility operations. Latin America and the Middle East and Africa represent smaller but strategically important pools, often tied to regional headquarters relocation, nearshoring initiatives, and specialized project deployments. The regional mix underscores a clear reality: demand is global, but compliance intensity, infrastructure readiness, and talent availability vary widely enough to require localized execution even within unified platforms.
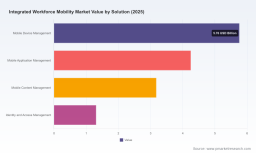
Deployment patterns further illustrate the market’s direction. Cloud-based delivery now dominates, favored for its scalability, faster integration with HR and identity systems, and ability to support rapid policy updates across jurisdictions. On-premises deployments persist in environments with stringent data residency, legacy infrastructure, or highly regulated operational requirements, but their relative share highlights the broader shift toward cloud-native architectures that can absorb new compliance rules and remote work scenarios without heavy re-engineering. On the solution side, mobile device management continues to anchor the market, given its role in securing endpoints and enabling secure access for distributed staff. Mobile application management and mobile content management extend that foundation by governing which tools employees can use and how sensitive information is stored, shared, and audited. Identity and access management, while smaller in absolute terms, is increasingly critical because cross-border mobility is only as reliable as the authentication, provisioning, and access governance that sit beneath it.
Core Challenges and Inflection Points
Several structural challenges are reshaping how organizations approach workforce mobility. The first is compliance fragmentation. Digital border systems, tax coordination, and social security scrutiny are intensifying, making it harder to treat mobility as a simple HR workflow. Assignees and remote workers increasingly move through environments where eligibility, withholding, and data handling rules change frequently, and organizations that rely on manual processes face higher compliance risk and slower deployment timelines.
A second challenge is the technology integration gap. Many enterprises still operate disjointed stacks for device management, application security, content controls, and identity governance. This fragmentation creates blind spots in visibility, slows provisioning, and complicates audit readiness. The more distributed the workforce becomes, the more acute the operational penalty of disconnected systems. Integrated platforms that unify policy execution, access controls, and user experience are gaining relevance precisely because they reduce the friction between compliance and productivity.
A third challenge involves talent experience and retention. Cross-border mobility has historically been managed as a cost and risk function, but competitive labor markets are forcing a reframe. Employees expect clear onboarding, supportive relocation experiences, and digital tools that make remote or mobile work seamless. Programs that overemphasize compliance at the expense of user experience risk higher assignment dropout, lower engagement, and weaker long-term workforce planning outcomes. The market is therefore shifting from transactional mobility administration toward experience-led, data-informed talent deployment.
Strategic Drivers Reshaping the Market
The market’s expansion is being propelled by a convergence of technology, policy, and demand-side dynamics. The most consequential driver is the maturation of cloud-native mobility architectures and the broader enterprise tooling ecosystem that supports distributed work. Secure device enrollment, policy-driven application distribution, content encryption, and identity verification are now expected capabilities rather than optional enhancements. These building blocks allow organizations to scale mobility programs without proportionally scaling administrative overhead, and they make it feasible to extend secure work environments to contingent staff, remote hires, and short-term cross-border deployees.
Policy and regulatory evolution is equally influential. Public infrastructure initiatives focused on advanced networks and broadband expansion are reinforcing the connectivity base that distributed work depends on. As legacy copper systems transition toward fiber-based and wireless capacity upgrades, organizations can rely on more consistent data transport for mobility applications, video collaboration, remote access, and location-aware compliance workflows. Alongside infrastructure modernization, regulatory attention on digital border processes and tax/social security coordination is increasing. This does not slow mobility so much as reshape it: programs must be designed with built-in compliance checks, jurisdictional logic, and audit trails, which in turn raises demand for platforms and advisory services that can operationalize those requirements at scale.
Demand-side behavior is shifting as well. Organizations are increasingly treating internal mobility, international assignments, and remote work as interconnected levers in talent strategy rather than separate programs. The rise of hybrid work models has expanded the definition of mobility to include employees who remain in one country but operate across borders digitally, consuming content, collaborating with international teams, and accessing systems that require consistent security and governance. At the same time, employers are seeking better visibility into workforce deployment patterns so they can balance tax efficiency, talent access, and employee experience. Payroll and HR data are increasingly used to optimize mobility program design, helping organizations identify where assignments are underutilized, where compliance costs can be reduced, and where policy adjustments can improve retention.
Cost structure and supply-side dynamics also play a meaningful role. Mobile workforce environments require ongoing management of devices, licenses, security policies, and support workflows. Companies that can consolidate these functions into integrated platforms gain operating leverage, especially when they face high assignment volumes or frequent policy changes across jurisdictions. Managed services further extend this advantage by offloading specialized immigration, tax, and relocation coordination to providers that maintain current regulatory knowledge and operational capacity. In a market where compliance mistakes and employee dissatisfaction both carry real costs, the economic case for integrated mobility solutions is growing stronger.
Competitive Landscape and Differentiation
The competitive environment blends advisory-led service providers, platform-focused specialists, and large technology firms whose tools underpin secure mobility at scale. This mix is one reason the market is both competitive and rapidly evolving: different players compete on service depth, technology breadth, geographic coverage, and employee experience, and the lines between them are increasingly blurred as platforms absorb compliance workflows and service providers invest in digital delivery.
EY occupies a strong position by combining tax, immigration, global compensation, and mobility pathway capabilities with a platform orientation that connects mobility to broader business strategy. Its recent emphasis on trust infrastructure and strategic integration signals a move beyond assignment administration toward the idea that mobility programs must be trusted, transparent, and aligned with enterprise priorities. That positioning matters because cross-border mobility increasingly depends on data governance, employee confidence, and executive sponsorship, not just operational execution.
Vialto Partners differentiates through globally integrated service design, covering immigration, tax, managed services, business travel, and remote work compliance, supported by digital tools such as its myMobility platform. Visibility in industry recognition and published insights on payroll-driven mobility optimization highlights an emphasis on practical program improvement and partnership-driven delivery. In a market where clients want both compliance rigor and user-friendly execution, that combination is a meaningful value proposition.
Mercer continues to leverage its scale in talent mobility services, policy benchmarking, and global mobility program support. Its comparative advantage lies in data-rich benchmarking and structured program design for international assignments and workforce strategy, which helps organizations calibrate policies against peer practice while maintaining compliance and cost discipline.
On the technology side, Microsoft provides the collaboration, cloud, security, and identity foundation that many mobility programs rely on, making it an important enabler of hybrid and remote work at enterprise scale. IBM contributes enterprise mobility management and workforce transformation capabilities, including device and application management tools designed for mobile workforce environments. VMware, now part of Broadcom, offers enterprise mobility management through its workspace and device management solutions, helping organizations secure access across endpoints and applications. Cartus rounds out the field with relocation and global talent mobility services that emphasize employee experience, policy design, and strategic program execution.
The landscape is moving toward tighter integration. Service providers are investing in digital platforms and data-driven insights to improve speed, consistency, and transparency, while technology firms continue to deepen the security, identity, and management layers that make mobility viable at scale. At the same time, new entrants and niche specialists can gain traction by focusing on specific pain points, such as remote work compliance, regional assignment complexity, or employee experience design. The result is a market that is consolidating around integration, yet still open to differentiation by specialty, geography, and service model. Market concentration remains moderate, with a meaningful share held by leading firms but enough fragmentation to reward focused capabilities and strong execution.
Healthcare Workforce Management System Market
Forward Outlook: Trends That Will Shape the Next Cycle
Over the next three to five years, the most consequential trend will be the emergence of mobility as an integrated control plane rather than a set of disconnected workflows. Platforms that combine compliance logic, identity and access governance, device and application management, and employee experience will become the default architecture for organizations managing distributed talent. This matters commercially because it shifts value from manual coordination toward scalable orchestration, where faster provisioning, stronger audit readiness, and better policy consistency become competitive advantages.
A second trend is the increasing use of workforce data to optimize mobility strategy. Payroll, assignment history, compliance outcomes, and employee feedback will be used more systematically to refine policy design, predict cost exposure, and improve assignment success rates. Organizations that treat mobility data as strategic rather than operational will be better positioned to balance talent access, cost control, and retention. This creates opportunities for advisory and technology capabilities that can translate raw data into program decisions.
A third trend is the continuing realignment of compliance expectations around digital borders, data handling, and cross-border employment rules. Rather than reducing mobility, this dynamic will likely accelerate demand for systems and services that embed jurisdictional logic, automate documentation, and support ongoing monitoring. The commercial implication is that mobility programs will need to be designed for adaptability, with policy engines and platform configurations that can absorb regulatory change without full rebuilds.
These trends carry uncertainty. Regulatory direction may diverge by region, technology integration may prove more complex in organizations with legacy systems, and talent expectations may evolve faster than program budgets. Companies that anticipate these variables by building flexible platforms, maintaining compliance visibility, and investing in employee experience will be better placed to convert change into advantage.
Strategic Actions for Decision Makers
For enterprise executives and strategic planning teams, the priority is to treat integrated workforce mobility as a structural capability rather than a periodic administrative need. That means consolidating device, application, content, and identity management into a coherent architecture, aligning mobility programs with broader talent strategy, and using benchmarking and internal data to refine policy design. Organizations that do this early will reduce compliance exposure, improve deployment speed, and strengthen retention in competitive talent markets.
For investors, the opportunity lies in identifying providers and technology layers that can sustain recurring value as mobility programs become more digital and data-driven. Attention should focus on platforms with strong integration potential, clear compliance and security differentiation, and the ability to support both managed services and self-serve enterprise usage. Given ongoing consolidation and specialization, selective exposure to capability leaders and enabling technologies is likely to outperform broad, undifferentiated exposure.
Integrated Smart Toilet Market
For procurement and mobility program owners, the practical task is to evaluate solutions based on integration depth, jurisdictional coverage, employee experience, and operational transparency. Procurement decisions should weigh not only initial cost but also the downstream impact on compliance risk, assignment success, and administrative burden. Detailed segmentation data, vendor comparisons, and tailored program recommendations can materially improve those decisions, especially when the market is changing this quickly.
For detailed analysis of this topic, please visit the official page: Integrated Workforce Mobility Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com