

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
Master Data Management Market: Strategic Trends and Commercial Opportunities in a Consolidating Data Economy
The global enterprise data landscape is undergoing a structural transformation, with Master Data Management (MDM) emerging as a critical control layer between fragmented operational systems and AI-driven decision processes. Market valuations have moved steadily upward through the 2020–2025 cycle, climbing from approximately $7.5 billion to $13.3 billion, and forward projections indicate sustained momentum through 2032. A compound annual growth rate of 12.5 percent places MDM among the faster-growing infrastructure categories in enterprise software, reflecting its shift from a specialized governance function to a strategic prerequisite for analytics, automation, and customer-facing applications.
This trajectory is not merely a reflection of incremental IT spending. It signals a deeper realignment in how organizations treat foundational data as a reusable, governed asset rather than a byproduct of operational databases. As organizations pursue data unification across customer, product, supplier, and organizational domains, MDM has become the connective tissue for compliance adherence, operational efficiency, and AI model reliability. For executives and capital allocators, the market's expansion carries both operational urgency and investment relevance. Grasping where value is concentrating, where vendor strategies are diverging, and how regulatory and technological pressures are reshaping procurement decisions is essential for positioning in the next phase of data management adoption.
Market Snapshot: Expansion With Maturing Structure
The MDM market's progression from 2020 through 2025 illustrates a category that has moved beyond early experimentation into mainstream enterprise deployment. Revenue growth accelerated notably as cloud architectures matured, data governance requirements hardened, and organizations recognized that AI initiatives frequently fail without reliable foundational data. Looking toward the 2026–2032 horizon, continued expansion is anticipated, with the market potentially reaching levels above $30 billion by the end of the forecast period. Growth velocity is expected to remain strong, though the character of that growth is changing as consolidation pressures and platform integration agendas reshape vendor positioning and buyer expectations.
Alongside top-line expansion, market structure is becoming more concentrated. A small group of large platform providers and specialized leaders now commands a significant share of enterprise engagements, while mid-tier and niche vendors compete on interoperability, domain specificity, and deployment simplicity. This concentration matters for decision-makers because it changes the purchasing environment: risk is shifting toward integration complexity, vendor lock-in, and the ability to govern data that spans both legacy and next-generation systems. At the same time, concentration is creating clearer reference architectures and more defined evaluation criteria for enterprises that need MDM to support cross-functional data products.
Core Challenges and Inflection Points
Despite strong demand, MDM adoption continues to face friction that limits the pace at which organizations can convert data unification ambitions into durable production outcomes. One persistent challenge is an operational paradox: many enterprises want MDM to be comprehensive, but comprehensive deployments often stall under the weight of governance overhead, cross-departmental alignment, and change management. MDM is no longer a one-time master data cleanup exercise; it increasingly requires continuous stewardship, workflow discipline, and integration with data quality and observability practices. Organizations that underestimate these operating requirements frequently encounter delayed time-to-value and reduced adoption across business units.
A second inflection point involves the collision between AI ambitions and data readiness. Enterprise interest in generative AI, agentic workflows, and advanced analytics has accelerated the realization that model performance and trustworthiness depend heavily on the consistency, lineage, and contextual completeness of master data. This has reframed MDM from a back-office governance concern to a front-line enabler of AI use cases. The challenge is that many existing MDM deployments were not designed for high-velocity, AI-ready data products. Bridging that gap requires new integration patterns, metadata enrichment, and governance that can accommodate both strict regulatory controls and the flexibility demanded by modern data architectures.
A third challenge is regulatory and compliance fragmentation across geographies and sectors. As privacy obligations, reporting mandates, and industry-specific standards continue to evolve, MDM implementations must support auditable stewardship, hierarchy management, and recordkeeping without becoming brittle. Compliance is no longer a side benefit; it is becoming a design constraint that shapes vendor selection, data model architecture, and operational workflows. Enterprises operating in multiple jurisdictions or regulated industries face a more complex balancing act between speed of deployment and durability of governance.
Primary Growth Drivers Reshaping the Market
Several interrelated forces are intensifying demand for MDM and changing the way solutions are evaluated. The first is technological innovation centered on AI-augmented data unification and cloud-native data foundations. MDM platforms are increasingly expected to support intelligent matching, automated stewardship, and continuous data quality feedback loops, reducing the manual burden that historically slowed adoption. This is particularly relevant as organizations attempt to scale data products across functions without proportionally increasing specialized labor. Embedded training, certification, and guided workflows are becoming part of the value proposition because they lower the practical cost of adoption and help standardize data governance practices across teams.
The second driver is the regulatory environment, which is turning data governance from an optional discipline into a compliance necessity. Privacy regulations and sector-level requirements are expanding the scope of data that must be traceable, correctable, and consistently governed. MDM architectures that provide documented stewardship workflows, hierarchy controls, and audit-ready trails are becoming more attractive in environments where data errors or inconsistent records create legal, operational, or reputational exposure. In parallel, emerging sustainability and environmental reporting expectations are adding new categories of master data that require governance and consistency, extending the relevance of MDM beyond traditional customer and product domains.
The third driver is demand-side behavior, particularly the growing expectation that enterprise data should support real-time, customer-centric, and cross-functional use cases. Organizations are moving away from treating master data as static reference content toward viewing it as an active input to segmentation, personalization, supply continuity, product lifecycle management, and trusted analytics. That shift creates demand for MDM solutions capable of producing reliable golden records, supporting multi-domain unification, and integrating with broader data platforms and cloud ecosystems. As consumers and business users alike expect more coherent experiences and more accurate information, the cost of fragmented master data becomes more visible and more consequential.
The fourth driver relates to the evolving cost and integration structure of enterprise data environments. Organizations are increasingly managing hybrid landscapes that blend legacy systems, cloud data platforms, and specialized applications. MDM that can operate across these environments without forcing a full platform replacement is gaining relevance because it reduces migration risk and preserves existing investments. This dynamic favors solutions that offer flexible deployment models, strong integration hooks, and the ability to function as a governed data layer rather than a closed ecosystem. The market is therefore rewarding vendors that can reduce complexity rather than add another rigid layer of infrastructure.
Competitive Dynamics and Strategic Positioning
The competitive landscape reflects a mix of platform-scale providers, specialized MDM vendors, and emerging entrants with strong cloud or AI orientations. Large enterprise platform companies continue to anchor the market by embedding MDM capabilities within broader data management and business application ecosystems. Their advantage lies in cross-functional reach, existing customer relationships, and the ability to connect master data governance with ERP, analytics, and cloud infrastructure strategies. In this context, MDM becomes part of a wider harmonization and AI-readiness agenda, which can simplify procurement for organizations already committed to a primary platform but can also raise integration dependency concerns for those seeking vendor flexibility.
Specialized vendors, meanwhile, compete on depth, agility, and targeted domain strengths. Some emphasize AI-powered SaaS platforms for multi-domain unification and governance, with particular attention to integration with widely used CRM and data ecosystems. Others differentiate through cloud-native architectures that support rapid scaling across business functions and simplify data cleaning and unification. Several leaders have positioned around multi-domain data platforms with strong governance, AI-ready data products, and native integration into modern cloud data warehouses. A further segment focuses on augmented platforms that combine MDM with embedded data quality and automation, appealing to organizations that want governance and quality in a single operational flow. In regulated verticals, product information management-oriented vendors extend MDM capabilities into lifecycle and compliance use cases where traceability and controlled authoring are critical.
Recent strategic movements make the consolidation theme especially visible. Major platform transactions completed in recent years demonstrate how MDM is being absorbed into broader data management and business data clouds. These moves are designed to strengthen AI-ready data unification across both native and external systems, while also expanding the reach of governance, quality, and master data capabilities within larger ecosystems. For buyers, this signals a market in which MDM is increasingly evaluated not as a standalone utility but as part of a larger data architecture strategy. The practical implication is that vendor selection is becoming more about ecosystem fit, integration roadmap, and long-term governance model than about point-feature comparison alone.
At the same time, analyst recognition and product releases indicate that differentiation remains highly active. Leadership placements in independent evaluations, continued platform releases, and public commitments to AI-powered MDM and broader ecosystem integration show that competition is not simply about scale. Vendors are competing on stewardship usability, compliance readiness, interoperability, and the ability to lower labor and training barriers to adoption. These factors matter because they influence not just initial purchase decisions but the likelihood that MDM will be operationalized effectively across the enterprise.
PW Consulting Information & Electronics Research Center
Strategic Implications of Market Evolution
One clear trend is the convergence of MDM with broader data governance, data quality, and data product thinking. The market is moving toward solutions that can serve as governed data foundations for multiple downstream consumers, including analytics, AI, customer operations, and supply chain processes. This convergence is reducing the isolation of MDM as a niche repository and increasing its role as an active contributor to enterprise data value chains. Organizations that treat MDM as a product platform rather than a static catalog are more likely to extract sustained value from their investments.
Another trend is the growing importance of interoperability across heterogeneous environments. As companies continue to accumulate cloud data platforms, legacy systems, and specialized applications, MDM must bridge gaps without demanding full architectural standardization. Solutions that support flexible integration, strong metadata handling, and consistent governance across environments are positioned to capture demand from enterprises that need progress without wholesale replacement. This favors a more practical, integration-aware buying posture, where evaluation criteria emphasize time-to-value, data product readiness, and operational maintainability.
A third trend is the increasing alignment between MDM and compliance-driven data operations. The demand for auditable workflows, stewardship accountability, and reliable hierarchy management is expanding the functional scope of MDM implementations. This is particularly relevant for organizations operating across regions or industries with distinct data obligations. MDM is increasingly expected to help demonstrate control, support reporting, and reduce exposure from inconsistent or poorly governed foundational data. In this environment, solution evaluation increasingly includes evidence of governance maturity, not just unification capability.
Digital Rights Management (DRM) Market
Future Outlook: Three Strategic Trajectories
Over the next three to five years, the MDM market is likely to be shaped by the continued blending of governance, AI readiness, and platform integration. One trajectory is the acceleration of AI-native MDM capabilities that support automated matching, stewardship assistance, and continuous data quality improvement. This will not eliminate the need for human oversight, but it should reduce the operational friction that has historically constrained scale. Commercial opportunities will arise for vendors and implementers that can demonstrate measurable improvements in data consistency, time-to-golden-record, and stewardship efficiency without sacrificing control.
A second trajectory is deeper embedding of MDM into broader data and application ecosystems. As enterprises pursue unified data foundations for analytics and AI, MDM is likely to be evaluated more often as part of a combined platform strategy rather than a discrete project. This creates opportunities for organizations that can connect master data governance with cloud data platforms, CRM workflows, and operational systems in a coherent way. It also raises the stakes for enterprises that must manage dependency risk and ensure that MDM remains adaptable if platform strategies shift.
Patient Data Management Systems (PDMS) Market
A third trajectory involves the widening applicability of MDM into sustainability, supply chain, and regulated product data contexts. As reporting obligations and operational transparency requirements grow, governed master data will become more relevant to environmental compliance, product traceability, and cross-border trade documentation. Commercial value will accrue to organizations that can extend MDM beyond traditional customer and product domains into new governance-sensitive areas. The uncertainty here lies in how quickly standards, data definitions, and audit expectations will crystallize across industries and regions, which will influence the pace of adoption in these newer use cases.
Actions for Decision-Makers Across Different Roles
For enterprise executives and strategy teams, the central task is to treat MDM as an operational capability with measurable business outcomes rather than a data cleanup initiative. That means defining the data domains that matter most to revenue, compliance, and customer experience, then investing in governance workflows, stewardship accountability, and integration to AI or analytics pipelines. Prioritizing use cases that produce visible improvements in customer data consistency, product information accuracy, or regulatory readiness can accelerate organizational support and reduce the risk of stalled deployments.
For technology and procurement leaders, the evaluation criteria should extend beyond feature lists to the reality of operating the platform in a hybrid enterprise. Important considerations include how well the solution supports multi-domain unification, how easily it integrates with existing cloud data environments, how it handles stewardship and compliance workflows, and how it lowers training and operational costs through usability and guided processes. Procurement decisions should also account for long-term adaptability, especially as platform consolidation, ecosystem integrations, and AI readiness requirements continue to evolve.
For investors and market participants, the key is to distinguish between vendors with durable differentiation and those that are primarily riding platform momentum. Value creation will increasingly depend on the ability to maintain AI-ready data products, support multi-domain governance, and demonstrate measurable improvements in data quality and operational efficiency. Monitoring strategic consolidation, ecosystem integrations, and analyst recognition can provide useful signals, but the underlying question remains whether a vendor's MDM capability is becoming a genuine enabler of enterprise data products or mainly a feature within a broader platform narrative.
Conclusion: Data Foundations as Strategic Leverage
The MDM market is expanding in a context where data is no longer a side concern but a core organizational capability. Growth is being driven by AI readiness demands, regulatory complexity, cloud-based data architectures, and the growing cost of inconsistent master data across customer, product, and operational domains. At the same time, the market is consolidating and maturing, which means the strategic question for most organizations is not whether to strengthen master data governance, but how to do so in a way that delivers durable, scalable value.
Organizations that succeed will be those that align MDM with real business outcomes, choose integration paths that reduce friction, and build governance models that can support both compliance and AI-driven innovation. Given the pace of change, timely access to detailed segment-level data, vendor benchmarking, and use-case-specific guidance can materially improve planning accuracy and investment confidence. For those seeking a deeper view of segmentation dynamics, competitive positioning, and tailored strategic options, the full PW Consulting research report provides a more granular basis for decision-making and next-step execution planning.
For detailed analysis of this topic, please visit the official page: Master Data Management (MDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
What Drives the UX Research Software Market's 11.6% CAGR to $769.85M by 2032
By pmarketresearch, 2026-09-21
The UX Research Software Market: Strategic Trends and Commercial Opportunities (2025–2032)
The user experience research software market has transitioned from a niche utility to a core component of enterprise product development. Over the past five years, the sector has demonstrated consistent expansion, moving from approximately $213 million in 2020 to roughly $362 million by 2025. This trajectory reflects a compound annual growth rate of 11.6% across the historical period, with forward projections indicating the market will approach $770 million by 2032. The growth is not merely incremental; it signals a structural shift in how organizations design, validate, and iterate digital products. For executives and investors, this landscape presents both operational imperatives and allocation decisions that require precise positioning. Understanding where the market is heading, who is shaping it, and what friction points are emerging will determine whether firms capture value or fall behind.
Market Overview and Core Challenges
The expansion of the UX research software market reflects broader digital transformation priorities. Organizations are no longer treating user research as an optional step in the design process; it has become embedded in product roadmaps, compliance frameworks, and customer retention strategies. The revenue trajectory shows steady acceleration, with the market crossing the $300 million threshold in 2024 and continuing to climb through the forecast window. This growth is distributed across cloud-based and on-premises deployment models, large enterprise buyers, and small to medium-sized enterprises, indicating that the demand is not confined to a single organizational profile or technology preference. The market remains concentrated, with the top three players accounting for roughly 60% of total revenue, which suggests that scale advantages, brand recognition, and integrated research workflows still matter significantly.
Despite the positive momentum, the sector faces several structural challenges that will shape competitive outcomes over the next few years. First, the proliferation of tools has created fragmentation. Research teams often juggle separate platforms for participant recruitment, usability testing, qualitative analysis, and insight repository management. This fragmentation increases operational overhead, complicates data continuity, and raises the risk of insights being siloed rather than operationalized. Second, data privacy and compliance requirements are tightening globally. Research software must now accommodate regional data protection standards, consent management, and secure handling of participant information, especially in regulated sectors such as healthcare and financial services. Tools that cannot demonstrate robust compliance posture face growing adoption friction. Third, the market is navigating an identity shift around artificial intelligence. While AI-driven synthesis and automated analysis promise efficiency gains, organizations are still evaluating where automation adds genuine rigor versus where it introduces noise or bias. The balance between speed and validity remains a live tension for buyers and vendors alike.
Key Drivers Shaping the Market
Technical innovation continues to be the most visible catalyst for market expansion. Platforms are moving beyond static testing workflows toward integrated environments that combine prototype evaluation, survey instrumentation, card sorting, tree testing, and automated insight generation within a single interface. The emergence of AI-assisted interview analysis, automated reporting, and rapid synthesis has reduced the turnaround time between data collection and actionable recommendations. This shift matters because it compresses the feedback loop for product teams, allowing faster iteration without sacrificing the depth of qualitative insight. For vendors, the strategic question is no longer whether to incorporate intelligent features, but how to embed them in ways that preserve methodological integrity and user trust.
Policy and regulatory dynamics are equally influential. Organizations are increasingly seeking solutions that not only comply with existing regulations but also provide clear safeguards for user data throughout the research lifecycle. This has led to product-level adjustments, including compliance-ready configurations, regional data handling options, and integration with enterprise governance workflows. In practice, compliance is no longer a backend concern; it is becoming a purchasing criterion. Buyers in healthcare, public sector, and financial services are evaluating research platforms through the lens of data protection, auditability, and consent management. Vendors that can articulate and demonstrate these capabilities are gaining a clearer path to enterprise accounts.
Demand-side behavior is also evolving. Consumer expectations for seamless, personalized digital experiences have raised the stakes for product teams. A single poorly designed flow can erode trust, increase support costs, and accelerate churn. As a result, organizations are investing more heavily in continuous research rather than episodic testing. This shift favors platforms that support recurring studies, participant panels, longitudinal tracking, and shared insight repositories. At the same time, small and mid-sized enterprises are gaining access to capabilities that were once concentrated in large organizations, because cloud-based delivery and panel access have lowered the barrier to entry. The net effect is a broader buyer base with more varied use cases and more diverse integration requirements.
Supply-side and cost dynamics contribute to the picture as well. The transition toward cloud-based deployment has expanded scalability and reduced the friction of setup and maintenance for many buyers. At the same time, the operational economics of running global participant panels, maintaining research infrastructure, and integrating with existing product toolchains require sustained investment. This creates a natural tilt toward vendors that can combine panel depth, workflow integration, and analytical automation without forcing buyers to stitch together multiple subscriptions. Cost efficiency is increasingly measured not only by license price, but by the reduction in time, coordination, and rework that a platform can deliver.
Competitive Landscape and Leading Strategies
The market features a mix of established platforms and specialized entrants, each pursuing a distinct value proposition. UserTesting operates as an enterprise-focused remote usability testing platform, offering both moderated and unmoderated studies with AI analytics integration and broad participant access. Its positioning emphasizes scale, enterprise readiness, and the ability to run structured studies across global audiences. The inclusion of UserZoom within the same platform ecosystem reflects a strategy of consolidating compliance-oriented and analytics-heavy research capabilities under a unified offering.
Maze has built its profile around an AI-first approach to prototype testing, surveys, card sorting, tree testing, and automated analysis. Its differentiation lies in speed and workflow simplicity, targeting teams that want rapid insights without navigating complex research setups. Optimal Workshop positions itself as a full research operations platform, combining card sorting, tree testing, unmoderated testing, AI-assisted interviews, and an integrated repository. Its strength is in supporting end-to-end research operations rather than isolated testing events. Lyssna, formerly known as UsabilityHub, offers an integrated user research platform spanning usability testing, surveys, interviews, and recruitment, with access to a large global panel. Its emphasis on breadth of research methods and participant availability appeals to teams seeking flexibility across study types.
Dovetail has carved out a distinct position as a customer intelligence platform focused on assembling, analyzing, and acting on qualitative research data. Its repository and AI synthesis capabilities address a recurring pain point: the loss of insight continuity when research findings remain scattered across files, notes, and individual team members. Baymard Institute takes a different approach, offering a subscription-based UX research database and tools derived from extensive original studies, paired with AI-powered assistants. Its model centers on curated insight access rather than primary data collection, which serves organizations that want to benchmark and inform decisions without running every study in-house. Great Question combines participant recruitment, study management, interviews, surveys, and AI-driven insights within a single platform, appealing to teams that want to reduce tool fragmentation. Userlytics rounds out the landscape with a full-featured remote user experience research platform backed by a large global participant panel and automated reporting, emphasizing reach and reporting efficiency.
PW Consulting Information & Electronics Research Center
Recent developments illustrate how these players are refining their positions in real time. In early 2025, Validately released a mobile-first UX research platform designed to enable usability studies and feedback collection directly from mobile devices, reflecting the growing importance of mobile-centric research workflows. Later in the year, Dovetail announced an integration partnership with Atlassian to streamline research documentation and collaboration within Jira and Confluence, signaling a push toward embedding research outputs directly into product and engineering workflows. UserZoom launched a compliance-ready UX research suite for the healthcare sector, supporting HIPAA and GDPR requirements for sensitive data, which highlights how regulatory specialization is becoming a viable differentiation path. These moves point to a market where vendors are competing not only on core testing capabilities, but on workflow integration, compliance readiness, and platform extensibility.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interrelated trends. The first is deeper workflow integration. Research platforms will increasingly connect with product management, design, engineering, and customer support tools, reducing the distance between insight generation and implementation. This will favor vendors that can embed research artifacts into existing collaboration environments and support traceability from finding to decision. For buyers, the commercial implication is clear: platforms that integrate smoothly will lower adoption barriers and increase the likelihood that research actually influences product outcomes.
Exit Interview Management Software Market
The second trend is the maturation of AI-assisted analysis, paired with growing demand for transparency and methodological rigor. Automated synthesis, summarization, and pattern detection will become more common, but buyers will also expect clearer controls around data sourcing, confidence levels, and human review. The opportunity lies in tools that augment rather than replace researcher judgment, especially in complex qualitative contexts where nuance matters. Vendors that can demonstrate consistent, auditable AI workflows will be better positioned to win enterprise trust, while those that overpromise on automation risk credibility setbacks.
User Generated Content (UGC) Software Market
The third trend is the continued expansion of compliance and data sovereignty requirements as a purchasing criterion. As regulations evolve and organizational risk tolerance shifts, research software will need to accommodate region-specific data handling, consent workflows, and sector-specific safeguards. This creates opportunities for platforms that can offer configurable compliance features without sacrificing usability or panel access. At the same time, it introduces uncertainty: regulatory trajectories are not uniform across geographies, and platforms that over-index on one compliance model may face friction when scaling into new markets. Buyers will need to evaluate not only current compliance posture, but also the flexibility to adapt as requirements change.
Strategic Recommendations for Decision Makers
For product and research leaders evaluating or expanding their use of UX research software, the priority should be to reduce fragmentation while preserving analytical depth. Consolidating recruitment, testing, qualitative analysis, and insight storage into a coherent workflow can improve speed and consistency, but only if the platform supports the methods and integrations that the organization actually uses. Before committing, teams should map their research lifecycle, identify where handoffs create delays or data loss, and assess whether a platform’s integration model aligns with existing product and engineering tools. The goal is not to chase feature lists, but to build a research operation that turns evidence into actionable decisions with minimal friction.
For investors and strategic planners, the market signals a shift from pure testing capability toward integrated research operations, compliance readiness, and workflow embedding. These are the areas where differentiation is becoming most visible. Investment attention should focus on vendors with clear expansion pathways: platforms that can deepen enterprise adoption through compliance and governance features, strengthen cross-tool integration, or scale participant access without compromising data security. At the same time, concentration in the market suggests that scale and ecosystem advantages still matter, so evaluating vendor durability, roadmap coherence, and customer retention will be important when weighing exposure.
For procurement teams and business unit leaders, the purchasing decision should be framed around operational fit and risk management rather than headline capabilities alone. Evaluate how each platform handles participant data, consent management, and regional compliance requirements, especially if the organization operates across multiple jurisdictions or serves regulated customer segments. Assess the total coordination cost, including integration with existing systems, training requirements, and the ease of moving insights into downstream workflows. Where possible, prioritize platforms that can demonstrate measurable improvements in research turnaround, insight reuse, and decision traceability, because these outcomes translate more directly into business value than feature volume.
The UX research software market is moving from expansion to refinement. Growth is still robust, but the next phase will reward platforms and buyers that prioritize integration, compliance, and actionable insight continuity. For decision makers who need detailed segmentation data, company-level benchmarking, and tailored recommendations aligned to specific operating models, the full PW Consulting market report provides a closer look at the segments, competitive dynamics, and implementation scenarios shaping the market through 2032.
For detailed analysis of this topic, please visit the official page: User Experience (UX) Research Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
RF Switches Market 2026: Beyond the 5.6% CAGR Story – PIN, GaAs, and MEMS Drivers
By pmarketresearch, 2026-09-21
Navigating the RF Switches Market: Strategic Trends and Commercial Opportunities Through 2032
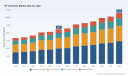
The RF switches market has entered a phase of methodical expansion, underpinned by steady revenue growth from 2020 through 2025 and a projected compound annual growth rate of 5.6 percent across the 2026–2032 forecast period. By 2025, total market revenue reached approximately 4.48 billion USD, with a clear trajectory toward 6.57 billion USD by 2032. This growth is not merely a reflection of incremental demand; it signals a structural shift in how radio frequency signal routing is designed, manufactured, and integrated across connected systems. The market’s expansion is broad-based, spanning mature telecommunications infrastructure, defense and aerospace platforms, industrial automation, and emerging satellite-linked communication networks. Yet beneath the headline numbers lies a more nuanced reality: technology transitions, regulatory pressures, and supply chain recalibration are simultaneously reshaping competitive positioning and creating asymmetric opportunities for firms that can anticipate rather than react to market shifts.
Pinpointing the Core Challenges and Market Inflection Points
Despite the favorable growth outlook, the industry is navigating several critical inflection points that will determine which players capture disproportionate value over the next five years. First, the coexistence of competing RF switch technologies is forcing design teams and procurement leaders to make increasingly complex trade-offs. PIN diode switches remain widely deployed for cost-sensitive and high-power applications, while GaAs and SOI/SOS platforms continue to dominate where isolation, linearity, and insertion loss are paramount. MEMS switches and emerging silicon-based alternatives are gradually gaining traction in scenarios where power consumption, footprint, and reliability must be optimized simultaneously. The absence of a single dominant architecture means that technology selection is becoming increasingly application-specific, raising integration complexity and lengthening qualification cycles for OEMs.
Second, the rapid expansion of low Earth orbit satellite constellations is introducing both demand tailwinds and spectrum management friction. Regulatory filings and policy analyses indicate that satellite production growth is outpacing existing coordination frameworks, creating heightened concerns over radio interference and orbital slot allocation. As operators scale constellations from thousands to tens of thousands of satellites, the RF front-end ecosystem—including switching, filtering, and amplification subsystems—must accommodate higher throughput, broader frequency coverage, and tighter thermal and reliability constraints. This dynamic is simultaneously opening new procurement pipelines for aerospace and defense suppliers while forcing terrestrial and wireless communication vendors to navigate increasingly crowded spectral environments.
Third, infrastructure deployment strategies are evolving in ways that reshape regional demand patterns. Broadband expansion initiatives are increasingly emphasizing microtrenching, surface-level deployments, and hybrid fiber-wireless architectures, which influence the mix of RF components required for last-mile and mid-mile connectivity. At the same time, sovereign spectrum rights and orbit governance frameworks are reinforcing the strategic importance of localized component sourcing, testing, and compliance. Together, these forces are pushing the market away from commoditized volume plays and toward differentiated, application-engineered solutions where switching performance, environmental ruggedness, and lifecycle support carry greater commercial weight.
Decoding the Key Demand Drivers Reshaping Revenue Trajectories
The market’s growth is being propelled by a convergence of technological, regulatory, and demand-side forces that reinforce one another rather than operate in isolation. Technological innovation remains the most direct catalyst. Recent product introductions from established manufacturers illustrate how switch architectures are being refined to meet the stringent requirements of radar, electronic warfare, broadband infrastructure, and high-reliability communications. Advancements in SOI-based SPDT platforms, high-isolation SPST/SPDT series, reflective antenna tuning switches, flip-chip architectures, and GaN-enabled high-power switching solutions demonstrate a clear industry emphasis on improving isolation, reducing loss, and expanding frequency ranges. These improvements are not incremental refinements; they enable system designers to consolidate RF paths, reduce module count, and improve overall signal integrity in increasingly dense electromagnetic environments.
Policy and regulatory developments are simultaneously acting as both an enabler and a constraint. The broadening of LEO satellite constellations has triggered heightened scrutiny around spectrum allocation, interference mitigation, and orbital coordination. Regulatory bodies and government analyses are increasingly emphasizing careful spectrum management and sovereign rights over orbital and frequency resources. For RF switch suppliers, this translates into a dual dynamic: expanded opportunities in satellite-linked communication ecosystems and test-and-measurement infrastructure, alongside stricter qualification requirements and a growing premium on components that can operate reliably under congested spectral conditions. The regulatory environment is effectively raising the barrier to entry for generic switching solutions while rewarding vendors with documented compliance, robust testing protocols, and application-specific design support.
Demand-side behavior is shifting as well. Cellular and wireless communication networks continue to anchor a substantial share of RF switch consumption, but the nature of that demand is changing. Base station architectures, antenna tuning systems, and broadband access equipment are becoming more modular and software-defined, requiring switching components that can adapt to dynamic reconfiguration without sacrificing performance. At the same time, industrial and automotive applications are gaining prominence as connectivity expands beyond traditional telecom into factory automation, vehicle-to-infrastructure communication, and sensor-heavy environments. These sectors demand switches that can tolerate harsher operating conditions, sustain long service intervals, and integrate cleanly into mixed-signal architectures. The result is a broadening of the demand base that reduces reliance on any single vertical while increasing the need for segmented product strategies.
PW Consulting Information & Electronics Research Center
Supply chain and cost structure dynamics round out the driver set. The concentration of revenue among a relatively small group of leading suppliers indicates that scale, technology maturity, and strategic customer relationships continue to confer meaningful advantages. At the same time, the market’s evolution toward specialized high-reliability and high-isolation solutions is elevating the importance of production consistency, material sourcing, and qualification documentation. Cost pressures persist, particularly in consumer-facing and mass-market wireless applications, but they are increasingly offset by value migration toward performance-critical segments where switching reliability, thermal handling, and integration flexibility directly influence system economics. The net effect is a market where cost leadership alone is no longer sufficient; competitive advantage is being redefined around design enablement, lifecycle support, and application-specific performance guarantees.
Competitive Landscape and the Strategies Defining Market Leadership
The competitive environment reflects a market that is neither fully consolidated nor fragmented beyond coherence. A concentrated core of established manufacturers anchors supply in defense, aerospace, telecommunications, and test-and-measurement applications, each pursuing distinct yet overlapping strategic positions. Leading players are differentiating not simply through product breadth, but through architecture specialization, application-specific tuning, and long-term ecosystem relationships that extend beyond component sales.
Network Switches Market
Companies focused on high-performance semiconductor-based switching are emphasizing platform continuity and portfolio expansion. Recent announcements in the first half of 2026 illustrate this pattern clearly. Qorvo introduced new X-Band amplifiers, GaN transistors, and SOI SPDT RF switches targeting defense, aerospace, radar, electronic warfare, communications, and DOCSIS 4.0 broadband applications, signaling a deliberate push to align switching solutions with high-growth, high-reliability segments. pSemi expanded its UltraCMOS+ portfolio with new high-isolation RF switches, reinforcing a strategy centered on isolation performance and integration simplicity for demanding RF front-end designs. Skyworks Solutions has continued to emphasize reflective antenna tuning switch architectures that support beamforming, coverage optimization, and adaptive impedance matching in advanced wireless systems. Analog Devices maintains a strong position in flip-chip SP4T switching for test and measurement and cellular applications, where repeatability, calibration stability, and signal path integrity are critical. MACOM’s reflective SPDT switches remain relevant across WiFi, Bluetooth, and base station ecosystems, particularly where rapid reconfiguration and compact integration are valued.
Parallel to these semiconductor-centric strategies, a cohort of suppliers is strengthening their position in electromechanical, coaxial, waveguide, and high-reliability switching for environments where solid-state alternatives face thermal, power-handling, or failure-mode constraints. Teledyne Microwave Solutions and Teledyne Relays & Coax Switches provide surface-mount and latching multi-throw coaxial switching that support communications systems and aerospace and defense deployments requiring extended lifecycle durability and deterministic switching behavior. JFW Industries’ absorptive failsafe switches and Dow-Key Microwave’s custom coaxial, waveguide, and space-grade switches highlight a persistent premium on tailored solutions for high-power and mission-critical scenarios. Narda-MITEQ and Pasternack Enterprises continue to serve wireless communication and test-and-measurement markets with reflective and electromechanical transfer switches that prioritize repeatability, isolation, and serviceability. Planar Monolithics Industries and Radiall reinforce the broader ecosystem with solid-state and microwave-component switching options that address military, industrial, and component-integration requirements.
The strategic lesson from this landscape is that leadership is increasingly defined by the ability to match switching technology to the failure modes, environmental constraints, and reconfiguration requirements of the end application. Firms that treat RF switches as interchangeable commodities risk margin erosion and displacement by suppliers offering integrated design support, application-specific qualification packages, and lifecycle reliability documentation. Conversely, suppliers that align product roadmaps with defense/aerospace ruggedness, broadband infrastructure scalability, satellite communication frequency expansion, and test infrastructure repeatability are positioning themselves to capture more resilient demand streams. The market is also showing signs of gradual consolidation pressure, as acquisition interest in specialized high-reliability portfolios and niche antenna-tuning platforms intensifies. At the same time, new entrants and smaller specialist firms can still find room in custom configurations, ultra-high isolation niches, and application-tailored electromechanical solutions where incumbents face limits in standard product coverage.
Forecasting the Next Phase: Three Trends to Watch Through 2032
The next three to five years will likely be shaped by a blend of technology migration, demand diversification, and ecosystem coordination challenges. The first trend is the continued broadening of application-specific switch architectures. As systems grow more software-defined and frequency-agile, RF switches will need to support dynamic reconfiguration, lower loss across wider bands, and improved robustness against interference. The commercial opportunity lies in developing modular switching families that can be rapidly adapted across cellular, broadband, satellite-linked, and industrial use cases without requiring full redesign cycles. Suppliers that can offer configurable isolation levels, compact integration footprints, and predictable thermal behavior will be better positioned to win in environments where system architects must balance performance, cost, and deployment speed.
Worldwide High Isolation RF Switches Market
The second trend is the deepening integration of RF switching into high-reliability and satellite-adjacent ecosystems. The scaling of LEO constellations and the growing emphasis on spectrum discipline are expanding the need for components that can operate across extended frequency ranges, withstand harsh environmental conditions, and satisfy rigorous qualification standards. This trend favors suppliers with documented aerospace and defense heritage, robust testing capabilities, and the ability to support long-lifecycle deployment models. Commercial upside will accrue to firms that can bridge the gap between terrestrial wireless demand and space-linked communication requirements, particularly where switching reliability directly affects link stability, interference resilience, and maintenance intervals.
The third trend is the gradual rebalancing of supply chain risk and regional procurement preferences. As regulatory frameworks reinforce sovereign rights over spectrum and orbital resources, and as infrastructure plans increasingly emphasize localized broadband expansion, procurement teams are placing greater weight on supply continuity, traceability, and compliance documentation. The commercial implication is a market where regional service capability, testing support, and component qualification transparency increasingly influence purchasing decisions alongside unit economics. Firms that can demonstrate consistent production quality, application engineering support, and resilient sourcing will be better positioned to retain strategic accounts and capture new programs that prioritize supply assurance over lowest-cost sourcing.
These trends carry embedded risks. Technology choices that appear advantageous today may face obsolescence pressure if network architectures shift toward new frequency plans, beamforming strategies, or integrated RF modules that reduce discrete switch count. Regulatory uncertainty around spectrum allocation and orbital coordination could delay program timing or alter component specifications mid-cycle. Cost pressure in high-volume wireless and consumer-adjacent applications could compress margins for suppliers that fail to differentiate on performance or lifecycle support. Finally, consolidation activity may accelerate, altering supplier relationships and forcing customers to reevaluate qualification pipelines, second-source strategies, and long-term roadmap alignment.
Strategic Actions for Decision-Makers Across the Value Chain
For manufacturers and product leaders, the priority is to align switch roadmaps with the applications where performance differentiation is both measurable and commercially rewarded. This means investing in architectures that improve isolation, reduce loss, and support broader frequency coverage while maintaining production consistency and qualification clarity. Teams should prioritize modular product families that can be adapted across cellular, broadband, satellite-adjacent, and industrial environments without fragmenting engineering resources. Equally important is strengthening design-in support: application notes, integration guidance, thermal and reliability documentation, and test-proven reference configurations can materially accelerate adoption in programs where switching performance affects overall system performance. Manufacturers should also evaluate second-source strategies and supply assurance capabilities early, since procurement teams increasingly weigh continuity and traceability alongside technical specifications.
For investors and corporate development teams, the market offers segmentation-specific opportunities rather than a uniform growth story. High-reliability aerospace and defense switching, broadband infrastructure expansion, and satellite-linked communication ecosystems represent segments where technical differentiation and qualification depth translate into more defensible revenue streams. In contrast, commoditized high-volume segments may deliver volume but limited margin expansion unless paired with integration advantages or platform-level partnerships. Due diligence should therefore focus on product roadmaps, technology ownership, qualification pipelines, customer concentration, and the ability to support long-lifecycle deployments. Portfolio construction should weigh the trade-off between scale-driven semiconductor platforms and specialized electromechanical or high-power solutions, recognizing that both can be attractive but require distinct execution models and customer engagement strategies.
For procurement and systems integration teams, the strategic emphasis should shift from unit price alone toward total cost of qualification, integration risk, and lifecycle reliability. Switching components that reduce design iterations, simplify calibration, and deliver predictable behavior under real-world thermal and interference conditions can lower program risk and shorten deployment timelines. Procurement strategies should incorporate supplier capability in application engineering, testing support, and documentation quality, particularly for programs where RF path integrity directly impacts throughput, coverage, or mission reliability. Where possible, qualification planning should account for regulatory evolution in spectrum management and orbital coordination, ensuring that selected components remain suitable as frequency plans, interference conditions, and system architectures evolve over the program lifecycle.
The RF switches market is expanding within a framework that rewards clarity of application focus, technical differentiation, and supply assurance. Executives who map their strategies to the segments where switching performance, reliability, and integration flexibility carry financial weight will be better positioned to capture value as the market moves from steady growth toward more segmented, performance-driven competition. For organizations seeking deeper segmentation data, region-specific demand patterns, detailed competitive benchmarking, and tailored scenario planning, the full research report provides the additional granularity required to translate these market-level insights into executable commercial decisions.
For detailed analysis of this topic, please visit the official page: RF Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Corporate Secretarial Services Market 2026: Beyond the 5.2% CAGR Story
By pmarketresearch, 2026-09-21
Navigating the Corporate Secretarial Services Market: Strategic Shifts and Emerging Opportunities
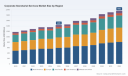
The corporate secretarial services landscape is undergoing a structural transformation driven by regulatory complexity, technological adoption, and evolving corporate governance expectations. Global revenue in this space reached approximately USD 1,435 million in 2025, up from USD 1,180 million in 2020, reflecting a compound annual growth rate of 5.2 percent through the 2032 outlook horizon. This growth trajectory is not uniform; it reflects a sector where routine compliance tasks are increasingly automated while high-value governance advisory, cross-border entity management, and risk mitigation services command premium positioning. For executives and investors, the market presents a dual narrative: steady top-line expansion paired with rapid shifts in how services are delivered, priced, and differentiated.
Market Landscape and Core Challenges
The corporate secretarial services market operates at the intersection of legal compliance, administrative governance, and strategic advisory. Over the past five years, revenue growth has consistently outpaced broader professional services benchmarks, yet the expansion masks underlying pressures that demand strategic attention. The sector's value is increasingly concentrated in complex jurisdictions, multinational entity structures, and organizations that cannot sustain in-house compliance teams at scale. This dynamic creates both opportunity and vulnerability for service providers and corporate buyers alike.
Regulatory Velocity and Compliance Gaps
One of the most persistent challenges is the pace of regulatory change. Directors and corporate secretaries must navigate an environment where filing requirements, governance standards, and disclosure obligations evolve faster than internal processes can adapt. Recent amendments to audit exemption frameworks and corporate governance enforcement provisions have introduced immediate compliance implications, altering statutory filing calendars and expanding the scope of director accountability. Simultaneously, broader corporate registry reforms in key markets have imposed transition periods that require updated entity documentation, enhanced beneficial ownership tracking, and revised board oversight procedures. Organizations that rely on reactive compliance workflows face elevated risk of late filings, governance lapses, or reputational exposure.
Cost Pressure and In-House Efficiency Gaps
A second structural pressure stems from the cost of maintaining compliance capabilities internally. As entity structures become more layered and regulatory expectations intensify, corporations are reassessing whether fully owned secretarial teams provide the most efficient path. The complexity of multi-jurisdiction operations, fluctuating staffing costs, and the need for specialized regulatory knowledge are pushing organizations toward outsourced or hybrid operating models. This shift is not simply about cost reduction; it reflects a strategic decision to redirect internal resources toward core business activities while leveraging external expertise for statutory adherence, governance administration, and risk tracking.
Share Registry Services Market
Technology Integration and Workflow Fragmentation
The third challenge lies in the uneven pace of digital transformation across the sector. While cloud-based entity management platforms and AI-enhanced tracking tools are increasingly referenced in advanced markets, many organizations still operate with fragmented workflows, manual document control, and siloed compliance calendars. The gap between early adopters and laggards creates operational inefficiencies and inconsistent compliance quality. Service providers that can unify statutory tracking, board administration, document automation, and regulatory intelligence into cohesive workflows are gaining traction, while legacy models struggle to justify premium pricing for purely administrative services.
Core Drivers Shaping Market Dynamics
The market's direction is shaped by a combination of technological, regulatory, demand-side, and cost-structure forces. Each driver reinforces the others, creating a cycle where complexity fuels outsourcing, outsourcing accelerates technology adoption, and technology enables stronger governance outcomes.
Worldwide Company Secretary Tool Market
Technology Innovation and Automation
Digital tools and automation are redefining what corporate secretarial services can deliver. Cloud-based entity management systems now support continuous compliance monitoring, automated filing reminders, digital board pack generation, and centralized document repositories. AI-assisted workflows are increasingly used for statutory tracking, contract review support, and regulatory change alerts. These capabilities reduce manual error rates, shorten turnaround times, and enable service providers to manage larger portfolios with greater consistency. In markets where regulatory evolution is rapid, such as advanced Asian financial hubs, cloud-enabled and AI-enhanced tools have accelerated the shift toward real-time governance administration and digital board meetings. The strategic implication is clear: technology is moving from a back-office enabler to a core differentiator that shapes service quality, scalability, and pricing power.
Regulatory and Governance Environment
Regulatory changes continue to be the most influential driver of demand. Amendments affecting audit exemptions, corporate governance enforcement provisions, and registry transparency requirements have expanded the compliance burden for directors and corporate secretaries. In the UK context, for example, recent reforms have created transition periods that require organizations to update governance documentation and strengthen preparedness for directors facing new filing and oversight expectations. These regulatory shifts do more than increase paperwork; they alter the compliance risk profile of companies and elevate the importance of proactive governance administration. Providers that can combine regulatory interpretation, practical implementation support, and ongoing monitoring are better positioned to capture demand from organizations seeking to reduce exposure to compliance failures.
Demand-Side Shifts in Corporate Behavior
Corporate behavior is changing in ways that expand the addressable market. Companies are increasingly viewing corporate secretarial functions not as a static administrative task but as a governance capability that supports board effectiveness, investor confidence, and operational resilience. Large corporations with complex legal entity structures need consistent oversight across jurisdictions, while small and medium enterprises require affordable, reliable compliance support to scale without governance breakdowns. Micro enterprises, meanwhile, often seek streamlined formation and basic compliance services that lower the barrier to formal incorporation. This segmentation of demand encourages providers to design service tiers that balance cost efficiency with depth of support, and it creates opportunities for specialized offerings in entity management, governance advisory, and shareholder administration.
Cost Structure and Outsourcing Economics
Cost dynamics are reinforcing the shift toward managed services. The rising complexity of entity structures and regulatory requirements increases the difficulty of maintaining fully in-house compliance teams, especially for organizations operating across multiple jurisdictions. Outsourced corporate secretarial services offer a pathway to reduce fixed compliance costs, access specialized expertise, and scale service capacity as business needs evolve. This economic logic is particularly compelling for firms that want to avoid the overhead of recruiting, training, and retaining niche compliance talent while still meeting statutory obligations. The result is a growing preference for service models that combine predictable pricing with flexible coverage, especially where compliance failures carry material financial or reputational consequences.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of global professional networks, specialized corporate service providers, and niche players with strong regional or sector focus. The market remains moderately fragmented, with the largest three players holding a combined share near 28 percent and the top five approaching 42 percent. This concentration indicates room for consolidation while also reflecting the practical realities of jurisdiction-specific licensing, regulatory knowledge, and client trust.
Strategic Positioning of Leading Players
PwC and Deloitte leverage broad professional service ecosystems to offer integrated corporate secretarial and entity management capabilities alongside regulatory compliance support across numerous jurisdictions. Their advantage lies in the ability to connect secretarial services with wider governance, tax, audit, and advisory offerings, creating cross-sell opportunities and a unified client experience. KPMG and Mazars pursue similar integration strategies, with strong emphasis on managed services, statutory compliance, and governance support delivered through global networks. These firms benefit from brand recognition, multinational reach, and the credibility that comes from operating across the full spectrum of corporate/advisory services.
Vistra and TMF Group represent the specialized end of the spectrum. Vistra focuses on corporate secretarial services, entity administration, and regulatory compliance for international clients, often serving organizations that require consistent handling across multiple jurisdictions. TMF Group emphasizes corporate secretarial services, trust administration, and compliance solutions for regulated entities, positioning itself around depth in regulated structures and operational execution. Citco narrows the focus further by specializing in corporate secretarial and management services for regulated entities such as hedge funds and private equity, where governance requirements and investor expectations are particularly stringent.
Other players add important dimensions to the competitive field. Ecovis relies on partnerships with local networks to deliver global compliance coverage, which can be an effective model for firms that value local execution combined with international coordination. Axiom Law integrates corporate secretarial services with legal network support, emphasizing board governance and compliance within a broader legal advisory context. Luther Corporate Services builds on entity management focus for Indian and international clients, reflecting the growing importance of India-linked operations in global compliance workflows. Equiniti provides company secretarial and governance administration services with an emphasis on UK and international compliance, and recently expanded its engagement model through new governance insight products designed to help clients track regulatory changes and company secretarial developments. Link Group complements this landscape with corporate secretarial, governance, and shareholder services across multiple markets, reinforcing the trend toward integrated administration and investor-facing support.
Differentiation and Market Evolution
Differentiation in this market is increasingly defined by three factors: jurisdictional coverage, technology-enabled delivery, and service integration. Providers that can demonstrate reliable multi-jurisdiction execution, combined with coherent governance advisory and digital workflow tools, are better positioned to retain multinational clients and command stronger pricing. At the same time, the market is evolving through both consolidation and specialization. Larger platforms may pursue selective acquisitions or partnership models to expand jurisdictional reach, while specialized firms may deepen expertise in regulated sectors, complex entity structures, or particular regional ecosystems. New entrants that offer modern digital interfaces, transparent pricing, and strong compliance quality can win share in segments where traditional providers remain dependent on manual processes.
For corporate buyers, the practical implication is that vendor selection should move beyond reputation alone and evaluate operational reliability, technology maturity, regulatory responsiveness, and the ability to scale as entity structures change. For providers, the strategic priority is to reduce dependency on purely administrative revenue by expanding into governance advisory, risk monitoring, and digital service models that improve margins and client stickiness.
Future Trends and Commercial Opportunities
Looking ahead, three trends are likely to shape the market over the next several years and create actionable opportunities for organizations that prepare early.
Trend 1: Governance-as-a-Service and Integrated Compliance Platforms
Corporate secretarial services are moving toward integrated platforms that combine entity management, statutory filings, board administration, document control, and regulatory intelligence in a single workflow. This shift creates an opportunity for providers to offer governance-as-a-service models that reduce friction for clients and improve consistency across jurisdictions. For corporations, the value lies in fewer handoffs, clearer audit trails, and faster response to regulatory changes. The opportunity is not limited to large enterprises; small and medium enterprises can benefit from tiered digital packages that provide reliable compliance coverage without the cost of building internal capability from scratch. A key risk is that platform complexity may outpace usability if solutions are not designed around practical client workflows, so success will depend on user experience and integration quality as much as feature breadth.
Trend 2: AI-Augmented Compliance Monitoring and Predictive Governance
AI and automation will increasingly support statutory tracking, regulatory change detection, and compliance calendar management. Predictive capabilities may enable earlier identification of filing obligations, potential governance gaps, and jurisdiction-specific requirements that change with little notice. This trend strengthens the case for outsourced and hybrid models, because providers that invest in intelligence layers can offer proactive monitoring rather than reactive filing support. The commercial opportunity lies in converting compliance from a transactional function into a continuously managed service with higher retention and clearer value justification. The uncertainty comes from regulatory acceptance, data governance expectations, and the need to ensure that AI-assisted workflows remain explainable and auditable, especially in sensitive compliance contexts.
Trend 3: Consolidation, Ecosystem Partnerships, and Regional Specialization
The market is likely to see continued consolidation among mid-tier providers seeking scale, alongside ecosystem partnerships that combine global coordination with local execution. At the same time, regional specialization will remain important because regulatory nuance, licensing requirements, and client expectations vary significantly by jurisdiction. This dynamic creates opportunities for firms that can balance global consistency with local depth, either through owned offices, strategic partnerships, or network-based delivery models. Investors and acquirers may find value in platforms with strong jurisdictional coverage, recurring revenue characteristics, and demonstrated technology adoption. The risk is that consolidation can be complicated by integration challenges, differing compliance standards, and client migration costs, so execution discipline will determine whether scale translates into durable advantage.
Actionable Recommendations for Decision Makers
Different stakeholders face distinct priorities in this environment, but all can benefit from a structured approach to corporate secretarial strategy.
For Corporate Executives and Governance Leaders
Evaluate whether internal compliance structures are aligned with current regulatory complexity and future growth plans. If entity structures are expanding or regulatory expectations are increasing, consider hybrid or outsourced models that reduce fixed overhead while improving coverage consistency. Prioritize providers that can demonstrate digital workflow maturity, proactive regulatory monitoring, and clear escalation paths for governance issues. Treat corporate secretarial capability as part of the broader governance and risk framework rather than an isolated administrative function.
For Investors and Strategic Acquirers
Focus on business models with recurring revenue, scalable delivery, and credible technology adoption. Jurisdictional breadth, regulated-sector expertise, and strong client retention are important indicators of resilience. Assess whether target providers rely too heavily on manual administrative work or have moved toward integrated platforms and governance advisory services. In consolidation plays, prioritize cultural and operational compatibility, since integration challenges can erode the value of expanded jurisdictional reach. Monitor regulatory transitions closely, as compliance-driven demand can accelerate engagement but may also shift in response to new filing structures and governance rules.
For Procurement Teams and Service Selection Leaders
Use structured criteria that go beyond price and reputation. Evaluate data security, filing accuracy history, response times during regulatory changes, and the ability to manage multi-jurisdiction portfolios without loss of consistency. Request evidence of digital integration, document control standards, and board administration capabilities rather than assuming these are available by default. Where possible, pilot services in a limited scope to test workflow reliability before expanding to broader entity portfolios. A well-designed procurement process can reduce the risk of service gaps and create a stronger foundation for long-term compliance performance.
For organizations that need detailed segmentation data, jurisdiction-level dynamics, and tailored scenario planning, deeper research can help translate these market-wide trends into specific investment, vendor selection, or operating-model decisions. A more granular view of service-type demand, company-size segmentation, regional growth patterns, and competitive positioning can support more precise go-to-market and procurement strategies. Readers interested in the full analytical framework, including expanded segmentation detail and customized recommendations, can access the complete PW Consulting study for this market.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Corporate Secretarial Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Brand Protection Software Market: Why 8.75% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-21
The Brand Protection Software Market: Strategic Shifts and Commercial Opportunities in a $2 Billion Landscape
The global market for brand protection software has crossed a significant inflection point. From $780.45 million in 2020, market revenue has grown at a consistent pace to reach $1,163.0 million in 2025, with a forecast trajectory lifting projections to $2,066.2 million by 2032. The compound annual growth rate of 8.75 percent underscores a sector that is far from a niche compliance tool; it is becoming a core layer of digital risk management, intellectual property defense, and revenue preservation. For executives, investors, and procurement leaders, the question is no longer whether to invest in brand protection capabilities but how to architect them in a way that aligns with operational reality, regulatory obligations, and the accelerating sophistication of threat actors.
Behind the headline numbers lies a market defined by structural fragmentation and rapid technological change. Brand abuse is no longer confined to counterfeiting in traditional retail channels. It now spans marketplace listings, social media impersonation, domain squatting, phishing infrastructure, gray-market distribution, and dark web proliferation. Defending against these exposures requires software that can detect at scale, triage accurately, enforce across jurisdictions, and integrate with internal legal, security, and supply chain workflows. The organizations that treat brand protection as a standalone monitoring function are increasingly finding themselves outpaced, while those embedding it into broader risk and revenue operations are beginning to capture measurable advantages.
Market Snapshot and Structural Headwinds
Revenue growth in this sector reflects sustained enterprise demand, but the growth itself is uneven across use cases and deployment models. Cloud-based implementations dominate the addressable spend, while on-premises deployments remain meaningful for organizations with stringent data residency or legacy system integration requirements. On the application side, anti-counterfeiting continues to anchor spending, followed by brand abuse monitoring, with social media protection and domain name protection representing smaller but strategically critical slices of the portfolio. Geographically, the largest revenue pools sit in North America, Europe, and Asia Pacific, with Latin America and the Middle East and Africa contributing more modest but fast-evolving demand.
What matters more than the split itself is what the mix reveals about buyer priorities. Enterprises are moving from reactive takedowns toward continuous monitoring, predictive detection, and cross-channel enforcement. At the same time, the market remains relatively fragmented at the top, with the top three players accounting for 22.35 percent of revenue and the top five reaching 27.18 percent. That concentration leaves substantial room for differentiation, partnerships, and consolidation, but it also signals that no single vendor has claimed a commanding, default position across all brand protection needs.
The current environment is shaped by three intersecting challenges.
-
The tension between scale and accuracy. Automated detection can surface enormous volumes of potential infringement, but high-confidence enforcement still depends on specialized human review, threat validation, and jurisdiction-specific takedown procedures. That creates an operational strain, particularly for small and mid-sized enterprises that lack the internal expertise to manage false positives or complex enforcement cases.
-
The compliance friction baked into data handling. Data privacy and security requirements, including frameworks such as GDPR, force vendors and buyers alike to treat brand threat intelligence as sensitive data. Secure storage, controlled sharing, and careful cross-border processing are not optional add-ons; they are design constraints that influence platform architecture and deployment decisions.
-
The cost of sustained effectiveness. High implementation and maintenance burdens persist because meaningful protection is not a one-time configuration. It requires ongoing monitoring updates, rule tuning, marketplace and platform coverage expansion, and continuous adaptation to new abuse patterns. For organizations without dedicated brand protection teams, these ongoing costs can become the difference between an installed capability and an actually effective one.
Taken together, these challenges are not simply headwinds; they are shaping the logic of the next generation of solutions. Buyers are looking for platforms that lower the human review burden without surrendering accuracy, that treat compliance as a built-in feature rather than a separate workstream, and that justify their total cost of ownership by connecting threat reduction to revenue retention and operational efficiency.
Core Drivers Redefining the Market
Four forces are doing the most to reshape demand, vendor strategy, and the pace of adoption.
AI and Automation as the New Baseline
Artificial intelligence is moving from a marketing differentiator to a practical requirement. The most advanced platforms now pair computer vision, predictive models, seller risk scoring, and AI-assisted enforcement workflows to reduce the time between detection and action. Recent product moves illustrate the direction of travel. In April 2026, Red Points introduced a Copilot AI assistant built around predictive models, seller risk scores, and computer vision for brand protection, signaling an emphasis on prioritizing high-probability abuse and reducing manual triage. That same vendor expanded marketplace brand protection capabilities in February 2026 with AI detection and API enforcement designed for e-commerce platforms, reinforcing the shift from manual monitoring toward automated, API-driven action.
Around the same time, Corsearch published its 2026 State of Trademarks Report in May 2026, highlighting AI-driven trademark monitoring advancements, and followed with a webinar in June 2026 on balancing AI, automation, and human expertise in trademark teams. Those activities reflect a broader industry recognition: automation can widen the detection surface and accelerate routine enforcement, but trademark, brand, and legal teams still require explainable outputs, defensible evidence, and human judgment for complex cases.
For decision-makers, the implication is straightforward. The competitive advantage is no longer simply whether a platform uses AI, but how it integrates AI into evidence collection, risk prioritization, enforcement pathways, and auditability. Solutions that only promise detection at scale, without clear escalation logic and human-in-the-loop controls, are likely to underperform in environments where false positives and enforcement friction carry real financial and reputational costs.
Regulatory Pressure and Cross-Border Enforcement Complexity
Regulatory and standards-driven dynamics are expanding both the need for brand protection software and the requirements placed on it. Global IP enforcement standards continue to push organizations toward automated compliance across multiple jurisdictions, especially as brand abuse moves fluidly across domains, marketplaces, social platforms, and dark web channels. At the same time, data privacy and security concerns remain a meaningful restraint, not because organizations want less protection, but because they need platforms that can handle threat intelligence in a compliant, defensible manner.
This creates a dual mandate. Buyers want broader coverage and faster enforcement, but they also need evidence-driven monitoring, secure handling of brand threat data, and workflows that respect jurisdiction-specific processes. The vendors best positioned to gain share are those that can frame compliance not as a limitation but as a reinforced operating model, where monitoring, evidence preservation, and enforcement actions are designed with regulatory and privacy obligations in mind from the outset.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer expectations and enterprise purchasing behavior are reinforcing each other. Consumers are increasingly sensitive to counterfeit goods, impersonation, and fraudulent storefronts, and they often encounter brand abuse before a company does. That puts pressure on brands to protect not only revenue but also trust, especially in categories where product authenticity and digital legitimacy directly affect purchasing decisions.
On the enterprise side, brand protection is increasingly evaluated alongside cybersecurity, fraud prevention, and e-commerce growth initiatives. This is visible in the expansion of platform scopes beyond traditional IP monitoring. Companies such as ZeroFox emphasize digital risk protection with dark web intelligence, threat validation, and disruption workflows for brand abuse, phishing, and executive threats. RiskIQ approaches the space from threat intelligence and risk profiling, targeting brand exposure and actionable risk insights across digital assets. BrandShield focuses on AI-powered detection with expert-enforced removal across phishing, impersonation, counterfeit listings, app threats, websites, social media, marketplaces, and the dark web. The common thread is that brand protection is being treated as part of a broader digital risk surface, rather than an isolated trademark issue.
Worldwide Anti-piracy Protection Market
Supply Chain, Marketplace, and Enforcement Economics
The economics of enforcement are changing as abuse migrates into faster-moving, harder-to-monitor channels. Marketplace volume, cross-border gray-market distribution, and decentralized digital storefronts increase the number of exposure points a brand must manage. At the same time, specialized human expertise in threat validation and enforcement remains essential for high-accuracy outcomes, which adds operational strain for smaller teams and raises the attractiveness of platforms that can automate more of the repeatable work.
This is why enforcement integration has become strategically important. API-based enforcement, marketplace partnerships, and takedown workflow automation can materially change the cost and speed of response. For manufacturers, distributors, and online sellers, the practical value of brand protection software increasingly depends on whether it can reduce manual effort across the full lifecycle: discovery, evidence gathering, escalation, removal, and ongoing monitoring after remediation.
Competitive Landscape and Strategic Positioning
The competitive field is broad and includes players with different origins, strengths, and go-to-market models. Understanding the landscape means looking past feature lists and examining how each organization positions itself against the market's core problems: detection breadth, enforcement credibility, evidence quality, and operational burden.
Corsearch builds its positioning around AI-powered trademark clearance, brand monitoring, revenue recovery, and content protection, with global enforcement spanning domains, marketplaces, and social media. Its recent emphasis on trademark monitoring advancements and the balance between automation and human expertise suggests a strategy that blends IP rigor with scalable monitoring. Red Points positions itself as an AI-driven platform for unlimited counterfeit removal, impersonation takedowns, gray-market enforcement, and piracy prevention across thousands of marketplaces, websites, and social platforms, with recent moves reinforcing AI assistants and marketplace enforcement capabilities. BrandShield emphasizes AI-powered detection and expert-enforced removal for phishing, brand impersonation, counterfeit listings, and app threats across websites, social media, marketplaces, and the dark web, pointing to a hybrid model that combines automated detection with expert-led enforcement.
ZeroFox and RiskIQ extend the conversation toward digital risk. ZeroFox frames its offering as an AI-powered digital risk protection platform with dark web intelligence, threat validation, and disruption workflows for brand abuse, phishing, and executive threats. RiskIQ approaches the market through threat intelligence and risk profiling, focusing on brand exposure, dark web monitoring, and actionable risk insights across digital assets. MarkMonitor remains associated with comprehensive domain monitoring, trademark protection, and online brand protection for large enterprise clients, reinforcing a legacy strength in domain and trademark-centric programs. OpSec Security contributes authentication and brand protection solutions, including AI-powered tools for counterfeit prevention and product authentication, tying digital protection to physical product integrity. PhishLabs combines phishing simulation and brand protection training with threat intelligence for enterprise risk management, an angle that connects brand defense to internal readiness and security awareness. Resolver concentrates on domain monitoring and trademark enforcement for IP protection, while Netcraft emphasizes evidence-based brand protection with domain and website monitoring for reputation and security threats. Netcraft's updated brand protection platform from November 2025, with its emphasis on evidence-driven domain and website monitoring, reflects a continuing emphasis on defensible visibility.
The strategic pattern across these players is not uniform, and that is the point. Some organizations compete on breadth of coverage and marketplace enforcement; others differentiate on evidence quality, authentication, digital risk, or trademark and domain specialization. For buyers, the decision often comes down to which type of protection aligns best with the brand's exposure profile. A company whose primary risk is marketplace counterfeiting may evaluate platforms differently from one facing phishing and executive-targeted impersonation, or from one that needs stronger product authentication and physical-digital linkage.
PW Consulting Information & Electronics Research Center
The landscape is also evolving through both consolidation and specialization. On one side, larger security, threat intelligence, and digital risk platforms continue to find value in folding brand protection into broader offerings, especially where customers want a single view of external threats. On the other side, specialized vendors continue to emerge or reposition around specific enforcement workflows, regional needs, or high-accuracy detection models. The relatively moderate top-level concentration suggests that this tug-of-war is still active, and that meaningful differentiation can still be created through execution, integrations, and domain expertise.
Forward Trends and Commercial Opportunity
Looking ahead across the next three to five years, three trends are likely to define where value accumulates.
From Detection to Prioritized, Evidence-Ready Enforcement
The market is moving toward platforms that not only find abuse but also rank it, package it as evidence, and push it through enforceable workflows. This matters because the cost of brand protection is increasingly measured in operational drag, not just license spend. Solutions that reduce review cycles, improve the quality of evidence, and integrate with marketplace and domain enforcement channels will be better positioned to justify investment. The commercial opportunity here lies in end-to-end effectiveness: customers will reward tools that make enforcement faster, more defensible, and less dependent on large internal teams.
Deeper Integration with Digital Risk, Security, and Authentication
Brand protection is increasingly overlapping with cybersecurity, fraud operations, and product authentication. Organizations are looking for coherent visibility across phishing, impersonation, counterfeit listings, domain abuse, and dark web exposure, rather than separate tools for each problem. The opportunity is for vendors and buyers alike to build or adopt architectures that link brand protection with adjacent risk functions. For manufacturers and product companies, the connection to authentication and physical supply-chain integrity is especially important, because digital enforcement and product verification increasingly reinforce each other.
Governance, Compliance, and Cross-Border Scalability as Differentiators
As privacy and data security requirements continue to shape deployments, governance will become a more visible competitive dimension. Platforms that can demonstrate secure handling of threat intelligence, consistent cross-border processes, and auditable enforcement documentation will have an advantage in regulated industries and in multinational programs. The broader opportunity is for brand protection to be evaluated not only on threat coverage but also on how well it supports compliance-ready operations. This is particularly relevant for organizations expanding into new markets or managing complex supplier and marketplace ecosystems.
These trends carry risk and uncertainty. AI-driven detection can improve scale, but it can also increase the volume of signals that must be managed, potentially raising operational complexity if workflows are not well designed. Regulatory expectations will continue to evolve, and platforms that cannot adapt to local enforcement and data-handling rules may lose traction in key regions. Cost structures may also remain elevated for organizations that treat brand protection as a set of disconnected tools rather than a coordinated program. Finally, market consolidation could shift bargaining power, integration expectations, and long-term vendor viability, making supplier strategy more important than ever.
Implications for Decision-Makers
The strategic takeaway is that brand protection is becoming a multi-dimensional investment, and the right posture depends on the organization's exposure profile, internal capability, and growth trajectory.
Digital Risk Protection Software Market
For manufacturers and consumer-facing brands, the priority is to align brand protection with both revenue defense and product integrity. That usually means broadening coverage beyond the most visible abuse channels, integrating detection with enforcement workflows, and connecting digital monitoring to authentication and supply chain controls where relevant. The goal is not simply to identify infringement, but to reduce the time to action and the cost of remediation across the channels that matter most to the business.
For investors, the opportunity sits in platforms that combine scalable detection with defensible enforcement, strong evidence handling, and credible paths to integration within larger security or risk stacks. Differentiated AI use cases matter, but durable value is more likely where automation lowers operational burden, where coverage extends across marketplaces and digital channels, and where compliance-ready design supports enterprise adoption. In a market that is still fragmented at the top, execution quality, workflow design, and customer outcomes will be key indicators of long-term positioning.
For procurement and security leaders, the focus should be on total cost of ownership and operational fit rather than feature breadth alone. Evaluation criteria should include how well the platform supports evidence-driven monitoring, how it handles data privacy and security obligations, how readily it integrates with marketplace enforcement or internal workflows, and whether the vendor's model matches the organization's internal capacity for review and escalation. A platform that is powerful on paper but difficult to operationalize can create hidden costs that outweigh its theoretical advantages.
In a market that is expanding steadily toward $2,066.2 million by 2032, the most consequential decisions will be about architecture, prioritization, and vendor fit rather than whether to act at all. Organizations that treat brand protection as a coordinated, evidence-driven, and compliance-aware program are better positioned to protect revenue, reduce risk, and keep pace with the next generation of digital abuse. For those seeking a more detailed segmentation view, deeper competitive benchmarking, and customized guidance tied to specific operating contexts, PW Consulting's full market report provides the additional breakdown and strategic recommendations needed to translate these trends into a concrete investment and implementation plan.
For detailed analysis of this topic, please visit the official page: Brand Protection Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dispatch Consoles Market: How 5 Strategic Shifts Drive 4.55% CAGR Through 2032
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Dispatch Consoles Market
The dispatch consoles market stands at an inflection point. Over the past half-decade, global revenue has steadily climbed from approximately $144 million in 2020 to an estimated $183.4 million in 2025, reflecting a compound annual growth rate of 4.55 percent across the 2026 to 2032 forecast horizon. While the absolute figures may appear modest relative to broader technology markets, the structural importance of these systems to mission-critical operations places them at the center of public safety modernization, transportation coordination, and utility resilience. The market is evolving from a mature, hardware-centric ecosystem toward an IP-enabled, software-defined environment where interoperability, cloud integration, and intelligent automation are reshaping procurement priorities. Understanding where the market is heading requires looking beyond headline scale and examining the forces that will determine competitive advantage over the next several years.
Market Snapshot and Structural Pressures
The dispatch consoles market has demonstrated consistent expansion, with revenue growth underpinned by replacement cycles, expanding public safety mandates, and incremental adoption across transportation and utility verticals. The five-year trajectory shows resilience despite procurement headwinds in certain regions, and forecast models suggest continued upward movement as legacy architectures are phased out. What matters strategically, however, is not only the pace of growth but the shifting composition of demand. Budget-constrained agencies are balancing modernization with operational continuity, while technology vendors are reorienting portfolios around IP-based platforms that can scale across multiple sites and integrate with broader command and control ecosystems.
Key Challenges and Inflection Points
Three structural pressures are reshaping how dispatch console solutions are evaluated, funded, and deployed. The first is the wave of regulatory-driven replacement cycles. Agencies across multiple regions are retiring mid-2000s console infrastructure to comply with Next Generation 911 frameworks and evolving European Electronic Communications Code requirements. This creates a predictable demand pipeline, but it also introduces complexity around integration with legacy radio systems, training, and change management. Organizations that treat replacement as a simple like-for-like swap risk missing the opportunity to redesign workflows and improve interoperability from the ground up.
The second challenge involves the intersection of cybersecurity, reimbursement uncertainties, and stretched municipal budgets. Compliance requirements are adding cost layers to console modernization, which slows procurement velocity and extends planning horizons. Tight budgets are pushing agencies toward phased rollouts and shared services rather than large, upfront deployments. Vendors and integrators that can demonstrate clear total-cost-of-ownership advantages, staged implementation paths, and transparent security postures are better positioned to convert long consideration cycles into signed engagements.
The third pressure is infrastructural rather than financial. Scarcity of dispatch-ready spectrum bands below 1 GHz imposes a long-term cost constraint on network deployment for dispatch operations, with effects expected to persist for at least four years. This constraint influences both radio architecture decisions and console design, because bandwidth, coverage, and interconnection assumptions shape what can be reliably supported in the field. Console strategies that assume abundant low-band spectrum or ignore spectrum constraints risk misaligning with deployment realities.
Core Drivers Shaping Market Direction
Technology Innovation and Platform Consolidation
The market’s center of gravity is shifting toward IP-based dispatch consoles that unify voice, data, and command workflows within scalable software platforms. This transition is being accelerated by acquisitions and product integrations that bundle console software with broader service offerings. A notable example is Motorola Solutions’ acquisition of HyperYou, aimed at embedding agentic AI capabilities for call triage and unit dispatch recommendations. The move signals a broader trend in which console vendors are expanding from operator interfaces into decision-support systems that reduce cognitive load and accelerate response workflows. At the same time, Motorola’s purchase of Bell Canada’s land-mobile-radio business for CAD 675 million illustrates how vendors are assembling end-to-end domestic infrastructure stacks, pairing nationwide radio assets with console software to create integrated deployment models. Similar logic is visible across the competitive set, where IP-based console platforms are increasingly positioned as the integration layer between radios, mobile apps, mapping tools, and incident management systems.
On the public safety side, deployment activity is reinforcing the shift toward modern platforms. Hexagon’s contract with Kitsap 911 in Washington to deploy HxGN OnCall Dispatch with live mapping and mobile apps reflects the growing expectation that dispatch consoles should not only manage voice but also deliver geospatial context, mobile field connectivity, and workflow integration. City-level procurements are likewise moving toward vendor-supported, IP-based solutions, as seen in the City of Riverside’s authorization to purchase and install CommandCentral AXS Dispatch Console equipment. These decisions matter because they establish reference points for interoperability and scalability in comparable jurisdictions. Even indirect indicators, such as bid awards for dispatch console furniture, underscore that console replacement is a multi-component program rather than a single software purchase, which expands the scope of integration and service requirements.
Regulatory and Policy Environment
Policy is a durable driver because it creates compliance-linked refresh cycles and raises performance expectations for mission-critical systems. In North America and Europe, agencies are replacing aging consoles to meet Next Generation 911 and European Electronic Communications Code requirements, which elevates the importance of IP readiness, data interoperability, and regulatory-aligned workflows. These frameworks do more than force replacement; they nudge procurement toward solutions that can support future data-rich call handling, multi-agency coordination, and auditable records. Policy-driven demand is less cyclical than budget-dependent demand, which makes it an important anchor for long-term planning.
In Asia-Pacific, the dynamics differ. Smart-city programs are leapfrogging straight to cloud-native command centers for dispatch consoles, bypassing some of the legacy refresh patterns seen elsewhere. This creates an environment where initial deployments can be architected for scalability and centralized operations from the outset, rather than incrementally upgraded from circuit-switched foundations. The policy-led opportunity in this context is not only about selling console software but also about aligning with broader city platforms, data standards, and integration roadmaps that span transportation, utilities, and emergency response.
Demand-Side Shifts in Mission-Critical Operations
Demand is being shaped by operational expectations that extend well beyond traditional radio dispatch. Public safety organizations want faster call triage, better situational awareness, and more reliable interoperability across agencies and jurisdictions. Transportation authorities seek coordinated fleet dispatch that ties together operations centers, field units, and passenger information systems. Utilities and energy operators require dispatch tools that can support outage response, field crew coordination, and resilience planning under increasing weather-related stress. Government and defense customers continue to prioritize mission-critical reliability, while healthcare and industrial users are exploring dispatch console capabilities for internal coordination and emergency escalation.
These demand-side shifts favor solutions that can be tailored without becoming fragile. Configurable IP platforms, vendor-neutral architectures, and repeatable integration patterns are gaining relevance because they allow organizations to adapt the console to operational realities rather than forcing operations to adapt to a rigid console design. Procurement teams are increasingly evaluating the breadth of interoperability, the speed of onboarding new sites or users, and the ability to add analytics or mapping capabilities without a complete platform replacement. That is why the market is gradually tilting toward software-defined consoles that can evolve alongside end-user workflows.
Cost Structure and Supply-Side Realities
Cost dynamics are increasingly influenced by infrastructure constraints and the financial realities of public sector procurement. The scarcity of dispatch-ready spectrum below 1 GHz places pressure on network deployment cost and timeline, which in turn affects console bundling, coverage planning, and the economics of multi-site rollout. On the procurement side, reimbursement uncertainty and tight municipal budgets are extending purchase cycles, making agency modernization timelines less predictable. This environment rewards vendors and integrators that can reduce the friction of buying by offering modular deployment, clear modernization roadmaps, and demonstrable security and compliance value.
Cost is also being redefined by what consoles must now protect. Growing cybersecurity compliance costs are becoming part of the modernization calculus, especially for agencies that cannot absorb extended cutovers or post-deployment vulnerabilities. In practice, cybersecurity is no longer an add-on concern; it is a selection criterion that influences architecture decisions, vendor choice, and deployment sequencing. Supply-side providers that can normalize security considerations within the product and service package rather than treating them as a separate negotiation will have an easier path through stretched budgets.
Competitive Landscape and Leading Approaches
The competitive field is relatively concentrated, with the top three players accounting for roughly 35 percent of market share and the top five combining for about half. Concentration of this level indicates that scale, reputation, and ecosystem breadth matter, but it also suggests room for differentiated positioning by specialized vendors and regional players. Leadership is increasingly defined by the ability to combine console software with interoperability, integration, and operational support rather than by console features alone.
Strategic Positioning and Differentiation
Motorola Solutions stands out through an integrated operating model that spans command center software, IP dispatch consoles, and radio infrastructure. Its focus on CommandCentral AXS, the MCC 7500e IP dispatch console, and Avtec Scout voice dispatch consoles positions the company around public safety and enterprise operations that require tightly coordinated dispatch, CAD, and field communications. Recent acquisition activity reinforces this orientation: embedding agentic AI for call triage and unit dispatch recommendations points toward workflow automation, while the land-mobile-radio acquisition supports bundled nationwide infrastructure with console software. The strategic advantage here is the ability to offer a more complete deployment path for agencies that want fewer integration seams and stronger alignment between console software and the underlying communications fabric.
Zetron emphasizes mission-critical interoperability and scalability through MAX Dispatch and ACOM Command and Control IP-based dispatch consoles. Its positioning is particularly relevant for organizations that need reliable multi-agency coordination and a platform designed to scale across complex operational environments. InterTalk Critical Information Systems takes a vendor-neutral approach with its Dispatch Console System and Enlite solution, which appeals to public safety and mission-critical radio dispatch users seeking an exact-fit configuration without locking into a single radio vendor’s ecosystem. Avtec pursues a similar philosophy with Scout Enterprise voice and radio dispatch consoles, built as a vendor-agnostic, highly configurable IP platform for organizations that value flexibility across radio vendors and sites.
Omnitronics focuses on omnicore Express and Enterprise radio dispatch consoles for small to large organizations, with RoIP interoperability as a foundation for bridging radio and IP environments. EF Johnson Technologies positions itself around StarGate and interoperability dispatch consoles for P25 and public safety systems, which aligns with agencies prioritizing standards-based public safety communications. L3Harris contributes through Symphony and VIP Dispatch Consoles within VIDA integrated network solutions, tying console capabilities into a broader public safety dispatch network context. Cisco Systems brings IP-based radio and incident management through IPICS and Command T4, leveraging its broader networking and collaboration footprint to support dispatch and incident coordination workflows.
Hexagon Safety and Infrastructure focuses on HxGN OnCall Dispatch, now Octave OnCall, for computer-aided dispatch with live mapping and mobile apps. Its differentiation lies in marrying CAD functionality with geospatial visualization and mobile connectivity, which is increasingly valued in public safety operations where situational awareness directly affects outcomes. Siemens Convergence Creators addresses mission-critical command and control through AtoS Dispatch Solutions and Control Center offerings, reflecting a focus on structured control-room environments and large-scale operational coordination.
Push-To-Talk Market
How the Landscape Is Evolving
Three patterns are visible in the market’s evolution. The first is consolidation through acquisition, as larger players absorb adjacent capabilities such as AI triage, regional radio businesses, or CAD and mapping assets. This is likely to continue because integrated stacks reduce integration risk for large deployments and create cross-selling opportunities across console software, infrastructure, and analytics. The second pattern is product divergence between fully integrated, vendor-supported platforms and vendor-neutral, interoperable systems. Agencies with standardized radio environments may gravitate toward bundled solutions, while multi-vendor or multi-agency environments may favor neutral platforms that preserve choice and reduce dependency. The third pattern is the emergence of new entry angles, particularly from software, analytics, and cloud integration players who are not traditional console manufacturers but can influence selection through workflow automation, mapping, incident management, or cloud-native command center capabilities.
For buyers, this landscape means that competitive differentiation is less about raw console features and more about deployment model, interoperability, integration depth, and the ability to support modernization under budget and security constraints. For vendors, it means that winning configurations increasingly combine a strong core console with clear integration pathways, security credibility, and growing intelligence capabilities that improve operator effectiveness without complicating the user experience.
Forward Outlook: Trends That Will Shape Opportunity
From Console to Intelligent Command Interface
Over the next three to five years, dispatch consoles are likely to be evaluated less as isolated operator interfaces and more as command interfaces that connect voice, data, mapping, analytics, and decision support. The acquisition of AI-focused capabilities by major players suggests that triage assistance, recommendation engines, and workflow guidance will become part of the console value proposition. For buyers, this creates an opportunity to reduce operator overload and improve consistency under pressure. For providers, it creates a differentiation path based on measurable improvements in response coordination, call handling efficiency, and situational awareness. The commercial opportunity lies in solutions that can embed intelligence without sacrificing reliability, auditability, or ease of use in high-stress environments.
Cloud-Native and Regional Divergence in Deployment Models
A second trend is the divergence in deployment philosophies across regions. While North America and Europe are largely driven by replacement cycles tied to regulatory modernization, Asia-Pacific smart-city initiatives are more likely to adopt cloud-native command centers from the outset. This does not mean cloud will dominate everywhere immediately, but it does indicate that hybrid and cloud-managed configurations will increasingly compete with on-premises architectures, especially where centralized operations, multi-site visibility, and rapid scaling matter. The strategic opportunity for vendors is to offer flexible deployment models that can meet regional expectations without fragmenting product strategy. For buyers, the opportunity is to design modernization programs that can adapt to future operating models, data-sharing needs, and interagency coordination requirements.
A related opportunity is the expansion of console relevance beyond traditional public safety into transportation, utilities, government, healthcare, and industrial coordination. Transportation demand is already among the largest application segments, and utility and energy operations are likely to increase investment as resilience and outage coordination become more critical. The strategic case for cross-vertical expansion is not that every sector needs the same console, but that core IP-based dispatch capabilities can be adapted to sector-specific workflows with the right integration, configuration, and support model.
Infrastructure, Cyber, and Budget Uncertainty as Chronic Factors
The third trend is less optimistic but strategically important: infrastructure constraints, cybersecurity compliance costs, and budget pressure will likely remain persistent influences on procurement timing and solution design. Spectrum scarcity below 1 GHz imposes long-term cost constraints on network deployment for dispatch operations, and cybersecurity compliance will continue to shape what agencies can afford to modernize and how quickly. Reimbursement uncertainty and stretched municipal budgets will keep extending procurement cycles in parts of the market. These factors increase the value of phased deployment, modular upgrades, and clear financial and security justification. They also raise the risk of mismatch when vendors assume a faster pace of change than agencies can fund or operate.
The commercial implication is that success will depend on helping customers sequence modernization intelligently. Providers that can align console upgrades with radio, mapping, cybersecurity, and budget realities will be better placed to convert demand into deployments. Conversely, solutions that over-index on advanced features without addressing integration, security, or affordability may struggle to win in a market where procurement patience is limited.
Strategic Recommendations for Decision-Makers
For Console and Platform Manufacturers
Focus investment on interoperability, security-by-design, and workflow automation rather than only on interface enhancements. The most defensible positions will belong to platforms that can integrate cleanly across radio vendors, CAD and mapping tools, mobile apps, and incident management systems while maintaining clear security and compliance value. AI and decision-support features should be introduced as operators’ aids that demonstrably improve triage, prioritization, and coordination, with measurable outcomes rather than speculative capability claims. In parallel, maintaining flexible deployment options—including configurations that can align with cloud-native expectations in regions pursuing smart-city command centers—will broaden addressable demand without sacrificing reliability in mission-critical settings.
Worldwide Portable Gaming Consoles Market
For Investors and Strategic Partners
Prioritize companies with credible paths to integrated stacks, regional scale, and interoperability leadership. Acquisition-driven expansion of console, radio, CAD, mapping, and AI capabilities is likely to continue, and the value created will depend on successful integration, cross-selling, and the ability to win complex multi-agency or multi-site deployments. Pay close attention to cybersecurity posture, spectrum-aware deployment planning, and the ability to support procurement under budget pressure, since these factors increasingly determine deal velocity. Opportunities also exist in enabling technologies—cloud management, analytics, mapping, and modular integration services—that reduce the friction of console modernization for end users.
For Procurement, Operations, and Public Sector Decision-Makers
Treat console modernization as a multi-year operational program rather than a single procurement event. Define enablement criteria that matter in practice: interoperability across current and future radio environments, integration with CAD, mapping, and mobile tools, security and compliance clarity, and a realistic pathway for phased rollout under budget constraints. Use replacement cycles mandated by Next Generation 911 or European Electronic Communications Code as an opportunity to redesign workflows and interoperability, not merely to refresh hardware. Where feasible, seek referenceable deployments that demonstrate measurable operational improvements, and require evidence that the solution can scale across sites and adapt to evolving data and coordination needs. In markets where spectrum constraints or cybersecurity costs are material, validate those assumptions early so that architecture and budgeting decisions are grounded in operational reality.
Navigating the Next Phase of Dispatch Console Modernization
The dispatch consoles market is moving through a period in which steady headline growth is accompanied by significant structural change. IP-based platforms, regulatory-driven replacement cycles, interoperability expectations, and emerging intelligence capabilities are reshaping what buyers need and what providers must deliver. At the same time, spectrum constraints, cybersecurity costs, and budget pressures are making procurement sequences more deliberate and more demanding. For executives, planners, and investors, the strategic question is no longer whether dispatch consoles are important, but how to position for a market where success depends on integration, adaptability, and credible modernization pathways.
PW Consulting Information & Electronics Research Center
Deeper segmentation data, regional demand patterns, and customized scenario analysis can help translate these market-level trends into durable business decisions. For readers seeking detailed breakdowns across segments, competitive positioning by region, and tailored guidance aligned with specific procurement, investment, or product strategies, the full PW Consulting research report provides the supporting structure needed to move from market awareness to execution planning.
For detailed analysis of this topic, please visit the official page: Dispatch Consoles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Inductors Market: Why 5.0% CAGR and Automotive Demand Redefine Growth by 2032
By pmarketresearch, 2026-09-21
Navigating the Power Inductors Market: Strategic Trends and Commercial Opportunities Through 2032
The power inductor market has entered a phase of steady, structurally supported expansion. From a global revenue base of approximately 163.15 million in 2020, the sector reached 215.0 million by 2025, reflecting consistent demand across electrified and digitized industries. Forecasts extending through 2032 project a trajectory toward 344.8 million, anchored by a compound annual growth rate of 5.0 percent. This growth is not merely cyclical; it reflects enduring shifts in power management architecture, vehicle electrification, and the miniaturization of high-performance electronics. Yet beneath the headline figures lies a complex landscape shaped by material constraints, regulatory realignments, and intensifying competition. For executives, investors, and procurement leaders, understanding these dynamics is essential to positioning for sustainable returns.
The market’s expansion has been broad-based, with Asia Pacific representing the largest regional footprint, followed by North America and Europe. Demand spans multiple application domains, with automotive and consumer electronics anchoring volume, while industrial and specialized sectors contribute incremental growth. Product segmentation reveals a clear preference for wire-wound configurations, though multilayer chip, thin film, and specialized alternatives continue to capture niche requirements driven by size, frequency, and thermal constraints. The competitive environment remains moderately concentrated, with the largest three players commanding a combined share near 64 percent and the top five approaching 72 percent. This concentration reflects the technical barriers, qualification cycles, and scale economics that characterize power magnetics, but it also signals that margin pressure and differentiation are increasingly determined by design expertise, supply chain resilience, and application-specific engineering support.
Core Challenges and Inflection Points
Despite the favorable growth trajectory, the industry faces structural headwinds that will shape competitive outcomes over the next several years. First, raw material volatility and supply concentration are reshaping cost structures and lead time predictability. Copper prices on the London Metal Exchange fluctuated between 8,200 and 10,500 U.S. dollars per ton in 2025, directly influencing the economics of wire-wound inductor production. At the same time, rare-earth export quotas introduced in early 2025 extended lead times for manganese-zinc ferrite from eight to sixteen weeks, while China’s control of roughly 70 percent of manganese-zinc ferrite capacity has concentrated supply risk for core materials. These dynamics are not transient pricing issues; they reflect geopolitical and policy-driven constraints that require proactive sourcing strategies and material substitution exploration.
Second, the demand environment is shifting faster than traditional qualification cycles can accommodate. Automotive electrification and high-efficiency power conversion in consumer electronics are pushing inductors into higher current, higher frequency, and wider temperature envelopes. Designers increasingly require components that minimize core losses, reduce magnetic field radiation, and maintain stability under thermal stress. Suppliers that can deliver shielded, low-resistance, and vehicle-grade solutions are gaining preferential placement in next-generation designs, while those reliant on commodity-grade offerings face margin compression and substitution risk.
Third, supply chain bottlenecks and import-export regulations have compounded availability challenges. Geopolitical tensions and evolving trade controls in 2025 increased friction across logistics networks, affecting the timely delivery of both raw materials and finished magnetics. For manufacturers and system integrators, this translates into a need for dual-sourcing, buffer inventory strategies, and closer collaboration with suppliers that offer transparent lead time management and regional manufacturing footprints.
PW Consulting Information & Electronics Research Center
Key Drivers Shaping Market Trajectory
Technological Innovation and Performance Boundaries
Innovation in power inductor design is being driven by the simultaneous requirements of higher efficiency, smaller form factors, and robust thermal performance. Shielding technology has become a critical differentiator, particularly in applications where electromagnetic interference must be minimized without sacrificing saturation current or heating capability. Recent product introductions illustrate how suppliers are pushing these boundaries. In April 2025, a major manufacturer added four new shielded power inductor series engineered for high heating and saturation current while reducing magnetic field radiation, addressing the needs of compact power supplies and automotive modules. Later that year, another supplier expanded its portfolio with ultra-low loss shielded power inductors featuring ultra-low inductance values starting from 40 nanohenries, specifically targeting DC-DC converter applications where switching efficiency and transient response are paramount.
Chip Power Inductor Market
Parallel advancements in core materials and winding techniques are also reshaping performance envelopes. Flat-wire molded power inductors introduced in late 2025 demonstrated exceptionally low direct current resistance, with values as low as 4.8 milliohms, and extended temperature ranges that support demanding industrial and automotive environments. These developments reflect a broader trend: power inductors are no longer commodities selected primarily on price, but engineered components whose electrical, thermal, and mechanical characteristics directly influence system-level efficiency and reliability. For design teams, this means that early supplier collaboration and application-specific characterization are becoming integral to product development cycles.
Policy and Regulatory Environment
Regulatory and policy forces are exerting both constraints and opportunities across the value chain. On the materials side, export quotas and trade controls have lengthened lead times for key ferrite and metal-based core materials, prompting manufacturers to reconsider inventory models and qualification pathways. Nickel price fluctuations, influenced by Indonesian export policy shifts in 2024 and 2025, have further affected the cost structure of powder core inductors, adding another layer of variability to procurement planning. These policy-driven dynamics are encouraging regional diversification of supply and increased interest in alternative material architectures where feasible.
On the demand side, regulatory emphasis on energy efficiency, emissions reduction, and vehicle electrification is reinforcing long-term adoption of high-performance power magnetics. Automotive standards and industrial efficiency mandates are pushing system designers toward components that reduce losses across broader operating ranges, which in turn elevates the importance of inductors with low core loss, stable inductance under DC bias, and proven reliability under vibration and thermal cycling. Compliance-driven design choices are therefore acting as a structural tailwind, particularly in segments where qualification rigor creates meaningful barriers for new entrants.
Demand-Side Shifts in Consumer and Industrial Behavior
Demand patterns are being reshaped by the convergence of electrification, digitalization, and compact power architecture. Automotive applications continue to dominate volume expectations, driven by the proliferation of electric drivetrains, onboard power management, and auxiliary systems that require reliable, high-current magnetics. Consumer electronics remain a core growth engine, with increasing power demands in charging infrastructure, portable devices, and smart home equipment pushing designers toward miniaturized, high-efficiency inductors that can operate at higher switching frequencies without sacrificing thermal stability.
Industrial applications, while smaller in relative volume, are experiencing incremental gains as automation, renewable energy systems, and smart manufacturing equipment require robust power conversion components. Across these segments, a common theme is the shift from off-the-shelf selection to application-engineered solutions. System architects are increasingly evaluating inductors based on integrated performance metrics—efficiency over temperature, saturation behavior, electromagnetic compatibility, and mechanical resilience—rather than nominal inductance and footprint alone. This shift rewards suppliers that can provide comprehensive technical support, design-in documentation, and fast turnaround on custom variants.
RF Inductors Market
Supply Chain and Cost Structure Evolution
Cost structures are being redefined by material volatility, manufacturing scale, and the growing importance of regional supply resilience. Copper and nickel price fluctuations, combined with extended lead times for ferrite materials, have heightened the need for dynamic sourcing and hedging strategies. Manufacturers that operate multiple production sites or maintain diversified supplier networks are better positioned to absorb shocks and maintain delivery continuity. At the same time, the premium on engineered performance is creating opportunities for suppliers that can balance cost efficiency with technical differentiation.
The trend toward flat-wire construction, advanced shielding, and precision winding illustrates how manufacturing process improvements can simultaneously reduce resistance, improve thermal handling, and support higher volume consistency. These process advancements are not merely incremental; they enable new performance tiers that align with the requirements of modern power conversion architectures. For procurement leaders, this underscores the value of evaluating total cost of ownership—including efficiency gains, qualification risk, and supply reliability—rather than unit price in isolation.
Competitive Landscape and Leading Strategies
The competitive field in power inductors is anchored by a mix of established global manufacturers and specialized producers, many of which have built defensible positions through application expertise, material know-how, and deep design-in relationships. Leading participants span North America, Europe, and Asia, with Japanese and U.S. firms historically strong in wire-wound and multilayer technologies, while European manufacturers have emphasized precision engineering and automotive-grade qualification. Chinese suppliers are expanding their footprint, particularly in vehicle-grade and high-current segments, leveraging scale and rapid product iteration to capture design opportunities in both domestic and export markets.
Strategic differentiation among top players increasingly hinges on three pillars. The first is performance engineering: the ability to deliver shielded, low-loss, high-saturation components that meet the thermal and electromagnetic requirements of modern power systems. Recent product announcements from multiple leading firms demonstrate a clear focus on reducing magnetic field radiation, lowering DC resistance, and expanding inductance ranges to cover ultra-low values for high-frequency converters. These capabilities are not merely technical achievements; they directly influence design wins in automotive, consumer, and industrial applications where efficiency and reliability are non-negotiable.
The second pillar is application-specific support. Suppliers that provide robust design tools, characterization data under DC bias and temperature, and rapid responsiveness to custom requirements are gaining advantage in qualification-heavy segments. This is especially relevant in automotive and industrial markets, where validation cycles are long and substitution costs are high. Companies that invest in technical marketing, reference designs, and close collaboration with system architects are better positioned to secure early design-in placement and sustain volume as platforms move into production.
The third pillar is supply chain resilience. In an environment marked by material volatility and extended lead times for core materials, manufacturers with diversified sourcing, regional production capabilities, and transparent inventory management are increasingly favored by procurement teams. This dynamic is reinforcing a preference for suppliers that can demonstrate continuity risk mitigation, including dual-sourcing of critical materials and flexible manufacturing footprints. As a result, competitive advantage is shifting from price leadership alone to a broader value proposition encompassing technical performance, qualification support, and delivery reliability.
The market structure is evolving along two converging paths. On one hand, concentration among the top players reflects the scale and expertise required to compete in high-performance segments, where R&D investment, qualification infrastructure, and global distribution networks create meaningful barriers. On the other hand, fragmentation persists in specialized niches where custom winding, non-standard footprints, and application-tailored materials enable smaller manufacturers to serve specific customer needs. New entrants and regional suppliers are gaining traction in vehicle-grade and high-current categories, often by combining aggressive pricing with focused engineering support. Over the next several years, the landscape is likely to see selective consolidation in commodity-adjacent segments alongside continued specialization in high-performance and application-specific domains.
Future Trends and Commercial Implications (2026–2032)
Trend One: Efficiency-Driven Magnetics Will Redefine Design Priorities
Over the next three to five years, power inductor selection will increasingly center on efficiency across broader operating envelopes. As switching frequencies rise and power densities increase, designers will prioritize components that minimize core and copper losses while maintaining stable inductance under DC bias and thermal stress. This trend will elevate the importance of advanced shielding, flat-wire construction, and core material optimization. Commercially, it creates opportunities for suppliers that can deliver validated performance data, application-specific characterization, and integrated design support. It also raises the stakes for manufacturers that rely on generic specifications, as efficiency-sensitive designs will favor components with demonstrable advantages in real-world operating conditions.
Trend Two: Supply Chain Diversification and Material Strategy Will Become Competitive Essentials
Material concentration risks, export controls, and commodity price volatility will continue to shape procurement and production strategies. Buyers and manufacturers alike will pursue dual-sourcing, regional inventory buffers, and alternative material pathways where feasible. Suppliers that can offer transparency on lead times, provide contingency sourcing options, and maintain consistent quality across production sites will gain preference in qualification discussions. For investors and executives, this trend signals that resilience is becoming a value driver in its own right, influencing both customer selection and long-term margin stability. Companies that proactively address material risk through supplier diversification, strategic stocking, and technical substitution research will be better positioned to sustain growth through cycles of volatility.
Trend Three: Application-Specialized Growth Will Outpace Generic Segments
Automotive and consumer electronics will remain the primary volume engines, but the most attractive margins will accrue to suppliers that can address specialized requirements within these segments. Vehicle-grade high-current inductors, ultra-low loss components for high-frequency converters, and compact shielded solutions for space-constrained designs are likely to command premium positioning. Meanwhile, industrial and niche applications will continue to generate steady demand, particularly where robustness, temperature tolerance, and electromagnetic compatibility are critical. The commercial implication is clear: growth will be strongest for manufacturers that align product roadmaps with application-specific performance needs and invest in the technical infrastructure to support design-in adoption. Generic, price-driven competition will face continued pressure as differentiation shifts toward engineered value and supply reliability.
These trends carry inherent uncertainties. Material policy changes could alter cost structures more abruptly than anticipated, and rapid shifts in automotive platform timing or consumer device cycles could affect demand pacing. Geopolitical friction and trade regulation may continue to introduce lead time variability, while technological substitution—such as alternative magnetics architectures or integrated power modules—could reshape component-level demand in specific applications. Navigating these uncertainties will require scenario-aware planning, flexible sourcing, and close alignment between product development and market intelligence.
Strategic Guidance for Decision Makers
For Manufacturers and Product Leaders
Align engineering roadmaps with the efficiency and thermal demands of next-generation power architectures. Prioritize shielded, low-resistance, and vehicle-grade capabilities where qualification cycles reward performance and reliability. Invest in application-specific characterization, design-in support, and rapid customization workflows to strengthen design-in placement and reduce time-to-qualification. Concurrently, build supply chain resilience through diversified material sourcing, regional manufacturing options, and transparent lead time management to mitigate raw material volatility and policy-driven constraints.
For Investors and Corporate Development Teams
Focus due diligence on suppliers that combine technical differentiation with supply chain robustness and clear application alignment. Evaluate total value rather than unit pricing, with attention to efficiency gains, qualification risk reduction, and delivery continuity. Monitor consolidation dynamics in commodity-adjacent segments and growth opportunities in vehicle-grade, high-current, and ultra-low loss categories. Companies that can sustain performance leadership while managing material and logistics risk are likely to capture disproportionate share in a moderately concentrated market.
For Procurement and Supply Chain Executives
Shift evaluation frameworks toward total cost of ownership, incorporating efficiency impact, thermal stability, qualification support, and supply reliability. Develop dual-sourcing strategies for critical materials and maintain buffer inventory where lead time variability is elevated. Engage suppliers early in the design process to secure preferred placement and align on contingency plans for material availability. In a market where performance and resilience increasingly determine selection, procurement decisions should reflect both immediate cost considerations and long-term system-level value.
Moving From Insight to Action
The power inductor market is expanding on the strength of electrification, digitalization, and the relentless pursuit of higher efficiency in smaller footprints. Yet the path to capturing value in this environment is shaped less by aggregate growth figures than by the ability to navigate material volatility, meet application-specific performance requirements, and secure reliable supply in a concentrated competitive field. For leaders across manufacturing, investment, and procurement, the most consequential decisions will involve aligning product and sourcing strategies with the trends that are redefining selection criteria: efficiency-driven magnetics, supply chain diversification, and application-specialized differentiation.
Detailed segmentation data, regional demand profiles, and company-level assessments can sharpen these decisions further, particularly when tailored to specific product lines, target applications, and operating regions. Access to comprehensive market intelligence enables more precise portfolio planning, competitive positioning, and risk mitigation. For organizations seeking to translate these strategic themes into concrete actions, a full research report provides the granular data and customized analysis needed to support execution with confidence.
For detailed analysis of this topic, please visit the official page: Power Inductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Auto Dealer Software Market: How 7.8% CAGR and Web Platforms Reshape Growth
By pmarketresearch, 2026-09-21
The Auto Dealer Software Market: Strategic Trends and Commercial Opportunities Through 2032
The auto dealer software market has entered a phase of structural transformation, driven by technological maturation, regulatory pressure, and shifting dealership economics. Measured in USD millions, the market expanded from 143.5 in 2020 to approximately 190.8 in 2025, reflecting a compound annual growth rate of 7.8 percent across the 2020–2025 historical window. Forward projections indicate continued expansion, with revenue reaching 200.7 in 2026 and progressing toward 309.2 by 2032. This trajectory signals more than incremental growth; it reflects a market where software is no longer a back-office utility but a core operational and competitive layer for dealership networks.
Market concentration remains high, with the top three providers capturing roughly 68.5 percent of overall revenue and the top five accounting for approximately 75.0 percent. Such concentration suggests that scale, integration depth, and compliance infrastructure create durable moats, while also leaving meaningful room for specialized entrants targeting specific dealership segments or workflow niches. The revenue split across software types shows dealer management systems commanding the largest share, followed by CRM and marketing platforms, with additional categories rounding out the portfolio. Deployment models reveal a clear tilt toward web-based solutions, which now represent the majority of market value, while installed software maintains a substantial but gradually declining footprint. Regional allocations point to North America as the largest revenue base, with Europe and Asia Pacific forming the next tier of meaningful demand centers, and Latin America along with the Middle East and Africa representing faster-growing but smaller absolute markets.
These headline trajectories mask underlying friction. Dealerships and software providers are navigating a landscape where legacy operational assumptions are colliding with cloud economics, regulatory scrutiny, and changing consumer expectations. The following sections break down the core challenges, demand drivers, competitive positioning, and forward-looking signals that matter for executives planning technology roadmaps, capital allocation, or market entry strategies.
Market Conditions and Critical Inflection Points
The current market environment is shaped by a combination of steady top-line growth and intensifying operational pressure. Three issues stand out as particularly consequential for how the market will evolve over the next several years.
First, cybersecurity and operational resilience have moved from a compliance checkbox to a strategic imperative. A major disruption in mid-2024 involving a leading DMS provider accelerated industry-wide reassessment of backup systems, access controls, and incident response planning. Providers have since increased investment in SOC 2-aligned platforms and AI-assisted fraud detection, while dealership groups have grown more cautious about single-vendor dependency and data exposure. This shift is not merely defensive; it is reshaping procurement standards, contract terms, and the value proposition of platforms that can demonstrate stronger security and continuity guarantees.
Second, data privacy expectations and compliance requirements are increasing the cost and complexity of software deployment. Cloud-native systems require ongoing alignment with evolving consumer information handling rules, particularly as platforms integrate more deeply with financing, marketing, and OEM data flows. For dealership operators, this creates a tension between the desire for streamlined digital experiences and the need to maintain rigorous consent management, retention controls, and audit readiness. For software vendors, it raises the bar for product design, documentation, and continuous updates, especially in markets where regulatory expectations differ by region or customer segment.
Third, labor economics are altering the calculus of dealership operations. DMS platforms that incorporate AI automation can reduce manual data entry and F&I processing time by up to 50 percent, easing reliance on specialized staffing for routine workflows. This is attractive in an environment where dealerships face persistent pressure on per-unit profitability and operational consistency. At the same time, automation creates new expectations: staff must be retrained, workflows must be redesigned, and the value of software shifts from record-keeping toward decision support and exception handling. The dealerships that benefit most are those that treat automation as a process redesign opportunity rather than a simple cost-reduction tool.
Taken together, these inflection points suggest a market that is expanding not just in size but in strategic importance. Software choices increasingly affect compliance posture, operational resilience, staffing models, and customer experience quality. That makes technology decisions harder to reverse and more consequential for long-term performance.
Core Drivers Reshaping the Market
Several interconnected forces are accelerating adoption and redefining what software must deliver to remain competitive.
Insurance Agency Software Market
Technological innovation continues to be the most visible driver. AI-enabled analytics, workflow automation, and modular integration architectures are becoming baseline expectations rather than differentiators. The industry context indicates that open integrations and API partnerships with lenders and OEMs have expanded the ecosystem around dealer platforms, but they have also increased licensing costs for third-party connectors in integrated DMS deployments. This dynamic is pushing providers to balance flexibility with cost control, and it is encouraging dealership groups to evaluate total cost of ownership rather than focusing narrowly on upfront subscription pricing. Recent platform launches have emphasized unified customer data and real-time insights, reflecting a broader shift from siloed records to connected intelligence. For example, a major provider launched a customer data platform in early 2026 designed to unify fragmented customer information, followed shortly by a foundations suite offered with free implementation for existing DMS renewals. These moves illustrate how vendors are using data unification and onboarding incentives to deepen adoption and reduce switching friction.
Policy and regulatory conditions are reinforcing this technological push. Cybersecurity expectations have tightened across the sector, and industry-wide investment in enhanced defenses following major disruptions has raised annual compliance expenditures for providers. In parallel, data privacy compliance demands continuous alignment for cloud-native systems handling consumer information. The result is a market where security and privacy are competitive factors: platforms that can demonstrate robust controls, transparent data practices, and predictable update cycles gain credibility with larger dealership groups and institutional partners. Regulatory pressure also indirectly benefits more mature providers, since compliance overhead can be harder for smaller players to absorb at scale.
Demand-side behavior is changing as well. Consumers and corporate buyers increasingly expect seamless digital interactions across the sales, service, and financing journey, even when the final transaction still involves in-person or hybrid steps. Dealerships are responding by investing in CRM and marketing software that complements the core DMS, using digital tools to improve lead handling, follow-up consistency, and retention marketing. Industry context shows AI-enabled tools expanding into areas such as driver’s license validation and fraud detection within F&I processes, signaling a broader expectation that software should reduce risk and improve speed without adding administrative burden. For dealerships, the strategic question is how to connect front-end digital engagement with back-end operational systems without creating new data silos or compliance gaps.
Cost structures and operating models are also in flux. Automation is reducing certain manual workloads, but API licensing, compliance, and integration complexity can offset some of those gains. At the same time, leadership changes and expansion initiatives among key vendors indicate that firms are betting on growth beyond their existing customer bases, often by broadening product scope, improving usability, or strengthening partner ecosystems. These developments suggest that the market is moving toward a more layered value proposition: core DMS functionality remains essential, but differentiation increasingly comes from analytics, automation, security, and ecosystem connectivity.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small set of scaled incumbents and a broader field of specialized and emerging providers. The leading companies share a common anchor in dealer management systems, but they differ in architecture, ecosystem strategy, and target customer segments.
CDK Global has reinforced its position through a combination of platform expansion, data unification, and adoption incentives. Its integrated dealership experience platform spans core sales, service, parts, finance, and accounting modules, with AI-driven analytics and open integrations. Recent activity includes the launch of a customer data platform for real-time insights, the introduction of a foundations suite with free implementation for existing DMS renewals, and a major industry event showcasing AI enhancements and expanded payment-related capabilities. These moves point to a strategy centered on deepening existing relationships, reducing churn risk, and making the platform more central to dealership data and workflow decisions.
Reynolds and Reynolds continues to compete through a comprehensive retail management system that covers inventory, customer management, and compliance tools. Its positioning emphasizes operational breadth and dealership-wide process support, which appeals to groups seeking a unified operational backbone. Dealertrack has carved out a strong niche around cloud-based DMS with a focus on F&I, digital contracting, and AI automation for deal closing and fraud reduction. Its recent introduction of AI-enabled driver’s license validation and expanded fraud detection for F&I processes underscores a strategy that ties technology directly to risk management and transaction efficiency. Cox Automotive, through its connected offerings, emphasizes AI-powered workflows and digital retailing tools, aligning DMS components with broader marketplace and retail technology ecosystems.
A second layer of competitors targets usability, small-to-medium dealer segments, and customer-service-centric relationships. Auto/Mate supplies a DMS focused on streamlined sales, service, finance, and accounting, with an emphasis on free upgrades and service responsiveness. Autosoft provides dedicated DMS platforms that stress ease of use, 360-degree dealership visibility, and automation for smaller dealers, and it recently appointed a new CEO to drive expansion beyond its current customer base. DealerSocket partners with Auto/Mate to offer connected DMS solutions, pairing integration with award-winning support and ongoing enhancements. Dominion Dealer Solutions supplies a VUE DMS aimed at comprehensive dealership management, including inventory and operational tracking. This segment of the market is more fragmented, and its growth often depends on delivering clear operational simplicity, responsive support, and cost-effective deployment models.
The market is evolving along three overlapping directions. Consolidation remains attractive at the top, where scale in data, compliance, and integrations strengthens competitive positioning. Differentiation is intensifying around AI, automation, security, and ecosystem breadth, with vendors competing to prove that their platforms can reduce friction in both routine operations and high-stakes processes like F&I. At the same time, new entrants and partner-led models continue to emerge in niches such as usability-focused DMS, specialized CRM and marketing layers, and region-specific compliance or deployment requirements. The practical implication is that buyers face a trade-off between the stability and depth of large platforms and the agility or specialization of smaller offerings, while vendors must decide whether to compete on breadth, depth, ecosystem access, or service quality.
PW Consulting Information & Electronics Research Center
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 period, several trends are likely to shape both market growth and opportunity allocation.
A first trend is the shift from modular software to integrated intelligence. As customer data platforms, AI analytics, and automated workflows become more embedded in dealer systems, the value of software will increasingly depend on how well it connects data across sales, service, parts, finance, and marketing. This creates opportunities for providers that can reduce fragmentation while preserving flexibility through open integrations. It also raises the stakes for dealerships that rely on patchwork systems, since disconnected data limits the benefits of automation and makes compliance and reporting more burdensome.
A second trend is the continued rise of cloud-native, web-based deployment as the dominant operating model. Web-based solutions already represent the larger share of market value, and their advantages in updates, remote access, integration, and scalability reinforce that position. The commercial implication is that procurement will increasingly favor platforms with strong security credentials, predictable data-handling practices, and clear upgrade paths. It also means that providers must manage ongoing compliance and integration costs, including the rising expense of third-party connectors and licensing arrangements with lenders and OEMs.
A third trend is the growing strategic role of automation in dealership economics. Reducing manual processing in F&I, inventory handling, and customer follow-up can meaningfully lower specialized staffing needs and improve consistency, but the payoff depends on workflow redesign and change management. The opportunity lies not just in adopting automation tools, but in reorganizing processes so that staff can focus on exception handling, relationship management, and higher-value decisions. The risk is that automation is treated as a plug-in cost saver without rethinking the surrounding operating model, which can blunt benefits and create new bottlenecks.
These trends carry uncertainty. Cybersecurity and data privacy requirements will continue to evolve, and compliance costs may rise further, particularly for providers operating across multiple jurisdictions. API licensing and integration expenses could pressure margins or slow ecosystem expansion if connector costs become a barrier. In addition, market concentration gives leading vendors significant influence over standards and pricing, which may limit the room for smaller players unless they serve clearly defined segments or offer distinctive workflow advantages. For investors and corporate strategists, the key is to distinguish between durable structural demand for connected, secure, automated dealer software and short-lived features that may be quickly commoditized.
Action Guidance for Decision-Makers
The strategic implications vary by role, but several priorities apply across the market.
Real Estate Software Market
For manufacturers and OEM-affiliated teams, the priority is to align technology partnerships with the broader retail experience strategy. As dealership software becomes more central to data flow, digital retailing, and compliance, OEM relationships with DMS and adjacent platforms can influence everything from inventory visibility to customer journey consistency. It is worth evaluating how open integrations, data-sharing models, and security expectations affect the long-term scalability of retail partnerships, rather than treating software selection as a purely dealership-level decision.
For investors, the most important signal is that growth is being driven by integration, automation, and compliance rather than by simple subscription expansion. That favors businesses with strong security posture, credible data unification capabilities, and sustainable ecosystem economics. At the same time, rising licensing costs, compliance expenses, and concentration risk argue for careful scrutiny of unit economics, customer retention dynamics, and the durability of differentiation. In a market where top providers hold a large share, incremental advantages in analytics, fraud controls, and workflow automation may matter more than headline feature counts.
For dealership groups and procurement teams, the practical question is total value rather than initial price. A platform that reduces manual processing, strengthens compliance readiness, and connects customer and operational data can create more value than one that appears cheaper but leaves workflows fragmented. Procurement decisions should weigh security certifications, integration costs with lenders and OEMs, support quality, and the feasibility of workflow redesign during implementation. It is also prudent to assess continuity and backup capabilities, given the sector’s heightened focus on operational resilience following recent disruptions.
Across these audiences, the value of detailed market intelligence lies in translating broad trends into segment-specific decisions. Revenue trajectories, deployment shifts, competitive moves, and compliance dynamics all interact differently across dealership size, region, and operational model. A fuller picture of these interactions, including granular segmentation and tailored strategic scenarios, can be found in the complete research report, which expands on the market structure, competitive dynamics, and decision frameworks discussed here.
For detailed analysis of this topic, please visit the official page: Auto Dealer Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Image Editing Software Market 2026: Beyond the 6.98% CAGR Growth Story
By pmarketresearch, 2026-09-21
The Image Editing Software Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The image editing software market has evolved from a niche desktop utility into a core component of digital content infrastructure, with global revenue reaching USD 206.85 million in 2025 and projected to expand to USD 335.5 million by 2032. The sector is on a steady growth trajectory, underpinned by a compound annual growth rate of 6.98 percent across the 2026-2032 forecast period, reflecting sustained demand for visual asset creation, modification, and optimization across professional and consumer segments. Historical momentum from 2020 through 2025 has been characterized by consistent expansion, with the market moving past the USD 145 million mark at the start of the cycle and steadily climbing as digital content workflows became deeply embedded in marketing, media, e-commerce, and individual creator economies.
Despite the favorable trajectory, the industry is confronting a set of structural challenges that are reshaping competitive dynamics and forcing players to rethink value delivery. First, the rapid integration of generative artificial intelligence is compressing traditional differentiation. Tools that once competed on feature depth, precision, and workflow specialization are now being benchmarked against AI-assisted editing capabilities that lower the skill threshold and accelerate output velocity. This shift is not merely a feature arms race; it is redefining what customers consider essential versus optional, and it is altering willingness to pay across segments.
Second, the subscription and licensing model continues to mature, creating both revenue stability and friction. Continuous access, cloud synchronization, and frequent update cycles have become table stakes for professional and mid-market users, yet pricing sensitivity remains acute in price-conscious regions and among solo creators. The balance between recurring monetization and perceived value is increasingly delicate, particularly as alternative licensing approaches and one-time purchase models regain relevance in certain niches.
Third, the market is navigating an open-source versus commercial software tension that is more nuanced than a simple price competition. Free and community-driven alternatives have improved markedly in stability, interface design, and compatibility, narrowing the functional gap for a broad range of editing tasks. This progression is not erasing commercial demand, but it is raising the bar for what paid solutions must deliver in terms of speed, integration, and advanced creative control.
For executives and investors, these challenges are not purely headwinds. They are signals of where value is migrating: toward workflow efficiency, intelligent automation, ecosystem lock-in, and specialized high-precision tools. Companies that treat these pressures as isolated product issues risk missing the broader reallocation of buyer expectations and spending patterns.
Key Drivers Reshaping the Market
Several interlocking forces are propelling the market forward, and their combined effect is more consequential than any single trend. Understanding how these drivers interact is essential for anticipating where growth will concentrate and which bets will pay off.
Technology Innovation and AI-Enabled Workflows
Generative and assistive AI has moved from experimental novelty to foundational capability in image editing. Modern tools now embed functions such as intelligent object removal, content-aware fills, style transfer, automated retouching, and template-driven composition directly into the editing interface. This reduces the time required to produce polished visual assets and widens the addressable user base by lowering technical barriers. The commercial implication is significant: software providers that can fuse AI features with predictable, repeatable workflows are gaining traction with both professional users seeking efficiency and casual users seeking quality without steep learning curves. The trajectory is not simply about adding more AI features; it is about orchestrating them into coherent, reliable editing experiences that fit into broader content pipelines.
Video Editing Software Market
Policy and Regulatory Environment
As image editing tools become more capable and more embedded in commercial content creation, questions around authenticity, provenance, and responsible use are gaining prominence. Regulatory attention to synthetic media, copyright safeguards, and disclosure norms is intensifying in several markets, indirectly influencing product roadmaps and go-to-market strategies. Software vendors are increasingly expected to provide controls for tracking edits, managing asset rights, and ensuring compliance with platform and jurisdictional requirements. This environment favors providers that can offer not just editing power but also governance-friendly features, auditability, and clear usage policies. In practical terms, trust and transparency are becoming part of the product value proposition rather than afterthoughts.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is expanding beyond traditional photography and graphic design into a broader set of visual content needs. Enterprises require rapid production of marketing assets, social media imagery, product visuals, and localized creative variations, while individual creators and small businesses seek affordable tools that can deliver professional-looking results without complex setups. This dual demand is pushing the market toward flexible delivery models. Users increasingly expect cross-device access, collaborative workflows, and the ability to move seamlessly between desktop, browser, and mobile contexts. The result is a widening emphasis on accessibility, speed, and integration, with buyers prioritizing tools that reduce context switching and align with existing content stacks.
PW Consulting Information & Electronics Research Center
Cost Structure and Supply-Side Dynamics
The economics of software delivery continue to shift. Development and maintenance costs remain significant, but distribution and update mechanisms have become more efficient, especially for cloud-connected and web-based solutions. At the same time, the broader software publishing ecosystem in adjacent areas such as design, editing, and rendering has experienced notable growth, reflecting the expanding value of digital creative tools and the talent required to build and support them. Cost pressures are not only about development expense; they also relate to the investment needed to sustain competitive AI capabilities, compatibility across formats, and frequent interface and performance improvements. Providers that can manage these costs while preserving feature quality and reliability are better positioned to defend margins and fund ongoing innovation.
Competitive Dynamics and Strategic Positioning
The market is defined by a mix of established commercial vendors, focused niche players, and increasingly capable open-source alternatives. Competitive advantage is no longer determined solely by the breadth of editing tools; it now hinges on workflow design, integration, reliability, and the ability to align product strategy with clear user segments.
Adobe Systems Inc. remains a central force in the space, anchored by a portfolio that spans professional editing, consumer-facing tools, and increasingly sophisticated generative AI capabilities. Its strategic strength lies in combining a familiar, deeply adopted editing environment with a continuous delivery model that keeps tools current and connected to broader creative ecosystems. The company’s recent emphasis on enhanced generative features, templates, and simplified workflows illustrates a deliberate push to serve both advanced users and those seeking quicker, guided editing paths. This dual-track approach helps sustain relevance across professional and mainstream audiences while reinforcing recurring engagement.
Corel Corporation maintains a differentiated position through vector and photo editing tools that appeal to users prioritizing design flexibility and standalone editing workflows. Its value proposition is rooted in practical creative control and a product family that serves both commercial and individual users. Serif (Europe) Ltd. has reinforced its relevance by offering standalone professional tools with a strong focus on performance and direct purchase appeal, and its decision to make a combined photo, vector, and layout application freely available broadened accessibility while preserving a professional-grade feature set. This move highlights a strategic willingness to reshape reach and adoption patterns without abandoning the core professional audience.
Other players illustrate how specialization and targeted positioning can sustain relevance. ACD Systems International Inc. and ON1, Inc. continue to serve professional and enthusiast segments with tools oriented toward efficient photo editing and batch processing. CyberLink Corporation bridges photo editing with broader multimedia capabilities, while Skylum Software emphasizes AI-assisted photo enhancement. ZONER, Inc. and Capture One ApS represent more focused offerings that cater to specific workflow needs, including RAW processing and studio-oriented editing. GNU Image Manipulation Program Team maintains a globally recognized open-source alternative, and its recent version releases have underscored steady improvements in stability, interface design, and usability, reinforcing the competitive pressure on commercial products to justify premium positioning through tangible workflow and performance advantages.
The broader competitive landscape is evolving along several axes. Consolidation pressure exists where integrated ecosystems and cross-product synergies can reduce churn and increase switching costs. At the same time, fragmentation persists as specialized tools continue to thrive for high-precision, domain-specific use cases. New entrants and open-source projects are not merely mimicking legacy tools; they are increasingly offering modern interfaces, better compatibility, and lighter-touch installation experiences that appeal to users who value simplicity and transparency. The net effect is a market where incumbents must defend their positions through continuous innovation and ecosystem strength, while challengers can win by serving underserved workflows or by offering a more streamlined, cost-effective experience.
For decision makers, the key takeaway is that market leadership is increasingly a function of how well a vendor balances breadth, depth, ease of use, and trust. Product features alone are no longer enough; the surrounding experience—updates, compatibility, integration, and clarity of licensing—plays a decisive role in adoption and retention.
Forward-Looking Trends and Commercial Implications
Looking ahead to the next three to five years, the market is likely to be shaped by a small number of high-impact trends that will influence product strategy, pricing, and partnership decisions.
One major trend is the deepening integration of AI as a collaborative layer rather than a standalone feature. Editing tools will increasingly act as co-pilots that suggest edits, automate repetitive tasks, and adapt to user intent, while still leaving creative control in human hands. The commercial opportunity here lies in building workflows that are both faster and more predictable, especially for teams that need to produce large volumes of visual assets with consistent quality. Companies that can demonstrate measurable time savings, reduced rework, and reliable output will have a compelling case across professional and enterprise segments.
A second trend is the continued expansion of cross-platform and browser-based editing as users expect fluid movement between devices and environments. This is not just about convenience; it is about fitting image editing into broader content operations where assets are created, reviewed, and deployed across multiple systems. The opportunity is for providers that can deliver consistent performance, seamless syncing, and integration with existing digital asset management and publishing tools. usability and interoperability will become stronger differentiators, especially for buyers evaluating total workflow value rather than isolated editing features.
A third trend is the growing importance of authenticity, rights management, and responsible use as edited and AI-assisted imagery becomes more prevalent in commercial and public-facing content. Software that offers clearer audit trails, asset provenance support, and configurable controls will be better positioned in environments where compliance and brand safety matter. This creates an opening for providers that can align product capabilities with governance needs, particularly in enterprise and regulated use cases.
These trends carry risk as well. Overreliance on AI features without corresponding attention to accuracy, consistency, and user control can erode trust. Pricing and licensing models that fail to align with perceived value may accelerate churn or push users toward alternatives. And as open-source and free tools continue to improve, commercial vendors will need to articulate a clearer reason for premium investment, whether through speed, precision, ecosystem integration, or specialized capabilities. The Uncertain factor is not whether these dynamics will intensify, but how quickly different segments will adopt new expectations and how sensitive they will be to price and complexity.
Actionable Guidance for Decision Makers
The most effective responses to these shifts depend on the role a stakeholder plays in the market. The following recommendations focus on practical priorities rather than generic advice.
- For software vendors and product leaders, prioritize workflow coherence over feature volume. AI and automation should be embedded in ways that make everyday editing faster, more reliable, and easier to learn, while preserving advanced control for users who need it. Investment should also extend to compatibility, performance, and update reliability, because these factors increasingly determine retention and referral in crowded markets.
- For investors and strategic buyers, focus on differentiation that is defensible in the face of AI democratization and open-source improvement. The most resilient opportunities are likely in segments where precision, speed, integration, or governance create meaningful switching costs. Watch for companies that can combine strong user experience with ecosystem reach and a licensing model that aligns with customer value, as these are the characteristics most likely to support durable growth.
- For procurement teams and enterprise buyers, evaluate tools against total workflow impact rather than feature checklists. Consider how well a solution integrates with existing content processes, how quickly teams can become productive, and whether licensing and update policies create predictable operating costs. Weigh the trade-offs between comprehensive commercial platforms and specialized or lower-cost alternatives based on actual usage patterns, quality requirements, and internal skill levels.
The image editing software market is large enough and dynamic enough that generic assumptions can lead to missed opportunities. Detailed segmentation data, regional demand patterns, application-level revenue splits, and company-level positioning can materially sharpen strategy, whether the goal is product planning, market entry, partnership evaluation, or investment selection. Readers seeking a more granular view of market size by segment, competitive mapping, and forward scenarios can access the full research report for deeper detail and tailored interpretation.
Education Software Market
For detailed analysis of this topic, please visit the official page: Image Editing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Interior Design Market: Why 6.5% CAGR and $331B by 2032 Changes Everything
By pmarketresearch, 2026-09-21
The Interior Design Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Context and Structural Challenges
The global interior design market has maintained a steady upward trajectory over the past half-decade, with total revenue expanding from approximately USD 157.5 billion in 2020 to an estimated USD 211.5 billion in 2025. The forward outlook points to continued expansion through 2032, supported by a projected compound annual growth rate of 6.5 percent. While the headline figures convey resilience, the underlying composition tells a more nuanced story. Residential-driven demand accounts for the largest share of value, commercial and institutional segments together form a substantial second pillar, and regional activity spans mature markets in North America and Europe alongside fast-growing corridors across Asia Pacific, Latin America, and the Middle East and Africa. This breadth provides a foundation of diversified demand, but it also masks pockets of volatility that are reshaping how firms plan capacity, pricing, and channel strategy.
The first structural challenge is cost volatility across materials and labor. Escalating input prices and tariff-driven distortions have placed margin pressure on manufacturers and contractors alike, while also complicating budgeting for end clients. Professional bodies have flagged rising material costs and widespread tariffs as factors that are directly reshaping demand for interior design services and product pricing, with independent analysis of recent trade actions estimating a meaningful per-home cost impact for builders that ripples through furnishing supply chains. At the same time, labor market tightness—paired with elevated housing prices in several regions—has made it harder for practices to scale project delivery without compressing fees or stretching timelines. For executives, the operational question is no longer whether costs will fluctuate, but how to build pricing architecture, sourcing flexibility, and service models that can absorb shocks without eroding client trust.
The second challenge is the shifting regulatory and credentialing landscape. Interest in formalizing the profession has accelerated, with a growing number of states considering legislation related to licensing or registration of interior design practitioners, and one state reaching a milestone as the thirtieth to regulate the profession following a sunset review. These developments affect liability exposure, permissible scope of work, and competitive differentiation across jurisdictions. Firms that rely on unlicensed staff or cross-border service delivery must anticipate uneven rule sets, while brands that invest in credentialed talent can turn compliance into a trust signal. The practical implication is that market access, insurance requirements, and partnership structures are becoming more localized and more consequential than in prior cycles.
The third challenge is fragmentation in how value is captured. Despite the presence of category-leading companies, the top three operators account for roughly 18 percent of revenue and the top five for about 22 percent, indicating a broadly distributed market with room for consolidation as well as for niche specialization. That dispersion creates both opportunity and risk: it allows agile entrants to win in specific use cases or geographies, but it also means that price competition, channel conflict, and brand dilution can emerge quickly when demand softens. Leaders that convert scale into service depth, proprietary product systems, and integrated delivery tend to outperform in mixed cycles, while undifferentiated players face margin erosion.
Together, these dynamics create a market that is growing in aggregate yet demanding more discipline at the micro level. Executives should read the growth trajectory not as an invitation to expand indiscriminately, but as a reason to prioritize resilience, credentialing readiness, and strategic focus in the segments where they can sustain advantage.
2. Core Drivers Reshaping Demand and Supply
Technology and Digital Enablement
Digital workflows are moving from support functions to core value drivers. Generative design, parametric specification tools, and integrated visualization platforms are compressing the time from concept to approval, which is particularly valuable in residential and commercial projects where client decision cycles can be protracted. More importantly, these tools are enabling firms to standardize repeatable elements while customizing high-impact spaces, improving both margin and client satisfaction. The same technologies support better inventory synchronization for product suppliers by aligning design intent with manufacturable options, reducing rework and last-minute substitutions. The practical takeaway is that technology investment is increasingly a margin and speed story: the firms that can deliver fast, high-fidelity options and keep specification accuracy high are winning a larger share of wallet in complex projects.
Policy and Regulatory Dynamics
Policy is becoming a more direct lever on demand and operating costs. Trade actions and material tariffs have altered the economics of building and furnishing products, pushing some procurement teams to re-evaluate sourcing footprints and specs. Regulatory attention to professional credentials is also changing the playing field, raising the stakes for firms that deliver design services under varying legal regimes. Rather than treating these as external noise, leading organizations are incorporating policy scenarios into their planning: they diversify supplier bases to reduce concentration risk, align service offerings with recognized credentials where regulation is tightening, and prepare documentation and compliance processes that can be scaled across jurisdictions. In short, policy predictability is now an asset to be managed, and the firms that institutionalize scenario planning around it are better positioned to protect margins when rules shift.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user priorities are evolving in ways that favor service-led value over transactional transactions. In residential contexts, homeowners and developers increasingly seek cohesive design systems that balance aesthetics, durability, and lifecycle cost, particularly as housing affordability pressures shape renovation versus move-up decisions. In commercial and institutional settings, organizations are recalibrating spaces for hybrid work, wellness, accessibility, and brand experience, which expands the scope of interior work beyond fit-out to include adaptive reuse and spatial programming. Awards, trade shows, and curated showcases continue to influence taste formation and accelerate the adoption of new styles, materials, and crafts; the steady cadence of global events across North America, Europe, and Asia underscores how quickly preference cycles can move and how important timely exposure is for brands aiming to stay relevant. For operators, the implication is that design value must be demonstrated through outcomes—usability, durability, speed, and emotional resonance—rather than through decoration alone.
Supply Chain and Cost Structure Realignment
The cost structure of interior products and services is being rebalanced by a combination of input volatility, logistics constraints, and labor economics. Builders and suppliers are absorbing higher baseline costs on key inputs, which cascades into product pricing and project budgets, while shortages of skilled labor raise the cost of execution and extend delivery windows. In response, many organizations are shifting toward regionalized sourcing, modular product platforms, and pre-configured systems that simplify installation and reduce on-site variability. Vertical integration is gaining renewed attention in certain categories because it can tighten quality control and improve lead-time reliability, though it also requires capital discipline and careful capacity planning. The strategic signal is clear: resilience and repeatability are becoming as important as design novelty, and supply chain choices are increasingly a competitive differentiator.
3. Competitive Landscape and Leading Strategies
Strategic Positioning of Key Participants
Several established players illustrate distinct routes to advantage in a fragmented market. Legacy-oriented product houses have leaned into brand portfolios that span heritage and contemporary aesthetics, allowing them to serve multiple price tiers while preserving prestige equity. Their strategic edge lies in breadth of offering—wallpapers, fabrics, ancillary interior products, and coordinated collections—that simplifies specification for designers and trade partners, and in the ability to refresh lines without abandoning recognizable franchises. Luxury lifestyle retailers, by contrast, compete on curation, service, and aspirational positioning, extending across furniture, textiles, lighting, bathware, and décor through multiple brand channels. Their advantage is the integration of high-end product with design advice and an experiential retail environment that supports higher price points and deeper client relationships. Vertically integrated furniture manufacturers combine custom-crafted production with design services and North American manufacturing, using that model to control lead times, quality, and cost-to-serve while offering complimentary design support that raises switching costs for customers. Large-scale flooring and interior panel producers anchor broad application coverage across furniture, cabinetry, and residential and commercial use, leveraging scale in materials and manufacturing to compete on specification frequency, consistency, and supply reliability.
Differentiation and Scope Decisions
Across these models, differentiation tends to emerge from a few recurring choices. The first is the depth of integration between product and service. Companies that pair specification-grade products with design assistance, installation guidance, or project coordination capture more of the project value and reduce the likelihood of substitution. The second is the balance between breadth and focus. Broad portfolios enable cross-selling and specifier convenience, but focused systems can command stronger loyalty in key segments if they solve a clear problem—durability, maintenance, speed of installation, or style cohesion. The third is the degree of vertical control. In an environment of cost and labor pressure, manufacturers with direct oversight of critical steps can protect quality and timing, while more decentralized players must invest in supplier governance and transparent communication to achieve similar outcomes. The practical lesson is that advantage rarely comes from a single attribute; it comes from a coherent system that aligns brand promise, product capability, service model, and supply discipline.
Evolution of the Market Structure
The competitive map is evolving along three lines. Consolidation is plausible where scale improves purchasing power, speeds innovation cycles, and expands distribution reach, particularly if larger players can integrate design services or channel access that smaller firms cannot easily replicate. Differentiation is intensifying in parallel, as segments such as sustainable interiors, wellness-focused spaces, and regionally specific aesthetics create demand for specialized expertise and materials, opening space for firms that can credibly claim depth in a niche. New entrants and adjacent players continue to test the boundaries of the market, using digital storefronts, direct-to-consumer channels, and subscription-style services to reach customers outside traditional trade paths. These movements do not point to a single end state; rather, they suggest a market in which the center will hold for broad-line players with strong systems, while edges will become more dynamic as specialists and digital-native models gain traction. Executives should therefore plan for a landscape that remains contested, with advantage determined by the clarity of positioning and the reliability of execution.
PW Consulting Information & Electronics Research Center
4. Forward Outlook: Trends and Commercial Implications (Next 3–5 Years)
Service-Integrated Product Systems Will Gain Share
Over the next few years, demand is likely to tilt toward offerings that combine repeatable product platforms with embedded design and specification support. Clients in both residential and commercial settings are seeking speed, certainty, and coherence, and they are willing to pay a premium when a solution reduces coordination risk and installation variability. Brands that can present curated systems—complete with sample libraries, digital specification tools, and clear installation sequences—will be better placed to capture project budgets and to defend margins against commoditization. The commercial opportunity lies in packaging: creating modular, specifiable systems that scale across use cases while retaining enough flexibility to meet local preferences. The risk is execution complexity, because systems that are too rigid can alienate designers, while systems that are too loose fail to deliver the promised consistency.
Credentialing and Compliance as Competitive Filters
The regulatory momentum around professional licensing and registration is expected to continue shaping how services are delivered and how firms are evaluated. As more jurisdictions formalize requirements, credentialed practitioners and organizations will gain an advantage in projects where liability, safety, and code interaction matter, and will be better positioned to partner with architects, contractors, and public-sector clients. This trend creates an opportunity for firms to use compliance as a trust asset, particularly in institutional and commercial work. The uncertainty is uneven adoption: if rules vary widely across regions, multi-market operators will need to maintain flexible staffing and documentation practices, and smaller firms may face higher relative compliance burdens. Executives should treat credentialing strategy as part of market access planning rather than as a back-office concern.
Industrial Design Market
Sustainability and Lifecycle Value Move From Messaging to Specification
Sustainability is becoming a practical filter in procurement, driven by a combination of client expectations, event-led trend diffusion, and a growing appetite for transparency in materials and processes. Dedicated showcases and trade events that emphasize sustainable interiors, alongside broader industry gatherings, indicate that eco-conscious design is moving from a marketing theme to a specification criterion, especially in commercial and institutional projects where operating costs and reputational risk are salient. The commercial implication is that firms able to provide clear, verifiable information on material sourcing, durability, maintenance, and end-of-life options can win preference in selection processes and reduce perceived risk for buyers. The caveat is that credibility matters: claims that cannot be substantiated may erode trust quickly, and the cost of verification can be a barrier for smaller suppliers unless they align with recognized standards or partner with testing and certification bodies.
5. Strategic Implications for Decision-Makers
For manufacturers and product suppliers, the priority is to reduce variability and increase specifiability. That means investing in modular platforms and coordinated collections that simplify selection for designers, expanding digital tools that connect design intent to manufacturable options, and hardening supplier governance to manage input volatility and lead-time risk. Where vertical integration is feasible, it should be pursued with clear attention to capital efficiency and capacity utilization; where it is not, stronger transparency and contingency planning with upstream partners become essential. The goal is to make it easier for the market to choose your products repeatedly, which in turn supports more predictable demand and better pricing power.
For investors, the most attractive exposure is likely to be found where service depth, credentialing readiness, and supply resilience compound rather than where growth is pursued through breadth alone. Categories and platforms that can demonstrate repeat specification, high switching costs through design services, and credible sustainability credentials are better positioned to sustain margins across cycles. Due diligence should focus on the operating model behind the headline momentum: how pricing responds to input shocks, how lead times are controlled, and how the firm plans for a more fragmented regulatory environment. Capital that supports operational discipline and credible differentiation is more likely to outperform than capital that simply chases segment tailwinds.
Worldwide Marine Interiors Market
For procurement and design leadership, the strategic task is to convert volatility into a negotiation advantage by diversifying sourcing, favoring specifiable systems that reduce rework, and aligning project timelines with realistic labor and material availability. Building internal criteria that reward durability, maintenance ease, and verifiable sustainability can lower total cost of ownership and reduce the risk of reactive substitutions. At the same time, keeping a close watch on regulatory changes in relevant jurisdictions will help avoid eligibility or liability surprises as projects scale across regions.
Keeping pace with a market that is both expanding and fragmenting requires current, granular visibility into how segments, regions, and company strategies are evolving together. Detailed segmentation data, competitive benchmarks, and tailored scenario planning can turn broad trends into concrete choices about where to invest, what to standardize, and which risks to hedge. Readers seeking a fuller picture of the subsegments, regional nuances, and company-level dynamics underpinning this analysis can access the complete research report for deeper data and customized recommendations.
For detailed analysis of this topic, please visit the official page: Interior Design Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com