

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Power Inductors Market: Why 5.0% CAGR and Automotive Demand Redefine Growth by 2032

Navigating the Power Inductors Market: Strategic Trends and Commercial Opportunities Through 2032
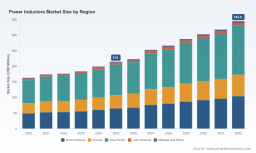
The power inductor market has entered a phase of steady, structurally supported expansion. From a global revenue base of approximately 163.15 million in 2020, the sector reached 215.0 million by 2025, reflecting consistent demand across electrified and digitized industries. Forecasts extending through 2032 project a trajectory toward 344.8 million, anchored by a compound annual growth rate of 5.0 percent. This growth is not merely cyclical; it reflects enduring shifts in power management architecture, vehicle electrification, and the miniaturization of high-performance electronics. Yet beneath the headline figures lies a complex landscape shaped by material constraints, regulatory realignments, and intensifying competition. For executives, investors, and procurement leaders, understanding these dynamics is essential to positioning for sustainable returns.
The market’s expansion has been broad-based, with Asia Pacific representing the largest regional footprint, followed by North America and Europe. Demand spans multiple application domains, with automotive and consumer electronics anchoring volume, while industrial and specialized sectors contribute incremental growth. Product segmentation reveals a clear preference for wire-wound configurations, though multilayer chip, thin film, and specialized alternatives continue to capture niche requirements driven by size, frequency, and thermal constraints. The competitive environment remains moderately concentrated, with the largest three players commanding a combined share near 64 percent and the top five approaching 72 percent. This concentration reflects the technical barriers, qualification cycles, and scale economics that characterize power magnetics, but it also signals that margin pressure and differentiation are increasingly determined by design expertise, supply chain resilience, and application-specific engineering support.
Core Challenges and Inflection Points
Despite the favorable growth trajectory, the industry faces structural headwinds that will shape competitive outcomes over the next several years. First, raw material volatility and supply concentration are reshaping cost structures and lead time predictability. Copper prices on the London Metal Exchange fluctuated between 8,200 and 10,500 U.S. dollars per ton in 2025, directly influencing the economics of wire-wound inductor production. At the same time, rare-earth export quotas introduced in early 2025 extended lead times for manganese-zinc ferrite from eight to sixteen weeks, while China’s control of roughly 70 percent of manganese-zinc ferrite capacity has concentrated supply risk for core materials. These dynamics are not transient pricing issues; they reflect geopolitical and policy-driven constraints that require proactive sourcing strategies and material substitution exploration.
Second, the demand environment is shifting faster than traditional qualification cycles can accommodate. Automotive electrification and high-efficiency power conversion in consumer electronics are pushing inductors into higher current, higher frequency, and wider temperature envelopes. Designers increasingly require components that minimize core losses, reduce magnetic field radiation, and maintain stability under thermal stress. Suppliers that can deliver shielded, low-resistance, and vehicle-grade solutions are gaining preferential placement in next-generation designs, while those reliant on commodity-grade offerings face margin compression and substitution risk.
Third, supply chain bottlenecks and import-export regulations have compounded availability challenges. Geopolitical tensions and evolving trade controls in 2025 increased friction across logistics networks, affecting the timely delivery of both raw materials and finished magnetics. For manufacturers and system integrators, this translates into a need for dual-sourcing, buffer inventory strategies, and closer collaboration with suppliers that offer transparent lead time management and regional manufacturing footprints.
PW Consulting Information & Electronics Research Center
Key Drivers Shaping Market Trajectory
Technological Innovation and Performance Boundaries
Innovation in power inductor design is being driven by the simultaneous requirements of higher efficiency, smaller form factors, and robust thermal performance. Shielding technology has become a critical differentiator, particularly in applications where electromagnetic interference must be minimized without sacrificing saturation current or heating capability. Recent product introductions illustrate how suppliers are pushing these boundaries. In April 2025, a major manufacturer added four new shielded power inductor series engineered for high heating and saturation current while reducing magnetic field radiation, addressing the needs of compact power supplies and automotive modules. Later that year, another supplier expanded its portfolio with ultra-low loss shielded power inductors featuring ultra-low inductance values starting from 40 nanohenries, specifically targeting DC-DC converter applications where switching efficiency and transient response are paramount.
Chip Power Inductor Market
Parallel advancements in core materials and winding techniques are also reshaping performance envelopes. Flat-wire molded power inductors introduced in late 2025 demonstrated exceptionally low direct current resistance, with values as low as 4.8 milliohms, and extended temperature ranges that support demanding industrial and automotive environments. These developments reflect a broader trend: power inductors are no longer commodities selected primarily on price, but engineered components whose electrical, thermal, and mechanical characteristics directly influence system-level efficiency and reliability. For design teams, this means that early supplier collaboration and application-specific characterization are becoming integral to product development cycles.
Policy and Regulatory Environment
Regulatory and policy forces are exerting both constraints and opportunities across the value chain. On the materials side, export quotas and trade controls have lengthened lead times for key ferrite and metal-based core materials, prompting manufacturers to reconsider inventory models and qualification pathways. Nickel price fluctuations, influenced by Indonesian export policy shifts in 2024 and 2025, have further affected the cost structure of powder core inductors, adding another layer of variability to procurement planning. These policy-driven dynamics are encouraging regional diversification of supply and increased interest in alternative material architectures where feasible.
On the demand side, regulatory emphasis on energy efficiency, emissions reduction, and vehicle electrification is reinforcing long-term adoption of high-performance power magnetics. Automotive standards and industrial efficiency mandates are pushing system designers toward components that reduce losses across broader operating ranges, which in turn elevates the importance of inductors with low core loss, stable inductance under DC bias, and proven reliability under vibration and thermal cycling. Compliance-driven design choices are therefore acting as a structural tailwind, particularly in segments where qualification rigor creates meaningful barriers for new entrants.
Demand-Side Shifts in Consumer and Industrial Behavior
Demand patterns are being reshaped by the convergence of electrification, digitalization, and compact power architecture. Automotive applications continue to dominate volume expectations, driven by the proliferation of electric drivetrains, onboard power management, and auxiliary systems that require reliable, high-current magnetics. Consumer electronics remain a core growth engine, with increasing power demands in charging infrastructure, portable devices, and smart home equipment pushing designers toward miniaturized, high-efficiency inductors that can operate at higher switching frequencies without sacrificing thermal stability.
Industrial applications, while smaller in relative volume, are experiencing incremental gains as automation, renewable energy systems, and smart manufacturing equipment require robust power conversion components. Across these segments, a common theme is the shift from off-the-shelf selection to application-engineered solutions. System architects are increasingly evaluating inductors based on integrated performance metrics—efficiency over temperature, saturation behavior, electromagnetic compatibility, and mechanical resilience—rather than nominal inductance and footprint alone. This shift rewards suppliers that can provide comprehensive technical support, design-in documentation, and fast turnaround on custom variants.
RF Inductors Market
Supply Chain and Cost Structure Evolution
Cost structures are being redefined by material volatility, manufacturing scale, and the growing importance of regional supply resilience. Copper and nickel price fluctuations, combined with extended lead times for ferrite materials, have heightened the need for dynamic sourcing and hedging strategies. Manufacturers that operate multiple production sites or maintain diversified supplier networks are better positioned to absorb shocks and maintain delivery continuity. At the same time, the premium on engineered performance is creating opportunities for suppliers that can balance cost efficiency with technical differentiation.
The trend toward flat-wire construction, advanced shielding, and precision winding illustrates how manufacturing process improvements can simultaneously reduce resistance, improve thermal handling, and support higher volume consistency. These process advancements are not merely incremental; they enable new performance tiers that align with the requirements of modern power conversion architectures. For procurement leaders, this underscores the value of evaluating total cost of ownership—including efficiency gains, qualification risk, and supply reliability—rather than unit price in isolation.
Competitive Landscape and Leading Strategies
The competitive field in power inductors is anchored by a mix of established global manufacturers and specialized producers, many of which have built defensible positions through application expertise, material know-how, and deep design-in relationships. Leading participants span North America, Europe, and Asia, with Japanese and U.S. firms historically strong in wire-wound and multilayer technologies, while European manufacturers have emphasized precision engineering and automotive-grade qualification. Chinese suppliers are expanding their footprint, particularly in vehicle-grade and high-current segments, leveraging scale and rapid product iteration to capture design opportunities in both domestic and export markets.
Strategic differentiation among top players increasingly hinges on three pillars. The first is performance engineering: the ability to deliver shielded, low-loss, high-saturation components that meet the thermal and electromagnetic requirements of modern power systems. Recent product announcements from multiple leading firms demonstrate a clear focus on reducing magnetic field radiation, lowering DC resistance, and expanding inductance ranges to cover ultra-low values for high-frequency converters. These capabilities are not merely technical achievements; they directly influence design wins in automotive, consumer, and industrial applications where efficiency and reliability are non-negotiable.
The second pillar is application-specific support. Suppliers that provide robust design tools, characterization data under DC bias and temperature, and rapid responsiveness to custom requirements are gaining advantage in qualification-heavy segments. This is especially relevant in automotive and industrial markets, where validation cycles are long and substitution costs are high. Companies that invest in technical marketing, reference designs, and close collaboration with system architects are better positioned to secure early design-in placement and sustain volume as platforms move into production.
The third pillar is supply chain resilience. In an environment marked by material volatility and extended lead times for core materials, manufacturers with diversified sourcing, regional production capabilities, and transparent inventory management are increasingly favored by procurement teams. This dynamic is reinforcing a preference for suppliers that can demonstrate continuity risk mitigation, including dual-sourcing of critical materials and flexible manufacturing footprints. As a result, competitive advantage is shifting from price leadership alone to a broader value proposition encompassing technical performance, qualification support, and delivery reliability.
The market structure is evolving along two converging paths. On one hand, concentration among the top players reflects the scale and expertise required to compete in high-performance segments, where R&D investment, qualification infrastructure, and global distribution networks create meaningful barriers. On the other hand, fragmentation persists in specialized niches where custom winding, non-standard footprints, and application-tailored materials enable smaller manufacturers to serve specific customer needs. New entrants and regional suppliers are gaining traction in vehicle-grade and high-current categories, often by combining aggressive pricing with focused engineering support. Over the next several years, the landscape is likely to see selective consolidation in commodity-adjacent segments alongside continued specialization in high-performance and application-specific domains.
Future Trends and Commercial Implications (2026–2032)
Trend One: Efficiency-Driven Magnetics Will Redefine Design Priorities
Over the next three to five years, power inductor selection will increasingly center on efficiency across broader operating envelopes. As switching frequencies rise and power densities increase, designers will prioritize components that minimize core and copper losses while maintaining stable inductance under DC bias and thermal stress. This trend will elevate the importance of advanced shielding, flat-wire construction, and core material optimization. Commercially, it creates opportunities for suppliers that can deliver validated performance data, application-specific characterization, and integrated design support. It also raises the stakes for manufacturers that rely on generic specifications, as efficiency-sensitive designs will favor components with demonstrable advantages in real-world operating conditions.
Trend Two: Supply Chain Diversification and Material Strategy Will Become Competitive Essentials
Material concentration risks, export controls, and commodity price volatility will continue to shape procurement and production strategies. Buyers and manufacturers alike will pursue dual-sourcing, regional inventory buffers, and alternative material pathways where feasible. Suppliers that can offer transparency on lead times, provide contingency sourcing options, and maintain consistent quality across production sites will gain preference in qualification discussions. For investors and executives, this trend signals that resilience is becoming a value driver in its own right, influencing both customer selection and long-term margin stability. Companies that proactively address material risk through supplier diversification, strategic stocking, and technical substitution research will be better positioned to sustain growth through cycles of volatility.
Trend Three: Application-Specialized Growth Will Outpace Generic Segments
Automotive and consumer electronics will remain the primary volume engines, but the most attractive margins will accrue to suppliers that can address specialized requirements within these segments. Vehicle-grade high-current inductors, ultra-low loss components for high-frequency converters, and compact shielded solutions for space-constrained designs are likely to command premium positioning. Meanwhile, industrial and niche applications will continue to generate steady demand, particularly where robustness, temperature tolerance, and electromagnetic compatibility are critical. The commercial implication is clear: growth will be strongest for manufacturers that align product roadmaps with application-specific performance needs and invest in the technical infrastructure to support design-in adoption. Generic, price-driven competition will face continued pressure as differentiation shifts toward engineered value and supply reliability.
These trends carry inherent uncertainties. Material policy changes could alter cost structures more abruptly than anticipated, and rapid shifts in automotive platform timing or consumer device cycles could affect demand pacing. Geopolitical friction and trade regulation may continue to introduce lead time variability, while technological substitution—such as alternative magnetics architectures or integrated power modules—could reshape component-level demand in specific applications. Navigating these uncertainties will require scenario-aware planning, flexible sourcing, and close alignment between product development and market intelligence.
Strategic Guidance for Decision Makers
For Manufacturers and Product Leaders
Align engineering roadmaps with the efficiency and thermal demands of next-generation power architectures. Prioritize shielded, low-resistance, and vehicle-grade capabilities where qualification cycles reward performance and reliability. Invest in application-specific characterization, design-in support, and rapid customization workflows to strengthen design-in placement and reduce time-to-qualification. Concurrently, build supply chain resilience through diversified material sourcing, regional manufacturing options, and transparent lead time management to mitigate raw material volatility and policy-driven constraints.
For Investors and Corporate Development Teams
Focus due diligence on suppliers that combine technical differentiation with supply chain robustness and clear application alignment. Evaluate total value rather than unit pricing, with attention to efficiency gains, qualification risk reduction, and delivery continuity. Monitor consolidation dynamics in commodity-adjacent segments and growth opportunities in vehicle-grade, high-current, and ultra-low loss categories. Companies that can sustain performance leadership while managing material and logistics risk are likely to capture disproportionate share in a moderately concentrated market.
For Procurement and Supply Chain Executives
Shift evaluation frameworks toward total cost of ownership, incorporating efficiency impact, thermal stability, qualification support, and supply reliability. Develop dual-sourcing strategies for critical materials and maintain buffer inventory where lead time variability is elevated. Engage suppliers early in the design process to secure preferred placement and align on contingency plans for material availability. In a market where performance and resilience increasingly determine selection, procurement decisions should reflect both immediate cost considerations and long-term system-level value.
Moving From Insight to Action
The power inductor market is expanding on the strength of electrification, digitalization, and the relentless pursuit of higher efficiency in smaller footprints. Yet the path to capturing value in this environment is shaped less by aggregate growth figures than by the ability to navigate material volatility, meet application-specific performance requirements, and secure reliable supply in a concentrated competitive field. For leaders across manufacturing, investment, and procurement, the most consequential decisions will involve aligning product and sourcing strategies with the trends that are redefining selection criteria: efficiency-driven magnetics, supply chain diversification, and application-specialized differentiation.
Detailed segmentation data, regional demand profiles, and company-level assessments can sharpen these decisions further, particularly when tailored to specific product lines, target applications, and operating regions. Access to comprehensive market intelligence enables more precise portfolio planning, competitive positioning, and risk mitigation. For organizations seeking to translate these strategic themes into concrete actions, a full research report provides the granular data and customized analysis needed to support execution with confidence.
For detailed analysis of this topic, please visit the official page: Power Inductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com