

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Dispatch Consoles Market: How 5 Strategic Shifts Drive 4.55% CAGR Through 2032

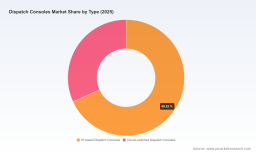
Strategic Shifts and Commercial Opportunities in the Dispatch Consoles Market
The dispatch consoles market stands at an inflection point. Over the past half-decade, global revenue has steadily climbed from approximately $144 million in 2020 to an estimated $183.4 million in 2025, reflecting a compound annual growth rate of 4.55 percent across the 2026 to 2032 forecast horizon. While the absolute figures may appear modest relative to broader technology markets, the structural importance of these systems to mission-critical operations places them at the center of public safety modernization, transportation coordination, and utility resilience. The market is evolving from a mature, hardware-centric ecosystem toward an IP-enabled, software-defined environment where interoperability, cloud integration, and intelligent automation are reshaping procurement priorities. Understanding where the market is heading requires looking beyond headline scale and examining the forces that will determine competitive advantage over the next several years.
Market Snapshot and Structural Pressures
The dispatch consoles market has demonstrated consistent expansion, with revenue growth underpinned by replacement cycles, expanding public safety mandates, and incremental adoption across transportation and utility verticals. The five-year trajectory shows resilience despite procurement headwinds in certain regions, and forecast models suggest continued upward movement as legacy architectures are phased out. What matters strategically, however, is not only the pace of growth but the shifting composition of demand. Budget-constrained agencies are balancing modernization with operational continuity, while technology vendors are reorienting portfolios around IP-based platforms that can scale across multiple sites and integrate with broader command and control ecosystems.
Key Challenges and Inflection Points
Three structural pressures are reshaping how dispatch console solutions are evaluated, funded, and deployed. The first is the wave of regulatory-driven replacement cycles. Agencies across multiple regions are retiring mid-2000s console infrastructure to comply with Next Generation 911 frameworks and evolving European Electronic Communications Code requirements. This creates a predictable demand pipeline, but it also introduces complexity around integration with legacy radio systems, training, and change management. Organizations that treat replacement as a simple like-for-like swap risk missing the opportunity to redesign workflows and improve interoperability from the ground up.
The second challenge involves the intersection of cybersecurity, reimbursement uncertainties, and stretched municipal budgets. Compliance requirements are adding cost layers to console modernization, which slows procurement velocity and extends planning horizons. Tight budgets are pushing agencies toward phased rollouts and shared services rather than large, upfront deployments. Vendors and integrators that can demonstrate clear total-cost-of-ownership advantages, staged implementation paths, and transparent security postures are better positioned to convert long consideration cycles into signed engagements.
The third pressure is infrastructural rather than financial. Scarcity of dispatch-ready spectrum bands below 1 GHz imposes a long-term cost constraint on network deployment for dispatch operations, with effects expected to persist for at least four years. This constraint influences both radio architecture decisions and console design, because bandwidth, coverage, and interconnection assumptions shape what can be reliably supported in the field. Console strategies that assume abundant low-band spectrum or ignore spectrum constraints risk misaligning with deployment realities.
Core Drivers Shaping Market Direction
Technology Innovation and Platform Consolidation
The market’s center of gravity is shifting toward IP-based dispatch consoles that unify voice, data, and command workflows within scalable software platforms. This transition is being accelerated by acquisitions and product integrations that bundle console software with broader service offerings. A notable example is Motorola Solutions’ acquisition of HyperYou, aimed at embedding agentic AI capabilities for call triage and unit dispatch recommendations. The move signals a broader trend in which console vendors are expanding from operator interfaces into decision-support systems that reduce cognitive load and accelerate response workflows. At the same time, Motorola’s purchase of Bell Canada’s land-mobile-radio business for CAD 675 million illustrates how vendors are assembling end-to-end domestic infrastructure stacks, pairing nationwide radio assets with console software to create integrated deployment models. Similar logic is visible across the competitive set, where IP-based console platforms are increasingly positioned as the integration layer between radios, mobile apps, mapping tools, and incident management systems.
On the public safety side, deployment activity is reinforcing the shift toward modern platforms. Hexagon’s contract with Kitsap 911 in Washington to deploy HxGN OnCall Dispatch with live mapping and mobile apps reflects the growing expectation that dispatch consoles should not only manage voice but also deliver geospatial context, mobile field connectivity, and workflow integration. City-level procurements are likewise moving toward vendor-supported, IP-based solutions, as seen in the City of Riverside’s authorization to purchase and install CommandCentral AXS Dispatch Console equipment. These decisions matter because they establish reference points for interoperability and scalability in comparable jurisdictions. Even indirect indicators, such as bid awards for dispatch console furniture, underscore that console replacement is a multi-component program rather than a single software purchase, which expands the scope of integration and service requirements.
Regulatory and Policy Environment
Policy is a durable driver because it creates compliance-linked refresh cycles and raises performance expectations for mission-critical systems. In North America and Europe, agencies are replacing aging consoles to meet Next Generation 911 and European Electronic Communications Code requirements, which elevates the importance of IP readiness, data interoperability, and regulatory-aligned workflows. These frameworks do more than force replacement; they nudge procurement toward solutions that can support future data-rich call handling, multi-agency coordination, and auditable records. Policy-driven demand is less cyclical than budget-dependent demand, which makes it an important anchor for long-term planning.
In Asia-Pacific, the dynamics differ. Smart-city programs are leapfrogging straight to cloud-native command centers for dispatch consoles, bypassing some of the legacy refresh patterns seen elsewhere. This creates an environment where initial deployments can be architected for scalability and centralized operations from the outset, rather than incrementally upgraded from circuit-switched foundations. The policy-led opportunity in this context is not only about selling console software but also about aligning with broader city platforms, data standards, and integration roadmaps that span transportation, utilities, and emergency response.
Demand-Side Shifts in Mission-Critical Operations
Demand is being shaped by operational expectations that extend well beyond traditional radio dispatch. Public safety organizations want faster call triage, better situational awareness, and more reliable interoperability across agencies and jurisdictions. Transportation authorities seek coordinated fleet dispatch that ties together operations centers, field units, and passenger information systems. Utilities and energy operators require dispatch tools that can support outage response, field crew coordination, and resilience planning under increasing weather-related stress. Government and defense customers continue to prioritize mission-critical reliability, while healthcare and industrial users are exploring dispatch console capabilities for internal coordination and emergency escalation.
These demand-side shifts favor solutions that can be tailored without becoming fragile. Configurable IP platforms, vendor-neutral architectures, and repeatable integration patterns are gaining relevance because they allow organizations to adapt the console to operational realities rather than forcing operations to adapt to a rigid console design. Procurement teams are increasingly evaluating the breadth of interoperability, the speed of onboarding new sites or users, and the ability to add analytics or mapping capabilities without a complete platform replacement. That is why the market is gradually tilting toward software-defined consoles that can evolve alongside end-user workflows.
Cost Structure and Supply-Side Realities
Cost dynamics are increasingly influenced by infrastructure constraints and the financial realities of public sector procurement. The scarcity of dispatch-ready spectrum below 1 GHz places pressure on network deployment cost and timeline, which in turn affects console bundling, coverage planning, and the economics of multi-site rollout. On the procurement side, reimbursement uncertainty and tight municipal budgets are extending purchase cycles, making agency modernization timelines less predictable. This environment rewards vendors and integrators that can reduce the friction of buying by offering modular deployment, clear modernization roadmaps, and demonstrable security and compliance value.
Cost is also being redefined by what consoles must now protect. Growing cybersecurity compliance costs are becoming part of the modernization calculus, especially for agencies that cannot absorb extended cutovers or post-deployment vulnerabilities. In practice, cybersecurity is no longer an add-on concern; it is a selection criterion that influences architecture decisions, vendor choice, and deployment sequencing. Supply-side providers that can normalize security considerations within the product and service package rather than treating them as a separate negotiation will have an easier path through stretched budgets.
Competitive Landscape and Leading Approaches
The competitive field is relatively concentrated, with the top three players accounting for roughly 35 percent of market share and the top five combining for about half. Concentration of this level indicates that scale, reputation, and ecosystem breadth matter, but it also suggests room for differentiated positioning by specialized vendors and regional players. Leadership is increasingly defined by the ability to combine console software with interoperability, integration, and operational support rather than by console features alone.
Strategic Positioning and Differentiation
Motorola Solutions stands out through an integrated operating model that spans command center software, IP dispatch consoles, and radio infrastructure. Its focus on CommandCentral AXS, the MCC 7500e IP dispatch console, and Avtec Scout voice dispatch consoles positions the company around public safety and enterprise operations that require tightly coordinated dispatch, CAD, and field communications. Recent acquisition activity reinforces this orientation: embedding agentic AI for call triage and unit dispatch recommendations points toward workflow automation, while the land-mobile-radio acquisition supports bundled nationwide infrastructure with console software. The strategic advantage here is the ability to offer a more complete deployment path for agencies that want fewer integration seams and stronger alignment between console software and the underlying communications fabric.
Zetron emphasizes mission-critical interoperability and scalability through MAX Dispatch and ACOM Command and Control IP-based dispatch consoles. Its positioning is particularly relevant for organizations that need reliable multi-agency coordination and a platform designed to scale across complex operational environments. InterTalk Critical Information Systems takes a vendor-neutral approach with its Dispatch Console System and Enlite solution, which appeals to public safety and mission-critical radio dispatch users seeking an exact-fit configuration without locking into a single radio vendor’s ecosystem. Avtec pursues a similar philosophy with Scout Enterprise voice and radio dispatch consoles, built as a vendor-agnostic, highly configurable IP platform for organizations that value flexibility across radio vendors and sites.
Omnitronics focuses on omnicore Express and Enterprise radio dispatch consoles for small to large organizations, with RoIP interoperability as a foundation for bridging radio and IP environments. EF Johnson Technologies positions itself around StarGate and interoperability dispatch consoles for P25 and public safety systems, which aligns with agencies prioritizing standards-based public safety communications. L3Harris contributes through Symphony and VIP Dispatch Consoles within VIDA integrated network solutions, tying console capabilities into a broader public safety dispatch network context. Cisco Systems brings IP-based radio and incident management through IPICS and Command T4, leveraging its broader networking and collaboration footprint to support dispatch and incident coordination workflows.
Hexagon Safety and Infrastructure focuses on HxGN OnCall Dispatch, now Octave OnCall, for computer-aided dispatch with live mapping and mobile apps. Its differentiation lies in marrying CAD functionality with geospatial visualization and mobile connectivity, which is increasingly valued in public safety operations where situational awareness directly affects outcomes. Siemens Convergence Creators addresses mission-critical command and control through AtoS Dispatch Solutions and Control Center offerings, reflecting a focus on structured control-room environments and large-scale operational coordination.
Push-To-Talk Market
How the Landscape Is Evolving
Three patterns are visible in the market’s evolution. The first is consolidation through acquisition, as larger players absorb adjacent capabilities such as AI triage, regional radio businesses, or CAD and mapping assets. This is likely to continue because integrated stacks reduce integration risk for large deployments and create cross-selling opportunities across console software, infrastructure, and analytics. The second pattern is product divergence between fully integrated, vendor-supported platforms and vendor-neutral, interoperable systems. Agencies with standardized radio environments may gravitate toward bundled solutions, while multi-vendor or multi-agency environments may favor neutral platforms that preserve choice and reduce dependency. The third pattern is the emergence of new entry angles, particularly from software, analytics, and cloud integration players who are not traditional console manufacturers but can influence selection through workflow automation, mapping, incident management, or cloud-native command center capabilities.
For buyers, this landscape means that competitive differentiation is less about raw console features and more about deployment model, interoperability, integration depth, and the ability to support modernization under budget and security constraints. For vendors, it means that winning configurations increasingly combine a strong core console with clear integration pathways, security credibility, and growing intelligence capabilities that improve operator effectiveness without complicating the user experience.
Forward Outlook: Trends That Will Shape Opportunity
From Console to Intelligent Command Interface
Over the next three to five years, dispatch consoles are likely to be evaluated less as isolated operator interfaces and more as command interfaces that connect voice, data, mapping, analytics, and decision support. The acquisition of AI-focused capabilities by major players suggests that triage assistance, recommendation engines, and workflow guidance will become part of the console value proposition. For buyers, this creates an opportunity to reduce operator overload and improve consistency under pressure. For providers, it creates a differentiation path based on measurable improvements in response coordination, call handling efficiency, and situational awareness. The commercial opportunity lies in solutions that can embed intelligence without sacrificing reliability, auditability, or ease of use in high-stress environments.
Cloud-Native and Regional Divergence in Deployment Models
A second trend is the divergence in deployment philosophies across regions. While North America and Europe are largely driven by replacement cycles tied to regulatory modernization, Asia-Pacific smart-city initiatives are more likely to adopt cloud-native command centers from the outset. This does not mean cloud will dominate everywhere immediately, but it does indicate that hybrid and cloud-managed configurations will increasingly compete with on-premises architectures, especially where centralized operations, multi-site visibility, and rapid scaling matter. The strategic opportunity for vendors is to offer flexible deployment models that can meet regional expectations without fragmenting product strategy. For buyers, the opportunity is to design modernization programs that can adapt to future operating models, data-sharing needs, and interagency coordination requirements.
A related opportunity is the expansion of console relevance beyond traditional public safety into transportation, utilities, government, healthcare, and industrial coordination. Transportation demand is already among the largest application segments, and utility and energy operations are likely to increase investment as resilience and outage coordination become more critical. The strategic case for cross-vertical expansion is not that every sector needs the same console, but that core IP-based dispatch capabilities can be adapted to sector-specific workflows with the right integration, configuration, and support model.
Infrastructure, Cyber, and Budget Uncertainty as Chronic Factors
The third trend is less optimistic but strategically important: infrastructure constraints, cybersecurity compliance costs, and budget pressure will likely remain persistent influences on procurement timing and solution design. Spectrum scarcity below 1 GHz imposes long-term cost constraints on network deployment for dispatch operations, and cybersecurity compliance will continue to shape what agencies can afford to modernize and how quickly. Reimbursement uncertainty and stretched municipal budgets will keep extending procurement cycles in parts of the market. These factors increase the value of phased deployment, modular upgrades, and clear financial and security justification. They also raise the risk of mismatch when vendors assume a faster pace of change than agencies can fund or operate.
The commercial implication is that success will depend on helping customers sequence modernization intelligently. Providers that can align console upgrades with radio, mapping, cybersecurity, and budget realities will be better placed to convert demand into deployments. Conversely, solutions that over-index on advanced features without addressing integration, security, or affordability may struggle to win in a market where procurement patience is limited.
Strategic Recommendations for Decision-Makers
For Console and Platform Manufacturers
Focus investment on interoperability, security-by-design, and workflow automation rather than only on interface enhancements. The most defensible positions will belong to platforms that can integrate cleanly across radio vendors, CAD and mapping tools, mobile apps, and incident management systems while maintaining clear security and compliance value. AI and decision-support features should be introduced as operators’ aids that demonstrably improve triage, prioritization, and coordination, with measurable outcomes rather than speculative capability claims. In parallel, maintaining flexible deployment options—including configurations that can align with cloud-native expectations in regions pursuing smart-city command centers—will broaden addressable demand without sacrificing reliability in mission-critical settings.
Worldwide Portable Gaming Consoles Market
For Investors and Strategic Partners
Prioritize companies with credible paths to integrated stacks, regional scale, and interoperability leadership. Acquisition-driven expansion of console, radio, CAD, mapping, and AI capabilities is likely to continue, and the value created will depend on successful integration, cross-selling, and the ability to win complex multi-agency or multi-site deployments. Pay close attention to cybersecurity posture, spectrum-aware deployment planning, and the ability to support procurement under budget pressure, since these factors increasingly determine deal velocity. Opportunities also exist in enabling technologies—cloud management, analytics, mapping, and modular integration services—that reduce the friction of console modernization for end users.
For Procurement, Operations, and Public Sector Decision-Makers
Treat console modernization as a multi-year operational program rather than a single procurement event. Define enablement criteria that matter in practice: interoperability across current and future radio environments, integration with CAD, mapping, and mobile tools, security and compliance clarity, and a realistic pathway for phased rollout under budget constraints. Use replacement cycles mandated by Next Generation 911 or European Electronic Communications Code as an opportunity to redesign workflows and interoperability, not merely to refresh hardware. Where feasible, seek referenceable deployments that demonstrate measurable operational improvements, and require evidence that the solution can scale across sites and adapt to evolving data and coordination needs. In markets where spectrum constraints or cybersecurity costs are material, validate those assumptions early so that architecture and budgeting decisions are grounded in operational reality.
Navigating the Next Phase of Dispatch Console Modernization
The dispatch consoles market is moving through a period in which steady headline growth is accompanied by significant structural change. IP-based platforms, regulatory-driven replacement cycles, interoperability expectations, and emerging intelligence capabilities are reshaping what buyers need and what providers must deliver. At the same time, spectrum constraints, cybersecurity costs, and budget pressures are making procurement sequences more deliberate and more demanding. For executives, planners, and investors, the strategic question is no longer whether dispatch consoles are important, but how to position for a market where success depends on integration, adaptability, and credible modernization pathways.
PW Consulting Information & Electronics Research Center
Deeper segmentation data, regional demand patterns, and customized scenario analysis can help translate these market-level trends into durable business decisions. For readers seeking detailed breakdowns across segments, competitive positioning by region, and tailored guidance aligned with specific procurement, investment, or product strategies, the full PW Consulting research report provides the supporting structure needed to move from market awareness to execution planning.
For detailed analysis of this topic, please visit the official page: Dispatch Consoles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com