

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Auto Dealer Software Market: How 7.8% CAGR and Web Platforms Reshape Growth

The Auto Dealer Software Market: Strategic Trends and Commercial Opportunities Through 2032
The auto dealer software market has entered a phase of structural transformation, driven by technological maturation, regulatory pressure, and shifting dealership economics. Measured in USD millions, the market expanded from 143.5 in 2020 to approximately 190.8 in 2025, reflecting a compound annual growth rate of 7.8 percent across the 2020–2025 historical window. Forward projections indicate continued expansion, with revenue reaching 200.7 in 2026 and progressing toward 309.2 by 2032. This trajectory signals more than incremental growth; it reflects a market where software is no longer a back-office utility but a core operational and competitive layer for dealership networks.
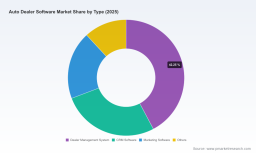
Market concentration remains high, with the top three providers capturing roughly 68.5 percent of overall revenue and the top five accounting for approximately 75.0 percent. Such concentration suggests that scale, integration depth, and compliance infrastructure create durable moats, while also leaving meaningful room for specialized entrants targeting specific dealership segments or workflow niches. The revenue split across software types shows dealer management systems commanding the largest share, followed by CRM and marketing platforms, with additional categories rounding out the portfolio. Deployment models reveal a clear tilt toward web-based solutions, which now represent the majority of market value, while installed software maintains a substantial but gradually declining footprint. Regional allocations point to North America as the largest revenue base, with Europe and Asia Pacific forming the next tier of meaningful demand centers, and Latin America along with the Middle East and Africa representing faster-growing but smaller absolute markets.
These headline trajectories mask underlying friction. Dealerships and software providers are navigating a landscape where legacy operational assumptions are colliding with cloud economics, regulatory scrutiny, and changing consumer expectations. The following sections break down the core challenges, demand drivers, competitive positioning, and forward-looking signals that matter for executives planning technology roadmaps, capital allocation, or market entry strategies.
Market Conditions and Critical Inflection Points
The current market environment is shaped by a combination of steady top-line growth and intensifying operational pressure. Three issues stand out as particularly consequential for how the market will evolve over the next several years.
First, cybersecurity and operational resilience have moved from a compliance checkbox to a strategic imperative. A major disruption in mid-2024 involving a leading DMS provider accelerated industry-wide reassessment of backup systems, access controls, and incident response planning. Providers have since increased investment in SOC 2-aligned platforms and AI-assisted fraud detection, while dealership groups have grown more cautious about single-vendor dependency and data exposure. This shift is not merely defensive; it is reshaping procurement standards, contract terms, and the value proposition of platforms that can demonstrate stronger security and continuity guarantees.
Second, data privacy expectations and compliance requirements are increasing the cost and complexity of software deployment. Cloud-native systems require ongoing alignment with evolving consumer information handling rules, particularly as platforms integrate more deeply with financing, marketing, and OEM data flows. For dealership operators, this creates a tension between the desire for streamlined digital experiences and the need to maintain rigorous consent management, retention controls, and audit readiness. For software vendors, it raises the bar for product design, documentation, and continuous updates, especially in markets where regulatory expectations differ by region or customer segment.
Third, labor economics are altering the calculus of dealership operations. DMS platforms that incorporate AI automation can reduce manual data entry and F&I processing time by up to 50 percent, easing reliance on specialized staffing for routine workflows. This is attractive in an environment where dealerships face persistent pressure on per-unit profitability and operational consistency. At the same time, automation creates new expectations: staff must be retrained, workflows must be redesigned, and the value of software shifts from record-keeping toward decision support and exception handling. The dealerships that benefit most are those that treat automation as a process redesign opportunity rather than a simple cost-reduction tool.
Taken together, these inflection points suggest a market that is expanding not just in size but in strategic importance. Software choices increasingly affect compliance posture, operational resilience, staffing models, and customer experience quality. That makes technology decisions harder to reverse and more consequential for long-term performance.
Core Drivers Reshaping the Market
Several interconnected forces are accelerating adoption and redefining what software must deliver to remain competitive.
Insurance Agency Software Market
Technological innovation continues to be the most visible driver. AI-enabled analytics, workflow automation, and modular integration architectures are becoming baseline expectations rather than differentiators. The industry context indicates that open integrations and API partnerships with lenders and OEMs have expanded the ecosystem around dealer platforms, but they have also increased licensing costs for third-party connectors in integrated DMS deployments. This dynamic is pushing providers to balance flexibility with cost control, and it is encouraging dealership groups to evaluate total cost of ownership rather than focusing narrowly on upfront subscription pricing. Recent platform launches have emphasized unified customer data and real-time insights, reflecting a broader shift from siloed records to connected intelligence. For example, a major provider launched a customer data platform in early 2026 designed to unify fragmented customer information, followed shortly by a foundations suite offered with free implementation for existing DMS renewals. These moves illustrate how vendors are using data unification and onboarding incentives to deepen adoption and reduce switching friction.
Policy and regulatory conditions are reinforcing this technological push. Cybersecurity expectations have tightened across the sector, and industry-wide investment in enhanced defenses following major disruptions has raised annual compliance expenditures for providers. In parallel, data privacy compliance demands continuous alignment for cloud-native systems handling consumer information. The result is a market where security and privacy are competitive factors: platforms that can demonstrate robust controls, transparent data practices, and predictable update cycles gain credibility with larger dealership groups and institutional partners. Regulatory pressure also indirectly benefits more mature providers, since compliance overhead can be harder for smaller players to absorb at scale.
Demand-side behavior is changing as well. Consumers and corporate buyers increasingly expect seamless digital interactions across the sales, service, and financing journey, even when the final transaction still involves in-person or hybrid steps. Dealerships are responding by investing in CRM and marketing software that complements the core DMS, using digital tools to improve lead handling, follow-up consistency, and retention marketing. Industry context shows AI-enabled tools expanding into areas such as driver’s license validation and fraud detection within F&I processes, signaling a broader expectation that software should reduce risk and improve speed without adding administrative burden. For dealerships, the strategic question is how to connect front-end digital engagement with back-end operational systems without creating new data silos or compliance gaps.
Cost structures and operating models are also in flux. Automation is reducing certain manual workloads, but API licensing, compliance, and integration complexity can offset some of those gains. At the same time, leadership changes and expansion initiatives among key vendors indicate that firms are betting on growth beyond their existing customer bases, often by broadening product scope, improving usability, or strengthening partner ecosystems. These developments suggest that the market is moving toward a more layered value proposition: core DMS functionality remains essential, but differentiation increasingly comes from analytics, automation, security, and ecosystem connectivity.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small set of scaled incumbents and a broader field of specialized and emerging providers. The leading companies share a common anchor in dealer management systems, but they differ in architecture, ecosystem strategy, and target customer segments.
CDK Global has reinforced its position through a combination of platform expansion, data unification, and adoption incentives. Its integrated dealership experience platform spans core sales, service, parts, finance, and accounting modules, with AI-driven analytics and open integrations. Recent activity includes the launch of a customer data platform for real-time insights, the introduction of a foundations suite with free implementation for existing DMS renewals, and a major industry event showcasing AI enhancements and expanded payment-related capabilities. These moves point to a strategy centered on deepening existing relationships, reducing churn risk, and making the platform more central to dealership data and workflow decisions.
Reynolds and Reynolds continues to compete through a comprehensive retail management system that covers inventory, customer management, and compliance tools. Its positioning emphasizes operational breadth and dealership-wide process support, which appeals to groups seeking a unified operational backbone. Dealertrack has carved out a strong niche around cloud-based DMS with a focus on F&I, digital contracting, and AI automation for deal closing and fraud reduction. Its recent introduction of AI-enabled driver’s license validation and expanded fraud detection for F&I processes underscores a strategy that ties technology directly to risk management and transaction efficiency. Cox Automotive, through its connected offerings, emphasizes AI-powered workflows and digital retailing tools, aligning DMS components with broader marketplace and retail technology ecosystems.
A second layer of competitors targets usability, small-to-medium dealer segments, and customer-service-centric relationships. Auto/Mate supplies a DMS focused on streamlined sales, service, finance, and accounting, with an emphasis on free upgrades and service responsiveness. Autosoft provides dedicated DMS platforms that stress ease of use, 360-degree dealership visibility, and automation for smaller dealers, and it recently appointed a new CEO to drive expansion beyond its current customer base. DealerSocket partners with Auto/Mate to offer connected DMS solutions, pairing integration with award-winning support and ongoing enhancements. Dominion Dealer Solutions supplies a VUE DMS aimed at comprehensive dealership management, including inventory and operational tracking. This segment of the market is more fragmented, and its growth often depends on delivering clear operational simplicity, responsive support, and cost-effective deployment models.
The market is evolving along three overlapping directions. Consolidation remains attractive at the top, where scale in data, compliance, and integrations strengthens competitive positioning. Differentiation is intensifying around AI, automation, security, and ecosystem breadth, with vendors competing to prove that their platforms can reduce friction in both routine operations and high-stakes processes like F&I. At the same time, new entrants and partner-led models continue to emerge in niches such as usability-focused DMS, specialized CRM and marketing layers, and region-specific compliance or deployment requirements. The practical implication is that buyers face a trade-off between the stability and depth of large platforms and the agility or specialization of smaller offerings, while vendors must decide whether to compete on breadth, depth, ecosystem access, or service quality.
PW Consulting Information & Electronics Research Center
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 period, several trends are likely to shape both market growth and opportunity allocation.
A first trend is the shift from modular software to integrated intelligence. As customer data platforms, AI analytics, and automated workflows become more embedded in dealer systems, the value of software will increasingly depend on how well it connects data across sales, service, parts, finance, and marketing. This creates opportunities for providers that can reduce fragmentation while preserving flexibility through open integrations. It also raises the stakes for dealerships that rely on patchwork systems, since disconnected data limits the benefits of automation and makes compliance and reporting more burdensome.
A second trend is the continued rise of cloud-native, web-based deployment as the dominant operating model. Web-based solutions already represent the larger share of market value, and their advantages in updates, remote access, integration, and scalability reinforce that position. The commercial implication is that procurement will increasingly favor platforms with strong security credentials, predictable data-handling practices, and clear upgrade paths. It also means that providers must manage ongoing compliance and integration costs, including the rising expense of third-party connectors and licensing arrangements with lenders and OEMs.
A third trend is the growing strategic role of automation in dealership economics. Reducing manual processing in F&I, inventory handling, and customer follow-up can meaningfully lower specialized staffing needs and improve consistency, but the payoff depends on workflow redesign and change management. The opportunity lies not just in adopting automation tools, but in reorganizing processes so that staff can focus on exception handling, relationship management, and higher-value decisions. The risk is that automation is treated as a plug-in cost saver without rethinking the surrounding operating model, which can blunt benefits and create new bottlenecks.
These trends carry uncertainty. Cybersecurity and data privacy requirements will continue to evolve, and compliance costs may rise further, particularly for providers operating across multiple jurisdictions. API licensing and integration expenses could pressure margins or slow ecosystem expansion if connector costs become a barrier. In addition, market concentration gives leading vendors significant influence over standards and pricing, which may limit the room for smaller players unless they serve clearly defined segments or offer distinctive workflow advantages. For investors and corporate strategists, the key is to distinguish between durable structural demand for connected, secure, automated dealer software and short-lived features that may be quickly commoditized.
Action Guidance for Decision-Makers
The strategic implications vary by role, but several priorities apply across the market.
Real Estate Software Market
For manufacturers and OEM-affiliated teams, the priority is to align technology partnerships with the broader retail experience strategy. As dealership software becomes more central to data flow, digital retailing, and compliance, OEM relationships with DMS and adjacent platforms can influence everything from inventory visibility to customer journey consistency. It is worth evaluating how open integrations, data-sharing models, and security expectations affect the long-term scalability of retail partnerships, rather than treating software selection as a purely dealership-level decision.
For investors, the most important signal is that growth is being driven by integration, automation, and compliance rather than by simple subscription expansion. That favors businesses with strong security posture, credible data unification capabilities, and sustainable ecosystem economics. At the same time, rising licensing costs, compliance expenses, and concentration risk argue for careful scrutiny of unit economics, customer retention dynamics, and the durability of differentiation. In a market where top providers hold a large share, incremental advantages in analytics, fraud controls, and workflow automation may matter more than headline feature counts.
For dealership groups and procurement teams, the practical question is total value rather than initial price. A platform that reduces manual processing, strengthens compliance readiness, and connects customer and operational data can create more value than one that appears cheaper but leaves workflows fragmented. Procurement decisions should weigh security certifications, integration costs with lenders and OEMs, support quality, and the feasibility of workflow redesign during implementation. It is also prudent to assess continuity and backup capabilities, given the sector’s heightened focus on operational resilience following recent disruptions.
Across these audiences, the value of detailed market intelligence lies in translating broad trends into segment-specific decisions. Revenue trajectories, deployment shifts, competitive moves, and compliance dynamics all interact differently across dealership size, region, and operational model. A fuller picture of these interactions, including granular segmentation and tailored strategic scenarios, can be found in the complete research report, which expands on the market structure, competitive dynamics, and decision frameworks discussed here.
For detailed analysis of this topic, please visit the official page: Auto Dealer Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com