

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Interior Design Market: Why 6.5% CAGR and $331B by 2032 Changes Everything

The Interior Design Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Context and Structural Challenges
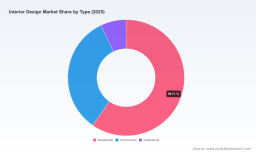
The global interior design market has maintained a steady upward trajectory over the past half-decade, with total revenue expanding from approximately USD 157.5 billion in 2020 to an estimated USD 211.5 billion in 2025. The forward outlook points to continued expansion through 2032, supported by a projected compound annual growth rate of 6.5 percent. While the headline figures convey resilience, the underlying composition tells a more nuanced story. Residential-driven demand accounts for the largest share of value, commercial and institutional segments together form a substantial second pillar, and regional activity spans mature markets in North America and Europe alongside fast-growing corridors across Asia Pacific, Latin America, and the Middle East and Africa. This breadth provides a foundation of diversified demand, but it also masks pockets of volatility that are reshaping how firms plan capacity, pricing, and channel strategy.
The first structural challenge is cost volatility across materials and labor. Escalating input prices and tariff-driven distortions have placed margin pressure on manufacturers and contractors alike, while also complicating budgeting for end clients. Professional bodies have flagged rising material costs and widespread tariffs as factors that are directly reshaping demand for interior design services and product pricing, with independent analysis of recent trade actions estimating a meaningful per-home cost impact for builders that ripples through furnishing supply chains. At the same time, labor market tightness—paired with elevated housing prices in several regions—has made it harder for practices to scale project delivery without compressing fees or stretching timelines. For executives, the operational question is no longer whether costs will fluctuate, but how to build pricing architecture, sourcing flexibility, and service models that can absorb shocks without eroding client trust.
The second challenge is the shifting regulatory and credentialing landscape. Interest in formalizing the profession has accelerated, with a growing number of states considering legislation related to licensing or registration of interior design practitioners, and one state reaching a milestone as the thirtieth to regulate the profession following a sunset review. These developments affect liability exposure, permissible scope of work, and competitive differentiation across jurisdictions. Firms that rely on unlicensed staff or cross-border service delivery must anticipate uneven rule sets, while brands that invest in credentialed talent can turn compliance into a trust signal. The practical implication is that market access, insurance requirements, and partnership structures are becoming more localized and more consequential than in prior cycles.
The third challenge is fragmentation in how value is captured. Despite the presence of category-leading companies, the top three operators account for roughly 18 percent of revenue and the top five for about 22 percent, indicating a broadly distributed market with room for consolidation as well as for niche specialization. That dispersion creates both opportunity and risk: it allows agile entrants to win in specific use cases or geographies, but it also means that price competition, channel conflict, and brand dilution can emerge quickly when demand softens. Leaders that convert scale into service depth, proprietary product systems, and integrated delivery tend to outperform in mixed cycles, while undifferentiated players face margin erosion.
Together, these dynamics create a market that is growing in aggregate yet demanding more discipline at the micro level. Executives should read the growth trajectory not as an invitation to expand indiscriminately, but as a reason to prioritize resilience, credentialing readiness, and strategic focus in the segments where they can sustain advantage.
2. Core Drivers Reshaping Demand and Supply
Technology and Digital Enablement
Digital workflows are moving from support functions to core value drivers. Generative design, parametric specification tools, and integrated visualization platforms are compressing the time from concept to approval, which is particularly valuable in residential and commercial projects where client decision cycles can be protracted. More importantly, these tools are enabling firms to standardize repeatable elements while customizing high-impact spaces, improving both margin and client satisfaction. The same technologies support better inventory synchronization for product suppliers by aligning design intent with manufacturable options, reducing rework and last-minute substitutions. The practical takeaway is that technology investment is increasingly a margin and speed story: the firms that can deliver fast, high-fidelity options and keep specification accuracy high are winning a larger share of wallet in complex projects.
Policy and Regulatory Dynamics
Policy is becoming a more direct lever on demand and operating costs. Trade actions and material tariffs have altered the economics of building and furnishing products, pushing some procurement teams to re-evaluate sourcing footprints and specs. Regulatory attention to professional credentials is also changing the playing field, raising the stakes for firms that deliver design services under varying legal regimes. Rather than treating these as external noise, leading organizations are incorporating policy scenarios into their planning: they diversify supplier bases to reduce concentration risk, align service offerings with recognized credentials where regulation is tightening, and prepare documentation and compliance processes that can be scaled across jurisdictions. In short, policy predictability is now an asset to be managed, and the firms that institutionalize scenario planning around it are better positioned to protect margins when rules shift.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user priorities are evolving in ways that favor service-led value over transactional transactions. In residential contexts, homeowners and developers increasingly seek cohesive design systems that balance aesthetics, durability, and lifecycle cost, particularly as housing affordability pressures shape renovation versus move-up decisions. In commercial and institutional settings, organizations are recalibrating spaces for hybrid work, wellness, accessibility, and brand experience, which expands the scope of interior work beyond fit-out to include adaptive reuse and spatial programming. Awards, trade shows, and curated showcases continue to influence taste formation and accelerate the adoption of new styles, materials, and crafts; the steady cadence of global events across North America, Europe, and Asia underscores how quickly preference cycles can move and how important timely exposure is for brands aiming to stay relevant. For operators, the implication is that design value must be demonstrated through outcomes—usability, durability, speed, and emotional resonance—rather than through decoration alone.
Supply Chain and Cost Structure Realignment
The cost structure of interior products and services is being rebalanced by a combination of input volatility, logistics constraints, and labor economics. Builders and suppliers are absorbing higher baseline costs on key inputs, which cascades into product pricing and project budgets, while shortages of skilled labor raise the cost of execution and extend delivery windows. In response, many organizations are shifting toward regionalized sourcing, modular product platforms, and pre-configured systems that simplify installation and reduce on-site variability. Vertical integration is gaining renewed attention in certain categories because it can tighten quality control and improve lead-time reliability, though it also requires capital discipline and careful capacity planning. The strategic signal is clear: resilience and repeatability are becoming as important as design novelty, and supply chain choices are increasingly a competitive differentiator.
3. Competitive Landscape and Leading Strategies
Strategic Positioning of Key Participants
Several established players illustrate distinct routes to advantage in a fragmented market. Legacy-oriented product houses have leaned into brand portfolios that span heritage and contemporary aesthetics, allowing them to serve multiple price tiers while preserving prestige equity. Their strategic edge lies in breadth of offering—wallpapers, fabrics, ancillary interior products, and coordinated collections—that simplifies specification for designers and trade partners, and in the ability to refresh lines without abandoning recognizable franchises. Luxury lifestyle retailers, by contrast, compete on curation, service, and aspirational positioning, extending across furniture, textiles, lighting, bathware, and décor through multiple brand channels. Their advantage is the integration of high-end product with design advice and an experiential retail environment that supports higher price points and deeper client relationships. Vertically integrated furniture manufacturers combine custom-crafted production with design services and North American manufacturing, using that model to control lead times, quality, and cost-to-serve while offering complimentary design support that raises switching costs for customers. Large-scale flooring and interior panel producers anchor broad application coverage across furniture, cabinetry, and residential and commercial use, leveraging scale in materials and manufacturing to compete on specification frequency, consistency, and supply reliability.
Differentiation and Scope Decisions
Across these models, differentiation tends to emerge from a few recurring choices. The first is the depth of integration between product and service. Companies that pair specification-grade products with design assistance, installation guidance, or project coordination capture more of the project value and reduce the likelihood of substitution. The second is the balance between breadth and focus. Broad portfolios enable cross-selling and specifier convenience, but focused systems can command stronger loyalty in key segments if they solve a clear problem—durability, maintenance, speed of installation, or style cohesion. The third is the degree of vertical control. In an environment of cost and labor pressure, manufacturers with direct oversight of critical steps can protect quality and timing, while more decentralized players must invest in supplier governance and transparent communication to achieve similar outcomes. The practical lesson is that advantage rarely comes from a single attribute; it comes from a coherent system that aligns brand promise, product capability, service model, and supply discipline.
Evolution of the Market Structure
The competitive map is evolving along three lines. Consolidation is plausible where scale improves purchasing power, speeds innovation cycles, and expands distribution reach, particularly if larger players can integrate design services or channel access that smaller firms cannot easily replicate. Differentiation is intensifying in parallel, as segments such as sustainable interiors, wellness-focused spaces, and regionally specific aesthetics create demand for specialized expertise and materials, opening space for firms that can credibly claim depth in a niche. New entrants and adjacent players continue to test the boundaries of the market, using digital storefronts, direct-to-consumer channels, and subscription-style services to reach customers outside traditional trade paths. These movements do not point to a single end state; rather, they suggest a market in which the center will hold for broad-line players with strong systems, while edges will become more dynamic as specialists and digital-native models gain traction. Executives should therefore plan for a landscape that remains contested, with advantage determined by the clarity of positioning and the reliability of execution.
PW Consulting Information & Electronics Research Center
4. Forward Outlook: Trends and Commercial Implications (Next 3–5 Years)
Service-Integrated Product Systems Will Gain Share
Over the next few years, demand is likely to tilt toward offerings that combine repeatable product platforms with embedded design and specification support. Clients in both residential and commercial settings are seeking speed, certainty, and coherence, and they are willing to pay a premium when a solution reduces coordination risk and installation variability. Brands that can present curated systems—complete with sample libraries, digital specification tools, and clear installation sequences—will be better placed to capture project budgets and to defend margins against commoditization. The commercial opportunity lies in packaging: creating modular, specifiable systems that scale across use cases while retaining enough flexibility to meet local preferences. The risk is execution complexity, because systems that are too rigid can alienate designers, while systems that are too loose fail to deliver the promised consistency.
Credentialing and Compliance as Competitive Filters
The regulatory momentum around professional licensing and registration is expected to continue shaping how services are delivered and how firms are evaluated. As more jurisdictions formalize requirements, credentialed practitioners and organizations will gain an advantage in projects where liability, safety, and code interaction matter, and will be better positioned to partner with architects, contractors, and public-sector clients. This trend creates an opportunity for firms to use compliance as a trust asset, particularly in institutional and commercial work. The uncertainty is uneven adoption: if rules vary widely across regions, multi-market operators will need to maintain flexible staffing and documentation practices, and smaller firms may face higher relative compliance burdens. Executives should treat credentialing strategy as part of market access planning rather than as a back-office concern.
Industrial Design Market
Sustainability and Lifecycle Value Move From Messaging to Specification
Sustainability is becoming a practical filter in procurement, driven by a combination of client expectations, event-led trend diffusion, and a growing appetite for transparency in materials and processes. Dedicated showcases and trade events that emphasize sustainable interiors, alongside broader industry gatherings, indicate that eco-conscious design is moving from a marketing theme to a specification criterion, especially in commercial and institutional projects where operating costs and reputational risk are salient. The commercial implication is that firms able to provide clear, verifiable information on material sourcing, durability, maintenance, and end-of-life options can win preference in selection processes and reduce perceived risk for buyers. The caveat is that credibility matters: claims that cannot be substantiated may erode trust quickly, and the cost of verification can be a barrier for smaller suppliers unless they align with recognized standards or partner with testing and certification bodies.
5. Strategic Implications for Decision-Makers
For manufacturers and product suppliers, the priority is to reduce variability and increase specifiability. That means investing in modular platforms and coordinated collections that simplify selection for designers, expanding digital tools that connect design intent to manufacturable options, and hardening supplier governance to manage input volatility and lead-time risk. Where vertical integration is feasible, it should be pursued with clear attention to capital efficiency and capacity utilization; where it is not, stronger transparency and contingency planning with upstream partners become essential. The goal is to make it easier for the market to choose your products repeatedly, which in turn supports more predictable demand and better pricing power.
For investors, the most attractive exposure is likely to be found where service depth, credentialing readiness, and supply resilience compound rather than where growth is pursued through breadth alone. Categories and platforms that can demonstrate repeat specification, high switching costs through design services, and credible sustainability credentials are better positioned to sustain margins across cycles. Due diligence should focus on the operating model behind the headline momentum: how pricing responds to input shocks, how lead times are controlled, and how the firm plans for a more fragmented regulatory environment. Capital that supports operational discipline and credible differentiation is more likely to outperform than capital that simply chases segment tailwinds.
Worldwide Marine Interiors Market
For procurement and design leadership, the strategic task is to convert volatility into a negotiation advantage by diversifying sourcing, favoring specifiable systems that reduce rework, and aligning project timelines with realistic labor and material availability. Building internal criteria that reward durability, maintenance ease, and verifiable sustainability can lower total cost of ownership and reduce the risk of reactive substitutions. At the same time, keeping a close watch on regulatory changes in relevant jurisdictions will help avoid eligibility or liability surprises as projects scale across regions.
Keeping pace with a market that is both expanding and fragmenting requires current, granular visibility into how segments, regions, and company strategies are evolving together. Detailed segmentation data, competitive benchmarks, and tailored scenario planning can turn broad trends into concrete choices about where to invest, what to standardize, and which risks to hedge. Readers seeking a fuller picture of the subsegments, regional nuances, and company-level dynamics underpinning this analysis can access the complete research report for deeper data and customized recommendations.
For detailed analysis of this topic, please visit the official page: Interior Design Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com