

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
MDM Market 2026: Why 12.5% CAGR and $13.3B Data Shift Strategy

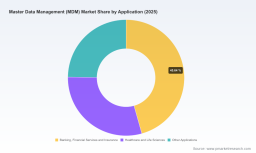
Master Data Management Market: Strategic Trends and Commercial Opportunities in a Consolidating Data Economy
The global enterprise data landscape is undergoing a structural transformation, with Master Data Management (MDM) emerging as a critical control layer between fragmented operational systems and AI-driven decision processes. Market valuations have moved steadily upward through the 2020–2025 cycle, climbing from approximately $7.5 billion to $13.3 billion, and forward projections indicate sustained momentum through 2032. A compound annual growth rate of 12.5 percent places MDM among the faster-growing infrastructure categories in enterprise software, reflecting its shift from a specialized governance function to a strategic prerequisite for analytics, automation, and customer-facing applications.
This trajectory is not merely a reflection of incremental IT spending. It signals a deeper realignment in how organizations treat foundational data as a reusable, governed asset rather than a byproduct of operational databases. As organizations pursue data unification across customer, product, supplier, and organizational domains, MDM has become the connective tissue for compliance adherence, operational efficiency, and AI model reliability. For executives and capital allocators, the market's expansion carries both operational urgency and investment relevance. Grasping where value is concentrating, where vendor strategies are diverging, and how regulatory and technological pressures are reshaping procurement decisions is essential for positioning in the next phase of data management adoption.
Market Snapshot: Expansion With Maturing Structure
The MDM market's progression from 2020 through 2025 illustrates a category that has moved beyond early experimentation into mainstream enterprise deployment. Revenue growth accelerated notably as cloud architectures matured, data governance requirements hardened, and organizations recognized that AI initiatives frequently fail without reliable foundational data. Looking toward the 2026–2032 horizon, continued expansion is anticipated, with the market potentially reaching levels above $30 billion by the end of the forecast period. Growth velocity is expected to remain strong, though the character of that growth is changing as consolidation pressures and platform integration agendas reshape vendor positioning and buyer expectations.
Alongside top-line expansion, market structure is becoming more concentrated. A small group of large platform providers and specialized leaders now commands a significant share of enterprise engagements, while mid-tier and niche vendors compete on interoperability, domain specificity, and deployment simplicity. This concentration matters for decision-makers because it changes the purchasing environment: risk is shifting toward integration complexity, vendor lock-in, and the ability to govern data that spans both legacy and next-generation systems. At the same time, concentration is creating clearer reference architectures and more defined evaluation criteria for enterprises that need MDM to support cross-functional data products.
Core Challenges and Inflection Points
Despite strong demand, MDM adoption continues to face friction that limits the pace at which organizations can convert data unification ambitions into durable production outcomes. One persistent challenge is an operational paradox: many enterprises want MDM to be comprehensive, but comprehensive deployments often stall under the weight of governance overhead, cross-departmental alignment, and change management. MDM is no longer a one-time master data cleanup exercise; it increasingly requires continuous stewardship, workflow discipline, and integration with data quality and observability practices. Organizations that underestimate these operating requirements frequently encounter delayed time-to-value and reduced adoption across business units.
A second inflection point involves the collision between AI ambitions and data readiness. Enterprise interest in generative AI, agentic workflows, and advanced analytics has accelerated the realization that model performance and trustworthiness depend heavily on the consistency, lineage, and contextual completeness of master data. This has reframed MDM from a back-office governance concern to a front-line enabler of AI use cases. The challenge is that many existing MDM deployments were not designed for high-velocity, AI-ready data products. Bridging that gap requires new integration patterns, metadata enrichment, and governance that can accommodate both strict regulatory controls and the flexibility demanded by modern data architectures.
A third challenge is regulatory and compliance fragmentation across geographies and sectors. As privacy obligations, reporting mandates, and industry-specific standards continue to evolve, MDM implementations must support auditable stewardship, hierarchy management, and recordkeeping without becoming brittle. Compliance is no longer a side benefit; it is becoming a design constraint that shapes vendor selection, data model architecture, and operational workflows. Enterprises operating in multiple jurisdictions or regulated industries face a more complex balancing act between speed of deployment and durability of governance.
Primary Growth Drivers Reshaping the Market
Several interrelated forces are intensifying demand for MDM and changing the way solutions are evaluated. The first is technological innovation centered on AI-augmented data unification and cloud-native data foundations. MDM platforms are increasingly expected to support intelligent matching, automated stewardship, and continuous data quality feedback loops, reducing the manual burden that historically slowed adoption. This is particularly relevant as organizations attempt to scale data products across functions without proportionally increasing specialized labor. Embedded training, certification, and guided workflows are becoming part of the value proposition because they lower the practical cost of adoption and help standardize data governance practices across teams.
The second driver is the regulatory environment, which is turning data governance from an optional discipline into a compliance necessity. Privacy regulations and sector-level requirements are expanding the scope of data that must be traceable, correctable, and consistently governed. MDM architectures that provide documented stewardship workflows, hierarchy controls, and audit-ready trails are becoming more attractive in environments where data errors or inconsistent records create legal, operational, or reputational exposure. In parallel, emerging sustainability and environmental reporting expectations are adding new categories of master data that require governance and consistency, extending the relevance of MDM beyond traditional customer and product domains.
The third driver is demand-side behavior, particularly the growing expectation that enterprise data should support real-time, customer-centric, and cross-functional use cases. Organizations are moving away from treating master data as static reference content toward viewing it as an active input to segmentation, personalization, supply continuity, product lifecycle management, and trusted analytics. That shift creates demand for MDM solutions capable of producing reliable golden records, supporting multi-domain unification, and integrating with broader data platforms and cloud ecosystems. As consumers and business users alike expect more coherent experiences and more accurate information, the cost of fragmented master data becomes more visible and more consequential.
The fourth driver relates to the evolving cost and integration structure of enterprise data environments. Organizations are increasingly managing hybrid landscapes that blend legacy systems, cloud data platforms, and specialized applications. MDM that can operate across these environments without forcing a full platform replacement is gaining relevance because it reduces migration risk and preserves existing investments. This dynamic favors solutions that offer flexible deployment models, strong integration hooks, and the ability to function as a governed data layer rather than a closed ecosystem. The market is therefore rewarding vendors that can reduce complexity rather than add another rigid layer of infrastructure.
Competitive Dynamics and Strategic Positioning
The competitive landscape reflects a mix of platform-scale providers, specialized MDM vendors, and emerging entrants with strong cloud or AI orientations. Large enterprise platform companies continue to anchor the market by embedding MDM capabilities within broader data management and business application ecosystems. Their advantage lies in cross-functional reach, existing customer relationships, and the ability to connect master data governance with ERP, analytics, and cloud infrastructure strategies. In this context, MDM becomes part of a wider harmonization and AI-readiness agenda, which can simplify procurement for organizations already committed to a primary platform but can also raise integration dependency concerns for those seeking vendor flexibility.
Specialized vendors, meanwhile, compete on depth, agility, and targeted domain strengths. Some emphasize AI-powered SaaS platforms for multi-domain unification and governance, with particular attention to integration with widely used CRM and data ecosystems. Others differentiate through cloud-native architectures that support rapid scaling across business functions and simplify data cleaning and unification. Several leaders have positioned around multi-domain data platforms with strong governance, AI-ready data products, and native integration into modern cloud data warehouses. A further segment focuses on augmented platforms that combine MDM with embedded data quality and automation, appealing to organizations that want governance and quality in a single operational flow. In regulated verticals, product information management-oriented vendors extend MDM capabilities into lifecycle and compliance use cases where traceability and controlled authoring are critical.
Recent strategic movements make the consolidation theme especially visible. Major platform transactions completed in recent years demonstrate how MDM is being absorbed into broader data management and business data clouds. These moves are designed to strengthen AI-ready data unification across both native and external systems, while also expanding the reach of governance, quality, and master data capabilities within larger ecosystems. For buyers, this signals a market in which MDM is increasingly evaluated not as a standalone utility but as part of a larger data architecture strategy. The practical implication is that vendor selection is becoming more about ecosystem fit, integration roadmap, and long-term governance model than about point-feature comparison alone.
At the same time, analyst recognition and product releases indicate that differentiation remains highly active. Leadership placements in independent evaluations, continued platform releases, and public commitments to AI-powered MDM and broader ecosystem integration show that competition is not simply about scale. Vendors are competing on stewardship usability, compliance readiness, interoperability, and the ability to lower labor and training barriers to adoption. These factors matter because they influence not just initial purchase decisions but the likelihood that MDM will be operationalized effectively across the enterprise.
PW Consulting Information & Electronics Research Center
Strategic Implications of Market Evolution
One clear trend is the convergence of MDM with broader data governance, data quality, and data product thinking. The market is moving toward solutions that can serve as governed data foundations for multiple downstream consumers, including analytics, AI, customer operations, and supply chain processes. This convergence is reducing the isolation of MDM as a niche repository and increasing its role as an active contributor to enterprise data value chains. Organizations that treat MDM as a product platform rather than a static catalog are more likely to extract sustained value from their investments.
Another trend is the growing importance of interoperability across heterogeneous environments. As companies continue to accumulate cloud data platforms, legacy systems, and specialized applications, MDM must bridge gaps without demanding full architectural standardization. Solutions that support flexible integration, strong metadata handling, and consistent governance across environments are positioned to capture demand from enterprises that need progress without wholesale replacement. This favors a more practical, integration-aware buying posture, where evaluation criteria emphasize time-to-value, data product readiness, and operational maintainability.
A third trend is the increasing alignment between MDM and compliance-driven data operations. The demand for auditable workflows, stewardship accountability, and reliable hierarchy management is expanding the functional scope of MDM implementations. This is particularly relevant for organizations operating across regions or industries with distinct data obligations. MDM is increasingly expected to help demonstrate control, support reporting, and reduce exposure from inconsistent or poorly governed foundational data. In this environment, solution evaluation increasingly includes evidence of governance maturity, not just unification capability.
Digital Rights Management (DRM) Market
Future Outlook: Three Strategic Trajectories
Over the next three to five years, the MDM market is likely to be shaped by the continued blending of governance, AI readiness, and platform integration. One trajectory is the acceleration of AI-native MDM capabilities that support automated matching, stewardship assistance, and continuous data quality improvement. This will not eliminate the need for human oversight, but it should reduce the operational friction that has historically constrained scale. Commercial opportunities will arise for vendors and implementers that can demonstrate measurable improvements in data consistency, time-to-golden-record, and stewardship efficiency without sacrificing control.
A second trajectory is deeper embedding of MDM into broader data and application ecosystems. As enterprises pursue unified data foundations for analytics and AI, MDM is likely to be evaluated more often as part of a combined platform strategy rather than a discrete project. This creates opportunities for organizations that can connect master data governance with cloud data platforms, CRM workflows, and operational systems in a coherent way. It also raises the stakes for enterprises that must manage dependency risk and ensure that MDM remains adaptable if platform strategies shift.
Patient Data Management Systems (PDMS) Market
A third trajectory involves the widening applicability of MDM into sustainability, supply chain, and regulated product data contexts. As reporting obligations and operational transparency requirements grow, governed master data will become more relevant to environmental compliance, product traceability, and cross-border trade documentation. Commercial value will accrue to organizations that can extend MDM beyond traditional customer and product domains into new governance-sensitive areas. The uncertainty here lies in how quickly standards, data definitions, and audit expectations will crystallize across industries and regions, which will influence the pace of adoption in these newer use cases.
Actions for Decision-Makers Across Different Roles
For enterprise executives and strategy teams, the central task is to treat MDM as an operational capability with measurable business outcomes rather than a data cleanup initiative. That means defining the data domains that matter most to revenue, compliance, and customer experience, then investing in governance workflows, stewardship accountability, and integration to AI or analytics pipelines. Prioritizing use cases that produce visible improvements in customer data consistency, product information accuracy, or regulatory readiness can accelerate organizational support and reduce the risk of stalled deployments.
For technology and procurement leaders, the evaluation criteria should extend beyond feature lists to the reality of operating the platform in a hybrid enterprise. Important considerations include how well the solution supports multi-domain unification, how easily it integrates with existing cloud data environments, how it handles stewardship and compliance workflows, and how it lowers training and operational costs through usability and guided processes. Procurement decisions should also account for long-term adaptability, especially as platform consolidation, ecosystem integrations, and AI readiness requirements continue to evolve.
For investors and market participants, the key is to distinguish between vendors with durable differentiation and those that are primarily riding platform momentum. Value creation will increasingly depend on the ability to maintain AI-ready data products, support multi-domain governance, and demonstrate measurable improvements in data quality and operational efficiency. Monitoring strategic consolidation, ecosystem integrations, and analyst recognition can provide useful signals, but the underlying question remains whether a vendor's MDM capability is becoming a genuine enabler of enterprise data products or mainly a feature within a broader platform narrative.
Conclusion: Data Foundations as Strategic Leverage
The MDM market is expanding in a context where data is no longer a side concern but a core organizational capability. Growth is being driven by AI readiness demands, regulatory complexity, cloud-based data architectures, and the growing cost of inconsistent master data across customer, product, and operational domains. At the same time, the market is consolidating and maturing, which means the strategic question for most organizations is not whether to strengthen master data governance, but how to do so in a way that delivers durable, scalable value.
Organizations that succeed will be those that align MDM with real business outcomes, choose integration paths that reduce friction, and build governance models that can support both compliance and AI-driven innovation. Given the pace of change, timely access to detailed segment-level data, vendor benchmarking, and use-case-specific guidance can materially improve planning accuracy and investment confidence. For those seeking a deeper view of segmentation dynamics, competitive positioning, and tailored strategic options, the full PW Consulting research report provides a more granular basis for decision-making and next-step execution planning.
For detailed analysis of this topic, please visit the official page: Master Data Management (MDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com