

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Brand Protection Software Market: Why 8.75% CAGR Through 2032 Changes Everything

The Brand Protection Software Market: Strategic Shifts and Commercial Opportunities in a $2 Billion Landscape
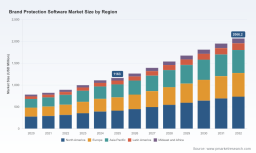
The global market for brand protection software has crossed a significant inflection point. From $780.45 million in 2020, market revenue has grown at a consistent pace to reach $1,163.0 million in 2025, with a forecast trajectory lifting projections to $2,066.2 million by 2032. The compound annual growth rate of 8.75 percent underscores a sector that is far from a niche compliance tool; it is becoming a core layer of digital risk management, intellectual property defense, and revenue preservation. For executives, investors, and procurement leaders, the question is no longer whether to invest in brand protection capabilities but how to architect them in a way that aligns with operational reality, regulatory obligations, and the accelerating sophistication of threat actors.
Behind the headline numbers lies a market defined by structural fragmentation and rapid technological change. Brand abuse is no longer confined to counterfeiting in traditional retail channels. It now spans marketplace listings, social media impersonation, domain squatting, phishing infrastructure, gray-market distribution, and dark web proliferation. Defending against these exposures requires software that can detect at scale, triage accurately, enforce across jurisdictions, and integrate with internal legal, security, and supply chain workflows. The organizations that treat brand protection as a standalone monitoring function are increasingly finding themselves outpaced, while those embedding it into broader risk and revenue operations are beginning to capture measurable advantages.
Market Snapshot and Structural Headwinds
Revenue growth in this sector reflects sustained enterprise demand, but the growth itself is uneven across use cases and deployment models. Cloud-based implementations dominate the addressable spend, while on-premises deployments remain meaningful for organizations with stringent data residency or legacy system integration requirements. On the application side, anti-counterfeiting continues to anchor spending, followed by brand abuse monitoring, with social media protection and domain name protection representing smaller but strategically critical slices of the portfolio. Geographically, the largest revenue pools sit in North America, Europe, and Asia Pacific, with Latin America and the Middle East and Africa contributing more modest but fast-evolving demand.
What matters more than the split itself is what the mix reveals about buyer priorities. Enterprises are moving from reactive takedowns toward continuous monitoring, predictive detection, and cross-channel enforcement. At the same time, the market remains relatively fragmented at the top, with the top three players accounting for 22.35 percent of revenue and the top five reaching 27.18 percent. That concentration leaves substantial room for differentiation, partnerships, and consolidation, but it also signals that no single vendor has claimed a commanding, default position across all brand protection needs.
The current environment is shaped by three intersecting challenges.
-
The tension between scale and accuracy. Automated detection can surface enormous volumes of potential infringement, but high-confidence enforcement still depends on specialized human review, threat validation, and jurisdiction-specific takedown procedures. That creates an operational strain, particularly for small and mid-sized enterprises that lack the internal expertise to manage false positives or complex enforcement cases.
-
The compliance friction baked into data handling. Data privacy and security requirements, including frameworks such as GDPR, force vendors and buyers alike to treat brand threat intelligence as sensitive data. Secure storage, controlled sharing, and careful cross-border processing are not optional add-ons; they are design constraints that influence platform architecture and deployment decisions.
-
The cost of sustained effectiveness. High implementation and maintenance burdens persist because meaningful protection is not a one-time configuration. It requires ongoing monitoring updates, rule tuning, marketplace and platform coverage expansion, and continuous adaptation to new abuse patterns. For organizations without dedicated brand protection teams, these ongoing costs can become the difference between an installed capability and an actually effective one.
Taken together, these challenges are not simply headwinds; they are shaping the logic of the next generation of solutions. Buyers are looking for platforms that lower the human review burden without surrendering accuracy, that treat compliance as a built-in feature rather than a separate workstream, and that justify their total cost of ownership by connecting threat reduction to revenue retention and operational efficiency.
Core Drivers Redefining the Market
Four forces are doing the most to reshape demand, vendor strategy, and the pace of adoption.
AI and Automation as the New Baseline
Artificial intelligence is moving from a marketing differentiator to a practical requirement. The most advanced platforms now pair computer vision, predictive models, seller risk scoring, and AI-assisted enforcement workflows to reduce the time between detection and action. Recent product moves illustrate the direction of travel. In April 2026, Red Points introduced a Copilot AI assistant built around predictive models, seller risk scores, and computer vision for brand protection, signaling an emphasis on prioritizing high-probability abuse and reducing manual triage. That same vendor expanded marketplace brand protection capabilities in February 2026 with AI detection and API enforcement designed for e-commerce platforms, reinforcing the shift from manual monitoring toward automated, API-driven action.
Around the same time, Corsearch published its 2026 State of Trademarks Report in May 2026, highlighting AI-driven trademark monitoring advancements, and followed with a webinar in June 2026 on balancing AI, automation, and human expertise in trademark teams. Those activities reflect a broader industry recognition: automation can widen the detection surface and accelerate routine enforcement, but trademark, brand, and legal teams still require explainable outputs, defensible evidence, and human judgment for complex cases.
For decision-makers, the implication is straightforward. The competitive advantage is no longer simply whether a platform uses AI, but how it integrates AI into evidence collection, risk prioritization, enforcement pathways, and auditability. Solutions that only promise detection at scale, without clear escalation logic and human-in-the-loop controls, are likely to underperform in environments where false positives and enforcement friction carry real financial and reputational costs.
Regulatory Pressure and Cross-Border Enforcement Complexity
Regulatory and standards-driven dynamics are expanding both the need for brand protection software and the requirements placed on it. Global IP enforcement standards continue to push organizations toward automated compliance across multiple jurisdictions, especially as brand abuse moves fluidly across domains, marketplaces, social platforms, and dark web channels. At the same time, data privacy and security concerns remain a meaningful restraint, not because organizations want less protection, but because they need platforms that can handle threat intelligence in a compliant, defensible manner.
This creates a dual mandate. Buyers want broader coverage and faster enforcement, but they also need evidence-driven monitoring, secure handling of brand threat data, and workflows that respect jurisdiction-specific processes. The vendors best positioned to gain share are those that can frame compliance not as a limitation but as a reinforced operating model, where monitoring, evidence preservation, and enforcement actions are designed with regulatory and privacy obligations in mind from the outset.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer expectations and enterprise purchasing behavior are reinforcing each other. Consumers are increasingly sensitive to counterfeit goods, impersonation, and fraudulent storefronts, and they often encounter brand abuse before a company does. That puts pressure on brands to protect not only revenue but also trust, especially in categories where product authenticity and digital legitimacy directly affect purchasing decisions.
On the enterprise side, brand protection is increasingly evaluated alongside cybersecurity, fraud prevention, and e-commerce growth initiatives. This is visible in the expansion of platform scopes beyond traditional IP monitoring. Companies such as ZeroFox emphasize digital risk protection with dark web intelligence, threat validation, and disruption workflows for brand abuse, phishing, and executive threats. RiskIQ approaches the space from threat intelligence and risk profiling, targeting brand exposure and actionable risk insights across digital assets. BrandShield focuses on AI-powered detection with expert-enforced removal across phishing, impersonation, counterfeit listings, app threats, websites, social media, marketplaces, and the dark web. The common thread is that brand protection is being treated as part of a broader digital risk surface, rather than an isolated trademark issue.
Worldwide Anti-piracy Protection Market
Supply Chain, Marketplace, and Enforcement Economics
The economics of enforcement are changing as abuse migrates into faster-moving, harder-to-monitor channels. Marketplace volume, cross-border gray-market distribution, and decentralized digital storefronts increase the number of exposure points a brand must manage. At the same time, specialized human expertise in threat validation and enforcement remains essential for high-accuracy outcomes, which adds operational strain for smaller teams and raises the attractiveness of platforms that can automate more of the repeatable work.
This is why enforcement integration has become strategically important. API-based enforcement, marketplace partnerships, and takedown workflow automation can materially change the cost and speed of response. For manufacturers, distributors, and online sellers, the practical value of brand protection software increasingly depends on whether it can reduce manual effort across the full lifecycle: discovery, evidence gathering, escalation, removal, and ongoing monitoring after remediation.
Competitive Landscape and Strategic Positioning
The competitive field is broad and includes players with different origins, strengths, and go-to-market models. Understanding the landscape means looking past feature lists and examining how each organization positions itself against the market's core problems: detection breadth, enforcement credibility, evidence quality, and operational burden.
Corsearch builds its positioning around AI-powered trademark clearance, brand monitoring, revenue recovery, and content protection, with global enforcement spanning domains, marketplaces, and social media. Its recent emphasis on trademark monitoring advancements and the balance between automation and human expertise suggests a strategy that blends IP rigor with scalable monitoring. Red Points positions itself as an AI-driven platform for unlimited counterfeit removal, impersonation takedowns, gray-market enforcement, and piracy prevention across thousands of marketplaces, websites, and social platforms, with recent moves reinforcing AI assistants and marketplace enforcement capabilities. BrandShield emphasizes AI-powered detection and expert-enforced removal for phishing, brand impersonation, counterfeit listings, and app threats across websites, social media, marketplaces, and the dark web, pointing to a hybrid model that combines automated detection with expert-led enforcement.
ZeroFox and RiskIQ extend the conversation toward digital risk. ZeroFox frames its offering as an AI-powered digital risk protection platform with dark web intelligence, threat validation, and disruption workflows for brand abuse, phishing, and executive threats. RiskIQ approaches the market through threat intelligence and risk profiling, focusing on brand exposure, dark web monitoring, and actionable risk insights across digital assets. MarkMonitor remains associated with comprehensive domain monitoring, trademark protection, and online brand protection for large enterprise clients, reinforcing a legacy strength in domain and trademark-centric programs. OpSec Security contributes authentication and brand protection solutions, including AI-powered tools for counterfeit prevention and product authentication, tying digital protection to physical product integrity. PhishLabs combines phishing simulation and brand protection training with threat intelligence for enterprise risk management, an angle that connects brand defense to internal readiness and security awareness. Resolver concentrates on domain monitoring and trademark enforcement for IP protection, while Netcraft emphasizes evidence-based brand protection with domain and website monitoring for reputation and security threats. Netcraft's updated brand protection platform from November 2025, with its emphasis on evidence-driven domain and website monitoring, reflects a continuing emphasis on defensible visibility.
The strategic pattern across these players is not uniform, and that is the point. Some organizations compete on breadth of coverage and marketplace enforcement; others differentiate on evidence quality, authentication, digital risk, or trademark and domain specialization. For buyers, the decision often comes down to which type of protection aligns best with the brand's exposure profile. A company whose primary risk is marketplace counterfeiting may evaluate platforms differently from one facing phishing and executive-targeted impersonation, or from one that needs stronger product authentication and physical-digital linkage.
PW Consulting Information & Electronics Research Center
The landscape is also evolving through both consolidation and specialization. On one side, larger security, threat intelligence, and digital risk platforms continue to find value in folding brand protection into broader offerings, especially where customers want a single view of external threats. On the other side, specialized vendors continue to emerge or reposition around specific enforcement workflows, regional needs, or high-accuracy detection models. The relatively moderate top-level concentration suggests that this tug-of-war is still active, and that meaningful differentiation can still be created through execution, integrations, and domain expertise.
Forward Trends and Commercial Opportunity
Looking ahead across the next three to five years, three trends are likely to define where value accumulates.
From Detection to Prioritized, Evidence-Ready Enforcement
The market is moving toward platforms that not only find abuse but also rank it, package it as evidence, and push it through enforceable workflows. This matters because the cost of brand protection is increasingly measured in operational drag, not just license spend. Solutions that reduce review cycles, improve the quality of evidence, and integrate with marketplace and domain enforcement channels will be better positioned to justify investment. The commercial opportunity here lies in end-to-end effectiveness: customers will reward tools that make enforcement faster, more defensible, and less dependent on large internal teams.
Deeper Integration with Digital Risk, Security, and Authentication
Brand protection is increasingly overlapping with cybersecurity, fraud operations, and product authentication. Organizations are looking for coherent visibility across phishing, impersonation, counterfeit listings, domain abuse, and dark web exposure, rather than separate tools for each problem. The opportunity is for vendors and buyers alike to build or adopt architectures that link brand protection with adjacent risk functions. For manufacturers and product companies, the connection to authentication and physical supply-chain integrity is especially important, because digital enforcement and product verification increasingly reinforce each other.
Governance, Compliance, and Cross-Border Scalability as Differentiators
As privacy and data security requirements continue to shape deployments, governance will become a more visible competitive dimension. Platforms that can demonstrate secure handling of threat intelligence, consistent cross-border processes, and auditable enforcement documentation will have an advantage in regulated industries and in multinational programs. The broader opportunity is for brand protection to be evaluated not only on threat coverage but also on how well it supports compliance-ready operations. This is particularly relevant for organizations expanding into new markets or managing complex supplier and marketplace ecosystems.
These trends carry risk and uncertainty. AI-driven detection can improve scale, but it can also increase the volume of signals that must be managed, potentially raising operational complexity if workflows are not well designed. Regulatory expectations will continue to evolve, and platforms that cannot adapt to local enforcement and data-handling rules may lose traction in key regions. Cost structures may also remain elevated for organizations that treat brand protection as a set of disconnected tools rather than a coordinated program. Finally, market consolidation could shift bargaining power, integration expectations, and long-term vendor viability, making supplier strategy more important than ever.
Implications for Decision-Makers
The strategic takeaway is that brand protection is becoming a multi-dimensional investment, and the right posture depends on the organization's exposure profile, internal capability, and growth trajectory.
Digital Risk Protection Software Market
For manufacturers and consumer-facing brands, the priority is to align brand protection with both revenue defense and product integrity. That usually means broadening coverage beyond the most visible abuse channels, integrating detection with enforcement workflows, and connecting digital monitoring to authentication and supply chain controls where relevant. The goal is not simply to identify infringement, but to reduce the time to action and the cost of remediation across the channels that matter most to the business.
For investors, the opportunity sits in platforms that combine scalable detection with defensible enforcement, strong evidence handling, and credible paths to integration within larger security or risk stacks. Differentiated AI use cases matter, but durable value is more likely where automation lowers operational burden, where coverage extends across marketplaces and digital channels, and where compliance-ready design supports enterprise adoption. In a market that is still fragmented at the top, execution quality, workflow design, and customer outcomes will be key indicators of long-term positioning.
For procurement and security leaders, the focus should be on total cost of ownership and operational fit rather than feature breadth alone. Evaluation criteria should include how well the platform supports evidence-driven monitoring, how it handles data privacy and security obligations, how readily it integrates with marketplace enforcement or internal workflows, and whether the vendor's model matches the organization's internal capacity for review and escalation. A platform that is powerful on paper but difficult to operationalize can create hidden costs that outweigh its theoretical advantages.
In a market that is expanding steadily toward $2,066.2 million by 2032, the most consequential decisions will be about architecture, prioritization, and vendor fit rather than whether to act at all. Organizations that treat brand protection as a coordinated, evidence-driven, and compliance-aware program are better positioned to protect revenue, reduce risk, and keep pace with the next generation of digital abuse. For those seeking a more detailed segmentation view, deeper competitive benchmarking, and customized guidance tied to specific operating contexts, PW Consulting's full market report provides the additional breakdown and strategic recommendations needed to translate these trends into a concrete investment and implementation plan.
For detailed analysis of this topic, please visit the official page: Brand Protection Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com