

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Pyrogenicity Testing Market: Why 8.25% CAGR and Regional Shifts Redefine Strategy

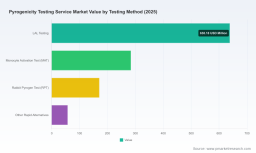
Strategic Shifts in the Pyrogenicity Testing Service Market: Navigating Growth, Regulation, and Innovation
Market Overview and Core Challenges
The pyrogenicity testing service market has evolved from a compliance-driven niche into a strategically important segment within the broader biopharma and medical device testing landscape. Over the past five years, the sector has demonstrated consistent expansion, reflecting the growing complexity of biologic development, the proliferation of implantable and advanced medical devices, and a gradual but decisive shift away from animal-based testing paradigms. The trajectory suggests a market that is maturing in terms of technical capability and regulatory alignment, while still navigating structural friction around method adoption, capacity planning, and cross-regional harmonization.
From a macroeconomic standpoint, the market has moved past the volatility associated with early-stage diagnostic and testing disruptions and entered a phase of more predictable growth. Demand is now anchored by expanding drug pipelines, increasingly stringent safety requirements for novel modalities, and the ongoing modernization of quality control workflows. Yet, beneath the headline growth, several operational and strategic challenges are reshaping how service providers, manufacturers, and regulators interact with pyrogen testing. One persistent tension lies in the pace of regulatory acceptance for non-animal methods. While monocyte activation testing and other in vitro alternatives have gained substantial scientific credibility, implementation timelines, validation requirements, and regional differences in end-user expectations continue to introduce complexity into product registration strategies. Companies developing biologics or devices for multiple markets must balance the scientific advantages of newer methods against the practical realities of parallel qualification pathways.
A second challenge centers on capacity and specialization. As demand for pyrogen testing broadens beyond traditional endotoxin screening, laboratories are under pressure to support a wider range of analytes, matrices, and product categories. This is especially relevant for advanced therapies, combination products, and device-drug hybrids, where material-mediated responses and non-endotoxin pyrogens require more nuanced assessment. Service providers that cannot scale specialized assays, interpret complex biological signals, or offer regulatory-ready documentation may find themselves squeezed between highly specialized niche players and large global testing organizations with broader service portfolios.
A third structural challenge involves the alignment of supply-side capabilities with evolving demand-side expectations. Manufacturers are increasingly looking for testing partners that can integrate pyrogenicity assessment earlier in development, reduce iteration cycles, and provide data that support both safety evaluation and regulatory submission. At the same time, cost pressures in pharmaceutical and device development are pushing organizations to optimize testing strategies without compromising compliance or patient safety. This environment favors providers that can deliver method flexibility, predictable turnaround, and consultative support for test selection, rather than offering testing as a purely transactional service.
For decision-makers, these challenges translate into a clear operational message: pyrogen testing is no longer a standardized checkpoint but a strategic variable in development planning, regulatory positioning, and partner selection. The organizations that respond effectively will be those that treat method choice, testing timeline, and vendor capability as integrated components of product strategy rather than isolated laboratory tasks.
Key Drivers Shaping Market Dynamics
The growth and transformation of the pyrogenicity testing service market are being driven by a combination of scientific advancement, regulatory momentum, evolving product complexity, and changing procurement expectations. These forces do not operate in isolation; rather, they reinforce one another and create a market environment where method innovation and service capability increasingly determine competitive advantage.
Pharmaceutical Testing Services Market
Scientific and Methodological Innovation
One of the most significant drivers is the maturation of non-animal testing methods. Monocyte activation testing, in particular, has moved from an emerging alternative to a credible, increasingly adopted approach for detecting both endotoxin and non-endotoxin pyrogens using human-derived blood cells. This capability addresses a long-standing limitation of methods focused primarily on bacterial endotoxin, offering a broader view of pyrogenic risk. For manufacturers, that broader coverage can support more comprehensive safety evaluation and reduce dependence on methods that are increasingly misaligned with institutional goals to minimize animal use.
The growing emphasis on in vitro alternatives also reflects a wider shift in testing philosophy: from reactive detection toward more mechanistically informative assessment. As assay systems improve and validation frameworks mature, service providers are better positioned to offer MAT and related alternatives in a way that is both scientifically robust and regulatory-compatible. This evolution is especially important for biologics, vaccines, and complex medical devices, where pyrogenicity concerns may not be fully captured by a single endpoint or method.
Regulatory and Policy Momentum
Regulatory developments are accelerating the transition toward non-animal pyrogen testing and reshaping compliance expectations across regions. In Europe, pharmacopoeial standards have increasingly favored replacement of the rabbit pyrogen test with non-animal approaches for applicable products, creating a clear directional signal for manufacturers and testing laboratories alike. Parallel validation strategies and regulatory discussions have also supported broader acceptance of MAT as a practical alternative to traditional rabbit-based testing in certain contexts, helping reduce uncertainty around method substitution.
At the same time, device and drug authorities continue to set expectations for pyrogen limit specifications, particularly for implants and products contacting sensitive biological systems or marketed with non-pyrogenic claims. These requirements do not simply mandate testing; they influence test selection, study design, and documentation standards. The cumulative effect is a environment in which compliance is still essential but is increasingly interpreted through the lens of method suitability, risk coverage, and alignment with modern quality systems.
Expanding Demand From Complex Products
Demand-side changes are also a major driver. Pharmaceutical and biotechnology companies continue to advance a broader range of biological products, and medical device manufacturers are developing increasingly sophisticated implantable, interventional, and combination technologies. These products raise more complex questions about material compatibility, immune response, and pyrogen-related risk. Testing requirements therefore expand not only in volume but also in technical breadth, as manufacturers seek data that account for both endotoxin and non-endotoxin pyrogens, different contact pathways, and device-specific exposure scenarios.
In parallel, research and academic institutions contribute to demand through product development, method validation, and translational projects. While their purchasing patterns differ from commercial manufacturers, these organizations support the broader ecosystem by generating evidence, refining assay applicability, and training the next generation of quality and regulatory professionals. The combined effect is a diversified demand base that strengthens market resilience while also raising expectations for methodological flexibility.
Operational and Capacity Considerations
Finally, the market is being shaped by supply-side dynamics around laboratory capacity, regional service networks, and the economics of specialized testing. As method portfolios expand, laboratories must invest in trained personnel, controlled biological materials, and quality systems capable of supporting reproducible performance. This creates a barrier to rapid entry for less specialized providers, while rewarding organizations that can integrate pyrogen testing into broader microbiology, biocompatibility, and quality assurance services.
Pyrometers Market
Cost structures are also influenced by the need to support multiple methods across regions and product types. Companies that rely on a single testing approach may face higher risk if that method is restricted, delayed, or deemed unsuitable for a specific product category. Conversely, service providers with multi-method capability and strong documentation support can offer greater predictability, which becomes a valuable commercial differentiator in a market where development timelines and regulatory submissions are tightly managed.
Competitive Landscape and Leading Strategies
The pyrogenicity testing service market is characterized by a mix of global testing organizations, specialized life science service providers, and focused suppliers with deep expertise in endotoxin and pyrogen detection. Market concentration remains moderate, meaning that while leading players hold meaningful share, there is still room for differentiation through method capability, regional reach, and application-specific expertise. In this environment, competitive advantage is less about scale alone and more about the ability to offer credible, compliant, and flexible testing solutions across a changing regulatory and product landscape.
Strategic Positioning of Leading Providers
Several established companies illustrate different strategic paths within the market. Charles River Laboratories has built a broad contract testing presence that spans MAT, RPT, and LAL-based endotoxin testing across global laboratories, with service coverage relevant to biologics and medical devices. Its positioning emphasizes breadth, global delivery, and the ability to support multiple testing needs within a single organization, which can be attractive to manufacturers managing complex development programs across regions.
Eurofins BioPharma Product Testing has focused on integrating MAT, rFC, and LAL endotoxin services within a global network that supports regulatory compliance, while also aligning with the transition toward non-animal methods. This approach reflects a broader strategy of combining method flexibility with compliance-oriented service design, which helps address manufacturer concerns about method substitution and multi-market registration.
PW Consulting Information & Electronics Research Center
NAMSA has carved out a distinctive role through its emphasis on biocompatibility and microbiology testing for medical devices, including material-mediated pyrogenicity assessment aligned with ISO 10993-11 and USP expectations. For device manufacturers, this specialization is strategically important because pyrogen testing cannot always be separated from broader biocompatibility evaluation, especially for products where material contact and systemic exposure must be assessed together.
Lonza occupies a distinct position through its provision of MAT systems and related pyrogen testing solutions that support replacement of rabbit-based approaches. Its relevance in the market stems not only from service provision but also from its association with equipment and assay infrastructure that enable consistent in vitro testing. This creates a linkage between product enablement and service delivery, which can strengthen long-term engagement with laboratories and manufacturers seeking standardized non-animal workflows.
SGS contributes through a broad pharmaceutical and medical device testing portfolio that includes pyrogen and endotoxin services such as MAT. Its advantage lies in the integration of pyrogen testing into a wider analytical and compliance framework, allowing customers to consolidate testing needs and reduce coordination friction across multiple evaluation domains.
Associates of Cape Cod, Inc. represents a more focused model, centering on LAL-based endotoxin and pyrogen detection products and services. This specialization supports customers with strong endotoxin-related needs and illustrates how a narrower portfolio can remain competitive when it delivers deep technical credibility and consistent assay performance.
Market Evolution Trends
Looking across this competitive set, several trends are shaping the market’s evolution. First, differentiation is increasingly tied to method flexibility. Providers that can support MAT alongside LAL and other alternatives are better positioned to serve customers navigating transition periods, multi-region submissions, and product-specific method suitability questions. Second, service integration is becoming more valuable. As manufacturers seek efficiency, they often prefer partners who can connect pyrogen testing with biocompatibility, microbiology, and quality support rather than treating it as an isolated service line. Third, geographic reach and local regulatory familiarity remain important. Even as non-animal methods gain momentum, operational realities differ by region, and providers with established laboratory networks and regional compliance knowledge can respond more effectively to customer requirements.
The market also appears open to further consolidation and to entry by organizations that can combine scientific credibility with strong service execution. Larger testing platforms may pursue expansion through capability acquisition or network broadening, while specialized players may strengthen their position by deepening expertise in device-related pyrogenicity, non-animal methods, or specific therapeutic categories. In either case, the winners are likely to be those that can translate technical capability into predictable, regulatory-ready outcomes for customers.
Future Outlook and Strategic Opportunities
Over the next three to five years, the pyrogenicity testing service market is likely to be defined by deeper adoption of non-animal methods, broader integration of pyrogen assessment into early development, and continued regional differentiation in regulatory implementation. These trends create opportunities for organizations that can align method strategy with product development timing and compliance planning.
One key trend is the increasing normalization of MAT and related in vitro approaches as primary options for many applications. As validation experience accumulates and regulatory expectations continue to evolve, non-animal testing is expected to become less of a transitional choice and more of a default consideration for appropriate product categories. This shift will likely increase demand for providers with robust MAT capability, reliable human blood cell sourcing, and documented performance across relevant matrices and product types. For manufacturers, the opportunity lies in designing development and submission strategies that take advantage of broader pyrogen coverage earlier, rather than treating non-animal testing as a late-stage alternative.
A second trend is the growing importance of application-specific testing strategies. Medical devices, biologics, and combination products will continue to create distinct pyrogenicity questions, and service providers that can tailor methods to material type, exposure scenario, and regulatory target will have a competitive edge. This favors a model in which testing is embedded into product risk assessment and quality planning, not treated as a stand-alone compliance step. Companies that can guide test selection, interpret results within a broader safety context, and produce submission-ready documentation will be particularly valuable.
A third trend is the continuing influence of regional regulatory timing. Even when scientific consensus moves in one direction, practical adoption can lag in certain markets or product contexts. That means multi-market manufacturers and global testing providers must maintain method portfolios that can accommodate differing expectations without creating unnecessary duplication or delays. The commercial opportunity here belongs to organizations that can manage regional variability while preserving efficiency and consistency in overall testing strategy.
Potential risks include uneven regulatory implementation, validation complexity for specialized products, and the possibility that some applications remain dependent on traditional methods for longer than anticipated. Supply chain constraints for biological reagents, training requirements for specialized assays, and the need for strong quality systems may also limit how quickly new capacity can be deployed. Decision-makers should therefore consider not only which methods are scientifically preferable, but also which partners can deliver them consistently under real-world compliance conditions.
Strategic Recommendations for Decision-Makers
For pharmaceutical and biotechnology manufacturers, the priority should be to incorporate pyrogen testing method strategy into development planning earlier. Selecting and validating appropriate methods before late-stage programs can reduce rework, support smoother regulatory interactions, and improve alignment with non-animal testing direction where applicable. Companies should also evaluate testing partners on the basis of method breadth, documentation quality, and ability to support product-specific risk assessments, rather than on price alone.
For medical device manufacturers, the emphasis should be on integrating pyrogenicity evaluation with biocompatibility and material selection processes. Because device-related pyrogen risk can depend on material behavior, contact pathway, and intended use, a fragmented testing approach may create gaps in evidence or delay design decisions. Engaging service providers with device-focused expertise and clear familiarity with relevant standards can help ensure that testing supports both safety and regulatory readiness.
For investors and strategic planners, the opportunity lies in identifying organizations that combine multi-method capability with strong compliance infrastructure and regional delivery capacity. The market’s growth is unlikely to be evenly distributed; value will increasingly accrue to providers that can support transition to non-animal methods, serve complex product categories, and maintain predictable quality across expanding demand. Assessing these capabilities in detail requires segmentation-level data, customer-side demand patterns, and provider-level operational comparisons that go beyond aggregate market figures.
In a market shaped by simultaneous scientific progress, regulatory transition, and product complexity, timely and granular intelligence is a practical asset. Detailed segmentation data, provider benchmarking, and region-specific regulatory mapping can sharpen strategy during periods when method choice and partner selection have outsized impact on development speed and compliance outcomes. Readers seeking a more detailed breakdown of segments, competitive dynamics, and forward-looking scenario analysis may find value in reviewing the complete PW Consulting market report for pyrogenicity testing services.
For detailed analysis of this topic, please visit the official page: Pyrogenicity Testing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com