

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
8-bit Automotive MCU Market: The 2026–2034 Growth and Concentration Dynamics

Strategic Trends and Commercial Opportunities in the 8-bit Automotive Microcontrollers Market
Market Landscape and Core Challenges
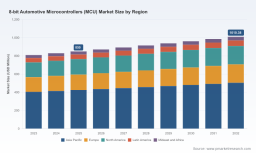
The 8-bit automotive microcontroller market represents a stable yet evolving segment within the broader automotive electronics ecosystem. Valued at $850.0 million in 2025, the market has demonstrated resilience, growing from $810.0 million in 2023. The trajectory projects a steady climb to approximately $1010.38 million by 2032, reflecting a compound annual growth rate (CAGR) of 2.5 percent over the forecast period from 2026 to 2032.
IoT Microcontroller (MCU) Market
This growth trajectory underscores a specific market dynamic: 8-bit architectures are not being displaced by higher-bit alternatives but are instead maintaining a critical niche. The market remains highly concentrated, with the top three companies commanding 68.5 percent of revenue, while the top five control 82.4 percent. This consolidation indicates high barriers to entry and established trust relationships between semiconductor suppliers and automotive OEMs.
Despite the steady numbers, the industry faces significant inflection points. The primary challenge lies in the tension between legacy reliability and modern functional requirements. As vehicles incorporate more complex electronic control units (ECUs), the expectation for 8-bit devices to interface with advanced networks while maintaining cost efficiency creates architectural pressure. Manufacturers must balance the proven stability of 8-bit cores with the need for enhanced security and processing capabilities.
Secondly, supply chain normalization following previous volatility is beneficial, but geopolitical factors are reshaping production footprints. There is increasing momentum toward localizing automotive MCU production, including 8-bit variants, within Asia to serve regional OEM supply chains. This shift requires existing players to adapt their manufacturing strategies to remain competitive in localized markets while managing global cost structures.
Finally, qualification standards remain a rigid gatekeeper. The requirement for AEC-Q100 Grade 0 qualification, ensuring operation from -40°C to 150°C, and ISO 26262 functional safety compliance for ASIL B applications sets a high bar for component selection. Any disruption in meeting these standards can disqualify a supplier from new design wins, making compliance a non-negotiable strategic priority.
Key Drivers of Market Dynamics
Several core factors are propelling the demand and evolution of 8-bit automotive MCUs. Understanding these drivers is essential for stakeholders looking to navigate the market effectively.
Technological Innovation and Integration
Innovation in 8-bit MCUs is focusing on integration rather than raw processing power. Modern automotive applications require devices to handle multiple functions within a single chip to save space and cost. Recent developments highlight this trend, such as the continued active support and availability of STM8AF/STM8AL automotive series with enhanced packages and ecosystem tools. These updates provide designers with greater flexibility in board layout while maintaining the reliability expected in automotive environments.
Similarly, Microchip Technology has highlighted the PIC18-Q83/84 and AVR DA/DD families for ongoing automotive applications. These devices support CAN FD and touch applications with functional safety certifications. The integration of communication protocols like CAN FD into 8-bit architectures allows these lower-cost controllers to remain relevant in vehicle body networks, bridging the gap between basic control and modern connectivity requirements.
Regulatory and Compliance Environment
Regulatory frameworks continue to shape product development cycles. The mandate for functional safety compliance, specifically ISO 26262 for ASIL B applications, remains a critical driver for processor selection. Automotive manufacturers cannot compromise on safety, meaning 8-bit MCUs must maintain certification throughout their lifecycle.
Furthermore, environmental and operational standards dictate performance. The requirement for operation from -40°C to 150°C ensures that components can withstand the harsh conditions of engine compartments and exterior modules. Companies that can demonstrate consistent compliance across temperature ranges and safety protocols gain a significant competitive advantage in the qualification process.
Demand-Side Shifts in Vehicle Electronics
Consumer and enterprise behavior is shifting toward more robust body electronics and safety features. While powertrain electrification often grabs headlines, body electronics remain a volume driver for 8-bit MCUs. Applications such as lighting control, window actuators, and sensor interfaces rely on cost-effective, reliable processing.
The demand for high-temperature operation up to 150°C is particularly pronounced in these areas. As vehicle designs become more compact and thermal loads increase, the ability of an MCU to operate reliably at elevated temperatures without degradation is a key selection criterion for engineering teams.
Supply Chain and Cost Structures
Economic factors play a substantial role in MCU selection. 8-bit solutions offer a cost-effective alternative for applications where 32-bit processing power is unnecessary. With semiconductor supply chain lead times for MCUs normalizing in 2026 following earlier volatility, production stability has returned. This stability allows automotive manufacturers to plan production runs with greater confidence, sustaining demand for established 8-bit parts.
However, cost pressures persist. Automotive OEMs continuously seek to reduce bill-of-materials costs. Suppliers that can offer integrated solutions—such as devices with built-in ADCs or memory—that reduce the need for external components provide value beyond the unit price of the MCU itself.
Competitive Landscape and Leading Strategies
The competitive environment is defined by established players leveraging long-standing relationships and specific technical capabilities. The market's high concentration indicates that incumbents hold significant leverage, but differentiation remains key to securing design wins.
Strategic Positioning of Key Players
Microchip Technology maintains a strong position through its focus on functional safety and connectivity. By offering AEC-Q100 Grade 0 certified PIC and AVR 8-bit MCUs with CAN/CAN FD support, they address the need for reliable communication in body and HMI applications. Their emphasis on ISO 26262 ASIL B compliance and high-temperature operation up to 150°C aligns directly with the rigorous demands of modern automotive designs.
STMicroelectronics competes through reliability and series expansion. The STM8AF and STM8AL series are positioned as high-reliability solutions for automotive body and powertrain applications. With features like data EEPROM, operation up to 150°C, and support for LIN and CAN, they cater to engineers seeking proven stability. Their continued investment in ecosystem tools and enhanced packages demonstrates a strategy of sustaining legacy architectures while improving usability.
NXP Semiconductors leverages its extensive automotive heritage. Supplying S08 and legacy HC05/HC08/HC11 8-bit MCUs with automotive qualification provides a pathway for cost-effective control applications. Their support for CAN in these legacy lines ensures compatibility with existing vehicle networks, making them a viable option for industrial control and automotive applications where upgrade costs must be minimized.
Silicon Laboratories focuses on integration and form factor. Their C8051F52x and C8051F5xx series offer high integration, including 12-bit ADCs, within small packages. This makes them suitable for industrial and automotive sensor and control applications where space is constrained. Their strategy centers on providing dense functionality in a compact footprint, appealing to designs with strict size limitations.
Renesas Electronics utilizes its power efficiency strengths. The RL78 family offers 8/16-bit low-power MCUs with automotive qualification. Targeting body control, lighting, and sensor applications, Renesas emphasizes energy efficiency, which is critical for battery-powered systems and overall vehicle energy management.
Infineon Technologies maintains a presence through established legacy lines. Offering the XC800 A-family 8-bit automotive MCUs for demanding applications, they rely on the trust associated with their broader automotive portfolio. Their strategy involves supporting proven architectures that meet rigorous quality standards for challenging environments.
PW Consulting Information & Electronics Research Center
Market Evolution and Consolidation Trends
The market structure suggests continued consolidation among top-tier suppliers. With the top five companies controlling over 80 percent of revenue, new entrants face significant hurdles in displacing established relationships. Automotive qualification cycles are long, and once a component is validated in a vehicle platform, switching costs are high.
However, differentiation opportunities exist in niche areas. Suppliers that can offer unique value propositions—such as superior integration, specific temperature ranges, or enhanced security features within the 8-bit constraint—can carve out sustainable positions. The trend toward localizing production in Asia also opens avenues for regional players to capture share by offering supply chain proximity to OEMs, provided they can meet global quality standards.
Future Trends and Commercial Opportunities
Looking ahead to the next 3-5 years, several trends will define the trajectory of the 8-bit automotive MCU market. Stakeholders should prepare for these shifts to capitalize on emerging opportunities.
Sustained Niche Dominance
Despite the rise of 32-bit and 64-bit processors in high-performance computing and ADAS, 8-bit MCUs will maintain dominance in specific body electronics and sensor applications. The cost-performance ratio for simple control tasks remains unbeatable. Commercial opportunities lie in optimizing these legacy architectures for modern interfaces, ensuring they remain compatible with evolving vehicle network standards without increasing cost.
Supply Chain Localization
Geopolitical tensions are accelerating the localization of automotive MCU production. Manufacturers may find opportunities in establishing or expanding regional production capabilities in Asia to serve local OEMs. This shift reduces logistics risks and aligns with government incentives for domestic semiconductor manufacturing. Companies that can guarantee regional supply stability will be preferred partners for OEMs seeking to de-risk their supply chains.
Enhanced Functionality in Legacy Cores
Expect to see continued updates to 8-bit portfolios, focusing on functional safety and connectivity. As regulatory requirements tighten, even lower-end controllers must support necessary safety mechanisms. Suppliers that proactively update their 8-bit lines to meet emerging safety and communication standards will secure long-term design wins. The commercial opportunity here is in providing support services and software ecosystems that make integrating these updating parts easier for engineering teams.
Potential Risks
Risks include the potential for stringent safety regulations to increase compliance costs, squeezing margins on cost-sensitive parts. Additionally, if geopolitical localization efforts fragment the market too severely, it could lead to inefficiencies in global supply chains. There is also a risk that rapid advancements in low-cost 32-bit alternatives could eventually erode the price advantage of 8-bit solutions in certain applications, necessitating careful monitoring of technology substitution trends.
Microcontrollers (MCU) Market
Actionable Insights for Decision Makers
For manufacturers, investors, and procurement teams, navigating the 8-bit automotive MCU market requires a balanced approach that respects legacy stability while anticipating change.
-
For Semiconductor Manufacturers: Focus on extending the lifecycle of proven 8-bit architectures through functional safety updates and enhanced integration. Invest in regional supply chain capabilities to meet localization demands in Asia. Prioritize customer support and ecosystem tools to differentiate beyond unit price, ensuring design wins stick through qualification cycles.
-
For Investors: Evaluate companies based on their ability to maintain compliance with evolving safety standards while managing cost pressures. Look for suppliers with strong regional presence in Asia to capitalize on localization trends. Monitor the balance between legacy revenue streams and investment in next-generation low-power interfaces that keep 8-bit relevant.
-
For OEMs and Procurement Teams: Diversify supplier bases where possible to mitigate geopolitical supply risks, while maintaining the stability required for long-term vehicle platforms. Engage early with suppliers regarding availability and qualification timelines for 8-bit parts, as lead times may fluctuate with regional production shifts. Prioritize components with robust functional safety certifications to streamline your own validation processes.
Detailed segmentation data, country-specific forecasts, and customized strategic recommendations are available in the comprehensive research report. Accessing granular insights allows stakeholders to validate assumptions and refine strategies based on precise market volumes and competitive positioning. For a deeper dive into the specific dynamics shaping this sector, refer to the full study for exhaustive data and analysis.
For detailed analysis of this topic, please visit the official page: 8-bit Automotive Microcontrollers (MCU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com