

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
RIM Systems Market 2026: Beyond the 8.25% CAGR and the $3.3B Growth Trajectory
By pmarketresearch, 2026-09-18
Navigating the Regulatory Information Management Systems Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
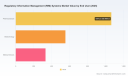
The global Regulatory Information Management (RIM) systems market has entered a phase of sustained expansion, reflecting the increasing complexity of product lifecycle governance across life sciences and medical technology sectors. From 2020 through 2025, the market demonstrated consistent year-over-year growth, reaching a baseline valuation of approximately $1.95 billion. Current projections indicate this trajectory will continue through the end of the decade, with the market expected to approach $2.14 billion by 2026 and ultimately surpassing $3.39 billion by 2032. This expansion is underpinned by a compound annual growth rate of 8.25 percent over the 2026 to 2032 forecast period, signaling a structural shift rather than a cyclical uptick. Organizations are no longer viewing RIM platforms as back-office compliance utilities but as strategic infrastructure that directly influences time-to-market, operational resilience, and cross-functional data integrity.
Despite this momentum, the market faces several structural challenges that are reshaping procurement decisions and vendor expectations. The first challenge lies in the fragmentation of regulatory data across silos. Many organizations still operate with disconnected systems for submissions, product registrations, change control, and archival management, creating bottlenecks during global market access initiatives. The second challenge centers on regulatory harmonization versus regional divergence. While international initiatives aim to streamline submission standards, the reality remains a patchwork of jurisdictional requirements that demand flexible, configurable workflows rather than rigid, one-size-fits-all architectures. The third challenge is the escalating expectation for real-time regulatory intelligence. Decision-makers increasingly require platforms that not only store compliance records but also monitor evolving requirements, assess impact, and trigger downstream processes without manual intervention. These tensions are forcing both buyers and vendors to reconsider what a modern RIM system must deliver.
The competitive field reflects these pressures. Market concentration remains moderate, with the top three providers collectively accounting for roughly 45 percent of revenue and the top five reaching slightly above 58 percent. This distribution suggests a market that is neither fully consolidated nor highly fragmented, leaving meaningful room for differentiation through specialization, integration depth, and technological maturity. For executives evaluating RIM investments, the immediate implication is clear: platform selection must align with organizational complexity, geographic footprint, and the urgency of automating regulatory execution rather than simply digitizing existing paperwork.
Key Drivers Reshaping the RIM Landscape
Several interconnected forces are accelerating adoption and shaping the next generation of RIM capabilities. Understanding these drivers is essential for executives who need to anticipate where investment will flow and which platform attributes will command premium positioning.
Technological Innovation and the Rise of Intelligent Workflows
The most visible driver is the integration of automation and intelligence into core regulatory processes. RIM platforms are evolving from documentation repositories into execution engines that support submission authoring, change impact assessment, and continuous regulatory monitoring. A clear example of this shift is the Spring 2026 launch of a regulatory execution engine embedded within a unified RIM platform, combining submission creation, AI-powered regulatory monitoring, and configurable impact workflows in a single environment. This development signals a broader industry movement toward systems that reduce manual handoffs and enable faster response to regulatory changes. For technology and operations leaders, the implication is that AI-enabled monitoring and configurable workflow engines are transitioning from differentiators to baseline expectations, particularly for organizations managing high volumes of product variations or frequent submission cycles.
Regulatory Complexity and Compliance Mandates
Policy and regulatory environments continue to exert direct pressure on RIM design and deployment. In FDA-regulated environments, platforms must support electronic records and signatures in alignment with 21 CFR Part 11, reinforcing the need for auditable, secure, and traceable data handling. At the same time, data security and privacy requirements have intensified. Regulations such as GDPR and CCPA remain central to RIM architecture, but the landscape is becoming more granular. By 2026, more than 20 U.S. states have enacted comprehensive data privacy laws, expanding the compliance surface for platforms that store sensitive regulatory information. This patchwork of privacy obligations is pushing vendors to build robust data governance controls, role-based access, and jurisdictional data handling logic directly into their systems. For regulated companies, these mandates are no longer peripheral IT concerns; they are core procurement criteria that affect vendor shortlists and implementation timelines.
Demand-Side Shifts in Life Sciences and MedTech Operations
On the demand side, organizations are under increasing pressure to accelerate product registrations, manage global submissions efficiently, and maintain compliance across heterogeneous jurisdictions. Pharmaceutical and biotechnology companies face heightened expectations for lifecycle transparency, while medical device and in vitro diagnostics manufacturers must navigate rapidly evolving technical and clinical documentation requirements. RIM platforms are increasingly selected based on their ability to centralize product data, registration records, submission artifacts, correspondence, and commitment tracking in a coherent workflow. The trend is especially pronounced among sponsors and service providers that must coordinate across internal teams, contract organizations, and multiple health authorities. The commercial logic is straightforward: centralized regulatory information reduces duplication, shortens review cycles, and improves the consistency of submissions across markets.
PW Consulting Information & Electronics Research Center
Cost Structures and Operational Efficiency
Cost dynamics are also influencing adoption patterns. Organizations are seeking to reduce the hidden costs of manual reconciliation, version control errors, and delayed submissions that can stall market entry or trigger compliance findings. Cloud-based deployment has become a significant enabler in this context, offering scalability, lower upfront infrastructure burden, and easier integration with adjacent quality, safety, and clinical systems. At the same time, on-premise deployments persist in settings where data residency, internal control requirements, or legacy integration constraints favor localized infrastructure. The broader cost story is not simply about license pricing; it is about total cost of ownership over the product lifecycle. Platforms that streamline regulatory execution, reduce rework, and provide reusable data structures are gaining preference because they translate compliance activity into measurable operational savings.
Competitive Landscape and Leading Strategies
The RIM market features a mix of purpose-built specialists, broad life sciences platform providers, and diversified compliance vendors. Their strategies reveal distinct approaches to capturing value in a market that rewards both domain depth and execution efficiency.
Supplier Relationship Management System Market
Several vendors have carved out strong positions by focusing on specific end markets or workflow strengths. Rimsys has built a unified RIM platform purpose-built for MedTech, emphasizing global registrations, submissions, product data, and change management within a single system. Its recent product launch illustrates a strategy centered on embedding regulatory execution, AI-powered monitoring, and configurable impact workflows directly into the platform, reducing the need for disjointed point solutions. RegDesk pursues a similar MedTech orientation with centralized regulatory data management, global compliance workflows, and regulatory intelligence, targeting organizations that need streamlined multi-jurisdiction execution. Kivo serves life sciences sponsors and service providers with document and process management, compliance workflows, and support for major authorities such as the FDA and EMA. These specialists compete by delivering focused functionality, faster implementation paths, and clear alignment with the daily realities of regulatory operations teams.
Broader platform players are taking a different approach, leveraging scale, ecosystem integration, and cloud architectures. Veeva Systems offers a cloud-based RIM capability within its Vault portfolio, covering submissions, registrations, publishing, and archival functions for life sciences. Its strategy benefits from a recognized cloud infrastructure and strong adoption across pharmaceutical and biotech organizations that already use Veeva for adjacent processes. IQVIA provides a cloud-based, AI-enabled platform for regulatory submissions, registrations, lifecycle management, and compliance across MedTech, IVD, and pharma, positioning its offering as part of a larger data and services ecosystem. ArisGlobal’s LifeSphere RIMS emphasizes end-to-end regulatory planning, tracking, registration management, and compliance with AI integration, appealing to organizations that want planning and execution tightly coupled. Ennov centralizes product, registration, submission, correspondence, and commitment data for regulatory operations and compliance, while Freyr Solutions offers RIM software as part of broader end-to-end regulatory services, including lifecycle management and compliance support. MasterControl rounds out the field with regulatory information management, product reviews, approvals, releases, and compliance tracking, targeting organizations that value integrated quality and regulatory workflows.
The market is evolving along two complementary paths. One is consolidation through ecosystem breadth, where larger vendors expand functionality and deepen integrations to reduce switching costs and capture more of the regulatory lifecycle. The other is differentiation through specialization, where focused vendors compete on ease of deployment, regulatory domain expertise, and workflow precision. A third dynamic is the continued entry of new players targeting underserved niches, particularly MedTech-specific workflows and AI-assisted monitoring. For buyers, this landscape creates both opportunity and risk. The upside is a growing set of options tailored to different operating models; the risk is platform sprawl if organizations select tools that do not integrate well with existing quality, safety, or content systems. The most effective strategies tend to prioritize data coherence, authorization and audit readiness, and the ability to scale across markets without rebuilding workflows from scratch.
Future Trends and Strategic Implications
Looking ahead three to five years, several trends are likely to define the next stage of RIM market evolution. The first is the deepening embedment of intelligence into regulatory execution. AI-assisted monitoring, automated impact assessment, and smarter submission preparation will become more common, enabling teams to respond faster to changing requirements and reduce manual review burdens. The commercial opportunity here lies in platforms that can translate regulatory signals into actionable workflow steps, not just alerts. Organizations that adopt these capabilities early may gain meaningful advantages in submission readiness and cycle time. The associated risk is over-reliance on automation without adequate validation, governance, and human oversight, especially in highly regulated contexts.
A second trend is the continued pressure toward centralized, interoperable regulatory data architectures. As product portfolios expand and market access strategies become more global, the ability to reuse product data, maintain consistent registration records, and connect regulatory information with quality and safety systems will increasingly separate high-performing organizations from those struggling with fragmentation. The opportunity is to treat regulatory data as a shared asset that supports cross-functional decisions, rather than as a compliance archive. The risk is that legacy system inertia and integration complexity slow transformation, leaving organizations with improved documentation but not improved execution.
A third trend is the tightening of data privacy and security expectations as a core selection criterion. With multiple U.S. state privacy laws in effect and international obligations still evolving, RIM platforms will be evaluated not only on regulatory functionality but also on data handling maturity, access controls, and auditability. Vendors that can demonstrate robust privacy-by-design architectures and clear jurisdictional controls will be better positioned in enterprise deals. The uncertainty lies in how quickly requirements will continue to multiply and whether standardization efforts will ease or complicate compliance burdens.
Actionable Guidance for Decision-Makers
For regulated product manufacturers, the priority should be to assess RIM platforms against the full regulatory execution lifecycle rather than isolated compliance tasks. Selection criteria ought to include submission authoring efficiency, registration and change management coherence, integration with quality and safety systems, and the ability to configure workflows for multiple jurisdictions without excessive customization. Organizations that treat RIM as a strategic execution layer typically see better alignment between regulatory planning and operational delivery.
For investors and strategic partners, the market signals value in vendors that combine domain focus with demonstrable automation benefits and credible data governance. Differentiation is increasingly tied to workflow intelligence, deployment flexibility, and the ability to serve complex MedTech or multi-entity life sciences environments. Due diligence should look beyond feature lists to adoption patterns, implementation outcomes, and the vendor’s capacity to sustain innovation as privacy and regulatory expectations continue to evolve.
Legal Risk And Compliance Solution Market
For procurement and operations leaders, the most practical step is to map current regulatory pain points—such as duplicate data entry, slow impact assessment, or fragmented submission records—against platform capabilities that directly address those bottlenecks. Cloud-based deployment may offer faster time-to-value in many scenarios, but the final decision should reflect data residency needs, internal control requirements, and the organization’s integration roadmap. Given the pace of change and the widening range of vendor strategies, timely access to detailed segmentation data, vendor benchmarking, and tailored implementation considerations can materially improve investment outcomes. Comprehensive research providing deeper segment-level insight and customized analysis is available for teams that need to move from strategic direction to execution planning with greater confidence.
For detailed analysis of this topic, please visit the official page: Regulatory Information Management (RIM) Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vacuum Isolators Market: Why 5.5% CAGR & $800M Scale Signal Pharma-Driven Shift
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Vacuum Isolators Market
Market Snapshot and Core Challenges
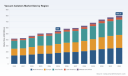
The vacuum isolators market has established itself as a critical infrastructure segment within controlled environment manufacturing, valued at approximately $550.0 million in 2025. Historical data from 2020 to 2025 reveals a compound annual growth rate (CAGR) of 5.5 percent, signaling steady expansion driven by the increasing demand for containment solutions across high-precision industries. Looking ahead to the forecast period of 2026 through 2032, the market trajectory remains positive, with projections indicating a potential valuation of $800.07 million by 2032. This growth reflects a maturation phase where volume increases are increasingly tied to technological sophistication rather than purely capacity expansion.
Regional dynamics show a clear dominance by established markets, with North America and Europe historically holding the largest shares, while Asia Pacific represents a rapidly growing volume center. However, the revenue concentration within the market is significant. The top three players account for 45.5 percent of the market, and the top five entities control 62.8 percent. This high level of concentration suggests that barriers to entry remain steep, largely due to the capital intensity and regulatory complexity associated with pharmaceutical-grade and semiconductor-grade isolation systems.
Three structural challenges define the current market environment. First, the high capital expenditure required for deployment acts as a friction point for adoption. Pharmaceutical-grade isolators often involve initial investments exceeding $150,000 per system, with validation processes adding 20 to 30 percent to total ownership costs. This cost structure limits accessibility for smaller enterprises and slows the rate of incremental capacity addition in mature markets. Second, the regulatory framework is evolving from static compliance to dynamic quality management. Recent updates, such as the FDA Quality Management System Regulation (QMSR) effective from February 2026, update quality system requirements relevant to device manufacturing equipment. These shifts require manufacturers to maintain agility in their design and validation protocols, increasing the operational burden on equipment providers. Third, the industry faces a tension between standardization and customization. While modular custom systems offer flexibility, the majority of revenue is still driven by stainless steel isolators, which are often standard-heavy but require significant integration efforts for specific vacuum processes. Balancing the efficiency of catalog products with the specific needs of potent compound handling or aseptic vacuum drying remains a persistent engineering and commercial challenge.
Key Drivers of Market Change
Technological innovation is reshaping the functional boundaries of vacuum isolators. The shift toward robotic gloveless systems represents a notable evolution in operational efficiency. Insights from the industry have highlighted the economic advantages of robotic gloveless pharmaceutical isolators over traditional manual systems. These systems reduce operator exposure to potent compounds while improving throughput consistency. By removing the human element from the critical path of manipulation within the isolator, manufacturers can achieve higher sterility assurance levels and lower contamination risks. This technological leap is not merely a feature improvement; it fundamentally alters the total cost of ownership calculation by reducing validation complexity related to operator intervention and enhancing long-duration process stability.
The regulatory environment continues to be a primary catalyst for demand. Compliance requirements such as EU GMP Annex 1 mandate that closed isolator systems correspond to a minimum Grade D background environment for sterile medicinal product manufacturing. This regulation reinforces the necessity of high-integrity isolators as the baseline standard rather than an optional upgrade. Furthermore, the alignment of global quality standards, exemplified by the FDA QMSR update, creates a more harmonized but stricter landscape for equipment qualification. Manufacturers operating in or exporting to regulated markets must ensure their isolator solutions can demonstrate robust traceability and quality management integration. This regulatory pressure drives demand for systems that are not only functionally capable but also documentation-ready, favoring suppliers with established quality infrastructure.
Demand-side dynamics are being influenced by the expanding application scope beyond traditional pharmaceutical manufacturing. While pharmaceutical production remains the dominant application, the semiconductor and electronics sector represents a substantial portion of market demand, driven by the need for contamination-free processing environments. The growth in battery and energy storage applications, though currently smaller in revenue contribution, indicates a diversification trend where vacuum isolation is required for handling sensitive materials. Additionally, healthcare capital expenditure trends provide context for the demand environment. Average annual capital expenditure on health across OECD countries remained around 0.6 percent of GDP between 2021 and 2024. While this figure suggests stable public investment, the focus on efficiency and advanced manufacturing capabilities within healthcare and pharmaceutical production pushes end-users toward technologies that offer long-term operational savings, supporting the adoption of advanced isolators despite high upfront costs.
Supply chain and cost structures present a mixed dynamic. The concentration of market revenue among a few key players indicates a mature supply base with strong technical capabilities, but it also implies that pricing power remains with incumbents. The high initial investment threshold creates a procurement cycle that is deliberate and long-term. However, the emergence of modular custom systems suggests a supply-side response to the need for flexibility. These systems aim to reduce lead times and allow for reconfiguration, addressing the cost challenge by potentially lowering integration expenses. The interplay between standardized stainless steel solutions, which offer durability and broad acceptance, and modular or polymer-based alternatives, which offer cost and flexibility benefits, is a key area where supply chain strategies are evolving. Suppliers that can offer a hybrid approach—leveraging the reliability of standard materials while providing modular adaptability—are better positioned to navigate the varying cost sensitivities of different customer segments.
Competitive Landscape and Leading Strategies
The competitive landscape is characterized by a mix of established multinational providers and specialized regional manufacturers. The market is anchored by companies with deep expertise in pharmaceutical containment and aseptic processing. Swiss provider SKAN AG stands out as a leading provider of pharmaceutical isolators with advanced containment and aseptic solutions, offering customized vacuum-compatible systems. Their positioning emphasizes high-end customization and integration, appealing to users with complex process requirements. Similarly, Swedish firm Getinge AB offers isolator systems such as ISOFLEX and ISOTEST for aseptic processing, supporting integrated vacuum operations. Their strategy leverages a broad portfolio of medical and pharmaceutical equipment, allowing for cross-selling and integration within larger facility setups.
Italian manufacturers play a significant role in the market structure. Comecer S.p.A. provides isolators and gloveboxes with integration for vacuum ovens, tray dryers, and potent API processing, focusing on the pharmaceutical manufacturing value chain. Tema Sinergie specializes in pharmaceutical isolators including aseptic and containment systems suitable for vacuum-integrated processes, targeting both production and quality control environments. These companies differentiate through application-specific expertise and regional proximity to European manufacturing hubs, allowing for responsive service and compliance alignment with EU regulations.
In the Asian market, Zhejiang Tailin Bioengineering Co., Ltd. offers vacuum isolators and containment isolators for pharmaceutical dispensing, drying, and filling of potent compounds. Their presence highlights the growing manufacturing capability in China, where cost competitiveness and expanding domestic demand drive growth. Schematic Engineering Industries in India manufactures integrated Vacuum Tray Dryer isolators in rigid and flexible barrier configurations, addressing specific drying applications with localized engineering solutions. These regional players contribute to market diversity by offering alternatives that may align better with specific cost structures or regional regulatory contexts.
Western specialized providers also maintain strong positions. Extract Technology Ltd. in the United Kingdom designs and manufactures containment and aseptic isolators, including systems compatible with vacuum processes for potent compounds and sterility testing. Their focus on containment and sterility underscores the importance of safety and validation in high-risk applications. In Spain, Azbil Telstar develops isolator technologies including dual-mode systems and vacuum-related solutions for sterile and containment applications. A notable recent development is the introduction of a new dual mode isolator system by Azbil Telstar, designed for enhanced flexibility in pharmaceutical processing. This product launch illustrates a strategic move toward versatility, allowing manufacturers to switch between operational modes to accommodate varying batch sizes or process requirements without changing equipment.
Optical Isolators Market
The competitive dynamics point to a trend of differentiation through functionality and integration. The market concentration, with the top three players holding 45.5 percent and the top five holding 62.8 percent, indicates that scale and brand reputation provide significant advantages. However, the rapid pace of innovation, such as the focus on robotic gloveless systems and dual-mode flexibility, suggests that competitive advantage is increasingly tied to technological agility. New entrants or smaller players may find opportunities by targeting niche applications, offering rapid customization, or focusing on specific regions where local service and support are critical differentiators. The evolution of the landscape is likely to see further consolidation as larger players acquire specialized technologies to broaden their portfolios, while smaller firms may need to specialize deeply to remain viable. The integration of vacuum compatibility into broader aseptic and containment solutions is becoming a standard expectation, pushing competitors to demonstrate seamless integration capabilities rather than standalone isolator performance.
Future Trends and Commercial Opportunities
Over the next three to five years, the vacuum isolators market is poised to undergo significant transformation driven by the convergence of automation, regulatory stringency, and application diversification. One key trend is the accelerated adoption of automation and robotic integration within isolator systems. As the economic case for robotic gloveless systems becomes more documented, the market will likely see a shift in procurement preferences, particularly among manufacturers handling highly potent compounds where operator safety and contamination control are paramount. This trend creates commercial opportunities for technology providers that can integrate robotics seamlessly with existing isolator architectures, as well as for service companies that can support the maintenance and validation of automated systems. Manufacturers that invest early in robotic-compatible designs may capture premium segments of the market.
A second trend is the increasing importance of modularity and flexibility in system design. The success of dual-mode systems and modular custom systems reflects a growing demand for equipment that can adapt to changing production needs without significant capital replacement. Future isolators will likely be expected to offer easier reconfiguration, faster changeover times, and interoperability with a wider range of peripheral equipment such as vacuum ovens and tray dryers. This trend opens opportunities for suppliers to develop platform-based solutions that allow customers to scale capabilities incrementally. The commercial advantage will lie in offering systems that reduce the total cost of ownership through adaptability, rather than competing solely on initial hardware price.
A third trend involves the expansion of application boundaries and regional growth. While pharmaceutical manufacturing remains the core driver, the substantial demand from semiconductor and electronics, combined with emerging interest in battery and energy storage, suggests that isolator technology will become relevant in a broader set of high-tech manufacturing environments. Asia Pacific, already a significant revenue contributor, is expected to continue its growth trajectory as manufacturing capacity expands and regulatory standards converge with global best practices. Commercial opportunities in these regions may focus on localized support, cost-optimized designs, and solutions tailored to specific regional regulatory requirements. However, risks remain. The potential for economic fluctuations affecting capital expenditure cycles could dampen demand, particularly in capital-intensive segments. Additionally, the high cost of validation and compliance could create bottlenecks if regulatory scrutiny intensifies further. Companies must also navigate the risk of technological disruption, where new containment paradigms could challenge the dominance of traditional vacuum isolator designs. Success in this environment will require a balance of innovation, cost discipline, and rigorous adherence to evolving quality standards.
Strategic Actions for Decision Makers
Manufacturers and equipment providers should prioritize investment in robotic and automated capabilities to align with the shifting demand toward safer and more efficient processing. Developing or integrating robotic gloveless solutions can provide a competitive edge, particularly in pharmaceutical segments where potent compound handling drives procurement criteria. Additionally, companies should explore modular design strategies that enhance system flexibility, allowing customers to adapt to varying batch sizes and process requirements. Offering dual-mode or reconfigurable systems can differentiate offerings in a market where customization is highly valued. Strengthening validation support and documentation readiness will also be critical, as regulatory frameworks continue to emphasize traceability and quality management integration.
For investors, the market presents opportunities in segments that combine technological advancement with scalable application potential. The concentration of market share among top players suggests that established firms with strong quality infrastructure offer stability, while innovation in automation and modularity may create value in specialized technology providers. Monitoring developments in semiconductor and battery applications, as well as regional growth in Asia Pacific, can inform investment in companies positioned to capture diversification trends. Assessing the total cost of ownership dynamics and the impact of regulatory changes on procurement cycles will be essential for evaluating long-term potential.
PW Consulting Information & Electronics Research Center
Procurement teams and end-users should focus on holistic evaluation criteria that extend beyond initial hardware costs. Given the high validation and integration expenses, assessing the total cost of ownership, including service support, validation assistance, and adaptability over the system lifecycle, is crucial. Engaging with suppliers that offer robust documentation and compliance alignment with regulations such as EU GMP Annex 1 and FDA QMSR can reduce project risk. Evaluating modular and dual-mode options may provide future-proofing benefits, allowing facilities to respond to changing production needs without major capital reinvestment. Detailed segmentation data and customized recommendations can further refine procurement strategies, and accessing comprehensive market intelligence will support informed decision-making in this evolving landscape.
Digital Isolators Market
For detailed analysis of this topic, please visit the official page: Vacuum Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The CMO Services Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape
Market Overview: Scale, Trajectory, and Structural Challenges
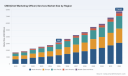
The executive marketing services market has transitioned from a niche advisory function into a core growth infrastructure for organizations navigating rapid digital and strategic change. Valued at approximately $3.2 billion in 2025, the market has expanded at a compound annual growth rate of 13.5 percent between 2020 and 2025, driven by shifting organizational priorities, the proliferation of fragmented marketing workloads, and the strategic recalibration of leadership capacity. Projections indicate the market will cross $5.9 billion by 2030 and reach $7.76 billion by 2032, reflecting sustained demand for specialized marketing leadership that bridges strategy, execution, and technology adoption. This trajectory places the CMO services space among the fastest-growing segments within the broader professional services and consulting ecosystem.
Behind the headline growth lies a structural inflection point. Organizations are no longer treating marketing leadership as a static, full-time executive appointment. Instead, they are decomposing the traditional CMO mandate into modular, outcome-oriented engagements. This shift is particularly pronounced among small and medium enterprises, which now account for a larger share of market activity than large enterprises. The fractional CMO model has become the dominant service architecture, reflecting a broader preference for scalable, variable-cost leadership that can be deployed across specific growth phases, market entries, or digital transformation initiatives. Strategic marketing consulting and digital transformation advisory represent the other major service pillars, each addressing distinct but overlapping organizational needs around positioning, go-to-market design, and technology-enabled execution.
Despite the strong growth trajectory, the market faces three interconnected challenges that will shape competitive dynamics over the next several years. First, demand fragmentation is outpacing standardization. Clients span multiple industries, growth stages, and regulatory environments, each requiring tailored leadership approaches, yet service providers are still consolidating repeatable frameworks that can scale without diluting effectiveness. Second, the talent supply chain remains constrained. The fractional CMO model depends on a pipeline of experienced marketing executives willing to operate across multiple engagements, and the limited depth of senior practitioners capable of managing AI-enabled, data-driven, and compliance-sensitive programs creates bottlenecks in high-demand verticals. Third, measurement and attribution expectations are rising faster than organizational maturity. Buyers increasingly expect clear ROI linkage, but many engagements still struggle to align strategic marketing inputs with quantified revenue outcomes, particularly in complex B2B and regulated environments. These challenges are not barriers to growth, but they are defining the terms on which providers will compete.
Key Drivers Shaping Market Expansion
Technological innovation is the most immediate catalyst reshaping demand for CMO services. Marketing organizations are adopting AI-enabled tools at a rapid pace, yet the gap between adoption and mature implementation remains wide. In 2026, three-quarters of marketing organizations reported using AI in some capacity, but only a small fraction had achieved mature deployment. This mismatch creates a structural need for strategic leadership that can translate technology capability into coherent marketing strategy, operating model design, and execution discipline. Fractional and advisory CMO engagements are increasingly anchored in AI-enabled marketing, digital transformation, and brand reinvention, particularly in sectors where experimentation velocity, personalization, and automation must be balanced with governance and compliance.
Regulatory and policy environments are also elevating the value of strategic marketing leadership. Data privacy expectations, content provenance concerns, and sector-specific compliance requirements are making marketing operations more complex, especially in healthcare, financial services, and other regulated industries. Organizations are finding that technology adoption alone does not resolve compliance risk; it requires leadership that can align marketing strategy with governance frameworks, data usage policies, and brand trust considerations. As a result, CMO services are expanding beyond growth acceleration into areas such as compliant demand generation, regulated content strategy, and cross-functional alignment between marketing, legal, and technology teams.
PW Consulting Information & Electronics Research Center
Demand-side behavior is shifting on both the buyer and consumer side. On the enterprise side, the rise of fractional leadership profiles has moved from experimental to mainstream. LinkedIn data shows a dramatic increase in profiles referencing fractional leadership roles, reflecting a broader organizational willingness to engage flexible executive talent for defined strategic missions. This adoption curve is reinforced by cost dynamics: fractional CMO engagements typically range from $3,000 to $15,000 per month, compared with full-time CMO total compensation that often falls between $275,000 and $500,000 annually. For many organizations, this cost differential is not simply about savings; it is about unlocking senior marketing leadership at a scale and duration that matches specific growth initiatives, market entries, or transformation programs.
Performance outcomes are reinforcing the demand shift. Organizations utilizing fractional CMO leadership have reported meaningfully stronger revenue growth compared with those operating without such leadership, suggesting that the model is delivering not only cost efficiency but also strategic lift. This is particularly relevant for B2B and B2B SaaS companies, where positioning, demand generation, product-led and sales-led integration, and repeatable go-to-market playbooks require experienced direction. The ability to embed leadership that can connect strategy with execution, analytical rigor, and team development is becoming a decisive factor in growth trajectories.
Cost structures and operating models are changing in parallel. Marketing budgets are under greater scrutiny, and organizations are increasingly optimizing for flexibility, specialized expertise, and measurable outcomes rather than fixed executive headcount. This is accelerating demand for service models that blend strategy, execution, analytics, and team capability building. Providers that can integrate SEO, content, analytics, and growth engineering into a coherent CMO-level engagement are positioning themselves to capture demand that would otherwise be spread across multiple agencies and consultants. The result is a market in which strategic marketing leadership is becoming more modular, more technology-integrated, and more closely tied to revenue outcomes.
Competitive Landscape and Leading Strategies
The competitive landscape is defined by a fragmented but increasingly specialized provider base. Market concentration remains relatively low, with the largest three participants holding roughly 12.5 percent of the market and the top five around 18.2 percent. This dispersion reflects the diversity of service models, industry focus, and operating approaches across the sector. Rather than competing on scale alone, leading providers are differentiating through vertical specialization, proprietary operating frameworks, and the ability to combine strategy with execution discipline.
Management Consulting Services Market
Several providers illustrate the strategic variety shaping the market. Chief Outsiders has built a broad fractional CMO and go-to-market executive practice focused on revenue growth, strategy, and execution across B2B, healthcare, and technology. Its recent executive additions reflect a deliberate push into digital transformation, AI-enabled marketing, brand reinvention, and sector-specific expansion across healthcare, financial services, technology, industrial, and infrastructure markets. This pattern signals a strategy of deepening sector coverage while broadening the leadership capability set required for complex transformation programs.
CMOx emphasizes process-driven strategy through a Functional Marketing Framework, focusing on team development, scalable growth, and agile marketing leadership. Its differentiation lies in operationalizing marketing leadership as a repeatable system rather than a purely advisory engagement. Kalungi, by contrast, has concentrated on B2B SaaS, with fractional CMO services centered on positioning, demand generation, product-led and sales-led growth integration, and execution playbooks such as T2D3. This vertical 좁히기 allows it to speak directly to the growth mechanics of software companies seeking predictable demand and scalable GTM motion.
Customer Insights Marketing Platform Market
NoGood targets high-velocity experimentation for SaaS, AI, fintech, and healthtech, blending growth engineering and rapid iteration with fractional leadership. Its positioning captures demand from technology-focused companies that value speed, testing discipline, and data-rich execution. Authentic Brand approaches the market through W-2 embedded fractional leadership, using an Authentic Growth framework that emphasizes alignment, change management, and sustained execution for B2B growth-stage companies. The emphasis on embedded leadership reflects a different answer to the same underlying need: not just strategy, but leadership presence that can drive organizational adoption.
Other participants illustrate further specialization. The Geisheker Group and Marketri focus on B2B and B2B SaaS, with emphasis on strategic direction, scalable systems, analytics, and ROI optimization. Digital Authority Partners blends fractional CMO services with analytics, SEO, and content for healthcare, regulated, and complex industries, where compliance and technical depth matter. Moving Minds emphasizes integrated strategy and execution across multi-channel marketing, serving sectors that include entertainment and private equity. Collectively, these providers demonstrate that the market is not converging on a single winning model; it is diversifying around industry focus, delivery model, and the balance between advisory and embedded execution.
The evolution of the competitive landscape is likely to move along three axes. First, consolidation will remain selective rather than wholesale. Larger consulting and services platforms may acquire or partner with specialized fractional CMO practices to add marketing leadership depth, but the market's fragmentation and vertical specificity will preserve room for independent specialists. Second, differentiation will increasingly hinge on measurable outcomes, operating frameworks, and technology integration rather than seniority alone. Providers that can connect leadership engagement to revenue growth, demand efficiency, and team capability will gain advantage. Third, new entrants will continue to emerge around AI-enabled marketing, regulated-industry compliance, and sector-specific GTM playbooks, particularly where demand is growing faster than the supply of experienced, sector-literate leaders. The market is therefore not simply expanding; it is becoming more structurally diverse, with competition shifting toward capability depth, delivery reliability, and evidenced impact.
Future Trends and Strategic Implications
Over the next three to five years, the CMO services market is likely to be shaped by three interrelated trends. The first is the maturation of AI-enabled marketing leadership. As adoption widens, the demand will shift from experimentation to integration: organizations will need leadership that can embed AI into positioning, content operations, demand generation, personalization, and performance measurement without losing strategic coherence. This creates opportunity for providers that can pair executive marketing leadership with practical AI operating models, governance, and change management. The risk is that AI capability becomes commoditized at the tool level, placing greater premium on the strategic judgment and execution discipline that sit above the technology layer.
The second trend is the continued expansion of sector-specialized fractional CMO services. Regulated and complex industries, B2B SaaS, fintech, healthtech, and industrial markets are all generating demand for leadership that understands both growth mechanics and sector constraints. Providers that develop deep vertical playbooks, compliance-aware execution, and repeatable GTM frameworks will be better positioned to command premium engagements and longer-term relationships. The counter risk is market overextension: providers that spread across too many verticals without sufficient depth may struggle to differentiate or deliver consistent outcomes.
The third trend is the growing expectation of outcome-linked engagements. As cost dynamics and performance data become more visible, buyers will increasingly compare fractional CMO engagements against full-time leadership not only on cost but on measurable revenue impact, team development, and execution reliability. This will reward providers that can articulate clear success metrics, embed analytics and accountability, and demonstrate how marketing leadership contributes to growth. A related uncertainty is the pace of organizational maturity: if measurement expectations rise faster than the ability to attribute marketing impact, some engagements may face heightened scrutiny, particularly in complex B2B and regulated contexts. The commercial opportunity lies in leading that transition rather than reacting to it.
Actionable Guidance for Decision-Makers
For organizations evaluating marketing leadership investments, the strategic priority is to match the service model to the mission. Fractional CMO engagements are most effective when tied to a defined growth phase, market entry, transformation program, or capability gap, rather than used as a generic substitute for executive headcount. Buyers should assess providers against vertical relevance, operating framework clarity, execution capability, and evidence of revenue impact, not just seniority or brand presence. For investors and strategic partners, the opportunity lies in providers that combine sector specialization with measurable outcomes and AI-ready operating models, since these characteristics are likely to command durable demand as the market matures. For service providers and ecosystem participants, the imperative is to strengthen delivery consistency, attribution rigor, and team development capabilities, because these will increasingly separate scaled impact from advisory only engagements.
Given the speed of change across AI adoption, sector demand, and leadership models, decision-makers benefit from current, segmented intelligence that goes beyond headline growth figures. Detailed segmentation data, provider benchmarking, and sector-specific demand signals can sharpen procurement decisions, partnership strategies, and investment timing. For organizations seeking a more granular view of service type dynamics, regional demand patterns, business-size adoption, and competitive positioning, the full PW Consulting research report provides expanded data and customized strategic guidance to support more precise planning.
For detailed analysis of this topic, please visit the official page: CMO(Chief Marketing Officer) Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Customer Churn Software Market’s 2026–2032 Trajectory: Decoding a 20% CAGR
By pmarketresearch, 2026-09-18
Navigating the Boom: Strategic Trends and Commercial Opportunities in the Customer Churn Software Market
Market Dynamics: Scale, Trajectory, and Core Challenges
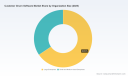
The customer churn software market has evolved from a niche retention tool into a core component of enterprise revenue operations. Between 2020 and 2025, the sector transitioned from a relatively concentrated ecosystem into a high-growth, multi-billion-dollar infrastructure market. Revenue expanded from approximately 742 million USD to over 1.8 billion USD by 2025, reflecting a compound annual growth rate of 20% across the forecast window. This acceleration is not merely a function of renewed demand; it signals a structural shift in how organizations view retention as a measurable, technology-driven discipline rather than an ad hoc customer service function. Cloud-based deployments now account for the overwhelming majority of revenue, with large enterprises driving more than two-thirds of total spend. Industry adoption remains concentrated in financial services, retail and e-commerce, and IT and telecommunications, though healthcare, media, and other verticals are expanding their footprint as subscription and recurring-revenue models proliferate across the economy.
Despite this momentum, the market faces several structural inflection points. The first is the paradox of data abundance versus actionable insight. Organizations now capture more behavioral, transactional, and engagement data than ever, yet many churn solutions struggle to translate fragmented signals into timely, prescriptive interventions. Without tight integration between data unification, predictive modeling, and workflow execution, tools risk becoming analytical dashboards rather than retention engines. The second challenge lies in economic and operational pressure. Rising compute and cloud hosting costs, particularly for workloads reliant on public IP exposure and high-throughput inference, are compressing margins for both vendors and enterprise buyers. At the same time, labor dynamics are shifting: automation and AI agents are reducing manual administrative burdens for customer success teams, but this reallocation moves cost from human labor to cloud infrastructure, demanding careful total cost of ownership planning. The third pressure is regulatory complexity. As privacy frameworks expand and enforcement intensifies around AI-driven data processing, vendors must balance predictive accuracy with compliance rigor, particularly for cross-border data flows and consent management. These forces are reshaping what it means to deliver durable retention value.
Customer Support Training Software Market
Key Drivers Reshaping the Market
Technological innovation is the most immediate catalyst. AI-driven churn prediction has moved beyond static health scores into real-time, event-triggered risk detection. Vendors are embedding AI agents capable of sentiment analysis, engagement scoring, and automated workflow recommendations directly into customer success and support environments. The recent introduction of no-code predictive AI agents illustrates how organizations are lowering the barrier to production-grade models without relying on internal data science teams, accelerating time-to-value for mid-market and enterprise deployments. This shift is particularly relevant for subscription-heavy businesses where early warning signals must be acted on within hours, not weeks. By unifying telemetry from product usage, support interactions, billing cycles, and communication channels, these platforms are transforming churn from a lagging metric into a continuous operational loop.
Policy and regulatory developments are simultaneously reshaping data strategies. New comprehensive privacy laws across multiple U.S. states have introduced stricter requirements for customer data processing, consent, and retention, while European enforcement activity has intensified around AI and advertising-related data practices. For churn platforms, this means data governance is no longer a back-office concern but a product design constraint. Vendors that embed privacy-by-design architectures, granular consent controls, and transparent model explainability are better positioned to scale across regulated industries such as financial services and healthcare. Conversely, tools that over-collect or obscure how behavioral data fuels predictions face growing procurement friction, particularly in sectors with elevated audit and compliance expectations.
Demand-side behavior is also evolving. Customers now expect seamless, personalized experiences across touchpoints, and they are quicker to disengage when value delivery feels inconsistent. In subscription and usage-based models, the lifetime value equation is increasingly sensitive to early-stage engagement, making the first 90 days of a customer journey a critical retention window. Enterprise buyers are consequently prioritizing platforms that connect churn prediction to actual retention actions—automated playbooks, in-product guidance, and cross-functional escalations—rather than standalone analytics. This behavior is reinforced by executive pressure to demonstrate retention ROI in uncertain macro conditions, where expanding existing relationships is often more capital-efficient than pursuing new logos.
Finally, cost and supply-side dynamics are influencing procurement and product architecture. Cloud cost pressures, including incremental charges tied to public IP usage, are prompting IT and finance leaders to scrutinize SaaS spend and optimize instance placement, data egress, and inference pipelines. At the same time, the broader shift from manual CS operations to AI-assisted workflows is redistributing cost structures. Organizations that once staffed large pools of administrators for health score maintenance and alert triage are reallocating budget toward cloud compute and integration work. Vendors that offer efficient model serving, flexible deployment options, and transparent pricing are gaining an edge, especially as buyers compare churn platforms against broader CX and revenue systems.
Competitive Landscape: Positioning, Differentiation, and Evolution
The market is defined by a mix of specialized customer success platforms, CX incumbents, and AI-native analytics providers. Gainsight has established a strong enterprise footprint by combining AI-powered churn prediction, health scoring, lifecycle analytics, and retention tooling within a broader customer success ecosystem. Its positioning emphasizes cross-functional orchestration for large, complex organizations that need to align product, support, and success teams around a unified view of customer health. ChurnZero has focused on subscription-oriented businesses, delivering AI-driven engagement scoring, real-time risk alerts, and churn prevention workflows tailored to recurring-revenue models. Its recent product updates reflect a clear emphasis on embedding AI agents for sentiment analysis, churn prediction, and engagement scoring directly into day-to-day CS operations, supported by leadership events that reinforce community and best-practice sharing among revenue and success leaders. Zendesk brings a different angle: an AI-powered CX platform that integrates churn prediction, analytics, and retention features into support and experience workflows, appealing to organizations that want retention signals to flow naturally from service interactions. Totango targets SaaS businesses with predictive revenue intelligence, churn reduction tools, and customer journey management, while Vitally combines data unification, automation, health scoring, and churn reduction into a platform designed for B2B SaaS teams seeking operational simplicity. Pecan AI stands apart as a no-code predictive analytics specialist, enabling business teams to convert questions into production-grade churn models without heavy data science investment, which broadens access to predictive retention capabilities across functions.
Differentiation increasingly hinges on three dimensions: integration depth, actionability, and accessibility. Platforms that connect predictive signals to automated workflows and existing CRM, support, and product stacks reduce the operational lag between detection and intervention. Those that simplify model creation and maintenance lower the skills barrier, enabling faster deployment and broader adoption beyond central data teams. Meanwhile, incumbents with extensive CX and support footprints can offer retention insights in the context of real-time service interactions, while specialist players can move faster on niche models and vertical-specific use cases. The market is evolving along two parallel tracks: consolidation among larger CX and customer success suites that seek to own the retention loop end to end, and continued entry by AI-native and no-code entrants that compress the path from data to decision. This duality creates both convergence risk and partnership opportunity, depending on how vendors handle data interoperability, model transparency, and pricing flexibility.
Forward Outlook: Trends Shaping 2026–2032
Over the next three to five years, churn software will increasingly function as an operational layer embedded within revenue and customer experience workflows, not a standalone analytics module. AI agents and automation will become standard for triage, early warning, and recommended interventions, allowing customer success teams to focus on high-value relationship moments while routine risk management is handled systematically. This transition will accelerate adoption in mid-market and growth-stage companies that previously lacked the data science capacity to operationalize prediction. At the same time, predictive accuracy will be judged not only by model performance but by the quality of the actions those models trigger, pushing vendors to invest in workflow design, playbook libraries, and integration breadth.
Customer Insights Marketing Platform Market
Data governance and compliance will become competitive differentiators rather than baseline requirements. As privacy regulation expands and enforcement tightens, platforms that provide consent-aware data processing, regional data handling options, and explainable prediction frameworks will be preferred in regulated verticals and multinational deployments. This creates an opportunity for vendors that can demonstrate measurable retention outcomes while maintaining auditable data practices. A parallel trend is the growing emphasis on total cost efficiency: organizations will increasingly evaluate churn platforms based on compute footprint, integration effort, and the degree to which automation replaces manual overhead. Solutions that combine strong prediction with economical inference and flexible deployment will be better positioned for long-term expansion.
The principal uncertainty lies in the balance between capability and complexity. As platforms accumulate more AI features, there is a risk of alert fatigue and fragmented toolchains if predictive outputs are not tightly aligned with operational realities. Economic volatility could also slow discretionary software investment, favoring vendors that can clearly tie retention gains to revenue protection and expansion. Finally, regulatory trajectories remain fluid, and any shift in data usage expectations for AI-driven analytics could reshape procurement timelines and feature requirements. Companies that plan for these variables—by prioritizing interoperability, governance, and measurable actionability—will be better prepared to capture durable value.
PW Consulting Information & Electronics Research Center
Actionable Guidance for Decision-Makers
For enterprise buyers evaluating churn software, the priority should be to connect prediction with execution. Select platforms that unify customer data across product, support, billing, and engagement channels, and that embed retention actions directly into daily workflows. Assess total cost of ownership with attention to cloud compute implications, integration effort, and the extent to which automation reduces manual overhead. In regulated environments, verify consent management, data handling options, and model transparency before scaling deployment.
For investors and strategic partners, the most promising opportunities lie in vendors that combine accessible model creation with strong workflow integration and defensible data governance. Differentiate between flashy AI features and repeatable retention outcomes by examining how quickly customers can move from risk detection to intervention, how broadly the solution fits across verticals, and how efficiently it operates at scale. Vertical specialization, no-code accessibility, and CX-centric integration are all viable paths, provided they are sustained by clear unit economics and customer success metrics.
For vendors and product leaders, the strategic imperative is to reduce friction between insight and action while maintaining compliance-ready data practices. Investments in interoperable data models, efficient inference, explainable predictions, and configurable playbooks will strengthen positioning as the market consolidates around platforms that can demonstrate measurable retention impact. As the market matures, detailed segmentation data, procurement benchmarks, and customized adoption scenarios can help refine go-to-market and investment decisions. Comprehensive research reports that break down deployment modes, organization sizes, industry verticals, regional dynamics, and competitive benchmarks offer the granularity needed to translate these trends into precise action plans.
For detailed analysis of this topic, please visit the official page: Customer Churn Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cloud-First SD-WAN Market: Why 18.5% CAGR and 18B USD Growth Redefine 2032
By pmarketresearch, 2026-09-18
Navigating the Cloud-First SD-WAN Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global Cloud-first SD-WAN market has moved decisively from a networking experiment to a foundational infrastructure discipline. In 2025, revenue is estimated at roughly 5.5 billion USD, building on a trajectory that saw the segment climb from about 3.9 billion USD in 2023 and 4.64 billion USD in 2024. The expansion continues at a compound annual growth rate of 18.5 percent through the end of the forecast window in 2032, when the market is projected to reach approximately 18.05 billion USD. This growth reflects more than incremental adoption; it captures a structural shift in how enterprises architect, secure, and optimize connectivity for distributed workloads, multi-cloud environments, and latency-sensitive SaaS applications. Geographic demand is broad-based, with North America accounting for a substantial share of 2025 revenue, Europe contributing a significant portion, Asia Pacific representing a sizeable segment, and Latin America along with the Middle East and Africa collectively rounding out the addressable base. Component-level spending is equally distributed across hardware appliances, software and virtual appliances, and managed services, indicating that buyers are no longer treating SD-WAN as a purely device-centric purchase but as a combined platform-and-services investment. Enterprise size also matters: large enterprises dominate spend, while small and medium enterprises form a rapidly growing segment as simplified, cloud-delivered models lower the operational barrier to entry. Despite a concentrated vendor landscape, with the top three players capturing just under half of market share and the top five holding roughly three-fifths, the competitive field remains active and fragmented enough to reward differentiated positioning.
Key Challenges and Inflection Points
The market is maturing, but that maturity introduces friction rather than certainty. One recurring challenge is the tension between cloud-first performance objectives and the realities of last-mile and backbone infrastructure economics. As of 2025, typical underground fiber deployment carries a median cost of about 18.00 USD per foot, with aerial deployment at roughly 8.00 USD per foot, and modest cost increases are expected to persist into 2026. These economics constrain how quickly enterprises can extend high-quality connectivity to edge sites, cloud on-ramps, and hybrid branches, which in turn shapes where SD-WAN delivers the greatest return and where legacy transport remains a limiting factor. A second challenge is the evolving regulatory backdrop. In the United States, the FCC has rolled back certain net neutrality rules during 2025 and 2026 in favor of lighter-touch oversight intended to stimulate broadband investment. While this can accelerate capacity availability in some markets, it also introduces uncertainty around service quality guarantees and traffic management practices, prompting network buyers to scrutinize the resilience and predictability of internet-based transport under SD-WAN. A third challenge lies in data sovereignty and localized control requirements. Various regions are strengthening digital policies that emphasize secure, localized handling of network traffic and infrastructure, which places new demands on SD-WAN designs that must support compliance without sacrificing cloud acceleration or global consistency. Together, these dynamics create a market at an inflection point: cloud-first SD-WAN is becoming indispensable, but successful deployments increasingly depend on infrastructure realism, regulatory agility, and sovereignty-aware architectures.
Core Drivers of Market Change
Technological Innovation and Architectural Shifts
Technology is reshaping what SD-WAN is expected to deliver. The migration of applications, data, and collaboration stacks to public cloud and SaaS platforms has made cloud-on-ramp performance, SaaS acceleration, and multi-cloud consistency first-order requirements rather than optional features. Vendors have responded with cloud-native control planes, virtual and software appliances that reduce dependence on fixed hardware at every site, and integrated security approaches that align networking with zero-trust and SASE concepts. This architectural evolution is visible in the segment mix, where software and virtual appliances command the largest share of 2025 revenue, signaling a shift toward flexible, programmatically managed deployments that scale with cloud adoption. The rise of AI-driven optimization is another accelerant. Rather than merely steering traffic across available links, newer platforms increasingly use predictive and behavioral analytics to adapt to application performance, link variability, and congestion patterns in real time. The practical effect is that SD-WAN is no longer evaluated only on connectivity resilience; buyers now assess how effectively a solution preserves user experience across cloud services, IaaS endpoints, and remote access scenarios. AI-powered optimization, SLA-backed managed delivery, and unified SASE-oriented constructs are becoming key differentiators for organizations seeking predictable performance while reducing operational complexity.
Policy, Regulation, and Data Sovereignty Pressures
Policy environments are shaping both opportunity and design constraints. The FCC’s lighter-touch regulatory posture in 2025-2026 reflects an attempt to encourage broadband investment, which could expand the availability and diversity of underlay options that SD-WAN relies on for broadband-first architectures. At the same time, data sovereignty laws and regional digital policies are pushing enterprises toward localized control of traffic flows and infrastructure, particularly for regulated industries and multinational deployments. This creates a strategic requirement for SD-WAN architectures that can enforce policy consistency globally while respecting regional data handling expectations. It also increases interest in solutions that combine centralized orchestration with distributed enforcement, and that can adapt to jurisdiction-specific security and retention mandates without fragmenting operations. The regulatory trend is therefore double-edged: it may unlock more affordable broadband-rich connectivity in some markets, while demanding greater architectural discipline in others. Enterprises that treat compliance and sovereignty as design inputs rather than afterthoughts are better positioned to move quickly as rules evolve.
Demand-Side Behavior and Cost Structure Dynamics
Demand is being rewritten by how organizations consume technology. Work-from-anywhere models, distributed manufacturing, multi-site retail and hospitality footprints, and accelerated digital transformation have increased the number of edge locations that must be connected economically and reliably. At the same time, enterprise buyers are pressing for measurable outcomes: reduced MPLS dependency, better cloud and SaaS performance, simpler operations, and tighter alignment between networking and security spend. The cost structure of the underlying infrastructure reinforces this demand shift. Data center construction costs average about 10-11 million USD per megawatt, with electricity representing roughly 40 percent of operating expenses for large facilities. These figures matter because they influence where processing and aggregation occur, how much traffic is backhauled, and whether organizations favor distributed edge resilience over centralized chokepoints. When facility and power costs rise, the value proposition of efficient, broadband-rich, cloud-direct connectivity becomes more compelling, especially for enterprises seeking to reduce transport waste and optimize cloud egress patterns. Combined with the growing appetite for managed services, this demand-side pressure is steering many organizations toward solutions that integrate connectivity, optimization, and ongoing operations into a more predictable commercial model.
PW Consulting Information & Electronics Research Center
Competitive Landscape and Leading Strategies
The vendor field reflects a spectrum of strategies rather than a single winning formula. Aryaka Networks positions around a cloud-first SD-WAN model backed by a global private network backbone, multi-cloud and SaaS acceleration, and Unified SASE delivered as a service, appealing to organizations that want cloud connectivity optimization with a managed, globally consistent backbone. Bigleaf Networks focuses on AI-powered cloud-first SD-WAN for internet optimization, redundancy, and high-performance cloud and SaaS access, with SLA-backed managed delivery that targets predictable performance for business-critical applications. Cisco Systems offers both Catalyst and Meraki SD-WAN portfolios, including cloud on-ramp capabilities for multi-cloud, IaaS, and SaaS optimization, alongside integrated security, which makes its approach attractive to enterprises seeking broad portfolio reach and familiar operational models. Fortinet emphasizes Secure SD-WAN with integrated security, cloud-native architecture, and AI-driven optimization designed for cloud-first deployments, aligning networking with a broader security-first narrative. Versa Networks markets a Universal SASE platform with SD-WAN aimed at global, security-focused, and cloud-first businesses by converging networking and security in a single fabric. VMware, under Broadcom, continues to push VMware SD-WAN with a cloud-first architecture suited to hybrid and multi-cloud environments and SaaS performance optimization, leveraging its strong enterprise footprint. Palo Alto Networks centers its Prisma SD-WAN on application-performance-centric outcomes with integrated security for cloud and SASE environments, which resonates with organizations prioritizing user experience and consolidated security policy. HPE Aruba targets cloud-first transformations with EdgeConnect SD-WAN designed to retire MPLS in favor of broadband for resilience and cost efficiency, often pairing connectivity modernization with broader edge and campus strategies.
Strategic Positioning and Differentiation
What separates leaders is not merely feature breadth but the coherence of their value proposition relative to enterprise priorities. The most durable positions are emerging around three axes: cloud performance, security integration, and operational model. Vendors that can demonstrably improve SaaS and IaaS experience while reducing reliance on expensive private transport are gaining traction, especially as broadband ecosystems expand and enterprises seek cost-efficient resilience. Those that bind SD-WAN closely to security and SASE-oriented architectures are helping buyers consolidate policy, simplify audits, and align network behavior with zero-trust expectations. Meanwhile, managed-service and SLA-backed models are becoming a competitive lever for organizations that want outcomes without expanding internal networking complexity. Differentiation is increasingly less about whether SD-WAN is available and more about how well it fits the way an enterprise actually uses cloud services, manages risk, and operates networks day to day. That is why deployments are diverging by use case: some organizations prioritize global backbone consistency and managed cloud acceleration, while others focus on AI-driven internet optimization, security convergence, or MPLS replacement economics.
Ongoing Developments and Market Evolution
Recent moves underscore how quickly the market is evolving around resilience, cryptography readiness, and deployment economics. In May 2026, Gorilla Technology Group Inc. signed an MOU with CHELPIS Quantum Corporation to integrate post-quantum cryptography into an SD-WAN platform, advancing toward commercial availability in April 2026, a signal that quantum-safe networking is moving from concept to product roadmaps. In April 2026, AT&T Business launched a post-quantum cryptography secure SD-WAN service powered by Cisco 8000 Series routers, positioning itself among the first major North American providers to offer quantum-resilient networking at service scale. The same month, HPE Aruba announced that Southern Sun hotel group had implemented EdgeConnect SD-WAN to replace MPLS with broadband, aiming for improved resilience and cost reduction. These developments illustrate three simultaneous threads: the rise of cryptography-forward networking as a future-proofing consideration, the role of major service providers in bringing advanced SD-WAN capabilities to market at scale, and the continued practical reality of MPLS-to-broadband transitions in real enterprise environments. The competitive landscape is likely to continue evolving through consolidation among broader platform vendors, continued specialization from cloud-first and security-centric challengers, and new entry points for providers that can combine network services, managed operations, and resilience guarantees in ways that match enterprise buying preferences.
Future Outlook: Three to Five Years Ahead
Trend 1: Security-Network Convergence as a Default
Over the next three to five years, the distinction between SD-WAN and security architecture is likely to keep narrowing. Enterprises will increasingly treat converged networking and security not as a procurement preference but as an operational baseline, especially as workforces, branches, and cloud touchpoints multiply. The commercial opportunity here lies in platforms that can deliver consistent policy, reduce tool sprawl, and simplify compliance across regions. The uncertainty is whether consolidation will accelerate through acquisitions and platform bundling or whether modular ecosystems will persist for organizations that value best-of-fit flexibility over single-vendor simplicity.
Trend 2: Performance-Centric, Cloud-Direct Connectivity
Cloud-first SD-WAN will continue to shift from link aggregation to application-aware optimization that prioritizes SaaS, IaaS, and collaboration performance. As broadband availability improves in some markets and enterprises become more comfortable with internet-based transport, more deployments will pursue cloud-direct patterns that reduce backhaul inefficiencies and improve user experience. The upside is significant for vendors and service providers that can prove measurable performance improvements and predictable SLAs. The risk is that underlay quality remains uneven across regions, and that infrastructure economics, including fiber deployment costs and data center operating expenses, may slow the pace at which some organizations can fully transition away from legacy transport.
Trend 3: Cryptographic Readiness and Resilience as Buying Criteria
Quantum-safe cryptography and broader resilience planning are likely to move from niche concerns to mainstream evaluation criteria, particularly for regulated sectors and organizations with long infrastructure life cycles. Early platform and service announcements already point in this direction, and buyers are beginning to ask how networking investments will hold up against future cryptographic and threat-evolution requirements. The opportunity is for vendors and operators to offer clear roadmaps, interoperable designs, and upgrade paths that reduce the risk of stranded assets. The challenge is that standards, migration timing, and operational complexity remain unsettled, so enterprises will need to balance urgency with pragmatism to avoid overinvesting in immature capabilities.
Worldwide Cloud VPN Market
Strategic Recommendations for Decision-Makers
For Enterprise Buyers and Network Leaders
Evaluate cloud-first SD-WAN against actual application behavior, not just topology diagrams. Prioritize solutions that deliver measurable SaaS and multi-cloud performance, predictable internet transport resilience, and security integration that aligns with your compliance posture. Where MPLS retirement is on the table, validate broadband quality at representative sites before scaling, and favor designs that can accommodate regional data sovereignty requirements without fragmenting operations. For organizations with long deployment horizons, ask vendors how post-quantum and cryptographic readiness will be introduced over time, so current purchases do not become obstacles to future compliance or resilience goals.
For Investors and Strategic Planners
The market’s 18.5 percent CAGR and projected scale through 2032 suggest durable demand, but returns will depend on differentiation in cloud performance, managed operations, and security convergence rather than broad connectivity alone. Interest is likely to remain strongest in platforms that can combine cloud acceleration, AI-driven optimization, SLA-backed delivery, and credible cryptographic-resilience roadmaps. Watch for consolidation that bundles SD-WAN into wider SASE or edge platforms, and for service provider moves that wrap advanced SD-WAN capabilities into managed offerings. In assessing opportunities, weigh not only vendor momentum but also the realism of their infrastructure assumptions, since fiber deployment costs and data center operating expenses will continue to shape where cloud-first architectures deliver the strongest economics.
For Manufacturers, Service Providers, and Channel Teams
Position offerings around outcomes that map directly to enterprise buying criteria: cloud and SaaS performance, resilience under variable internet conditions, operational simplicity, and clear security alignment. Managed and service-based models are gaining relevance because they reduce the internal burden of deployment and optimization, especially for distributed footprints. Differentiation will increasingly hinge on how well a solution handles sovereignty-aware policy, cryptographic futures, and real-world underlay variability. Teams that can translate technical capabilities into predictable business outcomes, backed by reference deployments and transparent service guarantees, are best placed to capture demand as the market matures.
Market momentum in cloud-first SD-WAN is clear, but the decisive question for any organization is how well its network strategy matches its cloud usage, regulatory exposure, and operational model. The fuller picture—detailed segmentation, regional dynamics, vendor-by-vendor positioning, use-case adoption patterns, and customized scenario analysis—can be explored in PW Consulting’s complete research report on the Cloud-first SD-WAN market, where the data and implications are developed in depth for practical decision-making.
Worldwide WAN Optimization Controllers Market
For detailed analysis of this topic, please visit the official page: Cloud-first SD-WAN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Why Cloud SaaS Is Driving the 8.75% CAGR in Commercial Debt Collection Tools
By pmarketresearch, 2026-09-18
The Commercial Debt Collection Tools Market: Navigating Growth, Innovation, and Regulatory Complexity
Market Overview and Core Challenges
The commercial debt collection tools market has entered a phase of sustained expansion, with total industry revenue climbing from approximately $512.8 million in 2020 to $780.0 million in 2025. This trajectory reflects a compound annual growth rate of 8.75 percent across the historical review period and a projected continuation of this pace through the 2026–2032 forecast window, reaching an estimated $1.4 billion by the final forecast year. The scale and consistency of this growth signal a structural shift rather than a cyclical correction. Organizations across credit origination, receivables management, healthcare revenue cycle, utilities, and telecommunications are increasingly treating collection technology as a core operational capability rather than a back-office compliance exercise.
Despite the upward momentum, the market faces several structural friction points that will shape competitive outcomes over the next five years. First, the regulatory environment is tightening at both the state and federal levels, creating a fragmented compliance landscape that complicates deployment across jurisdictions. Debt collection tools must now account for evolving consumer data privacy mandates, expanded protections around medical debt and credit reporting, and heightened scrutiny of automated decision-making. Second, the rapid adoption of cloud-based SaaS platforms has raised expectations around integration depth, real-time data exchange, and behavioral engagement, forcing legacy providers to accelerate modernization cycles while managing technical debt. Third, rising labor costs and talent shortages in traditional collection operations are compressing margins for organizations that still rely heavily on manual workflows, making automation and AI-driven prioritization increasingly non-negotiable.
These pressures are not merely operational headwinds; they are redefining what buyers expect from a collection platform. The organizations that will capture disproportionate value are those that can simultaneously deliver compliance resilience, measurable recovery improvements, and seamless customer engagement. The market is large enough and growing fast enough to reward focused innovation, but only for solutions that align technology with the operational realities of modern receivables management.
Key Drivers Shaping Market Evolution
Technological Innovation and AI-Native Architectures
The most visible driver of market growth is the maturation of AI-native collection platforms that move beyond simple task automation to intelligent workflow orchestration. Modern tools now prioritize accounts based on predicted payment probability, route outreach through optimized multi-channel sequences, and adjust messaging dynamically based on behavioral signals. This shift directly addresses the operational cost pressures noted across the sector, where automated platforms have been reported to reduce collection operating costs by 40 to 60 percent while improving recovery rates by 10 to 15 percent. The value proposition has matured from labor displacement to outcome optimization: collections teams spend less time on low-yield contacts and more time on accounts with the highest recovery potential.
This technological trajectory is reinforced by deeper data integration capabilities. The integration of open banking data and real-time financial insights into collection workflows is expanding the precision of payment propensity models and enabling more tailored settlement offers. Such capabilities allow organizations to anticipate liquidity constraints earlier and intervene before accounts deteriorate into charge-off territory. As these data pipelines become more standardized, platforms that can synthesize internal account history, external financial signals, and behavioral engagement data will set the performance benchmark for the industry.
Regulatory Acceleration and Compliance as a Strategic Differentiator
Regulatory activity has intensified on multiple fronts, transforming compliance from a baseline requirement into a competitive differentiator. U.S. states accelerated privacy and debt collection reforms throughout 2026, with stronger enforcement of comprehensive consumer data privacy laws and expanded protections focused on medical debt and credit reporting. At the federal level, the House Energy and Commerce Committee released the SECURE Data Act in April 2026, proposing a comprehensive framework that would preempt certain state privacy requirements for businesses processing significant consumer data. Meanwhile, the Consumer Financial Protection Bureau continues to sharpen its focus on collection practices, including updates to Regulation F, third-party disclosure expectations, and scrutiny of AI-driven decision-making in collection processes.
For vendors and buyers alike, this environment raises the bar for platform design. Tools that embed compliance controls directly into workflow automation, maintain auditable decision trails for automated outreach, and adapt quickly to jurisdiction-specific rule changes will face fewer deployment barriers. The regulatory complexity also increases the cost of inaction for organizations relying on fragmented or manual processes, as compliance missteps carry growing financial and reputational risk. This dynamic is pushing procurement teams to evaluate platforms not only on recovery performance but also on their ability to scale compliance governance across portfolios and geographies.
Demand-Side Shifts and the Customer Retention Imperative
On the demand side, enterprises are increasingly reframing collections as a customer experience function rather than a purely recovery-driven operation. Borrowers, patients, and utility customers now expect flexible payment options, transparent communication, and digital self-service pathways. Behavioral science-based engagement has emerged as a key response to this shift, with platforms designing outreach sequences that reduce friction, preserve relationships, and improve voluntary repayment rates. In sectors such as telecommunications, utilities, and financial services, the cost of churn and reputational damage now rivals the direct cost of delinquency, making recovery strategies that protect long-term customer value more attractive than aggressive contact models.
This demand evolution is also reshaping buyer segmentation. Large enterprises continue to lead in absolute adoption, but small and medium-sized organizations are accelerating their transition to cloud-based tools as deployment barriers fall and subscription pricing models become more accessible. Mid-market buyers are particularly interested in platforms that consolidate receivables visibility, payment reconciliation, and automated follow-up into a single workflow, reducing the operational friction of managing multiple point solutions. The result is a broadening demand base that values both enterprise-grade compliance and mid-market usability.
Cost Structure Pressures and the Automation Economics Case
The economic argument for modern collection tools has strengthened as labor costs rise and collection agencies, creditors, and receivables teams confront tighter operating margins. Automation is no longer positioned as a future efficiency play; it is increasingly treated as a present-day cost containment strategy. Platforms that can centralize account prioritization, payment posting, dispute handling, and multi-channel outreach reduce the manual burden that historically inflated cost-to-collect ratios. At the same time, the ability to allocate human agents to higher-value cases improves conversion on complex accounts and reduces burnout in collection teams.
Debt Collection Software Market
This cost structure shift is amplifying the appeal of cloud-based deployment models. Organizations are favoring solutions that can scale elastically with portfolio volume, integrate with existing ERP, CRM, and payment gateway systems, and avoid the long lead times associated with on-premise rollouts. The combination of rising labor expenses, stronger automation economics, and cloud-first deployment preferences is accelerating replacement cycles for legacy systems and expanding the addressable market for next-generation platforms.
Competitive Landscape and Leading Strategies
The competitive field is led by a diverse group of vendors that reflect different points of emphasis within the broader collection technology stack. C&R Software has built its position around an enterprise SaaS and AI-native platform that spans debt collection, recovery, credit risk, and agency management. Its strategic focus on handling large portfolios with integrated compliance, automation, and analytics aligns with the needs of creditors and agencies managing complex, high-volume books of business. The company’s recent partnership to integrate real-time open banking data and financial insights into its collection and logic platforms illustrates a broader move toward enriched decisioning and lifecycle intelligence.
HighRadius approaches the market from the accounts receivable and order-to-cash angle, offering an AI-powered autonomous finance platform that emphasizes automated collection workflows, dunning, prioritization, and AR management for mid-market and enterprise customers. Its differentiation lies in embedding collection automation within the broader receivables and cash application process, appealing to organizations that want to improve the full O2C cycle rather than optimize collections as an isolated function.
Symend has carved out a distinct position by combining AI with behavioral science to shape engagement sequences that improve recovery while protecting customer relationships. Its platform is especially relevant in telecommunications, utilities, and financial services, where retention and brand trust carry substantial long-term value. The launch of an embedded bill payment protection solution demonstrates how collection-oriented platforms are expanding into adjacent revenue protection and churn reduction use cases, creating new value levers for enterprise clients.
Kolleno focuses on AI-powered AR and collections automation for mid-size businesses, centering on centralized receivables, payments, reconciliation, and automated follow-ups. Its growth reflects the increasing appetite among mid-market organizations for consolidated workflows that reduce manual reconciliation and improve cash visibility without requiring enterprise-scale implementation complexity. Latitude by Genesys offers a more comprehensive recovery-oriented platform for creditors, debt buyers, and agencies, with strong support for pre- and post-charge-off accounts, workflow automation, and multi-channel engagement. Its positioning suits organizations that need end-to-end case management across the full recovery lifecycle.
Collect! by Comtech Systems and Finvi round out the competitive set with flexible platforms aimed at agencies, creditors, debt buyers, and healthcare revenue cycle environments. Collect! emphasizes scalability, automation, compliance tooling, and deployment flexibility across cloud and on-premise environments, while Finvi’s portfolio of receivables, recovery, and collections platforms targets both agency operations and specialized workflows such as healthcare RCM. Recent ecosystem expansions, including partner marketplace additions and enhanced consumer portal and digital communication capabilities, show that even established platforms are investing in broader integration and customer-facing digital experiences.
Several strategic patterns are emerging across this landscape. First, differentiation is increasingly defined by depth of data integration, behavioral engagement design, and compliance automation rather than by basic case management features. Second, the market is showing signs of both convergence and specialization: some vendors are broadening into adjacent AR, risk, and payment protection workflows, while others are deepening vertical expertise in sectors such as healthcare, utilities, and financial services. Third, ecosystem partnerships are becoming a key growth lever, as platforms integrate open banking data, payment gateways, insurance products, and digital communication providers to extend functionality without building every capability in-house. This combination of consolidation among larger platforms and continued room for specialized entrants suggests a market that will remain dynamic rather than rapidly consolidating into a single dominant architecture.
Future Trends and Commercial Opportunities
Over the next three to five years, the market is likely to be shaped by three interconnected trends. The first is the mainstreaming of AI-driven decisioning and behavioral engagement as standard platform capabilities. Predictive prioritization, adaptive outreach sequencing, and automated settlement modeling will move from differentiating features to baseline expectations. The commercial opportunity here lies not only in building smarter algorithms but in operationalizing them within compliant, auditable workflows that lenders, agencies, and AR teams can trust at scale.
PW Consulting Information & Electronics Research Center
The second trend is the continued expansion of ecosystem-based architectures. Platforms that connect seamlessly to open banking data sources, payment processors, CRM and ERP systems, and specialized communication or insurance partners will gain an advantage in deployment speed and functional breadth. As data-sharing standards and partner marketplaces mature, the most successful vendors will be those that can orchestrate a modular stack while maintaining a coherent user experience and consistent compliance posture.
B2B Debt Collection Services Market
The third trend is the growing intersection of collections, customer experience, and revenue protection. As organizations recognize that collection outcomes affect retention, lifetime value, and brand perception, tools that balance recovery performance with relationship preservation will see stronger demand. This opens opportunities for embedded protection products, proactive prevention workflows, and digital self-service experiences that reduce delinquency before it escalates. At the same time, uncertainty remains around the trajectory of federal privacy preemption, state-level enforcement variability, and regulatory treatment of AI-based decisioning in sensitive debt categories such as medical debt and buy-now-pay-later accounts. Organizations that build flexibility into their compliance and data governance frameworks will be better positioned to navigate this evolving landscape.
Strategic Recommendations for Decision Makers
For executives evaluating collection technology strategy, the immediate priority is to assess platforms against the combination of recovery performance, compliance automation, and customer engagement quality rather than treating any single metric in isolation. Procurement and operations leaders should prioritize solutions that can demonstrate measurable reductions in manual workload, clear audit trails for automated decisions, and integration paths that fit existing ERP, CRM, and payment ecosystems. Buyers should also stress-test vendor roadmaps for open banking connectivity, behavioral engagement capabilities, and the ability to adapt to state and federal rule changes without extensive re-configuration.
For investors and strategic partners, the most attractive opportunities lie with providers that have already moved beyond task-level automation into predictive prioritization, multi-channel orchestration, and vertical-specific workflow depth. Capital and partnership attention should favor platforms that can show credible unit economics, ecosystem integration momentum, and a clear response to regulatory complexity. Entry points that combine collection functionality with adjacent AR, payment protection, or revenue cycle capabilities may offer stronger differentiation than incremental point-solution plays.
For technology and product leaders, success will increasingly depend on balancing innovation with governance. AI-driven features can unlock meaningful recovery and efficiency gains, but they must be paired with explainable decision logic, data minimization practices, and jurisdiction-aware compliance controls. Organizations that align product development with these constraints while continuing to expand digital self-service and behavioral engagement options will be better placed to capture long-term demand. Given the pace of regulatory change, data integration evolution, and competitive repositioning, detailed market intelligence that maps vendor capabilities, segment dynamics, and regional variation can help decision makers move from broad direction to precise execution.
For detailed analysis of this topic, please visit the official page: Commercial Debt Collection Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Insurance Market to Reach $321 Billion By 2032, Growing at 14.25% CAGR
By pmarketresearch, 2026-09-17
Navigating the Digital Insurance Transformation: Strategic Intelligence for 2026 and Beyond
The insurance industry is undergoing a fundamental restructuring, driven by the convergence of cloud infrastructure, artificial intelligence, and evolving regulatory demands. As we enter 2026, the distinction between traditional insurers and digital-native competitors is blurring. The ability to process policies, manage claims, and engage customers through fully digital channels is no longer a differentiator; it is a baseline requirement for survival and growth.
PW Consulting's latest Digital Insurance Market report is designed to provide enterprise leaders with the clarity needed to navigate this complex landscape. This research does not merely track revenue figures; it decodes the operational shifts, technological adoption curves, and competitive maneuvers that are defining the next decade of insurance value chains. By integrating historical performance data with forward-looking forecasts, this analysis offers a strategic compass for C-suite executives, product leaders, and investment analysts.
Worldwide Blockchain Insurance Market
Macro Growth Trajectory and Market Scale
The scale of the digital insurance market reflects a sector in hyper-expansion. Building on a robust historical foundation from 2020 through 2025, the market has demonstrated consistent upward momentum. In 2025, the overall market revenue reached 126.36 billion USD, marking a significant increase from 110.6 billion USD in 2024 and 96.5 billion USD in 2023. This trajectory underscores the accelerating digitization of insurance products and services across the global economy.
Looking ahead, the forecast period from 2026 to 2032 projects sustained aggressive growth. The market is expected to climb to 144.37 billion USD in 2026, surpassing 164.94 billion USD by 2027, and reaching 188.45 billion USD by 2028. The long-term outlook remains strong, with revenue projections extending to 321.08 billion USD by 2032. This expansion is underpinned by a compound annual growth rate over the forecast period, signaling that digital transformation is not a temporary trend but a structural shift in how risk is underwritten and managed.
For strategic planners, these figures represent more than just top-line growth. They indicate increasing capital allocation toward digital capabilities, rising customer expectations for seamless digital interactions, and the compounding value of data-driven decision-making. However, capturing this growth requires navigating a fragmented ecosystem of technologies and regional nuances, details of which are fully mapped out in our comprehensive report.
Segmentation Drivers: Technology and Product Dynamics
The market is segmented across multiple dimensions that reveal where value is being created and where competition is most intense. Technological adoption is a primary driver, with cloud computing, AI and machine learning, IoT and telematics, and blockchain solutions forming the backbone of modern insurance operations. The integration of these technologies varies significantly by use case, from core policy administration to real-time claims assessment.
Beyond technology, the composition of insurance types plays a critical role in market dynamics. Life insurance, property and casualty, and health insurance segments each present unique digital challenges and opportunities. The interplay between these segments influences how carriers prioritize investments and how technology vendors tailor their offerings. For instance, the demands of health insurance digitization often diverge sharply from those of property and casualty modernization, requiring distinct strategic approaches.
Our report delves deep into these segmentation splits, providing actionable intelligence on which technologies are gaining traction and how different insurance types are adapting to digital pressures. Rather than presenting static percentages, we analyze the strategic implications of these splits, helping organizations identify where to allocate resources for maximum impact. The full breakdown of these dynamics, including regional influences and application-specific adoption rates, is available in the complete market intelligence package.
Competitive Landscape and Key Players
The competitive environment is characterized by a mix of established platform providers, agile insurtech startups, and traditional insurers undergoing digital transformation. Understanding the positioning of key players is essential for benchmarking and partnership strategies.
Guidewire Software continues to be a pivotal force, providing cloud-based core insurance platforms tailored for property and casualty insurers. Their focus on digital policy administration, claims management, and billing solutions addresses the foundational needs of large carriers modernizing legacy systems. Similarly, Duck Creek Technologies offers a SaaS insurance core platform with low-code tools that enable configurable digital experiences, supporting P&C carriers in achieving flexibility and speed to market.
On the innovation frontier, Shift Technology specializes in AI-driven solutions for fraud detection, claims automation, and decisioning agents. Their tools are used by major insurers globally to enhance accuracy and efficiency in critical operational workflows. Meanwhile, digital-first insurers like Lemonade are redefining customer expectations by using AI and chatbots for renters, homeowners, car, and pet insurance with fully online application and claims processes. These companies demonstrate how technology can be embedded into the core value proposition rather than merely supporting backend operations.
Additional players such as BriteCore and Next Insurance further diversify the landscape. BriteCore provides a cloud-native core platform for P&C insurers featuring AI-embedded tools, while Next Insurance focuses on digital platforms for small business insurance with instant quotes and online purchasing tools. The presence of these varied competitors highlights the multi-front nature of the digital insurance battle, where core system modernization, customer experience innovation, and niche market disruption occur simultaneously.
Recent Developments and Industry Momentum
Recent news cycles highlight the rapid pace of innovation and operational updates within the sector. In early 2026, Aetna launched a simplified, digital-first benefits onboarding experience for members, utilizing RCS-enabled text messaging and self-service tools. This move exemplifies the push toward frictionless member engagement and the adoption of modern communication channels in health benefits administration.
Simultaneously, Shift Technology advanced its agentic AI models in Shift Claims, enhancing capabilities for policy data interpretation, claims assessment, and anomaly detection. These innovations point toward a future where intelligent agents handle increasingly complex decision-making tasks, reducing manual intervention and improving outcomes. Additionally, Duck Creek Technologies saw recognition for core system modernization efforts, with Suncorp leveraging the Duck Creek platform to drive transformation. Such developments signal that core system upgrades remain a top priority for established insurers seeking to compete in a digital-first environment.
These events are not isolated; they are part of a broader pattern of accelerating digital maturity. Our report contextualizes these developments within the wider market trajectory, helping leaders understand which innovations are likely to become industry standards and which represent niche experiments.
Market Dynamics: Regulation, Compliance, and Operational Costs
The digital insurance landscape is heavily influenced by regulatory and operational factors that can dictate strategy and cost structures. In California, CPPA regulations on cybersecurity audits, risk assessments, and automated decision-making technology for insurance companies took effect on January 1, 2026. These rules impose new obligations on insurers deploying digital tools, particularly those involving algorithmic decision-making. Complying with these standards requires robust governance frameworks and transparent data practices.
At the federal and state level in the U.S., additional privacy laws effective January 1, 2026, introduce obligations for opt-out mechanisms and data protection assessments. These measures impact digital insurers that rely on extensive data collection for personalization and risk modeling, necessitating careful attention to user consent and data handling protocols.
Internationally, the EU Digital Operational Resilience Act (DORA) has been fully in effect since January 2025, mandating ICT risk management and third-party oversight for insurance entities. This regulation forces insurers to scrutinize their technology vendors and cloud dependencies, adding a layer of complexity to digital transformation initiatives. Organizations must ensure that their digital ecosystems are resilient against cyber threats and operational disruptions.
Digital Insurance Market
Operational costs also vary significantly based on compliance and infrastructure requirements. Managed HIPAA-compliant cloud hosting for digital health and insurance-related data ranges from 300 to 1,200+ USD per month depending on scale and features. This variable cost structure underscores the importance of right-sizing technology investments and understanding the total cost of ownership for digital insurance platforms.
Our report provides a detailed analysis of these dynamics, helping organizations anticipate regulatory shifts, manage compliance risks, and optimize operational expenditures. The full assessment of regulatory impacts and cost structures is elaborated upon in the complete market study.
Strategic Value for 2026 Decision-Making
For enterprises operating in or adjacent to the insurance sector, the insights contained in this report offer tangible strategic value. The concentration of the market, with CR3 at 18.5 percent and CR5 at 24.2 percent, indicates a landscape that is still relatively fragmented, leaving room for both consolidation and disruptive entry. Understanding where market power lies and how it is shifting is critical for partnership, acquisition, and competitive strategies.
Decision-makers can leverage this research to:
- Align technology roadmaps with emerging adoption trends in cloud, AI, and IoT.
- Evaluate competitive positioning relative to key platform providers and digital-native insurers.
- Anticipate regulatory changes and integrate compliance into product design from the outset.
- Assess market entry opportunities based on segmentation dynamics and regional growth potential.
- Optimize investment decisions by understanding the cost implications of digital infrastructure and data management.
The report is structured to move beyond high-level observations, offering operational insights that can be directly applied to strategic planning processes. From technology selection criteria to risk mitigation frameworks, the analysis covers the spectrum of considerations that leaders face in 2026.
Conclusion: Access the Complete Intelligence
The digital insurance market is at a pivotal juncture where technology, regulation, and customer expectations converge to reshape the industry. The growth trajectory, competitive movements, and regulatory developments outlined above provide a snapshot of the forces at play. However, the full depth of this transformation requires a more granular examination of segmentation data, regional nuances, and detailed company profiles.
PW Consulting's Digital Insurance Market report delivers the comprehensive intelligence needed to make informed, forward-looking decisions. By synthesizing market size forecasts, segmentation analysis, competitive profiling, and dynamic industry factors, this research equips stakeholders with the tools to navigate uncertainty and capitalize on emerging opportunities.
To access the complete dataset, detailed regional breakdowns, and actionable strategic recommendations, we invite you to explore the full report. The complete market intelligence is designed to support your organization's specific goals, whether you are optimizing core operations, launching new digital products, or evaluating investment opportunities in the insurance technology space.
For detailed analysis of this topic, please visit the official page: Digital Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DevSecOps Tool Market Hits $10.1B in 2025, surging 27.14% CAGR Through 2032
By pmarketresearch, 2026-09-17
The DevSecOps Tool Market in 2026: Strategic Intelligence for Enterprise Decision-Makers
The Imperative of Embedded Security
The software delivery landscape has fundamentally shifted. Security is no longer a final checkpoint before deployment; it is an intrinsic property woven into every stage of the development lifecycle. As organizations accelerate their digital transformation agendas, the DevSecOps tool market has emerged as a critical infrastructure layer that determines both velocity and resilience. Our latest market research provides a rigorous examination of this rapidly evolving sector, offering enterprise leaders the clarity required to make informed technology procurement, partnership, and investment decisions throughout 2026 and beyond.
DevSecOps Tool Market
This report is not merely a retrospective analysis of market growth. It is a forward-looking strategic instrument designed to help CISOs, VP of Engineering, procurement leaders, and board-level executives navigate a vendor ecosystem that is consolidating, differentiating through AI capabilities, and responding to an intensifying regulatory environment. The insights contained within are structured to translate raw market dynamics into actionable decision frameworks.
Understanding the Scale and Trajectory of the Market
The DevSecOps tool sector has experienced an extraordinary growth arc over the past half-decade. Between 2020 and 2025, the overall market expanded from a modest base to surpass the one billion dollar threshold, reflecting the compounding impact of cloud migration, regulatory pressure, and the mainstreaming of security-left practices. The momentum does not decelerate. Forecasts extending through 2032 indicate a sustained compound annual growth rate that underscores the structural rather than cyclical nature of this expansion.
For enterprise planners, this trajectory signals more than just vendor opportunity. It indicates that DevSecOps is transitioning from a competitive differentiator to a baseline operational requirement. Organizations that delay foundational investments risk falling behind peers who are already embedding automated scanning, policy enforcement, and continuous compliance into their delivery pipelines. Conversely, enterprises that approach tool selection with strategic discipline can achieve meaningful reductions in technical debt, operational friction, and exposure windows.
Our research models multiple forward scenarios to account for variables such as procurement cycle shifts, platform consolidation trends, and the emergence of AI-assisted security workflows. Rather than presenting a single deterministic forecast, the report equips leaders with a range of plausible outcomes, enabling scenario-based budgeting and vendor negotiation strategies that remain robust under uncertainty.
What the Research Delivers: Operational Content and Decision Frameworks
Deep market intelligence achieves its value only when it is directly applicable to operational decision-making. This study is structured to bridge the gap between high-level market awareness and the granular evaluations that procurement and engineering teams must perform. The following components define the analytical core of the report:
- Comprehensive platform capability mapping that evaluates how leading solutions address static analysis, software composition analysis, dynamic testing, infrastructure-as-code validation, container security, and correlated risk visibility across the full software development lifecycle.
- Deployment architecture analysis contrasting cloud-native delivery models with on-premise and hybrid patterns, including considerations around data residency, integration complexity, and total cost of ownership over multi-year horizons.
- Industry vertical applicability assessments that identify which solution categories align best with the regulatory and operational profiles of sectors such as financial services, healthcare, government and defense, telecommunications, and retail.
- Vendor consolidation and platformization evaluation, helping enterprises determine when to pursue integrated suites versus specialized point tools, based on organizational maturity, existing technology debt, and internal skill distribution.
- Procurement and negotiation intelligence that translates market positioning trends into practical guidance for license structuring, multi-year commitments, and service-level expectations.
- Operational efficiency benchmarking that quantifies the impact of automation maturity on developer workflows, including the hidden labor costs associated with manual approvals and redundant scanning processes.
These components are designed to be referenced during tool evaluation, architecture planning, and budgeting cycles. Each section is grounded in observable market signals, vendor behavior, and procurement patterns, allowing leaders to use the report not as a one-time read but as an ongoing reference during strategic planning.
Competitive Landscape: Platform Strategy, Differentiation, and Consolidation Signals
The vendor ecosystem in the DevSecOps space is characterized by a mix of established platform players, specialized security innovators, and large enterprise software vendors extending into developer-centric security workflows. With a moderately concentrated market structure, competitive dynamics are shaped by portfolio breadth, integration depth, and the ability to reduce tool sprawl for enterprise customers.
Several platform leaders define the current strategic conversation. Checkmarx continues to advance its unified DevSecOps platform approach, emphasizing correlated risk views and broad integration points across CI/CD and development environments. Snyk has positioned itself around a developer-first philosophy, extending its software composition and container scanning capabilities into secure AI software development through its AI Trust Platform. GitLab remains a powerful all-in-one delivery and security model for organizations seeking tightly integrated pipelines with built-in testing and compliance functionality.
On the cloud-native side, Aqua Security has built a strong reputation in container, Kubernetes, and serverless protection, while increasingly expanding into supply chain security for delivery pipelines. Palo Alto Networks, through its Prisma Cloud offering, provides a code-to-cloud perspective with compliance automation and broad multi-cloud visibility, appealing to organizations seeking centralized governance. Veracode maintains a strong enterprise footprint in application security testing, integrating static, composition, and dynamic capabilities into large-scale DevSecOps workflows. OpenText focuses on connecting tools, data, and teams across the full delivery lifecycle, emphasizing integration and lifecycle orchestration. Wiz has gained traction with a cloud-native platform that supports infrastructure-as-code scanning and runtime protection, reinforcing the code-to-cloud movement.
Recent activity illustrates how quickly strategic positioning evolves. Snyk expanded its AI security capabilities through acquisition, reinforcing its focus on secure AI software development. Aqua Security introduced new protections targeting AI workloads, reflecting the broader industry effort to secure next-generation application patterns. Partnerships are also reshaping workflow dynamics, with cloud platform providers and DevSecOps vendors collaborating to accelerate developer productivity and security integration. Together, these developments highlight a market where differentiation is increasingly tied to AI readiness, pipeline integration, and lifecycle coverage.
Market Dynamics: Regulation, Workflow Friction, and Architectural Pressure
DevSecOps adoption does not occur in a vacuum. Regulatory intervention, government guidance, and internal operational constraints are actively reshaping procurement priorities and architectural expectations.
In the public sector and regulated industries, guidance from national standards bodies and defense organizations has become more explicit about the expectations for secure software development and continuous operations. Recent publications have emphasized risk-based approaches aligned with established secure software development frameworks, reinforcing the need for traceable controls and repeatable security practices. Updates to defense enterprise guidance have further highlighted platform capability expectations and compliance program alignment, signaling that procurement in sensitive sectors will increasingly favor solutions with demonstrated governance integration. At the same time, cybersecurity risk management constructs are shifting toward continuous monitoring models that fit naturally into DevSecOps pipelines, requiring tools that can support ongoing compliance evidence rather than point-in-time assessments.
On the operational side, workflow efficiency is emerging as a decisive adoption factor. Engineers and security professionals are reporting significant time losses to manual approvals, duplicate scanning, and poor tool coordination. These inefficiencies do not merely slow delivery; they erode the business case for security tooling by increasing friction without reducing risk. Organizations that select platforms solely on feature checklists, without considering workflow integration and developer experience, often find themselves paying for capability they cannot operationalize effectively. Our research addresses this reality by incorporating assessment criteria that reflect integration smoothness, automation depth, and the practical burden placed on delivery teams.
Worldwide Database Testing Tool Market
Strategic Recommendations for 2026 Enterprise Planning
Enterprise decision-makers evaluating DevSecOps investments in 2026 should approach the market with a structured lens that balances security outcomes, delivery efficiency, and long-term platform viability. The following strategic priorities emerge from the research:
- Treat DevSecOps procurement as a platform architecture decision, not a point-tool purchase. Evaluate how well candidate solutions reduce fragmentation across scanning, dependency management, infrastructure validation, and runtime protection.
- Factor AI readiness into vendor selection. The integration of AI-assisted security workflows, secure development support, and workload protection for AI-enabled applications is rapidly becoming a differentiating capability rather than a niche enhancement.
- Align tool selection with regulatory exposure. Organizations operating in or serving heavily regulated sectors should prioritize solutions with clear compliance mapping, auditability, and continuous monitoring alignment, especially where guidance is moving toward lifecycle-based risk management.
- Quantify operational burden before committing. The hidden labor costs associated with inefficient approvals and duplicate processes can undermine the return on security investment. Platforms should be assessed for their ability to streamline developer workflows rather than add procedural overhead.
- Plan for multi-year integration evolution. The most effective DevSecOps environments are built through incremental orchestration, not a single procurement event. Budget and roadmap planning should account for integration effort, internal enablement, and the likely need to consolidate tools as platform capabilities mature.
- Use market concentration dynamics to inform negotiation strategy. A moderately consolidated vendor landscape creates both opportunities and risks. Enterprises should evaluate whether suite-based platforms or best-of-breed combinations better fit their maturity level, internal skill base, and tolerance for integration complexity.
Why This Research Matters Now
The DevSecOps tool market is entering a phase where strategic clarity determines execution advantage. Growth is strong, vendor positioning is shifting, and the regulatory and operational context is becoming more demanding. In this environment, organizations need more than a list of tools or a surface-level market summary. They need a disciplined, evidence-based view of where the market is heading, how leading vendors are differentiating, and what decision criteria will produce the best security and delivery outcomes over the next several years.
This research is designed to provide that view. It combines macroeconomic trajectory with operational depth, competitive analysis, and market dynamics that shape real procurement choices. For leaders preparing budgets, architecture roadmaps, and vendor evaluations during 2026, the report offers a structured foundation for decisions that are both defensible and forward looking.
Access the Full Intelligence
The overview presented here provides the strategic framing and analytical direction of the study, but the detailed segmentation logic, capability assessments, competitive benchmarks, and scenario-based planning guidance are contained in the full report. Enterprise buyers, investors, and technology leaders who need granular market structure, vendor-by-vendor evaluation, and decision-ready frameworks will find the complete intelligence essential for informed action.
To access the complete DevSecOps Tool Market research and use it directly in your 2026 planning, review the full publication at the source page.
For detailed analysis of this topic, please visit the official page: DevSecOps Tool Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AI Game Generator Market Hits $247.3M in 2025, Projected to Surge to $1,171.1M by 2032 at 24.5% CAGR
By pmarketresearch, 2026-09-17
The Strategic Imperative: Navigating the AI Game Generators Market in 2026
Previewing PW Consulting's Comprehensive Market Intelligence Report
The landscape of video game development is undergoing a seismic shift, driven by the rapid maturation of generative artificial intelligence. What was once a niche experimentation phase has evolved into a core component of production pipelines across the global industry. For executives, investors, and product strategists, understanding the trajectory of AI Game Generators is no longer optional—it is critical for sustaining competitive advantage in a hyper-accelerated market environment.
PW Consulting is pleased to introduce our latest deep-dive research study, designed specifically to equip decision-makers with the actionable intelligence needed to navigate the forecast period from 2026 to 2032. This article serves as a strategic overview, highlighting the magnitude of the opportunity and the key dynamics shaping the sector, while reserving the granular financial modeling and segmentation data for our full proprietary report.
Market Trajectory and Historical Acceleration
The momentum behind AI-driven game generation is best understood through the lens of recent historical performance. The market has demonstrated remarkable resilience and growth velocity over the past half-decade. Starting from a baseline of 42.1 million USD in 2020, the sector expanded to 63.33 million USD in 2021, and crossed the 100 million USD threshold in 2022. This upward trend accelerated significantly, reaching 161.87 million USD in 2023 and approaching 199.47 million USD in 2024.
AI Game Generators Market
By the base year of 2025, the market size was estimated at 247.3 million USD. This historical compound growth sets the stage for a forecast period where expansion is expected to continue at a robust pace. Our analysis projects the market to reach 301.04 million USD in 2026, further climbing to 395.98 million USD in 2027, and 482.08 million USD in 2028. The trajectory suggests a significant milestone near the end of the decade, with projections indicating a valuation of 768.14 million USD by 2030. Ultimately, the forecast extends to 1171.1 million USD by 2032.
This growth narrative supports a Compound Annual Growth Rate (CAGR) of 24.5 percent over the forecast period. Such a rate indicates not just incremental improvement, but a fundamental transformation in how games are conceived, built, and iterated. For enterprise strategists, this velocity implies that window of opportunity for market entry or expansion is narrowing. The differentiator will not be access to technology, but the strategic integration of these tools into broader business models.
Technological Pillars and Deployment Strategies
The AI Game Generators Market is not a monolith; it is composed of distinct technological capabilities that serve different stages of the development lifecycle. Understanding which technology pillars drive value is essential for allocating R&D budgets and partnership resources. The landscape includes advanced systems for Text-to-3D Models, which allow developers to generate complex three-dimensional assets from simple prompts. This capability is reshaping asset creation pipelines, reducing the time required for modeling and texturing.
Simultaneously, Text-to-2D Assets and Sprites remain a critical component, particularly for 2D gaming genres and UI element generation. These tools enable rapid prototyping and style-consistent asset production. Beyond visual assets, Code Generation Tools are increasingly being utilized to automate scripting and logic implementation, allowing engineers to focus on architecture rather than repetitive coding tasks. Furthermore, Level Generation Systems are automating the creation of virtual environments, enabling procedural world-building that scales with player engagement needs.
Deployment models also play a crucial role in market adoption. The market is split between Cloud-Based solutions, which offer scalability and lower upfront infrastructure costs, and On-Premises deployments, which cater to studios with stringent data security or latency requirements. Our full report dissects the revenue contribution and adoption rates of each segment, providing a clear picture of where capital is flowing within the technology stack. While specific allocation percentages are detailed in the comprehensive study, the overarching trend favors flexible, scalable solutions that integrate seamlessly with existing engine workflows.
Competitive Landscape and Key Market Players
The competitive environment is characterized by a mix of specialized AI-native startups and established technology giants integrating AI into their existing ecosystems. Market concentration data indicates a moderate level of consolidation, with the top three players holding a significant share, while the top five firms capture a broader portion of the total revenue. This structure suggests that while dominance is being established, there remains room for agile innovators to capture niche segments.
Several key companies are defining the boundaries of what is possible in this sector. Rosebud AI, based in San Francisco, provides AI-powered prompt-to-game generation for creating playable 2D/3D browser games, assets, NPCs, and full experiences without coding. This end-to-end approach appeals to indie developers and rapid prototyping teams. Scenario, also headquartered in San Francisco, offers an AI platform for generating style-consistent game assets, images, video, 3D, and textures by training custom models on studio art data, a solution utilized by major studios such as Ubisoft.
Layer AI operates as a creative AI platform for game studios, offering image, video, 3D, and audio generation with custom styles, workflow automation, and high-volume production capabilities. Ludo.ai, with a presence in Sacramento and Seattle, focuses on an AI platform for game research, concept generation, market analysis, asset creation including sprites and 3D models, and prototypes to accelerate game development. On the environmental side, Promethean AI provides an AI system for procedural world-building and environment design, automating placement and generation of assets for virtual worlds.
Additionally, established giants are integrating these capabilities. Unity Technologies, based in San Francisco, offers Muse and ML-Agents for AI-assisted game development, prompt-based generation, and behavioral AI within Unity engine workflows. These companies represent the vanguard of the industry, and our report includes detailed profiling of their strategic moves, product roadmaps, and partnership ecosystems. Understanding the specific positioning of each player is vital for identifying potential collaborations or competitive threats.
Regulatory Dynamics and Ethical Considerations
As the market matures, the regulatory environment is becoming an increasingly important factor in strategic planning. The introduction of frameworks governing artificial intelligence is shaping how developers deploy generative tools. For instance, the EU AI Act entered into force in August 2024, with full applicability for most provisions expected by August 2026. Under this framework, most AI-powered video games are classified as minimal or no risk, requiring limited or no obligations. However, compliance readiness remains a key concern for studios operating across multiple jurisdictions.
Complementing regulatory frameworks, industry bodies are establishing best practices. In July 2025, the International Gaming Standards Association (IGSA) released an Ethical Use of Artificial Intelligence best practices document. This framework provides guidance for the AI in gaming industry, developed with input from regulatory authorities. The IGSA released nine best practices for ethical AI use in gaming, covering purpose documentation, fairness, and oversight. These guidelines are becoming a de facto standard for responsible development.
Furthermore, legal considerations regarding intellectual property remain complex. AI-generated content in games raises copyright considerations in many jurisdictions, where AI is not recognized as an author, requiring human oversight for protection. Strategic teams must account for these legal nuances when building pipelines that rely heavily on generative outputs. Additionally, the high computational demands for training custom generative models and real-time inference in game asset creation rely heavily on GPU infrastructure, adding a layer of technical and capital planning to the regulatory equation.
Operational Content and Strategic Utility of the Report
PW Consulting's full market research report is designed to move beyond high-level trends and provide the operational data necessary for execution. The study encompasses a thorough analysis of market size drivers, restraints, and opportunities. It offers a detailed segmentation analysis that breaks down the market by region, technology, and deployment mode, allowing readers to identify high-growth pockets within the broader landscape.
The report includes comprehensive profiles of the key companies mentioned, along with an analysis of recent developments such as the IGSA standards release. It provides a competitive benchmarking section that evaluates market positioning, product capabilities, and strategic focus areas. For financial planners, the report includes forecast models that project revenue flows over the 2026-2032 period, enabling precise budgeting and investment forecasting.
Additionally, the study addresses the industry context noise, including regulatory shifts and technological constraints like computational requirements. This holistic view ensures that decision-makers are not blindsided by external factors that could impact deployment timelines or cost structures. The FAQ section of the report tackles common queries regarding copyright, risk classification, and infrastructure needs, serving as a quick reference guide for legal and technical teams.
Conclusion: Securing Position in a High-Growth Sector
The AI Game Generators Market represents one of the most dynamic growth sectors in the technology and entertainment industries. With a projected CAGR of 24.5 percent and a market trajectory moving toward over 1 billion USD by 2032, the stakes for strategic positioning are high. The convergence of advanced generative models, evolving regulatory standards, and intense competition among key players creates a complex environment that demands precise intelligence.
AI Perfume Generator Market
PW Consulting's latest report is built to provide that precision. By integrating historical data, detailed segmentation analysis, and competitive profiling, this study offers a roadmap for navigating the forecast period. We invite industry leaders, investors, and strategic planners to access the full comprehensive report to gain the granular insights required to make informed decisions. The full breakdown of regional splits, specific technology revenue shares, and detailed financial forecasts is available in our complete market intelligence package.
In a market moving at this speed, visibility is currency. Ensure your organization has the clarity needed to capitalize on the opportunities within the AI Game Generators Market. Reach out to access the full study and secure your strategic edge for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: AI Game Generators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bioprocessing Data Analytics Market Hits $680M in 2025, Poised for 12.5% CAGR to $1.55B by 2032
By pmarketresearch, 2026-09-17
Bioprocessing Data Analytics Software: Navigating the Next Wave of Market Intelligence
Executive Overview
The bioprocessing industry is undergoing a fundamental shift in how data is captured, analyzed, and acted upon. As biologics development cycles shorten and manufacturing complexity increases, organizations are moving from isolated laboratory systems toward integrated analytics platforms that span the entire value chain. Our latest market research on the Bioprocessing Data Analytics Software Market offers a structured, forward-looking view of this transition, designed specifically to inform capital allocation, technology roadmapping, and partnership strategy through 2032.
This article serves as a strategic preview of the full study. It highlights the macro trajectory, the operational drivers reshaping procurement decisions, the competitive architectures that buyers should monitor, and the regulatory currents that are quietly redefining software requirements. For teams preparing budgets, evaluating vendor shortlists, or building digital manufacturing strategies for 2026, this intelligence provides the context needed to move from reactive spending to deliberate investment.
Bioprocessing Data Analytics Software Market
Market Trajectory: From Steady Growth to Accelerated Scaling
The market has demonstrated consistent expansion over the past half-decade, with revenue climbing from approximately 377 million USD in 2020 to a projected 762.72 million USD in 2026. The base year of 2025 is estimated near 680 million USD, reflecting a sector that has absorbed multiple rounds of technological maturation, broader cloud adoption, and increasing regulatory pressure for data integrity across GxP workflows. Looking forward, our forecast model projects the market to surpass 844 million USD in 2027 and continue upward through 2032, reaching an estimated 1.55 billion USD by the close of the forecast period.
The compound annual growth rate measured across the 2026-2032 window is tracked at 12.5 percent. This pace is not merely a reflection of incremental software adoption; it signals a structural change in how biomanufacturers view analytics as a core operational capability rather than a supportive tool. Early historical years showed steady double-digit movement, and the acceleration in the near-term outlook aligns with the convergence of automation, multivariate analysis, and AI-ready dataset construction. Organizations that treat these platforms as long-term infrastructure investments are positioning themselves for more predictable process performance, faster tech transfer, and stronger compliance posture.
Strategic Drivers Shaping 2026 Decision-Making
Several interlocking forces are converging to reshape procurement priorities for bioprocessing analytics software. Understanding these drivers is essential for any team evaluating purchase timing, scope of deployment, or integration requirements.
-
Regulatory expectations for data integrity are intensifying. Software solutions deployed in bioprocessing environments must align with FDA 21 CFR Part 11 requirements for electronic records, audit trails, and data integrity within GxP settings. At the same time, EU GMP Annex 1 revisions emphasize risk-based approaches and sterile manufacturing controls, increasing demand for validated analytics platforms that can demonstrate traceability, controlled access, and robust dataset governance. These requirements are no longer peripheral compliance concerns; they are becoming central selection criteria that influence architecture, deployment models, and vendor due diligence.
-
Process Analytical Technology frameworks are normalizing real-time monitoring. FDA guidance on PAT encourages real-time monitoring and multivariate analysis in bioprocessing, pushing organizations toward tools that can support continuous measurement, feedback loops, and predictive modeling. Buyers are increasingly evaluating platforms not only for retrospective reporting but also for their ability to feed live process signals into decision workflows and to support QbD-oriented development programs.
-
The clinical and commercial pipeline is demanding faster, more reproducible outcomes. As molecule complexity rises and CDMO collaboration expands, manufacturers need analytics that can span process development, manufacturing, and quality functions without fragmentation. Teams are seeking platforms that reduce manual reconciliation across online, at-line, and offline data streams, while enabling cross-run analysis and structured data handoffs between development and production.
-
AI and natural language interfaces are lowering the barrier to advanced analytics. Recent product launches and software releases indicate an industry-wide push toward more intuitive interaction models, including conversational interfaces and automated insight generation. This trend is broadening the actionable user base beyond dedicated data scientists, allowing process engineers, quality teams, and manufacturing leads to engage directly with analytics outputs.
These dynamics do not operate in isolation. Regulatory pressure raises the compliance floor, PAT frameworks raise the analytical ceiling, and pipeline urgency raises the cost of delay. Together, they create a market environment where the strategic question is no longer whether to invest in analytics software, but how to select, integrate, and scale it in a way that supports both near-term operational wins and long-term data architecture resilience.
What the Full Study Delivers: A Practical Toolkit for Strategy Teams
Our report is constructed to move beyond high-level trends and offer directly usable market intelligence. It is organized to support multiple internal workflows, including technology sourcing, competitive benchmarking, M&A scouting, and regional expansion planning. The study combines macro market sizing with deep operational context so that decision-makers can connect market trajectory to their own execution plans.
Key components of the research include:
-
Historical and forecast market sizing with scenario-aware context. The report maps revenue evolution across the historical window and extends through the full forecast horizon, providing a structured view of growth inflection points and the factors that shape them. Rather than presenting numbers in isolation, the analysis ties sizing to adoption patterns, deployment shifts, and functional demand trends that explain why the market is moving as it does.
-
Segment-level evaluation across deployment and application dimensions. The study breaks the market into meaningful structural categories, including cloud-based and on-premises deployment paths, as well as application areas such as process development, manufacturing and production, and quality and regulatory compliance. This segmentation is used to identify where demand is concentrating, what use cases are accelerating adoption, and how different organizational maturity levels influence purchasing behavior.
-
Deployment and architecture considerations for enterprise buyers. Because bioprocessing data environments often span legacy instruments, LIMS/ELN systems, MES integration points, and cross-site data flows, the report evaluates how platform architecture influences scalability, validation effort, and long-term maintainability. These discussions are intended to help buyers align software selection with their broader digital manufacturing roadmap.
-
Competitive positioning and vendor strategy mapping. The analysis examines how leading providers differentiate through platform scope, compliance readiness, analytics depth, and ecosystem integration. It is designed to support vendor shortlisting, RFP design, and negotiation strategy by clarifying where each player is competing and what tradeoffs buyers should expect.
-
Regulatory and quality alignment mapping. Given the centrality of compliance to purchasing decisions, the study connects market dynamics to the practical implications of GxP data requirements, validated system expectations, and real-time monitoring frameworks. This helps organizations anticipate what vendors should demonstrate during evaluation and what internal validation effort may be required after selection.
For teams responsible for capital planning in 2026, the report is intended to function as a decision-support asset rather than a static industry summary. It provides the structure needed to compare deployment options, weigh integration complexity, and align software strategy with operational priorities across development and manufacturing functions.
Competitive Landscape: Six Players Shaping the Platform Race
The market is characterized by a mix of specialized analytics providers and broader life-science or manufacturing technology companies, with competitive intensity rising as platforms expand from data visualization into integrated workflow orchestration and AI-assisted analysis. Our research tracks the strategic postures of several core organizations that are actively shaping buyer expectations and setting the functional bar for next-generation bioprocessing analytics.
Genedata
Headquartered in Basel, Switzerland, Genedata offers an enterprise platform built around integrated data management, automation, and analytics across bioprocess development and CMC workflows. Its positioning emphasizes QbD support, AI-ready datasets, and compliance-aligned design, making it relevant for organizations seeking a more unified development-to-manufacturing data backbone. Recent activity underscores this trajectory: in August 2025, the company released a new version of Genedata Selector focused on GMP-compliant NGS in biopharma manufacturing and quality control. In March 2026, mAbxience selected Genedata Bioprocess to automate end-to-end CDMO workflows, an indicator of how broader workflow automation is becoming a competitive differentiator.
Invert
Based in San Francisco, Invert provides an infrastructure and AI-powered intelligence platform aimed at bioprocess data unification, real-time monitoring, analysis, and optimization. Its interface strategy has drawn attention with the introduction of Invert Assist, a natural language analysis interface launched in October 2025 to support process modeling, data analysis, and insight generation. This type of interface innovation matters strategically because it expands accessibility to analytics outputs and reduces reliance on highly specialized data teams for routine interpretation tasks.
Körber Pharma
Körber Pharma, based in Lüneburg, Germany, brings PAS-X Savvy, a collaborative real-time bioprocess data analytics and management platform focused on visualization, holistic analysis, PPI, and integration with MES systems. Its strength lies in connecting analytics more tightly to execution and operational systems, which appeals to manufacturers seeking a more continuous link between data insight and production control.
Sartorius
Sartorius, headquartered in Göttingen, Germany, offers SIMCA and MODDE software for multivariate data analysis, DOE, real-time process monitoring through SIMCA-online, predictive analytics, and QbD in bioprocessing. Its long-standing presence in analytical and process-related tooling gives it a strong foundation in multivariate methods and process understanding, which remains central for teams pursuing rigorous experimental design and live monitoring.
BioRaptor
BioRaptor, based in Binyamina, Israel, specializes in a bioprocessing data analytics platform that unifies online, at-line, and offline data, applies machine learning for optimization, supports cross-run analysis, and integrates with LIMS and ELN systems. Its value proposition is particularly relevant for organizations trying to break down data silos and create a more cohesive analytical record across heterogeneous measurement environments.
Merck KGaA / Sigma-Aldrich
Through its offering of Bio4C ProcessPad software, Merck KGaA / Sigma-Aldrich provides a solution focused on bioprocessing data collection, visualization, and analytics. As a player with broad life-science reach, its software entry can be attractive for organizations already embedded in its reagent, material, or service ecosystems, especially when data collection standardization and straightforward visualization are priorities.
Beyond individual profiles, the competitive picture is defined by concentration and consolidation pressure. The market reflects a meaningful share held by a limited number of leading firms, with the top three and top five players collectively representing a substantial portion of market value. This structure matters for buyers because it influences negotiation leverage, integration risk, and the breadth of alternative options available during vendor evaluation. At the same time, continued product launches, deployment wins, and software updates suggest that differentiation is increasingly occurring in areas such as compliance readiness, AI-assisted interaction, MES/LIMS connectivity, and end-to-end workflow automation.
Deployment, Application, and Geographic Context
The market's structure is being shaped not only by vendor competition but also by how organizations choose to deploy and apply analytics software. Cloud-based and on-premises deployment paths each carry distinct tradeoffs around scalability, control, validation effort, and connectivity to existing manufacturing systems. Meanwhile, application demand is distributed across process development, manufacturing and production, and quality and regulatory compliance, with each functional area placing different emphasis on multivariate analysis, real-time monitoring, traceability, and cross-functional data sharing. The full study examines these structural splits in detail so that buyers can assess where their own demand profile aligns with broader market momentum.
Geographic distribution also plays a role in shaping demand intensity, vendor reach, and implementation complexity. Different regions reflect varying levels of biomanufacturing maturity, regulatory interpretation, and digital infrastructure readiness. While our research maps these regional dynamics, the practical implication for 2026 planning is that deployment decisions should be evaluated with local compliance expectations, internal data governance maturity, and integration constraints in mind rather than treated as purely technology-driven choices.
Implications for 2026 Strategy and Beyond
For executives and strategy teams planning the 2026 investment cycle, the market signals point toward a few recurring priorities. First, analytics software is increasingly being treated as a multi-year enabler rather than a point solution, which means selection criteria should weigh scalability, data architecture compatibility, validation readiness, and the ability to support evolving use cases across development and manufacturing. Second, AI-enabled interfaces and natural language interaction are expanding the practical reach of analytics, but they do not remove the need for strong underlying data governance and compliance design. Third, the competitive field is maturing quickly, and vendor differentiation is becoming more subtle; buyers need a structured evaluation framework that goes beyond feature checklists to include workflow fit, integration effort, and long-term maintainability.
Bioprocess Controllers and Automation Systems Market
The broader takeaway is that the market is moving from early-stage adoption to a more demanding phase where performance, compliance, and integration quality determine the value a platform ultimately delivers. Organizations that enter this phase with clear internal requirements, realistic deployment assumptions, and a well-defined analytics strategy are better positioned to capture the operational benefits that fuel continued market growth.
Conclusion: From Signal to Strategic Action
The Bioprocessing Data Analytics Software Market is entering a period of sustained expansion supported by regulatory pressure, PAT-inspired real-time analytics, broader cloud and AI adoption, and increasing demand for unified data workflows across development and manufacturing. Our research provides a detailed map of that trajectory, the competitive structures shaping it, and the practical factors that should guide purchasing and investment decisions in 2026 and beyond.
This preview is intended to demonstrate the depth and orientation of the full study, but the complete report contains the segmentation detail, competitive benchmarking, deployment analysis, and regional context needed to turn market signals into actionable strategy. For teams preparing budgets, evaluating vendor shortlists, or building analytics roadmaps, accessing the full intelligence framework offers a more precise foundation for decision-making and a clearer view of where the market is headed through 2032.
For detailed analysis of this topic, please visit the official page: Bioprocessing Data Analytics Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com