

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Cloud-First SD-WAN Market: Why 18.5% CAGR and 18B USD Growth Redefine 2032

Navigating the Cloud-First SD-WAN Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
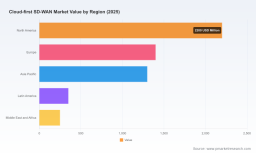
The global Cloud-first SD-WAN market has moved decisively from a networking experiment to a foundational infrastructure discipline. In 2025, revenue is estimated at roughly 5.5 billion USD, building on a trajectory that saw the segment climb from about 3.9 billion USD in 2023 and 4.64 billion USD in 2024. The expansion continues at a compound annual growth rate of 18.5 percent through the end of the forecast window in 2032, when the market is projected to reach approximately 18.05 billion USD. This growth reflects more than incremental adoption; it captures a structural shift in how enterprises architect, secure, and optimize connectivity for distributed workloads, multi-cloud environments, and latency-sensitive SaaS applications. Geographic demand is broad-based, with North America accounting for a substantial share of 2025 revenue, Europe contributing a significant portion, Asia Pacific representing a sizeable segment, and Latin America along with the Middle East and Africa collectively rounding out the addressable base. Component-level spending is equally distributed across hardware appliances, software and virtual appliances, and managed services, indicating that buyers are no longer treating SD-WAN as a purely device-centric purchase but as a combined platform-and-services investment. Enterprise size also matters: large enterprises dominate spend, while small and medium enterprises form a rapidly growing segment as simplified, cloud-delivered models lower the operational barrier to entry. Despite a concentrated vendor landscape, with the top three players capturing just under half of market share and the top five holding roughly three-fifths, the competitive field remains active and fragmented enough to reward differentiated positioning.
Key Challenges and Inflection Points
The market is maturing, but that maturity introduces friction rather than certainty. One recurring challenge is the tension between cloud-first performance objectives and the realities of last-mile and backbone infrastructure economics. As of 2025, typical underground fiber deployment carries a median cost of about 18.00 USD per foot, with aerial deployment at roughly 8.00 USD per foot, and modest cost increases are expected to persist into 2026. These economics constrain how quickly enterprises can extend high-quality connectivity to edge sites, cloud on-ramps, and hybrid branches, which in turn shapes where SD-WAN delivers the greatest return and where legacy transport remains a limiting factor. A second challenge is the evolving regulatory backdrop. In the United States, the FCC has rolled back certain net neutrality rules during 2025 and 2026 in favor of lighter-touch oversight intended to stimulate broadband investment. While this can accelerate capacity availability in some markets, it also introduces uncertainty around service quality guarantees and traffic management practices, prompting network buyers to scrutinize the resilience and predictability of internet-based transport under SD-WAN. A third challenge lies in data sovereignty and localized control requirements. Various regions are strengthening digital policies that emphasize secure, localized handling of network traffic and infrastructure, which places new demands on SD-WAN designs that must support compliance without sacrificing cloud acceleration or global consistency. Together, these dynamics create a market at an inflection point: cloud-first SD-WAN is becoming indispensable, but successful deployments increasingly depend on infrastructure realism, regulatory agility, and sovereignty-aware architectures.
Core Drivers of Market Change
Technological Innovation and Architectural Shifts
Technology is reshaping what SD-WAN is expected to deliver. The migration of applications, data, and collaboration stacks to public cloud and SaaS platforms has made cloud-on-ramp performance, SaaS acceleration, and multi-cloud consistency first-order requirements rather than optional features. Vendors have responded with cloud-native control planes, virtual and software appliances that reduce dependence on fixed hardware at every site, and integrated security approaches that align networking with zero-trust and SASE concepts. This architectural evolution is visible in the segment mix, where software and virtual appliances command the largest share of 2025 revenue, signaling a shift toward flexible, programmatically managed deployments that scale with cloud adoption. The rise of AI-driven optimization is another accelerant. Rather than merely steering traffic across available links, newer platforms increasingly use predictive and behavioral analytics to adapt to application performance, link variability, and congestion patterns in real time. The practical effect is that SD-WAN is no longer evaluated only on connectivity resilience; buyers now assess how effectively a solution preserves user experience across cloud services, IaaS endpoints, and remote access scenarios. AI-powered optimization, SLA-backed managed delivery, and unified SASE-oriented constructs are becoming key differentiators for organizations seeking predictable performance while reducing operational complexity.
Policy, Regulation, and Data Sovereignty Pressures
Policy environments are shaping both opportunity and design constraints. The FCC’s lighter-touch regulatory posture in 2025-2026 reflects an attempt to encourage broadband investment, which could expand the availability and diversity of underlay options that SD-WAN relies on for broadband-first architectures. At the same time, data sovereignty laws and regional digital policies are pushing enterprises toward localized control of traffic flows and infrastructure, particularly for regulated industries and multinational deployments. This creates a strategic requirement for SD-WAN architectures that can enforce policy consistency globally while respecting regional data handling expectations. It also increases interest in solutions that combine centralized orchestration with distributed enforcement, and that can adapt to jurisdiction-specific security and retention mandates without fragmenting operations. The regulatory trend is therefore double-edged: it may unlock more affordable broadband-rich connectivity in some markets, while demanding greater architectural discipline in others. Enterprises that treat compliance and sovereignty as design inputs rather than afterthoughts are better positioned to move quickly as rules evolve.
Demand-Side Behavior and Cost Structure Dynamics
Demand is being rewritten by how organizations consume technology. Work-from-anywhere models, distributed manufacturing, multi-site retail and hospitality footprints, and accelerated digital transformation have increased the number of edge locations that must be connected economically and reliably. At the same time, enterprise buyers are pressing for measurable outcomes: reduced MPLS dependency, better cloud and SaaS performance, simpler operations, and tighter alignment between networking and security spend. The cost structure of the underlying infrastructure reinforces this demand shift. Data center construction costs average about 10-11 million USD per megawatt, with electricity representing roughly 40 percent of operating expenses for large facilities. These figures matter because they influence where processing and aggregation occur, how much traffic is backhauled, and whether organizations favor distributed edge resilience over centralized chokepoints. When facility and power costs rise, the value proposition of efficient, broadband-rich, cloud-direct connectivity becomes more compelling, especially for enterprises seeking to reduce transport waste and optimize cloud egress patterns. Combined with the growing appetite for managed services, this demand-side pressure is steering many organizations toward solutions that integrate connectivity, optimization, and ongoing operations into a more predictable commercial model.
PW Consulting Information & Electronics Research Center
Competitive Landscape and Leading Strategies
The vendor field reflects a spectrum of strategies rather than a single winning formula. Aryaka Networks positions around a cloud-first SD-WAN model backed by a global private network backbone, multi-cloud and SaaS acceleration, and Unified SASE delivered as a service, appealing to organizations that want cloud connectivity optimization with a managed, globally consistent backbone. Bigleaf Networks focuses on AI-powered cloud-first SD-WAN for internet optimization, redundancy, and high-performance cloud and SaaS access, with SLA-backed managed delivery that targets predictable performance for business-critical applications. Cisco Systems offers both Catalyst and Meraki SD-WAN portfolios, including cloud on-ramp capabilities for multi-cloud, IaaS, and SaaS optimization, alongside integrated security, which makes its approach attractive to enterprises seeking broad portfolio reach and familiar operational models. Fortinet emphasizes Secure SD-WAN with integrated security, cloud-native architecture, and AI-driven optimization designed for cloud-first deployments, aligning networking with a broader security-first narrative. Versa Networks markets a Universal SASE platform with SD-WAN aimed at global, security-focused, and cloud-first businesses by converging networking and security in a single fabric. VMware, under Broadcom, continues to push VMware SD-WAN with a cloud-first architecture suited to hybrid and multi-cloud environments and SaaS performance optimization, leveraging its strong enterprise footprint. Palo Alto Networks centers its Prisma SD-WAN on application-performance-centric outcomes with integrated security for cloud and SASE environments, which resonates with organizations prioritizing user experience and consolidated security policy. HPE Aruba targets cloud-first transformations with EdgeConnect SD-WAN designed to retire MPLS in favor of broadband for resilience and cost efficiency, often pairing connectivity modernization with broader edge and campus strategies.
Strategic Positioning and Differentiation
What separates leaders is not merely feature breadth but the coherence of their value proposition relative to enterprise priorities. The most durable positions are emerging around three axes: cloud performance, security integration, and operational model. Vendors that can demonstrably improve SaaS and IaaS experience while reducing reliance on expensive private transport are gaining traction, especially as broadband ecosystems expand and enterprises seek cost-efficient resilience. Those that bind SD-WAN closely to security and SASE-oriented architectures are helping buyers consolidate policy, simplify audits, and align network behavior with zero-trust expectations. Meanwhile, managed-service and SLA-backed models are becoming a competitive lever for organizations that want outcomes without expanding internal networking complexity. Differentiation is increasingly less about whether SD-WAN is available and more about how well it fits the way an enterprise actually uses cloud services, manages risk, and operates networks day to day. That is why deployments are diverging by use case: some organizations prioritize global backbone consistency and managed cloud acceleration, while others focus on AI-driven internet optimization, security convergence, or MPLS replacement economics.
Ongoing Developments and Market Evolution
Recent moves underscore how quickly the market is evolving around resilience, cryptography readiness, and deployment economics. In May 2026, Gorilla Technology Group Inc. signed an MOU with CHELPIS Quantum Corporation to integrate post-quantum cryptography into an SD-WAN platform, advancing toward commercial availability in April 2026, a signal that quantum-safe networking is moving from concept to product roadmaps. In April 2026, AT&T Business launched a post-quantum cryptography secure SD-WAN service powered by Cisco 8000 Series routers, positioning itself among the first major North American providers to offer quantum-resilient networking at service scale. The same month, HPE Aruba announced that Southern Sun hotel group had implemented EdgeConnect SD-WAN to replace MPLS with broadband, aiming for improved resilience and cost reduction. These developments illustrate three simultaneous threads: the rise of cryptography-forward networking as a future-proofing consideration, the role of major service providers in bringing advanced SD-WAN capabilities to market at scale, and the continued practical reality of MPLS-to-broadband transitions in real enterprise environments. The competitive landscape is likely to continue evolving through consolidation among broader platform vendors, continued specialization from cloud-first and security-centric challengers, and new entry points for providers that can combine network services, managed operations, and resilience guarantees in ways that match enterprise buying preferences.
Future Outlook: Three to Five Years Ahead
Trend 1: Security-Network Convergence as a Default
Over the next three to five years, the distinction between SD-WAN and security architecture is likely to keep narrowing. Enterprises will increasingly treat converged networking and security not as a procurement preference but as an operational baseline, especially as workforces, branches, and cloud touchpoints multiply. The commercial opportunity here lies in platforms that can deliver consistent policy, reduce tool sprawl, and simplify compliance across regions. The uncertainty is whether consolidation will accelerate through acquisitions and platform bundling or whether modular ecosystems will persist for organizations that value best-of-fit flexibility over single-vendor simplicity.
Trend 2: Performance-Centric, Cloud-Direct Connectivity
Cloud-first SD-WAN will continue to shift from link aggregation to application-aware optimization that prioritizes SaaS, IaaS, and collaboration performance. As broadband availability improves in some markets and enterprises become more comfortable with internet-based transport, more deployments will pursue cloud-direct patterns that reduce backhaul inefficiencies and improve user experience. The upside is significant for vendors and service providers that can prove measurable performance improvements and predictable SLAs. The risk is that underlay quality remains uneven across regions, and that infrastructure economics, including fiber deployment costs and data center operating expenses, may slow the pace at which some organizations can fully transition away from legacy transport.
Trend 3: Cryptographic Readiness and Resilience as Buying Criteria
Quantum-safe cryptography and broader resilience planning are likely to move from niche concerns to mainstream evaluation criteria, particularly for regulated sectors and organizations with long infrastructure life cycles. Early platform and service announcements already point in this direction, and buyers are beginning to ask how networking investments will hold up against future cryptographic and threat-evolution requirements. The opportunity is for vendors and operators to offer clear roadmaps, interoperable designs, and upgrade paths that reduce the risk of stranded assets. The challenge is that standards, migration timing, and operational complexity remain unsettled, so enterprises will need to balance urgency with pragmatism to avoid overinvesting in immature capabilities.
Worldwide Cloud VPN Market
Strategic Recommendations for Decision-Makers
For Enterprise Buyers and Network Leaders
Evaluate cloud-first SD-WAN against actual application behavior, not just topology diagrams. Prioritize solutions that deliver measurable SaaS and multi-cloud performance, predictable internet transport resilience, and security integration that aligns with your compliance posture. Where MPLS retirement is on the table, validate broadband quality at representative sites before scaling, and favor designs that can accommodate regional data sovereignty requirements without fragmenting operations. For organizations with long deployment horizons, ask vendors how post-quantum and cryptographic readiness will be introduced over time, so current purchases do not become obstacles to future compliance or resilience goals.
For Investors and Strategic Planners
The market’s 18.5 percent CAGR and projected scale through 2032 suggest durable demand, but returns will depend on differentiation in cloud performance, managed operations, and security convergence rather than broad connectivity alone. Interest is likely to remain strongest in platforms that can combine cloud acceleration, AI-driven optimization, SLA-backed delivery, and credible cryptographic-resilience roadmaps. Watch for consolidation that bundles SD-WAN into wider SASE or edge platforms, and for service provider moves that wrap advanced SD-WAN capabilities into managed offerings. In assessing opportunities, weigh not only vendor momentum but also the realism of their infrastructure assumptions, since fiber deployment costs and data center operating expenses will continue to shape where cloud-first architectures deliver the strongest economics.
For Manufacturers, Service Providers, and Channel Teams
Position offerings around outcomes that map directly to enterprise buying criteria: cloud and SaaS performance, resilience under variable internet conditions, operational simplicity, and clear security alignment. Managed and service-based models are gaining relevance because they reduce the internal burden of deployment and optimization, especially for distributed footprints. Differentiation will increasingly hinge on how well a solution handles sovereignty-aware policy, cryptographic futures, and real-world underlay variability. Teams that can translate technical capabilities into predictable business outcomes, backed by reference deployments and transparent service guarantees, are best placed to capture demand as the market matures.
Market momentum in cloud-first SD-WAN is clear, but the decisive question for any organization is how well its network strategy matches its cloud usage, regulatory exposure, and operational model. The fuller picture—detailed segmentation, regional dynamics, vendor-by-vendor positioning, use-case adoption patterns, and customized scenario analysis—can be explored in PW Consulting’s complete research report on the Cloud-first SD-WAN market, where the data and implications are developed in depth for practical decision-making.
Worldwide WAN Optimization Controllers Market
For detailed analysis of this topic, please visit the official page: Cloud-first SD-WAN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com