

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Digital Insurance Market to Reach $321 Billion By 2032, Growing at 14.25% CAGR

Navigating the Digital Insurance Transformation: Strategic Intelligence for 2026 and Beyond
The insurance industry is undergoing a fundamental restructuring, driven by the convergence of cloud infrastructure, artificial intelligence, and evolving regulatory demands. As we enter 2026, the distinction between traditional insurers and digital-native competitors is blurring. The ability to process policies, manage claims, and engage customers through fully digital channels is no longer a differentiator; it is a baseline requirement for survival and growth.
PW Consulting's latest Digital Insurance Market report is designed to provide enterprise leaders with the clarity needed to navigate this complex landscape. This research does not merely track revenue figures; it decodes the operational shifts, technological adoption curves, and competitive maneuvers that are defining the next decade of insurance value chains. By integrating historical performance data with forward-looking forecasts, this analysis offers a strategic compass for C-suite executives, product leaders, and investment analysts.
Worldwide Blockchain Insurance Market
Macro Growth Trajectory and Market Scale
The scale of the digital insurance market reflects a sector in hyper-expansion. Building on a robust historical foundation from 2020 through 2025, the market has demonstrated consistent upward momentum. In 2025, the overall market revenue reached 126.36 billion USD, marking a significant increase from 110.6 billion USD in 2024 and 96.5 billion USD in 2023. This trajectory underscores the accelerating digitization of insurance products and services across the global economy.
Looking ahead, the forecast period from 2026 to 2032 projects sustained aggressive growth. The market is expected to climb to 144.37 billion USD in 2026, surpassing 164.94 billion USD by 2027, and reaching 188.45 billion USD by 2028. The long-term outlook remains strong, with revenue projections extending to 321.08 billion USD by 2032. This expansion is underpinned by a compound annual growth rate over the forecast period, signaling that digital transformation is not a temporary trend but a structural shift in how risk is underwritten and managed.
For strategic planners, these figures represent more than just top-line growth. They indicate increasing capital allocation toward digital capabilities, rising customer expectations for seamless digital interactions, and the compounding value of data-driven decision-making. However, capturing this growth requires navigating a fragmented ecosystem of technologies and regional nuances, details of which are fully mapped out in our comprehensive report.
Segmentation Drivers: Technology and Product Dynamics
The market is segmented across multiple dimensions that reveal where value is being created and where competition is most intense. Technological adoption is a primary driver, with cloud computing, AI and machine learning, IoT and telematics, and blockchain solutions forming the backbone of modern insurance operations. The integration of these technologies varies significantly by use case, from core policy administration to real-time claims assessment.
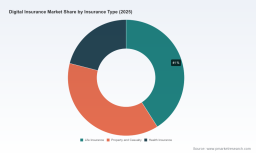
Beyond technology, the composition of insurance types plays a critical role in market dynamics. Life insurance, property and casualty, and health insurance segments each present unique digital challenges and opportunities. The interplay between these segments influences how carriers prioritize investments and how technology vendors tailor their offerings. For instance, the demands of health insurance digitization often diverge sharply from those of property and casualty modernization, requiring distinct strategic approaches.
Our report delves deep into these segmentation splits, providing actionable intelligence on which technologies are gaining traction and how different insurance types are adapting to digital pressures. Rather than presenting static percentages, we analyze the strategic implications of these splits, helping organizations identify where to allocate resources for maximum impact. The full breakdown of these dynamics, including regional influences and application-specific adoption rates, is available in the complete market intelligence package.
Competitive Landscape and Key Players
The competitive environment is characterized by a mix of established platform providers, agile insurtech startups, and traditional insurers undergoing digital transformation. Understanding the positioning of key players is essential for benchmarking and partnership strategies.
Guidewire Software continues to be a pivotal force, providing cloud-based core insurance platforms tailored for property and casualty insurers. Their focus on digital policy administration, claims management, and billing solutions addresses the foundational needs of large carriers modernizing legacy systems. Similarly, Duck Creek Technologies offers a SaaS insurance core platform with low-code tools that enable configurable digital experiences, supporting P&C carriers in achieving flexibility and speed to market.
On the innovation frontier, Shift Technology specializes in AI-driven solutions for fraud detection, claims automation, and decisioning agents. Their tools are used by major insurers globally to enhance accuracy and efficiency in critical operational workflows. Meanwhile, digital-first insurers like Lemonade are redefining customer expectations by using AI and chatbots for renters, homeowners, car, and pet insurance with fully online application and claims processes. These companies demonstrate how technology can be embedded into the core value proposition rather than merely supporting backend operations.
Additional players such as BriteCore and Next Insurance further diversify the landscape. BriteCore provides a cloud-native core platform for P&C insurers featuring AI-embedded tools, while Next Insurance focuses on digital platforms for small business insurance with instant quotes and online purchasing tools. The presence of these varied competitors highlights the multi-front nature of the digital insurance battle, where core system modernization, customer experience innovation, and niche market disruption occur simultaneously.
Recent Developments and Industry Momentum
Recent news cycles highlight the rapid pace of innovation and operational updates within the sector. In early 2026, Aetna launched a simplified, digital-first benefits onboarding experience for members, utilizing RCS-enabled text messaging and self-service tools. This move exemplifies the push toward frictionless member engagement and the adoption of modern communication channels in health benefits administration.
Simultaneously, Shift Technology advanced its agentic AI models in Shift Claims, enhancing capabilities for policy data interpretation, claims assessment, and anomaly detection. These innovations point toward a future where intelligent agents handle increasingly complex decision-making tasks, reducing manual intervention and improving outcomes. Additionally, Duck Creek Technologies saw recognition for core system modernization efforts, with Suncorp leveraging the Duck Creek platform to drive transformation. Such developments signal that core system upgrades remain a top priority for established insurers seeking to compete in a digital-first environment.
These events are not isolated; they are part of a broader pattern of accelerating digital maturity. Our report contextualizes these developments within the wider market trajectory, helping leaders understand which innovations are likely to become industry standards and which represent niche experiments.
Market Dynamics: Regulation, Compliance, and Operational Costs
The digital insurance landscape is heavily influenced by regulatory and operational factors that can dictate strategy and cost structures. In California, CPPA regulations on cybersecurity audits, risk assessments, and automated decision-making technology for insurance companies took effect on January 1, 2026. These rules impose new obligations on insurers deploying digital tools, particularly those involving algorithmic decision-making. Complying with these standards requires robust governance frameworks and transparent data practices.
At the federal and state level in the U.S., additional privacy laws effective January 1, 2026, introduce obligations for opt-out mechanisms and data protection assessments. These measures impact digital insurers that rely on extensive data collection for personalization and risk modeling, necessitating careful attention to user consent and data handling protocols.
Internationally, the EU Digital Operational Resilience Act (DORA) has been fully in effect since January 2025, mandating ICT risk management and third-party oversight for insurance entities. This regulation forces insurers to scrutinize their technology vendors and cloud dependencies, adding a layer of complexity to digital transformation initiatives. Organizations must ensure that their digital ecosystems are resilient against cyber threats and operational disruptions.
Digital Insurance Market
Operational costs also vary significantly based on compliance and infrastructure requirements. Managed HIPAA-compliant cloud hosting for digital health and insurance-related data ranges from 300 to 1,200+ USD per month depending on scale and features. This variable cost structure underscores the importance of right-sizing technology investments and understanding the total cost of ownership for digital insurance platforms.
Our report provides a detailed analysis of these dynamics, helping organizations anticipate regulatory shifts, manage compliance risks, and optimize operational expenditures. The full assessment of regulatory impacts and cost structures is elaborated upon in the complete market study.
Strategic Value for 2026 Decision-Making
For enterprises operating in or adjacent to the insurance sector, the insights contained in this report offer tangible strategic value. The concentration of the market, with CR3 at 18.5 percent and CR5 at 24.2 percent, indicates a landscape that is still relatively fragmented, leaving room for both consolidation and disruptive entry. Understanding where market power lies and how it is shifting is critical for partnership, acquisition, and competitive strategies.
Decision-makers can leverage this research to:
- Align technology roadmaps with emerging adoption trends in cloud, AI, and IoT.
- Evaluate competitive positioning relative to key platform providers and digital-native insurers.
- Anticipate regulatory changes and integrate compliance into product design from the outset.
- Assess market entry opportunities based on segmentation dynamics and regional growth potential.
- Optimize investment decisions by understanding the cost implications of digital infrastructure and data management.
The report is structured to move beyond high-level observations, offering operational insights that can be directly applied to strategic planning processes. From technology selection criteria to risk mitigation frameworks, the analysis covers the spectrum of considerations that leaders face in 2026.
Conclusion: Access the Complete Intelligence
The digital insurance market is at a pivotal juncture where technology, regulation, and customer expectations converge to reshape the industry. The growth trajectory, competitive movements, and regulatory developments outlined above provide a snapshot of the forces at play. However, the full depth of this transformation requires a more granular examination of segmentation data, regional nuances, and detailed company profiles.
PW Consulting's Digital Insurance Market report delivers the comprehensive intelligence needed to make informed, forward-looking decisions. By synthesizing market size forecasts, segmentation analysis, competitive profiling, and dynamic industry factors, this research equips stakeholders with the tools to navigate uncertainty and capitalize on emerging opportunities.
To access the complete dataset, detailed regional breakdowns, and actionable strategic recommendations, we invite you to explore the full report. The complete market intelligence is designed to support your organization's specific goals, whether you are optimizing core operations, launching new digital products, or evaluating investment opportunities in the insurance technology space.
For detailed analysis of this topic, please visit the official page: Digital Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com