

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: AI Game Generator Market Hits $247.3M in 2025, Projected to Surge to $1,171.1M by 2032 at 24.5% CAGR

The Strategic Imperative: Navigating the AI Game Generators Market in 2026
Previewing PW Consulting's Comprehensive Market Intelligence Report
The landscape of video game development is undergoing a seismic shift, driven by the rapid maturation of generative artificial intelligence. What was once a niche experimentation phase has evolved into a core component of production pipelines across the global industry. For executives, investors, and product strategists, understanding the trajectory of AI Game Generators is no longer optional—it is critical for sustaining competitive advantage in a hyper-accelerated market environment.
PW Consulting is pleased to introduce our latest deep-dive research study, designed specifically to equip decision-makers with the actionable intelligence needed to navigate the forecast period from 2026 to 2032. This article serves as a strategic overview, highlighting the magnitude of the opportunity and the key dynamics shaping the sector, while reserving the granular financial modeling and segmentation data for our full proprietary report.
Market Trajectory and Historical Acceleration
The momentum behind AI-driven game generation is best understood through the lens of recent historical performance. The market has demonstrated remarkable resilience and growth velocity over the past half-decade. Starting from a baseline of 42.1 million USD in 2020, the sector expanded to 63.33 million USD in 2021, and crossed the 100 million USD threshold in 2022. This upward trend accelerated significantly, reaching 161.87 million USD in 2023 and approaching 199.47 million USD in 2024.
AI Game Generators Market
By the base year of 2025, the market size was estimated at 247.3 million USD. This historical compound growth sets the stage for a forecast period where expansion is expected to continue at a robust pace. Our analysis projects the market to reach 301.04 million USD in 2026, further climbing to 395.98 million USD in 2027, and 482.08 million USD in 2028. The trajectory suggests a significant milestone near the end of the decade, with projections indicating a valuation of 768.14 million USD by 2030. Ultimately, the forecast extends to 1171.1 million USD by 2032.
This growth narrative supports a Compound Annual Growth Rate (CAGR) of 24.5 percent over the forecast period. Such a rate indicates not just incremental improvement, but a fundamental transformation in how games are conceived, built, and iterated. For enterprise strategists, this velocity implies that window of opportunity for market entry or expansion is narrowing. The differentiator will not be access to technology, but the strategic integration of these tools into broader business models.
Technological Pillars and Deployment Strategies
The AI Game Generators Market is not a monolith; it is composed of distinct technological capabilities that serve different stages of the development lifecycle. Understanding which technology pillars drive value is essential for allocating R&D budgets and partnership resources. The landscape includes advanced systems for Text-to-3D Models, which allow developers to generate complex three-dimensional assets from simple prompts. This capability is reshaping asset creation pipelines, reducing the time required for modeling and texturing.
Simultaneously, Text-to-2D Assets and Sprites remain a critical component, particularly for 2D gaming genres and UI element generation. These tools enable rapid prototyping and style-consistent asset production. Beyond visual assets, Code Generation Tools are increasingly being utilized to automate scripting and logic implementation, allowing engineers to focus on architecture rather than repetitive coding tasks. Furthermore, Level Generation Systems are automating the creation of virtual environments, enabling procedural world-building that scales with player engagement needs.
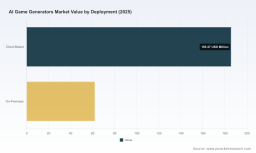
Deployment models also play a crucial role in market adoption. The market is split between Cloud-Based solutions, which offer scalability and lower upfront infrastructure costs, and On-Premises deployments, which cater to studios with stringent data security or latency requirements. Our full report dissects the revenue contribution and adoption rates of each segment, providing a clear picture of where capital is flowing within the technology stack. While specific allocation percentages are detailed in the comprehensive study, the overarching trend favors flexible, scalable solutions that integrate seamlessly with existing engine workflows.
Competitive Landscape and Key Market Players
The competitive environment is characterized by a mix of specialized AI-native startups and established technology giants integrating AI into their existing ecosystems. Market concentration data indicates a moderate level of consolidation, with the top three players holding a significant share, while the top five firms capture a broader portion of the total revenue. This structure suggests that while dominance is being established, there remains room for agile innovators to capture niche segments.
Several key companies are defining the boundaries of what is possible in this sector. Rosebud AI, based in San Francisco, provides AI-powered prompt-to-game generation for creating playable 2D/3D browser games, assets, NPCs, and full experiences without coding. This end-to-end approach appeals to indie developers and rapid prototyping teams. Scenario, also headquartered in San Francisco, offers an AI platform for generating style-consistent game assets, images, video, 3D, and textures by training custom models on studio art data, a solution utilized by major studios such as Ubisoft.
Layer AI operates as a creative AI platform for game studios, offering image, video, 3D, and audio generation with custom styles, workflow automation, and high-volume production capabilities. Ludo.ai, with a presence in Sacramento and Seattle, focuses on an AI platform for game research, concept generation, market analysis, asset creation including sprites and 3D models, and prototypes to accelerate game development. On the environmental side, Promethean AI provides an AI system for procedural world-building and environment design, automating placement and generation of assets for virtual worlds.
Additionally, established giants are integrating these capabilities. Unity Technologies, based in San Francisco, offers Muse and ML-Agents for AI-assisted game development, prompt-based generation, and behavioral AI within Unity engine workflows. These companies represent the vanguard of the industry, and our report includes detailed profiling of their strategic moves, product roadmaps, and partnership ecosystems. Understanding the specific positioning of each player is vital for identifying potential collaborations or competitive threats.
Regulatory Dynamics and Ethical Considerations
As the market matures, the regulatory environment is becoming an increasingly important factor in strategic planning. The introduction of frameworks governing artificial intelligence is shaping how developers deploy generative tools. For instance, the EU AI Act entered into force in August 2024, with full applicability for most provisions expected by August 2026. Under this framework, most AI-powered video games are classified as minimal or no risk, requiring limited or no obligations. However, compliance readiness remains a key concern for studios operating across multiple jurisdictions.
Complementing regulatory frameworks, industry bodies are establishing best practices. In July 2025, the International Gaming Standards Association (IGSA) released an Ethical Use of Artificial Intelligence best practices document. This framework provides guidance for the AI in gaming industry, developed with input from regulatory authorities. The IGSA released nine best practices for ethical AI use in gaming, covering purpose documentation, fairness, and oversight. These guidelines are becoming a de facto standard for responsible development.
Furthermore, legal considerations regarding intellectual property remain complex. AI-generated content in games raises copyright considerations in many jurisdictions, where AI is not recognized as an author, requiring human oversight for protection. Strategic teams must account for these legal nuances when building pipelines that rely heavily on generative outputs. Additionally, the high computational demands for training custom generative models and real-time inference in game asset creation rely heavily on GPU infrastructure, adding a layer of technical and capital planning to the regulatory equation.
Operational Content and Strategic Utility of the Report
PW Consulting's full market research report is designed to move beyond high-level trends and provide the operational data necessary for execution. The study encompasses a thorough analysis of market size drivers, restraints, and opportunities. It offers a detailed segmentation analysis that breaks down the market by region, technology, and deployment mode, allowing readers to identify high-growth pockets within the broader landscape.
The report includes comprehensive profiles of the key companies mentioned, along with an analysis of recent developments such as the IGSA standards release. It provides a competitive benchmarking section that evaluates market positioning, product capabilities, and strategic focus areas. For financial planners, the report includes forecast models that project revenue flows over the 2026-2032 period, enabling precise budgeting and investment forecasting.
Additionally, the study addresses the industry context noise, including regulatory shifts and technological constraints like computational requirements. This holistic view ensures that decision-makers are not blindsided by external factors that could impact deployment timelines or cost structures. The FAQ section of the report tackles common queries regarding copyright, risk classification, and infrastructure needs, serving as a quick reference guide for legal and technical teams.
Conclusion: Securing Position in a High-Growth Sector
The AI Game Generators Market represents one of the most dynamic growth sectors in the technology and entertainment industries. With a projected CAGR of 24.5 percent and a market trajectory moving toward over 1 billion USD by 2032, the stakes for strategic positioning are high. The convergence of advanced generative models, evolving regulatory standards, and intense competition among key players creates a complex environment that demands precise intelligence.
AI Perfume Generator Market
PW Consulting's latest report is built to provide that precision. By integrating historical data, detailed segmentation analysis, and competitive profiling, this study offers a roadmap for navigating the forecast period. We invite industry leaders, investors, and strategic planners to access the full comprehensive report to gain the granular insights required to make informed decisions. The full breakdown of regional splits, specific technology revenue shares, and detailed financial forecasts is available in our complete market intelligence package.
In a market moving at this speed, visibility is currency. Ensure your organization has the clarity needed to capitalize on the opportunities within the AI Game Generators Market. Reach out to access the full study and secure your strategic edge for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: AI Game Generators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com