

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bioprocessing Data Analytics Market Hits $680M in 2025, Poised for 12.5% CAGR to $1.55B by 2032

Bioprocessing Data Analytics Software: Navigating the Next Wave of Market Intelligence
Executive Overview
The bioprocessing industry is undergoing a fundamental shift in how data is captured, analyzed, and acted upon. As biologics development cycles shorten and manufacturing complexity increases, organizations are moving from isolated laboratory systems toward integrated analytics platforms that span the entire value chain. Our latest market research on the Bioprocessing Data Analytics Software Market offers a structured, forward-looking view of this transition, designed specifically to inform capital allocation, technology roadmapping, and partnership strategy through 2032.
This article serves as a strategic preview of the full study. It highlights the macro trajectory, the operational drivers reshaping procurement decisions, the competitive architectures that buyers should monitor, and the regulatory currents that are quietly redefining software requirements. For teams preparing budgets, evaluating vendor shortlists, or building digital manufacturing strategies for 2026, this intelligence provides the context needed to move from reactive spending to deliberate investment.
Bioprocessing Data Analytics Software Market
Market Trajectory: From Steady Growth to Accelerated Scaling
The market has demonstrated consistent expansion over the past half-decade, with revenue climbing from approximately 377 million USD in 2020 to a projected 762.72 million USD in 2026. The base year of 2025 is estimated near 680 million USD, reflecting a sector that has absorbed multiple rounds of technological maturation, broader cloud adoption, and increasing regulatory pressure for data integrity across GxP workflows. Looking forward, our forecast model projects the market to surpass 844 million USD in 2027 and continue upward through 2032, reaching an estimated 1.55 billion USD by the close of the forecast period.
The compound annual growth rate measured across the 2026-2032 window is tracked at 12.5 percent. This pace is not merely a reflection of incremental software adoption; it signals a structural change in how biomanufacturers view analytics as a core operational capability rather than a supportive tool. Early historical years showed steady double-digit movement, and the acceleration in the near-term outlook aligns with the convergence of automation, multivariate analysis, and AI-ready dataset construction. Organizations that treat these platforms as long-term infrastructure investments are positioning themselves for more predictable process performance, faster tech transfer, and stronger compliance posture.
Strategic Drivers Shaping 2026 Decision-Making
Several interlocking forces are converging to reshape procurement priorities for bioprocessing analytics software. Understanding these drivers is essential for any team evaluating purchase timing, scope of deployment, or integration requirements.
-
Regulatory expectations for data integrity are intensifying. Software solutions deployed in bioprocessing environments must align with FDA 21 CFR Part 11 requirements for electronic records, audit trails, and data integrity within GxP settings. At the same time, EU GMP Annex 1 revisions emphasize risk-based approaches and sterile manufacturing controls, increasing demand for validated analytics platforms that can demonstrate traceability, controlled access, and robust dataset governance. These requirements are no longer peripheral compliance concerns; they are becoming central selection criteria that influence architecture, deployment models, and vendor due diligence.
-
Process Analytical Technology frameworks are normalizing real-time monitoring. FDA guidance on PAT encourages real-time monitoring and multivariate analysis in bioprocessing, pushing organizations toward tools that can support continuous measurement, feedback loops, and predictive modeling. Buyers are increasingly evaluating platforms not only for retrospective reporting but also for their ability to feed live process signals into decision workflows and to support QbD-oriented development programs.
-
The clinical and commercial pipeline is demanding faster, more reproducible outcomes. As molecule complexity rises and CDMO collaboration expands, manufacturers need analytics that can span process development, manufacturing, and quality functions without fragmentation. Teams are seeking platforms that reduce manual reconciliation across online, at-line, and offline data streams, while enabling cross-run analysis and structured data handoffs between development and production.
-
AI and natural language interfaces are lowering the barrier to advanced analytics. Recent product launches and software releases indicate an industry-wide push toward more intuitive interaction models, including conversational interfaces and automated insight generation. This trend is broadening the actionable user base beyond dedicated data scientists, allowing process engineers, quality teams, and manufacturing leads to engage directly with analytics outputs.
These dynamics do not operate in isolation. Regulatory pressure raises the compliance floor, PAT frameworks raise the analytical ceiling, and pipeline urgency raises the cost of delay. Together, they create a market environment where the strategic question is no longer whether to invest in analytics software, but how to select, integrate, and scale it in a way that supports both near-term operational wins and long-term data architecture resilience.
What the Full Study Delivers: A Practical Toolkit for Strategy Teams
Our report is constructed to move beyond high-level trends and offer directly usable market intelligence. It is organized to support multiple internal workflows, including technology sourcing, competitive benchmarking, M&A scouting, and regional expansion planning. The study combines macro market sizing with deep operational context so that decision-makers can connect market trajectory to their own execution plans.
Key components of the research include:
-
Historical and forecast market sizing with scenario-aware context. The report maps revenue evolution across the historical window and extends through the full forecast horizon, providing a structured view of growth inflection points and the factors that shape them. Rather than presenting numbers in isolation, the analysis ties sizing to adoption patterns, deployment shifts, and functional demand trends that explain why the market is moving as it does.
-
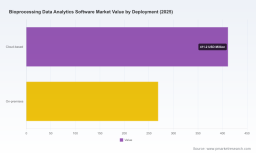
Segment-level evaluation across deployment and application dimensions. The study breaks the market into meaningful structural categories, including cloud-based and on-premises deployment paths, as well as application areas such as process development, manufacturing and production, and quality and regulatory compliance. This segmentation is used to identify where demand is concentrating, what use cases are accelerating adoption, and how different organizational maturity levels influence purchasing behavior.
-
Deployment and architecture considerations for enterprise buyers. Because bioprocessing data environments often span legacy instruments, LIMS/ELN systems, MES integration points, and cross-site data flows, the report evaluates how platform architecture influences scalability, validation effort, and long-term maintainability. These discussions are intended to help buyers align software selection with their broader digital manufacturing roadmap.
-
Competitive positioning and vendor strategy mapping. The analysis examines how leading providers differentiate through platform scope, compliance readiness, analytics depth, and ecosystem integration. It is designed to support vendor shortlisting, RFP design, and negotiation strategy by clarifying where each player is competing and what tradeoffs buyers should expect.
-
Regulatory and quality alignment mapping. Given the centrality of compliance to purchasing decisions, the study connects market dynamics to the practical implications of GxP data requirements, validated system expectations, and real-time monitoring frameworks. This helps organizations anticipate what vendors should demonstrate during evaluation and what internal validation effort may be required after selection.
For teams responsible for capital planning in 2026, the report is intended to function as a decision-support asset rather than a static industry summary. It provides the structure needed to compare deployment options, weigh integration complexity, and align software strategy with operational priorities across development and manufacturing functions.
Competitive Landscape: Six Players Shaping the Platform Race
The market is characterized by a mix of specialized analytics providers and broader life-science or manufacturing technology companies, with competitive intensity rising as platforms expand from data visualization into integrated workflow orchestration and AI-assisted analysis. Our research tracks the strategic postures of several core organizations that are actively shaping buyer expectations and setting the functional bar for next-generation bioprocessing analytics.
Genedata
Headquartered in Basel, Switzerland, Genedata offers an enterprise platform built around integrated data management, automation, and analytics across bioprocess development and CMC workflows. Its positioning emphasizes QbD support, AI-ready datasets, and compliance-aligned design, making it relevant for organizations seeking a more unified development-to-manufacturing data backbone. Recent activity underscores this trajectory: in August 2025, the company released a new version of Genedata Selector focused on GMP-compliant NGS in biopharma manufacturing and quality control. In March 2026, mAbxience selected Genedata Bioprocess to automate end-to-end CDMO workflows, an indicator of how broader workflow automation is becoming a competitive differentiator.
Invert
Based in San Francisco, Invert provides an infrastructure and AI-powered intelligence platform aimed at bioprocess data unification, real-time monitoring, analysis, and optimization. Its interface strategy has drawn attention with the introduction of Invert Assist, a natural language analysis interface launched in October 2025 to support process modeling, data analysis, and insight generation. This type of interface innovation matters strategically because it expands accessibility to analytics outputs and reduces reliance on highly specialized data teams for routine interpretation tasks.
Körber Pharma
Körber Pharma, based in Lüneburg, Germany, brings PAS-X Savvy, a collaborative real-time bioprocess data analytics and management platform focused on visualization, holistic analysis, PPI, and integration with MES systems. Its strength lies in connecting analytics more tightly to execution and operational systems, which appeals to manufacturers seeking a more continuous link between data insight and production control.
Sartorius
Sartorius, headquartered in Göttingen, Germany, offers SIMCA and MODDE software for multivariate data analysis, DOE, real-time process monitoring through SIMCA-online, predictive analytics, and QbD in bioprocessing. Its long-standing presence in analytical and process-related tooling gives it a strong foundation in multivariate methods and process understanding, which remains central for teams pursuing rigorous experimental design and live monitoring.
BioRaptor
BioRaptor, based in Binyamina, Israel, specializes in a bioprocessing data analytics platform that unifies online, at-line, and offline data, applies machine learning for optimization, supports cross-run analysis, and integrates with LIMS and ELN systems. Its value proposition is particularly relevant for organizations trying to break down data silos and create a more cohesive analytical record across heterogeneous measurement environments.
Merck KGaA / Sigma-Aldrich
Through its offering of Bio4C ProcessPad software, Merck KGaA / Sigma-Aldrich provides a solution focused on bioprocessing data collection, visualization, and analytics. As a player with broad life-science reach, its software entry can be attractive for organizations already embedded in its reagent, material, or service ecosystems, especially when data collection standardization and straightforward visualization are priorities.
Beyond individual profiles, the competitive picture is defined by concentration and consolidation pressure. The market reflects a meaningful share held by a limited number of leading firms, with the top three and top five players collectively representing a substantial portion of market value. This structure matters for buyers because it influences negotiation leverage, integration risk, and the breadth of alternative options available during vendor evaluation. At the same time, continued product launches, deployment wins, and software updates suggest that differentiation is increasingly occurring in areas such as compliance readiness, AI-assisted interaction, MES/LIMS connectivity, and end-to-end workflow automation.
Deployment, Application, and Geographic Context
The market's structure is being shaped not only by vendor competition but also by how organizations choose to deploy and apply analytics software. Cloud-based and on-premises deployment paths each carry distinct tradeoffs around scalability, control, validation effort, and connectivity to existing manufacturing systems. Meanwhile, application demand is distributed across process development, manufacturing and production, and quality and regulatory compliance, with each functional area placing different emphasis on multivariate analysis, real-time monitoring, traceability, and cross-functional data sharing. The full study examines these structural splits in detail so that buyers can assess where their own demand profile aligns with broader market momentum.
Geographic distribution also plays a role in shaping demand intensity, vendor reach, and implementation complexity. Different regions reflect varying levels of biomanufacturing maturity, regulatory interpretation, and digital infrastructure readiness. While our research maps these regional dynamics, the practical implication for 2026 planning is that deployment decisions should be evaluated with local compliance expectations, internal data governance maturity, and integration constraints in mind rather than treated as purely technology-driven choices.
Implications for 2026 Strategy and Beyond
For executives and strategy teams planning the 2026 investment cycle, the market signals point toward a few recurring priorities. First, analytics software is increasingly being treated as a multi-year enabler rather than a point solution, which means selection criteria should weigh scalability, data architecture compatibility, validation readiness, and the ability to support evolving use cases across development and manufacturing. Second, AI-enabled interfaces and natural language interaction are expanding the practical reach of analytics, but they do not remove the need for strong underlying data governance and compliance design. Third, the competitive field is maturing quickly, and vendor differentiation is becoming more subtle; buyers need a structured evaluation framework that goes beyond feature checklists to include workflow fit, integration effort, and long-term maintainability.
Bioprocess Controllers and Automation Systems Market
The broader takeaway is that the market is moving from early-stage adoption to a more demanding phase where performance, compliance, and integration quality determine the value a platform ultimately delivers. Organizations that enter this phase with clear internal requirements, realistic deployment assumptions, and a well-defined analytics strategy are better positioned to capture the operational benefits that fuel continued market growth.
Conclusion: From Signal to Strategic Action
The Bioprocessing Data Analytics Software Market is entering a period of sustained expansion supported by regulatory pressure, PAT-inspired real-time analytics, broader cloud and AI adoption, and increasing demand for unified data workflows across development and manufacturing. Our research provides a detailed map of that trajectory, the competitive structures shaping it, and the practical factors that should guide purchasing and investment decisions in 2026 and beyond.
This preview is intended to demonstrate the depth and orientation of the full study, but the complete report contains the segmentation detail, competitive benchmarking, deployment analysis, and regional context needed to turn market signals into actionable strategy. For teams preparing budgets, evaluating vendor shortlists, or building analytics roadmaps, accessing the full intelligence framework offers a more precise foundation for decision-making and a clearer view of where the market is headed through 2032.
For detailed analysis of this topic, please visit the official page: Bioprocessing Data Analytics Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com