

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
Degradable Implants Market: Why 8.25% CAGR and Material Shifts Redefine Growth
By pmarketresearch, 2026-09-18
Degradable Implants Market: Stragetic Trends and Commercial Opportunities in the Bioabsorbable Era
1. Market Reality and Core Challenges
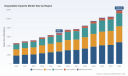
The global market for degradable implants has crossed a critical inflection point. Valued at approximately USD 6.85 billion in 2025, the segment has expanded steadily from around USD 4.61 billion in 2020, reflecting a compound annual growth rate of 8.25 percent through 2032. By the end of the forecast window, annual revenue is projected to approach USD 11.93 billion. This trajectory is not merely a function of rising procedural volumes; it reflects a structural shift in how clinicians and health systems evaluate implant performance. The preference is moving away from permanent hardware that requires secondary removal procedures, toward bioabsorbable solutions that support tissue regeneration while gradually transferring load back to native structures.
Despite the growth trajectory, the industry faces several operational and commercial headwinds that shape how value is captured. First, the regulatory bar for bioresorbable devices remains unusually high. Agencies require comprehensive biocompatibility profiling, long-term in vivo degradation tracking, and explicit demonstration of mechanical equivalence throughout the resorption timeline. These requirements extend development cycles and raise the cost of clinical validation, particularly for metallic and polymer systems that behave differently during early inflammation and remodeling phases.
Biodegradable Micro Screws Market
Second, the economics of advanced biomaterials create a narrow margin window. Specialized magnesium alloy development and precision manufacturing currently generate production costs 30-50 percent higher than conventional titanium or stainless-steel implants. Procurement teams accustomed to cost-per-procedure comparisons must reconcile upfront premium pricing with downstream savings from eliminated removal surgeries and reduced revision rates. This value proposition is persuasive in controlled pilot settings, yet it demands robust real-world evidence before widespread formulary adoption.
Third, supply chain concentration introduces pricing volatility and geographic risk. China dominates primary magnesium production, which means medical-grade biodegradable magnesium alloys are exposed to raw material fluctuations and logistics constraints. Manufacturers must navigate this dependency while maintaining strict purity and structural consistency for load-bearing applications. The convergence of these challenges—regulatory rigor, cost premiums, and commodity exposure—means that commercial success depends less on product novelty alone and more on integrated evidence generation, manufacturing discipline, and reimbursement strategy.
2. Key Drivers Reshaping the Market
Technology Innovation and Material Breakthroughs
Material science is the primary engine behind the market's expansion. Polymer-based systems have matured significantly, with self-reinforced PLGA constructs now enabling trauma, pediatric, and extremity applications that were previously limited by mechanical strength concerns. Magnesium alloy implants have emerged as the most disruptive category, combining favorable mechanical compatibility with predictable resorption and bioactive stimulation of bone healing. The ability to offer magnesium-based screws and pins with regulatory clearances has shifted magnesium from a research curiosity to a clinically viable fixation option. These advances are crossing over into cardiovascular scaffolds and soft-tissue repair, where temporary support structures reduce long-term foreign-body concerns. The broader implication is that device manufacturers are no longer choosing between resorbable and permanent hardware on a binary basis; they are engineering degradation profiles to match specific anatomical and clinical timelines.
Regulatory Evolution and Evidence Standards
Regulatory pathways are becoming more defined, but they are also more demanding. Guidance from major agencies now consistently requires ISO 10993 biocompatibility testing, long-term in vivo degradation studies, and demonstration of mechanical equivalence across the degradation window. This framework is simultaneously a barrier and a competitive moat. Companies that build rigorous evidence pipelines early can secure first-mover advantages, while laggards face lengthened development timelines and fewer differentiation points. Recent milestones illustrate the trend: magnesium-based orthopedic implants have achieved landmark clearances in the US and CE marks in Europe, establishing regulatory precedents for metallic bioabsorbable devices. These approvals do not lower the bar; they clarify it. The message to the industry is that evidence design, not just device design, increasingly determines commercial viability.
Demand-Side Shifts and Clinical Economics
Clinical demand is being shaped by two reinforcing forces: procedural preference and total-care economics. Surgeons increasingly favor implants that eliminate the need for secondary removal, particularly in pediatric populations, sports medicine, and trauma cases where revision surgery carries additional risk. At the same time, health systems are scrutinizing downstream costs more closely. A premium-priced bioabsorbable implant can be economically justified when it reduces readmission, revision, and rehabilitation burden. Dental and craniofacial applications further expand the demand base, as temporary fixation and guided bone regeneration benefit from materials that resorb without leaving permanent hardware in aesthetically sensitive sites. This demand evolution is not uniform across regions or service lines; it is strongest where clinical outcomes and total episode cost can be linked through credible evidence.
Supply Chain Dynamics and Manufacturing Capability
Cost structure and supply resilience are becoming strategic differentiators. Medical-grade biodegradable alloys and specialty polymers depend on controlled synthesis, precision machining, and consistent sterilization processes. The concentration of primary magnesium production in specific geographies amplifies pricing exposure and incentivizes manufacturers to diversify sourcing, secure long-term agreements, and invest in internal alloy formulation expertise. Manufacturing scale is not the only concern; consistency is. Slight variations in degradation rate or surface characterization can alter clinical performance and regulatory acceptance. As a result, the supply chain is evolving from a commodity procurement function into a core competency that shapes margin structure, product reliability, and time-to-market.
3. Competitive Landscape and Leading Strategies
The competitive field blends focused specialty innovators with large musculoskeletal and cardiovascular platforms. The landscape is not yet consolidated around a single material class, but it is increasingly segmented by evidence depth, regulatory positioning, and application focus. Understanding how the leading players position themselves helps clarify where value is being created and where openings remain.
Among the specialty innovators, Bioretec has emerged as a notable example of a focused strategy centered on fully absorbable orthopedic implants. The company has pursued regulatory milestones in parallel with portfolio expansion, including CE mark approvals for trauma screw products, FDA Breakthrough Device Designation for a magnesium alloy drill pin, and continued commercialization of PLGA-based Activa implants for trauma and pediatric applications. These moves reflect a deliberate pathway strategy: pair magnesium fixation with polymer options where mechanical or resorption profiles differ, and build an evidence base that spans adults and children. Inion, another Finland-based specialist, has commercialized bioabsorbable and bioactive plates, screws, pins, and anchors across orthopedics, CMF, spine, sports medicine, and dental indications, with a substantial clinical footprint. Inion's approach emphasizes a broad polymer platform and cross-application reuse of material know-how, which allows it to serve multiple surgical specialties while maintaining a coherent product architecture. Syntellix has built its identity around magnesium alloy bioabsorbable screws and pins for orthopedic and trauma fixation, leveraging CE-certified metallic solutions and clinical use across multiple regions. Its positioning underscores the growing credibility of magnesium as a load-bearing resorbable option and the importance of demonstrating real-world fixation performance.
Large players are entering and scaling through complementary strategies. Medtronic offers bioresorbable technologies across orthopedic and cardiovascular applications, including vascular scaffolds and fixation solutions, leveraging broad distribution and clinical networks. Johnson & Johnson, through its medtech division, develops polymer-based bioresorbable fixation systems for orthopedics and CMF, aligning resorbable hardware with established surgical franchises. Stryker and Zimmer Biomet supply bioabsorbable implants and fixation devices for orthopedic trauma and sports medicine, integrating resorbable options into wider product portfolios. Smith+Nephew markets bioabsorbable implants for soft tissue repair and orthopedic applications, where temporary scaffolds can support healing without permanent hardware. In the cardiovascular space, Biotronik has developed resorbable magnesium scaffolds for coronary interventions, illustrating how degradable technology extends beyond fixation into vessel support and remodeling.
PW Consulting Health Care Research Center
Several strategic patterns distinguish the leaders. First, material-platform thinking is replacing single-product tactics. Companies that can adapt a polymer or magnesium base across trauma, pediatrics, CMF, spine, or dental applications gain manufacturing leverage and clinical credibility simultaneously. Second, regulatory positioning is being used as a competitive moat. Early clearances, breakthrough designations, and well-documented degradation data create preference in formulary discussions and surgeon adoption cycles. Third, application breadth versus depth is a deliberate trade-off. Some specialists pursue deep evidence and regulatory traction in a narrow field to command premium positioning, while larger firms use resorbable lines to complement existing franchises and cross-sell into established procedural volumes.
Endosseous Implant Market
The market structure is evolving along three axes. Consolidation is likely in distribution and evidence generation, where scale matters for clinical studies, reimbursement files, and surgeon education. Differentiation is intensifying around degradation control, mechanical performance, and application-specific evidence. New entrants will continue to emerge where there are unmet indications or underserved geographies, but they will face the same evidence and supply expectations that define the leaders. The net effect is a competitive environment where technology alone is insufficient; credible clinical data, manufacturing consistency, and commercial execution determine who captures durable share.
4. Outlook: Three Trends to Watch Over the Next Three to Five Years
The next phase of market evolution will be defined by how companies convert material advances into repeatable commercial value. Three trends are particularly consequential.
1. Evidence-led adoption will become the primary growth lever. As more bioabsorbable products reach mature regulatory status, the differentiation shift moves from approval to adoption. Expect a rising emphasis on prospective registries, comparative studies against permanent hardware, and total-cost-of-care analyses that justify premium pricing. Manufacturers that publish robust, indication-specific outcomes will gain formulary momentum; those relying on mechanistic promises will face longer adoption cycles.
2. Material segmentation will deepen, with magnesium and polymers occupying distinct clinical lanes. Magnesium alloys will continue to expand in load-bearing fixation where rapid resorption and mechanical compatibility matter, while polymers will remain strong in applications requiring tunable degradation and softer tissue integration. The opportunity lies in matching material behavior to clinical timelines rather than treating bioabsorbable technology as a single category. Companies that articulate these lanes clearly will reduce misinterpretations and accelerate surgeon confidence.
3. Supply resilience and cost control will separate sustainable players from fragile ones. With raw material concentration and precision manufacturing requirements, the ability to manage alloy sourcing, purity, and scale consistency will increasingly influence margin stability. Expect more dual-sourcing strategies, long-term supply agreements, and internal process control investments. Pricing pressure will not disappear, but it will be offset by value demonstration and supply reliability rather than by cost competition alone.
These trends carry risk. Regulatory expectations may tighten further if post-market data reveal variability in degradation or inflammatory response. Reimbursement momentum could slow if health systems demand more localized cost evidence. Magnesium supply volatility may re-emerge, affecting planning and margins. Still, the directional signal is clear: the market is moving from novelty to execution, and the winners will be those who combine material innovation with credible evidence and dependable supply.
5. Strategic Moves for Decision Makers
For manufacturers, the priority is to build a coherent evidence-to-commercialization plan around a defined material and application strategy. That means selecting indications where degradation profiles and mechanical demands align, designing clinical studies that speak to total episode value, and securing supply pathways that can withstand raw material volatility. A narrow, well-supported indication can outperform a broad but thinly evidenced portfolio in both adoption speed and pricing power.
For investors, the most durable opportunities are likely in companies that pair regulatory traction with repeatable manufacturing and a clear value narrative. Look for credible biocompatibility data, evidence of mechanical equivalence across degradation timelines, and signs that premium pricing is being justified by reduced revision, removal, or rehabilitation burden. Diversified platforms with resorbable lines integrated into established surgical franchises may offer broader exposure, while focused specialists can deliver higher optionality if they secure and defend key regulatory and clinical positions.
For procurement and clinical leaders, the practical step is to structure evaluation criteria that compare total cost of care rather than unit price alone. Pilot programs should track revision rates, removal procedures, patient-reported outcomes, and downstream resource use, not just implant performance at the time of surgery. Where evidence supports it, bioabsorbable options can reduce long-term burden in appropriate indications, but that conclusion must be validated within local clinical pathways and reimbursement realities.
The market is moving quickly enough that portfolio decisions, partnership choices, and procurement frameworks need current, granular intelligence. A detailed report can map segment-level dynamics, company-by-company regulatory status, material cost structures, and application-specific adoption signals with the granularity needed for timing and prioritization decisions.
For detailed analysis of this topic, please visit the official page: Degradable Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nystatin API Market 2026: Why 3.85% CAGR and Geography Redefine Growth Drivers
By pmarketresearch, 2026-09-18
The Nystatin API Market at an Inflection Point: Sizing the Opportunity in a Mature, Quality-Driven Segment
Market Overview: A Steady Trajectory Masked by Structural Headwinds
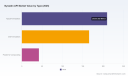
The Nystatin API market has followed a measured expansion path over the past half-decade, settling into a phase where growth is real but increasingly dependent on margin preservation rather than volume surges. Valued at approximately $345.5 million in 2020, the market climbed to $385.58 million by 2023 and reached $409.68 million in 2024 before settling at $417.33 million in 2025. The forward trajectory points to a consolidated rise, with the market expected to reach $441.53 million in 2026, $490.43 million by 2028, and peak around $543.65 million by 2032. The implied compound annual growth rate of roughly 3.85% across the 2025–2032 horizon reflects a market that is growing but not booming, where incremental gains depend heavily on formulation refinement, regional access expansion, and supply chain reliability.
This baseline growth masks a more nuanced operational picture. The segment is not characterized by explosive demand spikes; rather, it is defined by steady clinical utilization, a mature therapeutic footprint, and a supply base that must continuously adapt to tighter quality expectations and shifting cost structures. For decision-makers, the headline figures should not be read as a signal of untapped volume potential. Instead, they point to a market where value capture will increasingly come from operational efficiency, regional market access, and differentiation in product format rather than from broad-based consumption growth.
Three structural challenges dominate the current landscape and shape how participants allocate capital and attention. First, the market exhibits moderate but meaningful concentration, with a handful of established suppliers controlling a significant share of the addressable supply. This concentration limits pricing flexibility for smaller entrants and raises switching costs for buyers who rely on validated sources with established regulatory footprints. Second, production economics are tightly coupled to fermentation-based synthesis, which introduces exposure to raw material variability, process control complexity, and impurity management. Even when demand is predictable, margin pressure can emerge quickly if input costs rise or yield consistency falters. Third, regulatory and quality expectations continue to intensify. Compliance with recognized pharmacopeial standards and contamination-control protocols is no longer a baseline differentiator; it has become a gatekeeper for market access, especially in procurement environments where audit-ready documentation and consistent batch quality dictate supplier selection.
These challenges do not signal stagnation. They signal a market in which the rules of competition are shifting from supply availability toward supply credibility, operational resilience, and formulation relevance. Companies that treat Nystatin API as a commodity input may find themselves squeezed by price comparisons and tender dynamics. Those that approach it as a regulated, process-sensitive specialty ingredient can defend position through certification depth, supply continuity, and application-specific support.
What Is Actually Driving the Market
Technical Process Complexity as a Demand Filter
Nystatin API remains bound to fermentation-derived production methods, and that dependence shapes both who can compete and how they must operate. The production process requires rigorous control of fermentation-derived impurities, with tight adherence to recognized pharmacopeial and quality guidelines. In practical terms, this means that scale alone is not a reliable competitive advantage. A manufacturer with high-volume capacity but inconsistent process control will face greater rejection risk, more frequent quality investigations, and higher cost of compliance than a smaller operator with superior process discipline. This dynamic reinforces a filter in the market: quality maturity is becoming a precondition for sustained commercial relevance, not simply a hygiene factor.
Penicillin Active Pharmaceutical Ingredients Market
The business implication is clear. For producers, the most durable gains are likely to come from refining fermentation yield, tightening impurity control, and building repeatable batch consistency. For buyers, the decision logic increasingly favors sources that can demonstrate documented process control and traceability, especially where finished formulations must meet stringent pharmacopeial performance expectations. In this environment, technical capability translates directly into commercial optionality.
Certification and Regulatory Access as Commercial Currency
Regulatory documentation has evolved from a back-office requirement into a front-line commercial asset. Recent certification activity illustrates how suppliers use compliance milestones to reinforce market standing. In December 2025, VUAB Pharma updated its CEP certificate for Nystatin, a move that reinforces its position in markets where European compliance documentation carries significant procurement weight. Certifications such as CEP, USDMF, FDA-related approvals, and GMP alignment are not just regulatory checkboxes; they reduce friction in sourcing decisions, support cross-border supply, and give buyers a defensible basis for supplier qualification.
This is especially relevant because the Nystatin API supply chain is geographically distributed, with meaningful production presence across multiple regions rather than confined to a single sourcing hub. In such an environment, buyers often weigh not just price but the speed with which a supplier can enter qualified status, support routine procurement without repeated documentary burden, and respond to audit or quality inquiries. Regulatory readiness therefore functions as both a barrier and an enabler: it raises entry difficulty, but it also protects incumbents that have already invested in the necessary compliance infrastructure.
Application Mix and Formulation Relevance
The market’s demand side is shaped by how Nystatin is deployed across therapeutic settings. The most significant application footprint lies in dermatology, followed by gastroenterology, with a smaller remainder distributed across other uses. This split matters because it shapes product format requirements, delivery expectations, and buyer preferences. Topical and oral formulations continue to carry the largest share of market activity, with powder intended for compounding representing a more specialized but important niche. The practical consequence is that demand is not uniform. Buyers in dermatology-oriented procurement may prioritize batch-to-batch consistency, formulation compatibility, and supply stability, while gastroenterology-driven demand may place additional weight on oral dosage requirements and handling characteristics.
Beyond clinical application, the demand picture is also influenced by procurement behavior. In many purchasing environments, repeat procurement is driven less by brand novelty and more by reliability, documentation readiness, and total cost of ownership. As a result, suppliers that can align their product formats with the practical needs of compounding, dispensing, or formulation integration have a stronger chance of becoming preferred partners rather than interchangeable vendors.
Supply Geography and Cost Structure Realignment
Global Nystatin API production reached approximately 128 tons in 2025, with an average market price around $298 per kilogram. These figures provide a useful anchor for understanding the market’s cost geography. The supply base is concentrated in a limited number of manufacturing centers, including Romania, the Czech Republic, China, and India, while procurement patterns are more dispersed. This uneven distribution creates both opportunity and friction. On one hand, multiple sourcing geographies can support competition and resilience. On the other, fermentation raw material sourcing and process inputs remain vulnerable points that can affect availability and pricing.
For commercial strategy, the key takeaway is that cost leadership cannot be pursued naively. Price competitiveness in this market is inseparable from process stability, certification depth, and logistics reliability. A lower headline price may be offset by qualification delays, quality disputes, or supply interruptions. Conversely, suppliers that can maintain disciplined production economics while offering predictable availability may command stronger buyer preference even in a price-sensitive environment.
Competitive Landscape: Scale, Certification, and Strategic Positioning
Established Producers and Their Distinct Advantages
The competitive field is led by manufacturers that combine long operating history, fermentation expertise, and regulatory documentation with broad market reach. Antibiotice S.A., headquartered in Iași, Romania, stands out as one of the most established Nystatin API producers, with more than 66 years of experience in fermentation-based synthesis. Its commercial footprint extends to more than 75 markets, supported by FDA approval, CEP, and EU GMP certifications. That combination of longevity, certification breadth, and multi-market distribution gives the company a structural advantage in procurement environments where supplier track record and regulatory completeness reduce sourcing risk.
VUAB Pharma a.s., based in Roztoky u Prahy, Czech Republic, is another central player in the global supply picture. As a major producer of Nystatin API for both human and veterinary use, the company has built a profile around multiple certifications, including CEP, USDMF, FDA, and GMP alignment. Its affiliation with the Safichem Group further extends its operational context, alongside additional production in injections and cytostatic intermediates. For buyers, VUAB’s relevance lies in its ability to serve diversified demand while maintaining documentation that supports international procurement pathways.
Centrient Pharmaceuticals, operating from the Netherlands, reinforces the importance of certification-based positioning by supplying Nystatin API with active USDMF and CEP certifications. In a market where buyer confidence often hinges on documentation readiness and cross-border compliance, this type of positioning can be as important as volume capacity. Pfizer Inc. also remains relevant in the broader landscape through its historical and operational involvement, illustrating that large pharmaceutical organizations can maintain a presence even in smaller, mature API categories when alignment with broader supply strategy or legacy portfolio logic exists.
Regional Manufacturing Depth and Emerging Competition
Beyond the established European and multinational names, the supply base includes active manufacturers in China and India. Companies such as Fujian Fukang Pharmaceutical, Guangzhou Tosun Pharmaceutical, Zhejiang Huida Biotech, and Cerata Pharmaceuticals LLP represent the regional manufacturing depth that continues to shape sourcing options. Cerata’s WHO-GMP certification status, for example, signals a pathway to compete in procurement environments that value internationally recognized quality frameworks. Chinese manufacturers listed as Nystatin API suppliers contribute to broader availability and price competition, while also increasing the importance of due diligence on consistency and documentation.
Olon S.p.A. adds an Italian manufacturing dimension as an active supplier with GMP capabilities, showing that even within Europe, competition is not limited to the largest names. Collectively, these players indicate a market that is neither fully consolidated nor highly fragmented in a chaotic sense. Instead, it is a structured competitive field where several manufacturers hold defensible positions, and where differentiation depends on the intersection of quality assurance, supply continuity, and regional access.
How the Landscape Is Evolving
The current trajectory suggests a market that is consolidating competence rather than merely consolidating share. Certification updates, documentation maturity, and process discipline are becoming more important than the ability to simply offer an API in bulk. New entry is possible, but it is more likely to succeed where a company brings verifiable quality infrastructure, recognized compliance credentials, and a clear route to buyer qualification. In contrast, undifferentiated capacity expansion without credible regulatory or quality positioning is increasingly difficult to monetize in a market where procurement teams weigh audit readiness and supply reliability heavily.
PW Consulting Health Care Research Center
At the same time, M&A dynamics, group affiliations, and portfolio extensions may continue to shape the field. Where manufacturers can combine API supply with formulation relevance, veterinary lines, or related intermediates, they may create broader commercial resilience. For decision-makers, the competitive signal is straightforward: the market rewards manufacturers that can present themselves as low-friction, well-documented, and operationally dependable sources rather than as low-cost commodity providers alone.
The Next Three to Five Years: Trends That Will Shape Value Capture
Trend One: Compliance Depth as a Pricing and Access Lever
Over the next several years, the ability to demonstrate robust compliance documentation is likely to become a stronger commercial lever than in the past. As procurement organizations compare suppliers not only on unit price but also on qualification effort, audit exposure, and supply continuity, manufacturers with stronger certification portfolios and more mature process control will be better positioned to defend margins. The trend does not imply that price becomes irrelevant; it implies that price negotiations occur within a narrower field of qualified, trusted sources. Companies that can present clean documentation, consistent quality performance, and traceable manufacturing practices will have more room to compete on total value rather than on headline cost alone.
For commercial strategy, this trend suggests that investments in documentation rigor, regulatory upkeep, and quality systems can pay dividends in buyer preference and supplier longevity. The opportunity is not just to maintain certifications, but to use them as part of a broader value narrative that reduces friction for procurement teams.
Worldwide Butenafine API Market
Trend Two: Supply Resilience and Procurement Behavior Realignment
Supply chain vulnerabilities linked to fermentation raw material sourcing and geographically concentrated production are likely to remain a central concern. Buyers will continue to evaluate multi-source options, safety stock logic, and supplier responsiveness, especially where recurring demand must be met without interruption. This creates an environment in which suppliers that can provide predictable availability, transparent communication, and contingency readiness may gain preference even if their unit pricing is not the lowest in a tender comparison.
The commercial opportunity here lies in reliability as a differentiator. For manufacturers, this may mean investing in feedstock management, yield consistency, inventory planning, or regional distribution support. For buyers, it means re-evaluating sourcing strategies so that resilience is priced into supplier selection rather than treated as an afterthought. In practice, the market may increasingly reward a “ dependable supplier premium,” where dependable means more than delivery timeliness and includes documentation, quality stability, and responsiveness under stress.
Trend Three: Formulation Alignment and Application-Specific Differentiation
Because dermatological and gastrointestinal applications dominate usage, the most relevant commercial opportunities will continue to cluster around formulation alignment and practical usability. Topical and oral products represent the largest share of activity, while compounding-oriented powder remains a narrower but meaningful niche. Suppliers that understand how their API behaves in downstream formulation contexts, and that can support customers with relevant documentation, handling guidance, and format consistency, may strengthen their commercial position beyond what volume competition alone allows.
This trend opens the door to more application-aware engagement. Rather than selling Nystatin API purely as an ingredient, successful players may increasingly frame their offering around formulation compatibility, batch consistency, and customer-specific supply needs. That shift does not require dramatic product innovation; it requires a sharper understanding of how purchasing and formulation teams evaluate risk and usability in day-to-day operations.
Strategic Implications for Different Decision-Makers
For manufacturers and suppliers, the most important move is to treat quality and documentation as core competitive assets rather than administrative overhead. Reducing process variability, maintaining certification currency, and building a credible narrative around supply reliability can improve both buyer confidence and margin resilience. Where capacity expansion is considered, it should be tied to demonstrable quality capability and clear sourcing differentiation, not solely to cost leadership.
For investors and strategic backers, the market offers a relatively stable but selective opportunity. Growth is present, but value creation depends on competitive position, compliance maturity, and supply continuity rather than on broad category expansion. Due diligence should focus on process control, certification status, raw material exposure, and the supplier’s ability to serve procurement needs across regulated markets. In this segment, durable advantage is more likely to arise from operational credibility than from speculative volume plays.
For procurement and sourcing teams, the practical task is to balance cost with qualification burden and continuity risk. Diversifying among competent suppliers, evaluating total cost of ownership, and not over-relying on the lowest-unit-price option can reduce exposure to quality or availability disruptions. In markets where documentation and process consistency determine how quickly a supplier can be onboarded and retained, procurement strategy should make those factors part of the evaluation framework from the outset.
The broader strategic implication is that the Nystatin API market is not primarily a story of explosive scale. It is a story of maturing competition, where disciplined manufacturing, regulatory readiness, and supply dependability determine who retains commercial leverage over time. The market rewards participants who can reduce friction for buyers while preserving operational control over quality and availability.
For organizations seeking a more granular view of regional dynamics, format-level demand shifts, procurement behavior patterns, and supplier-level benchmarking, a fuller commercial intelligence package can help translate these high-level trends into sourcing decisions, investment theses, and operational planning. Detailed segmentation-level data and tailored scenario analysis can sharpen the picture considerably, especially when the objective is to move from general market awareness to concrete purchasing, production, or entry decisions.
For detailed analysis of this topic, please visit the official page: Nystatin API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
HNB Heater Market: 8% CAGR Trajectory and Asia Pacific's 47% Value Share
By pmarketresearch, 2026-09-18
HNB Heater Market: Navigating Strategic Shifts and Commercial Opportunities in a Growing Landscape
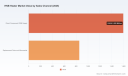
The Heat-Not-Burn (HNB) heater market has evolved from a niche alternative to a substantial commercial category, driven by shifting consumer preferences, technological maturation, and regulatory accommodations in key regions. Tracking the market from 2020 through the current cycle reveals a consistent upward trajectory, with revenue expanding from approximately $1.65 billion in 2020 to roughly $2.45 billion in 2025. Forward projections indicate growth accelerating through the end of the decade, with annual revenue expected to approach $4.2 billion by 2032. This expansion reflects a compound annual growth rate of approximately 8.0 percent, signaling sustained momentum rather than a temporary adoption spike.
The scale and pace of this growth are notable, but the market's structure matters just as much as its size. Concentration remains relatively high, with the top three players capturing roughly 65 percent of revenue and the top five accounting for nearly 79 percent. This concentration suggests that scale advantages, brand equity, and control over heating technologies and consumable ecosystems continue to dominate competitive dynamics. At the same time, the presence of specialized electronics manufacturers and component suppliers indicates a layered value chain where differentiation occurs not only at the device level but also in heating element design, thermal management, and manufacturing precision.
Despite the positive trajectory, the industry faces several structural challenges that will shape strategy over the next few years. First, regulatory frameworks remain uneven across jurisdictions. In some markets, HNB devices operate within established harm-reduction or tobacco-product guidelines that permit commercialization but impose compliance costs, labeling requirements, and marketing constraints. In other regions, uncertainty around classification and taxation creates planning complexity for manufacturers and distributors alike. Second, supply chain friction persists. While raw material constraints for electronic components have stabilized relative to peak disruption periods, elevated input costs and intermittent shortages still affect production scheduling and unit economics. Roughly one in ten U.S. plants continues to report capacity impediments tied to component availability, a reminder that manufacturing resilience remains a live operational concern. Third, the market is navigating a cost environment shaped by trade policy. Import tariffs on certain components increase supply chain expenses and put pressure on both manufacturing margins and retail pricing strategies, forcing companies to balance affordability with profitability.
For decision-makers, the core implication is that growth alone does not guarantee commercial success. The winners in this market are increasingly defined by how effectively they manage regulatory navigation, supply chain continuity, and technology differentiation simultaneously. Companies that treat these as separate functions risk losing ground to competitors who integrate compliance, sourcing, and product design into a coherent strategy.
Key Drivers Shaping Market Direction
Several interdependent forces are propelling the HNB heater market forward. Understanding these drivers is essential for anticipating where value will accumulate and which business models are most likely to scale.
Technology Innovation and Thermal Precision
Heating technology remains the central competitive axis. Three broad approaches dominate the landscape: ceramic heating elements, induction heating modules, and resistance metal film heaters. Ceramic systems continue to command significant share because they offer reliable temperature control, consistent heating patterns, and a familiar form factor for consumers transitioning from combustion products. Induction modules, however, represent one of the most consequential technological shifts in the category. By eliminating direct contact between the heating source and the consumable, induction systems reduce residue buildup, simplify maintenance, and improve session consistency. This architecture also creates opportunities for faster heat-up times and more precise thermal profiling, which matters to users who value repeatability and convenience.
Recent product activity underscores the strategic importance of heating architecture. In March 2024, a major tobacco company commercialized an induction-based model in Japan, signaling a deliberate move toward contact-free heating in a mature market. That launch reflects a broader industry pattern: leading manufacturers are investing in next-generation heating methods that differentiate the user experience while also supporting manufacturing efficiency and consumable compatibility. For B2B participants, this trend creates demand for precision components, thermal management solutions, and assembly capabilities that can meet tighter tolerances and higher throughput requirements.
Policy and Regulatory Dynamics
Policy frameworks are reshaping where and how HNB products can be commercialized. In the European Union, the Tobacco Products Directive provides a regulatory structure that accommodates HNB devices as harm-reduction-oriented products in compliant markets, while still imposing requirements that affect product design, packaging, and market access. This framework allows commercialization but does not eliminate compliance complexity. Companies must align device specifications, consumable formats, and communication strategies with local rules, which often vary not only by country but also by channel and audience.
In the United States, the regulatory and trade environment introduces a different set of considerations. Import tariffs on certain components raise the cost of assembled heaters and sub-assemblies, affecting both production planning and end-price positioning. This dynamic is particularly relevant for markets that rely on cross-border component flows or finished-device imports. At the same time, the U.S. rollout of new HNB devices in select cities demonstrates that companies are willing to invest in phased market entries, using localized activation events, trial programs, and consumer education to build awareness in a controlled manner. The combination of regulatory structure and trade costs means that market entry strategy is increasingly a function of supply chain geography, compliance readiness, and localized consumer engagement rather than product availability alone.
Demand-Side Shifts and Consumer Behavior
Consumer preferences are evolving as the category matures. Early adoption was heavily influenced by curiosity and the appeal of an alternative to combustion, but current demand is increasingly shaped by experience quality, session consistency, device ergonomics, and the practicalities of maintenance. Users are comparing heating performance, residue management, battery behavior, and the convenience of consumable formats. This shift favors products that deliver predictable performance and simple operation, and it puts pressure on manufacturers to reduce variability across production batches.
At the same time, the demand base is broadening beyond early adopters. Adult smokers evaluating alternatives are looking for demonstrable differences in experience, while existing users are increasingly attentive to device durability and consumable availability. For commercial stakeholders, this means that product reliability and consumable ecosystem strength are becoming as important as initial feature differentiation. In aftermarked-driven segments, replacement parts and ongoing support also matter, because repeat usage depends on the availability of compatible components and the perceived longevity of the device.
Supply Chain and Cost Structure Evolution
The cost structure of HNB heaters is influenced by component sourcing, assembly complexity, and trade conditions. Electronics manufacturing services providers play a significant role in this ecosystem, supplying heaters, precision components, and assembled devices to larger brand owners. This services model allows brand owners to scale production without building all manufacturing capacity internally, but it also dependencies on supplier capacity, quality control, and geographic distribution. Where tariffs or logistics constraints raise costs, manufacturers must decide whether to absorb those costs, adjust pricing, or reconfigure sourcing strategies.
Material availability has improved compared with earlier disruption periods, but the baseline is still higher than pre-2020 norms. Component shortages have stabilized, yet some facilities continue to report impediments that affect scheduling and output. For companies operating in this environment, resilience is not solely a procurement issue; it is a product strategy issue. Designs that reduce dependency on constrained components, dual-sourcing arrangements, and manufacturing footprints that balance cost with continuity are increasingly relevant. The practical takeaway is that cost optimization can no longer be pursued in isolation from risk management.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of large international tobacco companies, electronics manufacturing services providers, and specialized component and device manufacturers. This mix creates a multi-layered market in which competitive advantage can arise from brand strength, heating technology, manufacturing scale, or component specialization.
Strategic Positioning Among Leading Companies
Among the most prominent players, Philip Morris International has built a strong position around its IQOS heated tobacco system, using blade and induction heating technologies alongside a compatible consumable ecosystem. Its recent U.S. activity illustrates a deliberate, phased approach: a commercial launch in Austin with a device priced at $60, supported by guided trials and community-based demonstrations, followed by a broader rollout strategy that emphasizes consumer exposure and repeat trial. This combination of product introduction and localized engagement suggests a focus on converting interest into habitual use through direct experience rather than broad advertising alone. The earlier introduction of an induction-based model in Japan further reflects a technology-forward posture aimed at strengthening performance perception and long-term category relevance.
Worldwide In-Line Heaters Market
British American Tobacco competes with its Glo series, emphasizing heating performance that aligns with consumer preferences. Its positioning highlights the importance of perceived experience quality in a category where users compare session consistency, taste delivery, and convenience. Japan Tobacco International markets Ploom devices and newer EVO and AURA systems, building on a portfolio that spans multiple device generations and consumable formats. Imperial Brands offers Pulze heating devices with compatible sticks, with an emphasis on compact design and session capacity, showing that form factor and usability remain meaningful differentiators.
Beyond the brand-owning companies, the supply side includes electronics manufacturing services firms such as Venture Corporation and Flex, both of which provide HNB heater components and device manufacturing support to major tobacco brands. Their presence indicates that scale manufacturing, precision assembly, and supply reliability are valuable capabilities in their own right. Chinese manufacturers and component specialists, including Shenzhen Buddy Technology, TaoTao Technology, Dongguan Guoyan Electric Heating Materials, and Shenzhen Huachengda Precision Industry, add further depth to the value chain by focusing on heating devices, electronic components, heating materials, and precision assemblies. This ecosystem suggests that the market is not only competitive at the consumer-facing level but also highly contested in the component and manufacturing segment, where differentiation comes from material quality, process control, and the ability to meet evolving device specifications.
Heat Cost Allocator Market
How the Landscape Is Evolving
The market is showing signs of both consolidation and differentiation. Concentration among leading brand owners reflects the advantages of ecosystem control, established distribution, and sustained investment in product iterations. At the same time, the breadth of component and manufacturing suppliers indicates that specialization remains viable, particularly for firms that can serve multiple brand owners or provide advanced heating materials and precision parts. New entrants and expanding manufacturers are likely to continue exploring niches where thermal performance, cost efficiency, or supply flexibility offer a clear advantage.
One noticeable trend is the alignment of device architecture with long-term consumable strategy. Companies are increasingly treating heating technology not just as a product feature but as a structural decision that affects consumable compatibility, maintenance requirements, and manufacturing complexity. That alignment can create stronger customer retention where the experience is consistent, but it also raises the stakes for initial product execution. In parallel, the growing role of contract manufacturing and component suppliers means that competitive advantage increasingly depends on partnerships and process excellence as much as on branded product design.
PW Consulting Health Care Research Center
For businesses observing this landscape, the key question is not simply who leads today, but which capabilities will matter most as the category matures. Brand recognition remains powerful, but thermal engineering, supply reliability, regulatory readiness, and consumer trial conversion are becoming equally important determinants of long-term positioning.
Forward Outlook: Trends and Commercial Implications
Looking ahead over the next three to five years, several trends are likely to shape how value is created and captured in the HNB heater market.
One important trend is the continued refinement of heating architecture, with induction and advanced ceramic systems competing on performance, consistency, and manufacturability. As designs mature, the competitive edge will shift from introducing novel heating methods to optimizing them for reliability, cost, and consumable compatibility. Companies that can deliver stable thermal performance at scale while reducing maintenance friction will be well positioned to retain users and support repeat consumable purchases.
A second trend is the increasing importance of localized market strategy. Regulatory variation, trade costs, and consumer education requirements make broad, uniform launches less effective than targeted introductions supported by trials, demonstrations, and channel-specific engagement. This pattern favors organizations that can coordinate product availability, compliance, and consumer activation in a coordinated way, rather than treating each function separately. It also favors supply chains that can adapt to regional cost structures and component availability.
A third trend is the growing relevance of the component and manufacturing layer. As brand owners scale device volumes and introduce new heating formats, demand for precision components, heating materials, and electronics assembly is likely to remain strong. Suppliers that can provide consistent quality, flexible capacity, and material expertise will find continued opportunity, especially if they can support multiple clients or rapidly adapt to new device requirements. This creates a parallel opportunity set for B2B players who are not necessarily consumer-facing but are essential to device production and performance.
These trends connect directly to commercial opportunities. For device makers, the opportunity lies in pairing technology differentiation with execution discipline, ensuring that product advantages are reproducible across production and supported by a dependable consumable supply. For component and manufacturing suppliers, the opportunity lies in becoming trusted partners for brands that need thermal precision, quality consistency, and supply resilience. For investors, the opportunity is to distinguish between market-level growth and company-level execution, since the category's expansion does not automatically translate into uniform returns across all participants.
Potential risks and uncertainties should also be factored into planning. Regulatory changes could alter market access or compliance costs in important regions. Trade policy shifts may continue to affect component pricing and sourcing strategies. Supply chain disruption, while less severe than in earlier periods, can still affect production cadence and cost stability. In addition, consumer acceptance may evolve as alternative products emerge and as users become more discriminating about performance and convenience. These uncertainties do not negate the growth outlook, but they do mean that strategy must be flexible enough to respond to changing conditions in policy, cost, and consumer behavior.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product design with both consumer experience and supply chain realities. That means evaluating heating technology choices not only for performance but also for manufacturability, component dependency, and consumable compatibility. Building tolerance for supply variability through design flexibility, dual sourcing, or regional manufacturing options can help protect output and margin when input conditions shift. Equally important is consistency: producing devices that deliver repeatable heating performance reduces user dissatisfaction and supports long-term adoption.
For investors, the more useful question is not whether the category will grow, but which participants are best equipped to convert growth into durable advantage. Factors worth weighing include technology positioning, concentration of revenue across products and regions, exposure to trade and component cost pressures, and the strength of the consumable ecosystem. Companies that rely on a single product format or a narrow supply base may face more volatility than those with broader manufacturing relationships and multiple heating approaches. Evaluating these operational and strategic details is often more revealing than headline revenue projections alone.
For procurement and supply chain leaders, the focus should be on resilience and quality rather than price alone. Given that component availability has stabilized but remains above pre-2020 baselines, and that tariffs can affect landed costs, sourcing strategies should account for continuity, lead-time reliability, and specification precision. Partnerships with manufacturers and component suppliers that understand HNB heating requirements can reduce the risk of performance variation and production delays. In practice, this means treating supplier selection as a strategic decision that affects product reliability and market readiness, not just a transactional cost exercise.
For organizations seeking a more detailed view of segmentation, regional dynamics, technology splits, channel structures, and company-level positioning, deeper commercial intelligence can help translate these broad trends into specific plans. A comprehensive research report can provide the granular data needed to compare sub-segments, assess competitive exposure, and identify where to commit resources with greater confidence. The strategic direction is clear enough to act on, but the specifics matter when turning insight into investment, sourcing, or product decisions.
For detailed analysis of this topic, please visit the official page: HNB Heater Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the ESD Grounding Mats Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Overview and Core Challenges
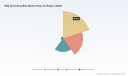
The global market for electrostatic discharge (ESD) grounding mats has reached a critical inflection point, driven by converging forces of electronics proliferation, regulatory tightening, and manufacturing modernization. Over the past five years, revenue expansion has been steady rather than explosive, reflecting the specialized nature of the product category and its deep integration into critical production environments. From a 2020 baseline, the market has grown through incremental capacity additions, material science improvements, and widening compliance requirements across high-value assembly sectors. Current projections indicate a compound annual growth rate of approximately 6.25 percent through the end of the decade, positioning the segment among the more resilient categories within the broader static control and cleanroom consumables ecosystem.
This growth trajectory is not uniform. Value creation is increasingly concentrated around product reliability, certification rigor, and lifecycle service models rather than raw volume. The industry is navigating a transitional phase where legacy procurement cycles collide with newer compliance expectations, material cost volatility, and substrate performance standardization. For decision-makers, the headline growth figure masks several structural shifts that will shape competitive positioning and purchasing economics over the next several years.
PW Consulting Health Care Research Center
One defining challenge is the tension between performance consistency and cost pressure. ESD grounding mats are precision-engineered consumables whose dissipation characteristics, tear resistance, chemical tolerance, and grounding integrity directly affect yield in sensitive assembly environments. Manufacturers and end-users face the dual burden of sourcing materials that meet established resistance thresholds while managing budget constraints. As raw material pricing fluctuates—most notably in natural rubber benchmarks and synthetic rubber indices—the margin between premium performance and acceptable compliance becomes a strategic negotiation rather than a fixed specification. Operators must determine whether to standardize across lower-cost homogeneous designs or invest in multi-layer architectures that offer improved durability and ergonomic properties at a higher acquisition cost.
Another structural challenge lies in certification complexity and verification cadence. The acceptance of ESD matting into qualified production environments increasingly depends on documented conformance, traceable testing records, and routine verification protocols. Organizations operating under strict electrostatic protected area (EPA) frameworks are expected to maintain meticulous records of mat performance, grounding continuity, and periodic inspection schedules. This has transformed what was once a transactional equipment purchase into a compliance-driven operational requirement. Procurement teams that treat matting as a commodity often encounter hidden costs related to rework, documentation, training, and downstream audit risk. The distinction between a product that simply claims compliance and one that supports repeatable verification workflows is now a meaningful competitive differentiator.
A third challenge is the fragmentation of application-specific requirements. ESD grounding mats are no longer evaluated solely by resistance values. Electronic assembly floors, precision laboratory environments, medical instrumentation suites, and aerospace integration sites each impose distinct demands for chemical resistance, surface topology, anti-fatigue properties, and physical wear cycles. Suppliers that attempt to serve all applications with a single product architecture struggle to maintain relevance as end-users increasingly match substrate design to operational context. The market is therefore bifurcating between generalized compliant products and engineered solutions calibrated for specific handling conditions, operator fatigue considerations, and cleaning regimes.
Worldwide ESD Packing Market
Taken together, these dynamics suggest that the market's next phase of expansion will reward operators who can align material performance, verification support, and application-specific engineering with procurement practicality. Growth will remain robust, but competitive advantage will shift toward reliability documentation, lifecycle economics, and the ability to translate compliance language into operational outcomes.
Key Growth Drivers Reshaping the Market
Three to four underlying forces are propelling the ESD grounding mats market forward, and their interaction defines where value will compound most quickly over the coming years. These drivers are not isolated; each one amplifies the strategic relevance of the others.
Material and Manufacturing Innovation
Advancements in substrate engineering have become one of the most practical catalysts for market evolution. The category now spans homogeneous vinyl constructions, reinforced rubber architectures, and layered designs engineered for durability, chemical resilience, and ergonomic comfort. Multi-layer rubber constructions contribute to longer service life under heavy operator traffic while supporting controlled dissipation within required thresholds. At the same dependent point, material cost volatility keeps pressure on pricing strategies. Recent benchmarks in natural rubber and synthetic rubber indices illustrate that input cost movements can influence both supplier margin and buyer willingness to adopt higher-performance formats. Companies that can decouple performance from cost sensitivity—through optimized layer structures, improved wear resistance, or longer replacement cycles—gain a structural advantage in procurement-heavy environments.
Regulatory and Standards Alignment
Regulatory expectations continue to elevate the technical baseline for ESD matting. Frameworks such as ANSI/ESD S20.20 and IEC 61340 remain the dominant reference points for controlled dissipation, with resistance-to-ground boundaries guiding worksurface and flooring eligibility. More significantly, verification expectations have moved from periodic certification toward daily or routine checks for footwear and mat grounding continuity within EPA environments. This does not simply raise the technical bar; it reshapes purchasing logic. Buyers increasingly favor products that simplify compliance documentation, support traceable testing, and integrate into inspection workflows. Recent product certifications emphasizing individual testing, serialization, and alignment with updated standards illustrate how manufacturers are turning compliance into a commercial asset. As semiconductor and electronics manufacturing capacity expands, the demand for matting that satisfies updated IEC and ANSI frameworks becomes a direct operational requirement rather than a best-practice preference.
Demand-Side Shifts in Electronics and Advanced Manufacturing
Demand growth is increasingly shaped by sector-specific production expansion rather than generic industrial consumption. Electronics manufacturing remains the dominant application driver, reflecting the sensitivity of assembly processes to static discharge and the scale at which modern production lines operate. Aerospace and defense applications contribute meaningfully as well, particularly where precision integration, rigorous inspection cultures, and controlled work environments are standard. Healthcare and laboratory settings add further demand for ESD-safe surfaces, especially where sensitive instrumentation, diagnostic equipment, and clean handling protocols intersect. The commercial implication is clear: matting demand is tied to capital expansion in high-value manufacturing and to compliance-sensitive handling in regulated environments. As new fab capacity, aerospace programs, and laboratory infrastructure come online, ESD grounding mats move from optional safeguarding to integral production support.
Supply Chain and Procurement Model Evolution
Procurement behavior is shifting from single-transaction buying to lifecycle management. Operators are becoming more attentive to replacement frequency, inspection support, chemical and heat resistance, and the operational cost of downtime or rework triggered by premature mat failure. Simultaneously, suppliers are responding with more prescriptive selection guidance, testing references, and application-specific recommendation frameworks. Updated selection guides tested against recognized standards reflect an industry-wide move toward helping buyers navigate compatibility rather than simply supplying a catalog SKU. This evolution benefits suppliers that can provide clear technical justification, consistent quality, and documentation support, while exposing those that compete purely on price without maintaining compliance or service infrastructure.
These overlapping drivers create a market where technical credibility, standards alignment, and procurement practicality collectively determine share gain.
Competitive Landscape and Leading Strategies
The competitive field in ESD grounding mats is defined by a mix of specialized manufacturers, diversified safety-product groups, and larger industrial suppliers with broader static-control portfolios. Market concentration remains moderate rather than highly consolidated, which gives room for differentiated positioning and application-specific wins. Several companies have built recognizable identities by emphasizing certification rigor, product architecture, and ergonomic or chemical-resistance features.
Anti-static Floor Market
Desco Industries has maintained a strong profile through a focused offering of ESD worksurface mats, floor mats, and grounding solutions that align with ANSI/ESD expectations across vinyl and rubber dissipative formats. Its positioning leans on protocol familiarity, broad worksurface support, and established integration within electronics handling environments. ACL Staticide differentiates with dual-layer and homogeneous options that emphasize chemical and heat resistance, making its matting particularly relevant where exposure to cleaning agents or elevated surface stress is common. Botron's emphasis on multi-layer rubber table mats, including proprietary three-layer designs, targets durability and ergonomic function, appealing to environments where operator comfort and product service life carry direct financial weight. NoTrax, operating within a broader safety group, addresses industrial and electronics workplaces through anti-fatigue and anti-static mat series that combine static control with workplace ergonomics. 3M contributes through a portfolio approach that places ESD grounding mats within a wider static-control and worksurface protection ecosystem, enabling potential cross-selling and integrated environmental planning.
Recent industry actions clarify how competition is intensifying on compliance and guidance rather than on price alone. One manufacturer introduced an ESD bench mat kit built around individual testing, serialization, and certification to current standards, signaling a move toward traceable, verifiable compliance as a value proposition. Another supplier released an updated comparison and selection guide oriented around testing against IEC standards for electronics manufacturing, reflecting a strategic bet that helping buyers navigate compatibility will strengthen loyalty and reduce purchase friction. A technical organization also published guidance on testing frequency and alignment with major ESD frameworks, reinforcing the expectation that routine verification is now part of acceptable operational practice. Together, these developments indicate that the market is rewarding suppliers who support documentation, inspection discipline, and application-matched selection.
The competitive landscape is likely to continue evolving along two parallel tracks. On one side, consolidation may increase as larger industrial safety and static-control players absorb niche capabilities or distribution reach, particularly where complementary product lines can be bundled. On the other side, specialization will remain powerful because application requirements differ too widely for a single product to dominate all use cases. New entrants that focus on verification enablement, material durability, or codified selection support can establish meaningful positions without needing broad portfolios, provided they can demonstrate repeatable performance under recognized standards. For buyers and investors, the practical implication is that the most defensible advantages are emerging around compliance support, material performance predictability, and the ability to reduce hidden operational risk.
Future Trends and Commercial Implications (2026–2032)
Looking ahead three to five years, several trends are likely to shape both demand composition and supplier viability. The first is a continued premiumization of compliance-oriented products. As verification expectations become more operationally embedded, suppliers that offer serialized testing records, clear certification alignment, and straightforward inspection workflows will capture a disproportionate share of regulated environments. This trend expands commercial opportunities for products that make audit readiness easier, but it also raises the bar for market entry because documentation capability becomes as important as material performance.
The second trend is application-specific product design gaining share over generic compliance matting. Environments that combine static control with chemical exposure, ergonomic fatigue concerns, or heavy traffic will increasingly favor engineered substrates over basic dissipative surfaces. This shift creates opportunities for differentiated architectures—such as multi-layer rubber formats or chemically resistant homogeneous designs—but also introduces complexity for buyers who must match specifications to real operating conditions rather than to a one-size-fits-all product line.
The third trend is cost and input volatility becoming a more visible strategic variable. Rubber pricing movements and synthetic material indices can compress margins or shift buyer sensitivity toward lower-cost alternatives at exactly the moments when compliance demands are rising. Suppliers that can manage material exposure, extend service life, or demonstrate lower total cost of ownership through reduced replacement frequency will be better positioned to retain share during pricing cycles. The associated risk is that price competition could intensify in commoditized segments, especially if procurement teams face budget pressure while still needing to meet minimum compliance thresholds.
These trends point to a market where growth remains attractive, but value will accrue to operators who can translate technical credibility into procurement efficiency, compliance simplicity, and application-fit reliability.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority should be to strengthen verifiable performance claims and make compliance support part of the product story rather than an afterthought. Serialization, traceable testing, and selection guidance aligned with recognized standards are no longer optional differentiators in regulated environments. Suppliers should also evaluate whether their product architecture supports distinct application profiles so that buyers can justify performance features in procurement language that connects to yield, durability, and audit readiness.
For investors, the most resilient exposure will likely come from companies that combine material durability with compliance enablement and have clear positioning in electronics manufacturing, aerospace, or laboratory workflows. Market growth is stable, but the winners will be those that can defend share through documentation support and application-fit engineering rather than through price alone. Evaluating exposure to raw material volatility and the ability to extend replacement cycles should be part of any investment screening in this segment.
For procurement leaders and operations managers, the practical move is to shift from purchasing a compliant item to managing a verified ESD control point. That means specifying products with clear resistance alignment, planning for routine verification, and reconciling acquisition cost against replacement frequency, chemical exposure, and operator fatigue. Selecting matting based on documented inspection support and application compatibility often reduces downstream risk more effectively than selecting based on unit price alone. More detailed segmentation, scenario-based pricing implications, and supplier-level comparison data can help refine these choices; for deeper analysis, the full PW Consulting research report provides expanded breakdowns and customized decision support.
For detailed analysis of this topic, please visit the official page: ESD Grounding Mats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Ice Cubers Market Hits $3.85B in 2025, Projects 6.5% CAGR Through 2032
By pmarketresearch, 2026-09-17
Navigating the Frozen Horizon: Strategic Insights into the Global Ice Cubers Market (2026-2032)
In the modern commercial landscape, ice is no longer merely a commodity; it is a critical component of operational efficiency, customer satisfaction, and regulatory compliance. From high-volume foodservice establishments to precision-driven healthcare facilities, the reliability of ice production systems directly impacts the bottom line. As we move further into 2026, understanding the trajectory of the Ice Cubers Market is essential for stakeholders looking to capitalize on emerging opportunities or mitigate supply chain risks. This article serves as a strategic preamble to our comprehensive market research report, offering a high-level view of the market architecture while reserving the granular intelligence for our full analysis.
Our latest study, Ice Cubers Market Forecast 2026-2032 , leverages historical data from 2020 through 2025 to construct a robust model for the coming seven years. The narrative is one of steady expansion, driven by evolving consumption patterns, technological advancements in refrigeration, and shifts in global manufacturing capacities. For enterprise leaders, the question is no longer whether the market is growing, but where to position assets and partnerships to best ride this wave.
Macro Growth Trajectory and Market Valuation
The historical performance of the ice cuber sector indicates a resilient demand curve. Drawing from our base year analysis in 2025, the global market has demonstrated consistent upward momentum over the past half-decade. The overall market size has traversed from a baseline of approximately 2,550 million USD in 2020 to an estimated 3,850 million USD in 2025. This growth underscores the integral role of commercial ice systems in daily operations across multiple sectors.
Looking forward, the forecast period from 2026 to 2032 projects a continued compound annual growth rate (CAGR) of 6.5 percent. This trajectory suggests that by the end of the forecast window, the market value will approach nearly 6,000 million USD. Such expansion is not uniform; it is punctuated by specific inflection points related to raw material availability, regulatory shifts, and regional economic health.
Key macroeconomic indicators included in our full report highlight the following progression:
- 2026 Valuation: The market is positioned to open the forecast period at over 4,100 million USD, reflecting immediate post-2025 momentum.
- Mid-Decade Outlook: By 2029, valuations are expected to surpass the 5,000 million USD threshold, signaling a mature growth phase.
- Terminal Year 2032: The market is projected to reach approximately 5,982 million USD, reinforcing the long-term viability of ice equipment investments.
These figures represent the aggregate revenue landscape in USD millions. However, understanding the drivers behind these numbers requires a deeper dive into segmentation and regional dynamics, which our full report dissects in detail.
Strategic Segmentation: Product and Application Dynamics
The Ice Cubers Market is not a monolith. It is defined by distinct product technologies and application verticals that respond differently to economic pressures. Our research categorizes the market into key product types, including Cube Ice Machines, Flake Ice Machines, Nugget Ice Machines, and Scale Ice Machines. While cube ice remains a dominant force due to its versatility in foodservice and retail, the demand for specialized ice forms is influencing manufacturing priorities.
On the application front, the sector is diversified across Foodservice, Healthcare, Retail, and Industrial uses. Foodservice continues to be a primary consumption driver, given the reliance on ice for beverages and preservation. However, the healthcare segment represents a critical niche where hygiene and reliability are non-negotiable. Retail and industrial applications further broaden the demand base, creating a buffer against sector-specific downturns.
Our full segmentation analysis explores the revenue contribution of each category without exposing the precise percentage splits publicly. This approach allows us to discuss the weight of each segment strategically. For instance, the interplay between high-volume cube ice production and the growing preference for gourmet clear cubes in premium hospitality settings is a key narrative thread. Similarly, the industrial demand for heavy-duty ice systems influences the type of equipment manufacturers prioritize in their R&D pipelines.
Global Regional Landscape
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities shaped by local infrastructure, climate conditions, and economic development levels.
North America remains a cornerstone of the market, supported by a mature foodservice industry and high standards for commercial equipment. Europe contributes significantly through stringent regulatory environments that drive innovation in energy efficiency. Asia Pacific represents a dynamic growth engine, where expanding hospitality sectors and urbanization are accelerating adoption rates. Latin America and the Middle East and Africa, while smaller in aggregate volume, offer strategic entry points for manufacturers targeting emerging markets.
Our report provides a nuanced view of these regional contributions. Rather than simple rankings, we analyze the velocity of growth in each territory. This helps investors and operational leaders decide where to allocate inventory or establish distribution networks. The detailed regional revenue data, however, is reserved for the full intelligence package to maintain competitive advantage for our clients.
Competitive Landscape and Industry Leadership
The market structure is characterized by a mix of established multinational manufacturers and specialized regional players. Our analysis identifies key companies that define the competitive boundaries. Leaders in this space include Hoshizaki Corporation (Japan), known for its global manufacturing footprint in Japan and the US; Manitowoc Ice (US), a major producer integrated into Pentair; and Scotsman Ice Systems (US), recognized for gourmet clear cube technologies.
Other significant entities shaping the market include Ice-O-Matic (US), Follett Ice (US), Brema Ice Makers (Italy), Cornelius Inc. (US), North Star Ice Equipment (US), and KOLD-DRAFT (US). Each brings distinct technological advantages, from horizontal evaporator technology to specialized dispensing systems. The competitive intensity is reflected in the market concentration metrics, where the top three players hold a notable share of the revenue, and the top five expand that influence further.
Ice Cubers Market
Recent developments indicate an active strategy of visibility and innovation among these players. Throughout 2025 and early 2026, major industry participants have leveraged trade shows to showcase next-generation solutions. For example, ICESTA exhibited ice making solutions at the Canton Fair in April 2026, while Naixer displayed commercial cube ice machines at the NRA Show in Chicago in March 2026. Additionally, Icematic participated in SIGEP World in early 2025 to highlight cube machine capabilities. These exhibitions are not merely promotional; they signal where R&D investments are being directed, particularly in response to changing customer expectations and operational constraints.
Critical Market Dynamics: Materials, Regulation, and Efficiency
Beyond the financials and the players, the underlying dynamics of the Ice Cubers Market are shifting. Three primary forces are currently reshaping the operational environment for manufacturers and buyers alike: raw material costs, regulatory compliance, and energy efficiency mandates.
Ice Maker Market
Raw Material Volatility
Stainless steel remains the primary material for ice cuber construction, chosen for its corrosion resistance and adherence to hygiene standards. However, cost structures are sensitive to commodity price fluctuations. Sector analysis from March 2026 indicated that prices for relevant stainless steel grades showed declines of up to 16 percent in early 2026 across Asia and Europe. While this offers potential margin relief for manufacturers, it introduces volatility into procurement planning. Furthermore, benchmarks such as steel rebar traded around 3,174 CNY/T as of May 20, 2026, with modest monthly increases. Volatility tied to nickel and chromium for stainless variants used in equipment remains a risk factor that requires active supply chain management.
Regulatory Compliance
Commercial ice machines must comply with NSF/ANSI standards for food equipment safety and sanitation. These regulations drive the use of high-grade stainless steel and efficient designs, effectively setting a barrier to entry for lower-quality producers. Compliance is not static; it evolves with health standards, forcing continuous design iterations. Manufacturers who fail to align with these standards risk market exclusion, making regulatory intelligence a critical component of strategic planning.
Energy Efficiency and Refrigerants
Macro trends are increasingly dictating product design. Energy efficiency mandates and R290 refrigerant compliance are influencing new ice cuber model designs to reduce operational costs in hospitality and foodservice. As energy costs rise and sustainability goals become central to corporate strategy, the total cost of ownership (TCO) for ice machines is gaining prominence over initial purchase price. Models that minimize energy consumption while maintaining production capacity are becoming the preferred choice for facility managers.
The Strategic Value of Comprehensive Intelligence
While the overview provided here outlines the structural health and directional trends of the Ice Cubers Market, effective decision-making requires granular data. Enterprise leaders need to know more than just the aggregate growth rate; they need to understand the specific revenue splits across regions to optimize distribution, the precise segmentation shares to tailor product portfolios, and the detailed competitive moves to anticipate market shifts.
Our full market research report delivers this depth. It provides a detailed breakdown of historical and forecast data, allowing for precise scenario planning. It dissects the segmentation splits by region, product type, and application, giving you the clarity to identify high-growth niches. It also includes comprehensive profiles of key companies, analyzing their headquarters, operational focus, and recent strategic developments.
Furthermore, the report contextualizes raw material trends and regulatory shifts within the broader market dynamics, offering actionable recommendations for procurement and product development. Whether you are a manufacturer looking to optimize production capacity, a distributor seeking high-potential regions, or an investor evaluating market entry points, the full intelligence suite is designed to reduce uncertainty and enhance strategic agility.
Conclusion
The Ice Cubers Market is on a stable growth path, underpinned by essential demand across foodservice, healthcare, retail, and industrial sectors. The projected CAGR of 6.5 percent through 2032 indicates a healthy environment for investment and innovation. However, success in this environment depends on navigating the complexities of material costs, regulatory compliance, and competitive differentiation.
This article has provided the strategic framework necessary to understand the market's trajectory. To unlock the specific data points, regional revenue figures, and detailed competitive analysis required to execute your strategy, we invite you to access the full Ice Cubers Market Forecast 2026-2032 report. Equip your organization with the precise intelligence needed to thrive in the frozen horizon of the coming decade.
For detailed analysis of this topic, please visit the official page: Ice Cubers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vet Speculum Market Hits $185M in 2025, Projected 5.2% CAGR Through 2032
By pmarketresearch, 2026-09-17
Navigating the Next Horizon: Strategic Insights into the Veterinary Speculums Market Through 2032
The global veterinary healthcare industry is undergoing a structural transformation driven by rising pet ownership, expanding large animal husbandry practices, and an increasing emphasis on procedural precision. Within this ecosystem, the veterinary speculums market represents a critical yet often under-analyzed segment of surgical and diagnostic instrumentation. For executives, procurement leaders, and clinical product strategists, understanding the trajectory of this market is not merely an academic exercise—it is a prerequisite for capital allocation, supply chain resilience, and competitive positioning.
Our latest market research publication delivers a comprehensive, data-backed examination of this sector, tracing historical performance from 2020 through 2025 and projecting forward across a forecast window extending to 2032. Anchored in a base year of 2025 and denominated in USD millions, the analysis quantifies a market that has demonstrated resilient expansion. Total market revenue grew from 145.0 million in 2020 to 185.0 million in 2025, reflecting sustained demand across both companion animal and production animal segments. The forecast period projects continued momentum, with valuations advancing to 194.16 million in 2026 and reaching 263.8 million by 2032. This trajectory translates to a compound annual growth rate of 5.2 percent, a figure that underscores moderate but predictable upside for stakeholders who can align product portfolios and distribution strategies with emerging clinical workflows.
What separates this study from generic industry summaries is its deliberate focus on operational decision-making. Rather than presenting abstract growth narratives, the report dissects the mechanical, regulatory, and competitive forces that will dictate margin profiles, fulfillment costs, and market access between now and the end of the decade. The following sections outline the analytical architecture of the research and explain why it should be treated as a foundational input for 2026 planning cycles.
Report Architecture: Operational Intelligence for Cross-Functional Teams
The publication is structured to serve multiple internal audiences simultaneously. Clinical product managers, supply chain directors, finance leads, and regional sales heads will each find modules tailored to their decision responsibilities. The core of the report is built around a multi-dimensional segmentation framework that isolates structural demand drivers without obscuring the practical considerations that influence purchasing behavior.
Readers will encounter a detailed examination of product typologies that dominate veterinary diagnostic and surgical procedures. The analysis covers oral speculums, vaginal speculums, and ear speculums paired with otoscope systems, each evaluated through the lens of clinical utility, sterilization compatibility, and practitioner adoption patterns. Rather than merely cataloging product categories, the report connects design variations to real-world usage scenarios. For instance, the prevalence of three-blade Polansky configurations with butterfly screw mechanisms for large animal work, alongside set-screw Killian designs optimized for canine vaginal examinations, is contextualized within the broader demand for durable, sterilizable instrumentation. This product-level granularity enables manufacturers and distributors to identify where specification standardization can reduce inventory complexity and where customization remains a pricing advantage.
The application dimension of the study maps demand across small animal practice and large animal and equine practice. This split is particularly important because procurement cycles, clinician preferences, and facility sterilization capabilities differ materially between these environments. By analyzing how usage intensity, procedure frequency, and replacement cycles vary by practice type, the report equips commercial teams with the insight needed to tailor bundling strategies, reorder scheduling, and field education programs.
Regional coverage is likewise presented through a demand-weighted lens. The research evaluates North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa as distinct operational theaters, each with its own mix of veterinary infrastructure maturity, import dependency, and domestic manufacturing capability. The report does not stop at mapping where demand is concentrated; it investigates the logistical and regulatory friction points that influence time-to-market for imported instruments, the sensitivity of pricing to freight and duty fluctuations, and the extent to which local reprocessing standards shape material selection.
Beyond segmentation, the study incorporates a deep dive into competitive positioning, recent product developments, and the broader industrial context that shapes manufacturing economics. This holistic design ensures that the report can function as both a strategic briefing document for executive committees and a tactical reference for business unit planning.
Competitive Landscape: Concentration, Differentiation, and Strategic Arbitrage
One of the most decision-relevant sections of the research examines the structure of the competitive field. The market is characterized by a moderately fragmented but increasingly disciplined supplier base. Industry concentration metrics indicate that the top three firms command approximately 28.5 percent of total revenue, while the top five account for 35.2 percent. This level of concentration suggests that scale advantages exist, but there is still meaningful room for specialized manufacturers to compete on design fidelity, material quality, and application-specific engineering.
The report profiles the organizations that currently anchor the supply landscape, drawing on product portfolios, geographic footprints, and stated clinical focus areas. GerVetUSA Inc. stands out for its emphasis on German-forged surgical instruments, including vaginal and nasal speculum variants designed for both small and large animals. Jalal Surgical has positioned itself as a manufacturer and supplier of high-quality vaginal speculums built from premium materials intended for repeated veterinary use. Sklar Surgical Instruments contributes to the competitive mix with surgical-grade designs, including Graves and Pederson vaginal speculums adapted for veterinary applications. Jorgensen Laboratories, operating under the JorVet brand, offers specialized instruments such as the Killian K-9 Vaginal Speculum and Polansky Vaginal Speculum, targeting dogs and large animals with configuration-specific engineering. Welch Allyn, now part of Hillrom, provides reusable veterinary specula compatible with otoscopes for ear examinations, including bivalve designs and multiple size options. Surgical Holdings, based in the United Kingdom, focuses on stainless steel obstetrical and vaginal speculums intended for large animal veterinary use. Medline Industries rounds out the profiled set with supplies such as SofSpec reusable veterinary specula and other diagnostic speculums supporting a range of veterinary procedures.
Rather than presenting these companies as static company profiles, the report evaluates them through a strategic lens. It assesses where overlapping product lines create price compression, where differentiated material choices or blade configurations create defensible value, and where distribution partnerships can accelerate adoption in underpenetrated practice types. The analysis also considers the implications of competitive density for private-label and co-branding opportunities, especially in regions where procurement teams prioritize cost predictability without sacrificing sterilizability or mechanical reliability.
Recent innovation activity reinforces the importance of this competitive review. In December 2024, a development effort led by Nail Tekin Önder and colleagues produced and evaluated a novel Onder Speculum designed to improve visualization and retraction of the cervix in small ruminants during transcervical procedures. Documented in the Kafkas University Veterinary Faculty Journal, this work illustrates how targeted procedural challenges can generate new instrumentation concepts with potential downstream commercialization pathways. For incumbent suppliers, such developments signal the need to monitor academic and clinical innovation pipelines, not only to identify potential acquisition or licensing targets, but also to anticipate shifts in procedural standards that may alter demand for conventional configurations.
Market Dynamics and Material Realities: The Forces Shaping Margin and Adoption
Any credible market strategy must account for the underlying industrial and regulatory conditions that determine what can be manufactured, how it can be sterilized, and how it is positioned relative to human-use equivalents. The report integrates these forces explicitly so that readers can distinguish temporary pricing fluctuations from structural cost drivers.
Material composition is a foundational consideration. Veterinary speculums are primarily manufactured from surgical-grade stainless steel chosen for corrosion resistance and compatibility with frequent autoclave sterilization. This material baseline influences not only unit economics but also supplier qualification requirements, reprocessing infrastructure expectations, and lifecycle durability claims. The study examines how variations in steel grade, surface finishing, and mechanical tolerances interact with sterilization cycles to affect total cost of ownership for veterinary practices and, by extension, how suppliers can justify premium positioning when they deliver verifiable durability and consistent tangential performance across repeated reprocessing events.
Regulatory context adds another layer of strategic nuance. Animal-use devices such as veterinary speculums are generally not subject to FDA premarket notification requirements, including the 510(k) pathway, in the same manner as human-use equivalents. This regulatory distinction lowers certain barriers to market entry and can accelerate the commercialization of new designs, but it does not remove scrutiny around quality systems, labeling, and post-market expectations. The report explains how this dynamic shapes competitive speed-to-market on one hand and clinical confidence requirements on the other, and why companies that invest early in robust manufacturing documentation and consistent quality control often gain an advantage in procurement evaluations even when formal device regulation is less prescriptive than in human healthcare.
Product design conventions further influence purchasing decisions. Standard configurations such as Polansky speculums with three blades and butterfly screws for large animals, and Killian speculums with set screws for canine vaginal examinations, are not merely catalog details; they reflect established clinician ergonomics and procedural workflows. The research shows how entrenched design familiarity can slow adoption of alternative geometries unless the replacement clearly improves visualization, reduces tissue trauma, or simplifies handling. For suppliers, this highlights the importance of field education, demonstration programs, and specification sheets that align new designs with existing procedural mental models rather than attempting to displace them without clear clinical justification.
Together, these dynamics create a market environment where growth is neither purely volume-driven nor purely price-driven. Instead, it is shaped by the interaction of material durability, sterilization compatibility, procedural specificity, and procurement behavior across different practice types. Companies that understand these interacting variables are better positioned to set realistic pricing strategies, optimize production planning, and avoid investment in features that add manufacturing cost without translating into procurement preference.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle is likely to be defined by procurement recalibration, product portfolio prioritization, and regional expansion decisions. In that environment, decision-makers need more than headline growth figures; they need an integrated view of how demand is distributed, how competitive intensity will affect margin retention, and where product innovation can create durable differentiation.
Veterinary Speculums Market
This study is designed to support those decisions in several concrete ways. First, it provides a consistent historical and forecast baseline that allows finance and operations teams to model revenue scenarios against a 5.2 percent compound annual growth trajectory without relying on anecdotal estimates. Second, it breaks down the market along typological, application, and regional dimensions so that commercial leaders can identify where to concentrate sales effort, where to streamline SKU counts, and where localized manufacturing or distribution partnerships may reduce exposure to freight volatility and import friction. Third, it frames the competitive field in terms of concentration, specialization, and recent innovation signals, enabling strategy teams to assess where head-to-head competition is most likely to compress pricing and where niche engineering or procedural focus can preserve value.
Equally important, the report translates industrial realities into commercial implications. By addressing the role of surgical-grade stainless steel, autoclave compatibility, design conventions such as Polansky and Killian configurations, and the regulatory distinction between animal-use devices and human-use equivalents, it helps product and quality leaders anticipate the operational prerequisites for scale-up, supplier qualification, and market entry. This level of detail is intended to reduce the gap between strategic ambition and execution risk.
For executives evaluating expansion into new practice types or geographies, the research also clarifies where demand is deepening versus where it is merely price-sensitive. Understanding this distinction is essential for deciding whether to compete on throughput and cost efficiency or to invest in clinical value propositions that justify premium positioning. The study does not offer generic advice; it provides a structured foundation for making that choice with greater confidence.
Looking Ahead: Positioning for Sustained, Predictable Growth
The veterinary speculums market is not characterized by sudden disruptive swings, but it is increasingly shaped by procedural refinement, material expectations, and competitive maturation. The forecast window to 2032 suggests a market that will continue to expand in a measured way, with total revenue advancing from approximately 194 million in 2026 toward the mid-260 million range by the end of the decade. Translating that trajectory into a viable corporate strategy requires more than awareness of the growth rate. It requires a working knowledge of the segmentation logic, competitive archetypes, material constraints, and procedural preferences that will determine which companies capture disproportionate value along the way.
Our full report extends far beyond the high-level framework summarized here. It contains the detailed segmentation analysis, competitive profiling, regional demand context, and operational implications that procurement, product, and strategy teams need to build defensible plans for 2026 and beyond. Readers seeking the complete dataset, deeper competitive evaluations, and the full set of market dynamics discussed in this introduction are encouraged to access the source publication for the full intelligence package. In a market where margin protection and product relevance depend on precise market understanding, that deeper view is not a luxury; it is a strategic necessity.
Worldwide Veterinary Endoscopes Market
For detailed analysis of this topic, please visit the official page: Veterinary Speculums Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Composite Acrylic Solid Surface Market Hits $3.25B in 2025, 6.18% CAGR to 2032
By pmarketresearch, 2026-09-17
Navigating the Composite Acrylic Solid Surface Market: A Strategic Outlook for 2026 and Beyond
The built environment stands at a critical inflection point. As architects, designers, and procurement leaders navigate post-pandemic workspace redesigns, sustainability mandates, and shifting consumer aesthetics, material selection has become a decisive lever for operational and brand strategy. Composite acrylic solid surfaces have rapidly evolved from niche interior finishes to mainstream architectural solutions, driven by their seamless fabrication, hygiene advantages, and design flexibility. Yet behind this visible growth lies a complex matrix of raw material volatility, regional demand asymmetry, and intensifying competitive positioning. This is precisely where structured, forward-looking market intelligence becomes indispensable.
Our latest research on the Composite Acrylic Solid Surface Market delivers a comprehensive, data-grounded assessment designed specifically for executive decision-making through 2026 and beyond. Drawing on historical performance from 2020 through 2025 and extending our forecasts through 2032, the study maps the trajectory of a sector that has demonstrated resilient expansion, with a projected compound annual growth rate of 6.18 percent. The market, valued in the billions of USD, has consistently moved from a baseline of approximately 2.4 billion USD in 2020 to an estimated 3.25 billion USD by 2025. More importantly, the forecast horizon reveals an accelerating value pathway, with revenue projections climbing toward nearly 5 billion USD by the end of the decade. These figures are not abstract statistics; they represent the scale of capital allocation, capacity planning, and regional investment required to capture share in a maturing but still expanding landscape.
Why 2026 Is a Defining Year for Strategic Positioning
The 2026 outlook is shaped by converging forces that will separate reactive market participants from proactive strategic leaders. First, the end of the historical review period places 2025 as the foundational baseline, meaning any forward-looking capacity expansion, product portfolio adjustment, or channel strategy must be calibrated against a market that has already absorbed several years of steady demand absorption. Second, raw material economics are introducing new cost structures that demand agile procurement and formulation strategies. The primary feedstock for acrylic resin, methyl methacrylate, continues to reflect regional pricing divergence and petrochemical cycle sensitivity. Observations from mid-2026 indicate notable price differentials across key producing regions, underscoring how feedstock volatility directly influences manufacturing margins and pricing architecture. Companies that treat raw material dynamics as a strategic variable rather than a passive cost will be better positioned to protect profitability while maintaining competitive price points.
Third, environmental and regulatory pressures are reshaping product development roadmaps. Sustainability is no longer a marketing overlay; it is becoming embedded in procurement criteria, certification requirements, and end-user expectations. Regulatory focus on volatile organic compound emissions and the broader push toward circular material flows are accelerating adoption of recycled content formulations and low-impact production processes. Organizations that integrate sustainable design and transparent environmental reporting into their product positioning will find themselves aligned with emerging compliance demands and premium segment preferences. Fourth, the competitive field is consolidating around differentiated value propositions. With market concentration reflecting a moderately fragmented landscape, where the top three players account for roughly a third of total revenue and the top five approach half, scale advantages coexist with clear opportunities for specialized innovation. Companies that cannot articulate a distinct material, aesthetic, or service advantage risk being squeezed between global incumbents and agile regional producers.
What This Research Delivers: An Executive-Level Intelligence Framework
This study is engineered to translate market complexity into actionable decision support. Rather than stopping at high-level sizing, the report unpacks the structural drivers, constraints, and competitive mechanics that will define growth through the end of the forecast period. The analytical framework is organized to provide immediate relevance for strategy, operations, and commercial teams:
- Comprehensive market sizing that tracks historical revenue evolution from 2020 through 2025 and extends a rigorous forecast to 2032, enabling scenario planning for capacity investment, revenue targets, and product mix optimization.
- Granular segmentation analysis covering material composition types, application verticals, and regional demand footprints, giving leaders visibility into where value is concentrated and where growth pockets are emerging.
- Competitive landscape profiling that examines the strategic positioning, product portfolios, and geographic footprints of leading manufacturers, including how incumbent players and emerging exporters are differentiating through color systems, fabrication compatibility, and sustainability credentials.
- Raw material and cost structure assessment that connects feedstock pricing behavior, petrochemical linkage, and regional supply dynamics to manufacturing economics, supporting more resilient sourcing and pricing strategies.
- Regulatory and sustainability trend mapping that identifies the compliance themes, certification expectations, and formulation shifts influencing product development and market access.
- Recent industry developments that illustrate how leading players are translating market signals into product launches, design collections, and application-specific positioning, with particular attention to how aesthetic innovation is being leveraged for commercial sector adoption.
Each section is designed to stand alone as a decision-ready reference while contributing to a cohesive narrative about where the market is heading and how organizations can align their portfolios, channels, and cost structures to capture disproportionate value.
Competitive Dynamics: Scale, Innovation, and Regional Rebalancing
The competitive architecture of the composite acrylic solid surface market is defined by a blend of established global brands, technology-forward Korean producers, and increasingly capable export-oriented manufacturers. At the center of the landscape sits DuPont Corian Design, whose longstanding leadership in 100 percent acrylic and composite acrylic solid surfaces continues to shape benchmark expectations for seamless, non-porous, and repairable surfaces across countertops, sinks, and commercial installations. The company's recent product activity reflects a deliberate emphasis on commercial-sector aesthetics, with new color collections inspired by natural travertine and layered patterns aimed at expanding design versatility in high-visibility installations.
Alongside this incumbent presence, LG Hausys, through its HI-MACS brand, has built a strong reputation for high-quality acrylic-based sheets, extensive color libraries, and a growing focus on sustainability features. Samsung Staron complements this Korean manufacturing strength by offering acrylic and composite options known for balancing quality and affordability across countertops and surface applications. These Korean producers have been instrumental in broadening design variety and reinforcing the material's appeal in both residential and commercial contexts. In the North American market, Formica Group and Wilsonart continue to advance acrylic-based solid surface solutions that emphasize fabrication-friendly formats, durability, and non-porous performance for wet walls, countertops, and commercial environments. Trinseo, through its AVONITE offering, further diversifies the supply base by emphasizing design features and application breadth in acrylic solid surfaces.
A notable structural trend is the rising influence of Asian export-oriented manufacturers. Hanex, under Hanwha L&C, supplies acrylic and modified composite variants with a clear focus on innovation and global market reach. KingKonree has carved a position in modified acrylic solid surface sheets and finished products such as countertops and basins, targeting international export channels. LUXUStone similarly operates multiple production lines to serve global demand for both pure acrylic and composite acrylic solid surfaces. This broadening of supply sources is reshaping price competition, shortening lead times in certain regions, and intensifying the need for differentiation based on quality consistency, color stability, post-sale support, and sustainability credentials. The presence of multiple capable producers means that competitive advantage will increasingly derive from portfolio strategy, application specialization, and the ability to align material properties with specific project requirements rather than from generic product availability alone.
Raw Material Realities and Supply-Side Sensitivity
Any credible market strategy must account for the cost architecture beneath the finished product. The production of acrylic resin for composite acrylic solid surfaces is fundamentally linked to methyl methacrylate, a feedstock whose supply and pricing behavior reflects broader petrochemical cycles and regional production dynamics. Price observations from mid-2026 highlight the sensitivity of manufacturing economics to regional feedstock costs, with notable differentials between major producing markets. Because acrylic resin production depends on precursors such as acetone and propylene, the material cost base remains exposed to commodity volatility, logistical factors, and regional supply constraints. For commercial leaders, this means that procurement resilience, formulation efficiency, and regional sourcing flexibility are not operational niceties but strategic imperatives. Companies that build scenario-aware sourcing models and maintain a clear view of feedstock-to-finished-product cost pass-through dynamics will be better equipped to manage margin pressure in fluctuating markets.
Composite Acrylic Solid Surface Market
Sustainability, Regulation, and the Shift Toward Circular Formulations
Regulatory and sustainability trends are steadily redefining the competitive baseline. Environmental requirements centered on VOC emissions, indoor air quality, and lifecycle impacts are influencing both production methods and specification decisions. Parallel to regulatory pressure, end-users and architects are increasingly scrutinizing material transparency, recycled content integration, and manufacturing footprint. This environment is encouraging the adoption of recycled content formulations and more sustainable process designs, as reflected in the sustainability reporting and environmental product documentation pursued by leading manufacturers. In practice, sustainability is becoming a dual-purpose lever: it mitigates compliance risk while opening doors to premium projects and institutional specifications that prioritize environmental performance alongside aesthetic and functional requirements. Organizations that proactively align product development with these expectations will strengthen their positioning in specification-driven markets and reduce exposure to future regulatory tightening.
Strategic Priorities for 2026 Decision-Makers
Translating these dynamics into action requires a clear set of strategic priorities. First, leaders should treat the forecast horizon as a planning scaffold rather than a static prediction, using the 2026 to 2032 pathway to test capacity decisions, market entry assumptions, and product mix investments against multiple growth scenarios. Second, competitive positioning should be sharpened around durable differentiation: color and aesthetic innovation, fabrication compatibility, hygiene and maintenance performance, and verifiable sustainability attributes all offer credible points of contrast in a crowded field. Third, procurement and cost strategy must incorporate feedstock sensitivity and regional pricing divergence, enabling more informed sourcing decisions and more stable margin profiles. Fourth, commercial teams should align application-focused messaging with the segments where value is strongest, using evidence-based insights to guide sales narratives, specification support, and channel development. Fifth, sustainability should be embedded as a core product and compliance strategy, ensuring that environmental performance is visible, credible, and integrated into the value proposition rather than treated as an afterthought.
Acrylic Solid Surface Market
Closing Perspective: From Market Awareness to Strategic Advantage
The composite acrylic solid surface market is entering a phase where growth is still substantial, but the rewards are increasingly concentrated for organizations that combine analytical rigor with operational discipline. Historical expansion from 2020 through 2025 demonstrates a market that has matured without losing momentum, while the forecast period signals continued value creation driven by design evolution, application broadening, and regional demand rebalancing. Yet the same environment that offers opportunity also raises the stakes: feedstock volatility, sustainability expectations, and a diversifying competitive base mean that generic positioning will not be enough. The leaders of 2026 will be those who interpret market signals early, convert insights into portfolio and cost decisions, and communicate a clear, credible value proposition to architects, fabricators, and end-users.
Full access to the detailed segmentation data, regional demand estimates, application breakdowns, and company-level strategic profiles is essential for organizations that need to move from directional awareness to precise execution. The complete report provides the depth required to calibrate investment thresholds, benchmark competitive exposure, and build procurement and product strategies with confidence. We invite strategy, commercial, and operations leaders to explore the full study and leverage its structured intelligence to shape decisions that will define performance through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Composite Acrylic Solid Surface Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ocular Inflammation Market to Hit $17.87 Billion by 2032 at 6.5% CAGR
By pmarketresearch, 2026-09-17
Strategic Foresight in Ocular Inflammation Treatment: Navigating the 2026 Market Landscape
As we enter 2026, the global landscape for treating ocular inflammation stands at a critical inflection point. Driven by an aging population, increased prevalence of chronic eye conditions, and a evolving therapeutic pipeline, stakeholders across the pharmaceutical and medical device value chain must recalibrate their strategies. The recently published Ocular Inflammation Treatment Market research report serves as an indispensable compass for navigating this complex terrain. This analysis is not merely a collection of statistics; it is a strategic asset designed to inform capital allocation, product development, and competitive positioning for the remainder of the decade.
Understanding the magnitude of this opportunity requires a clear view of the historical trajectory and future projections. Over the past five years, the market has demonstrated resilience and steady growth, overcoming supply chain disruptions and evolving regulatory frameworks. From a base valuation in the early 2020s, the sector has expanded robustly, reaching an estimated 11,500 million USD in 2025. Looking ahead, the momentum is expected to sustain itself, with projections indicating a climb toward 17,870.86 million USD by 2032. This growth trajectory is underpinned by a compound annual growth rate that signals healthy expansion, suggesting that demand for ocular anti-inflammatory therapies will continue to outpace many traditional pharmaceutical segments. For executives and investors, these figures represent more than top-line revenue; they indicate the overall health of the sector and the viability of long-term investments in ophthalmic innovation.
Defining the Scope of Opportunity
To fully leverage this market intelligence, one must understand the depth of the data covered in the comprehensive study. The report dissects the industry through multiple lenses, ensuring that no strategic blind spots remain. It provides a granular look at the forces shaping the industry, moving beyond high-level estimates to offer actionable intelligence.
The core of the analysis rests on several pivotal pillars:
- Historical and Forecast Data: The study offers a detailed retrospective from 2020 to 2025, establishing a robust baseline, alongside a forward-looking forecast period extending through 2032. This dual perspective allows companies to benchmark past performance against future expectations.
- Segmentation Analysis: The market is broken down by drug class, indication, and region. This allows stakeholders to identify high-growth pockets within the broader ecosystem. Whether the interest lies in corticosteroids, NSAIDs, immunomodulators, or anti-infectives, the data isolates performance drivers for each category.
- Competitive Benchmarking: Profiles of key industry players are included, offering insights into their product portfolios, geographic footprints, and strategic moves. This section is crucial for understanding relative market strength and potential partnership opportunities.
- Regulatory and Reimbursement Dynamics: Given the highly regulated nature of ophthalmic products, the report integrates critical information regarding FDA approvals, patent protections, and reimbursement pathways such as J-codes for intravitreal implants.
Regulatory Catalysts and Innovation Trends
The environment for ocular inflammation treatment is being reshaped by recent regulatory milestones and technological advancements. For strategic planners, staying ahead of these curves is essential to maintaining competitiveness. The report captures these dynamics in real-time, ensuring that decision-makers are not operating on outdated assumptions.
Recent FDA Approvals and Clinical Clearances
In mid-2025, the regulatory landscape saw significant activity. Amneal Pharmaceuticals secured FDA approval for generic prednisolone acetate ophthalmic suspension 1%, with a launch planned for the third quarter of 2025. This move increases accessibility for steroid-responsive ocular inflammation treatments, potentially shifting pricing dynamics and market share among generic manufacturers. Simultaneously, Alcon achieved FDA approval for TRYPTYR (acoltremon ophthalmic solution) for signs and symptoms of dry eye disease, a condition intimately linked with ocular surface inflammation. These approvals highlight a trend toward both cost-effective generics and novel mechanisms of action.
Looking toward early 2026, the pipeline shows promise for steroid-sparing options. Novaliq received FDA IND clearance for NOV05 (tacrolimus ophthalmic solution) for a Phase 2 trial in non-infectious anterior uveitis. This development is particularly noteworthy for strategists monitoring the shift away from long-term steroid use due to side effect profiles. Such innovations suggest a diversifying treatment arsenal that could disrupt incumbent franchises relying heavily on traditional corticosteroids.
Supply Chain and Intellectual Property Considerations
Beyond approvals, operational realities play a significant role in market dynamics. Tariffs on imported pharmaceutical ingredients remain a concern, potentially increasing production costs for treatments reliant on global supply chains. Consequently, pricing strategies and margin management require careful scrutiny. Furthermore, intellectual property continues to be a moat for sustained-release technologies. Multiple patents protect formulations such as DEXTENZA and YUTIQ, securing revenue streams for innovators while setting barriers for entrants. Understanding the patent cliff scenarios and the protection lifecycle of these devices is vital for risk assessment.
Competitive Landscape and Strategic Positioning
The market concentration indicates a moderately consolidated environment where strategic partnerships and portfolio diversification are key. The top three companies hold a significant portion of the market share, while the top five control more than half of the total revenue. This structure suggests that while there is room for niche players, scale and broad product portfolios offer distinct advantages.
Several key corporations define the current competitive arena. AbbVie Inc., based in North Chicago, remains a powerhouse with offerings like prednisolone acetate (Pred Forte) for steroid-responsive conditions. Their established presence underscores the enduring importance of classic corticosteroids. In the realm of sustained-release implants, Alimera Sciences and EyePoint Pharmaceuticals, Inc. are critical players. Alimera markets ILUVIEN (fluocinolone acetonide intravitreal implant) for diabetic macular edema and related conditions, while EyePoint commercializes YUTIQ for chronic non-infectious uveitis and DEXYCU for postoperative inflammation. These intravitreal implants represent a high-value segment where reimbursement pathways including J-codes have been established, stabilizing revenue models for these therapies.
Worldwide Conjunctivitis Ophthalmic Drugs Market
Bausch Health Companies Inc. continues to market a range of ophthalmic steroids, including Lotemax, catering to inflammation and pain management. Novartis AG supplies anti-inflammatory products through its broader ophthalmology portfolio, leveraging global scale. In the generic space, Amneal Pharmaceuticals is expanding its footprint, challenging branded formulations on price. Pfizer Inc. provides various corticosteroid and NSAID formulations, while Santen Pharmaceutical Co., Ltd. maintains a strong global focus on ophthalmic therapeutics from its base in Osaka. Ocular Therapeutix, Inc. offers DEXTENZA, a dexamethasone ophthalmic insert for postoperative inflammation and allergic conjunctivitis itching, showcasing innovation in delivery mechanisms.
Ocular Inflammation Treatment Market
Segmentation Insights for Targeted Strategy
Strategic success in this market requires understanding where the value is created. The report provides segmentation data that allows companies to tailor their approaches. By drug class, the market is diversified. Corticosteroids continue to hold substantial ground, reflecting their status as a standard of care. However, immunomodulators and NSAIDs also command significant market presence, indicating a balanced therapeutic mix. Anti-infectives represent another crucial segment, particularly for inflammation with an infectious etiology. Companies must decide whether to compete on volume in mature classes or innovate in expanding categories.
By indication, the demand drivers are varied. Dry Eye Syndrome represents a large portion of the market, driven by high prevalence and ongoing innovation in managing ocular surface disease. Allergic Conjunctivitis remains a consistent driver, often seasonal but broadly impactful. Uveitis, while less prevalent, represents a high-value specialty segment where advanced therapies and implants are often required. Post-operative inflammation is another critical area, directly linked to the volume of ophthalmic surgeries performed globally. Understanding the specific growth rates and revenue contributions of each indication helps companies prioritize R&D and marketing resources effectively.
Regionally, the market exhibits distinct characteristics. North America continues to be a dominant force, reflecting high healthcare spending and adoption rates. Europe remains a substantial market with its own regulatory nuances. The Asia Pacific region represents a high-growth opportunity, driven by improving access and increasing awareness. Latin America and the Middle East and Africa offer emerging potential, though they come with unique reimbursement and access challenges. A one-size-fits-all strategy is rarely effective; regional customization is key to capturing value across these geographies.
Why This Research Matters for 2026 Decisions
As the market moves through the forecast period, the cost of uncertainty is high. Misjudging the impact of a new generic entrant, misinterpreting regulatory signals, or overlooking a shift in reimbursement policy can lead to significant strategic errors. This report mitigates those risks by providing a consolidated view of the forces at play.
For business development teams, the competitive profiles and recent developments sections offer leads for potential collaborations or acquisition targets. For marketing leaders, the segmentation data informs messaging and territory planning. For C-suite executives, the macro trends and financial projections support budgeting and long-term visioning. The inclusion of supply chain risks and patent landscapes adds a layer of operational realism that is often missing from broader industry overviews.
The data suggests that the path to 2032 is not linear. While the overall trajectory is positive, there will be fluctuations based on drug launches, patent expirations, and regulatory changes. Companies that possess granular intelligence will be better positioned to pivot when necessary. For instance, the rise of steroid-sparing therapies could alter the demand curve for traditional corticosteroids over the next few years. Similarly, changes in reimbursement codes for intravitreal implants could impact the economics of sustained-release products.
Accessing the Full Intelligence
This overview provides a glimpse into the depth and breadth of the analysis available. However, the true value lies in the detailed data tables, comprehensive company profiles, and scenario-based forecasts that form the core of the full report. The macro figures and trends mentioned here are derived from a sophisticated modeling process that accounts for multiple variables influencing the market.
To make fully informed decisions, stakeholders need access to the complete dataset. This includes specific revenue breakdowns by segment, detailed historical comparisons, and the nuanced analysis of competitive moves that cannot be fully captured in a summary. The interplay between drug classes, indications, and regions creates a complex matrix where specific insights can reveal hidden opportunities or threats.
Investing in this knowledge asset is an investment in strategic clarity. As the ocular inflammation treatment market continues to evolve through 2026 and beyond, those equipped with the most accurate and comprehensive data will lead the sector. We invite you to explore the full report to gain the detailed intelligence necessary to navigate this dynamic market with confidence. The complete analysis offers the granularity required to transform high-level trends into actionable business strategies.
For detailed analysis of this topic, please visit the official page: Ocular Inflammation Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trigger Point Injection Market to Reach $320.2M by 2032, CAGR 5.85%
By pmarketresearch, 2026-09-17
Beyond the Pain Point: Strategic Intelligence for the Trigger Point Injection Treatment Market in 2026 and Beyond
The global landscape for pain management is undergoing a structural shift, driven by an aging population, the rising prevalence of musculoskeletal disorders, and a persistent move toward minimally invasive therapeutic interventions. Within this broader ecosystem, the trigger point injection treatment market stands out as a critical segment for investors, service providers, and pharmaceutical manufacturers seeking sustainable growth in the chronic pain sector. At PW Consulting, we have just published a comprehensive market research study designed to cut through the noise of general industry forecasts and deliver actionable intelligence for the 2026 decision-making cycle.
This study is not merely a collection of historical data points. It is a strategic roadmap built to help organizations anticipate the regulatory, clinical, and competitive shifts that will define the market through the end of the decade. As healthcare systems increasingly prioritize cost-effective outpatient solutions, understanding the precise trajectory of trigger point injections is essential for allocating capital, refining service portfolios, and securing competitive advantage.
Market Trajectory and Growth Dynamics
Our analysis captures a market that has demonstrated consistent resilience and expansion over the past half-decade. Tracking revenue figures from 2020 through the base year of 2025, the data reveals a steady upward climb from approximately 165.2 million USD to a projected 215.0 million USD in the current year. This historical performance sets a robust foundation for the forecast period extending from 2026 to 2032.
Looking ahead, we project the market to reach a valuation of 320.2 million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.85 percent. For strategic planners, this figure represents more than aggregate expansion; it signals a maturing market where volume increases are complemented by evolving clinical standards and reimbursement scrutiny. The transition from 2025 to 2026 alone marks a notable inflection point, with revenue expected to jump to 233.37 million USD, reflecting pent-up demand and the gradual normalization of procedural volumes post-pandemic.
It is crucial for stakeholders to recognize that this growth is not uniform across all vectors. The total market size is the sum of distinct drivers involving specific agent types, clinical indications, and geographic regions. While our full report deconstructs these segments in granular detail, the aggregate trend confirms that demand is being fueled by a combination of established clinical protocols and emerging procedural training initiatives. Organizations that understand how these specific vectors interact will be best positioned to capture value.
Competitive Landscape and Key Participants
The competitive environment in the trigger point injection space is characterized by a mix of specialized pain management clinics, multidisciplinary health groups, and medical device manufacturers. Our report profiles key players who are actively shaping the market through service delivery, equipment supply, and clinical standardization.
On the service delivery side, organizations such as Paragon Health Group, Encore Health Group, Premier Pain & Spine, Synergy Health Partners, and the Cleveland Clinic are central to the ecosystem. These entities provide trigger point injections as part of broader pain management services, often focusing on myofascial pain relief, symptomatic pain relief in musculoskeletal conditions, or comprehensive non-surgical pain management. Their operational models and patient volumes contribute significantly to the market's service-based revenue streams.
Complementing these service providers is a critical component of the supply chain represented by manufacturers like B. Braun Melsungen AG. Companies in this tier supply the essential needles and injection equipment, such as ultrasound-guided systems, that enable precise and effective procedures. The interplay between procedural providers and equipment suppliers creates a dynamic where innovation in delivery tools often precedes or enables wider adoption of specific injection techniques.
Trigger Point Injection Treatment Market
Market concentration analysis indicates a fragmented yet structured competitive field. The top three companies hold a combined market share of 22.5 percent, while the top five account for 31.8 percent. This concentration level suggests that while no single entity dominates the entire spectrum, there is room for strategic consolidation or targeted market penetration by agile competitors. For new entrants or existing players looking to expand, identifying the gaps between these key players and leveraging specialized niches in agent delivery or regional service coverage is a viable path to growth.
Operational Opportunities and Service Expansion
For healthcare administrators and investors, the operational value of this market lies in its integration potential and the alignment with non-surgical care pathways. Trigger point injection procedures are frequently bundled with physical therapy, medication management, and patient education programs. Our research explores how service providers are maximizing revenue cycles by positioning these injections within comprehensive care plans.
Several strategic opportunities emerge from our analysis:
- Service Line Optimization: Clinics are refining their protocols to align with the most frequently treated indications, ensuring that patient flow and inventory management for injection agents are tightly synchronized with demand patterns.
- Provider Training and Credentialing: As procedural techniques evolve, there is a growing emphasis on formal training and certification for providers. Organizations that support or participate in accredited training programs can enhance their reputation, ensure compliance, and capture referrals from a broader network of referring physicians.
- Equipment and Supply Chain Alignment: Facilities performing high volumes of trigger point injections require reliable access to specialized needles and imaging guidance tools. Strategic partnerships with equipment suppliers or bulk procurement agreements can significantly impact cost structures and operational throughput.
- Post-Procedure Care Integration: Extending the value proposition beyond the injection itself by offering structured follow-up and rehabilitation services helps improve patient outcomes and enhances the overall attractiveness of the service to payers and referral sources.
Our full report provides detailed breakdowns of how these operational levers are being applied across different segments of the market, including specific insights into agent utilization patterns and indication-based service frequency.
Industry Dynamics: Regulatory, Reimbursement, and Clinical Guidelines
No strategic assessment of the trigger point injection market would be complete without a deep dive into the regulatory and reimbursement environment. Market participants must navigate a landscape defined by evolving coverage policies, clinical consensus statements, and procedural billing requirements. Our study maps out the critical developments that are directly influencing patient access and provider behavior.
A significant recent development is the publication of multi-society guidelines by the American Society of Regional Anesthesia and Pain Medicine (ASRA) in March 2025. These guidelines address the use of corticosteroids in trigger point injections for adult chronic pain interventions, with specific attention to dosing strategies. Notably, the guidance highlights that lower doses of corticosteroids may provide similar benefits to higher doses, a finding that has profound implications for inventory planning, cost management, and clinical protocol design. Following this, in May 2025, major payer Anthem updated its medical policy (CG-SURG-17) to reference these 2025 multi-society guidelines, signaling a swift alignment between clinical standards and coverage criteria.
Reimbursement dynamics also play a pivotal role in shaping market behavior. Trigger point injection procedures billed under CPT codes 20552 and 20553 are covered when criteria for myofascial pain are met, but there are strict limits on frequency and number of sessions. More specifically, Medicare Local Coverage Determinations (LCDs) limit trigger point injections to no more than three sessions per rolling 12 months for medically necessary myofascial pain treatment. These constraints force providers to optimize the timing and composition of their interventions, balancing clinical need with compliance requirements. The coding and billing landscape requires meticulous documentation and adherence to medical necessity standards, making operational excellence in revenue cycle management a key differentiator.
On the education and workforce front, the American Academy of Procedural Medicine (AAOPM) announced ongoing trigger point injection training courses and certification for providers as of March 2026. This institutional investment in provider competency is likely to drive broader adoption of standardized, high-quality procedures and may influence payer perceptions regarding the appropriateness and consistency of trigger point injection services.
These dynamics interact in complex ways. For example, the interplay between clinical guideline recommendations on dose reduction and reimbursement limits on session frequency requires providers to carefully sequence treatments and potentially explore alternative agent combinations. Our report dissects these interactions to provide a clear picture of how market participants can adapt their strategies to remain both clinically effective and financially viable.
Strategic Imperatives for 2026 Executives
As we move deeper into the forecast period, executives across the value chain must make decisions that align with the market's underlying structural trends. The 5.85 percent CAGR and the projected expansion to 320.2 million USD by 2032 present clear growth opportunities, but realizing these opportunities requires more than passive participation in a rising tide.
Worldwide Intra-Articular Injection Market
For pharmaceutical and device companies, the data underscores the need for targeted engagement with clinical guidelines and payer policies. Understanding how corticosteroid dosing recommendations and session limits affect product utilization can inform marketing strategies, clinical education programs, and inventory forecasting. For service providers, the competitive landscape analysis highlights the importance of differentiation. With a CR3 of 22.5 percent, the market supports multiple players, but success will depend on demonstrating superior outcomes, efficient workflows, and compliance with the latest policy and guideline frameworks.
Additionally, the growing emphasis on provider training and certification points to an emerging ecosystem where quality metrics and professional credentials may increasingly influence referral patterns and payer contracting. Organizations that invest early in staff development and align their protocols with the most current multi-society guidance will likely secure a more resilient position as the market matures.
Our full Trigger Point Injection Treatment Market research study goes much further than the summary presented here. It contains detailed breakdowns of regional revenue distributions, agent type adoption rates, and indication-specific demand patterns that are essential for precise market entry, partnership evaluation, or investment due diligence. The analysis includes comprehensive competitor profiles, an exhaustive review of regulatory and reimbursement updates, and a forward-looking assessment of how clinical guideline shifts will reshape operational economics over the next several years.
In a market where clinical nuance, policy compliance, and competitive positioning converge, generic data is insufficient. Decision-makers need a granular, verified, and strategically contextualized view of the trigger point injection landscape. The PW Consulting report is designed to deliver exactly that level of insight.
We invite you to access the complete report for a full exploration of the data, the competitive profiles, and the strategic recommendations tailored to your specific role in the market. The full intelligence necessary to navigate 2026 and the forecast period through 2032 awaits.
For detailed analysis of this topic, please visit the official page: Trigger Point Injection Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Whetstones Market to Expand at 4.25% CAGR, Reaching $198.73M by 2032
By pmarketresearch, 2026-09-16
The Whetstones Market in 2026: Strategic Intelligence for Precision and Edge Maintenance Industries
The global whetstones market is entering a phase of measured yet structurally significant expansion. As manufacturing floors, professional kitchens, and home hobbyists increasingly prioritize tool longevity and surface precision, sharpening stones have evolved from peripheral consumables into strategic SKUs that signal quality, consistency, and operational discipline. Our latest market research on the whetstones industry offers decision-makers a comprehensive, data-grounded map of where this category stands today and where it is headed through the end of the decade. Published with a 2025 base year and a forecast horizon extending to 2032, the study translates historical performance, material innovation, and competitive signaling into actionable intelligence for product strategy, sourcing, and market entry planning.
Why This Research Matters for 2026 Decision-Making
Strategic planning in 2026 requires more than top-line projections. Companies need to understand how demand is shifting across use cases, how material science is reshaping product performance expectations, and which competitive dynamics will determine pricing power and channel control in the years ahead. The whetstones market illustrates these pressures vividly. Historical data from 2020 through 2025 reveals a market that weathered volatility yet consistently rebounded toward growth, culminating in a global revenue base measured in the high hundred millions of U.S. dollars by 2025. Looking forward, our forecast models project a steady compound annual growth trajectory of 4.25 percent across the 2026 to 2032 window, with total market value climbing toward the vicinity of 200 million dollars by the close of the forecast period.
These figures are not merely descriptive. They serve as a strategic compass. A mid-single-digit CAGR in a mature, low-tech-adjacent category signals that growth will increasingly come from differentiation rather than broad category expansion. Manufacturers and distributors that rely on undifferentiated assortments will find themselves squeezed by margin pressure and channel consolidation. Conversely, organizations that align their portfolios with emerging performance standards, regional demand rhythms, and application-specific preferences will be positioned to capture share without relying on aggressive discounting. Our report is designed to help leadership teams make that distinction clear before capital is committed.
Equally important is what the research deliberately preserves for deeper analysis. While this overview communicates the trajectory and structural forces shaping the market, the full study reserves granular segmentation detail, regional volume and revenue distributions, and application-level breakdowns for readers who need to model entry strategies, allocation decisions, and competitive response scenarios. The intent is to provide enough rigor to establish credibility while ensuring that the most decision-critical intelligence remains within the complete report, accessible through our primary research portal.
Market Trajectory and Structural Signals
The historical record from 2020 to 2025 underscores a category that has matured without stagnating. Revenue moved from the 120 million-dollar range in 2020 into a tighter band through 2022 and 2023 before resuming a clearer upward path in 2024 and 2025. This pattern is consistent with a market absorbing supply-chain normalization, shifting procurement rhythms, and gradual demand recovery in both professional and consumer segments. The rebound in the most recent base-year figures reinforces the view that whetstones are no longer treated as discretionary gadgets but as maintenance essentials across multiple end-use environments.
Forward-looking, the forecast period from 2026 through 2032 projects incremental but durable expansion. The modeled trajectory points toward a total market value approaching roughly 199 million dollars by 2032, with year-over-year movement shaped by product innovation, application-driven demand, and regional purchasing patterns. Importantly, this expansion is not uniform across the board. Growth will be concentrated where performance benefits are most visible, where replacement cycles align with sharpening frequency, and where channel execution translates product quality into repeat purchases. Decision-makers should therefore interpret the headline CAGR as a directional anchor, not a guarantee of equal opportunity across all product types or customer groups.
A defining structural feature of this market is its moderate fragmentation. The top three competitors collectively hold approximately 21.4 percent of revenue, while the top five command around 29.8 percent. This concentration profile suggests a landscape where incumbents enjoy meaningful brand and supply advantages, yet there remains sufficient room for specialized players to win in niche applications or geographic pockets. For strategists, the implication is clear: competitive advantage in whetstones will increasingly depend on authenticity of material claims, consistency of sharpening performance, and the ability to serve distinct use cases rather than on scale alone.
What the Whetstones Market Report Covers
Our study is built around practical utility. It is intended to support product planners, category managers, sourcing leaders, and investor analysts who need a coherent narrative from raw material economics through end-user demand behavior. The report integrates the following functional layers:
- Historical performance data spanning 2020 to 2025, providing context for demand rhythm, recovery patterns, and base-year valuation.
- A forward forecast from 2026 to 2032 that models revenue progression, highlights inflection points, and clarifies the pace of category expansion.
- A structured segmentation framework that examines the market by region, material type, and application, with interpretive guidance on where demand intensity and product mix are likely to diverge.
- A competitive landscape assessment that maps key manufacturers, their positioning, and the strategic implications of concentration and differentiation.
- An industry dynamics section that addresses raw material availability, regulatory considerations, and emerging product-testing signals influencing buyer behavior.
- Recent market developments and evaluation activity that reflect how consumer media, professional reviewers, and end users are shaping perceived product leadership.
Readers should note that while the overview presented here describes the architecture of the study, the full report contains the detailed split data and interpretive matrices needed to build region-specific entry plans, allocate SKUs across channels, and benchmark product strategies against peers. The complete segmentation values, regional revenue contributions, and application-level breakdowns are reserved for the report itself to ensure that strategic decisions are made with the full evidentiary context.
Competitive Landscape: Established Players and Specialized Entrants
The whetstones competitive field is defined by a blend of broad-abrasive manufacturers, heritage natural-stone producers, and precision-oriented specialists. This mix shapes both pricing logic and brand perception. On one side are companies with extensive abrasives portfolios that treat whetstones as part of a broader industrial and consumer sharpening ecosystem. On the other are organizations whose identity is anchored in geological sourcing, craftsmanship, or performance engineering, often commanding loyalty through perceived authenticity and consistency.
Major manufacturers with synthetic and natural sharpening portfolios play a pivotal role in setting performance expectations across industrial, professional, and consumer channels. Their scale, distribution reach, and ability to supply multiple material formats allow them to compete on availability, technical support, and product range. Alongside them, natural-stone specialists rooted in specific geological deposits maintain a differentiated value proposition based on material origin, grade consistency, and domestic manufacturing credibility. In certain segments, the control of quarry access and reserve longevity functions as a strategic moat, reinforcing both supply security and narrative authority around traditional performance.
The Japanese manufacturing cohort deserves particular attention. Firms specializing in high-performance ceramic stones, water whetstones, and precision abrasives have influenced global sharpening standards by emphasizing fast cutting behavior, user-friendly maintenance characteristics, and repeatable grit performance. Their product architecture has raised the bar for what buyers expect from a sharpening stone, particularly in professional culinary and precision tool contexts. As a result, competitive positioning increasingly hinges on how well a product communicates edge refinement quality, ease of use, and reliability under repeated sharpening cycles.
Further down the field, regional suppliers and distributors of specialized stones contribute to the market's mosaic by serving jewelry making, tool making, and other precision applications. Their role is often less about headline volume and more about enabling high-value craftsmanship workflows where consistency and surface finish matter disproportionately. For strategists evaluating partnerships, distribution agreements, or private-label opportunities, this layered competitive structure means that the right fit depends on application requirements, claim substantiation, and channel expectations rather than on a single dominant formula for success.
Industry Dynamics Shaping Demand and Supply
Several structural forces are influencing how the whetstones market will evolve over the forecast window. Raw material provenance remains central. For natural stones, the availability of specific deposits and the long-term control of reserves affect both supply continuity and brand storytelling. Where producers maintain secure access to high-quality geological sources, they can support consistent product grades and reinforce heritage positioning. In synthetic categories, the use of abrasives such as aluminum oxide or silicon carbide, bonded for stable grit performance across ceramic and resin-bonded formats, governs consistency and repeatability. Performance reliability in synthetic lines is becoming a key purchase criterion as users compare labor, maintenance, and sharpening outcomes across material types.
Regulatory and claim-substantiation dynamics also matter. In markets where domestic manufacturing claims carry legal and consumer-trust weight, producers must align sourcing, processing, and labeling with applicable standards. Compliance with recognized domestic content requirements can influence procurement decisions in government, institutional, and quality-conscious commercial settings, while also shaping brand perception among consumers who value origin transparency. Companies that proactively manage these claims while maintaining visible quality assurance processes can turn compliance into a differentiator rather than a constraint.
Demand-side signals from recent evaluation activity further illuminate where attention is flowing. Updated 2026 product testing and recommendation coverage has highlighted specific collaboration sets and starter systems as top performers based on edge performance metrics and practical usability. These independent assessments do more than endorse individual products; they reinforce consumer expectations around sharpening quality, ease of use, and system completeness. For manufacturers and retailers, such coverage functions as a market signal about which attributes are gaining salience and which product configurations are resonating with buyers in the current cycle.
Together, these dynamics suggest that the whetstones market will reward organizations that treat sharpening performance as a measurable value driver, that protect their material supply narratives with verifiable sourcing, and that stay responsive to how review ecosystems and professional testing influence buying criteria.
Winches Market
Strategic Implications for Product, Channel, and Sourcing Decisions
For companies operating in or entering the whetstones market, the strategic agenda in 2026 should center on three questions. First, how will the portfolio balance heritage and performance claims without diluting either? Natural-stone narratives and synthetic-consistency arguments can coexist in a single company's offering, but they require distinct positioning, quality documentation, and channel messaging. Blurring the two risks weakening trust with buyers who are increasingly attentive to material identity and claim accuracy.
Second, how should assortments be built for application reality rather than category averages? The whetstones market includes domestic and hobbyist use, professional culinary sharpening, and industrial or woodworking maintenance. Each environment places different demands on grit progression, surface behavior, durability, and ease of maintenance. A portfolio strategy that recognizes these distinctions will create more reliable repeat purchase behavior than one that relies on generic one-size assortments.
Third, where should growth be pursued given moderate concentration and uneven regional demand? The market's concentration profile leaves space for targeted expansion, but the most efficient path will vary by company capabilities. Some players will find value in deepening presence where their material identity and manufacturing footprint provide the strongest credibility. Others will benefit from aligning product offerings with the expectations set by recent testing and professional recommendations, using performance evidence to justify premium positioning or to accelerate adoption in underpenetrated user groups.
What the Full Report Delivers
This overview is intended to give executives a clear sense of the market's direction and the analytical depth available in the complete study. The full report extends this foundation into detailed segmentation figures, interpretive regional and application analyses, and a structured competitive assessment that links company profiles to strategic implications. It also integrates raw material context, regulatory considerations, and recent evaluation activity into a unified narrative that supports product roadmapping, channel planning, and sourcing strategy.
Whetstones Market
For teams that need to commit budget, define SKU architecture, assess partnership opportunities, or evaluate competitive response, the complete report provides the specificity required to move from directional confidence to executed strategy. The headline trajectory, structural signals, and competitive logic described here are only the starting point. The detailed intelligence behind them is available through our primary research page, where the full dataset and analytical commentary can be accessed in context.
Closing Perspective
The whetstones market in 2026 is best understood as a category where consistency, provenance, and performance perception now matter as much as price. Historical resilience, a mid-single-digit growth path, and a moderately concentrated competitive field create a landscape that rewards precise positioning and disciplined execution. Organizations that understand how material types, application needs, and claim standards interact will be better placed to build portfolios that hold their value as the market matures. Our research is designed to make that understanding operational, giving decision-makers the clarity required to act with confidence throughout the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Whetstones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com