

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
HNB Heater Market: 8% CAGR Trajectory and Asia Pacific's 47% Value Share

HNB Heater Market: Navigating Strategic Shifts and Commercial Opportunities in a Growing Landscape
The Heat-Not-Burn (HNB) heater market has evolved from a niche alternative to a substantial commercial category, driven by shifting consumer preferences, technological maturation, and regulatory accommodations in key regions. Tracking the market from 2020 through the current cycle reveals a consistent upward trajectory, with revenue expanding from approximately $1.65 billion in 2020 to roughly $2.45 billion in 2025. Forward projections indicate growth accelerating through the end of the decade, with annual revenue expected to approach $4.2 billion by 2032. This expansion reflects a compound annual growth rate of approximately 8.0 percent, signaling sustained momentum rather than a temporary adoption spike.
The scale and pace of this growth are notable, but the market's structure matters just as much as its size. Concentration remains relatively high, with the top three players capturing roughly 65 percent of revenue and the top five accounting for nearly 79 percent. This concentration suggests that scale advantages, brand equity, and control over heating technologies and consumable ecosystems continue to dominate competitive dynamics. At the same time, the presence of specialized electronics manufacturers and component suppliers indicates a layered value chain where differentiation occurs not only at the device level but also in heating element design, thermal management, and manufacturing precision.
Despite the positive trajectory, the industry faces several structural challenges that will shape strategy over the next few years. First, regulatory frameworks remain uneven across jurisdictions. In some markets, HNB devices operate within established harm-reduction or tobacco-product guidelines that permit commercialization but impose compliance costs, labeling requirements, and marketing constraints. In other regions, uncertainty around classification and taxation creates planning complexity for manufacturers and distributors alike. Second, supply chain friction persists. While raw material constraints for electronic components have stabilized relative to peak disruption periods, elevated input costs and intermittent shortages still affect production scheduling and unit economics. Roughly one in ten U.S. plants continues to report capacity impediments tied to component availability, a reminder that manufacturing resilience remains a live operational concern. Third, the market is navigating a cost environment shaped by trade policy. Import tariffs on certain components increase supply chain expenses and put pressure on both manufacturing margins and retail pricing strategies, forcing companies to balance affordability with profitability.
For decision-makers, the core implication is that growth alone does not guarantee commercial success. The winners in this market are increasingly defined by how effectively they manage regulatory navigation, supply chain continuity, and technology differentiation simultaneously. Companies that treat these as separate functions risk losing ground to competitors who integrate compliance, sourcing, and product design into a coherent strategy.
Key Drivers Shaping Market Direction
Several interdependent forces are propelling the HNB heater market forward. Understanding these drivers is essential for anticipating where value will accumulate and which business models are most likely to scale.
Technology Innovation and Thermal Precision
Heating technology remains the central competitive axis. Three broad approaches dominate the landscape: ceramic heating elements, induction heating modules, and resistance metal film heaters. Ceramic systems continue to command significant share because they offer reliable temperature control, consistent heating patterns, and a familiar form factor for consumers transitioning from combustion products. Induction modules, however, represent one of the most consequential technological shifts in the category. By eliminating direct contact between the heating source and the consumable, induction systems reduce residue buildup, simplify maintenance, and improve session consistency. This architecture also creates opportunities for faster heat-up times and more precise thermal profiling, which matters to users who value repeatability and convenience.
Recent product activity underscores the strategic importance of heating architecture. In March 2024, a major tobacco company commercialized an induction-based model in Japan, signaling a deliberate move toward contact-free heating in a mature market. That launch reflects a broader industry pattern: leading manufacturers are investing in next-generation heating methods that differentiate the user experience while also supporting manufacturing efficiency and consumable compatibility. For B2B participants, this trend creates demand for precision components, thermal management solutions, and assembly capabilities that can meet tighter tolerances and higher throughput requirements.
Policy and Regulatory Dynamics
Policy frameworks are reshaping where and how HNB products can be commercialized. In the European Union, the Tobacco Products Directive provides a regulatory structure that accommodates HNB devices as harm-reduction-oriented products in compliant markets, while still imposing requirements that affect product design, packaging, and market access. This framework allows commercialization but does not eliminate compliance complexity. Companies must align device specifications, consumable formats, and communication strategies with local rules, which often vary not only by country but also by channel and audience.
In the United States, the regulatory and trade environment introduces a different set of considerations. Import tariffs on certain components raise the cost of assembled heaters and sub-assemblies, affecting both production planning and end-price positioning. This dynamic is particularly relevant for markets that rely on cross-border component flows or finished-device imports. At the same time, the U.S. rollout of new HNB devices in select cities demonstrates that companies are willing to invest in phased market entries, using localized activation events, trial programs, and consumer education to build awareness in a controlled manner. The combination of regulatory structure and trade costs means that market entry strategy is increasingly a function of supply chain geography, compliance readiness, and localized consumer engagement rather than product availability alone.
Demand-Side Shifts and Consumer Behavior
Consumer preferences are evolving as the category matures. Early adoption was heavily influenced by curiosity and the appeal of an alternative to combustion, but current demand is increasingly shaped by experience quality, session consistency, device ergonomics, and the practicalities of maintenance. Users are comparing heating performance, residue management, battery behavior, and the convenience of consumable formats. This shift favors products that deliver predictable performance and simple operation, and it puts pressure on manufacturers to reduce variability across production batches.
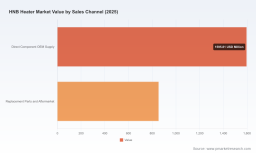
At the same time, the demand base is broadening beyond early adopters. Adult smokers evaluating alternatives are looking for demonstrable differences in experience, while existing users are increasingly attentive to device durability and consumable availability. For commercial stakeholders, this means that product reliability and consumable ecosystem strength are becoming as important as initial feature differentiation. In aftermarked-driven segments, replacement parts and ongoing support also matter, because repeat usage depends on the availability of compatible components and the perceived longevity of the device.
Supply Chain and Cost Structure Evolution
The cost structure of HNB heaters is influenced by component sourcing, assembly complexity, and trade conditions. Electronics manufacturing services providers play a significant role in this ecosystem, supplying heaters, precision components, and assembled devices to larger brand owners. This services model allows brand owners to scale production without building all manufacturing capacity internally, but it also dependencies on supplier capacity, quality control, and geographic distribution. Where tariffs or logistics constraints raise costs, manufacturers must decide whether to absorb those costs, adjust pricing, or reconfigure sourcing strategies.
Material availability has improved compared with earlier disruption periods, but the baseline is still higher than pre-2020 norms. Component shortages have stabilized, yet some facilities continue to report impediments that affect scheduling and output. For companies operating in this environment, resilience is not solely a procurement issue; it is a product strategy issue. Designs that reduce dependency on constrained components, dual-sourcing arrangements, and manufacturing footprints that balance cost with continuity are increasingly relevant. The practical takeaway is that cost optimization can no longer be pursued in isolation from risk management.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of large international tobacco companies, electronics manufacturing services providers, and specialized component and device manufacturers. This mix creates a multi-layered market in which competitive advantage can arise from brand strength, heating technology, manufacturing scale, or component specialization.
Strategic Positioning Among Leading Companies
Among the most prominent players, Philip Morris International has built a strong position around its IQOS heated tobacco system, using blade and induction heating technologies alongside a compatible consumable ecosystem. Its recent U.S. activity illustrates a deliberate, phased approach: a commercial launch in Austin with a device priced at $60, supported by guided trials and community-based demonstrations, followed by a broader rollout strategy that emphasizes consumer exposure and repeat trial. This combination of product introduction and localized engagement suggests a focus on converting interest into habitual use through direct experience rather than broad advertising alone. The earlier introduction of an induction-based model in Japan further reflects a technology-forward posture aimed at strengthening performance perception and long-term category relevance.
Worldwide In-Line Heaters Market
British American Tobacco competes with its Glo series, emphasizing heating performance that aligns with consumer preferences. Its positioning highlights the importance of perceived experience quality in a category where users compare session consistency, taste delivery, and convenience. Japan Tobacco International markets Ploom devices and newer EVO and AURA systems, building on a portfolio that spans multiple device generations and consumable formats. Imperial Brands offers Pulze heating devices with compatible sticks, with an emphasis on compact design and session capacity, showing that form factor and usability remain meaningful differentiators.
Beyond the brand-owning companies, the supply side includes electronics manufacturing services firms such as Venture Corporation and Flex, both of which provide HNB heater components and device manufacturing support to major tobacco brands. Their presence indicates that scale manufacturing, precision assembly, and supply reliability are valuable capabilities in their own right. Chinese manufacturers and component specialists, including Shenzhen Buddy Technology, TaoTao Technology, Dongguan Guoyan Electric Heating Materials, and Shenzhen Huachengda Precision Industry, add further depth to the value chain by focusing on heating devices, electronic components, heating materials, and precision assemblies. This ecosystem suggests that the market is not only competitive at the consumer-facing level but also highly contested in the component and manufacturing segment, where differentiation comes from material quality, process control, and the ability to meet evolving device specifications.
Heat Cost Allocator Market
How the Landscape Is Evolving
The market is showing signs of both consolidation and differentiation. Concentration among leading brand owners reflects the advantages of ecosystem control, established distribution, and sustained investment in product iterations. At the same time, the breadth of component and manufacturing suppliers indicates that specialization remains viable, particularly for firms that can serve multiple brand owners or provide advanced heating materials and precision parts. New entrants and expanding manufacturers are likely to continue exploring niches where thermal performance, cost efficiency, or supply flexibility offer a clear advantage.
One noticeable trend is the alignment of device architecture with long-term consumable strategy. Companies are increasingly treating heating technology not just as a product feature but as a structural decision that affects consumable compatibility, maintenance requirements, and manufacturing complexity. That alignment can create stronger customer retention where the experience is consistent, but it also raises the stakes for initial product execution. In parallel, the growing role of contract manufacturing and component suppliers means that competitive advantage increasingly depends on partnerships and process excellence as much as on branded product design.
PW Consulting Health Care Research Center
For businesses observing this landscape, the key question is not simply who leads today, but which capabilities will matter most as the category matures. Brand recognition remains powerful, but thermal engineering, supply reliability, regulatory readiness, and consumer trial conversion are becoming equally important determinants of long-term positioning.
Forward Outlook: Trends and Commercial Implications
Looking ahead over the next three to five years, several trends are likely to shape how value is created and captured in the HNB heater market.
One important trend is the continued refinement of heating architecture, with induction and advanced ceramic systems competing on performance, consistency, and manufacturability. As designs mature, the competitive edge will shift from introducing novel heating methods to optimizing them for reliability, cost, and consumable compatibility. Companies that can deliver stable thermal performance at scale while reducing maintenance friction will be well positioned to retain users and support repeat consumable purchases.
A second trend is the increasing importance of localized market strategy. Regulatory variation, trade costs, and consumer education requirements make broad, uniform launches less effective than targeted introductions supported by trials, demonstrations, and channel-specific engagement. This pattern favors organizations that can coordinate product availability, compliance, and consumer activation in a coordinated way, rather than treating each function separately. It also favors supply chains that can adapt to regional cost structures and component availability.
A third trend is the growing relevance of the component and manufacturing layer. As brand owners scale device volumes and introduce new heating formats, demand for precision components, heating materials, and electronics assembly is likely to remain strong. Suppliers that can provide consistent quality, flexible capacity, and material expertise will find continued opportunity, especially if they can support multiple clients or rapidly adapt to new device requirements. This creates a parallel opportunity set for B2B players who are not necessarily consumer-facing but are essential to device production and performance.
These trends connect directly to commercial opportunities. For device makers, the opportunity lies in pairing technology differentiation with execution discipline, ensuring that product advantages are reproducible across production and supported by a dependable consumable supply. For component and manufacturing suppliers, the opportunity lies in becoming trusted partners for brands that need thermal precision, quality consistency, and supply resilience. For investors, the opportunity is to distinguish between market-level growth and company-level execution, since the category's expansion does not automatically translate into uniform returns across all participants.
Potential risks and uncertainties should also be factored into planning. Regulatory changes could alter market access or compliance costs in important regions. Trade policy shifts may continue to affect component pricing and sourcing strategies. Supply chain disruption, while less severe than in earlier periods, can still affect production cadence and cost stability. In addition, consumer acceptance may evolve as alternative products emerge and as users become more discriminating about performance and convenience. These uncertainties do not negate the growth outlook, but they do mean that strategy must be flexible enough to respond to changing conditions in policy, cost, and consumer behavior.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product design with both consumer experience and supply chain realities. That means evaluating heating technology choices not only for performance but also for manufacturability, component dependency, and consumable compatibility. Building tolerance for supply variability through design flexibility, dual sourcing, or regional manufacturing options can help protect output and margin when input conditions shift. Equally important is consistency: producing devices that deliver repeatable heating performance reduces user dissatisfaction and supports long-term adoption.
For investors, the more useful question is not whether the category will grow, but which participants are best equipped to convert growth into durable advantage. Factors worth weighing include technology positioning, concentration of revenue across products and regions, exposure to trade and component cost pressures, and the strength of the consumable ecosystem. Companies that rely on a single product format or a narrow supply base may face more volatility than those with broader manufacturing relationships and multiple heating approaches. Evaluating these operational and strategic details is often more revealing than headline revenue projections alone.
For procurement and supply chain leaders, the focus should be on resilience and quality rather than price alone. Given that component availability has stabilized but remains above pre-2020 baselines, and that tariffs can affect landed costs, sourcing strategies should account for continuity, lead-time reliability, and specification precision. Partnerships with manufacturers and component suppliers that understand HNB heating requirements can reduce the risk of performance variation and production delays. In practice, this means treating supplier selection as a strategic decision that affects product reliability and market readiness, not just a transactional cost exercise.
For organizations seeking a more detailed view of segmentation, regional dynamics, technology splits, channel structures, and company-level positioning, deeper commercial intelligence can help translate these broad trends into specific plans. A comprehensive research report can provide the granular data needed to compare sub-segments, assess competitive exposure, and identify where to commit resources with greater confidence. The strategic direction is clear enough to act on, but the specifics matter when turning insight into investment, sourcing, or product decisions.
For detailed analysis of this topic, please visit the official page: HNB Heater Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com