

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vet Speculum Market Hits $185M in 2025, Projected 5.2% CAGR Through 2032

Navigating the Next Horizon: Strategic Insights into the Veterinary Speculums Market Through 2032
The global veterinary healthcare industry is undergoing a structural transformation driven by rising pet ownership, expanding large animal husbandry practices, and an increasing emphasis on procedural precision. Within this ecosystem, the veterinary speculums market represents a critical yet often under-analyzed segment of surgical and diagnostic instrumentation. For executives, procurement leaders, and clinical product strategists, understanding the trajectory of this market is not merely an academic exercise—it is a prerequisite for capital allocation, supply chain resilience, and competitive positioning.
Our latest market research publication delivers a comprehensive, data-backed examination of this sector, tracing historical performance from 2020 through 2025 and projecting forward across a forecast window extending to 2032. Anchored in a base year of 2025 and denominated in USD millions, the analysis quantifies a market that has demonstrated resilient expansion. Total market revenue grew from 145.0 million in 2020 to 185.0 million in 2025, reflecting sustained demand across both companion animal and production animal segments. The forecast period projects continued momentum, with valuations advancing to 194.16 million in 2026 and reaching 263.8 million by 2032. This trajectory translates to a compound annual growth rate of 5.2 percent, a figure that underscores moderate but predictable upside for stakeholders who can align product portfolios and distribution strategies with emerging clinical workflows.
What separates this study from generic industry summaries is its deliberate focus on operational decision-making. Rather than presenting abstract growth narratives, the report dissects the mechanical, regulatory, and competitive forces that will dictate margin profiles, fulfillment costs, and market access between now and the end of the decade. The following sections outline the analytical architecture of the research and explain why it should be treated as a foundational input for 2026 planning cycles.
Report Architecture: Operational Intelligence for Cross-Functional Teams
The publication is structured to serve multiple internal audiences simultaneously. Clinical product managers, supply chain directors, finance leads, and regional sales heads will each find modules tailored to their decision responsibilities. The core of the report is built around a multi-dimensional segmentation framework that isolates structural demand drivers without obscuring the practical considerations that influence purchasing behavior.
Readers will encounter a detailed examination of product typologies that dominate veterinary diagnostic and surgical procedures. The analysis covers oral speculums, vaginal speculums, and ear speculums paired with otoscope systems, each evaluated through the lens of clinical utility, sterilization compatibility, and practitioner adoption patterns. Rather than merely cataloging product categories, the report connects design variations to real-world usage scenarios. For instance, the prevalence of three-blade Polansky configurations with butterfly screw mechanisms for large animal work, alongside set-screw Killian designs optimized for canine vaginal examinations, is contextualized within the broader demand for durable, sterilizable instrumentation. This product-level granularity enables manufacturers and distributors to identify where specification standardization can reduce inventory complexity and where customization remains a pricing advantage.
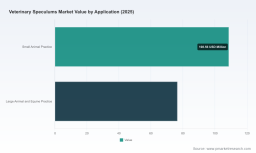
The application dimension of the study maps demand across small animal practice and large animal and equine practice. This split is particularly important because procurement cycles, clinician preferences, and facility sterilization capabilities differ materially between these environments. By analyzing how usage intensity, procedure frequency, and replacement cycles vary by practice type, the report equips commercial teams with the insight needed to tailor bundling strategies, reorder scheduling, and field education programs.
Regional coverage is likewise presented through a demand-weighted lens. The research evaluates North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa as distinct operational theaters, each with its own mix of veterinary infrastructure maturity, import dependency, and domestic manufacturing capability. The report does not stop at mapping where demand is concentrated; it investigates the logistical and regulatory friction points that influence time-to-market for imported instruments, the sensitivity of pricing to freight and duty fluctuations, and the extent to which local reprocessing standards shape material selection.
Beyond segmentation, the study incorporates a deep dive into competitive positioning, recent product developments, and the broader industrial context that shapes manufacturing economics. This holistic design ensures that the report can function as both a strategic briefing document for executive committees and a tactical reference for business unit planning.
Competitive Landscape: Concentration, Differentiation, and Strategic Arbitrage
One of the most decision-relevant sections of the research examines the structure of the competitive field. The market is characterized by a moderately fragmented but increasingly disciplined supplier base. Industry concentration metrics indicate that the top three firms command approximately 28.5 percent of total revenue, while the top five account for 35.2 percent. This level of concentration suggests that scale advantages exist, but there is still meaningful room for specialized manufacturers to compete on design fidelity, material quality, and application-specific engineering.
The report profiles the organizations that currently anchor the supply landscape, drawing on product portfolios, geographic footprints, and stated clinical focus areas. GerVetUSA Inc. stands out for its emphasis on German-forged surgical instruments, including vaginal and nasal speculum variants designed for both small and large animals. Jalal Surgical has positioned itself as a manufacturer and supplier of high-quality vaginal speculums built from premium materials intended for repeated veterinary use. Sklar Surgical Instruments contributes to the competitive mix with surgical-grade designs, including Graves and Pederson vaginal speculums adapted for veterinary applications. Jorgensen Laboratories, operating under the JorVet brand, offers specialized instruments such as the Killian K-9 Vaginal Speculum and Polansky Vaginal Speculum, targeting dogs and large animals with configuration-specific engineering. Welch Allyn, now part of Hillrom, provides reusable veterinary specula compatible with otoscopes for ear examinations, including bivalve designs and multiple size options. Surgical Holdings, based in the United Kingdom, focuses on stainless steel obstetrical and vaginal speculums intended for large animal veterinary use. Medline Industries rounds out the profiled set with supplies such as SofSpec reusable veterinary specula and other diagnostic speculums supporting a range of veterinary procedures.
Rather than presenting these companies as static company profiles, the report evaluates them through a strategic lens. It assesses where overlapping product lines create price compression, where differentiated material choices or blade configurations create defensible value, and where distribution partnerships can accelerate adoption in underpenetrated practice types. The analysis also considers the implications of competitive density for private-label and co-branding opportunities, especially in regions where procurement teams prioritize cost predictability without sacrificing sterilizability or mechanical reliability.
Recent innovation activity reinforces the importance of this competitive review. In December 2024, a development effort led by Nail Tekin Önder and colleagues produced and evaluated a novel Onder Speculum designed to improve visualization and retraction of the cervix in small ruminants during transcervical procedures. Documented in the Kafkas University Veterinary Faculty Journal, this work illustrates how targeted procedural challenges can generate new instrumentation concepts with potential downstream commercialization pathways. For incumbent suppliers, such developments signal the need to monitor academic and clinical innovation pipelines, not only to identify potential acquisition or licensing targets, but also to anticipate shifts in procedural standards that may alter demand for conventional configurations.
Market Dynamics and Material Realities: The Forces Shaping Margin and Adoption
Any credible market strategy must account for the underlying industrial and regulatory conditions that determine what can be manufactured, how it can be sterilized, and how it is positioned relative to human-use equivalents. The report integrates these forces explicitly so that readers can distinguish temporary pricing fluctuations from structural cost drivers.
Material composition is a foundational consideration. Veterinary speculums are primarily manufactured from surgical-grade stainless steel chosen for corrosion resistance and compatibility with frequent autoclave sterilization. This material baseline influences not only unit economics but also supplier qualification requirements, reprocessing infrastructure expectations, and lifecycle durability claims. The study examines how variations in steel grade, surface finishing, and mechanical tolerances interact with sterilization cycles to affect total cost of ownership for veterinary practices and, by extension, how suppliers can justify premium positioning when they deliver verifiable durability and consistent tangential performance across repeated reprocessing events.
Regulatory context adds another layer of strategic nuance. Animal-use devices such as veterinary speculums are generally not subject to FDA premarket notification requirements, including the 510(k) pathway, in the same manner as human-use equivalents. This regulatory distinction lowers certain barriers to market entry and can accelerate the commercialization of new designs, but it does not remove scrutiny around quality systems, labeling, and post-market expectations. The report explains how this dynamic shapes competitive speed-to-market on one hand and clinical confidence requirements on the other, and why companies that invest early in robust manufacturing documentation and consistent quality control often gain an advantage in procurement evaluations even when formal device regulation is less prescriptive than in human healthcare.
Product design conventions further influence purchasing decisions. Standard configurations such as Polansky speculums with three blades and butterfly screws for large animals, and Killian speculums with set screws for canine vaginal examinations, are not merely catalog details; they reflect established clinician ergonomics and procedural workflows. The research shows how entrenched design familiarity can slow adoption of alternative geometries unless the replacement clearly improves visualization, reduces tissue trauma, or simplifies handling. For suppliers, this highlights the importance of field education, demonstration programs, and specification sheets that align new designs with existing procedural mental models rather than attempting to displace them without clear clinical justification.
Together, these dynamics create a market environment where growth is neither purely volume-driven nor purely price-driven. Instead, it is shaped by the interaction of material durability, sterilization compatibility, procedural specificity, and procurement behavior across different practice types. Companies that understand these interacting variables are better positioned to set realistic pricing strategies, optimize production planning, and avoid investment in features that add manufacturing cost without translating into procurement preference.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle is likely to be defined by procurement recalibration, product portfolio prioritization, and regional expansion decisions. In that environment, decision-makers need more than headline growth figures; they need an integrated view of how demand is distributed, how competitive intensity will affect margin retention, and where product innovation can create durable differentiation.
Veterinary Speculums Market
This study is designed to support those decisions in several concrete ways. First, it provides a consistent historical and forecast baseline that allows finance and operations teams to model revenue scenarios against a 5.2 percent compound annual growth trajectory without relying on anecdotal estimates. Second, it breaks down the market along typological, application, and regional dimensions so that commercial leaders can identify where to concentrate sales effort, where to streamline SKU counts, and where localized manufacturing or distribution partnerships may reduce exposure to freight volatility and import friction. Third, it frames the competitive field in terms of concentration, specialization, and recent innovation signals, enabling strategy teams to assess where head-to-head competition is most likely to compress pricing and where niche engineering or procedural focus can preserve value.
Equally important, the report translates industrial realities into commercial implications. By addressing the role of surgical-grade stainless steel, autoclave compatibility, design conventions such as Polansky and Killian configurations, and the regulatory distinction between animal-use devices and human-use equivalents, it helps product and quality leaders anticipate the operational prerequisites for scale-up, supplier qualification, and market entry. This level of detail is intended to reduce the gap between strategic ambition and execution risk.
For executives evaluating expansion into new practice types or geographies, the research also clarifies where demand is deepening versus where it is merely price-sensitive. Understanding this distinction is essential for deciding whether to compete on throughput and cost efficiency or to invest in clinical value propositions that justify premium positioning. The study does not offer generic advice; it provides a structured foundation for making that choice with greater confidence.
Looking Ahead: Positioning for Sustained, Predictable Growth
The veterinary speculums market is not characterized by sudden disruptive swings, but it is increasingly shaped by procedural refinement, material expectations, and competitive maturation. The forecast window to 2032 suggests a market that will continue to expand in a measured way, with total revenue advancing from approximately 194 million in 2026 toward the mid-260 million range by the end of the decade. Translating that trajectory into a viable corporate strategy requires more than awareness of the growth rate. It requires a working knowledge of the segmentation logic, competitive archetypes, material constraints, and procedural preferences that will determine which companies capture disproportionate value along the way.
Our full report extends far beyond the high-level framework summarized here. It contains the detailed segmentation analysis, competitive profiling, regional demand context, and operational implications that procurement, product, and strategy teams need to build defensible plans for 2026 and beyond. Readers seeking the complete dataset, deeper competitive evaluations, and the full set of market dynamics discussed in this introduction are encouraged to access the source publication for the full intelligence package. In a market where margin protection and product relevance depend on precise market understanding, that deeper view is not a luxury; it is a strategic necessity.
Worldwide Veterinary Endoscopes Market
For detailed analysis of this topic, please visit the official page: Veterinary Speculums Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com