

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ocular Inflammation Market to Hit $17.87 Billion by 2032 at 6.5% CAGR

Strategic Foresight in Ocular Inflammation Treatment: Navigating the 2026 Market Landscape
As we enter 2026, the global landscape for treating ocular inflammation stands at a critical inflection point. Driven by an aging population, increased prevalence of chronic eye conditions, and a evolving therapeutic pipeline, stakeholders across the pharmaceutical and medical device value chain must recalibrate their strategies. The recently published Ocular Inflammation Treatment Market research report serves as an indispensable compass for navigating this complex terrain. This analysis is not merely a collection of statistics; it is a strategic asset designed to inform capital allocation, product development, and competitive positioning for the remainder of the decade.
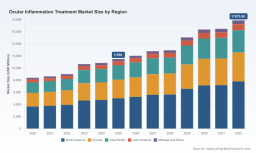
Understanding the magnitude of this opportunity requires a clear view of the historical trajectory and future projections. Over the past five years, the market has demonstrated resilience and steady growth, overcoming supply chain disruptions and evolving regulatory frameworks. From a base valuation in the early 2020s, the sector has expanded robustly, reaching an estimated 11,500 million USD in 2025. Looking ahead, the momentum is expected to sustain itself, with projections indicating a climb toward 17,870.86 million USD by 2032. This growth trajectory is underpinned by a compound annual growth rate that signals healthy expansion, suggesting that demand for ocular anti-inflammatory therapies will continue to outpace many traditional pharmaceutical segments. For executives and investors, these figures represent more than top-line revenue; they indicate the overall health of the sector and the viability of long-term investments in ophthalmic innovation.
Defining the Scope of Opportunity
To fully leverage this market intelligence, one must understand the depth of the data covered in the comprehensive study. The report dissects the industry through multiple lenses, ensuring that no strategic blind spots remain. It provides a granular look at the forces shaping the industry, moving beyond high-level estimates to offer actionable intelligence.
The core of the analysis rests on several pivotal pillars:
- Historical and Forecast Data: The study offers a detailed retrospective from 2020 to 2025, establishing a robust baseline, alongside a forward-looking forecast period extending through 2032. This dual perspective allows companies to benchmark past performance against future expectations.
- Segmentation Analysis: The market is broken down by drug class, indication, and region. This allows stakeholders to identify high-growth pockets within the broader ecosystem. Whether the interest lies in corticosteroids, NSAIDs, immunomodulators, or anti-infectives, the data isolates performance drivers for each category.
- Competitive Benchmarking: Profiles of key industry players are included, offering insights into their product portfolios, geographic footprints, and strategic moves. This section is crucial for understanding relative market strength and potential partnership opportunities.
- Regulatory and Reimbursement Dynamics: Given the highly regulated nature of ophthalmic products, the report integrates critical information regarding FDA approvals, patent protections, and reimbursement pathways such as J-codes for intravitreal implants.
Regulatory Catalysts and Innovation Trends
The environment for ocular inflammation treatment is being reshaped by recent regulatory milestones and technological advancements. For strategic planners, staying ahead of these curves is essential to maintaining competitiveness. The report captures these dynamics in real-time, ensuring that decision-makers are not operating on outdated assumptions.
Recent FDA Approvals and Clinical Clearances
In mid-2025, the regulatory landscape saw significant activity. Amneal Pharmaceuticals secured FDA approval for generic prednisolone acetate ophthalmic suspension 1%, with a launch planned for the third quarter of 2025. This move increases accessibility for steroid-responsive ocular inflammation treatments, potentially shifting pricing dynamics and market share among generic manufacturers. Simultaneously, Alcon achieved FDA approval for TRYPTYR (acoltremon ophthalmic solution) for signs and symptoms of dry eye disease, a condition intimately linked with ocular surface inflammation. These approvals highlight a trend toward both cost-effective generics and novel mechanisms of action.
Looking toward early 2026, the pipeline shows promise for steroid-sparing options. Novaliq received FDA IND clearance for NOV05 (tacrolimus ophthalmic solution) for a Phase 2 trial in non-infectious anterior uveitis. This development is particularly noteworthy for strategists monitoring the shift away from long-term steroid use due to side effect profiles. Such innovations suggest a diversifying treatment arsenal that could disrupt incumbent franchises relying heavily on traditional corticosteroids.
Supply Chain and Intellectual Property Considerations
Beyond approvals, operational realities play a significant role in market dynamics. Tariffs on imported pharmaceutical ingredients remain a concern, potentially increasing production costs for treatments reliant on global supply chains. Consequently, pricing strategies and margin management require careful scrutiny. Furthermore, intellectual property continues to be a moat for sustained-release technologies. Multiple patents protect formulations such as DEXTENZA and YUTIQ, securing revenue streams for innovators while setting barriers for entrants. Understanding the patent cliff scenarios and the protection lifecycle of these devices is vital for risk assessment.
Competitive Landscape and Strategic Positioning
The market concentration indicates a moderately consolidated environment where strategic partnerships and portfolio diversification are key. The top three companies hold a significant portion of the market share, while the top five control more than half of the total revenue. This structure suggests that while there is room for niche players, scale and broad product portfolios offer distinct advantages.
Several key corporations define the current competitive arena. AbbVie Inc., based in North Chicago, remains a powerhouse with offerings like prednisolone acetate (Pred Forte) for steroid-responsive conditions. Their established presence underscores the enduring importance of classic corticosteroids. In the realm of sustained-release implants, Alimera Sciences and EyePoint Pharmaceuticals, Inc. are critical players. Alimera markets ILUVIEN (fluocinolone acetonide intravitreal implant) for diabetic macular edema and related conditions, while EyePoint commercializes YUTIQ for chronic non-infectious uveitis and DEXYCU for postoperative inflammation. These intravitreal implants represent a high-value segment where reimbursement pathways including J-codes have been established, stabilizing revenue models for these therapies.
Worldwide Conjunctivitis Ophthalmic Drugs Market
Bausch Health Companies Inc. continues to market a range of ophthalmic steroids, including Lotemax, catering to inflammation and pain management. Novartis AG supplies anti-inflammatory products through its broader ophthalmology portfolio, leveraging global scale. In the generic space, Amneal Pharmaceuticals is expanding its footprint, challenging branded formulations on price. Pfizer Inc. provides various corticosteroid and NSAID formulations, while Santen Pharmaceutical Co., Ltd. maintains a strong global focus on ophthalmic therapeutics from its base in Osaka. Ocular Therapeutix, Inc. offers DEXTENZA, a dexamethasone ophthalmic insert for postoperative inflammation and allergic conjunctivitis itching, showcasing innovation in delivery mechanisms.
Ocular Inflammation Treatment Market
Segmentation Insights for Targeted Strategy
Strategic success in this market requires understanding where the value is created. The report provides segmentation data that allows companies to tailor their approaches. By drug class, the market is diversified. Corticosteroids continue to hold substantial ground, reflecting their status as a standard of care. However, immunomodulators and NSAIDs also command significant market presence, indicating a balanced therapeutic mix. Anti-infectives represent another crucial segment, particularly for inflammation with an infectious etiology. Companies must decide whether to compete on volume in mature classes or innovate in expanding categories.
By indication, the demand drivers are varied. Dry Eye Syndrome represents a large portion of the market, driven by high prevalence and ongoing innovation in managing ocular surface disease. Allergic Conjunctivitis remains a consistent driver, often seasonal but broadly impactful. Uveitis, while less prevalent, represents a high-value specialty segment where advanced therapies and implants are often required. Post-operative inflammation is another critical area, directly linked to the volume of ophthalmic surgeries performed globally. Understanding the specific growth rates and revenue contributions of each indication helps companies prioritize R&D and marketing resources effectively.
Regionally, the market exhibits distinct characteristics. North America continues to be a dominant force, reflecting high healthcare spending and adoption rates. Europe remains a substantial market with its own regulatory nuances. The Asia Pacific region represents a high-growth opportunity, driven by improving access and increasing awareness. Latin America and the Middle East and Africa offer emerging potential, though they come with unique reimbursement and access challenges. A one-size-fits-all strategy is rarely effective; regional customization is key to capturing value across these geographies.
Why This Research Matters for 2026 Decisions
As the market moves through the forecast period, the cost of uncertainty is high. Misjudging the impact of a new generic entrant, misinterpreting regulatory signals, or overlooking a shift in reimbursement policy can lead to significant strategic errors. This report mitigates those risks by providing a consolidated view of the forces at play.
For business development teams, the competitive profiles and recent developments sections offer leads for potential collaborations or acquisition targets. For marketing leaders, the segmentation data informs messaging and territory planning. For C-suite executives, the macro trends and financial projections support budgeting and long-term visioning. The inclusion of supply chain risks and patent landscapes adds a layer of operational realism that is often missing from broader industry overviews.
The data suggests that the path to 2032 is not linear. While the overall trajectory is positive, there will be fluctuations based on drug launches, patent expirations, and regulatory changes. Companies that possess granular intelligence will be better positioned to pivot when necessary. For instance, the rise of steroid-sparing therapies could alter the demand curve for traditional corticosteroids over the next few years. Similarly, changes in reimbursement codes for intravitreal implants could impact the economics of sustained-release products.
Accessing the Full Intelligence
This overview provides a glimpse into the depth and breadth of the analysis available. However, the true value lies in the detailed data tables, comprehensive company profiles, and scenario-based forecasts that form the core of the full report. The macro figures and trends mentioned here are derived from a sophisticated modeling process that accounts for multiple variables influencing the market.
To make fully informed decisions, stakeholders need access to the complete dataset. This includes specific revenue breakdowns by segment, detailed historical comparisons, and the nuanced analysis of competitive moves that cannot be fully captured in a summary. The interplay between drug classes, indications, and regions creates a complex matrix where specific insights can reveal hidden opportunities or threats.
Investing in this knowledge asset is an investment in strategic clarity. As the ocular inflammation treatment market continues to evolve through 2026 and beyond, those equipped with the most accurate and comprehensive data will lead the sector. We invite you to explore the full report to gain the detailed intelligence necessary to navigate this dynamic market with confidence. The complete analysis offers the granularity required to transform high-level trends into actionable business strategies.
For detailed analysis of this topic, please visit the official page: Ocular Inflammation Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com