

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Degradable Implants Market: Why 8.25% CAGR and Material Shifts Redefine Growth

Degradable Implants Market: Stragetic Trends and Commercial Opportunities in the Bioabsorbable Era
1. Market Reality and Core Challenges
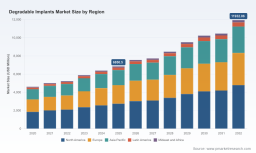
The global market for degradable implants has crossed a critical inflection point. Valued at approximately USD 6.85 billion in 2025, the segment has expanded steadily from around USD 4.61 billion in 2020, reflecting a compound annual growth rate of 8.25 percent through 2032. By the end of the forecast window, annual revenue is projected to approach USD 11.93 billion. This trajectory is not merely a function of rising procedural volumes; it reflects a structural shift in how clinicians and health systems evaluate implant performance. The preference is moving away from permanent hardware that requires secondary removal procedures, toward bioabsorbable solutions that support tissue regeneration while gradually transferring load back to native structures.
Despite the growth trajectory, the industry faces several operational and commercial headwinds that shape how value is captured. First, the regulatory bar for bioresorbable devices remains unusually high. Agencies require comprehensive biocompatibility profiling, long-term in vivo degradation tracking, and explicit demonstration of mechanical equivalence throughout the resorption timeline. These requirements extend development cycles and raise the cost of clinical validation, particularly for metallic and polymer systems that behave differently during early inflammation and remodeling phases.
Biodegradable Micro Screws Market
Second, the economics of advanced biomaterials create a narrow margin window. Specialized magnesium alloy development and precision manufacturing currently generate production costs 30-50 percent higher than conventional titanium or stainless-steel implants. Procurement teams accustomed to cost-per-procedure comparisons must reconcile upfront premium pricing with downstream savings from eliminated removal surgeries and reduced revision rates. This value proposition is persuasive in controlled pilot settings, yet it demands robust real-world evidence before widespread formulary adoption.
Third, supply chain concentration introduces pricing volatility and geographic risk. China dominates primary magnesium production, which means medical-grade biodegradable magnesium alloys are exposed to raw material fluctuations and logistics constraints. Manufacturers must navigate this dependency while maintaining strict purity and structural consistency for load-bearing applications. The convergence of these challenges—regulatory rigor, cost premiums, and commodity exposure—means that commercial success depends less on product novelty alone and more on integrated evidence generation, manufacturing discipline, and reimbursement strategy.
2. Key Drivers Reshaping the Market
Technology Innovation and Material Breakthroughs
Material science is the primary engine behind the market's expansion. Polymer-based systems have matured significantly, with self-reinforced PLGA constructs now enabling trauma, pediatric, and extremity applications that were previously limited by mechanical strength concerns. Magnesium alloy implants have emerged as the most disruptive category, combining favorable mechanical compatibility with predictable resorption and bioactive stimulation of bone healing. The ability to offer magnesium-based screws and pins with regulatory clearances has shifted magnesium from a research curiosity to a clinically viable fixation option. These advances are crossing over into cardiovascular scaffolds and soft-tissue repair, where temporary support structures reduce long-term foreign-body concerns. The broader implication is that device manufacturers are no longer choosing between resorbable and permanent hardware on a binary basis; they are engineering degradation profiles to match specific anatomical and clinical timelines.
Regulatory Evolution and Evidence Standards
Regulatory pathways are becoming more defined, but they are also more demanding. Guidance from major agencies now consistently requires ISO 10993 biocompatibility testing, long-term in vivo degradation studies, and demonstration of mechanical equivalence across the degradation window. This framework is simultaneously a barrier and a competitive moat. Companies that build rigorous evidence pipelines early can secure first-mover advantages, while laggards face lengthened development timelines and fewer differentiation points. Recent milestones illustrate the trend: magnesium-based orthopedic implants have achieved landmark clearances in the US and CE marks in Europe, establishing regulatory precedents for metallic bioabsorbable devices. These approvals do not lower the bar; they clarify it. The message to the industry is that evidence design, not just device design, increasingly determines commercial viability.
Demand-Side Shifts and Clinical Economics
Clinical demand is being shaped by two reinforcing forces: procedural preference and total-care economics. Surgeons increasingly favor implants that eliminate the need for secondary removal, particularly in pediatric populations, sports medicine, and trauma cases where revision surgery carries additional risk. At the same time, health systems are scrutinizing downstream costs more closely. A premium-priced bioabsorbable implant can be economically justified when it reduces readmission, revision, and rehabilitation burden. Dental and craniofacial applications further expand the demand base, as temporary fixation and guided bone regeneration benefit from materials that resorb without leaving permanent hardware in aesthetically sensitive sites. This demand evolution is not uniform across regions or service lines; it is strongest where clinical outcomes and total episode cost can be linked through credible evidence.
Supply Chain Dynamics and Manufacturing Capability
Cost structure and supply resilience are becoming strategic differentiators. Medical-grade biodegradable alloys and specialty polymers depend on controlled synthesis, precision machining, and consistent sterilization processes. The concentration of primary magnesium production in specific geographies amplifies pricing exposure and incentivizes manufacturers to diversify sourcing, secure long-term agreements, and invest in internal alloy formulation expertise. Manufacturing scale is not the only concern; consistency is. Slight variations in degradation rate or surface characterization can alter clinical performance and regulatory acceptance. As a result, the supply chain is evolving from a commodity procurement function into a core competency that shapes margin structure, product reliability, and time-to-market.
3. Competitive Landscape and Leading Strategies
The competitive field blends focused specialty innovators with large musculoskeletal and cardiovascular platforms. The landscape is not yet consolidated around a single material class, but it is increasingly segmented by evidence depth, regulatory positioning, and application focus. Understanding how the leading players position themselves helps clarify where value is being created and where openings remain.
Among the specialty innovators, Bioretec has emerged as a notable example of a focused strategy centered on fully absorbable orthopedic implants. The company has pursued regulatory milestones in parallel with portfolio expansion, including CE mark approvals for trauma screw products, FDA Breakthrough Device Designation for a magnesium alloy drill pin, and continued commercialization of PLGA-based Activa implants for trauma and pediatric applications. These moves reflect a deliberate pathway strategy: pair magnesium fixation with polymer options where mechanical or resorption profiles differ, and build an evidence base that spans adults and children. Inion, another Finland-based specialist, has commercialized bioabsorbable and bioactive plates, screws, pins, and anchors across orthopedics, CMF, spine, sports medicine, and dental indications, with a substantial clinical footprint. Inion's approach emphasizes a broad polymer platform and cross-application reuse of material know-how, which allows it to serve multiple surgical specialties while maintaining a coherent product architecture. Syntellix has built its identity around magnesium alloy bioabsorbable screws and pins for orthopedic and trauma fixation, leveraging CE-certified metallic solutions and clinical use across multiple regions. Its positioning underscores the growing credibility of magnesium as a load-bearing resorbable option and the importance of demonstrating real-world fixation performance.
Large players are entering and scaling through complementary strategies. Medtronic offers bioresorbable technologies across orthopedic and cardiovascular applications, including vascular scaffolds and fixation solutions, leveraging broad distribution and clinical networks. Johnson & Johnson, through its medtech division, develops polymer-based bioresorbable fixation systems for orthopedics and CMF, aligning resorbable hardware with established surgical franchises. Stryker and Zimmer Biomet supply bioabsorbable implants and fixation devices for orthopedic trauma and sports medicine, integrating resorbable options into wider product portfolios. Smith+Nephew markets bioabsorbable implants for soft tissue repair and orthopedic applications, where temporary scaffolds can support healing without permanent hardware. In the cardiovascular space, Biotronik has developed resorbable magnesium scaffolds for coronary interventions, illustrating how degradable technology extends beyond fixation into vessel support and remodeling.
PW Consulting Health Care Research Center
Several strategic patterns distinguish the leaders. First, material-platform thinking is replacing single-product tactics. Companies that can adapt a polymer or magnesium base across trauma, pediatrics, CMF, spine, or dental applications gain manufacturing leverage and clinical credibility simultaneously. Second, regulatory positioning is being used as a competitive moat. Early clearances, breakthrough designations, and well-documented degradation data create preference in formulary discussions and surgeon adoption cycles. Third, application breadth versus depth is a deliberate trade-off. Some specialists pursue deep evidence and regulatory traction in a narrow field to command premium positioning, while larger firms use resorbable lines to complement existing franchises and cross-sell into established procedural volumes.
Endosseous Implant Market
The market structure is evolving along three axes. Consolidation is likely in distribution and evidence generation, where scale matters for clinical studies, reimbursement files, and surgeon education. Differentiation is intensifying around degradation control, mechanical performance, and application-specific evidence. New entrants will continue to emerge where there are unmet indications or underserved geographies, but they will face the same evidence and supply expectations that define the leaders. The net effect is a competitive environment where technology alone is insufficient; credible clinical data, manufacturing consistency, and commercial execution determine who captures durable share.
4. Outlook: Three Trends to Watch Over the Next Three to Five Years
The next phase of market evolution will be defined by how companies convert material advances into repeatable commercial value. Three trends are particularly consequential.
1. Evidence-led adoption will become the primary growth lever. As more bioabsorbable products reach mature regulatory status, the differentiation shift moves from approval to adoption. Expect a rising emphasis on prospective registries, comparative studies against permanent hardware, and total-cost-of-care analyses that justify premium pricing. Manufacturers that publish robust, indication-specific outcomes will gain formulary momentum; those relying on mechanistic promises will face longer adoption cycles.
2. Material segmentation will deepen, with magnesium and polymers occupying distinct clinical lanes. Magnesium alloys will continue to expand in load-bearing fixation where rapid resorption and mechanical compatibility matter, while polymers will remain strong in applications requiring tunable degradation and softer tissue integration. The opportunity lies in matching material behavior to clinical timelines rather than treating bioabsorbable technology as a single category. Companies that articulate these lanes clearly will reduce misinterpretations and accelerate surgeon confidence.
3. Supply resilience and cost control will separate sustainable players from fragile ones. With raw material concentration and precision manufacturing requirements, the ability to manage alloy sourcing, purity, and scale consistency will increasingly influence margin stability. Expect more dual-sourcing strategies, long-term supply agreements, and internal process control investments. Pricing pressure will not disappear, but it will be offset by value demonstration and supply reliability rather than by cost competition alone.
These trends carry risk. Regulatory expectations may tighten further if post-market data reveal variability in degradation or inflammatory response. Reimbursement momentum could slow if health systems demand more localized cost evidence. Magnesium supply volatility may re-emerge, affecting planning and margins. Still, the directional signal is clear: the market is moving from novelty to execution, and the winners will be those who combine material innovation with credible evidence and dependable supply.
5. Strategic Moves for Decision Makers
For manufacturers, the priority is to build a coherent evidence-to-commercialization plan around a defined material and application strategy. That means selecting indications where degradation profiles and mechanical demands align, designing clinical studies that speak to total episode value, and securing supply pathways that can withstand raw material volatility. A narrow, well-supported indication can outperform a broad but thinly evidenced portfolio in both adoption speed and pricing power.
For investors, the most durable opportunities are likely in companies that pair regulatory traction with repeatable manufacturing and a clear value narrative. Look for credible biocompatibility data, evidence of mechanical equivalence across degradation timelines, and signs that premium pricing is being justified by reduced revision, removal, or rehabilitation burden. Diversified platforms with resorbable lines integrated into established surgical franchises may offer broader exposure, while focused specialists can deliver higher optionality if they secure and defend key regulatory and clinical positions.
For procurement and clinical leaders, the practical step is to structure evaluation criteria that compare total cost of care rather than unit price alone. Pilot programs should track revision rates, removal procedures, patient-reported outcomes, and downstream resource use, not just implant performance at the time of surgery. Where evidence supports it, bioabsorbable options can reduce long-term burden in appropriate indications, but that conclusion must be validated within local clinical pathways and reimbursement realities.
The market is moving quickly enough that portfolio decisions, partnership choices, and procurement frameworks need current, granular intelligence. A detailed report can map segment-level dynamics, company-by-company regulatory status, material cost structures, and application-specific adoption signals with the granularity needed for timing and prioritization decisions.
For detailed analysis of this topic, please visit the official page: Degradable Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com