

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Whetstones Market to Expand at 4.25% CAGR, Reaching $198.73M by 2032

The Whetstones Market in 2026: Strategic Intelligence for Precision and Edge Maintenance Industries
The global whetstones market is entering a phase of measured yet structurally significant expansion. As manufacturing floors, professional kitchens, and home hobbyists increasingly prioritize tool longevity and surface precision, sharpening stones have evolved from peripheral consumables into strategic SKUs that signal quality, consistency, and operational discipline. Our latest market research on the whetstones industry offers decision-makers a comprehensive, data-grounded map of where this category stands today and where it is headed through the end of the decade. Published with a 2025 base year and a forecast horizon extending to 2032, the study translates historical performance, material innovation, and competitive signaling into actionable intelligence for product strategy, sourcing, and market entry planning.
Why This Research Matters for 2026 Decision-Making
Strategic planning in 2026 requires more than top-line projections. Companies need to understand how demand is shifting across use cases, how material science is reshaping product performance expectations, and which competitive dynamics will determine pricing power and channel control in the years ahead. The whetstones market illustrates these pressures vividly. Historical data from 2020 through 2025 reveals a market that weathered volatility yet consistently rebounded toward growth, culminating in a global revenue base measured in the high hundred millions of U.S. dollars by 2025. Looking forward, our forecast models project a steady compound annual growth trajectory of 4.25 percent across the 2026 to 2032 window, with total market value climbing toward the vicinity of 200 million dollars by the close of the forecast period.
These figures are not merely descriptive. They serve as a strategic compass. A mid-single-digit CAGR in a mature, low-tech-adjacent category signals that growth will increasingly come from differentiation rather than broad category expansion. Manufacturers and distributors that rely on undifferentiated assortments will find themselves squeezed by margin pressure and channel consolidation. Conversely, organizations that align their portfolios with emerging performance standards, regional demand rhythms, and application-specific preferences will be positioned to capture share without relying on aggressive discounting. Our report is designed to help leadership teams make that distinction clear before capital is committed.
Equally important is what the research deliberately preserves for deeper analysis. While this overview communicates the trajectory and structural forces shaping the market, the full study reserves granular segmentation detail, regional volume and revenue distributions, and application-level breakdowns for readers who need to model entry strategies, allocation decisions, and competitive response scenarios. The intent is to provide enough rigor to establish credibility while ensuring that the most decision-critical intelligence remains within the complete report, accessible through our primary research portal.
Market Trajectory and Structural Signals
The historical record from 2020 to 2025 underscores a category that has matured without stagnating. Revenue moved from the 120 million-dollar range in 2020 into a tighter band through 2022 and 2023 before resuming a clearer upward path in 2024 and 2025. This pattern is consistent with a market absorbing supply-chain normalization, shifting procurement rhythms, and gradual demand recovery in both professional and consumer segments. The rebound in the most recent base-year figures reinforces the view that whetstones are no longer treated as discretionary gadgets but as maintenance essentials across multiple end-use environments.
Forward-looking, the forecast period from 2026 through 2032 projects incremental but durable expansion. The modeled trajectory points toward a total market value approaching roughly 199 million dollars by 2032, with year-over-year movement shaped by product innovation, application-driven demand, and regional purchasing patterns. Importantly, this expansion is not uniform across the board. Growth will be concentrated where performance benefits are most visible, where replacement cycles align with sharpening frequency, and where channel execution translates product quality into repeat purchases. Decision-makers should therefore interpret the headline CAGR as a directional anchor, not a guarantee of equal opportunity across all product types or customer groups.
A defining structural feature of this market is its moderate fragmentation. The top three competitors collectively hold approximately 21.4 percent of revenue, while the top five command around 29.8 percent. This concentration profile suggests a landscape where incumbents enjoy meaningful brand and supply advantages, yet there remains sufficient room for specialized players to win in niche applications or geographic pockets. For strategists, the implication is clear: competitive advantage in whetstones will increasingly depend on authenticity of material claims, consistency of sharpening performance, and the ability to serve distinct use cases rather than on scale alone.
What the Whetstones Market Report Covers
Our study is built around practical utility. It is intended to support product planners, category managers, sourcing leaders, and investor analysts who need a coherent narrative from raw material economics through end-user demand behavior. The report integrates the following functional layers:
- Historical performance data spanning 2020 to 2025, providing context for demand rhythm, recovery patterns, and base-year valuation.
- A forward forecast from 2026 to 2032 that models revenue progression, highlights inflection points, and clarifies the pace of category expansion.
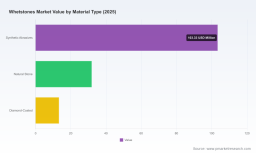
- A structured segmentation framework that examines the market by region, material type, and application, with interpretive guidance on where demand intensity and product mix are likely to diverge.
- A competitive landscape assessment that maps key manufacturers, their positioning, and the strategic implications of concentration and differentiation.
- An industry dynamics section that addresses raw material availability, regulatory considerations, and emerging product-testing signals influencing buyer behavior.
- Recent market developments and evaluation activity that reflect how consumer media, professional reviewers, and end users are shaping perceived product leadership.
Readers should note that while the overview presented here describes the architecture of the study, the full report contains the detailed split data and interpretive matrices needed to build region-specific entry plans, allocate SKUs across channels, and benchmark product strategies against peers. The complete segmentation values, regional revenue contributions, and application-level breakdowns are reserved for the report itself to ensure that strategic decisions are made with the full evidentiary context.
Competitive Landscape: Established Players and Specialized Entrants
The whetstones competitive field is defined by a blend of broad-abrasive manufacturers, heritage natural-stone producers, and precision-oriented specialists. This mix shapes both pricing logic and brand perception. On one side are companies with extensive abrasives portfolios that treat whetstones as part of a broader industrial and consumer sharpening ecosystem. On the other are organizations whose identity is anchored in geological sourcing, craftsmanship, or performance engineering, often commanding loyalty through perceived authenticity and consistency.
Major manufacturers with synthetic and natural sharpening portfolios play a pivotal role in setting performance expectations across industrial, professional, and consumer channels. Their scale, distribution reach, and ability to supply multiple material formats allow them to compete on availability, technical support, and product range. Alongside them, natural-stone specialists rooted in specific geological deposits maintain a differentiated value proposition based on material origin, grade consistency, and domestic manufacturing credibility. In certain segments, the control of quarry access and reserve longevity functions as a strategic moat, reinforcing both supply security and narrative authority around traditional performance.
The Japanese manufacturing cohort deserves particular attention. Firms specializing in high-performance ceramic stones, water whetstones, and precision abrasives have influenced global sharpening standards by emphasizing fast cutting behavior, user-friendly maintenance characteristics, and repeatable grit performance. Their product architecture has raised the bar for what buyers expect from a sharpening stone, particularly in professional culinary and precision tool contexts. As a result, competitive positioning increasingly hinges on how well a product communicates edge refinement quality, ease of use, and reliability under repeated sharpening cycles.
Further down the field, regional suppliers and distributors of specialized stones contribute to the market's mosaic by serving jewelry making, tool making, and other precision applications. Their role is often less about headline volume and more about enabling high-value craftsmanship workflows where consistency and surface finish matter disproportionately. For strategists evaluating partnerships, distribution agreements, or private-label opportunities, this layered competitive structure means that the right fit depends on application requirements, claim substantiation, and channel expectations rather than on a single dominant formula for success.
Industry Dynamics Shaping Demand and Supply
Several structural forces are influencing how the whetstones market will evolve over the forecast window. Raw material provenance remains central. For natural stones, the availability of specific deposits and the long-term control of reserves affect both supply continuity and brand storytelling. Where producers maintain secure access to high-quality geological sources, they can support consistent product grades and reinforce heritage positioning. In synthetic categories, the use of abrasives such as aluminum oxide or silicon carbide, bonded for stable grit performance across ceramic and resin-bonded formats, governs consistency and repeatability. Performance reliability in synthetic lines is becoming a key purchase criterion as users compare labor, maintenance, and sharpening outcomes across material types.
Regulatory and claim-substantiation dynamics also matter. In markets where domestic manufacturing claims carry legal and consumer-trust weight, producers must align sourcing, processing, and labeling with applicable standards. Compliance with recognized domestic content requirements can influence procurement decisions in government, institutional, and quality-conscious commercial settings, while also shaping brand perception among consumers who value origin transparency. Companies that proactively manage these claims while maintaining visible quality assurance processes can turn compliance into a differentiator rather than a constraint.
Demand-side signals from recent evaluation activity further illuminate where attention is flowing. Updated 2026 product testing and recommendation coverage has highlighted specific collaboration sets and starter systems as top performers based on edge performance metrics and practical usability. These independent assessments do more than endorse individual products; they reinforce consumer expectations around sharpening quality, ease of use, and system completeness. For manufacturers and retailers, such coverage functions as a market signal about which attributes are gaining salience and which product configurations are resonating with buyers in the current cycle.
Together, these dynamics suggest that the whetstones market will reward organizations that treat sharpening performance as a measurable value driver, that protect their material supply narratives with verifiable sourcing, and that stay responsive to how review ecosystems and professional testing influence buying criteria.
Winches Market
Strategic Implications for Product, Channel, and Sourcing Decisions
For companies operating in or entering the whetstones market, the strategic agenda in 2026 should center on three questions. First, how will the portfolio balance heritage and performance claims without diluting either? Natural-stone narratives and synthetic-consistency arguments can coexist in a single company's offering, but they require distinct positioning, quality documentation, and channel messaging. Blurring the two risks weakening trust with buyers who are increasingly attentive to material identity and claim accuracy.
Second, how should assortments be built for application reality rather than category averages? The whetstones market includes domestic and hobbyist use, professional culinary sharpening, and industrial or woodworking maintenance. Each environment places different demands on grit progression, surface behavior, durability, and ease of maintenance. A portfolio strategy that recognizes these distinctions will create more reliable repeat purchase behavior than one that relies on generic one-size assortments.
Third, where should growth be pursued given moderate concentration and uneven regional demand? The market's concentration profile leaves space for targeted expansion, but the most efficient path will vary by company capabilities. Some players will find value in deepening presence where their material identity and manufacturing footprint provide the strongest credibility. Others will benefit from aligning product offerings with the expectations set by recent testing and professional recommendations, using performance evidence to justify premium positioning or to accelerate adoption in underpenetrated user groups.
What the Full Report Delivers
This overview is intended to give executives a clear sense of the market's direction and the analytical depth available in the complete study. The full report extends this foundation into detailed segmentation figures, interpretive regional and application analyses, and a structured competitive assessment that links company profiles to strategic implications. It also integrates raw material context, regulatory considerations, and recent evaluation activity into a unified narrative that supports product roadmapping, channel planning, and sourcing strategy.
Whetstones Market
For teams that need to commit budget, define SKU architecture, assess partnership opportunities, or evaluate competitive response, the complete report provides the specificity required to move from directional confidence to executed strategy. The headline trajectory, structural signals, and competitive logic described here are only the starting point. The detailed intelligence behind them is available through our primary research page, where the full dataset and analytical commentary can be accessed in context.
Closing Perspective
The whetstones market in 2026 is best understood as a category where consistency, provenance, and performance perception now matter as much as price. Historical resilience, a mid-single-digit growth path, and a moderately concentrated competitive field create a landscape that rewards precise positioning and disciplined execution. Organizations that understand how material types, application needs, and claim standards interact will be better placed to build portfolios that hold their value as the market matures. Our research is designed to make that understanding operational, giving decision-makers the clarity required to act with confidence throughout the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Whetstones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com