

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
ESD Grounding Mats Market: Heading to $482.28M by 2032 at 6.25% CAGR

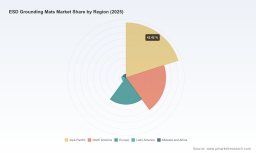
Navigating the ESD Grounding Mats Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Overview and Core Challenges
The global market for electrostatic discharge (ESD) grounding mats has reached a critical inflection point, driven by converging forces of electronics proliferation, regulatory tightening, and manufacturing modernization. Over the past five years, revenue expansion has been steady rather than explosive, reflecting the specialized nature of the product category and its deep integration into critical production environments. From a 2020 baseline, the market has grown through incremental capacity additions, material science improvements, and widening compliance requirements across high-value assembly sectors. Current projections indicate a compound annual growth rate of approximately 6.25 percent through the end of the decade, positioning the segment among the more resilient categories within the broader static control and cleanroom consumables ecosystem.
This growth trajectory is not uniform. Value creation is increasingly concentrated around product reliability, certification rigor, and lifecycle service models rather than raw volume. The industry is navigating a transitional phase where legacy procurement cycles collide with newer compliance expectations, material cost volatility, and substrate performance standardization. For decision-makers, the headline growth figure masks several structural shifts that will shape competitive positioning and purchasing economics over the next several years.
PW Consulting Health Care Research Center
One defining challenge is the tension between performance consistency and cost pressure. ESD grounding mats are precision-engineered consumables whose dissipation characteristics, tear resistance, chemical tolerance, and grounding integrity directly affect yield in sensitive assembly environments. Manufacturers and end-users face the dual burden of sourcing materials that meet established resistance thresholds while managing budget constraints. As raw material pricing fluctuates—most notably in natural rubber benchmarks and synthetic rubber indices—the margin between premium performance and acceptable compliance becomes a strategic negotiation rather than a fixed specification. Operators must determine whether to standardize across lower-cost homogeneous designs or invest in multi-layer architectures that offer improved durability and ergonomic properties at a higher acquisition cost.
Another structural challenge lies in certification complexity and verification cadence. The acceptance of ESD matting into qualified production environments increasingly depends on documented conformance, traceable testing records, and routine verification protocols. Organizations operating under strict electrostatic protected area (EPA) frameworks are expected to maintain meticulous records of mat performance, grounding continuity, and periodic inspection schedules. This has transformed what was once a transactional equipment purchase into a compliance-driven operational requirement. Procurement teams that treat matting as a commodity often encounter hidden costs related to rework, documentation, training, and downstream audit risk. The distinction between a product that simply claims compliance and one that supports repeatable verification workflows is now a meaningful competitive differentiator.
A third challenge is the fragmentation of application-specific requirements. ESD grounding mats are no longer evaluated solely by resistance values. Electronic assembly floors, precision laboratory environments, medical instrumentation suites, and aerospace integration sites each impose distinct demands for chemical resistance, surface topology, anti-fatigue properties, and physical wear cycles. Suppliers that attempt to serve all applications with a single product architecture struggle to maintain relevance as end-users increasingly match substrate design to operational context. The market is therefore bifurcating between generalized compliant products and engineered solutions calibrated for specific handling conditions, operator fatigue considerations, and cleaning regimes.
Worldwide ESD Packing Market
Taken together, these dynamics suggest that the market's next phase of expansion will reward operators who can align material performance, verification support, and application-specific engineering with procurement practicality. Growth will remain robust, but competitive advantage will shift toward reliability documentation, lifecycle economics, and the ability to translate compliance language into operational outcomes.
Key Growth Drivers Reshaping the Market
Three to four underlying forces are propelling the ESD grounding mats market forward, and their interaction defines where value will compound most quickly over the coming years. These drivers are not isolated; each one amplifies the strategic relevance of the others.
Material and Manufacturing Innovation
Advancements in substrate engineering have become one of the most practical catalysts for market evolution. The category now spans homogeneous vinyl constructions, reinforced rubber architectures, and layered designs engineered for durability, chemical resilience, and ergonomic comfort. Multi-layer rubber constructions contribute to longer service life under heavy operator traffic while supporting controlled dissipation within required thresholds. At the same dependent point, material cost volatility keeps pressure on pricing strategies. Recent benchmarks in natural rubber and synthetic rubber indices illustrate that input cost movements can influence both supplier margin and buyer willingness to adopt higher-performance formats. Companies that can decouple performance from cost sensitivity—through optimized layer structures, improved wear resistance, or longer replacement cycles—gain a structural advantage in procurement-heavy environments.
Regulatory and Standards Alignment
Regulatory expectations continue to elevate the technical baseline for ESD matting. Frameworks such as ANSI/ESD S20.20 and IEC 61340 remain the dominant reference points for controlled dissipation, with resistance-to-ground boundaries guiding worksurface and flooring eligibility. More significantly, verification expectations have moved from periodic certification toward daily or routine checks for footwear and mat grounding continuity within EPA environments. This does not simply raise the technical bar; it reshapes purchasing logic. Buyers increasingly favor products that simplify compliance documentation, support traceable testing, and integrate into inspection workflows. Recent product certifications emphasizing individual testing, serialization, and alignment with updated standards illustrate how manufacturers are turning compliance into a commercial asset. As semiconductor and electronics manufacturing capacity expands, the demand for matting that satisfies updated IEC and ANSI frameworks becomes a direct operational requirement rather than a best-practice preference.
Demand-Side Shifts in Electronics and Advanced Manufacturing
Demand growth is increasingly shaped by sector-specific production expansion rather than generic industrial consumption. Electronics manufacturing remains the dominant application driver, reflecting the sensitivity of assembly processes to static discharge and the scale at which modern production lines operate. Aerospace and defense applications contribute meaningfully as well, particularly where precision integration, rigorous inspection cultures, and controlled work environments are standard. Healthcare and laboratory settings add further demand for ESD-safe surfaces, especially where sensitive instrumentation, diagnostic equipment, and clean handling protocols intersect. The commercial implication is clear: matting demand is tied to capital expansion in high-value manufacturing and to compliance-sensitive handling in regulated environments. As new fab capacity, aerospace programs, and laboratory infrastructure come online, ESD grounding mats move from optional safeguarding to integral production support.
Supply Chain and Procurement Model Evolution
Procurement behavior is shifting from single-transaction buying to lifecycle management. Operators are becoming more attentive to replacement frequency, inspection support, chemical and heat resistance, and the operational cost of downtime or rework triggered by premature mat failure. Simultaneously, suppliers are responding with more prescriptive selection guidance, testing references, and application-specific recommendation frameworks. Updated selection guides tested against recognized standards reflect an industry-wide move toward helping buyers navigate compatibility rather than simply supplying a catalog SKU. This evolution benefits suppliers that can provide clear technical justification, consistent quality, and documentation support, while exposing those that compete purely on price without maintaining compliance or service infrastructure.
These overlapping drivers create a market where technical credibility, standards alignment, and procurement practicality collectively determine share gain.
Competitive Landscape and Leading Strategies
The competitive field in ESD grounding mats is defined by a mix of specialized manufacturers, diversified safety-product groups, and larger industrial suppliers with broader static-control portfolios. Market concentration remains moderate rather than highly consolidated, which gives room for differentiated positioning and application-specific wins. Several companies have built recognizable identities by emphasizing certification rigor, product architecture, and ergonomic or chemical-resistance features.
Anti-static Floor Market
Desco Industries has maintained a strong profile through a focused offering of ESD worksurface mats, floor mats, and grounding solutions that align with ANSI/ESD expectations across vinyl and rubber dissipative formats. Its positioning leans on protocol familiarity, broad worksurface support, and established integration within electronics handling environments. ACL Staticide differentiates with dual-layer and homogeneous options that emphasize chemical and heat resistance, making its matting particularly relevant where exposure to cleaning agents or elevated surface stress is common. Botron's emphasis on multi-layer rubber table mats, including proprietary three-layer designs, targets durability and ergonomic function, appealing to environments where operator comfort and product service life carry direct financial weight. NoTrax, operating within a broader safety group, addresses industrial and electronics workplaces through anti-fatigue and anti-static mat series that combine static control with workplace ergonomics. 3M contributes through a portfolio approach that places ESD grounding mats within a wider static-control and worksurface protection ecosystem, enabling potential cross-selling and integrated environmental planning.
Recent industry actions clarify how competition is intensifying on compliance and guidance rather than on price alone. One manufacturer introduced an ESD bench mat kit built around individual testing, serialization, and certification to current standards, signaling a move toward traceable, verifiable compliance as a value proposition. Another supplier released an updated comparison and selection guide oriented around testing against IEC standards for electronics manufacturing, reflecting a strategic bet that helping buyers navigate compatibility will strengthen loyalty and reduce purchase friction. A technical organization also published guidance on testing frequency and alignment with major ESD frameworks, reinforcing the expectation that routine verification is now part of acceptable operational practice. Together, these developments indicate that the market is rewarding suppliers who support documentation, inspection discipline, and application-matched selection.
The competitive landscape is likely to continue evolving along two parallel tracks. On one side, consolidation may increase as larger industrial safety and static-control players absorb niche capabilities or distribution reach, particularly where complementary product lines can be bundled. On the other side, specialization will remain powerful because application requirements differ too widely for a single product to dominate all use cases. New entrants that focus on verification enablement, material durability, or codified selection support can establish meaningful positions without needing broad portfolios, provided they can demonstrate repeatable performance under recognized standards. For buyers and investors, the practical implication is that the most defensible advantages are emerging around compliance support, material performance predictability, and the ability to reduce hidden operational risk.
Future Trends and Commercial Implications (2026–2032)
Looking ahead three to five years, several trends are likely to shape both demand composition and supplier viability. The first is a continued premiumization of compliance-oriented products. As verification expectations become more operationally embedded, suppliers that offer serialized testing records, clear certification alignment, and straightforward inspection workflows will capture a disproportionate share of regulated environments. This trend expands commercial opportunities for products that make audit readiness easier, but it also raises the bar for market entry because documentation capability becomes as important as material performance.
The second trend is application-specific product design gaining share over generic compliance matting. Environments that combine static control with chemical exposure, ergonomic fatigue concerns, or heavy traffic will increasingly favor engineered substrates over basic dissipative surfaces. This shift creates opportunities for differentiated architectures—such as multi-layer rubber formats or chemically resistant homogeneous designs—but also introduces complexity for buyers who must match specifications to real operating conditions rather than to a one-size-fits-all product line.
The third trend is cost and input volatility becoming a more visible strategic variable. Rubber pricing movements and synthetic material indices can compress margins or shift buyer sensitivity toward lower-cost alternatives at exactly the moments when compliance demands are rising. Suppliers that can manage material exposure, extend service life, or demonstrate lower total cost of ownership through reduced replacement frequency will be better positioned to retain share during pricing cycles. The associated risk is that price competition could intensify in commoditized segments, especially if procurement teams face budget pressure while still needing to meet minimum compliance thresholds.
These trends point to a market where growth remains attractive, but value will accrue to operators who can translate technical credibility into procurement efficiency, compliance simplicity, and application-fit reliability.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority should be to strengthen verifiable performance claims and make compliance support part of the product story rather than an afterthought. Serialization, traceable testing, and selection guidance aligned with recognized standards are no longer optional differentiators in regulated environments. Suppliers should also evaluate whether their product architecture supports distinct application profiles so that buyers can justify performance features in procurement language that connects to yield, durability, and audit readiness.
For investors, the most resilient exposure will likely come from companies that combine material durability with compliance enablement and have clear positioning in electronics manufacturing, aerospace, or laboratory workflows. Market growth is stable, but the winners will be those that can defend share through documentation support and application-fit engineering rather than through price alone. Evaluating exposure to raw material volatility and the ability to extend replacement cycles should be part of any investment screening in this segment.
For procurement leaders and operations managers, the practical move is to shift from purchasing a compliant item to managing a verified ESD control point. That means specifying products with clear resistance alignment, planning for routine verification, and reconciling acquisition cost against replacement frequency, chemical exposure, and operator fatigue. Selecting matting based on documented inspection support and application compatibility often reduces downstream risk more effectively than selecting based on unit price alone. More detailed segmentation, scenario-based pricing implications, and supplier-level comparison data can help refine these choices; for deeper analysis, the full PW Consulting research report provides expanded breakdowns and customized decision support.
For detailed analysis of this topic, please visit the official page: ESD Grounding Mats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com