

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Trigger Point Injection Market to Reach $320.2M by 2032, CAGR 5.85%

Beyond the Pain Point: Strategic Intelligence for the Trigger Point Injection Treatment Market in 2026 and Beyond
The global landscape for pain management is undergoing a structural shift, driven by an aging population, the rising prevalence of musculoskeletal disorders, and a persistent move toward minimally invasive therapeutic interventions. Within this broader ecosystem, the trigger point injection treatment market stands out as a critical segment for investors, service providers, and pharmaceutical manufacturers seeking sustainable growth in the chronic pain sector. At PW Consulting, we have just published a comprehensive market research study designed to cut through the noise of general industry forecasts and deliver actionable intelligence for the 2026 decision-making cycle.
This study is not merely a collection of historical data points. It is a strategic roadmap built to help organizations anticipate the regulatory, clinical, and competitive shifts that will define the market through the end of the decade. As healthcare systems increasingly prioritize cost-effective outpatient solutions, understanding the precise trajectory of trigger point injections is essential for allocating capital, refining service portfolios, and securing competitive advantage.
Market Trajectory and Growth Dynamics
Our analysis captures a market that has demonstrated consistent resilience and expansion over the past half-decade. Tracking revenue figures from 2020 through the base year of 2025, the data reveals a steady upward climb from approximately 165.2 million USD to a projected 215.0 million USD in the current year. This historical performance sets a robust foundation for the forecast period extending from 2026 to 2032.
Looking ahead, we project the market to reach a valuation of 320.2 million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.85 percent. For strategic planners, this figure represents more than aggregate expansion; it signals a maturing market where volume increases are complemented by evolving clinical standards and reimbursement scrutiny. The transition from 2025 to 2026 alone marks a notable inflection point, with revenue expected to jump to 233.37 million USD, reflecting pent-up demand and the gradual normalization of procedural volumes post-pandemic.
It is crucial for stakeholders to recognize that this growth is not uniform across all vectors. The total market size is the sum of distinct drivers involving specific agent types, clinical indications, and geographic regions. While our full report deconstructs these segments in granular detail, the aggregate trend confirms that demand is being fueled by a combination of established clinical protocols and emerging procedural training initiatives. Organizations that understand how these specific vectors interact will be best positioned to capture value.
Competitive Landscape and Key Participants
The competitive environment in the trigger point injection space is characterized by a mix of specialized pain management clinics, multidisciplinary health groups, and medical device manufacturers. Our report profiles key players who are actively shaping the market through service delivery, equipment supply, and clinical standardization.
On the service delivery side, organizations such as Paragon Health Group, Encore Health Group, Premier Pain & Spine, Synergy Health Partners, and the Cleveland Clinic are central to the ecosystem. These entities provide trigger point injections as part of broader pain management services, often focusing on myofascial pain relief, symptomatic pain relief in musculoskeletal conditions, or comprehensive non-surgical pain management. Their operational models and patient volumes contribute significantly to the market's service-based revenue streams.
Complementing these service providers is a critical component of the supply chain represented by manufacturers like B. Braun Melsungen AG. Companies in this tier supply the essential needles and injection equipment, such as ultrasound-guided systems, that enable precise and effective procedures. The interplay between procedural providers and equipment suppliers creates a dynamic where innovation in delivery tools often precedes or enables wider adoption of specific injection techniques.
Trigger Point Injection Treatment Market
Market concentration analysis indicates a fragmented yet structured competitive field. The top three companies hold a combined market share of 22.5 percent, while the top five account for 31.8 percent. This concentration level suggests that while no single entity dominates the entire spectrum, there is room for strategic consolidation or targeted market penetration by agile competitors. For new entrants or existing players looking to expand, identifying the gaps between these key players and leveraging specialized niches in agent delivery or regional service coverage is a viable path to growth.
Operational Opportunities and Service Expansion
For healthcare administrators and investors, the operational value of this market lies in its integration potential and the alignment with non-surgical care pathways. Trigger point injection procedures are frequently bundled with physical therapy, medication management, and patient education programs. Our research explores how service providers are maximizing revenue cycles by positioning these injections within comprehensive care plans.
Several strategic opportunities emerge from our analysis:
- Service Line Optimization: Clinics are refining their protocols to align with the most frequently treated indications, ensuring that patient flow and inventory management for injection agents are tightly synchronized with demand patterns.
- Provider Training and Credentialing: As procedural techniques evolve, there is a growing emphasis on formal training and certification for providers. Organizations that support or participate in accredited training programs can enhance their reputation, ensure compliance, and capture referrals from a broader network of referring physicians.
- Equipment and Supply Chain Alignment: Facilities performing high volumes of trigger point injections require reliable access to specialized needles and imaging guidance tools. Strategic partnerships with equipment suppliers or bulk procurement agreements can significantly impact cost structures and operational throughput.
- Post-Procedure Care Integration: Extending the value proposition beyond the injection itself by offering structured follow-up and rehabilitation services helps improve patient outcomes and enhances the overall attractiveness of the service to payers and referral sources.
Our full report provides detailed breakdowns of how these operational levers are being applied across different segments of the market, including specific insights into agent utilization patterns and indication-based service frequency.
Industry Dynamics: Regulatory, Reimbursement, and Clinical Guidelines
No strategic assessment of the trigger point injection market would be complete without a deep dive into the regulatory and reimbursement environment. Market participants must navigate a landscape defined by evolving coverage policies, clinical consensus statements, and procedural billing requirements. Our study maps out the critical developments that are directly influencing patient access and provider behavior.
A significant recent development is the publication of multi-society guidelines by the American Society of Regional Anesthesia and Pain Medicine (ASRA) in March 2025. These guidelines address the use of corticosteroids in trigger point injections for adult chronic pain interventions, with specific attention to dosing strategies. Notably, the guidance highlights that lower doses of corticosteroids may provide similar benefits to higher doses, a finding that has profound implications for inventory planning, cost management, and clinical protocol design. Following this, in May 2025, major payer Anthem updated its medical policy (CG-SURG-17) to reference these 2025 multi-society guidelines, signaling a swift alignment between clinical standards and coverage criteria.
Reimbursement dynamics also play a pivotal role in shaping market behavior. Trigger point injection procedures billed under CPT codes 20552 and 20553 are covered when criteria for myofascial pain are met, but there are strict limits on frequency and number of sessions. More specifically, Medicare Local Coverage Determinations (LCDs) limit trigger point injections to no more than three sessions per rolling 12 months for medically necessary myofascial pain treatment. These constraints force providers to optimize the timing and composition of their interventions, balancing clinical need with compliance requirements. The coding and billing landscape requires meticulous documentation and adherence to medical necessity standards, making operational excellence in revenue cycle management a key differentiator.
On the education and workforce front, the American Academy of Procedural Medicine (AAOPM) announced ongoing trigger point injection training courses and certification for providers as of March 2026. This institutional investment in provider competency is likely to drive broader adoption of standardized, high-quality procedures and may influence payer perceptions regarding the appropriateness and consistency of trigger point injection services.
These dynamics interact in complex ways. For example, the interplay between clinical guideline recommendations on dose reduction and reimbursement limits on session frequency requires providers to carefully sequence treatments and potentially explore alternative agent combinations. Our report dissects these interactions to provide a clear picture of how market participants can adapt their strategies to remain both clinically effective and financially viable.
Strategic Imperatives for 2026 Executives
As we move deeper into the forecast period, executives across the value chain must make decisions that align with the market's underlying structural trends. The 5.85 percent CAGR and the projected expansion to 320.2 million USD by 2032 present clear growth opportunities, but realizing these opportunities requires more than passive participation in a rising tide.
Worldwide Intra-Articular Injection Market
For pharmaceutical and device companies, the data underscores the need for targeted engagement with clinical guidelines and payer policies. Understanding how corticosteroid dosing recommendations and session limits affect product utilization can inform marketing strategies, clinical education programs, and inventory forecasting. For service providers, the competitive landscape analysis highlights the importance of differentiation. With a CR3 of 22.5 percent, the market supports multiple players, but success will depend on demonstrating superior outcomes, efficient workflows, and compliance with the latest policy and guideline frameworks.
Additionally, the growing emphasis on provider training and certification points to an emerging ecosystem where quality metrics and professional credentials may increasingly influence referral patterns and payer contracting. Organizations that invest early in staff development and align their protocols with the most current multi-society guidance will likely secure a more resilient position as the market matures.
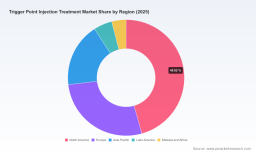
Our full Trigger Point Injection Treatment Market research study goes much further than the summary presented here. It contains detailed breakdowns of regional revenue distributions, agent type adoption rates, and indication-specific demand patterns that are essential for precise market entry, partnership evaluation, or investment due diligence. The analysis includes comprehensive competitor profiles, an exhaustive review of regulatory and reimbursement updates, and a forward-looking assessment of how clinical guideline shifts will reshape operational economics over the next several years.
In a market where clinical nuance, policy compliance, and competitive positioning converge, generic data is insufficient. Decision-makers need a granular, verified, and strategically contextualized view of the trigger point injection landscape. The PW Consulting report is designed to deliver exactly that level of insight.
We invite you to access the complete report for a full exploration of the data, the competitive profiles, and the strategic recommendations tailored to your specific role in the market. The full intelligence necessary to navigate 2026 and the forecast period through 2032 awaits.
For detailed analysis of this topic, please visit the official page: Trigger Point Injection Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com