

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
Gaucher Disease Market: Why 6% CAGR and High Concentration Reshape Strategy
By pmarketresearch, 2026-09-21
Navigating the Gaucher Disease Market: Strategic Trends and Commercial Opportunities (2025–2032)
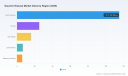
The Gaucher disease market has evolved from a niche orphan indication into a structured commercial landscape shaped by diagnostic maturation, expanded therapeutic options, and increasing payer scrutiny. Measured across recent historical years and extended through the forecast horizon, the global market reached approximately 168.56 million USD in 2025 and is projected to climb to 252.31 million USD by 2032, reflecting a compound annual growth rate of 6.0 percent. This trajectory is not merely a function of patient population growth; it is the result of deliberate therapeutic innovation, shifting reimbursement architectures, and regional access programs that progressively convert diagnosed patients into treated patients. For executives and investors, the opportunity lies in understanding where value is being created, where margin pressure is building, and how competitive positioning will reshape over the next several years.
Market Snapshot and Core Challenges
The current market structure reflects a concentrated but strategically dynamic environment. A small group of companies controls the majority of branded therapeutic volume, with top-three concentration exceeding 85 percent and top-five concentration approaching 95 percent. Such concentration typically signals high barriers to entry, entrenched clinical familiarity, and payer relationships built over years of treatment continuity. At the same time, the market is not static. Two simultaneous forces are redefining commercial logic: first, the expanding treatment envelope for non-neurological manifestations, particularly in Type 3 disease, which broadens the addressable patient pool for existing enzyme replacement therapies; second, the intensification of payer oversight, where preferred-product criteria and medical necessity documentation are increasingly shaping formulary access and prescribing behavior.
These forces introduce three core challenges for market participants.
- Therapeutic differentiation is narrowing in mature segments. Multiple recombinant enzyme replacement options and oral substrate reduction therapies now compete within similar clinical niches, making brand loyalty, service infrastructure, and real-world evidence increasingly decisive.
- Reimbursement frameworks are shifting from broad coverage to conditional access. Updated commercial insurance policies are introducing product preference criteria and stricter documentation requirements, which can compress uptake velocity even when clinical approval expands.
- Regional access remains uneven. While North America and Europe account for the largest share of revenue, Asia Pacific, Latin America, and Middle East and Africa represent smaller but strategically important corridors where local approval, reimbursement inclusion, and supply reliability determine whether innovation translates into commercial scale.
For decision-makers, the strategic implication is clear. The market is large enough to support specialized players, but growth will increasingly depend on access navigation, evidence generation, and therapeutic adjacency rather than on undifferentiated presence in established indications.
Key Drivers Shaping Market Dynamics
Therapeutic Innovation and the Push Toward Neurological Indications
Innovation is moving beyond symptomatic control of visceral and hematologic manifestations toward addressing neurological involvement, which has historically represented a major unmet need. The most visible signal is the progression of venglustat through late-stage clinical evaluation, including a Phase 3 trial that met all primary endpoints for Type 3 Gaucher disease and subsequent regulatory designation intended to expedite review for neurological manifestations. This trajectory matters because neurological indications reconfigure both clinical value and commercial scope. They create a potential market expansion beyond the patient segments traditionally served by enzyme replacement therapy and substrate reduction therapy, and they raise the strategic stakes for companies that can deliver central nervous system penetration with manageable safety and dosing profiles.
Even where approvals are not yet final, the development path demonstrates how pipeline momentum can influence market expectations. Positive clinical signals and breakthrough designations shape physician interest, patient advocacy priorities, and payer preparedness, all of which affect how quickly a new option may be adopted once regulatory clearance is secured.
Regulatory Label Evolution and Broader Access Pathways
Regulatory action is expanding the practical use of existing therapies. Recent label expansion for Cerezyme to cover non-central nervous system manifestations of Type 3 Gaucher disease in adults and pediatric patients illustrates how regulatory clarity can open reimbursement pathways that were previously constrained by narrower indications. In parallel, regional market access developments are altering the commercial map. In China, inclusion of a domestically developed recombinant enzyme replacement therapy in a commercial health insurance innovative drug list represents a meaningful step toward broader affordability and utilization. These milestones show that label scope and reimbursement inclusion are tightly coupled: broader labels provide the clinical rationale, while insurance inclusion enables the economic pathway.
The commercial lesson is that regulatory success alone does not guarantee traction. Label expansions must be paired with payer education, documentation support, and, in some markets, local pricing and distribution strategies that align with insurance architecture. Companies that treat regulatory milestones as access enablers rather than standalone achievements are better positioned to convert approvals into utilization.
Demand-Side Behavior and Diagnostic/Uptake Patterns
Demand in Gaucher disease is shaped by a mix of rare-disease dynamics and evolving care pathways. Improved diagnostic awareness, registry participation, and long-term disease management programs are gradually increasing the share of diagnosed patients who receive treatment. At the same time, clinicians are becoming more selective about therapy selection, weighing route of administration, infusion burden, oral availability, and tolerability. This selectivity is especially visible in the coexistence of enzyme replacement therapy and substrate reduction therapy, where oral convenience and infusion logistics create different value propositions for different patient profiles.
Additionally, real-world evidence is increasingly influencing prescribing confidence. Registry-based data and post-marketing experience provide context that clinical trials alone may not capture, particularly for long-term outcomes and specific patient subgroups. As treatment decisions extend over years, evidence continuity becomes a commercial asset, reinforcing adherence, supporting payer conversations, and strengthening brand trust.
Worldwide Biotinidase Deficiency Market
Supply Infrastructure and Cost Considerations
Cost structure and manufacturing technology remain important differentiators. Plant cell expression platforms, for example, have enabled alternative production routes for certain recombinant enzymes, with potential implications for supply resilience, cost efficiency, and product availability. In a market where therapy is often chronic and demand can be sensitive to supply interruptions, manufacturing diversity can translate into commercial reliability. At the same time, payer pressure on pricing and preferential product criteria means that cost efficiency is not only an operational concern but also a market-access concern. Companies that can connect manufacturing advantage to value-based positioning are better equipped to defend share in an environment where payers are increasingly selective.
Zellweger Spectrum Disorders Market
Competitive Landscape and Leading Strategies
The competitive field is led by companies with well-established branded franchises and distinct strategic angles. Sanofi maintains a strong position through a dual approach: a long-standing enzyme replacement therapy franchise and an oral substrate reduction therapy option, supplemented by late-stage neurological pipeline activity. Its recent moves, including label expansion for non-CNS Type 3 manifestations and breakthrough therapy designation for neurological disease, reflect a strategy of extending the therapeutic footprint while preparing for higher-value neurological indications.
Takeda represents a focused enzymatic franchise strategy with a recombinant enzyme approved for long-term treatment across pediatric and adult patients. Pfizer’s position is notable for its connection to plant cell technology, with a recombinant enzyme commercialized in most markets under a partnership model. This arrangement highlights how manufacturing technology and commercial partnerships can combine to create differentiated supply and market access dynamics. Johnson & Johnson participates through an oral substrate reduction option intended for patients when enzyme replacement therapy is not suitable, reinforcing the role of oral therapy as a strategic alternative in specific clinical scenarios.
A parallel dynamic is emerging in regional markets. CANbridge has advanced a domestically developed recombinant enzyme replacement therapy, with regulatory approval in China and recent inclusion in a commercial health insurance innovative drug list. This illustrates a broader trend: regional players can build relevance by aligning product development with local approval pathways and reimbursement programs, even in a market where global brands dominate overall revenue.
Several strategic patterns are shaping the competitive trajectory.
- Portfolio extension over single-product dependence. Leading companies are investing in adjacent indications and new modalities rather than relying solely on mature enzyme replacement franchises.
- Access-aware commercialization. Label updates and reimbursement inclusion are being used as coordinated levers, not isolated events, especially in markets where payer policy directly influences utilization.
- Evidence-led differentiation. Real-world data from registries and long-term clinical follow-up are becoming important tools for reinforcing therapeutic choice, particularly where head-to-head differentiation is limited.
- Regional market building. In markets such as China, local approval, insurance inclusion, and domestic development can create credible positions even where global concentration is high.
Looking ahead, the landscape is likely to experience both consolidation pressure and selective differentiation. High concentration favors incumbents with established service networks, payer relationships, and long-term patient follow-up systems. However, breakthrough designations, new neurological indications, and regional reimbursement advances create openings for companies that can combine scientific credibility with access execution. New entrants will face the challenge of proving clinical and economic value in a space where therapeutic familiarity and payer preference are already entrenched.
Future Trends and Commercial Implications (2026–2032)
Neurological indications as a value-creation frontier
Over the next several years, the most consequential opportunity is likely to come from therapies that address neurological manifestations of Gaucher disease. If late-stage development and regulatory pathways continue to advance, the market could see a shift in differentiation from primarily visceral and hematologic control toward central nervous system impact. This would expand the commercial relevance of substrate reduction approaches and potentially reshape prescribing priorities for Type 3 disease. For manufacturers, the trend suggests a need to prepare clinical narratives, endpoint strategies, and payer engagement plans around neurological outcomes, not just traditional disease markers.
Access policy as a growth regulator
Reimbursement policy will increasingly act as a growth regulator. The emergence of preferred-product criteria, medical necessity requirements, and periodic coverage revisions indicates that payers are moving toward more conditional access models. In practice, this means that market growth will depend not only on approval and clinical efficacy but also on documentation readiness, formularies, and channel-specific contracting. Companies that invest early in payer education and real-world evidence packages are more likely to maintain uptake stability when coverage policies tighten.
Regional market acceleration through insurance inclusion
In select regions, insurance inclusion and local development are likely to accelerate utilization more rapidly than global revenue trends alone would suggest. Where innovative drug lists, commercial insurance coverage, or domestic approval pathways reduce access barriers, local markets can scale faster and become more strategically relevant. This creates opportunities for companies that can combine product availability with localized pricing, distribution, and patient support models. It also raises the importance of monitoring regional policy changes, since inclusion events can alter demand trajectories quickly.
Risk and uncertainty
Several risks should temper optimistic projections. First, neurological indications may deliver clinical promise without the convenience, safety, or outcome differentiation needed for rapid adoption. Second, payer policy could become more restrictive, particularly if cost pressures intensify or if preferred-product frameworks narrow the practical choices available to prescribers. Third, competitive similarity in mature enzyme replacement segments may lead to price and service competition that erodes margin even as overall market size grows. Finally, regional access progress can be uneven, with policy reversals or pricing constraints slowing uptake in otherwise promising markets.
Strategic Implications for Decision-Makers
For manufacturers and therapy developers
Prioritize evidence continuity. In a market where treatment spans years and payer scrutiny is rising, registry participation, real-world data, and long-term safety information can be as commercially important as trial results. Build access-ready launch plans that treat label expansion, reimbursement inclusion, and payer policy as interconnected milestones rather than separate events. For companies with neurological pipeline assets, align endpoint strategy and market preparation early so that scientific progress can translate into reimbursement readiness. For incumbents in mature segments, differentiate through service quality, supply reliability, and patient support infrastructure, since product similarity raises the value of non-clinical advantages.
For investors and portfolio strategists
Focus on indication expansion and access execution rather than headline market size alone. The projected growth path is meaningful, but the highest value may accrue to assets that can extend into neurological indications, secure favorable reimbursement positioning, or gain regional inclusion efficiently. Evaluate competitive durability by examining concentration, payer preference, and the strength of long-term patient relationships, since these factors shape margin resilience. Monitor regulatory designations, label expansions, and insurance inclusion events as leading indicators of near-term commercial shifts, especially where policies are changing on short cycles.
For procurement, market access, and hospital 의사결정 teams
Treat formulary and contracting decisions as dynamic. Preferred-product criteria and medical necessity requirements are becoming more common, so procurement strategies should account for documentation demands, product availability, and the relative role of oral versus infusion-based therapy in specific patient populations. Use real-world evidence and registry insights to support selection when therapeutic differentiation is limited. Keep attention on supply reliability and regional access programs, particularly where local insurance inclusion may expand utilization quickly and create demand for predictable supply and robust patient management.
PW Consulting Health Care Research Center
Conclusion
The Gaucher disease market is entering a phase in which growth is increasingly determined by therapeutic expansion, access policy, and evidence-led differentiation rather than by baseline prevalence alone. The combination of neurological pipeline progress, label and reimbursement developments, and regional market inclusion is reshaping where commercial value will be captured between 2025 and 2032. Concentration remains high, but that does not eliminate opportunity; it simply raises the bar for companies that must justify therapeutic choice, defend payer access, and build durable patient relationships.
For executives, investors, and access professionals, the critical task is to interpret these shifts in time to act. The details that matter most—segment-level demand patterns, regional reimbursement dynamics, competitive positioning by therapy type, and policy-driven access constraints—are often obscured in high-level summaries. Readers seeking a deeper, decision-ready view of these dimensions can refer to the full PW Consulting Gaucher Disease Market report, where more granular segmentation, scenario considerations, and customized strategic implications are available for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Gaucher Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Organic Dairy Products Market: Why 5.37% CAGR and $30.96B by 2032 Redefine Growth
By pmarketresearch, 2026-09-21
Organic Dairy Products Market: Strategic Trends and Commercial Opportunities Through 2032
A Market Intelligence Perspective for Executives, Strategists, and Investors
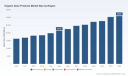
The organic dairy sector has moved from a niche premium segment into a structural component of the broader dairy economy. Over the past five years, the market has expanded from roughly $16.3 billion in 2020 to approximately $21.5 billion in 2025, reflecting sustained demand for certified organic milk, yogurt, cheese, butter, and cream across retail and foodservice channels. Forward projections indicate the market will reach approximately $31.0 billion by 2032, supported by a compound annual growth rate of 5.37 percent. This trajectory signals more than incremental premiumization; it reflects a durable shift in how consumers, retailers, and food manufacturers think about sourcing, labeling, and product formulation.
For decision-makers, the strategic question is no longer whether organic dairy will continue to grow, but how the growth will be distributed across product categories, channels, and geographies, and which operational capabilities will separate scalable operators from those squeezed by input costs, regulatory shifts, and quality-control pressures. The following analysis outlines the market’s current shape, the forces reshaping it, the competitive playbook of leading firms, and the trends that will define commercial opportunities over the next three to five years.
Market Context and Core Challenges
The organic dairy market has demonstrated consistent expansion, but the pace and composition of that growth vary meaningfully by product type and distribution path. Fluid milk remains the largest revenue contributor, followed by yogurt, cheese, butter, and cream. Supermarkets and hypermarkets continue to dominate volume distribution, while specialty stores and online channels represent smaller but strategically important pathways for brand building, margin management, and direct consumer engagement. Regionally, North America accounts for the largest share of market value, with Europe, Asia Pacific, Latin America, and the Middle East and Africa each representing distinct growth profiles shaped by local certification norms, retail infrastructure, and consumer familiarity with organic labeling.
A market of this scale and maturity is not immune to friction. Three challenges stand out as particularly consequential for operators and investors.
- Input cost volatility and margin pressure. Organic feed costs have remained elevated and uneven, with organic corn, soybean, and grain prices moving in ways that complicate budgeting for dairy producers and processors. Because organic systems depend on certified feed and pasture-based management, cost shocks translate quickly into producer economics and, ultimately, into pricing strategy for branded and private-label products.
- Supply utilization and demand balance. Recent federal milk marketing order data show organic whole milk utilization declining from one year to the next in key markets, even as the broader category continues to expand. This points to a market where aggregate growth can coexist with short-term utilization softness, channel shifts, or competitive substitution. Operators need to read utilization signals carefully rather than assuming uniform tailwinds.
- Quality assurance and reputational risk. Voluntary recalls across organic fluid milk and premium ice cream products in recent months highlight the operational reality that scale, packaging complexity, and production lot control can create exposure. In a category where trust is tied directly to certification and ingredient integrity, quality incidents can have outsized brand and retail-consequence effects.
These challenges do not undermine the market’s growth thesis, but they raise the bar for execution. Companies that can manage feed-cost exposure, interpret utilization trends with granularity, and maintain rigorous quality systems will be better positioned to convert category growth into stable margin performance.
Key Drivers Reshaping the Market
The expansion of organic dairy is being pulled by a combination of consumer behavior, regulatory clarity, supply-chain economics, and product innovation. Understanding how these forces interact is essential for strategic planning.
Consumer Demand and the Premiumization-Trust Matrix
Demand for organic dairy is no longer driven solely by price-insensitive premium buyers. A broader consumer base now treats organic certification as a baseline expectation for certain product categories, especially fluid milk and yogurt consumed by families, children, and health-conscious shoppers. This shift changes the commercial logic of the category: organic is increasingly a table-stakes attribute rather than a marginal differentiator, which means brands must compete on formulation, flavor, convenience, and trust signals as much as on certification itself.
At the same time, demand is increasingly shaped by nutritional and functional positioning. Products associated with omega-3 fortification, DHA, protein content, and clean-label profiles are gaining attention, particularly in shelf-stable and kid-facing formats. That creates opportunity for differentiated SKUs, but it also raises formulation and packaging complexity, which can increase quality-control risk if not managed carefully.
Regulatory Clarity and Certification Economics
Regulatory frameworks continue to shape both market access and operating costs. The Origin of Livestock final rule, effective from mid-2022, established more uniform standards for livestock transition and ongoing management, reducing ambiguity around what qualifies as organic dairy production. For the industry, clearer rules can improve confidence in labeling and reduce fragmented interpretations across buyers and suppliers, but they also require producers and handlers to align operations with consistent standards.
Organic Milk (Organic Milk Products) Market
Certification costs remain a practical consideration for smaller producers and new entrants. Programs that reimburse a significant share of certification fees can lower barriers to entry and help sustain a diversified producer base. For strategists, this matters because the long-term health of the organic dairy supply base depends on whether smaller farms and regional processors can remain economically viable alongside larger integrated operators.
Feed Costs, Grain Markets, and Producer Economics
Organic feed markets have their own price dynamics, and those dynamics influence the entire value chain. Recent reporting shows organic feed corn and soybean prices at elevated levels, with organic soft red winter wheat also trading at premiums in certain report periods. These input costs affect farm-level margins, milking herd decisions, and the economics of expansion or contraction in organic production.
For processors and brand owners, this environment underscores the importance of stable supplier relationships, forward contracting where feasible, and pricing strategies that can absorb input volatility without eroding consumer accessibility. For investors and strategic planners, feed-cost trends are not merely an agricultural issue; they are a structural factor in channel pricing, product rollouts, and the attractiveness of vertical integration.
Product Innovation and Channel Evolution
Innovation in organic dairy is moving along multiple paths. One is functional enhancement, such as omega-3 and DHA-enriched milk, which expands the category’s appeal beyond basic organic certification. Another is format expansion, including shelf-stable boxes, specialty ice cream, and cultured products that broaden usage occasions. A third is channel diversification, with online and specialty-store pathways enabling brand experimentation, targeted merchandising, and higher-margin positioning even as supermarkets and hypermarkets remain the dominant volume channel.
The strategic implication is that growth is not limited to selling more of the same. Companies can create value by aligning product architecture with consumer occasions, using channel mix to manage margin and exposure, and ensuring that innovation does not outpace quality systems.
PW Consulting Health Care Research Center
Competitive Landscape and Leading Strategies
The organic dairy market remains moderately concentrated, with the top three players holding a modest share and the top five still leaving a substantial portion of the market in the hands of regional brands, cooperatives, and specialty producers. That structure matters because it suggests room for differentiation, niche leadership, and targeted consolidation rather than a single dominant playbook.
Strategic Positioning Among Leading Operators
Several firms illustrate distinct approaches to scale, supply-chain control, and category focus.
- Large-scale integrated processors. Some leading operators manage extensive organic herds and dedicated processing facilities, enabling them to supply a broad lineup of fluid milk, cheese, butter, and yogurt across B2B and retail channels. Their strategic advantage lies in supply continuity, brand reach, and the ability to serve national retail and foodservice requirements with a consistent organic supply base.
- Farmer-owned cooperatives. Cooperative models combine production scale with a structural alignment to organic farm members. These organizations often emphasize full supply-chain control, diversified product sets that can include milk, cheese, butter, oat milk, and eggs, and direct payment relationships with farmers. The cooperative model can support supply resilience and brand trust, particularly when consumer narratives value farmer partnership and regional identity.
- Category-focused and heritage brands. Some established brands have built long-running reputations around specific product categories such as yogurt, fluid milk, and cultured dairy, often with emphasis on regenerative or pasture-based production. Their advantage typically comes from category credibility, consumer trust, and the ability to command premium positioning through storytelling and quality signaling.
- Specialized processors with traceability strength. Certain regional creameries and processors compete by emphasizing full organic traceability, premium product lines, and product-extension into adjacent categories such as ice cream. Their strategy often depends on strong local or regional demand, brand authenticity, and precise execution in production and distribution.
These models are not mutually exclusive, but they highlight a central strategic tension: scale can support national distribution and cost efficiency, while differentiation can support margin, loyalty, and category leadership. The most resilient organizations often combine enough scale to secure supply and distribution with enough distinct positioning to avoid competing solely on price.
Recent Events as Strategic Signals
Recent developments in the market illustrate the operational and market-dynamic realities that strategists must factor into planning.
- Quality and packaging exposure. Voluntary recalls involving shelf-stable flavored milk and organic super premium ice cream products show how packaging integrity and foreign-material control can affect even well-established brands. The practical takeaway is that product safety, packaging validation, and lot control are not back-office concerns; they are commercially material to brand equity, retail relationships, and consumer trust.
- Utilization signals in fluid milk. Recent federal milk marketing order data showing a decline in organic whole milk utilization in a major market order suggests that growth at the category level can coexist with fluctuating demand at the product or channel level. Operators should treat utilization data as an early indicator of shifting buying patterns, inventory dynamics, or competitive pressure rather than as a simple growth proxy.
- Feed market conditions. Elevated organic feed pricing reinforces the need for disciplined cost management and supplier strategy. In practical terms, operators with strong forward visibility and diversified sourcing options are better equipped to navigate periods when certified grain and feed costs move sharply.
How the Competitive Landscape Is Evolving
Three directional trends are shaping the next phase of competition.
First, consolidation pressure is likely to persist where scale, distribution access, and supply-chain control confer advantages. Larger integrated players and cooperatives with broad farm networks can use volume and continuity to strengthen retail and foodservice relationships, which may create acquisition or partnership opportunities for regional brands seeking broader reach.
Second, differentiation will remain powerful in subcategories. Yogurt, functional milks, premium ice cream, and specialty cheese can support distinct brand positions, especially when paired with clear claims around sourcing, pasture-based production, or nutritional benefits. In these subcategories, success depends less on brute scale and more on formulation, trust, and channel execution.
Third, new entrants and adjacent players may continue to test specific formats or channels rather than attempting to compete across the full dairy spectrum. Online-first brands, functional-product specialists, and regional processors targeting high-trust consumer segments can carve out profitable positions without needing to match national-scale infrastructure immediately. The risk is that such entrants can be vulnerable to quality incidents, input-cost swings, or retail listing barriers if they do not build operational depth alongside brand appeal.
Outlook: Three Critical Trends for the Next Three to Five Years
Looking ahead to the 2026–2032 period, the organic dairy market is likely to be shaped by a combination of steady category expansion, continued input and quality challenges, and increasing strategic importance of differentiation and channel strategy.
1. Growth will continue, but the upside will be uneven across products and channels
The projected market trajectory implies sustained double-digit growth in absolute terms over the forecast horizon, but that growth will not be uniform. Fluid milk will remain central, yet yogurt, cheese, and premium specialty items may outperform in specific subsegments if brands successfully align with functional, convenience, or indulgence occasions. Supermarkets and hypermarkets will likely remain the backbone of volume, but online and specialty channels can provide disproportionate strategic value for brand building, margin optimization, and consumer insight.
For businesses, this means portfolio allocation matters. Overexposure to a single product or channel can leave a company exposed to utilization softness or retail concentration risk, while a balanced mix can capture broader category growth and create more stable demand patterns.
2. Cost discipline and supply-chain reliability will become competitive advantages
As long as organic feed and grain markets remain subject to volatility, the winners will be organizations that treat supply economics as a strategic capability rather than a tactical procurement issue. That includes relationships with certified producers, risk management around input pricing, and the operational discipline to maintain margins without sacrificing accessibility in key retail formats.
This trend also has implications for vertical integration. Companies that control more of the chain—from farm relationships to processing to distribution—can gain predictability and quality control, but they also take on more operational complexity. The strategic question is whether integration improves resilience and margin stability in a way that justifies the added exposure.
3. Trust, certification, and quality systems will increasingly determine brand resilience
Organic dairy competes on trust as much as on taste or price. Certification clarity, consistent labeling standards, and strong quality controls are becoming central to brand durability. Recent recalls and utilization fluctuations show that even growing markets can experience disruptions that affect consumer confidence and retail logistics. Over the next few years, the brands that weather such events most effectively will likely be those that invest in traceability, packaging validation, production controls, and transparent communication.
At the same time, regulatory and certification environments may continue to evolve, influencing both access and operating costs. Organizations that monitor these changes proactively can adapt sourcing, labeling, and compliance practices ahead of competitors rather than reacting after market conditions shift.
Commercial Opportunities Linked to These Trends
These trends open several practical avenues for value creation.
- Portfolio tuning around occasion and function. Brands can prioritize products that fit family consumption, snacking, on-the-go, and functional-nutrition occasions, using format and fortification to differentiate within the organic frame.
- Channel mix as a margin and insight tool. Online and specialty channels can support higher-margin experimentation and direct consumer feedback, while mainstream retail provides scale. A deliberate channel strategy can balance reach and profitability.
- Supply resilience as a strategic asset. Long-term supplier relationships, certified-feed planning, and selective integration can reduce exposure to input volatility and improve execution consistency.
- Trust-led brand architecture. Clear certification practices, traceability storytelling, and disciplined quality systems can strengthen consumer and retail confidence, which is especially important in a category where reputation travels quickly.
Potential Risks and Uncertainties
The outlook is constructive but not risk-free. Feed-cost pressure could compress margins faster than pricing or efficiency gains can offset. Quality incidents could damage brand equity and retail relationships, particularly for products with complex packaging or lot-dependent production. Utilization softness in some fluid milk markets could signal channel-specific headwinds that require tactical response. Regulatory or certification developments could alter cost structures or market-access expectations. Finally, competitive intensity may increase if larger players consolidate supply and distribution or if new entrants target high-visibility subcategories with aggressive positioning.
Strategic Actions for Decision-Makers
The most useful response to this market is not simply to track its growth, but to align strategy with the forces that will determine who converts growth into durable advantage.
For Manufacturers and Brand Owners
- Build portfolio and pricing strategies that reflect product-level utilization realities rather than assuming uniform category momentum. If organic whole milk utilization is softening in certain markets, examine whether the issue is channel-specific, occasion-driven, or competitive, and adjust merchandising, format, or innovation priorities accordingly.
- Treat quality and packaging validation as core strategic investments. In categories where trust and certification matter, reliability in production, lot control, and packaging integrity can be as commercially important as product features.
- Manage feed and input exposure proactively. Where possible, strengthen supplier relationships, evaluate forward planning options, and align pricing and margin models with realistic input-cost scenarios rather than optimistic baselines.
For Investors
- Assess companies on supply-chain resilience and operational discipline, not just brand recognition. Scale, traceability, quality systems, and feed-cost management can be decisive in sustaining margins through cycle pressure.
- Look for positioned leadership in subcategories where trust and differentiation can command premium economics, such as functional milks, yogurt, or premium specialty items, while remaining attentive to the operational capability required to deliver them consistently.
- Monitor consolidation potential and cooperative dynamics. Structures that align producers with processing and branding can influence supply stability, cost behavior, and long-term competitive positioning.
For Procurement and Channel Leaders
- Use channel mix strategically. If mainstream retail is the volume engine, consider how online and specialty pathways can support margin, insight, and brand reinforcement without overexposing the business to channel-specific risk.
- Prioritize suppliers and partners with strong certification discipline and transparent sourcing. In organic dairy, the reliability of certification and traceability can affect both compliance confidence and consumer perception.
- Plan for input-cost volatility in sourcing and price negotiations. Where procurement strategies assume stable costs, they may underprepare for periods when organic grain and feed markets move sharply.
The strategic picture is clear enough to act on, but granular enough that execution quality will separate winners from followers. Market-level growth signals provide direction; product-level utilization, feed economics, quality performance, and channel dynamics determine outcomes. Decision-makers who combine category awareness with operational specificity will be better equipped to allocate capital, shape portfolios, and manage risk through the rest of the decade.
For leaders who need deeper segmentation, regional breakdowns, product-level revenue paths, channel detail, and company-specific competitive profiles, the full research report provides the structured data and customized analysis required to translate these strategic themes into precise planning assumptions.
Liquid Dairy Products Market
For detailed analysis of this topic, please visit the official page: Organic Dairy Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aquaculture Cages Market: Why 6.8% CAGR and Asia Pacific’s 126.14M Dominance Redefine Market Dynamics
By pmarketresearch, 2026-09-21
Navigating the Aquaculture Cages Market: Strategic Shifts, Competitive Realignment, and Commercial Opportunities
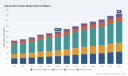
The aquaculture cages market has evolved from a niche equipment segment into a critical infrastructure layer for global protein production. As of 2025, the market stands at approximately $298 billion in revenue, reflecting a steady upward trajectory from $214 billion in 2020. The compound annual growth rate of 6.8 percent through 2032 signals more than linear expansion; it points to a structural shift in how finfish and shellfish are cultivated at scale. Over the next seven years, the market is projected to cross $464 billion, driven by intensifying demand for controlled aquatic production, evolving regulatory expectations, and the gradual replacement of aging cage infrastructure with higher-performing systems. This momentum is not uniform across all segments or geographies, but the underlying direction is clear: aquaculture is moving toward more robust, compliant, and technologically integrated cage architectures.
For executives and investors, the scale of this market is only the starting point. The real strategic value lies in understanding where capital efficiency, regulatory alignment, and technological readiness converge. Cages are no longer passive containment structures; they function as platforms that influence disease exposure, environmental footprint, operational labor, and ultimately, the economic viability of farms. The market’s growth is being shaped by a combination of cyclical replacement cycles, long-term expansion in high-density farming regions, and a growing emphasis on systems that can withstand harsher marine conditions while meeting stricter compliance thresholds. These forces are creating new decision points for manufacturers, farm operators, and capital allocators who must balance short-term procurement costs against long-term operational resilience.
Key Challenges and Inflection Points Shaping the Market
The industry is navigating several structural challenges that will redefine competitive advantage over the next few years. First, environmental compliance and waste management pressures are accelerating the retirement of legacy cage designs. Stricter oversight around water quality, nutrient dispersion, and disease control is pushing operators to adopt cage configurations that support better monitoring, improved water exchange, and reduced localized impact. This transition is not merely a regulatory checkbox; it directly affects permitting timelines, community acceptance, and access to premium buyer channels. Operators that continue to rely on outdated containment approaches face increasing operational friction, while those that modernize early can secure faster approvals and build stronger market positioning.
Second, the durability-versus-cost equation is creating a procurement inflection point. High-density polyethylene (HDPE) cages have become the dominant choice in marine environments because of their resilience under rough sea conditions, flexibility in large-scale deployments, and extended service life. In marine settings, HDPE typically delivers seven to ten years of effective operation, while freshwater applications can stretch that range to ten to fifteen years. This longevity reduces replacement frequency and total cost of ownership, even though the initial material outlay runs 25 to 35 percent higher than alternative options. For farm operators, the decision is increasingly about lifecycle economics rather than upfront price. For equipment suppliers, it means that differentiation is shifting toward proven longevity, corrosion resistance, and ease of maintenance rather than simple cost competition.
Third, regulatory and certification dynamics are reshaping market access. Standards associated with responsible aquaculture practices and environmental stewardship are incentivizing producers to upgrade infrastructure in order to qualify for premium market segments. At the same time, tighter restrictions tied to biomass limits, overfishing concerns, and cage placement rules are introducing constraints that can temper growth in certain regions or applications. These dual pressures create a strategic paradox: compliance and certification open doors to higher-value channels, but they also raise the bar for entry and increase the cost of non-compliant operations. Companies that treat regulatory alignment as a core engineering requirement rather than a downstream compliance task are better positioned to scale without disruption.
Key Drivers of Market Change
The market’s growth trajectory is being propelled by a combination of technological, regulatory, demand-side, and supply-chain forces. Each driver has distinct implications for equipment strategy, risk management, and commercial positioning.
Technological innovation remains one of the most visible catalysts. Manufacturers are moving beyond basic containment toward integrated cage systems that support semi-closed or closed configurations, improved structural stability, and stronger compatibility with monitoring and handling equipment. Recent product supply agreements illustrate this shift in practice. For example, in late 2024, a supplier committed to providing semi-closed fish cages for floating closed cage systems, reinforcing the trend toward containment designs that offer better control over water quality and biological risk. Such arrangements are not isolated transactions; they reflect a broader preference for systems that can reduce environmental leakage, improve biosecurity, and support more predictable production cycles.
Policy and regulatory environments are equally influential. Stringent rules around water quality, waste management, and disease control are making advanced cage designs and integrated monitoring systems more attractive, and in many cases necessary. Certification frameworks and recognized stewardship standards add further momentum by rewarding infrastructure upgrades that unlock premium pricing or preferred supplier status. This regulatory layer is especially important for operators seeking to expand in regions where permitting, environmental impact assessment, and community scrutiny are becoming more rigorous. The practical implication is clear: cage design decisions are increasingly tied to long-term license to operate, not just short-term production needs.
Demand-side behavior is also reshaping the market. Consumers, food retailers, and foodservice buyers are paying greater attention to sourcing practices, environmental impact, and traceability. This shifts commercial value toward producers who can demonstrate consistent quality, lower environmental risk, and more controlled production conditions. Cage systems that support better biological management, reduced escape risk, and cleaner production profiles can become enablers of brand differentiation. For equipment providers, this means that product value is increasingly linked to the operational outcomes their systems help customers achieve, including yield stability, compliance readiness, and market access.
Supply chain and cost structure changes are adding another layer of complexity. Material availability, fabrication capacity, and logistics for large marine-grade components influence both lead times and pricing. The dominance of HDPE reflects not only performance advantages but also a mature supply base that can support large-scale production and replacement programs. At the same time, the higher upfront cost of durable materials requires financing-aware procurement strategies, especially for mid-sized operators. Companies that can offer lifecycle cost clarity, service support, and modular replacement options are gaining an edge in markets where operators need to manage capital constraints while maintaining operational continuity.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a moderate level of concentration, with the top three players accounting for roughly 24.5 percent of the market and the top five reaching about 28.5 percent. This structure suggests a market that is still open to regional specialists and targeted innovators, but where scale, product breadth, and technical credibility increasingly matter. The leading companies are not competing on cage volume alone; they are building differentiated positions around material expertise, structural design, and containment technology.
Several Norwegian and European firms anchor the high-end segment of the market. One global leader has built a strong reputation in plastic pens and cage systems, offering HDPE cages and broader technology solutions for marine and inland fish farming. Its positioning reflects an emphasis on complete system capability rather than isolated component supply. Another European specialist focuses on net cages and submersible cage systems, including models designed for exposed sea sites. This capability highlights a strategic focus on environments where structural stability and containment performance under demanding conditions are critical. A third Norwegian supplier contributes additional differentiation through a broad material range, including nylon, HDPE, Dyneema®, and UHMWPE, across circular, rectangular, and specialized cage formats. This material versatility allows the company to address varied operational conditions and customer preferences, particularly where strength-to-weight characteristics or specific environmental tolerances matter.
Worldwide Fish Farming Equipment Market
In parallel, Mediterranean and Asian manufacturers are expanding the market’s regional depth and cost-performance options. An Italian group has strengthened its portfolio by broadening its aquaculture containment solutions, including a recent acquisition that extended its offer set. This type of consolidation signals a move toward broader solution capabilities and more integrated customer offerings. Chinese manufacturers are also playing a growing role, particularly in offshore HDPE cages and net cage systems for neritic and deeper water applications, alongside suppliers focused on HDPE and related net cage products. Another Chinese manufacturer emphasizes marine and freshwater cage and netting products, reinforcing the region’s broad production capacity. Meanwhile, an Indian manufacturer has carved out a distinct position through high-performance synthetic netting materials and solutions, underscoring the importance of material science in cage durability and performance. A separate Israeli provider illustrates the convergence of cage systems with broader recirculating technology, offering floating closed fish cage systems and integrated approaches that bridge offshore and land-based production needs.
The strategic takeaway is that competition is fragmenting by application environment, material specialization, and system integration. Leading players are differentiating in three main ways: engineering for durability and stability in challenging sea conditions, expanding containment and closed-system capabilities, and broadening portfolios through acquisition or product expansion. At the same time, the moderate concentration levels indicate room for agile entrants, especially those targeting niche applications, specific materials, or regional demand pools. The market is therefore unlikely to consolidate into a single dominant model; instead, it will likely continue to reward companies that can align product strengths with clear operational outcomes and compliance requirements.
Recent corporate activity reinforces this direction. In late 2024, one supplier agreed to continue supplying semi-closed fish cages for floating closed cage systems, indicating renewed demand for containment approaches that improve biological and environmental control. Around the same period, another group completed an acquisition to expand its aquaculture containment solutions portfolio. These moves are not merely incremental; they reflect a strategic preference for broader solution coverage, stronger positioning in higher-value system configurations, and closer alignment with operators seeking more controlled production environments.
Future Trends and Commercial Opportunities
Looking ahead to the 2026–2032 period, three trends are likely to define the market’s next phase of development. The first is the continued shift toward higher-performance, longer-life cage systems in marine and exposed environments. As operations scale and site conditions become more demanding, the practical value of durable HDPE and advanced netting materials will increase. Commercial opportunities will accrue to suppliers that can prove service-life advantages, reduce downtime, and provide replacement and maintenance strategies that lower total cost of ownership. For operators, the opportunity lies in standardizing on cage architectures that can be deployed across multiple sites with consistent performance, thereby simplifying training, maintenance, and procurement.
The second trend is the growing importance of containment and semi-closed or closed cage solutions. Biosecurity, waste management, and site permitting pressures are making controlled-environment cage systems more relevant, especially where environmental sensitivity or disease risk is high. This trend creates opportunities for equipment providers that can integrate cage design with monitoring, handling, and operational support, as well as for operators that can use these systems to strengthen their market positioning. The commercial logic is straightforward: systems that help reduce biological and environmental risk also help stabilize production and improve access to buyers that value predictable, responsibly sourced supply.
PW Consulting Health Care Research Center
The third trend is regulatory-driven infrastructure modernization. As water quality, waste, and disease-related requirements become more rigorous, and as certification and stewardship expectations influence market access, cage upgrades will increasingly be treated as strategic investments rather than discretionary purchases. This trend favors suppliers that can help operators navigate compliance requirements through design choices, documentation, and operational compatibility. It also favors operators that modernize early enough to avoid permitting delays and to secure access to premium market channels. The uncertainty here lies in the pace and variability of regulatory enforcement across regions, which can create uneven adoption curves and affect near-term demand patterns.
Alongside these opportunities, there are risks that decision-makers should monitor. Overly restrictive placement rules or biomass constraints could limit expansion in certain areas, even as demand continues to grow elsewhere. Material cost volatility and fabrication bottlenecks could affect project timing, particularly for large offshore deployments. In addition, the market’s moderate concentration means competitive intensity may increase as regional players expand portfolios or as new entrants target specific applications with lower-cost or higher-specialization offerings. Companies that rely on narrow product lines or single-region exposure may face more pressure than those with diversified application coverage and stronger lifecycle support capabilities.
Strategic Actions for Decision-Makers
For manufacturers and equipment suppliers, the priority is to align product roadmaps with the market’s shift toward durability, containment, and compliance-enabling design. This means investing not only in HDPE and advanced netting capabilities, but also in system configurations that support monitoring, maintenance, and modular replacement. Differentiation will increasingly come from demonstrating measurable operational outcomes, such as reduced replacement frequency, improved structural resilience, and easier integration with farm workflows. Suppliers should also prepare for a competitive environment where portfolio breadth and targeted acquisitions can strengthen positioning in higher-value containment segments.
For investors, the most relevant question is where growth will be most defensible. The market’s projected expansion suggests continued demand, but value capture will depend on exposure to the right applications, materials, and system types. Investments in companies with strong marine durability expertise, containment system capabilities, and credible service and support models are better aligned with the market’s structural direction than those focused solely on low-cost commodity exposure. At the same time, regulatory uncertainty and regional variability mean that portfolio diversification and scenario planning are essential, particularly when evaluating companies with concentrated geographic or application dependence.
Laboratory Animal Housing Cage Market
For procurement leaders and farm operators, the strategic focus should be on lifecycle economics and compliance readiness rather than initial price alone. Selecting cage systems with longer service life, stronger material performance, and better compatibility with monitoring or containment requirements can reduce long-term disruption and support expansion plans. Early alignment with certification and stewardship expectations can also improve market access and reduce the risk of future retrofit costs. Where possible, operators should evaluate suppliers based on total cost of ownership, service availability, and the ability to support standardized deployment across multiple sites.
The pace of change in this market makes detailed, segment-level intelligence increasingly valuable. Regional demand patterns, material substitution trends, regulatory timing, and competitive moves can alter procurement timing, pricing assumptions, and investment priorities in ways that broad market figures alone cannot capture. Decision-makers who need clearer visibility into application-specific demand, regional dynamics, and company-level positioning will benefit from deeper coverage that translates market growth into operational and commercial choices. For those evaluating expansion, procurement strategy, or capital allocation, a more detailed research view can help convert the market’s momentum into a practical plan.
For detailed analysis of this topic, please visit the official page: Aquaculture Cages Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Chocolate Market: Why 4.39% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-21
Navigating the Industrial Chocolate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
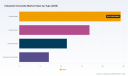
The industrial chocolate market has established itself as a resilient yet complex segment within the broader food ingredients landscape. From 2020 through 2025, the market expanded from approximately USD 49.3 billion to USD 59.7 billion, reflecting steady growth driven by consistent demand across baked goods, confectionery, and beverage applications. Looking ahead to the forecast period of 2026 through 2032, the trajectory projects a market value reaching USD 80.4 billion by 2032, supported by a compound annual growth rate of 4.39 percent. This pace suggests that industrial chocolate will continue to benefit from foundational consumption patterns while facing structural shifts that separate high-performing players from stagnant operations. The growth is not uniform across all product forms and end uses, and understanding where value concentrates requires looking beyond headline figures to the underlying dynamics shaping procurement, formulation, and distribution.
Several critical challenges are reshaping how manufacturers and suppliers approach the market. First, raw material volatility remains a persistent pressure point. Cocoa pricing has experienced significant swings, moving from elevated levels in prior years to notable declines in early 2026 as improved harvest outlooks and surplus expectations in West Africa altered the cost environment. While falling prices can relieve margin compression for downstream buyers, they also introduce planning complexity for suppliers who must manage inventory, hedging, and long-term contracting in a shifting landscape. Second, food safety and compliance oversight has intensified, with multiple recalls across different companies in early to mid-2026 highlighting the industry's exposure to microbiological contamination and undeclared ingredient risks. These incidents underscore the operational fragility that can disrupt supply continuity and erode buyer confidence, particularly for bulk industrial buyers who depend on consistent quality and traceability. Third, the industry must navigate a concentration dynamic where a relatively small number of large players account for a disproportionate share of market activity, creating both barriers to entry and opportunities for differentiation through specialization, technical service, and regional agility.
Cocoa Market
- Raw material price volatility creates planning uncertainty for both suppliers and bulk buyers, requiring more sophisticated hedging and contract strategies
- Food safety incidents and regulatory recalls highlight the need for robust traceability, supplier auditing, and rapid response capabilities across the value chain
- Market concentration among major players raises the importance of differentiation through formulation expertise, regional service, and flexible supply arrangements
Key Drivers of Market Change
Technical Innovation and Formulation Advances
Innovation continues to redefine what industrial chocolate suppliers can deliver, particularly as manufacturers seek cleaner labels, consistent performance, and cost-efficient formulations. Advanced cocoa processing, precision conching, and enhanced particle refinement allow ingredient suppliers to offer compounds, coatings, and fillings with tighter control over texture, viscosity, and flavor stability. Equally important is the growth of functional and flavor-modulation solutions. Ingredient specialists are increasingly providing cocoa extracts, flavor boosters, and formulation aids that enable manufacturers to reduce cocoa usage without sacrificing sensory quality. This approach is gaining traction in an environment where cost optimization and ingredient efficiency matter more than ever, especially for confectionery and bakery producers operating on thin margins. Innovation is also visible in product versatility: compound chocolate and specialty blends are being positioned to meet demands for thermal stability, ease of handling, and compatibility with different processing lines, supporting broader adoption in high-volume manufacturing environments.
Policy and Regulatory Environment
Regulatory oversight and food safety expectations are becoming more influential in shaping procurement and product design decisions. Recent recall activity involving potential Salmonella contamination and undeclared active ingredients has drawn attention to supplier compliance, ingredient sourcing, and quality control rigor. For industrial buyers, these events reinforce the importance of documented traceability, validated sanitation practices, and proactive supplier monitoring. In parallel, regulatory frameworks in key markets are encouraging greater transparency around allergens, labeling, and ingredient origin, which affects how industrial chocolate products are specified and documented. Companies that invest in quality management systems and clear compliance communication are better positioned to maintain trust with food manufacturers and foodservice customers. The regulatory environment is not merely a risk factor; it is also a filter that rewards organizations with disciplined operations and transparent supply practices.
Demand-Side Shifts in Consumer and Business Behavior
End-market demand is being shaped by changing consumer preferences and the operational needs of food manufacturers. Bakery products and confectionery remain central usage channels for industrial chocolate, but the way these categories evolve is changing. Consumers continue to seek indulgence, yet they also expect cleaner ingredient lists, consistent texture, and reliable flavor delivery. For industrial buyers, this translates into demand for ingredients that perform well in high-speed production while supporting product positioning around quality and simplicity. The rise of private label and contract manufacturing further influences demand, as retailers and brands look for suppliers capable of delivering consistent bulk formats with flexible customization. Beverage and frozen dessert applications, while smaller in share, are expanding in relevance as manufacturers explore new use occasions and flavor experiences. These demand-side shifts reward suppliers that can combine technical support with formulation flexibility, helping customers adapt products quickly to changing market expectations.
Supply Chain and Cost Structure Evolution
The cost structure of industrial chocolate is closely tied to cocoa supply dynamics, logistics, and processing capacity. Early 2026 data showed cocoa bean prices declining more than 10 percent year-on-year in some assessments, reflecting improved harvest expectations and changing supply balances in West Africa. At the same time, futures market movements indicated notable day-to-day and month-to-month swings, which reminds participants that even in periods of declining prices, volatility can persist. For industrial buyers, cost relief does not eliminate the need for strategic sourcing; rather, it shifts focus toward supplier reliability, hedging approaches, and contract structures that balance price and continuity. On the supply side, investments in processing capacity and regional facilities are shaping availability and service levels. For example, new pilot bakery and chocolate-related facilities in the United States reflect efforts to strengthen local support for industrial production and shorten response times for nearby customers. These developments suggest a gradual shift toward more regionally attuned service models, which can improve lead-time reliability and technical collaboration for manufacturers seeking closer supplier partnerships.
PW Consulting Health Care Research Center
- Cocoa price movements may ease some input costs, but volatility still demands disciplined sourcing, hedging, and inventory planning
- Food safety recalls reinforce the commercial value of traceability, supplier auditing, and rapid quality response across the industrial supply chain
- Demand for cleaner labels, formulation efficiency, and processing reliability is expanding the role of specialized ingredients and technical service
- Regional capacity additions and pilot facilities indicate a move toward closer supplier proximity and faster support for industrial customers
Competitive Landscape and Leading Strategies
The competitive field in industrial chocolate is defined by a mix of global cocoa processors, bulk ingredient suppliers, and specialists with strong formulation and application capabilities. Companies such as Barry Callebaut, Cargill, Blommer Chocolate Company, and Cémoi occupy prominent positions as large-scale suppliers of bulk dark, milk, and white chocolates, compounds, and cocoa-derived ingredients. Their scale provides advantages in sourcing, processing efficiency, and the ability to serve high-volume industrial and foodservice customers across multiple regions. At the same time, firms like Puratos, Fuji Oil, Guittard, and Natra compete with emphasis on specific application strengths, premium couverture options, and tailored ingredient solutions for bakery, patisserie, and professional manufacturing. A separate layer of competition comes from ingredient technology providers such as Kerry Group, which focuses on cocoa extracts and flavor boosters that help manufacturers achieve desired sensory outcomes while managing cocoa usage. This multi-layered structure means that competition is not only about price and volume; it is also about technical value, application expertise, and the ability to solve customer formulation challenges.
Leading players are pursuing distinct strategic positions. Global processors generally emphasize supply reliability, broad product portfolios, and the capacity to support large-scale manufacturing with consistent bulk formats. Their differentiation often rests on integrated sourcing, processing scale, and the ability to serve diverse end markets through a unified ingredient platform. Application-focused suppliers, by contrast, tend to compete on formulation support, specialty coatings, and solutions designed for specific production environments. Their advantage lies in helping customers achieve desired texture, stability, and flavor with greater precision, particularly in bakery and confectionery operations where processing conditions vary widely. Ingredient innovation specialists contribute another angle: by offering flavor modulation and cocoa-reduction solutions, they address cost and formulation efficiency directly, making them valuable partners for manufacturers looking to optimize recipes without compromising consumer appeal. These strategic differences suggest that the market is increasingly segmented by value proposition rather than by product category alone.
The competitive landscape is likely to evolve through a combination of consolidation, specialization, and selective new entry. Consolidation remains plausible among companies seeking broader geographic reach, ingredient breadth, or enhanced processing capacity. At the same time, specialization will continue to matter for suppliers that can deliver unique functional benefits, stronger application support, or more responsive regional service. New entrants may find opportunity in niche segments such as compound chocolate systems, bakery premix integration, or flavor-modulation ingredients, especially where they can address specific pain points in formulation, shelf stability, or cost control. Recent operational developments illustrate these dynamics: recalls have prompted renewed attention to safety and process control across multiple firms, while capacity additions such as new pilot bakery facilities in the United States indicate strategic investment in closer customer support. For decision-makers, the practical implication is that supplier selection should weigh not only price and availability, but also technical capability, compliance discipline, and the ability to adapt to product and process requirements.
- Global processors differentiate through scale, sourcing breadth, and consistent bulk supply across multiple industrial applications
- Application-focused suppliers compete on formulation precision, specialty coatings, and close support for bakery and confectionery production
- Flavor and ingredient technology providers create value by enabling cocoa usage optimization without sacrificing sensory quality
- Market evolution favors firms that combine compliance rigor, regional responsiveness, and technical service with competitive pricing
Forward Outlook: Three Trends to Watch
Cost Discipline and Ingredient Efficiency Will Become Central to Formulation Strategy
Even with periods of lower cocoa prices, the broader cost environment for food manufacturing remains sensitive to logistics, energy, labor, and compliance expenses. This means industrial chocolate buyers will continue to prioritize ingredient efficiency and formulation flexibility. Suppliers that can offer solutions designed to reduce cocoa dependence, improve handling characteristics, or streamline production steps are likely to capture stronger interest from cost-conscious manufacturers. Over the next three to five years, ingredient strategy will increasingly revolve around achieving target sensory profiles while controlling input costs and maintaining processing reliability. The commercial opportunity lies in partnerships that combine product performance with measurable efficiency gains, especially for high-volume bakery and confectionery operations. The risk is that cost pressure may intensify competition on price alone, squeezing margins for suppliers that cannot demonstrate differentiated value or technical support.
Food Safety, Traceability, and Compliance Will Act as Competitive Filters
Recent recall events have made it clear that food safety performance is not a back-office concern; it directly affects brand trust, supply continuity, and buyer willingness to commit to long-term supply arrangements. Over the coming years, buyers are likely to place greater weight on documented traceability, supplier quality systems, and rapid incident response. Companies that can provide transparent process controls, clear audit trails, and proactive communication will be better positioned to secure and retain industrial contracts. This trend benefits suppliers with mature quality infrastructure and creates headwinds for those with weaker controls. The commercial opportunity for well-prepared suppliers is to use compliance strength as a differentiator in procurement decisions. The uncertainty lies in the possibility of further regulatory scrutiny and the need to adapt quickly to new expectations around labeling, ingredient purity, and contamination prevention.
Regional Proximity and Application-Specific Service Will Gain Importance
Industrial chocolate buyers are increasingly looking for faster response, closer technical collaboration, and supply arrangements that align with local production needs. Capacity investments near key markets, along with pilot and application facilities, suggest that suppliers are responding to demand for more immediate support and better integration with customer workflows. In the next few years, regional service capability may become as important as product range, particularly for manufacturers that need formulation tweaks, troubleshooting, or shorter lead times. The opportunity is for suppliers to build regional footprints and application expertise that reduce friction in product development and production scaling. The risk is that regional expansion requires disciplined execution; without strong operational control, proximity alone will not deliver the reliability or technical value customers expect.
- Ingredient efficiency and formulation flexibility will be central as manufacturers balance sensory goals with cost and processing constraints
- Compliance and traceability capability will increasingly influence supplier selection and long-term contracting decisions
- Regional proximity and application support are likely to become stronger differentiators for suppliers serving industrial production environments
Strategic Actions for Decision-Makers
For Industrial Manufacturers and Formulators
Treat ingredient selection as a multidimensional decision rather than a simple price comparison. Evaluate suppliers on their ability to support formulation targets, maintain processing consistency, and respond quickly when products or production conditions change. Prioritize partners that can demonstrate strong quality systems, traceable sourcing, and clear communication around safety and compliance. Where possible, build relationships that include technical collaboration, whether for recipe optimization, compound chocolate handling, or coatings performance. In a market where volatility and regulatory attention remain elevated, the most resilient sourcing strategies combine cost awareness with reliability and application expertise.
For Investors and Corporate Strategists
Focus on business models that can convert technical value into durable competitive advantage. Scale alone is unlikely to guarantee outperformance if it is not paired with differentiated service, formulation capability, or strong compliance infrastructure. Look for companies that are expanding regional support, strengthening quality systems, and offering ingredient solutions that address cost efficiency or sensory optimization. Pay attention to how firms manage raw material volatility through hedging, contracting, and inventory discipline, as these capabilities influence margin stability. The most compelling opportunities are likely to emerge where suppliers can align product performance with the practical needs of high-volume manufacturing and evolving end-market expectations.
For Procurement and Supply Chain Leaders
Strengthen sourcing resilience by diversifying supplier options where feasible, while maintaining rigorous qualification standards. Incorporate food safety performance, traceability documentation, and incident response capability into supplier evaluation frameworks. Use contract structures that balance price exposure with supply continuity, especially in a market where raw material prices can move sharply over short periods. Establish clear expectations around audit access, documentation, and communication so that compliance becomes a shared operational standard rather than a reactive obligation. In practice, procurement teams that combine cost discipline with risk awareness are best positioned to protect production continuity and support product quality across changing market conditions.
Worldwide Chocolate Machines Market
- Evaluate suppliers on formulation support, processing reliability, and compliance discipline, not only on unit price
- Identify business models that combine scale, regional service, and technical differentiation to assess long-term resilience
- Build sourcing frameworks that integrate traceability, audit readiness, and flexible contracting to manage volatility and continuity risk
For executives seeking deeper segmentation, regional breakdowns, company-level benchmarks, and scenario-based planning inputs, a full research report can provide the detail needed to translate these market-wide observations into operational decisions. Access to more granular data on product forms, application flows, pricing dynamics, and supplier positioning enables more precise strategy design across manufacturing, sourcing, and investment priorities.
For detailed analysis of this topic, please visit the official page: Industrial Chocolate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Plasma Protein Therapeutics Market: Why 5.6% CAGR and $29.7B Scale Signal a Strategic Realignment
By pmarketresearch, 2026-09-21
Navigating the Plasma Protein Therapeutics Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot: Sizing the Opportunity and Identifying Critical Inflection Points
The global plasma protein therapeutics market has crossed a significant threshold, reaching approximately $29.7 billion in 2025. From 2020 through 2025, the sector demonstrated steady expansion, moving from $22.15 billion to its current level. The forward trajectory points to continued growth, with revenue expected to approach $43.26 billion by 2032, representing a compound annual growth rate of 5.6 percent over the forecast period. This expansion is not merely a function of demographic aging or incremental demand growth; it reflects structural shifts in clinical practice, regulatory evolution, and supply chain realignment that are reshaping how plasma-derived therapies are sourced, manufactured, and delivered.
Market concentration remains high. The top three players control roughly 55.8 percent of total revenue, while the top five account for approximately 69.3 percent. This concentration signals an industry where scale, regulatory compliance, and collection network density create formidable barriers to entry. At the same time, the distribution of revenue across product categories and clinical applications reveals a diversified demand base. Immunoglobulins and albumin continue to anchor the portfolio, while coagulation factors and other specialized proteins serve distinct patient populations with concentrated but high-value needs. The application landscape spans hemophilia, primary immunodeficiency disorders, idiopathic thrombocytopenic purpura, and a broader set of indications that collectively sustain demand across multiple therapeutic areas.
Critical Challenges and Inflection Points Shaping the Near Term
Three interconnected challenges define the current market environment and will determine which organizations capture disproportionate value over the next several years.
The first challenge is supply-demand imbalance at the raw material level. Plasma collection volumes are running 5 to 10 million liters per year below full industry need, creating persistent pressure on downstream production capacity. This gap is not a transient disruption; it reflects donor recruitment challenges, geographic concentration of collection centers, and the time lag required to build new fractionation capacity. For manufacturers, the implication is clear: securing reliable plasma supply is no longer an operational detail but a strategic priority that directly affects product availability, pricing power, and market share.
The second challenge centers on regulatory tightening and supply chain resilience, particularly in Europe. The European Medicines Agency issued recommendations in July 2025 to strengthen the anti-D immunoglobulin supply chain, citing declining EU plasma donor numbers and limited EU manufacturing capacity. This development highlights a broader trend: regulators are increasingly viewing plasma-derived therapies as essential medicines requiring proactive supply chain management rather than routine biologics procurement. Companies that depend on single-region sourcing or fragile collection networks face elevated regulatory and continuity risk.
The third challenge is the tension between scale economics and product differentiation. While plasma fractionation benefits from volume-driven cost structures, the most attractive commercial opportunities are emerging in specialized formulations, streamlined administration profiles, and indication-specific therapies. The leaders who navigate this tension effectively are those investing in next-generation manufacturing facilities, pursuing targeted regulatory approvals, and aligning product roadmaps with unmet clinical needs rather than competing solely on price in mature categories.
Core Drivers Reshaping Market Dynamics
Technology and Manufacturing Innovation
Manufacturing innovation is a primary engine of competitive differentiation. The approval and commercialization of next-generation immunoglobulin products illustrate how process innovation translates into market opportunity. Yimmugo®, a novel immunoglobulin product, received FDA approval in June 2024 and is produced at Biotest's new FDA-certified Next Level facility. This combination of regulatory clearance and modernized production infrastructure signals a broader shift toward facilities designed for higher operational standards, improved traceability, and greater flexibility in product output. In practical terms, companies that operate advanced, certified facilities can bring differentiated products to market faster, respond more effectively to supply constraints, and position themselves as preferred partners for payers and clinical networks seeking reliability.
Beyond individual product launches, the industry is seeing incremental gains in fractionation efficiency, purification methods, and formulation design. These improvements may not generate headline-grabbing disruption, but they compound over time. Better yield from collected plasma, reduced processing losses, and more stable formulations all contribute to margin improvement and supply resilience. For decision-makers, the strategic question is whether capital is being directed toward incremental refinement or toward step-change capabilities that can create durable advantages in cost structure and product quality.
Regulatory and Policy Environment
Policy dynamics are influencing both market access and supply chain strategy. The EMA's July 2025 recommendations on anti-D immunoglobulin supply reflect a regulatory posture that prioritizes continuity of care for critical therapies. This approach is likely to expand beyond anti-D as regulators assess vulnerabilities across plasma-derived portfolios. Companies should expect heightened scrutiny of source plasma origins, manufacturing redundancy, and contingency planning. At the same time, regulatory pathways for new plasma-derived products remain active. The FDA approval of QIVIGY®, a 10 percent immunoglobulin for intravenous use in primary humoral immunodeficiency, announced by Kedrion Biopharma in September 2025 with commercial availability planned for early 2026, demonstrates that the regulatory environment continues to support innovation when clinical value and manufacturing quality are clearly established.
From a commercial standpoint, regulatory developments create both constraints and opportunities. Constraints arise where supply vulnerabilities trigger intervention or where compliance requirements raise the cost of market participation. Opportunities emerge for organizations that can demonstrate robust supply chains, clear quality systems, and products that address gaps in current treatment options. The regulatory trajectory favors players who treat compliance and supply resilience as strategic assets rather than baseline obligations.
Demand-Side Shifts in Clinical Practice and Patient Populations
Demand growth is being reinforced by several interlocking factors. Primary immunodeficiency disorders and hemophilia remain central drivers of plasma protein therapeutic utilization, with both categories representing substantial and sustained patient populations. The broader application base, including idiopathic thrombocytopenic purpura and other indications, adds further stability to demand patterns. Clinical practice trends also support continued expansion: earlier diagnosis, expanded treatment protocols, and growing recognition of the role plasma-derived therapies play in managing chronic and rare conditions all contribute to utilization growth.
In addition, the shift toward home-based and outpatient administration where clinically appropriate is influencing product design and service expectations. Therapies that support easier administration, predictable dosing, and reliable availability align with healthcare systems seeking to reduce hospitalization burden and improve patient adherence. This demand-side evolution is not uniform across all products, but it is shaping the competitive priorities for immunoglobulin and albumin offerings, where convenience and consistency increasingly matter alongside efficacy.
Supply Chain and Cost Structure Realignment
Cost structures in plasma protein therapeutics are influenced by collection economics, fractionation yields, regulatory overhead, and logistics. The persistent shortfall in plasma collection relative to industry need is intensifying competition for source material and placing upward pressure on input costs. In response, companies are pursuing multiple levers: expanding collection networks in strategically located regions, investing in facilities that improve yield and throughput, and renegotiating supply arrangements to secure priority access.
Blood Plasma Derivatives Market
At the same time, the cost of maintaining regulatory compliance and quality assurance is rising, particularly where authorities are strengthening expectations around traceability, donor screening, and manufacturing redundancy. Organizations that can manage these costs without sacrificing product quality or supply reliability are better positioned to protect margins. The broader supply chain realignment also favors players with diversified sourcing strategies, regional manufacturing presence, and the operational discipline to manage complex logistics across multiple markets.
Competitive Landscape and Leadership Strategies
Strategic Positioning of Leading Companies
The market's leading players are pursuing distinct but overlapping strategies that emphasize scale, product diversification, and targeted innovation. Grifols S.A. continues to operate as a global leader in plasma-derived medicines, with a portfolio that includes immunoglobulin therapies and a strong presence in fractionation and distribution. Its recent activities, including the launch of Yimmugo® immunoglobulin in the United States in October 2025 for primary immunodeficiencies, reflect a strategy centered on expanding access to differentiated products in key markets while leveraging established collection and manufacturing infrastructure.
CSL Limited remains a major producer of plasma-derived therapies, including immunoglobulins and albumin. Its scale and broad therapeutic footprint provide a foundation for resilience across demand cycles and regulatory environments. Octapharma AG, based in Vienna, has built a specialist reputation in plasma protein therapeutics with a clear focus on immunoglobulin and related derived therapies, positioning itself as a focused competitor in categories where product specificity and clinical reputation matter. Takeda Pharmaceutical Company Limited maintains a significant portfolio in plasma protein therapeutics, including offerings from its acquired Shire assets such as immunoglobulin therapies, combining global commercial reach with established treatment franchises.
Differentiation Through Product Innovation and Facility Investment
Biotest AG and Kedrion S.p.A. illustrate how targeted product innovation can create competitive separation. Biotest's production of innovative plasma-derived immunoglobulins, including Yimmugo®, and its operation of an FDA-certified Next Level facility demonstrate the value of aligning product development with advanced manufacturing capability. Kedrion's FDA approval for QIVIGY® in September 2025, with commercial availability planned for early 2026, underscores how focused development programs can yield new options for specific patient populations, such as those with primary humoral immunodeficiency. These moves are not simply product launches; they are strategic signals that a company can bring new therapies to market with the regulatory and operational backing required for sustained commercialization.
Other significant participants, including Bayer AG, Baxter International Inc., Bio Products Laboratory Ltd, and China Biologic Products Holdings, Inc., contribute to a competitive field that spans specialty medicine portfolios, regional manufacturing strengths, and global distribution capabilities. Collectively, these companies reflect an industry in which competitive advantage is built through a combination of product breadth, supply reliability, manufacturing quality, and market-specific commercial execution.
Evolution of the Market Structure
The competitive landscape is evolving along several dimensions. Consolidation remains a plausible path for players seeking to strengthen collection networks, expand fractionation capacity, or acquire specialized product portfolios. At the same time, there is room for differentiation and selective entry in areas where new formulations, streamlined manufacturing, or region-specific supply strategies create value. The high concentration levels suggest that scale matters, but they do not preclude companies from gaining share through superior product offerings, regulatory success, and stronger supply chain positioning.
Plasma Fractionation Market
Leadership changes at industry associations also point to evolving governance and coordination within the sector. In May 2026, the Plasma Protein Therapeutics Association announced changes to its Global Executive Board and European Board leadership. While such changes do not directly alter competitive dynamics, they can influence industry coordination on supply chain practices, regulatory engagement, and standards development. Organizations that engage constructively with industry bodies and align their strategies with emerging sector priorities may benefit from stronger relationships and earlier insight into collective challenges.
Forward Outlook: Key Trends and Associated Commercial Opportunities
Trend One: Supply Security as a Strategic Differentiator
Over the next three to five years, supply security is likely to move from an operational concern to a core competitive attribute. The ongoing gap between plasma collection and industry demand, combined with regulatory attention to supply chain resilience, will reward organizations that can demonstrate reliable access to source plasma, diversified collection footprints, and manufacturing redundancy. Companies that treat supply security as a market-facing strength may gain preference with payers, hospital networks, and regulators, particularly for therapies where continuity of care is critical.
The commercial opportunity here is twofold. First, organizations with stronger supply positions can protect market share during periods of tightness and potentially expand share when competitors face constraints. Second, supply resilience can support premium positioning in categories where reliability is valued by clinicians and health systems, especially for chronic conditions requiring consistent therapy access.
Trend Two: Product-Level Differentiation in High-Value Indications
Growth is expected to be shaped not only by aggregate demand expansion but also by the success of differentiated products in high-value indications. Immunoglobulins for primary immunodeficiency disorders and hemophilia-related therapies represent areas where clinical need, treatment continuity, and product performance converge to support sustained demand. New formulations and refined administration profiles can create incremental advantage even within mature categories.
This trend creates opportunities for companies that invest in indication-specific development, pursue timely regulatory approvals, and build commercial capabilities tailored to specialist prescribing patterns. It also favors organizations that can connect product attributes to practical clinical benefits, such as dosing predictability, administration feasibility, and consistent supply. The risk is that product differentiation requires disciplined development timelines, strong regulatory execution, and commercial readiness; delays or unclear value propositions can weaken launch impact.
Trend Three: Regional Rebalancing and Supply Chain Diversification
The market is likely to see continued regional rebalancing as companies respond to donor availability, regulatory expectations, and cost considerations. European supply vulnerabilities, reflected in the EMA's anti-D immunoglobulin recommendations, are prompting renewed attention to regional collection and manufacturing capacity. At the same time, other regions may attract investment where collection potential, regulatory pathways, and operational conditions support growth.
For commercial strategy, regional diversification can reduce concentration risk and open pathways to market expansion. Companies that build or strengthen regional capabilities may be better positioned to serve local demand, respond to regulatory requirements, and manage logistics more efficiently. The uncertainty lies in the pace and shape of regulatory evolution, which can vary significantly across jurisdictions and affect the viability of specific sourcing or manufacturing models.
Strategic Recommendations for Decision-Makers
For Manufacturers and Therapy Developers
- Prioritize supply chain resilience as a strategic investment. Expand or diversify plasma sourcing, strengthen contingency planning, and align facility investments with regulatory expectations and production flexibility. The companies that can assure continuity of supply will be better positioned to protect revenue and build trust with clinical customers.
- Focus innovation on products that combine clinical value with operational practicality. Targeted therapies for high-need indications, supported by modernized manufacturing and clear regulatory pathways, offer a stronger path to differentiation than broad-based price competition in commoditizing segments.
- Engage early with regulatory and industry frameworks. Proactive alignment with evolving expectations on supply chain management, quality systems, and product traceability can reduce friction in approvals and market access while strengthening long-term operating credibility.
For Investors and Capital Allocators
- Evaluate competitive strength through supply position and regulatory execution, not just revenue scale. Collection access, certified manufacturing capacity, and a track record of timely approvals are indicators of durable advantage in a concentrated market.
- Look for companies with clear product roadmaps in high-value indications and the operational discipline to convert development progress into commercial availability. Launch execution, distribution readiness, and market-specific commercial capability often determine whether product innovation translates into share gains.
- Monitor regional dynamics and supply-side constraints as leading indicators of margin pressure and competitive shifts. Organizations that can navigate collection shortages, regulatory changes, and cost realignment are more likely to sustain performance across cycles.
For Procurement and Market Access Leaders
- Assess supplier reliability beyond price. In a market shaped by plasma collection gaps and regulatory attention to supply continuity, sourcing decisions should weigh manufacturing redundancy, collection diversity, and supply chain transparency alongside cost.
- Build flexibility into procurement strategies for critical therapies. Where possible, maintain awareness of alternative sources, formulation options, and regional supply pathways to reduce vulnerability to single-source disruptions or sudden demand surges.
- Align purchasing and access planning with clinical continuity requirements. For chronic and essential therapies, reliability and predictability can create value that outweighs short-term cost differences, particularly when supply constraints are likely to persist.
Where to Go From Here
The plasma protein therapeutics market is entering a phase in which supply resilience, product differentiation, and regulatory alignment will separate durable performers from organizations that simply participate in growth. The broad trajectory toward $43.26 billion by 2032 signals a sizable opportunity, but the distribution of value will depend on how effectively companies manage collection constraints, invest in modernized manufacturing, and execute in high-need indications. Leadership in this environment will belong to those who treat supply security and product quality as strategic assets, not background conditions.
PW Consulting Health Care Research Center
For decision-makers seeking deeper segmentation data, competitive benchmarking, and tailored scenarios across regions, product categories, and application areas, the full PW Consulting research report provides a more detailed view of the market structure and the strategic options it creates. Access to that level of granularity can help translate the trends outlined here into specific investment, sourcing, and development decisions.
For detailed analysis of this topic, please visit the official page: Plasma Protein Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Topical Skin Adhesive Market: Why 8.4% CAGR and Surgical Shift Redefine Growth
By pmarketresearch, 2026-09-21
The Topical Skin Adhesive Market: Strategic Shifts and Commercial Opportunities Through 2032
The global market for topical skin adhesives has reached a pivotal inflection point, with 2025 baseline revenues establishing a valuation of USD 626.0 million and projected to climb to approximately USD 1.1 billion by 2032, reflecting a compound annual growth rate of 8.4 percent across the forecast horizon. This trajectory represents a meaningful recovery and acceleration from the volatility witnessed between 2020 and 2024, when revenue fluctuated between roughly USD 418 million and USD 564 million before consolidating near USD 462 million. The rebound underscores a structural shift rather than a cyclical correction: healthcare providers are increasingly viewing tissue adhesives as essential components of streamlined wound closure protocols, not merely as substitutes for sutures or staples. Yet beneath the headline growth lies a complex landscape where technological differentiation, regulatory navigation, and supply chain resilience will determine which participants capture lasting value.
Market Snapshot and the Weight Behind the Numbers
The market’s scale and institutional inertia are shaped by pronounced concentration dynamics. Three manufacturers command roughly 80 percent of global revenue, while five players account for close to 95 percent, creating an environment where incumbency confers significant advantages in distribution networks, clinical familiarity, and procurement relationships. At the same time, the product archetype remains relatively focused, with cyanoacrylate-based chemistries dominating clinical practice across surgical incisions, trauma-induced laceration repair, burn management, and skin grafting procedures. This concentration does not imply stagnation. On the contrary, it signals that meaningful growth will be captured by participants who can extend their reach through formulation innovation, application-specific differentiation, and strategic expansion into adjacent wound closure workflows.
Three Structural Challenges Defining the Next Phase of Growth
Several intersecting challenges will test market participants over the forecast period. First, the regulatory pathway for topical skin adhesives remains rigorous, with tissue adhesives for the topical approximation of skin classified as Class II devices under established FDA special controls frameworks. Manufacturers must demonstrate biocompatibility, sterility assurance, and consistent performance through controlled testing, while maintaining ongoing device registration and listing obligations. The clearance process is well-defined, but it imposes a persistent compliance burden and a timeline hurdle that can slow portfolio expansion, particularly for differentiated chemistries that fall outside legacy predicate pathways.
Worldwide Cosmetic Adhesive Market
Second, reimbursement mechanics introduce pricing and adoption friction. While topical skin adhesives are integral to wound closure procedures, billing structures for skin substitute grafts and related applications operate under separate CPT coding frameworks, meaning the economic case for adhesives must be built around procedural efficiency, reduced follow-up visits, and faster patient throughput rather than direct product reimbursement. In cost-conscious healthcare environments, demonstrating measurable impact on operating room efficiency and complication reduction becomes a commercial prerequisite, not a clinical nice-to-have.
Third, the market faces a structural tension between standardization and differentiation. A handful of legacy formulations have achieved broad clinical trust, creating high switching thresholds for new entrants and established competitors alike. At the same time, clinical needs vary considerably across incision types, tissue tension profiles, and practice settings ranging from high-volume surgical centers to emergency and outpatient environments. Companies that default to undifferentiated commodity positioning risk margin compression, while those that over-specialize without clear reimbursement or workflow integration may struggle to scale.
Innovation, Regulation, and Demand: The Forces Reshaping the Category
Technological innovation is expanding the functional envelope of topical skin adhesives. Recent regulatory milestones highlight a clear trend toward next-generation chemistries designed to address specific clinical pain points such as high-viscosity handling, controlled polymerization speed, and reduced tissue tension during closure. For example, a methylidene malonate-based formulation received FDA 510(k) clearance for incision and laceration closure, signaling interest in alternatives to traditional cyanoacrylate profiles. Around the same period, a high-viscosity topical skin adhesive and a companion skin closure system secured clearance, reflecting advances in application control and tissue sealing performance. Additional clearances for new cyanoacrylate-based variants further demonstrate that innovation is not limited to a single molecular pathway but spans formulation rheology, dispenser ergonomics, and procedural integration.
Policy and regulatory dynamics are simultaneously shaping the pace of commercialization. The Class II special controls framework establishes a predictable but demanding bar for market entry. Biocompatibility, sterility, and performance testing requirements create a baseline of safety and consistency that supports clinician confidence but also raise the cost of portfolio development. Manufacturers that build robust regulatory capabilities early are better positioned to introduce differentiated products with reduced delay, while those that rely on reactive compliance strategies face greater risk of rework and slower time to market. The regulatory environment also interacts with international market access, where CE marking and other regional clearances influence the sequence and geography of product launches.
Demand-side behavior is evolving as clinical and operational priorities shift. Surgical teams and emergency departments are increasingly optimizing for speed, reproducibility, and patient satisfaction. Topical adhesives that reduce closure time, minimize suture-related discomfort, and support cleaner wound edge approximation align well with these priorities. In parallel, outpatient and ambulatory surgical growth continues to redirect wound closure volume away from traditional inpatient settings, increasing demand for products that are easy to deploy, consistently perform under varied conditions, and fit into lean procedural workflows. The result is a demand profile that rewards both clinical reliability and practical usability, including dispenser design and application control features that influence day-to-day adoption.
Supply chain and cost structures add another layer of strategic importance. Concentration among top suppliers means that raw material availability, manufacturing scale, and quality control consistency can influence both product availability and margin stability. Geopolitical volatility, logistics constraints, and the cost of regulated-grade inputs can pressure pricing and complicate capacity planning. Participants who invest in resilient sourcing, disciplined manufacturing operations, and transparent quality systems are better positioned to protect service levels and sustain competitive pricing through periods of input cost fluctuation.
Competitive Landscape: Incumbency, Differentiation, and the Entry of New Players
The competitive field is anchored by a mix of large multinational portfolios and specialized device manufacturers, each pursuing a distinct route to relevance. One prominent incumbent maintains a market-leading position in 2-octyl cyanoacrylate formulations for surgical and trauma wound closure, leveraging long-standing clinical associations and broad procedural familiarity. This type of leadership is difficult to dislodge because it is reinforced by habit, surgeon comfort, and established procurement relationships, but it is not immune to erosion, especially where newer products offer materially improved handling, adhesion profiles, or deployment systems.
Another cluster of competitors competes through diversified wound closure portfolios and global distribution. These players often frame adhesives as part of broader surgical efficiency solutions, integrating topical adhesives with complementary consumables and procedural support. Their advantage lies in cross-selling opportunities across hospital systems and the ability to position products within institutional purchasing frameworks that value breadth and reliability. A third group focuses on specific product attributes, such as fast polymerization, high-viscosity control, or low-tension closure in minimal-tension scenarios. This specialization can create strong clinical niches, but success depends on translating a technical advantage into documented workflow benefits that procurement teams and clinicians can recognize and justify.
Recent development activity illustrates how the competitive frontier is moving. Multiple companies have secured FDA clearances over the past eighteen months for products spanning n-butyl cyanoacrylate, high-viscosity formulations, and methylidene malonate-based systems. Several of these launches emphasize ease of skin edge approximation, controlled application, or closure system compatibility. Taken together, these approvals indicate a market that is opening to more varied chemical options and application architectures, reducing the effective monopoly that any single formulation family might otherwise hold. The practical implication is that incumbents must continue to innovate or at least demonstrate consistent performance improvements to defend share, while new entrants can gain traction by solving specific procedural problems rather than competing on generic product claims.
The market structure is likely to evolve through a combination of consolidation and fragmentation. Concentration supports stability and scale at the top, but it also creates room for focused challengers that address unmet needs in specialized clinical areas or geographies. Potential M&A activity could unite complementary portfolios, particularly where a large platform seeks to deepen its wound closure offering or a specialized firm aims to gain global reach. At the same time, entrepreneurial entrants with differentiated chemistries or dispenser technologies may carve out segments in outpatient surgery, urgent care, or emerging markets where procedural efficiency and cost control are particularly acute.
Three Trends That Will Define the Next Three to Five Years
The first trend is formulation and delivery system convergence. Demand for improved handling, predictable bonding, and reduced operative time will encourage products that pair advanced chemistries with purpose-built dispensers and closure systems. The commercial winners will be those that integrate product and procedure, not just product alone. This creates opportunities for companies that can design around clinician workflow, minimize variability in application, and support consistent outcomes across different users and settings.
Worldwide Topical Dispenser Market
The second trend is geographic and setting expansion driven by procedural shift and access growth. As surgical volume continues to migrate toward ambulatory and outpatient environments, and as emerging markets broaden access to advanced wound closure options, topical skin adhesives will encounter new adoption pathways. Success in these channels will depend less on replicating the same hospital-centric sales models and more on packaging value propositions around ease of use, training support, and total cost of care. Manufacturers that adapt their go-to-market approach to these settings can unlock incremental volume without relying solely on large-institution contracts.
The third trend is intensified scrutiny of value and total procedural economics. With reimbursement structures separating adhesive application from related graft and substitute billing pathways, the burden of proof shifts toward demonstrated efficiency and clinical outcomes. Companies that can articulate how their products reduce closure time, lower the need for suture removal visits, or support faster discharge will be better positioned in procurement discussions. This trend also creates a risk: products that cannot clearly connect clinical performance to operational benefit may face pricing pressure or slower adoption despite strong regulatory clearance.
Strategic Implications for Decision Makers
For manufacturers, the priority is to balance portfolio breadth with credible differentiation. A broad catalog alone is unlikely to sustain premium positioning in a concentrated market. Instead, companies should identify the specific clinical problems where their chemistry or delivery system delivers a measurable advantage, then build the evidence, training, and system compatibility needed to reinforce that advantage. Regulatory strategy should be treated as a growth lever, not just a compliance checkpoint, with early planning for biocompatibility, sterility, and performance testing that aligns with intended launch geographies and indications. Supply chain resilience deserves equal attention, particularly for regulated inputs and critical components, because service continuity and quality consistency increasingly influence purchasing decisions.
For investors, the most promising opportunities lie at the intersection of innovation, workflow integration, and access expansion. Capital should favor companies with clear formulation or delivery differentiation, demonstrable regulatory execution, and business models that can scale beyond a single product cycle. Particular attention should be paid to how reimbursable procedural context influences adoption, since the economic case for adhesives often depends on operational benefits rather than direct product reimbursement. Investors should also monitor consolidation signals, as the concentrated structure of the market may incentivize platform acquisitions that reshape competitive dynamics and create new distribution advantages.
For procurement and clinical leaders, the decision framework should extend beyond unit price to total procedural impact. Evaluating adhesives through the lens of closure consistency, application ergonomics, training burden, and post-procedure follow-up can reveal value that is not visible in a simple cost comparison. Institutions should seek products that align with their patient flow, staff skill mix, and setting-specific requirements, while ensuring that supplier quality systems and supply reliability support ongoing operational stability. In concentrated markets, disciplined supplier evaluation and clear internal performance criteria help avoid overreliance on legacy familiarity alone.
PW Consulting Health Care Research Center
Why Timely Intelligence Matters
The topical skin adhesive market is at a stage where incremental advantages in formulation, regulatory execution, and workflow integration can translate into durable share gains, but the window to act is narrowing as more products enter the cleared pipeline and procurement teams reassess alternatives. Strategic decisions made today, whether around portfolio focus, launch sequencing, supply resilience, or sourcing criteria, will shape competitive positioning well into the latter part of the decade. For teams that need detailed segmentation data, competitive benchmarking, pricing dynamics, and customized scenario analysis, deeper intelligence is essential to convert these directional trends into precise execution plans. Comprehensive research resources are available to support that next step, offering the granular insight required to move from strategic direction to operational commitment.
For detailed analysis of this topic, please visit the official page: Topical Skin Adhesive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Prosthetic Liners Market: How 42.5% CR3 Concentration Meets 6.8% CAGR Growth
By pmarketresearch, 2026-09-21
Prosthetic Liners Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Structural Challenges
The prosthetic liners market has entered a phase of sustained expansion, defined by a compound annual growth rate of 6.8 percent from 2026 through 2032. Revenue reached approximately 648.4 million USD in the base year of 2025, following a decade of steady accumulation that pushed the sector from 163.15 million USD in 2020 to 474.98 million USD by 2024. The trajectory points to 832.5 million USD in 2026, with growth accelerating into the latter half of the forecast window and approaching 4.475 billion USD by 2032. This expansion reflects more than demographic tailwinds; it signals a structural recalibration of how residual limb interfaces are designed, validated, and reimbursed.
Three interlocking challenges define the current inflection point. First, functional level eligibility has historically constrained access to advanced liners, particularly for patients classified at the K2 mobility tier. Coverage frameworks that restricted component reimbursement to higher functional categories left a large segment of the amputee population relying on legacy interface materials, limiting both clinical outcomes and addressable demand. Second, material performance trade-offs continue to pressure manufacturers. Silicone, thermoplastic elastomers, and polyurethane each offer distinct advantages in cushioning, durability, and moisture handling, yet balancing skin compatibility with long-term structural integrity remains a persistent engineering constraint. Third, regulatory and reimbursement fragmentation across geographies creates uneven adoption curves. While some markets have streamlined coverage pathways, others maintain multi-layered approval processes that delay commercial rollout and complicate forecasting for suppliers operating across jurisdictions.
Key Drivers Reshaping the Landscape
Technology Innovation and Interface Intelligence
Material science and embedded sensing are converging to redefine what a prosthetic liner must deliver. Recent product introductions highlight a move toward liners that do more than provide a cushion between residual limb and socket. Micro-sensors embedded within liner structures now capture pressure distribution and movement data, giving clinicians and patients real-time visibility into fit dynamics and tissue stress. At the same time, advanced material formulations prioritize moisture management and sustained comfort, addressing one of the most persistent barrier to extended wear and consistent use. These developments are not incremental tweaks; they represent a shift from passive interface components to active, data-enabled elements that integrate with broader prosthetic systems.
Raw material suppliers have contributed to this shift by delivering new chemistries that meet stringent biocompatibility standards while improving tear resistance and water-vapor transmission. Medical-grade silicone, urethane, and thermoplastic elastomers remain the foundation of most commercial liners, but reformulated variants are expanding the performance envelope. The result is a market where differentiation increasingly depends on how well a liner manages humidity, shear forces, and long-duration comfort, rather than on price positioning alone. For manufacturers, this elevates the importance of formulation expertise and application-specific tuning, particularly for lower extremity use cases where load-bearing demands are highest.
Policy and Reimbursement Realignment
Coverage policy is emerging as a decisive demand-side lever. In September 2024, the Centers for Medicare & Medicaid Services implemented expanded coverage criteria for microprocessor-controlled knee units and related lower limb prosthesis components, including liners for K2 functional level beneficiaries. This adjustment broadens the population eligible for higher-performance interface components and directly enlarges the commercial base for manufacturers serving public payers and aligned private plans. Reimbursement approvals at the product level further reinforce this trend. Recent PDAC approvals for specific liner codes have clarified billing pathways across Durable Medical Equipment Medicare Administrative Contractors, reducing ambiguity for suppliers and downstream providers.
Regulatory refinement is also shaping cost structures. Updated guidance around biocompatibility testing for intact-skin devices has reduced redundant test spending, freeing capital that companies are redirecting toward material innovation and moisture-management development. In parallel, manufacturers operating in regulated markets continue to align production and quality systems with established medical device standards, ensuring that new offerings can navigate certification requirements without compromising time-to-market. The cumulative effect is a more navigable pathway for liner innovation, provided companies maintain disciplined documentation and design controls.
Demand-Side Shifts and Clinical Expectations
Clinician and patient expectations are evolving in tandem with material and policy changes. Prosthetic users increasingly prioritize liners that support all-day wear, reduce skin breakdown risk, and accommodate variable activity levels without frequent adjustments. For lower extremity applications, where load distribution and socket interface stability are critical, this translates into sustained demand for liners that combine cushioning with reliable moisture control. Upper extremity users, meanwhile, drive requirements around dexterity, socket fit precision, and cosmetic discretion, creating distinct performance priorities across application segments.
The broader demand environment is also being influenced by improved access pathways and a growing recognition that interface quality affects rehabilitation outcomes, device adherence, and long-term socket performance. As prosthetic care teams place greater emphasis on interface selection as a clinical decision rather than a commodity choice, suppliers are seeing more specification-driven purchasing. This shifts competition toward proven comfort characteristics, compatibility with socket systems, and clinical support materials that help practitioners match liners to patient profiles.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by both material innovation and regulatory efficiency. Improved biocompatibility pathways have lowered certain validation costs, while advanced chemistries from raw material suppliers have improved performance per unit of material input. These dynamics help manufacturers manage the tension between premium material attributes and price sensitivity in cost-constrained procurement environments. At the same time, the concentration of the market among a relatively small group of leading suppliers indicates that scale, certification readiness, and established distribution relationships still confer meaningful advantages.
Supply chain strategy is increasingly tied to formulation control and application-specific production. Because advanced liners commonly rely on medical-grade silicone, urethane, or thermoplastic elastomers, companies that can secure consistent input quality and tune material properties for specific use cases are better positioned to protect margins. For products designed and produced under recognized quality management standards, alignment with regional regulatory expectations also reduces friction in cross-border commercialization and supports repeat procurement cycles among institutional buyers.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with the top three suppliers accounting for roughly 42.5 percent of revenue and the top five reaching approximately 48.2 percent. This structure suggests that scale, brand trust, and clinical adoption matter, but also that space remains for differentiated specialists and regionally focused players to compete on performance, service, and fit. The competitive field spans established prosthetic brands, interface specialists, and material-forward suppliers, each pursuing distinct strategic positions.
Össur has reinforced a technology-integrated positioning through recent liner launches, including a generation featuring embedded micro-sensors for pressure and movement analysis, followed by a new line emphasizing advanced materials with superior moisture management and comfort. This dual focus on data capture and material comfort aligns with the broader shift toward intelligent interfaces and supports a clinical narrative centered on fit optimization and wear-time improvement.
PW Consulting Health Care Research Center
Ottobock has pursued a reimbursement-forward strategy, exemplified by PDAC approval for a liner under an HCPCS code that clarifies billing across the four Durable Medical Equipment Medicare Administrative Contractors. By reducing reimbursement uncertainty for a specific product, the company strengthens procurement confidence among providers operating within public payer systems and improves the commercial predictability of the offering.
Specialist and material-focused players have carved out positions around fit customization, production standards, and application-specific comfort. Willow Wood, ALPS, College Park Industries, Blatchford, Fillauer Europe AB, Freedom Innovations, Medi, SILIPOS HOLDING, Streifeneder USA, and ST&G Corporation each bring distinct emphases, from interface design heritage and medical-grade material expertise to regional manufacturing and quality system alignment. ALPS, for example, frames its products around ISO 13485 and GMP-based design and production, meeting EU regulatory requirements and conforming to MDR 2017/745, an approach that signals compliance readiness for buyers in regulated markets. ST&G Corporation reflects the continued presence of South Korean manufacturing capability within a globally distributed supplier base, illustrating how regional sourcing and specialized production can support broader international distribution.
Market evolution is likely to follow a bifurcated path. Larger brands will continue to leverage integrated prosthetic ecosystems, reimbursement expertise, and global distribution to defend share in high-volume segments. Meanwhile, smaller and mid-sized players will compete on niche performance attributes, custom fit capabilities, and specialized material formulations that address unmet comfort or durability needs. Consolidation pressures may emerge where scale advantages in procurement, testing, and market access become decisive, but fragmentation is also likely to persist where clinical preference, patient-specific fitting, and regional reimbursement patterns reward differentiated offerings. New entrants will face the highest barriers in regulated reimbursement channels, but may find opportunity in specialty applications, advanced material variants, or smart-interface partnerships that do not require full-spectrum prosthetic portfolios.
Outlook for the Next 3 to 5 Years
Three trends are likely to shape the market over the next several years. First, intelligent interface features will move from differentiated novelty to expected capability in a growing share of premium and mid-tier offerings. Pressure and movement sensing, paired with moisture-management material improvements, will increasingly define how clinicians evaluate liner quality. The commercial opportunity lies in pairing sensor-enabled liners with interpretation tools, clinical training, and service models that turn raw data into actionable fit adjustments, rather than selling sensing as a standalone feature.
Worldwide Heel Liner Market
Second, reimbursement expansion for broader functional levels should continue to widen the addressable base, particularly for lower extremity liners where load-bearing performance and wear-time demands are greatest. As coverage clarity improves, procurement cycles may become more predictable, and suppliers that can demonstrate consistent clinical value and documentation readiness will be better positioned to capture institutional demand. The opportunity here is to align product portfolios, coding clarity, and clinical evidence so that expanded eligibility translates into sustained share gains rather than short-term spikes.
Third, material formulation leadership will become a more visible battleground. As new chemistries improve tear resistance and water-vapor transmission while meeting biocompatibility expectations, suppliers with strong formulation know-how and reliable input quality will be able to differentiate on comfort and durability without relying solely on brand heritage. The opportunity is to build application-specific material platforms that can be tuned across silicone, thermoplastic elastomer, and polyurethane use cases, allowing faster response to clinical feedback and regional preference.
These trends carry inherent risks. Reimbursement policy remains subject to revision, and coverage expansions that benefit current demand could be adjusted if budgetary pressures intensify or if evidence standards tighten. Material innovation also introduces validation and consistency challenges; new chemistries must perform reliably across production batches and diverse patient populations, or commercial gains can be undermined by fit variability and complaints. Finally, the integration of sensing features raises questions about data interpretation, service responsibility, and long-term support, creating execution risk for companies that introduce smart capabilities without clear clinical workflows or after-sales models.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to convert material and interface innovation into clinically defensible differentiation. Products that pair advanced moisture management and fit stability with clear reimbursement positioning will have an advantage in procurement environments where providers must justify component selection. Companies should also prepare for intelligent-interface expectations by defining how sensor data will be interpreted, who supports fit adjustments, and how service commitments will be structured. Formulation consistency, application-specific tuning, and documentation readiness will be decisive in protecting margins as performance expectations rise.
For investors, the market offers opportunity in companies that can demonstrate a credible link between material leadership, reimbursement navigation, and recurring procurement cycles. The most attractive profiles combine formulation or sensor-enabled differentiation with clear coding and coverage alignment, especially where expanded eligibility has broadened the addressable population. Due diligence should weigh not only product announcements, but also the quality systems, input supply reliability, and clinical evidence pathways that determine whether new features translate into durable share and margin expansion.
For procurement and clinical leaders, selection decisions should increasingly weigh interface performance across moisture handling, load distribution, and wear-time comfort, rather than treating liners as interchangeable commodity inputs. Alignment with reimbursement clarity, fitting support, and compatible socket systems can reduce downstream variability and improve patient adherence. Where intelligent interface features are under consideration, buyers should assess data workflows, training, and support obligations before adoption to ensure that added capability improves outcomes rather than complicating service.
Prosthetic Foot Market
For organizations seeking to move from high-level trends to segment-specific sizing, application-level demand patterns, regional growth differentials, and competitive share dynamics, a detailed market report provides the granular context needed to convert these insights into investment, development, and procurement decisions. Prepared by PW Consulting, the full research report extends the macro view into actionable breakdowns that support portfolio planning, entry strategy, and sourcing decisions with detailed data and customized guidance.
For detailed analysis of this topic, please visit the official page: Prosthetic Liners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Plastic Food Containers Market Report: Why 6.98% CAGR Signals Strategic Shifts
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Plastic Food Containers Market
The plastic food containers market has entered a defining phase, shaped by steady demand expansion, shifting regulatory expectations, and an intensifying race toward sustainable materials. Valued at approximately USD 215.0 million in 2025 and projected to reach USD 344.8 million by 2032, the sector is advancing at a compound annual growth rate of 6.98 percent over the forecast period. This trajectory reflects more than incremental volume growth; it signals a structural transition in how food is packaged, distributed, and consumed across household and commercial channels. Market participants are navigating a landscape where performance, compliance, and circularity increasingly determine competitive positioning.
Market Landscape and Core Challenges
The market has demonstrated consistent expansion since 2020, with revenue compounding from roughly USD 163.15 million to a 2025 baseline near USD 215.0 million. The upward momentum is expected to continue through 2032, though the pace will be uneven as regional maturity, product mix, and regulatory adoption diverge. A moderately fragmented landscape persists, with the top three firms capturing 24.6 percent of revenue and the top five firms representing 26.2 percent. This concentration suggests that scale advantages coexist with room for differentiated players to compete on innovation, regional reach, and specialized applications rather than price alone.
Despite the favorable growth path, the industry faces three structural challenges that will shape margin dynamics and go-to-market strategies over the next several years. First, sustainability mandates are compressing traditional design cycles and forcing material substitution decisions that carry cost and performance trade-offs. Companies must reconcile recyclability targets, recycled content requirements, and consumer expectations while preserving functional properties such as heat resistance, shelf life, and leak protection. Second, raw material price volatility continues to pressure unit economics. Resin costs, energy inputs, and logistics expenses have introduced greater variability into production planning, making procurement strategy and hedging decisions more consequential. Third, regulatory fragmentation across jurisdictions is increasing compliance complexity. Divergent rules on single-use items, expanded polystyrene, PFAS restrictions, and recycled content create a patchwork that favors firms with robust regulatory intelligence and flexible manufacturing footprints.
These challenges are not purely defensive. They are reshaping value pools by rewarding capabilities in material science, supply chain agility, and compliance readiness. Firms that treat sustainability and regulation as design constraints rather than afterthought considerations are better positioned to capture premium segments and secure long-term customer relationships.
Key Demand Drivers
Material Innovation and Performance Breakthroughs
Material innovation is emerging as a primary engine of differentiation. The industry is moving beyond conventional resin formulations toward BPA-free architectures, compostable fibers, and natural polymer systems that retain or improve performance while addressing end-of-life concerns. Joint development efforts are accelerating the translation of laboratory concepts into commercial packaging, particularly where moisture barriers, thermal stability, and structural integrity must be maintained without relying on traditional additives. Recent collaborations signal a broader shift: the market is seeing coordinated work between packaging producers and specialty material suppliers to create fully plastic-free and biodegradable solutions built on natural polymers, alongside recyclable paper alternatives for confectionery and other sensitive categories. These advances expand the commercial envelope for foodservice operators who need to meet sustainability commitments without compromising food quality or handling convenience.
Worldwide Plastic Sterilization Containers Market
The commercial implication is clear. Packaging is increasingly a strategic asset rather than a commodity input. Buyers are evaluating suppliers on material safety, recyclability pathways, and compatibility with circular systems. Suppliers that can demonstrate verified performance, transparent lifecycle attributes, and scalable production will command stronger positioning in both household and commercial segments.
Regulation and Compliance as Market Architecture
Regulatory developments are no longer peripheral; they are becoming the scaffolding around which product portfolios, sourcing strategies, and regional expansion plans are built. The Packaging and Packaging Waste Regulation entered into force in early 2025 and is set to generally apply later in the year, with expectations that recyclable packaging will be mandatory by 2030 and that recycled plastic use in EU packaging will increase. In the United States, California finalized permanent regulations for its packaging extended producer responsibility program, establishing producer fees for single-use plastic food service ware and a mandatory 25 percent recycling rate for expanded polystyrene. Meanwhile, Virginia implemented a ban on single-use plastic food containers for large food businesses, with full expansion to all vendors scheduled for mid-2026.
These measures create two simultaneous effects. They raise the compliance bar for legacy materials, particularly expanded polystyrene and non-recyclable formats, while also opening space for alternative designs that align with extended producer responsibility economics and recycling infrastructure. For manufacturers, this means product roadmaps must account for jurisdictional timelines, fee structures, and end-market recycling availability. For investors, regulatory tailwinds can validate capital allocation into recyclable, compostable, and fiber-based lines, but only where end-user adoption and collection infrastructure can support scale.
Demand-Side Shifts in Household and Foodservice Channels
Demand patterns are evolving on both sides of the market. In household use, consumers continue to prioritize convenience, food safety, and storage efficiency, but purchasing decisions are increasingly influenced by perceived health safety and environmental impact. BPA-free containers have gained traction as a baseline expectation rather than a premium feature, reflecting broader awareness of material safety in food contact applications. In commercial and foodservice channels, operators are balancing cost discipline with brand positioning around sustainability. Quick-service and delivery models depend on containers that withstand microwave heating, maintain temperature integrity, and resist leakage during transit, while also meeting corporate sustainability targets and local ordinance requirements.
These demand dynamics create a split incentive structure. Household buyers reward safety, clarity, and convenience, while commercial buyers reward volume reliability, compliance, and brand alignment. Suppliers that can tailor product attributes to each channel, without over-indexing on a single use case, are better equipped to capture cross-channel growth. The market is therefore rewarding flexible product architectures and application-specific engineering over uniform commodity offerings.
PW Consulting Health Care Research Center
Supply Chain and Cost Structure Dynamics
Cost structure volatility is a persistent theme. Resin pricing, energy costs, and transportation expenses have introduced variability into production planning and margin forecasting. The U.S. Producer Price Index for plastics material and resin manufacturing has reflected elevated levels, underscoring the sensitivity of input costs to macroeconomic and feedstock conditions. In this environment, procurement strategy, contract design, and production scheduling are becoming competitive levers. Companies are increasingly seeking to stabilize input exposure through long-term agreements, diversified sourcing, and operational efficiency programs that reduce scrap and rework.
The broader implication is that cost leadership will depend less on sheer volume and more on resilience and precision. Manufacturers that can manage resin exposure, optimize changeover times, and maintain quality consistency under input cost pressure will protect margins more effectively than those relying solely on price negotiation. This dynamic also favors regional production strategies that shorten lead times and reduce transport exposure for bulky food containers.
Competitive Landscape and Leading Strategies
The competitive field features global container specialists, foodservice packaging producers, and paper-based packaging suppliers that are extending into plastic and hybrid formats. Several firms have established distinct strategic positions. Amcor operates as a global leader in rigid plastic containers, including polypropylene and PET food containers and trays for foodservice, leveraging scale and application engineering across multiple regions. Huhtamaki produces polypropylene and paper-based disposable food containers and takeaway packaging, with a visible push toward recyclable and biodegradable formats. Dart Container Corporation has expanded its ProPlanet compostable fiber and plastic food containers for foodservice and retail, including PFAS-free solutions, reflecting a focus on compliance-friendly sustainable lines. Berry Global Inc. produces rigid plastic containers and packaging solutions for disposable food containers and foodservice, combining broad portfolio coverage with manufacturing flexibility. Pactiv Evergreen remains a leading manufacturer of foam and plastic foodservice containers and disposable packaging, while Genpak and Sabert serve quick-service and catering segments with durable plastic and paper disposable containers and hot/cold/catering solutions.
Additional players contribute to regional depth and specialty positioning. Novolex focuses on recycled and compostable plastic take-out containers and foodservice packaging. Anchor Packaging specializes in premium take-out and delivery plastic containers resistant to microwave and heat, targeting delivery-heavy operators. International Paper supplies paper-based and plastic food containers with sustainable packaging solutions and has moved to strengthen U.S. production capacity through a recent sustainable packaging facility expansion. Reynolds Consumer Products and Silgan Holdings continue to participate in plastic foodservice and takeaway containers and packaging, while Sealed Air provides protective and disposable plastic food packaging and containers. International exposure is also evident from exporters such as Jinhua Lanxin Commodity Co., Ltd., which supplies disposable plastic food containers, plates, and tableware for catering.
Plastic Caps Market
Several strategic patterns stand out. First, differentiation is increasingly product- and compliance-led. Expandable polystyrene portfolios face mounting regulatory and consumer pressure, while recyclable, compostable, fiber-based, and BPA-free lines are gaining attention from buyers seeking to align with sustainability targets and local rules. Second, partnerships and collaborations are accelerating material transitions. Recent joint development work on natural polymer-based, plastic-free, and biodegradable packaging, alongside conversions of plastic packaging to recyclable paper options in confectionery, indicate that incumbents are using ecosystem partnerships to reduce time-to-market for next-generation formats. Third, capacity and geographic alignment are being revisited. Investments in U.S. production and sustainable packaging facilities point to a desire to serve regional demand more efficiently while reducing transport exposure and improving responsiveness.
The market is likely to continue a dual trajectory. Consolidated leaders will compete on scale, breadth, and integrated feedstock-to-finished-product capabilities, while smaller and regional players will compete on application specialization, speed, and localized compliance readiness. M&A and partnership activity may intensify where companies seek to fill gaps in recyclable or compostable lines, expand geographic coverage, or acquire material science competencies. New entrants will find opportunity in niches where conventional players are slower to adapt, particularly in compostable fibers, PFAS-free constructions, and microwave-resistant premium delivery containers.
Forward Outlook: Three Trends for the Next 3 to 5 Years
Trend 1: Compliance-Driven Portfolio Rebalancing
Over the next several years, product portfolios will increasingly reflect jurisdiction-specific compliance requirements rather than one-size-fits-all designs. Recyclable packaging expectations, expanded polystyrene restrictions, and recycled content mandates will push manufacturers to maintain parallel product lines tailored to different regions and customer segments. This rebalancing will favor firms with strong regulatory monitoring, flexible tooling, and clear communication of end-of-life pathways. The commercial opportunity lies in helping buyers navigate transition timelines with products that meet near-term rules while remaining compatible with longer-term recycling and circular economy goals.
Trend 2: Sustainable Materials Moving from Differentiator to Baseline
BPA-free containers, recyclable paper alternatives, compostable fibers, and PFAS-free formulations are expected to shift from premium or niche offerings toward baseline expectations in selected channels. As major foodservice operators and household brands set public sustainability targets, procurement specifications will increasingly include material safety, recyclability, and reduced additive use as standard criteria. The opportunity is not simply to launch sustainable products, but to build verifiable performance data, scalable production, and transparent claims that withstand scrutiny from regulators, retailers, and consumers. Companies that can prove functionality alongside sustainability will be better positioned to protect price points and customer loyalty.
Trend 3: Regionalized Production and Input Cost Management
Given resin price volatility and the logistical footprint of bulky food containers, regional production strategies are likely to gain importance. Facilities positioned closer to demand centers can reduce transport costs, shorten lead times, and improve responsiveness to local regulatory shifts. At the same time, procurement teams will continue to refine resin sourcing, hedging, and scrap reduction to protect margins against input cost swings. The strategic value will accrue to operators that can combine regional capacity with disciplined cost control and consistent quality, especially in high-volume commercial and foodservice applications where reliability is paramount.
These trends carry inherent uncertainties. Regulatory timelines may shift or be implemented unevenly, recycling infrastructure may lag packaging design ambitions, and raw material costs may remain volatile. Consumer willingness to accept tradeoffs in price or convenience will also shape adoption speed. Market participants should therefore treat sustainability and compliance investments as adaptive capabilities, with clear triggers for scaling successful formats and withdrawing underperformers.
Action Considerations for Decision Makers
For manufacturers, the priority is to align product roadmaps with compliance trajectories and channel-specific performance needs. This means investing in recyclable, compostable, and BPA-free lines where demand is most credible, while maintaining the engineering rigor required for heat resistance, leakage control, and structural durability. Procurement and production teams should also strengthen input cost resilience through diversified resin sourcing, longer-term contract structures where feasible, and continuous improvement in scrap and energy efficiency. Regional capacity decisions should be evaluated against local demand density, regulatory timing, and transport economics, particularly for bulky foodservice packaging.
For investors, the key is to distinguish between sustainability claims and scalable, commercially viable solutions. Preference should be given to companies with verified material performance, clear recycling or composting pathways, and manufacturing footprints that can respond to regional regulation. Growth exposure may be strongest where portfolios are expanding into PFAS-free compostable fibers, microwave-resistant delivery containers, and recyclable paper alternatives, especially if supported by partnerships that reduce development risk. Capital allocation should also account for the pace of infrastructure development, since end-market recycling and collection capacity will influence the practical impact of regulatory mandates.
For procurement and purchasing leaders, the focus should be on building supplier partnerships that can navigate a fragmented compliance environment without disrupting supply continuity. Evaluation criteria should include material safety, recyclability evidence, compatibility with delivery and heating workflows, and the supplier’s ability to adapt portfolios as regulations evolve. Multi-region sourcing and flexible specification management can help balance cost, compliance, and performance, particularly when local ordinances diverge on expanded polystyrene or single-use items. Maintaining visibility into resin cost trends and regional regulatory changes will also support more informed negotiation and inventory planning.
In a market advancing at a steady 6.98 percent CAGR through 2032, the winners will be those who convert sustainability, compliance, and cost volatility into structured competitive advantages. Detailed segmentation data, company-level tracking, and scenario modeling can sharpen these decisions further by illuminating where growth is concentrating, how portfolios are shifting, and which capabilities will matter most in each channel. For decision makers seeking a deeper view of regional dynamics, application splits, and company strategies, the full research report provides the granularity needed to translate these trends into targeted action.
For detailed analysis of this topic, please visit the official page: Plastic Food Containers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bubble Tea Syrup Market beyond 7.45% CAGR: 5 Strategic Shifts Shaping 2032 Growth
By pmarketresearch, 2026-09-18
Beyond the Boba Cup: Strategic Trends and Commercial Opportunities in the Bubble Tea Syrup Market
Market Snapshot: Navigating a Phase of Maturation and Complexity
The global bubble tea syrup market has entered a defining expansion phase, with total revenue reaching $2,150.0 million in base year 2025. Driven by sustained consumer enthusiasm and the international diffusion of Asian beverage culture, the market is projected to grow at a compound annual growth rate of 7.45%, advancing to an estimated $2,243.73 million in 2026 and reaching $3,555.43 million by 2032. Over the historical period from 2020 through 2025, the sector demonstrated consistent upward momentum, transitioning from a niche novelty to a structured global ingredient category. This trajectory reflects more than simple volume growth; it signals a market that is maturing, professionalizing, and increasingly susceptible to macroeconomic and regulatory forces.
PW Consulting Health Care Research Center
Despite the favorable growth backdrop, industry participants are navigating a period of structural transition. The first critical challenge lies in flavor standardization versus localization. As bubble tea operators scale across diverse cultural contexts, syrup providers must balance consistent taste profiles with regional palates, driving formulation complexity and elevating inventory management costs. The second challenge centers on supply chain fragility. Production depends heavily on sugar, fruit extracts, and natural flavor compounds, all of which remain exposed to agricultural volatility, export restrictions, and logistics bottlenecks. Price fluctuations in these inputs can quickly compress margins, particularly for mid-sized manufacturers operating with limited hedging capacity. The third challenge is the tightening regulatory perimeter. Markets in North America and Europe increasingly demand rigorous food safety certifications, traceability documentation, and compliance testing for imported syrup products. Navigating divergent regulatory frameworks while maintaining competitive lead times has become a prerequisite for sustained market access rather than a back-office compliance exercise.
Together, these dynamics are reshaping how syrup companies prioritize portfolio design, sourcing strategies, and geographic expansion. The market's continued growth is no longer solely a function of rising tea shop openings; it is increasingly determined by which players can align product innovation with supply resilience and regulatory readiness.
Key Demand Drivers: Forces Reshaping the Value Chain
Ingredient Innovation and Formulation Agility
The beverage landscape is shifting away from uniform sweetness profiles toward layered, experience-driven flavor architectures. Syrup manufacturers are responding by investing in multi-stage flavor layering, juicy acid-sugar balances, and texture-enhancing additives that complement tapioca pearls, jellies, and popping toppings. Recent activity in the sector highlights this strategic pivot. Companies are actively showcasing advanced syrup portfolios at major international trade events, using platforms like TUTTOFOOD Milano, IFE London, and the Winter Fancy Food Show San Diego to preview formulations tailored to emerging consumer expectations. These exhibitions have become essential testing grounds for cross-category inspiration, where fruit-forward blends, dessert-inspired reductions, and botanical accents are evaluated for mainstream commercial viability.
Equally significant is the acceleration of functional and health-aligned formulations. Consumer habits are evolving toward reduced-sugar, natural, and functional syrup concepts, including adaptogen-infused flavors and clean-label profiles. Syrup suppliers that embed these attributes early are capturing premium positioning and building loyalty with health-conscious operators. The competitive advantage now lies not just in taste replication but in delivering formulations that align with broader wellness narratives without sacrificing the indulgent experience that defines bubble tea.
Regulatory Pressure as a Catalyst for Quality Infrastructure
Food safety regulations in major Western markets have tightened considerably, requiring extensive testing, certification, and documentation for imported syrups. Rather than treating compliance as a reactive hurdle, leading manufacturers are using regulatory convergence as a driver of operational excellence. Suppliers are building internal quality frameworks that integrate HACCP, ISO, FDA, and Halal standards, creating multi-certified product lines that can cross borders with reduced friction. This shift is also reshaping buyer expectations. Franchise chains and QSR operators now prioritize suppliers who can demonstrate auditable quality processes across multiple jurisdictions, effectively turning regulatory capability into a procurement differentiator.
Cost Structure and Supply Chain Reconfiguration
Raw materials account for roughly 45-55% of operating expenses in bubble tea-related manufacturing, with sweeteners and fruit derivatives representing the largest cost blocks. This concentration makes cost volatility a strategic risk. Industry participants are responding by diversifying sourcing geographies, securing forward contracts for key inputs, and investing in formulation optimization to reduce dependency on price-sensitive commodities. Several manufacturers are also exploring concentrated juice and pulp integration to add perceived value while managing base ingredient costs. The broader effect is a supply chain under structural recalibration, where resilience and cost predictability are becoming as important as flavor performance.
Worldwide Flavor Tea Market
Competitive Landscape: Positioning, Diversification, and Consolidation Signals
The market remains relatively fragmented, with CR3 and CR5 concentration levels at 22.4% and 31.8% respectively. This structure leaves ample room for specialized players while simultaneously encouraging consolidation among manufacturers seeking scale, certification breadth, and geographic reach. Several core companies illustrate the strategic diversity emerging across the competitive field. Taiwan-based Sunnysyrup Food Co., Ltd. leverages more than six decades of manufacturing experience to offer concentrated juice, flavor syrups, popping boba, and full bubble tea ingredient suites, supported by OEM/ODM capabilities. Its active presence at multiple international trade shows reflects a go-to-market strategy centered on showcasing integrated solutions rather than single-ingredient transactions.
Chinese manufacturer Zonegoing Food has built its positioning around bulk boba syrup supply, including caramelized milk and brown sugar varieties, backed by HACCP, ISO, FDA, and Halal certifications. This multi-certification footprint enables cross-border flexibility and supports wholesale and private-label partnerships. Meanwhile, Fanale Drinks differentiates through ingredient transparency, offering flavoring syrups made in Taiwan with up to 25% real fruit juice and pulp, targeting operators seeking premium fruit-forward positioning. On the distribution side, Bossen and Qbubble serve as wholesale gateways, with Qbubble adding training and consultation services to deepen operator relationships beyond ingredient supply. Inspire Food Company has carved out a European leadership role by combining syrups, popping boba, tapioca pearls, and accessories into a single-channel offering, simplifying procurement for regional operators. Possmei extends its Taiwanese manufacturing base through U.S. agents and global distribution, while Yujie Food focuses on bulk syrups, jams, and cane sugar inputs, appealing to cost-sensitive and volume-driven segments.
Bubble Tea Market
The strategic divergence across these players points to a market that is simultaneously consolidating around certification and scale while fragmenting around niche differentiation. Leading manufacturers are moving beyond commodity syrup supply into integrated ingredient ecosystems, technical support, and portfolio depth. New entrants are likely to succeed by targeting underserved flavor specializations, functional claims, or regional compliance readiness rather than competing solely on price. The next phase of competitive evolution will favor companies that can combine formulation agility with reliable export infrastructure and clear brand narratives around quality, flavor authenticity, and operational support.
Future Outlook: Trends Shaping the Next Three to Five Years
Premiumization and Functional Flavor Convergence
Over the next three to five years, the syrup market is likely to see accelerated convergence between premium taste design and functional positioning. Consumers and operators will increasingly expect syrups that deliver layered flavor experiences while aligning with reduced-sugar, natural, or wellness-oriented narratives. This trend creates commercial opportunities for manufacturers who can develop clean-label bases, adaptogen or botanical additives, and fruit-forward formulations that command higher margins without alienating core indulgence buyers. Brands that invest early in R&D around these hybrid profiles will be better positioned to secure premium contracts with expanding tea houses and specialty beverage concepts.
Geographic Expansion in Asia Pacific and North America
Asia Pacific continues to anchor significant demand, supported by cultural familiarity, dense tea house networks, and rapid novelty adoption. North America remains a powerful growth engine driven by mainstream beverage experimentation, QSR integration, and wholesale distribution. Syrup suppliers that build localized portfolio strategies for these regions—adapting flavor intensity, packaging sizes, and certification readiness—can capture disproportionate share during the forecast period. Expansion success will depend less on blanket global offerings and more on region-specific product architectures that match local procurement habits and regulatory expectations.
Operational Resilience as a Competitive Moat
Supply chain volatility and raw material cost sensitivity will continue to reward manufacturers with diversified sourcing, forward procurement discipline, and formulation efficiency. Companies that treat cost resilience as a core capability rather than an operational afterthought will be better equipped to maintain pricing stability and margin protection. At the same time, regulatory divergence across markets will increase the premium on multi-certified production systems. The operational players that can scale while preserving compliance agility will hold a durable advantage, especially as larger franchise and retail buyers consolidate supplier lists around reliability and risk management.
Potential risks include overinvestment in narrowly defined flavor trends that may cycle quickly, escalating input costs that erode pricing power, and regulatory shifts that alter import requirements faster than supplier certification cycles can adapt. Navigating these uncertainties will require scenario-aware portfolio planning and flexible manufacturing footprints.
Strategic Actions for Decision Makers
For syrup manufacturers and ingredient suppliers: prioritize formulation platforms that can scale across premium, reduced-sugar, and functional variants without fragmenting production efficiency. Invest in multi-certification readiness and geographic sourcing diversification to reduce exposure to raw material volatility and import barriers. Use trade show channels and technical consultation services to deepen relationships with operators, turning ingredient supply into a broader operational partnership.
For investors evaluating exposure: focus on companies with credible OEM/ODM capabilities, multi-region certification coverage, and distribution infrastructure that supports export scalability. Favor business models that combine portfolio breadth with clear differentiation in flavor authenticity or functional positioning, as these are likely to command resilience in a fragmented but consolidating market. Monitor consolidation indicators, particularly around certification-driven M&A or regional distribution tie-ups.
For tea house operators, QSR buyers, and procurement teams: treat syrup selection as a strategic input that affects menu differentiation, compliance risk, and margin stability. Prioritize suppliers who can demonstrate consistent quality, regional certification coverage, and portfolio flexibility across fruit, brown sugar, and floral/herbal lines. Negotiate for formulation support and menu co-development where possible, since supplier collaboration can accelerate seasonal launches and reduce time-to-market for new offerings.
For operators, investors, and manufacturers seeking detailed segmentation data, region-specific demand mapping, and tailored scenario planning across the 2026-2032 forecast horizon, PW Consulting's full market research report provides deeper quantitative breakdowns and customized strategic guidance.
For detailed analysis of this topic, please visit the official page: Bubble Tea Syrup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tongbianling Jiaonang Market 5.85% CAGR: Why 78% China Share Defines 2032 Growth
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Tongbianling Jiaonang Market
Market Overview and Core Challenges
The global market for Tongbianling Jiaonang, a traditional Chinese medicine formulation primarily used for constipation relief, has demonstrated steady expansion over the past five years. Valued at approximately USD 85.0 million in 2025, the market is projected to reach USD 126.55 million by 2032, reflecting a compound annual growth rate of 5.85 percent. This trajectory underscores a consistent demand environment supported by demographic shifts, expanding access to over-the-counter traditional medicine, and growing acceptance of TCM-based gastrointestinal solutions in both domestic and select international markets. The growth pattern suggests a maturing yet still expanding ecosystem where volume expansion is gradually complemented by value-oriented formulation upgrades and channel diversification.
Despite this favorable backdrop, the market faces several structural challenges that shape commercial execution and long-term positioning. First, regulatory fragmentation across export destinations remains a persistent friction point. Products that are classified as OTC Class A traditional Chinese medicine under domestic standards encounter varying registration pathways, documentation requirements, and quality verification expectations when entering neighboring healthcare systems. This divergence creates compliance overhead and delays market entry for manufacturers pursuing cross-border distribution. Second, pricing pressure in domestic channels continues to compress margins for value-oriented SKUs. Competitive intensity among regional producers has led to a wide range of generic offerings, making it difficult for mid-tier brands to differentiate solely on formulation familiarity without reinforcing trust signals through quality management, packaging modernization, or clinical positioning. Third, channel migration is reshaping replenishment behavior. While traditional pharmacy networks still account for the majority of sales volume, digital commerce is gaining share among younger adults and urban consumers who prioritize convenience, repeat ordering, and transparent product information. Manufacturers that rely heavily on legacy distribution must adapt inventory planning and promotional design to avoid losing share to more agile players.
Taken together, these dynamics define a market that is growing but not necessarily becoming uniformly more profitable. The key inflection point for stakeholders lies in balancing scale-driven volume expansion with compliance readiness, channel relevance, and brand differentiation. Companies that treat regulatory navigation, pricing architecture, and digital channel engagement as integrated strategic priorities are better positioned to convert top-line growth into sustainable market advantage.
Key Demand Drivers Shaping Market Trajectory
Three interlocking forces are propelling the Tongbianling Jiaonang market forward: formulation and channel innovation, regulatory and policy evolution, and shifting demand-side behavior across patient demographics. Each driver reinforces the others, creating a landscape where commercial success depends on aligning product strategy with both compliance realities and consumer access patterns.
Formulation Innovation and Accessibility Improvements
Innovation in this segment is less about radical new molecular entities and more about optimizing established herbal combinations, improving consistency, and widening access through modern delivery and packaging. Producers are increasingly focusing on batch consistency, label clarity, and usage simplicity to reinforce OTC usability for elderly and long-term users. At the same time, select manufacturers are pursuing international product registration to validate quality standards and open new revenue channels. The successful completion of Indonesian drug registration for Tongbianling Jiaonang in late 2025 illustrates how regulatory validation can unlock export pathways and signal quality assurance to overseas buyers. Such milestones matter because they convert formulation familiarity into defensible market access, especially in countries where consumer interest in TCM-based digestive solutions is rising but regulatory scrutiny remains high.
Policy and Regulatory Environment
Policy dynamics are shaping both domestic confidence and export feasibility. On the domestic side, standardized OTC classification and dosing guidance provide a clear regulatory framework that supports consumer recognition and pharmacy stocking decisions. This clarity reduces uncertainty for retailers and helps maintain steady replenishment cycles. On the international side, however, the absence of uniform registration processes introduces variability. Public advisories in certain markets have highlighted concerns about unregistered imports and the need for local product verification. Rather than representing a fixed barrier, this environment rewards manufacturers that invest early in documentation, quality traceability, and regional compliance alignment. For companies with export ambitions, proactive regulatory planning is becoming a competitive differentiator rather than a back-office function.
Demand-Side Shifts Across Patient Groups
Demand patterns are increasingly influenced by demographic trends and self-care behavior. Elderly consumers represent a substantial share of usage, driven by age-related digestive concerns and habitual constipation management. Adults, including those with sedentary lifestyles or intermittent digestive discomfort, are also contributing to volume growth, particularly where convenience and repeat purchase ease are priorities. This dual demographic base supports a market where both clinical trust and everyday accessibility matter. Consumers are not only seeking symptom relief; they are also evaluating ease of purchase, packaging readability, and the credibility of product origin. As a result, manufacturers that align formulation communication with target user needs and provide clear usage guidance tend to resonate more effectively across both pharmacy and digital channels.
Wallichinine Market
Supply Chain and Cost Structure Dynamics
Supply chain considerations are exerting subtle but important influence on pricing and product availability. The domestic market includes a broad range of generic versions priced at accessible levels, which keeps the category affordable but also intensifies competition on cost. Producers that can manage raw material sourcing, manufacturing consistency, and distribution efficiency are better equipped to defend margins without eroding consumer trust. For export-oriented players, additional cost components such as registration, documentation, and localized quality verification can affect runway and pricing strategy. In this environment, operational discipline and selective scale advantages increasingly determine which manufacturers can compete on both affordability and reliability.
Competitive Landscape and Leading Strategies
The competitive field in the Tongbianling Jiaonang market is shaped by a mix of established domestic producers, regional manufacturers, and players with varying levels of international ambition. Market concentration indicates that a limited number of leading firms control a meaningful share of revenue, but the presence of multiple active producers suggests ongoing competition on formulation reputation, channel access, and pricing. This structure creates both opportunities for consolidation and room for differentiated positioning.
Strategic Positioning Among Leading Players
Leading manufacturers are pursuing distinct strategic postures that reflect their product portfolios, geographic focus, and channel strengths. One active producer holds a prominent position through its association with a widely recognized drug registration code and a formulation built around senna leaf, angelica, and cistanche for constipation relief. Its recent Indonesian drug registration demonstrates a deliberate push into regulated export markets, using compliance achievement as a gateway to international credibility. Another major player markets its product for heat-induced constipation, long-term bedridden constipation, and habitual elderly constipation, with a strong emphasis on international e-commerce distribution. This approach reflects a channel-led expansion strategy that prioritizes reach, repeat purchase convenience, and direct consumer engagement beyond traditional pharmacy networks. Other significant participants contribute to the broader ecosystem by producing related or equivalent TCM constipation formulas, serving clinical and research channels, or maintaining listed-manufacturer status with national-standard specifications. Together, these players illustrate a market where differentiation arises from a combination of formulation narrative, regulatory readiness, channel strategy, and supply reliability.
Worldwide Oblong Jar Market
Differentiation Beyond Price
Because generic alternatives are available at accessible domestic price points, sustained differentiation increasingly depends on trust-building elements rather than cost alone. Manufacturers that can demonstrate consistent quality, clear labeling, and reliable availability are better positioned to defend shelf presence and digital visibility. For international expansion, documented regulatory approvals and adherence to destination-market requirements provide additional credibility. In domestic settings, product education, pharmacy relationships, and packaging clarity can serve as practical differentiators that help brands stand out without relying solely on promotional discounting.
Consolidation, Fragmentation, and New Entry Dynamics
The market appears to be moving toward a dual trajectory. On one hand, larger producers with established compliance infrastructure and broader distribution networks are well placed to capture share from smaller or less organized competitors, especially as regulatory and export requirements become more demanding. On the other hand, regional manufacturers continue to serve local price-sensitive segments, and digital channels lower entry barriers for brands that can compete on convenience and consumer messaging. New entrants or expanding players therefore face a choice: compete on affordability in crowded domestic segments, or invest in compliance and channel capabilities to access higher-value export and digital opportunities. The balance between consolidation and fragmentation will likely depend on how quickly regulatory harmonization progresses in key export markets and how fast digital commerce reshapes purchasing behavior.
Future Outlook and Emerging Trends
Looking ahead to the next several years, the Tongbianling Jiaonang market is likely to be shaped by three major trends, each carrying distinct commercial implications.
Steady Growth with Channel Rebalancing
Market expansion is expected to continue at a moderate pace, supported by demographic demand and broader acceptance of OTC TCM solutions. However, the composition of growth will increasingly shift toward channels that offer convenience, repeat ordering, and stronger consumer data feedback. Manufacturers that align supply planning, packaging, and promotional execution with digital and retail pharmacy dynamics will be better positioned to capture this rebalancing. The commercial opportunity lies not just in selling more units, but in building channel-relevant customer journeys that reduce friction and improve replenishment consistency.
Regulatory Validation as a Market Access Lever
As export interest grows, regulatory approval and quality documentation will become more central to commercial strategy. Milestones such as overseas registration validate product standards and open doors to distributors and retailers who require assurance before stocking imported OTC products. This trend favors manufacturers that treat regulatory investment as a pathway to market access rather than a compliance cost. The related risk is that uneven registration timelines and varying documentation expectations can slow expansion plans, making phased market prioritization and realistic compliance budgeting essential.
Differentiation Through Trust, Clarity, and Consistency
With multiple generic options available, future competition will increasingly reward brands that communicate clear usage guidance, consistent quality, and reliable availability. This is especially relevant for elderly users and caregivers who value straightforward instructions and dependable supply. Companies that strengthen these attributes can limit direct price confrontation and build more resilient demand. At the same time, the risk of advisory notices or quality concerns in unregulated import channels underscores the importance of maintaining strong documentation and respecting destination-market requirements. Commercial players that proactively manage these trust factors will be better insulated against reputation and compliance disruptions.
Strategic Actions for Decision Makers
For manufacturers, the priority is to align product strategy with both domestic affordability and international compliance readiness. This means investing in formulation consistency, documentation rigor, and channel-specific packaging or labeling that supports pharmacy stocking and digital selling. Where export markets are targeted, early regulatory planning and phased geographic prioritization can reduce time-to-access risk while protecting operating margins.
For investors, the market offers exposure to a steadily expanding OTC TCM category, but value creation will depend on selecting operators with credible compliance execution, channel adaptability, and clear differentiation beyond pricing. Due diligence should emphasize regulatory milestones, distribution resilience, and the ability to manage generic competition without eroding brand trust. Companies that combine scale efficiency with targeted international validation are more likely to generate durable returns in a fragmented but growing landscape.
For procurement and distribution stakeholders, the practical focus should be on supply reliability, documentation transparency, and channel fit. Evaluating suppliers on consistency of availability, clarity of product information, and readiness to meet local registration or quality expectations can reduce downstream risk. Building relationships with manufacturers that demonstrate both domestic reach and export discipline provides a stronger foundation for long-term category management. In a market where detailed segment dynamics, pricing structures, and regional access conditions vary meaningfully, comprehensive market intelligence can help decision makers time entry, prioritize segments, and tailor strategy with greater confidence.
PW Consulting Health Care Research Center
For detailed analysis of this topic, please visit the official page: Tongbianling Jiaonang Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com