

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Plastic Food Containers Market Report: Why 6.98% CAGR Signals Strategic Shifts

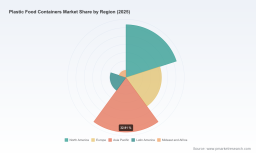
Strategic Trends and Commercial Opportunities in the Plastic Food Containers Market
The plastic food containers market has entered a defining phase, shaped by steady demand expansion, shifting regulatory expectations, and an intensifying race toward sustainable materials. Valued at approximately USD 215.0 million in 2025 and projected to reach USD 344.8 million by 2032, the sector is advancing at a compound annual growth rate of 6.98 percent over the forecast period. This trajectory reflects more than incremental volume growth; it signals a structural transition in how food is packaged, distributed, and consumed across household and commercial channels. Market participants are navigating a landscape where performance, compliance, and circularity increasingly determine competitive positioning.
Market Landscape and Core Challenges
The market has demonstrated consistent expansion since 2020, with revenue compounding from roughly USD 163.15 million to a 2025 baseline near USD 215.0 million. The upward momentum is expected to continue through 2032, though the pace will be uneven as regional maturity, product mix, and regulatory adoption diverge. A moderately fragmented landscape persists, with the top three firms capturing 24.6 percent of revenue and the top five firms representing 26.2 percent. This concentration suggests that scale advantages coexist with room for differentiated players to compete on innovation, regional reach, and specialized applications rather than price alone.
Despite the favorable growth path, the industry faces three structural challenges that will shape margin dynamics and go-to-market strategies over the next several years. First, sustainability mandates are compressing traditional design cycles and forcing material substitution decisions that carry cost and performance trade-offs. Companies must reconcile recyclability targets, recycled content requirements, and consumer expectations while preserving functional properties such as heat resistance, shelf life, and leak protection. Second, raw material price volatility continues to pressure unit economics. Resin costs, energy inputs, and logistics expenses have introduced greater variability into production planning, making procurement strategy and hedging decisions more consequential. Third, regulatory fragmentation across jurisdictions is increasing compliance complexity. Divergent rules on single-use items, expanded polystyrene, PFAS restrictions, and recycled content create a patchwork that favors firms with robust regulatory intelligence and flexible manufacturing footprints.
These challenges are not purely defensive. They are reshaping value pools by rewarding capabilities in material science, supply chain agility, and compliance readiness. Firms that treat sustainability and regulation as design constraints rather than afterthought considerations are better positioned to capture premium segments and secure long-term customer relationships.
Key Demand Drivers
Material Innovation and Performance Breakthroughs
Material innovation is emerging as a primary engine of differentiation. The industry is moving beyond conventional resin formulations toward BPA-free architectures, compostable fibers, and natural polymer systems that retain or improve performance while addressing end-of-life concerns. Joint development efforts are accelerating the translation of laboratory concepts into commercial packaging, particularly where moisture barriers, thermal stability, and structural integrity must be maintained without relying on traditional additives. Recent collaborations signal a broader shift: the market is seeing coordinated work between packaging producers and specialty material suppliers to create fully plastic-free and biodegradable solutions built on natural polymers, alongside recyclable paper alternatives for confectionery and other sensitive categories. These advances expand the commercial envelope for foodservice operators who need to meet sustainability commitments without compromising food quality or handling convenience.
Worldwide Plastic Sterilization Containers Market
The commercial implication is clear. Packaging is increasingly a strategic asset rather than a commodity input. Buyers are evaluating suppliers on material safety, recyclability pathways, and compatibility with circular systems. Suppliers that can demonstrate verified performance, transparent lifecycle attributes, and scalable production will command stronger positioning in both household and commercial segments.
Regulation and Compliance as Market Architecture
Regulatory developments are no longer peripheral; they are becoming the scaffolding around which product portfolios, sourcing strategies, and regional expansion plans are built. The Packaging and Packaging Waste Regulation entered into force in early 2025 and is set to generally apply later in the year, with expectations that recyclable packaging will be mandatory by 2030 and that recycled plastic use in EU packaging will increase. In the United States, California finalized permanent regulations for its packaging extended producer responsibility program, establishing producer fees for single-use plastic food service ware and a mandatory 25 percent recycling rate for expanded polystyrene. Meanwhile, Virginia implemented a ban on single-use plastic food containers for large food businesses, with full expansion to all vendors scheduled for mid-2026.
These measures create two simultaneous effects. They raise the compliance bar for legacy materials, particularly expanded polystyrene and non-recyclable formats, while also opening space for alternative designs that align with extended producer responsibility economics and recycling infrastructure. For manufacturers, this means product roadmaps must account for jurisdictional timelines, fee structures, and end-market recycling availability. For investors, regulatory tailwinds can validate capital allocation into recyclable, compostable, and fiber-based lines, but only where end-user adoption and collection infrastructure can support scale.
Demand-Side Shifts in Household and Foodservice Channels
Demand patterns are evolving on both sides of the market. In household use, consumers continue to prioritize convenience, food safety, and storage efficiency, but purchasing decisions are increasingly influenced by perceived health safety and environmental impact. BPA-free containers have gained traction as a baseline expectation rather than a premium feature, reflecting broader awareness of material safety in food contact applications. In commercial and foodservice channels, operators are balancing cost discipline with brand positioning around sustainability. Quick-service and delivery models depend on containers that withstand microwave heating, maintain temperature integrity, and resist leakage during transit, while also meeting corporate sustainability targets and local ordinance requirements.
These demand dynamics create a split incentive structure. Household buyers reward safety, clarity, and convenience, while commercial buyers reward volume reliability, compliance, and brand alignment. Suppliers that can tailor product attributes to each channel, without over-indexing on a single use case, are better equipped to capture cross-channel growth. The market is therefore rewarding flexible product architectures and application-specific engineering over uniform commodity offerings.
PW Consulting Health Care Research Center
Supply Chain and Cost Structure Dynamics
Cost structure volatility is a persistent theme. Resin pricing, energy costs, and transportation expenses have introduced variability into production planning and margin forecasting. The U.S. Producer Price Index for plastics material and resin manufacturing has reflected elevated levels, underscoring the sensitivity of input costs to macroeconomic and feedstock conditions. In this environment, procurement strategy, contract design, and production scheduling are becoming competitive levers. Companies are increasingly seeking to stabilize input exposure through long-term agreements, diversified sourcing, and operational efficiency programs that reduce scrap and rework.
The broader implication is that cost leadership will depend less on sheer volume and more on resilience and precision. Manufacturers that can manage resin exposure, optimize changeover times, and maintain quality consistency under input cost pressure will protect margins more effectively than those relying solely on price negotiation. This dynamic also favors regional production strategies that shorten lead times and reduce transport exposure for bulky food containers.
Competitive Landscape and Leading Strategies
The competitive field features global container specialists, foodservice packaging producers, and paper-based packaging suppliers that are extending into plastic and hybrid formats. Several firms have established distinct strategic positions. Amcor operates as a global leader in rigid plastic containers, including polypropylene and PET food containers and trays for foodservice, leveraging scale and application engineering across multiple regions. Huhtamaki produces polypropylene and paper-based disposable food containers and takeaway packaging, with a visible push toward recyclable and biodegradable formats. Dart Container Corporation has expanded its ProPlanet compostable fiber and plastic food containers for foodservice and retail, including PFAS-free solutions, reflecting a focus on compliance-friendly sustainable lines. Berry Global Inc. produces rigid plastic containers and packaging solutions for disposable food containers and foodservice, combining broad portfolio coverage with manufacturing flexibility. Pactiv Evergreen remains a leading manufacturer of foam and plastic foodservice containers and disposable packaging, while Genpak and Sabert serve quick-service and catering segments with durable plastic and paper disposable containers and hot/cold/catering solutions.
Additional players contribute to regional depth and specialty positioning. Novolex focuses on recycled and compostable plastic take-out containers and foodservice packaging. Anchor Packaging specializes in premium take-out and delivery plastic containers resistant to microwave and heat, targeting delivery-heavy operators. International Paper supplies paper-based and plastic food containers with sustainable packaging solutions and has moved to strengthen U.S. production capacity through a recent sustainable packaging facility expansion. Reynolds Consumer Products and Silgan Holdings continue to participate in plastic foodservice and takeaway containers and packaging, while Sealed Air provides protective and disposable plastic food packaging and containers. International exposure is also evident from exporters such as Jinhua Lanxin Commodity Co., Ltd., which supplies disposable plastic food containers, plates, and tableware for catering.
Plastic Caps Market
Several strategic patterns stand out. First, differentiation is increasingly product- and compliance-led. Expandable polystyrene portfolios face mounting regulatory and consumer pressure, while recyclable, compostable, fiber-based, and BPA-free lines are gaining attention from buyers seeking to align with sustainability targets and local rules. Second, partnerships and collaborations are accelerating material transitions. Recent joint development work on natural polymer-based, plastic-free, and biodegradable packaging, alongside conversions of plastic packaging to recyclable paper options in confectionery, indicate that incumbents are using ecosystem partnerships to reduce time-to-market for next-generation formats. Third, capacity and geographic alignment are being revisited. Investments in U.S. production and sustainable packaging facilities point to a desire to serve regional demand more efficiently while reducing transport exposure and improving responsiveness.
The market is likely to continue a dual trajectory. Consolidated leaders will compete on scale, breadth, and integrated feedstock-to-finished-product capabilities, while smaller and regional players will compete on application specialization, speed, and localized compliance readiness. M&A and partnership activity may intensify where companies seek to fill gaps in recyclable or compostable lines, expand geographic coverage, or acquire material science competencies. New entrants will find opportunity in niches where conventional players are slower to adapt, particularly in compostable fibers, PFAS-free constructions, and microwave-resistant premium delivery containers.
Forward Outlook: Three Trends for the Next 3 to 5 Years
Trend 1: Compliance-Driven Portfolio Rebalancing
Over the next several years, product portfolios will increasingly reflect jurisdiction-specific compliance requirements rather than one-size-fits-all designs. Recyclable packaging expectations, expanded polystyrene restrictions, and recycled content mandates will push manufacturers to maintain parallel product lines tailored to different regions and customer segments. This rebalancing will favor firms with strong regulatory monitoring, flexible tooling, and clear communication of end-of-life pathways. The commercial opportunity lies in helping buyers navigate transition timelines with products that meet near-term rules while remaining compatible with longer-term recycling and circular economy goals.
Trend 2: Sustainable Materials Moving from Differentiator to Baseline
BPA-free containers, recyclable paper alternatives, compostable fibers, and PFAS-free formulations are expected to shift from premium or niche offerings toward baseline expectations in selected channels. As major foodservice operators and household brands set public sustainability targets, procurement specifications will increasingly include material safety, recyclability, and reduced additive use as standard criteria. The opportunity is not simply to launch sustainable products, but to build verifiable performance data, scalable production, and transparent claims that withstand scrutiny from regulators, retailers, and consumers. Companies that can prove functionality alongside sustainability will be better positioned to protect price points and customer loyalty.
Trend 3: Regionalized Production and Input Cost Management
Given resin price volatility and the logistical footprint of bulky food containers, regional production strategies are likely to gain importance. Facilities positioned closer to demand centers can reduce transport costs, shorten lead times, and improve responsiveness to local regulatory shifts. At the same time, procurement teams will continue to refine resin sourcing, hedging, and scrap reduction to protect margins against input cost swings. The strategic value will accrue to operators that can combine regional capacity with disciplined cost control and consistent quality, especially in high-volume commercial and foodservice applications where reliability is paramount.
These trends carry inherent uncertainties. Regulatory timelines may shift or be implemented unevenly, recycling infrastructure may lag packaging design ambitions, and raw material costs may remain volatile. Consumer willingness to accept tradeoffs in price or convenience will also shape adoption speed. Market participants should therefore treat sustainability and compliance investments as adaptive capabilities, with clear triggers for scaling successful formats and withdrawing underperformers.
Action Considerations for Decision Makers
For manufacturers, the priority is to align product roadmaps with compliance trajectories and channel-specific performance needs. This means investing in recyclable, compostable, and BPA-free lines where demand is most credible, while maintaining the engineering rigor required for heat resistance, leakage control, and structural durability. Procurement and production teams should also strengthen input cost resilience through diversified resin sourcing, longer-term contract structures where feasible, and continuous improvement in scrap and energy efficiency. Regional capacity decisions should be evaluated against local demand density, regulatory timing, and transport economics, particularly for bulky foodservice packaging.
For investors, the key is to distinguish between sustainability claims and scalable, commercially viable solutions. Preference should be given to companies with verified material performance, clear recycling or composting pathways, and manufacturing footprints that can respond to regional regulation. Growth exposure may be strongest where portfolios are expanding into PFAS-free compostable fibers, microwave-resistant delivery containers, and recyclable paper alternatives, especially if supported by partnerships that reduce development risk. Capital allocation should also account for the pace of infrastructure development, since end-market recycling and collection capacity will influence the practical impact of regulatory mandates.
For procurement and purchasing leaders, the focus should be on building supplier partnerships that can navigate a fragmented compliance environment without disrupting supply continuity. Evaluation criteria should include material safety, recyclability evidence, compatibility with delivery and heating workflows, and the supplier’s ability to adapt portfolios as regulations evolve. Multi-region sourcing and flexible specification management can help balance cost, compliance, and performance, particularly when local ordinances diverge on expanded polystyrene or single-use items. Maintaining visibility into resin cost trends and regional regulatory changes will also support more informed negotiation and inventory planning.
In a market advancing at a steady 6.98 percent CAGR through 2032, the winners will be those who convert sustainability, compliance, and cost volatility into structured competitive advantages. Detailed segmentation data, company-level tracking, and scenario modeling can sharpen these decisions further by illuminating where growth is concentrating, how portfolios are shifting, and which capabilities will matter most in each channel. For decision makers seeking a deeper view of regional dynamics, application splits, and company strategies, the full research report provides the granularity needed to translate these trends into targeted action.
For detailed analysis of this topic, please visit the official page: Plastic Food Containers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com