

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Aquaculture Cages Market: Why 6.8% CAGR and Asia Pacific’s 126.14M Dominance Redefine Market Dynamics

Navigating the Aquaculture Cages Market: Strategic Shifts, Competitive Realignment, and Commercial Opportunities
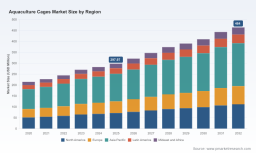
The aquaculture cages market has evolved from a niche equipment segment into a critical infrastructure layer for global protein production. As of 2025, the market stands at approximately $298 billion in revenue, reflecting a steady upward trajectory from $214 billion in 2020. The compound annual growth rate of 6.8 percent through 2032 signals more than linear expansion; it points to a structural shift in how finfish and shellfish are cultivated at scale. Over the next seven years, the market is projected to cross $464 billion, driven by intensifying demand for controlled aquatic production, evolving regulatory expectations, and the gradual replacement of aging cage infrastructure with higher-performing systems. This momentum is not uniform across all segments or geographies, but the underlying direction is clear: aquaculture is moving toward more robust, compliant, and technologically integrated cage architectures.
For executives and investors, the scale of this market is only the starting point. The real strategic value lies in understanding where capital efficiency, regulatory alignment, and technological readiness converge. Cages are no longer passive containment structures; they function as platforms that influence disease exposure, environmental footprint, operational labor, and ultimately, the economic viability of farms. The market’s growth is being shaped by a combination of cyclical replacement cycles, long-term expansion in high-density farming regions, and a growing emphasis on systems that can withstand harsher marine conditions while meeting stricter compliance thresholds. These forces are creating new decision points for manufacturers, farm operators, and capital allocators who must balance short-term procurement costs against long-term operational resilience.
Key Challenges and Inflection Points Shaping the Market
The industry is navigating several structural challenges that will redefine competitive advantage over the next few years. First, environmental compliance and waste management pressures are accelerating the retirement of legacy cage designs. Stricter oversight around water quality, nutrient dispersion, and disease control is pushing operators to adopt cage configurations that support better monitoring, improved water exchange, and reduced localized impact. This transition is not merely a regulatory checkbox; it directly affects permitting timelines, community acceptance, and access to premium buyer channels. Operators that continue to rely on outdated containment approaches face increasing operational friction, while those that modernize early can secure faster approvals and build stronger market positioning.
Second, the durability-versus-cost equation is creating a procurement inflection point. High-density polyethylene (HDPE) cages have become the dominant choice in marine environments because of their resilience under rough sea conditions, flexibility in large-scale deployments, and extended service life. In marine settings, HDPE typically delivers seven to ten years of effective operation, while freshwater applications can stretch that range to ten to fifteen years. This longevity reduces replacement frequency and total cost of ownership, even though the initial material outlay runs 25 to 35 percent higher than alternative options. For farm operators, the decision is increasingly about lifecycle economics rather than upfront price. For equipment suppliers, it means that differentiation is shifting toward proven longevity, corrosion resistance, and ease of maintenance rather than simple cost competition.
Third, regulatory and certification dynamics are reshaping market access. Standards associated with responsible aquaculture practices and environmental stewardship are incentivizing producers to upgrade infrastructure in order to qualify for premium market segments. At the same time, tighter restrictions tied to biomass limits, overfishing concerns, and cage placement rules are introducing constraints that can temper growth in certain regions or applications. These dual pressures create a strategic paradox: compliance and certification open doors to higher-value channels, but they also raise the bar for entry and increase the cost of non-compliant operations. Companies that treat regulatory alignment as a core engineering requirement rather than a downstream compliance task are better positioned to scale without disruption.
Key Drivers of Market Change
The market’s growth trajectory is being propelled by a combination of technological, regulatory, demand-side, and supply-chain forces. Each driver has distinct implications for equipment strategy, risk management, and commercial positioning.
Technological innovation remains one of the most visible catalysts. Manufacturers are moving beyond basic containment toward integrated cage systems that support semi-closed or closed configurations, improved structural stability, and stronger compatibility with monitoring and handling equipment. Recent product supply agreements illustrate this shift in practice. For example, in late 2024, a supplier committed to providing semi-closed fish cages for floating closed cage systems, reinforcing the trend toward containment designs that offer better control over water quality and biological risk. Such arrangements are not isolated transactions; they reflect a broader preference for systems that can reduce environmental leakage, improve biosecurity, and support more predictable production cycles.
Policy and regulatory environments are equally influential. Stringent rules around water quality, waste management, and disease control are making advanced cage designs and integrated monitoring systems more attractive, and in many cases necessary. Certification frameworks and recognized stewardship standards add further momentum by rewarding infrastructure upgrades that unlock premium pricing or preferred supplier status. This regulatory layer is especially important for operators seeking to expand in regions where permitting, environmental impact assessment, and community scrutiny are becoming more rigorous. The practical implication is clear: cage design decisions are increasingly tied to long-term license to operate, not just short-term production needs.
Demand-side behavior is also reshaping the market. Consumers, food retailers, and foodservice buyers are paying greater attention to sourcing practices, environmental impact, and traceability. This shifts commercial value toward producers who can demonstrate consistent quality, lower environmental risk, and more controlled production conditions. Cage systems that support better biological management, reduced escape risk, and cleaner production profiles can become enablers of brand differentiation. For equipment providers, this means that product value is increasingly linked to the operational outcomes their systems help customers achieve, including yield stability, compliance readiness, and market access.
Supply chain and cost structure changes are adding another layer of complexity. Material availability, fabrication capacity, and logistics for large marine-grade components influence both lead times and pricing. The dominance of HDPE reflects not only performance advantages but also a mature supply base that can support large-scale production and replacement programs. At the same time, the higher upfront cost of durable materials requires financing-aware procurement strategies, especially for mid-sized operators. Companies that can offer lifecycle cost clarity, service support, and modular replacement options are gaining an edge in markets where operators need to manage capital constraints while maintaining operational continuity.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a moderate level of concentration, with the top three players accounting for roughly 24.5 percent of the market and the top five reaching about 28.5 percent. This structure suggests a market that is still open to regional specialists and targeted innovators, but where scale, product breadth, and technical credibility increasingly matter. The leading companies are not competing on cage volume alone; they are building differentiated positions around material expertise, structural design, and containment technology.
Several Norwegian and European firms anchor the high-end segment of the market. One global leader has built a strong reputation in plastic pens and cage systems, offering HDPE cages and broader technology solutions for marine and inland fish farming. Its positioning reflects an emphasis on complete system capability rather than isolated component supply. Another European specialist focuses on net cages and submersible cage systems, including models designed for exposed sea sites. This capability highlights a strategic focus on environments where structural stability and containment performance under demanding conditions are critical. A third Norwegian supplier contributes additional differentiation through a broad material range, including nylon, HDPE, Dyneema®, and UHMWPE, across circular, rectangular, and specialized cage formats. This material versatility allows the company to address varied operational conditions and customer preferences, particularly where strength-to-weight characteristics or specific environmental tolerances matter.
Worldwide Fish Farming Equipment Market
In parallel, Mediterranean and Asian manufacturers are expanding the market’s regional depth and cost-performance options. An Italian group has strengthened its portfolio by broadening its aquaculture containment solutions, including a recent acquisition that extended its offer set. This type of consolidation signals a move toward broader solution capabilities and more integrated customer offerings. Chinese manufacturers are also playing a growing role, particularly in offshore HDPE cages and net cage systems for neritic and deeper water applications, alongside suppliers focused on HDPE and related net cage products. Another Chinese manufacturer emphasizes marine and freshwater cage and netting products, reinforcing the region’s broad production capacity. Meanwhile, an Indian manufacturer has carved out a distinct position through high-performance synthetic netting materials and solutions, underscoring the importance of material science in cage durability and performance. A separate Israeli provider illustrates the convergence of cage systems with broader recirculating technology, offering floating closed fish cage systems and integrated approaches that bridge offshore and land-based production needs.
The strategic takeaway is that competition is fragmenting by application environment, material specialization, and system integration. Leading players are differentiating in three main ways: engineering for durability and stability in challenging sea conditions, expanding containment and closed-system capabilities, and broadening portfolios through acquisition or product expansion. At the same time, the moderate concentration levels indicate room for agile entrants, especially those targeting niche applications, specific materials, or regional demand pools. The market is therefore unlikely to consolidate into a single dominant model; instead, it will likely continue to reward companies that can align product strengths with clear operational outcomes and compliance requirements.
Recent corporate activity reinforces this direction. In late 2024, one supplier agreed to continue supplying semi-closed fish cages for floating closed cage systems, indicating renewed demand for containment approaches that improve biological and environmental control. Around the same period, another group completed an acquisition to expand its aquaculture containment solutions portfolio. These moves are not merely incremental; they reflect a strategic preference for broader solution coverage, stronger positioning in higher-value system configurations, and closer alignment with operators seeking more controlled production environments.
Future Trends and Commercial Opportunities
Looking ahead to the 2026–2032 period, three trends are likely to define the market’s next phase of development. The first is the continued shift toward higher-performance, longer-life cage systems in marine and exposed environments. As operations scale and site conditions become more demanding, the practical value of durable HDPE and advanced netting materials will increase. Commercial opportunities will accrue to suppliers that can prove service-life advantages, reduce downtime, and provide replacement and maintenance strategies that lower total cost of ownership. For operators, the opportunity lies in standardizing on cage architectures that can be deployed across multiple sites with consistent performance, thereby simplifying training, maintenance, and procurement.
The second trend is the growing importance of containment and semi-closed or closed cage solutions. Biosecurity, waste management, and site permitting pressures are making controlled-environment cage systems more relevant, especially where environmental sensitivity or disease risk is high. This trend creates opportunities for equipment providers that can integrate cage design with monitoring, handling, and operational support, as well as for operators that can use these systems to strengthen their market positioning. The commercial logic is straightforward: systems that help reduce biological and environmental risk also help stabilize production and improve access to buyers that value predictable, responsibly sourced supply.
PW Consulting Health Care Research Center
The third trend is regulatory-driven infrastructure modernization. As water quality, waste, and disease-related requirements become more rigorous, and as certification and stewardship expectations influence market access, cage upgrades will increasingly be treated as strategic investments rather than discretionary purchases. This trend favors suppliers that can help operators navigate compliance requirements through design choices, documentation, and operational compatibility. It also favors operators that modernize early enough to avoid permitting delays and to secure access to premium market channels. The uncertainty here lies in the pace and variability of regulatory enforcement across regions, which can create uneven adoption curves and affect near-term demand patterns.
Alongside these opportunities, there are risks that decision-makers should monitor. Overly restrictive placement rules or biomass constraints could limit expansion in certain areas, even as demand continues to grow elsewhere. Material cost volatility and fabrication bottlenecks could affect project timing, particularly for large offshore deployments. In addition, the market’s moderate concentration means competitive intensity may increase as regional players expand portfolios or as new entrants target specific applications with lower-cost or higher-specialization offerings. Companies that rely on narrow product lines or single-region exposure may face more pressure than those with diversified application coverage and stronger lifecycle support capabilities.
Strategic Actions for Decision-Makers
For manufacturers and equipment suppliers, the priority is to align product roadmaps with the market’s shift toward durability, containment, and compliance-enabling design. This means investing not only in HDPE and advanced netting capabilities, but also in system configurations that support monitoring, maintenance, and modular replacement. Differentiation will increasingly come from demonstrating measurable operational outcomes, such as reduced replacement frequency, improved structural resilience, and easier integration with farm workflows. Suppliers should also prepare for a competitive environment where portfolio breadth and targeted acquisitions can strengthen positioning in higher-value containment segments.
For investors, the most relevant question is where growth will be most defensible. The market’s projected expansion suggests continued demand, but value capture will depend on exposure to the right applications, materials, and system types. Investments in companies with strong marine durability expertise, containment system capabilities, and credible service and support models are better aligned with the market’s structural direction than those focused solely on low-cost commodity exposure. At the same time, regulatory uncertainty and regional variability mean that portfolio diversification and scenario planning are essential, particularly when evaluating companies with concentrated geographic or application dependence.
Laboratory Animal Housing Cage Market
For procurement leaders and farm operators, the strategic focus should be on lifecycle economics and compliance readiness rather than initial price alone. Selecting cage systems with longer service life, stronger material performance, and better compatibility with monitoring or containment requirements can reduce long-term disruption and support expansion plans. Early alignment with certification and stewardship expectations can also improve market access and reduce the risk of future retrofit costs. Where possible, operators should evaluate suppliers based on total cost of ownership, service availability, and the ability to support standardized deployment across multiple sites.
The pace of change in this market makes detailed, segment-level intelligence increasingly valuable. Regional demand patterns, material substitution trends, regulatory timing, and competitive moves can alter procurement timing, pricing assumptions, and investment priorities in ways that broad market figures alone cannot capture. Decision-makers who need clearer visibility into application-specific demand, regional dynamics, and company-level positioning will benefit from deeper coverage that translates market growth into operational and commercial choices. For those evaluating expansion, procurement strategy, or capital allocation, a more detailed research view can help convert the market’s momentum into a practical plan.
For detailed analysis of this topic, please visit the official page: Aquaculture Cages Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com