

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Organic Dairy Products Market: Why 5.37% CAGR and $30.96B by 2032 Redefine Growth

Organic Dairy Products Market: Strategic Trends and Commercial Opportunities Through 2032
A Market Intelligence Perspective for Executives, Strategists, and Investors
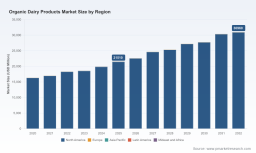
The organic dairy sector has moved from a niche premium segment into a structural component of the broader dairy economy. Over the past five years, the market has expanded from roughly $16.3 billion in 2020 to approximately $21.5 billion in 2025, reflecting sustained demand for certified organic milk, yogurt, cheese, butter, and cream across retail and foodservice channels. Forward projections indicate the market will reach approximately $31.0 billion by 2032, supported by a compound annual growth rate of 5.37 percent. This trajectory signals more than incremental premiumization; it reflects a durable shift in how consumers, retailers, and food manufacturers think about sourcing, labeling, and product formulation.
For decision-makers, the strategic question is no longer whether organic dairy will continue to grow, but how the growth will be distributed across product categories, channels, and geographies, and which operational capabilities will separate scalable operators from those squeezed by input costs, regulatory shifts, and quality-control pressures. The following analysis outlines the market’s current shape, the forces reshaping it, the competitive playbook of leading firms, and the trends that will define commercial opportunities over the next three to five years.
Market Context and Core Challenges
The organic dairy market has demonstrated consistent expansion, but the pace and composition of that growth vary meaningfully by product type and distribution path. Fluid milk remains the largest revenue contributor, followed by yogurt, cheese, butter, and cream. Supermarkets and hypermarkets continue to dominate volume distribution, while specialty stores and online channels represent smaller but strategically important pathways for brand building, margin management, and direct consumer engagement. Regionally, North America accounts for the largest share of market value, with Europe, Asia Pacific, Latin America, and the Middle East and Africa each representing distinct growth profiles shaped by local certification norms, retail infrastructure, and consumer familiarity with organic labeling.
A market of this scale and maturity is not immune to friction. Three challenges stand out as particularly consequential for operators and investors.
- Input cost volatility and margin pressure. Organic feed costs have remained elevated and uneven, with organic corn, soybean, and grain prices moving in ways that complicate budgeting for dairy producers and processors. Because organic systems depend on certified feed and pasture-based management, cost shocks translate quickly into producer economics and, ultimately, into pricing strategy for branded and private-label products.
- Supply utilization and demand balance. Recent federal milk marketing order data show organic whole milk utilization declining from one year to the next in key markets, even as the broader category continues to expand. This points to a market where aggregate growth can coexist with short-term utilization softness, channel shifts, or competitive substitution. Operators need to read utilization signals carefully rather than assuming uniform tailwinds.
- Quality assurance and reputational risk. Voluntary recalls across organic fluid milk and premium ice cream products in recent months highlight the operational reality that scale, packaging complexity, and production lot control can create exposure. In a category where trust is tied directly to certification and ingredient integrity, quality incidents can have outsized brand and retail-consequence effects.
These challenges do not undermine the market’s growth thesis, but they raise the bar for execution. Companies that can manage feed-cost exposure, interpret utilization trends with granularity, and maintain rigorous quality systems will be better positioned to convert category growth into stable margin performance.
Key Drivers Reshaping the Market
The expansion of organic dairy is being pulled by a combination of consumer behavior, regulatory clarity, supply-chain economics, and product innovation. Understanding how these forces interact is essential for strategic planning.
Consumer Demand and the Premiumization-Trust Matrix
Demand for organic dairy is no longer driven solely by price-insensitive premium buyers. A broader consumer base now treats organic certification as a baseline expectation for certain product categories, especially fluid milk and yogurt consumed by families, children, and health-conscious shoppers. This shift changes the commercial logic of the category: organic is increasingly a table-stakes attribute rather than a marginal differentiator, which means brands must compete on formulation, flavor, convenience, and trust signals as much as on certification itself.
At the same time, demand is increasingly shaped by nutritional and functional positioning. Products associated with omega-3 fortification, DHA, protein content, and clean-label profiles are gaining attention, particularly in shelf-stable and kid-facing formats. That creates opportunity for differentiated SKUs, but it also raises formulation and packaging complexity, which can increase quality-control risk if not managed carefully.
Regulatory Clarity and Certification Economics
Regulatory frameworks continue to shape both market access and operating costs. The Origin of Livestock final rule, effective from mid-2022, established more uniform standards for livestock transition and ongoing management, reducing ambiguity around what qualifies as organic dairy production. For the industry, clearer rules can improve confidence in labeling and reduce fragmented interpretations across buyers and suppliers, but they also require producers and handlers to align operations with consistent standards.
Organic Milk (Organic Milk Products) Market
Certification costs remain a practical consideration for smaller producers and new entrants. Programs that reimburse a significant share of certification fees can lower barriers to entry and help sustain a diversified producer base. For strategists, this matters because the long-term health of the organic dairy supply base depends on whether smaller farms and regional processors can remain economically viable alongside larger integrated operators.
Feed Costs, Grain Markets, and Producer Economics
Organic feed markets have their own price dynamics, and those dynamics influence the entire value chain. Recent reporting shows organic feed corn and soybean prices at elevated levels, with organic soft red winter wheat also trading at premiums in certain report periods. These input costs affect farm-level margins, milking herd decisions, and the economics of expansion or contraction in organic production.
For processors and brand owners, this environment underscores the importance of stable supplier relationships, forward contracting where feasible, and pricing strategies that can absorb input volatility without eroding consumer accessibility. For investors and strategic planners, feed-cost trends are not merely an agricultural issue; they are a structural factor in channel pricing, product rollouts, and the attractiveness of vertical integration.
Product Innovation and Channel Evolution
Innovation in organic dairy is moving along multiple paths. One is functional enhancement, such as omega-3 and DHA-enriched milk, which expands the category’s appeal beyond basic organic certification. Another is format expansion, including shelf-stable boxes, specialty ice cream, and cultured products that broaden usage occasions. A third is channel diversification, with online and specialty-store pathways enabling brand experimentation, targeted merchandising, and higher-margin positioning even as supermarkets and hypermarkets remain the dominant volume channel.
The strategic implication is that growth is not limited to selling more of the same. Companies can create value by aligning product architecture with consumer occasions, using channel mix to manage margin and exposure, and ensuring that innovation does not outpace quality systems.
PW Consulting Health Care Research Center
Competitive Landscape and Leading Strategies
The organic dairy market remains moderately concentrated, with the top three players holding a modest share and the top five still leaving a substantial portion of the market in the hands of regional brands, cooperatives, and specialty producers. That structure matters because it suggests room for differentiation, niche leadership, and targeted consolidation rather than a single dominant playbook.
Strategic Positioning Among Leading Operators
Several firms illustrate distinct approaches to scale, supply-chain control, and category focus.
- Large-scale integrated processors. Some leading operators manage extensive organic herds and dedicated processing facilities, enabling them to supply a broad lineup of fluid milk, cheese, butter, and yogurt across B2B and retail channels. Their strategic advantage lies in supply continuity, brand reach, and the ability to serve national retail and foodservice requirements with a consistent organic supply base.
- Farmer-owned cooperatives. Cooperative models combine production scale with a structural alignment to organic farm members. These organizations often emphasize full supply-chain control, diversified product sets that can include milk, cheese, butter, oat milk, and eggs, and direct payment relationships with farmers. The cooperative model can support supply resilience and brand trust, particularly when consumer narratives value farmer partnership and regional identity.
- Category-focused and heritage brands. Some established brands have built long-running reputations around specific product categories such as yogurt, fluid milk, and cultured dairy, often with emphasis on regenerative or pasture-based production. Their advantage typically comes from category credibility, consumer trust, and the ability to command premium positioning through storytelling and quality signaling.
- Specialized processors with traceability strength. Certain regional creameries and processors compete by emphasizing full organic traceability, premium product lines, and product-extension into adjacent categories such as ice cream. Their strategy often depends on strong local or regional demand, brand authenticity, and precise execution in production and distribution.
These models are not mutually exclusive, but they highlight a central strategic tension: scale can support national distribution and cost efficiency, while differentiation can support margin, loyalty, and category leadership. The most resilient organizations often combine enough scale to secure supply and distribution with enough distinct positioning to avoid competing solely on price.
Recent Events as Strategic Signals
Recent developments in the market illustrate the operational and market-dynamic realities that strategists must factor into planning.
- Quality and packaging exposure. Voluntary recalls involving shelf-stable flavored milk and organic super premium ice cream products show how packaging integrity and foreign-material control can affect even well-established brands. The practical takeaway is that product safety, packaging validation, and lot control are not back-office concerns; they are commercially material to brand equity, retail relationships, and consumer trust.
- Utilization signals in fluid milk. Recent federal milk marketing order data showing a decline in organic whole milk utilization in a major market order suggests that growth at the category level can coexist with fluctuating demand at the product or channel level. Operators should treat utilization data as an early indicator of shifting buying patterns, inventory dynamics, or competitive pressure rather than as a simple growth proxy.
- Feed market conditions. Elevated organic feed pricing reinforces the need for disciplined cost management and supplier strategy. In practical terms, operators with strong forward visibility and diversified sourcing options are better equipped to navigate periods when certified grain and feed costs move sharply.
How the Competitive Landscape Is Evolving
Three directional trends are shaping the next phase of competition.
First, consolidation pressure is likely to persist where scale, distribution access, and supply-chain control confer advantages. Larger integrated players and cooperatives with broad farm networks can use volume and continuity to strengthen retail and foodservice relationships, which may create acquisition or partnership opportunities for regional brands seeking broader reach.
Second, differentiation will remain powerful in subcategories. Yogurt, functional milks, premium ice cream, and specialty cheese can support distinct brand positions, especially when paired with clear claims around sourcing, pasture-based production, or nutritional benefits. In these subcategories, success depends less on brute scale and more on formulation, trust, and channel execution.
Third, new entrants and adjacent players may continue to test specific formats or channels rather than attempting to compete across the full dairy spectrum. Online-first brands, functional-product specialists, and regional processors targeting high-trust consumer segments can carve out profitable positions without needing to match national-scale infrastructure immediately. The risk is that such entrants can be vulnerable to quality incidents, input-cost swings, or retail listing barriers if they do not build operational depth alongside brand appeal.
Outlook: Three Critical Trends for the Next Three to Five Years
Looking ahead to the 2026–2032 period, the organic dairy market is likely to be shaped by a combination of steady category expansion, continued input and quality challenges, and increasing strategic importance of differentiation and channel strategy.
1. Growth will continue, but the upside will be uneven across products and channels
The projected market trajectory implies sustained double-digit growth in absolute terms over the forecast horizon, but that growth will not be uniform. Fluid milk will remain central, yet yogurt, cheese, and premium specialty items may outperform in specific subsegments if brands successfully align with functional, convenience, or indulgence occasions. Supermarkets and hypermarkets will likely remain the backbone of volume, but online and specialty channels can provide disproportionate strategic value for brand building, margin optimization, and consumer insight.
For businesses, this means portfolio allocation matters. Overexposure to a single product or channel can leave a company exposed to utilization softness or retail concentration risk, while a balanced mix can capture broader category growth and create more stable demand patterns.
2. Cost discipline and supply-chain reliability will become competitive advantages
As long as organic feed and grain markets remain subject to volatility, the winners will be organizations that treat supply economics as a strategic capability rather than a tactical procurement issue. That includes relationships with certified producers, risk management around input pricing, and the operational discipline to maintain margins without sacrificing accessibility in key retail formats.
This trend also has implications for vertical integration. Companies that control more of the chain—from farm relationships to processing to distribution—can gain predictability and quality control, but they also take on more operational complexity. The strategic question is whether integration improves resilience and margin stability in a way that justifies the added exposure.
3. Trust, certification, and quality systems will increasingly determine brand resilience
Organic dairy competes on trust as much as on taste or price. Certification clarity, consistent labeling standards, and strong quality controls are becoming central to brand durability. Recent recalls and utilization fluctuations show that even growing markets can experience disruptions that affect consumer confidence and retail logistics. Over the next few years, the brands that weather such events most effectively will likely be those that invest in traceability, packaging validation, production controls, and transparent communication.
At the same time, regulatory and certification environments may continue to evolve, influencing both access and operating costs. Organizations that monitor these changes proactively can adapt sourcing, labeling, and compliance practices ahead of competitors rather than reacting after market conditions shift.
Commercial Opportunities Linked to These Trends
These trends open several practical avenues for value creation.
- Portfolio tuning around occasion and function. Brands can prioritize products that fit family consumption, snacking, on-the-go, and functional-nutrition occasions, using format and fortification to differentiate within the organic frame.
- Channel mix as a margin and insight tool. Online and specialty channels can support higher-margin experimentation and direct consumer feedback, while mainstream retail provides scale. A deliberate channel strategy can balance reach and profitability.
- Supply resilience as a strategic asset. Long-term supplier relationships, certified-feed planning, and selective integration can reduce exposure to input volatility and improve execution consistency.
- Trust-led brand architecture. Clear certification practices, traceability storytelling, and disciplined quality systems can strengthen consumer and retail confidence, which is especially important in a category where reputation travels quickly.
Potential Risks and Uncertainties
The outlook is constructive but not risk-free. Feed-cost pressure could compress margins faster than pricing or efficiency gains can offset. Quality incidents could damage brand equity and retail relationships, particularly for products with complex packaging or lot-dependent production. Utilization softness in some fluid milk markets could signal channel-specific headwinds that require tactical response. Regulatory or certification developments could alter cost structures or market-access expectations. Finally, competitive intensity may increase if larger players consolidate supply and distribution or if new entrants target high-visibility subcategories with aggressive positioning.
Strategic Actions for Decision-Makers
The most useful response to this market is not simply to track its growth, but to align strategy with the forces that will determine who converts growth into durable advantage.
For Manufacturers and Brand Owners
- Build portfolio and pricing strategies that reflect product-level utilization realities rather than assuming uniform category momentum. If organic whole milk utilization is softening in certain markets, examine whether the issue is channel-specific, occasion-driven, or competitive, and adjust merchandising, format, or innovation priorities accordingly.
- Treat quality and packaging validation as core strategic investments. In categories where trust and certification matter, reliability in production, lot control, and packaging integrity can be as commercially important as product features.
- Manage feed and input exposure proactively. Where possible, strengthen supplier relationships, evaluate forward planning options, and align pricing and margin models with realistic input-cost scenarios rather than optimistic baselines.
For Investors
- Assess companies on supply-chain resilience and operational discipline, not just brand recognition. Scale, traceability, quality systems, and feed-cost management can be decisive in sustaining margins through cycle pressure.
- Look for positioned leadership in subcategories where trust and differentiation can command premium economics, such as functional milks, yogurt, or premium specialty items, while remaining attentive to the operational capability required to deliver them consistently.
- Monitor consolidation potential and cooperative dynamics. Structures that align producers with processing and branding can influence supply stability, cost behavior, and long-term competitive positioning.
For Procurement and Channel Leaders
- Use channel mix strategically. If mainstream retail is the volume engine, consider how online and specialty pathways can support margin, insight, and brand reinforcement without overexposing the business to channel-specific risk.
- Prioritize suppliers and partners with strong certification discipline and transparent sourcing. In organic dairy, the reliability of certification and traceability can affect both compliance confidence and consumer perception.
- Plan for input-cost volatility in sourcing and price negotiations. Where procurement strategies assume stable costs, they may underprepare for periods when organic grain and feed markets move sharply.
The strategic picture is clear enough to act on, but granular enough that execution quality will separate winners from followers. Market-level growth signals provide direction; product-level utilization, feed economics, quality performance, and channel dynamics determine outcomes. Decision-makers who combine category awareness with operational specificity will be better equipped to allocate capital, shape portfolios, and manage risk through the rest of the decade.
For leaders who need deeper segmentation, regional breakdowns, product-level revenue paths, channel detail, and company-specific competitive profiles, the full research report provides the structured data and customized analysis required to translate these strategic themes into precise planning assumptions.
Liquid Dairy Products Market
For detailed analysis of this topic, please visit the official page: Organic Dairy Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com