

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Gaucher Disease Market: Why 6% CAGR and High Concentration Reshape Strategy

Navigating the Gaucher Disease Market: Strategic Trends and Commercial Opportunities (2025–2032)
The Gaucher disease market has evolved from a niche orphan indication into a structured commercial landscape shaped by diagnostic maturation, expanded therapeutic options, and increasing payer scrutiny. Measured across recent historical years and extended through the forecast horizon, the global market reached approximately 168.56 million USD in 2025 and is projected to climb to 252.31 million USD by 2032, reflecting a compound annual growth rate of 6.0 percent. This trajectory is not merely a function of patient population growth; it is the result of deliberate therapeutic innovation, shifting reimbursement architectures, and regional access programs that progressively convert diagnosed patients into treated patients. For executives and investors, the opportunity lies in understanding where value is being created, where margin pressure is building, and how competitive positioning will reshape over the next several years.
Market Snapshot and Core Challenges
The current market structure reflects a concentrated but strategically dynamic environment. A small group of companies controls the majority of branded therapeutic volume, with top-three concentration exceeding 85 percent and top-five concentration approaching 95 percent. Such concentration typically signals high barriers to entry, entrenched clinical familiarity, and payer relationships built over years of treatment continuity. At the same time, the market is not static. Two simultaneous forces are redefining commercial logic: first, the expanding treatment envelope for non-neurological manifestations, particularly in Type 3 disease, which broadens the addressable patient pool for existing enzyme replacement therapies; second, the intensification of payer oversight, where preferred-product criteria and medical necessity documentation are increasingly shaping formulary access and prescribing behavior.
These forces introduce three core challenges for market participants.
- Therapeutic differentiation is narrowing in mature segments. Multiple recombinant enzyme replacement options and oral substrate reduction therapies now compete within similar clinical niches, making brand loyalty, service infrastructure, and real-world evidence increasingly decisive.
- Reimbursement frameworks are shifting from broad coverage to conditional access. Updated commercial insurance policies are introducing product preference criteria and stricter documentation requirements, which can compress uptake velocity even when clinical approval expands.
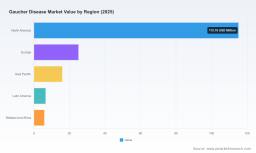
- Regional access remains uneven. While North America and Europe account for the largest share of revenue, Asia Pacific, Latin America, and Middle East and Africa represent smaller but strategically important corridors where local approval, reimbursement inclusion, and supply reliability determine whether innovation translates into commercial scale.
For decision-makers, the strategic implication is clear. The market is large enough to support specialized players, but growth will increasingly depend on access navigation, evidence generation, and therapeutic adjacency rather than on undifferentiated presence in established indications.
Key Drivers Shaping Market Dynamics
Therapeutic Innovation and the Push Toward Neurological Indications
Innovation is moving beyond symptomatic control of visceral and hematologic manifestations toward addressing neurological involvement, which has historically represented a major unmet need. The most visible signal is the progression of venglustat through late-stage clinical evaluation, including a Phase 3 trial that met all primary endpoints for Type 3 Gaucher disease and subsequent regulatory designation intended to expedite review for neurological manifestations. This trajectory matters because neurological indications reconfigure both clinical value and commercial scope. They create a potential market expansion beyond the patient segments traditionally served by enzyme replacement therapy and substrate reduction therapy, and they raise the strategic stakes for companies that can deliver central nervous system penetration with manageable safety and dosing profiles.
Even where approvals are not yet final, the development path demonstrates how pipeline momentum can influence market expectations. Positive clinical signals and breakthrough designations shape physician interest, patient advocacy priorities, and payer preparedness, all of which affect how quickly a new option may be adopted once regulatory clearance is secured.
Regulatory Label Evolution and Broader Access Pathways
Regulatory action is expanding the practical use of existing therapies. Recent label expansion for Cerezyme to cover non-central nervous system manifestations of Type 3 Gaucher disease in adults and pediatric patients illustrates how regulatory clarity can open reimbursement pathways that were previously constrained by narrower indications. In parallel, regional market access developments are altering the commercial map. In China, inclusion of a domestically developed recombinant enzyme replacement therapy in a commercial health insurance innovative drug list represents a meaningful step toward broader affordability and utilization. These milestones show that label scope and reimbursement inclusion are tightly coupled: broader labels provide the clinical rationale, while insurance inclusion enables the economic pathway.
The commercial lesson is that regulatory success alone does not guarantee traction. Label expansions must be paired with payer education, documentation support, and, in some markets, local pricing and distribution strategies that align with insurance architecture. Companies that treat regulatory milestones as access enablers rather than standalone achievements are better positioned to convert approvals into utilization.
Demand-Side Behavior and Diagnostic/Uptake Patterns
Demand in Gaucher disease is shaped by a mix of rare-disease dynamics and evolving care pathways. Improved diagnostic awareness, registry participation, and long-term disease management programs are gradually increasing the share of diagnosed patients who receive treatment. At the same time, clinicians are becoming more selective about therapy selection, weighing route of administration, infusion burden, oral availability, and tolerability. This selectivity is especially visible in the coexistence of enzyme replacement therapy and substrate reduction therapy, where oral convenience and infusion logistics create different value propositions for different patient profiles.
Additionally, real-world evidence is increasingly influencing prescribing confidence. Registry-based data and post-marketing experience provide context that clinical trials alone may not capture, particularly for long-term outcomes and specific patient subgroups. As treatment decisions extend over years, evidence continuity becomes a commercial asset, reinforcing adherence, supporting payer conversations, and strengthening brand trust.
Worldwide Biotinidase Deficiency Market
Supply Infrastructure and Cost Considerations
Cost structure and manufacturing technology remain important differentiators. Plant cell expression platforms, for example, have enabled alternative production routes for certain recombinant enzymes, with potential implications for supply resilience, cost efficiency, and product availability. In a market where therapy is often chronic and demand can be sensitive to supply interruptions, manufacturing diversity can translate into commercial reliability. At the same time, payer pressure on pricing and preferential product criteria means that cost efficiency is not only an operational concern but also a market-access concern. Companies that can connect manufacturing advantage to value-based positioning are better equipped to defend share in an environment where payers are increasingly selective.
Zellweger Spectrum Disorders Market
Competitive Landscape and Leading Strategies
The competitive field is led by companies with well-established branded franchises and distinct strategic angles. Sanofi maintains a strong position through a dual approach: a long-standing enzyme replacement therapy franchise and an oral substrate reduction therapy option, supplemented by late-stage neurological pipeline activity. Its recent moves, including label expansion for non-CNS Type 3 manifestations and breakthrough therapy designation for neurological disease, reflect a strategy of extending the therapeutic footprint while preparing for higher-value neurological indications.
Takeda represents a focused enzymatic franchise strategy with a recombinant enzyme approved for long-term treatment across pediatric and adult patients. Pfizer’s position is notable for its connection to plant cell technology, with a recombinant enzyme commercialized in most markets under a partnership model. This arrangement highlights how manufacturing technology and commercial partnerships can combine to create differentiated supply and market access dynamics. Johnson & Johnson participates through an oral substrate reduction option intended for patients when enzyme replacement therapy is not suitable, reinforcing the role of oral therapy as a strategic alternative in specific clinical scenarios.
A parallel dynamic is emerging in regional markets. CANbridge has advanced a domestically developed recombinant enzyme replacement therapy, with regulatory approval in China and recent inclusion in a commercial health insurance innovative drug list. This illustrates a broader trend: regional players can build relevance by aligning product development with local approval pathways and reimbursement programs, even in a market where global brands dominate overall revenue.
Several strategic patterns are shaping the competitive trajectory.
- Portfolio extension over single-product dependence. Leading companies are investing in adjacent indications and new modalities rather than relying solely on mature enzyme replacement franchises.
- Access-aware commercialization. Label updates and reimbursement inclusion are being used as coordinated levers, not isolated events, especially in markets where payer policy directly influences utilization.
- Evidence-led differentiation. Real-world data from registries and long-term clinical follow-up are becoming important tools for reinforcing therapeutic choice, particularly where head-to-head differentiation is limited.
- Regional market building. In markets such as China, local approval, insurance inclusion, and domestic development can create credible positions even where global concentration is high.
Looking ahead, the landscape is likely to experience both consolidation pressure and selective differentiation. High concentration favors incumbents with established service networks, payer relationships, and long-term patient follow-up systems. However, breakthrough designations, new neurological indications, and regional reimbursement advances create openings for companies that can combine scientific credibility with access execution. New entrants will face the challenge of proving clinical and economic value in a space where therapeutic familiarity and payer preference are already entrenched.
Future Trends and Commercial Implications (2026–2032)
Neurological indications as a value-creation frontier
Over the next several years, the most consequential opportunity is likely to come from therapies that address neurological manifestations of Gaucher disease. If late-stage development and regulatory pathways continue to advance, the market could see a shift in differentiation from primarily visceral and hematologic control toward central nervous system impact. This would expand the commercial relevance of substrate reduction approaches and potentially reshape prescribing priorities for Type 3 disease. For manufacturers, the trend suggests a need to prepare clinical narratives, endpoint strategies, and payer engagement plans around neurological outcomes, not just traditional disease markers.
Access policy as a growth regulator
Reimbursement policy will increasingly act as a growth regulator. The emergence of preferred-product criteria, medical necessity requirements, and periodic coverage revisions indicates that payers are moving toward more conditional access models. In practice, this means that market growth will depend not only on approval and clinical efficacy but also on documentation readiness, formularies, and channel-specific contracting. Companies that invest early in payer education and real-world evidence packages are more likely to maintain uptake stability when coverage policies tighten.
Regional market acceleration through insurance inclusion
In select regions, insurance inclusion and local development are likely to accelerate utilization more rapidly than global revenue trends alone would suggest. Where innovative drug lists, commercial insurance coverage, or domestic approval pathways reduce access barriers, local markets can scale faster and become more strategically relevant. This creates opportunities for companies that can combine product availability with localized pricing, distribution, and patient support models. It also raises the importance of monitoring regional policy changes, since inclusion events can alter demand trajectories quickly.
Risk and uncertainty
Several risks should temper optimistic projections. First, neurological indications may deliver clinical promise without the convenience, safety, or outcome differentiation needed for rapid adoption. Second, payer policy could become more restrictive, particularly if cost pressures intensify or if preferred-product frameworks narrow the practical choices available to prescribers. Third, competitive similarity in mature enzyme replacement segments may lead to price and service competition that erodes margin even as overall market size grows. Finally, regional access progress can be uneven, with policy reversals or pricing constraints slowing uptake in otherwise promising markets.
Strategic Implications for Decision-Makers
For manufacturers and therapy developers
Prioritize evidence continuity. In a market where treatment spans years and payer scrutiny is rising, registry participation, real-world data, and long-term safety information can be as commercially important as trial results. Build access-ready launch plans that treat label expansion, reimbursement inclusion, and payer policy as interconnected milestones rather than separate events. For companies with neurological pipeline assets, align endpoint strategy and market preparation early so that scientific progress can translate into reimbursement readiness. For incumbents in mature segments, differentiate through service quality, supply reliability, and patient support infrastructure, since product similarity raises the value of non-clinical advantages.
For investors and portfolio strategists
Focus on indication expansion and access execution rather than headline market size alone. The projected growth path is meaningful, but the highest value may accrue to assets that can extend into neurological indications, secure favorable reimbursement positioning, or gain regional inclusion efficiently. Evaluate competitive durability by examining concentration, payer preference, and the strength of long-term patient relationships, since these factors shape margin resilience. Monitor regulatory designations, label expansions, and insurance inclusion events as leading indicators of near-term commercial shifts, especially where policies are changing on short cycles.
For procurement, market access, and hospital 의사결정 teams
Treat formulary and contracting decisions as dynamic. Preferred-product criteria and medical necessity requirements are becoming more common, so procurement strategies should account for documentation demands, product availability, and the relative role of oral versus infusion-based therapy in specific patient populations. Use real-world evidence and registry insights to support selection when therapeutic differentiation is limited. Keep attention on supply reliability and regional access programs, particularly where local insurance inclusion may expand utilization quickly and create demand for predictable supply and robust patient management.
PW Consulting Health Care Research Center
Conclusion
The Gaucher disease market is entering a phase in which growth is increasingly determined by therapeutic expansion, access policy, and evidence-led differentiation rather than by baseline prevalence alone. The combination of neurological pipeline progress, label and reimbursement developments, and regional market inclusion is reshaping where commercial value will be captured between 2025 and 2032. Concentration remains high, but that does not eliminate opportunity; it simply raises the bar for companies that must justify therapeutic choice, defend payer access, and build durable patient relationships.
For executives, investors, and access professionals, the critical task is to interpret these shifts in time to act. The details that matter most—segment-level demand patterns, regional reimbursement dynamics, competitive positioning by therapy type, and policy-driven access constraints—are often obscured in high-level summaries. Readers seeking a deeper, decision-ready view of these dimensions can refer to the full PW Consulting Gaucher Disease Market report, where more granular segmentation, scenario considerations, and customized strategic implications are available for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Gaucher Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com