

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Plasma Protein Therapeutics Market: Why 5.6% CAGR and $29.7B Scale Signal a Strategic Realignment

Navigating the Plasma Protein Therapeutics Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot: Sizing the Opportunity and Identifying Critical Inflection Points
The global plasma protein therapeutics market has crossed a significant threshold, reaching approximately $29.7 billion in 2025. From 2020 through 2025, the sector demonstrated steady expansion, moving from $22.15 billion to its current level. The forward trajectory points to continued growth, with revenue expected to approach $43.26 billion by 2032, representing a compound annual growth rate of 5.6 percent over the forecast period. This expansion is not merely a function of demographic aging or incremental demand growth; it reflects structural shifts in clinical practice, regulatory evolution, and supply chain realignment that are reshaping how plasma-derived therapies are sourced, manufactured, and delivered.
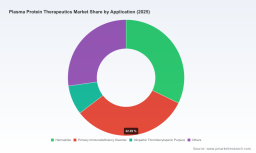
Market concentration remains high. The top three players control roughly 55.8 percent of total revenue, while the top five account for approximately 69.3 percent. This concentration signals an industry where scale, regulatory compliance, and collection network density create formidable barriers to entry. At the same time, the distribution of revenue across product categories and clinical applications reveals a diversified demand base. Immunoglobulins and albumin continue to anchor the portfolio, while coagulation factors and other specialized proteins serve distinct patient populations with concentrated but high-value needs. The application landscape spans hemophilia, primary immunodeficiency disorders, idiopathic thrombocytopenic purpura, and a broader set of indications that collectively sustain demand across multiple therapeutic areas.
Critical Challenges and Inflection Points Shaping the Near Term
Three interconnected challenges define the current market environment and will determine which organizations capture disproportionate value over the next several years.
The first challenge is supply-demand imbalance at the raw material level. Plasma collection volumes are running 5 to 10 million liters per year below full industry need, creating persistent pressure on downstream production capacity. This gap is not a transient disruption; it reflects donor recruitment challenges, geographic concentration of collection centers, and the time lag required to build new fractionation capacity. For manufacturers, the implication is clear: securing reliable plasma supply is no longer an operational detail but a strategic priority that directly affects product availability, pricing power, and market share.
The second challenge centers on regulatory tightening and supply chain resilience, particularly in Europe. The European Medicines Agency issued recommendations in July 2025 to strengthen the anti-D immunoglobulin supply chain, citing declining EU plasma donor numbers and limited EU manufacturing capacity. This development highlights a broader trend: regulators are increasingly viewing plasma-derived therapies as essential medicines requiring proactive supply chain management rather than routine biologics procurement. Companies that depend on single-region sourcing or fragile collection networks face elevated regulatory and continuity risk.
The third challenge is the tension between scale economics and product differentiation. While plasma fractionation benefits from volume-driven cost structures, the most attractive commercial opportunities are emerging in specialized formulations, streamlined administration profiles, and indication-specific therapies. The leaders who navigate this tension effectively are those investing in next-generation manufacturing facilities, pursuing targeted regulatory approvals, and aligning product roadmaps with unmet clinical needs rather than competing solely on price in mature categories.
Core Drivers Reshaping Market Dynamics
Technology and Manufacturing Innovation
Manufacturing innovation is a primary engine of competitive differentiation. The approval and commercialization of next-generation immunoglobulin products illustrate how process innovation translates into market opportunity. Yimmugo®, a novel immunoglobulin product, received FDA approval in June 2024 and is produced at Biotest's new FDA-certified Next Level facility. This combination of regulatory clearance and modernized production infrastructure signals a broader shift toward facilities designed for higher operational standards, improved traceability, and greater flexibility in product output. In practical terms, companies that operate advanced, certified facilities can bring differentiated products to market faster, respond more effectively to supply constraints, and position themselves as preferred partners for payers and clinical networks seeking reliability.
Beyond individual product launches, the industry is seeing incremental gains in fractionation efficiency, purification methods, and formulation design. These improvements may not generate headline-grabbing disruption, but they compound over time. Better yield from collected plasma, reduced processing losses, and more stable formulations all contribute to margin improvement and supply resilience. For decision-makers, the strategic question is whether capital is being directed toward incremental refinement or toward step-change capabilities that can create durable advantages in cost structure and product quality.
Regulatory and Policy Environment
Policy dynamics are influencing both market access and supply chain strategy. The EMA's July 2025 recommendations on anti-D immunoglobulin supply reflect a regulatory posture that prioritizes continuity of care for critical therapies. This approach is likely to expand beyond anti-D as regulators assess vulnerabilities across plasma-derived portfolios. Companies should expect heightened scrutiny of source plasma origins, manufacturing redundancy, and contingency planning. At the same time, regulatory pathways for new plasma-derived products remain active. The FDA approval of QIVIGY®, a 10 percent immunoglobulin for intravenous use in primary humoral immunodeficiency, announced by Kedrion Biopharma in September 2025 with commercial availability planned for early 2026, demonstrates that the regulatory environment continues to support innovation when clinical value and manufacturing quality are clearly established.
From a commercial standpoint, regulatory developments create both constraints and opportunities. Constraints arise where supply vulnerabilities trigger intervention or where compliance requirements raise the cost of market participation. Opportunities emerge for organizations that can demonstrate robust supply chains, clear quality systems, and products that address gaps in current treatment options. The regulatory trajectory favors players who treat compliance and supply resilience as strategic assets rather than baseline obligations.
Demand-Side Shifts in Clinical Practice and Patient Populations
Demand growth is being reinforced by several interlocking factors. Primary immunodeficiency disorders and hemophilia remain central drivers of plasma protein therapeutic utilization, with both categories representing substantial and sustained patient populations. The broader application base, including idiopathic thrombocytopenic purpura and other indications, adds further stability to demand patterns. Clinical practice trends also support continued expansion: earlier diagnosis, expanded treatment protocols, and growing recognition of the role plasma-derived therapies play in managing chronic and rare conditions all contribute to utilization growth.
In addition, the shift toward home-based and outpatient administration where clinically appropriate is influencing product design and service expectations. Therapies that support easier administration, predictable dosing, and reliable availability align with healthcare systems seeking to reduce hospitalization burden and improve patient adherence. This demand-side evolution is not uniform across all products, but it is shaping the competitive priorities for immunoglobulin and albumin offerings, where convenience and consistency increasingly matter alongside efficacy.
Supply Chain and Cost Structure Realignment
Cost structures in plasma protein therapeutics are influenced by collection economics, fractionation yields, regulatory overhead, and logistics. The persistent shortfall in plasma collection relative to industry need is intensifying competition for source material and placing upward pressure on input costs. In response, companies are pursuing multiple levers: expanding collection networks in strategically located regions, investing in facilities that improve yield and throughput, and renegotiating supply arrangements to secure priority access.
Blood Plasma Derivatives Market
At the same time, the cost of maintaining regulatory compliance and quality assurance is rising, particularly where authorities are strengthening expectations around traceability, donor screening, and manufacturing redundancy. Organizations that can manage these costs without sacrificing product quality or supply reliability are better positioned to protect margins. The broader supply chain realignment also favors players with diversified sourcing strategies, regional manufacturing presence, and the operational discipline to manage complex logistics across multiple markets.
Competitive Landscape and Leadership Strategies
Strategic Positioning of Leading Companies
The market's leading players are pursuing distinct but overlapping strategies that emphasize scale, product diversification, and targeted innovation. Grifols S.A. continues to operate as a global leader in plasma-derived medicines, with a portfolio that includes immunoglobulin therapies and a strong presence in fractionation and distribution. Its recent activities, including the launch of Yimmugo® immunoglobulin in the United States in October 2025 for primary immunodeficiencies, reflect a strategy centered on expanding access to differentiated products in key markets while leveraging established collection and manufacturing infrastructure.
CSL Limited remains a major producer of plasma-derived therapies, including immunoglobulins and albumin. Its scale and broad therapeutic footprint provide a foundation for resilience across demand cycles and regulatory environments. Octapharma AG, based in Vienna, has built a specialist reputation in plasma protein therapeutics with a clear focus on immunoglobulin and related derived therapies, positioning itself as a focused competitor in categories where product specificity and clinical reputation matter. Takeda Pharmaceutical Company Limited maintains a significant portfolio in plasma protein therapeutics, including offerings from its acquired Shire assets such as immunoglobulin therapies, combining global commercial reach with established treatment franchises.
Differentiation Through Product Innovation and Facility Investment
Biotest AG and Kedrion S.p.A. illustrate how targeted product innovation can create competitive separation. Biotest's production of innovative plasma-derived immunoglobulins, including Yimmugo®, and its operation of an FDA-certified Next Level facility demonstrate the value of aligning product development with advanced manufacturing capability. Kedrion's FDA approval for QIVIGY® in September 2025, with commercial availability planned for early 2026, underscores how focused development programs can yield new options for specific patient populations, such as those with primary humoral immunodeficiency. These moves are not simply product launches; they are strategic signals that a company can bring new therapies to market with the regulatory and operational backing required for sustained commercialization.
Other significant participants, including Bayer AG, Baxter International Inc., Bio Products Laboratory Ltd, and China Biologic Products Holdings, Inc., contribute to a competitive field that spans specialty medicine portfolios, regional manufacturing strengths, and global distribution capabilities. Collectively, these companies reflect an industry in which competitive advantage is built through a combination of product breadth, supply reliability, manufacturing quality, and market-specific commercial execution.
Evolution of the Market Structure
The competitive landscape is evolving along several dimensions. Consolidation remains a plausible path for players seeking to strengthen collection networks, expand fractionation capacity, or acquire specialized product portfolios. At the same time, there is room for differentiation and selective entry in areas where new formulations, streamlined manufacturing, or region-specific supply strategies create value. The high concentration levels suggest that scale matters, but they do not preclude companies from gaining share through superior product offerings, regulatory success, and stronger supply chain positioning.
Plasma Fractionation Market
Leadership changes at industry associations also point to evolving governance and coordination within the sector. In May 2026, the Plasma Protein Therapeutics Association announced changes to its Global Executive Board and European Board leadership. While such changes do not directly alter competitive dynamics, they can influence industry coordination on supply chain practices, regulatory engagement, and standards development. Organizations that engage constructively with industry bodies and align their strategies with emerging sector priorities may benefit from stronger relationships and earlier insight into collective challenges.
Forward Outlook: Key Trends and Associated Commercial Opportunities
Trend One: Supply Security as a Strategic Differentiator
Over the next three to five years, supply security is likely to move from an operational concern to a core competitive attribute. The ongoing gap between plasma collection and industry demand, combined with regulatory attention to supply chain resilience, will reward organizations that can demonstrate reliable access to source plasma, diversified collection footprints, and manufacturing redundancy. Companies that treat supply security as a market-facing strength may gain preference with payers, hospital networks, and regulators, particularly for therapies where continuity of care is critical.
The commercial opportunity here is twofold. First, organizations with stronger supply positions can protect market share during periods of tightness and potentially expand share when competitors face constraints. Second, supply resilience can support premium positioning in categories where reliability is valued by clinicians and health systems, especially for chronic conditions requiring consistent therapy access.
Trend Two: Product-Level Differentiation in High-Value Indications
Growth is expected to be shaped not only by aggregate demand expansion but also by the success of differentiated products in high-value indications. Immunoglobulins for primary immunodeficiency disorders and hemophilia-related therapies represent areas where clinical need, treatment continuity, and product performance converge to support sustained demand. New formulations and refined administration profiles can create incremental advantage even within mature categories.
This trend creates opportunities for companies that invest in indication-specific development, pursue timely regulatory approvals, and build commercial capabilities tailored to specialist prescribing patterns. It also favors organizations that can connect product attributes to practical clinical benefits, such as dosing predictability, administration feasibility, and consistent supply. The risk is that product differentiation requires disciplined development timelines, strong regulatory execution, and commercial readiness; delays or unclear value propositions can weaken launch impact.
Trend Three: Regional Rebalancing and Supply Chain Diversification
The market is likely to see continued regional rebalancing as companies respond to donor availability, regulatory expectations, and cost considerations. European supply vulnerabilities, reflected in the EMA's anti-D immunoglobulin recommendations, are prompting renewed attention to regional collection and manufacturing capacity. At the same time, other regions may attract investment where collection potential, regulatory pathways, and operational conditions support growth.
For commercial strategy, regional diversification can reduce concentration risk and open pathways to market expansion. Companies that build or strengthen regional capabilities may be better positioned to serve local demand, respond to regulatory requirements, and manage logistics more efficiently. The uncertainty lies in the pace and shape of regulatory evolution, which can vary significantly across jurisdictions and affect the viability of specific sourcing or manufacturing models.
Strategic Recommendations for Decision-Makers
For Manufacturers and Therapy Developers
- Prioritize supply chain resilience as a strategic investment. Expand or diversify plasma sourcing, strengthen contingency planning, and align facility investments with regulatory expectations and production flexibility. The companies that can assure continuity of supply will be better positioned to protect revenue and build trust with clinical customers.
- Focus innovation on products that combine clinical value with operational practicality. Targeted therapies for high-need indications, supported by modernized manufacturing and clear regulatory pathways, offer a stronger path to differentiation than broad-based price competition in commoditizing segments.
- Engage early with regulatory and industry frameworks. Proactive alignment with evolving expectations on supply chain management, quality systems, and product traceability can reduce friction in approvals and market access while strengthening long-term operating credibility.
For Investors and Capital Allocators
- Evaluate competitive strength through supply position and regulatory execution, not just revenue scale. Collection access, certified manufacturing capacity, and a track record of timely approvals are indicators of durable advantage in a concentrated market.
- Look for companies with clear product roadmaps in high-value indications and the operational discipline to convert development progress into commercial availability. Launch execution, distribution readiness, and market-specific commercial capability often determine whether product innovation translates into share gains.
- Monitor regional dynamics and supply-side constraints as leading indicators of margin pressure and competitive shifts. Organizations that can navigate collection shortages, regulatory changes, and cost realignment are more likely to sustain performance across cycles.
For Procurement and Market Access Leaders
- Assess supplier reliability beyond price. In a market shaped by plasma collection gaps and regulatory attention to supply continuity, sourcing decisions should weigh manufacturing redundancy, collection diversity, and supply chain transparency alongside cost.
- Build flexibility into procurement strategies for critical therapies. Where possible, maintain awareness of alternative sources, formulation options, and regional supply pathways to reduce vulnerability to single-source disruptions or sudden demand surges.
- Align purchasing and access planning with clinical continuity requirements. For chronic and essential therapies, reliability and predictability can create value that outweighs short-term cost differences, particularly when supply constraints are likely to persist.
Where to Go From Here
The plasma protein therapeutics market is entering a phase in which supply resilience, product differentiation, and regulatory alignment will separate durable performers from organizations that simply participate in growth. The broad trajectory toward $43.26 billion by 2032 signals a sizable opportunity, but the distribution of value will depend on how effectively companies manage collection constraints, invest in modernized manufacturing, and execute in high-need indications. Leadership in this environment will belong to those who treat supply security and product quality as strategic assets, not background conditions.
PW Consulting Health Care Research Center
For decision-makers seeking deeper segmentation data, competitive benchmarking, and tailored scenarios across regions, product categories, and application areas, the full PW Consulting research report provides a more detailed view of the market structure and the strategic options it creates. Access to that level of granularity can help translate the trends outlined here into specific investment, sourcing, and development decisions.
For detailed analysis of this topic, please visit the official page: Plasma Protein Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com