

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Prosthetic Liners Market: How 42.5% CR3 Concentration Meets 6.8% CAGR Growth

Prosthetic Liners Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Structural Challenges
The prosthetic liners market has entered a phase of sustained expansion, defined by a compound annual growth rate of 6.8 percent from 2026 through 2032. Revenue reached approximately 648.4 million USD in the base year of 2025, following a decade of steady accumulation that pushed the sector from 163.15 million USD in 2020 to 474.98 million USD by 2024. The trajectory points to 832.5 million USD in 2026, with growth accelerating into the latter half of the forecast window and approaching 4.475 billion USD by 2032. This expansion reflects more than demographic tailwinds; it signals a structural recalibration of how residual limb interfaces are designed, validated, and reimbursed.
Three interlocking challenges define the current inflection point. First, functional level eligibility has historically constrained access to advanced liners, particularly for patients classified at the K2 mobility tier. Coverage frameworks that restricted component reimbursement to higher functional categories left a large segment of the amputee population relying on legacy interface materials, limiting both clinical outcomes and addressable demand. Second, material performance trade-offs continue to pressure manufacturers. Silicone, thermoplastic elastomers, and polyurethane each offer distinct advantages in cushioning, durability, and moisture handling, yet balancing skin compatibility with long-term structural integrity remains a persistent engineering constraint. Third, regulatory and reimbursement fragmentation across geographies creates uneven adoption curves. While some markets have streamlined coverage pathways, others maintain multi-layered approval processes that delay commercial rollout and complicate forecasting for suppliers operating across jurisdictions.
Key Drivers Reshaping the Landscape
Technology Innovation and Interface Intelligence
Material science and embedded sensing are converging to redefine what a prosthetic liner must deliver. Recent product introductions highlight a move toward liners that do more than provide a cushion between residual limb and socket. Micro-sensors embedded within liner structures now capture pressure distribution and movement data, giving clinicians and patients real-time visibility into fit dynamics and tissue stress. At the same time, advanced material formulations prioritize moisture management and sustained comfort, addressing one of the most persistent barrier to extended wear and consistent use. These developments are not incremental tweaks; they represent a shift from passive interface components to active, data-enabled elements that integrate with broader prosthetic systems.
Raw material suppliers have contributed to this shift by delivering new chemistries that meet stringent biocompatibility standards while improving tear resistance and water-vapor transmission. Medical-grade silicone, urethane, and thermoplastic elastomers remain the foundation of most commercial liners, but reformulated variants are expanding the performance envelope. The result is a market where differentiation increasingly depends on how well a liner manages humidity, shear forces, and long-duration comfort, rather than on price positioning alone. For manufacturers, this elevates the importance of formulation expertise and application-specific tuning, particularly for lower extremity use cases where load-bearing demands are highest.
Policy and Reimbursement Realignment
Coverage policy is emerging as a decisive demand-side lever. In September 2024, the Centers for Medicare & Medicaid Services implemented expanded coverage criteria for microprocessor-controlled knee units and related lower limb prosthesis components, including liners for K2 functional level beneficiaries. This adjustment broadens the population eligible for higher-performance interface components and directly enlarges the commercial base for manufacturers serving public payers and aligned private plans. Reimbursement approvals at the product level further reinforce this trend. Recent PDAC approvals for specific liner codes have clarified billing pathways across Durable Medical Equipment Medicare Administrative Contractors, reducing ambiguity for suppliers and downstream providers.
Regulatory refinement is also shaping cost structures. Updated guidance around biocompatibility testing for intact-skin devices has reduced redundant test spending, freeing capital that companies are redirecting toward material innovation and moisture-management development. In parallel, manufacturers operating in regulated markets continue to align production and quality systems with established medical device standards, ensuring that new offerings can navigate certification requirements without compromising time-to-market. The cumulative effect is a more navigable pathway for liner innovation, provided companies maintain disciplined documentation and design controls.
Demand-Side Shifts and Clinical Expectations
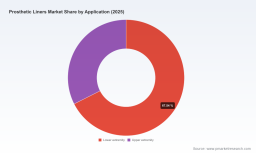
Clinician and patient expectations are evolving in tandem with material and policy changes. Prosthetic users increasingly prioritize liners that support all-day wear, reduce skin breakdown risk, and accommodate variable activity levels without frequent adjustments. For lower extremity applications, where load distribution and socket interface stability are critical, this translates into sustained demand for liners that combine cushioning with reliable moisture control. Upper extremity users, meanwhile, drive requirements around dexterity, socket fit precision, and cosmetic discretion, creating distinct performance priorities across application segments.
The broader demand environment is also being influenced by improved access pathways and a growing recognition that interface quality affects rehabilitation outcomes, device adherence, and long-term socket performance. As prosthetic care teams place greater emphasis on interface selection as a clinical decision rather than a commodity choice, suppliers are seeing more specification-driven purchasing. This shifts competition toward proven comfort characteristics, compatibility with socket systems, and clinical support materials that help practitioners match liners to patient profiles.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by both material innovation and regulatory efficiency. Improved biocompatibility pathways have lowered certain validation costs, while advanced chemistries from raw material suppliers have improved performance per unit of material input. These dynamics help manufacturers manage the tension between premium material attributes and price sensitivity in cost-constrained procurement environments. At the same time, the concentration of the market among a relatively small group of leading suppliers indicates that scale, certification readiness, and established distribution relationships still confer meaningful advantages.
Supply chain strategy is increasingly tied to formulation control and application-specific production. Because advanced liners commonly rely on medical-grade silicone, urethane, or thermoplastic elastomers, companies that can secure consistent input quality and tune material properties for specific use cases are better positioned to protect margins. For products designed and produced under recognized quality management standards, alignment with regional regulatory expectations also reduces friction in cross-border commercialization and supports repeat procurement cycles among institutional buyers.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with the top three suppliers accounting for roughly 42.5 percent of revenue and the top five reaching approximately 48.2 percent. This structure suggests that scale, brand trust, and clinical adoption matter, but also that space remains for differentiated specialists and regionally focused players to compete on performance, service, and fit. The competitive field spans established prosthetic brands, interface specialists, and material-forward suppliers, each pursuing distinct strategic positions.
Össur has reinforced a technology-integrated positioning through recent liner launches, including a generation featuring embedded micro-sensors for pressure and movement analysis, followed by a new line emphasizing advanced materials with superior moisture management and comfort. This dual focus on data capture and material comfort aligns with the broader shift toward intelligent interfaces and supports a clinical narrative centered on fit optimization and wear-time improvement.
PW Consulting Health Care Research Center
Ottobock has pursued a reimbursement-forward strategy, exemplified by PDAC approval for a liner under an HCPCS code that clarifies billing across the four Durable Medical Equipment Medicare Administrative Contractors. By reducing reimbursement uncertainty for a specific product, the company strengthens procurement confidence among providers operating within public payer systems and improves the commercial predictability of the offering.
Specialist and material-focused players have carved out positions around fit customization, production standards, and application-specific comfort. Willow Wood, ALPS, College Park Industries, Blatchford, Fillauer Europe AB, Freedom Innovations, Medi, SILIPOS HOLDING, Streifeneder USA, and ST&G Corporation each bring distinct emphases, from interface design heritage and medical-grade material expertise to regional manufacturing and quality system alignment. ALPS, for example, frames its products around ISO 13485 and GMP-based design and production, meeting EU regulatory requirements and conforming to MDR 2017/745, an approach that signals compliance readiness for buyers in regulated markets. ST&G Corporation reflects the continued presence of South Korean manufacturing capability within a globally distributed supplier base, illustrating how regional sourcing and specialized production can support broader international distribution.
Market evolution is likely to follow a bifurcated path. Larger brands will continue to leverage integrated prosthetic ecosystems, reimbursement expertise, and global distribution to defend share in high-volume segments. Meanwhile, smaller and mid-sized players will compete on niche performance attributes, custom fit capabilities, and specialized material formulations that address unmet comfort or durability needs. Consolidation pressures may emerge where scale advantages in procurement, testing, and market access become decisive, but fragmentation is also likely to persist where clinical preference, patient-specific fitting, and regional reimbursement patterns reward differentiated offerings. New entrants will face the highest barriers in regulated reimbursement channels, but may find opportunity in specialty applications, advanced material variants, or smart-interface partnerships that do not require full-spectrum prosthetic portfolios.
Outlook for the Next 3 to 5 Years
Three trends are likely to shape the market over the next several years. First, intelligent interface features will move from differentiated novelty to expected capability in a growing share of premium and mid-tier offerings. Pressure and movement sensing, paired with moisture-management material improvements, will increasingly define how clinicians evaluate liner quality. The commercial opportunity lies in pairing sensor-enabled liners with interpretation tools, clinical training, and service models that turn raw data into actionable fit adjustments, rather than selling sensing as a standalone feature.
Worldwide Heel Liner Market
Second, reimbursement expansion for broader functional levels should continue to widen the addressable base, particularly for lower extremity liners where load-bearing performance and wear-time demands are greatest. As coverage clarity improves, procurement cycles may become more predictable, and suppliers that can demonstrate consistent clinical value and documentation readiness will be better positioned to capture institutional demand. The opportunity here is to align product portfolios, coding clarity, and clinical evidence so that expanded eligibility translates into sustained share gains rather than short-term spikes.
Third, material formulation leadership will become a more visible battleground. As new chemistries improve tear resistance and water-vapor transmission while meeting biocompatibility expectations, suppliers with strong formulation know-how and reliable input quality will be able to differentiate on comfort and durability without relying solely on brand heritage. The opportunity is to build application-specific material platforms that can be tuned across silicone, thermoplastic elastomer, and polyurethane use cases, allowing faster response to clinical feedback and regional preference.
These trends carry inherent risks. Reimbursement policy remains subject to revision, and coverage expansions that benefit current demand could be adjusted if budgetary pressures intensify or if evidence standards tighten. Material innovation also introduces validation and consistency challenges; new chemistries must perform reliably across production batches and diverse patient populations, or commercial gains can be undermined by fit variability and complaints. Finally, the integration of sensing features raises questions about data interpretation, service responsibility, and long-term support, creating execution risk for companies that introduce smart capabilities without clear clinical workflows or after-sales models.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to convert material and interface innovation into clinically defensible differentiation. Products that pair advanced moisture management and fit stability with clear reimbursement positioning will have an advantage in procurement environments where providers must justify component selection. Companies should also prepare for intelligent-interface expectations by defining how sensor data will be interpreted, who supports fit adjustments, and how service commitments will be structured. Formulation consistency, application-specific tuning, and documentation readiness will be decisive in protecting margins as performance expectations rise.
For investors, the market offers opportunity in companies that can demonstrate a credible link between material leadership, reimbursement navigation, and recurring procurement cycles. The most attractive profiles combine formulation or sensor-enabled differentiation with clear coding and coverage alignment, especially where expanded eligibility has broadened the addressable population. Due diligence should weigh not only product announcements, but also the quality systems, input supply reliability, and clinical evidence pathways that determine whether new features translate into durable share and margin expansion.
For procurement and clinical leaders, selection decisions should increasingly weigh interface performance across moisture handling, load distribution, and wear-time comfort, rather than treating liners as interchangeable commodity inputs. Alignment with reimbursement clarity, fitting support, and compatible socket systems can reduce downstream variability and improve patient adherence. Where intelligent interface features are under consideration, buyers should assess data workflows, training, and support obligations before adoption to ensure that added capability improves outcomes rather than complicating service.
Prosthetic Foot Market
For organizations seeking to move from high-level trends to segment-specific sizing, application-level demand patterns, regional growth differentials, and competitive share dynamics, a detailed market report provides the granular context needed to convert these insights into investment, development, and procurement decisions. Prepared by PW Consulting, the full research report extends the macro view into actionable breakdowns that support portfolio planning, entry strategy, and sourcing decisions with detailed data and customized guidance.
For detailed analysis of this topic, please visit the official page: Prosthetic Liners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com