

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Industrial Chocolate Market: Why 4.39% CAGR Through 2032 Changes Everything

Navigating the Industrial Chocolate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
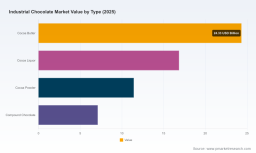
The industrial chocolate market has established itself as a resilient yet complex segment within the broader food ingredients landscape. From 2020 through 2025, the market expanded from approximately USD 49.3 billion to USD 59.7 billion, reflecting steady growth driven by consistent demand across baked goods, confectionery, and beverage applications. Looking ahead to the forecast period of 2026 through 2032, the trajectory projects a market value reaching USD 80.4 billion by 2032, supported by a compound annual growth rate of 4.39 percent. This pace suggests that industrial chocolate will continue to benefit from foundational consumption patterns while facing structural shifts that separate high-performing players from stagnant operations. The growth is not uniform across all product forms and end uses, and understanding where value concentrates requires looking beyond headline figures to the underlying dynamics shaping procurement, formulation, and distribution.
Several critical challenges are reshaping how manufacturers and suppliers approach the market. First, raw material volatility remains a persistent pressure point. Cocoa pricing has experienced significant swings, moving from elevated levels in prior years to notable declines in early 2026 as improved harvest outlooks and surplus expectations in West Africa altered the cost environment. While falling prices can relieve margin compression for downstream buyers, they also introduce planning complexity for suppliers who must manage inventory, hedging, and long-term contracting in a shifting landscape. Second, food safety and compliance oversight has intensified, with multiple recalls across different companies in early to mid-2026 highlighting the industry's exposure to microbiological contamination and undeclared ingredient risks. These incidents underscore the operational fragility that can disrupt supply continuity and erode buyer confidence, particularly for bulk industrial buyers who depend on consistent quality and traceability. Third, the industry must navigate a concentration dynamic where a relatively small number of large players account for a disproportionate share of market activity, creating both barriers to entry and opportunities for differentiation through specialization, technical service, and regional agility.
Cocoa Market
- Raw material price volatility creates planning uncertainty for both suppliers and bulk buyers, requiring more sophisticated hedging and contract strategies
- Food safety incidents and regulatory recalls highlight the need for robust traceability, supplier auditing, and rapid response capabilities across the value chain
- Market concentration among major players raises the importance of differentiation through formulation expertise, regional service, and flexible supply arrangements
Key Drivers of Market Change
Technical Innovation and Formulation Advances
Innovation continues to redefine what industrial chocolate suppliers can deliver, particularly as manufacturers seek cleaner labels, consistent performance, and cost-efficient formulations. Advanced cocoa processing, precision conching, and enhanced particle refinement allow ingredient suppliers to offer compounds, coatings, and fillings with tighter control over texture, viscosity, and flavor stability. Equally important is the growth of functional and flavor-modulation solutions. Ingredient specialists are increasingly providing cocoa extracts, flavor boosters, and formulation aids that enable manufacturers to reduce cocoa usage without sacrificing sensory quality. This approach is gaining traction in an environment where cost optimization and ingredient efficiency matter more than ever, especially for confectionery and bakery producers operating on thin margins. Innovation is also visible in product versatility: compound chocolate and specialty blends are being positioned to meet demands for thermal stability, ease of handling, and compatibility with different processing lines, supporting broader adoption in high-volume manufacturing environments.
Policy and Regulatory Environment
Regulatory oversight and food safety expectations are becoming more influential in shaping procurement and product design decisions. Recent recall activity involving potential Salmonella contamination and undeclared active ingredients has drawn attention to supplier compliance, ingredient sourcing, and quality control rigor. For industrial buyers, these events reinforce the importance of documented traceability, validated sanitation practices, and proactive supplier monitoring. In parallel, regulatory frameworks in key markets are encouraging greater transparency around allergens, labeling, and ingredient origin, which affects how industrial chocolate products are specified and documented. Companies that invest in quality management systems and clear compliance communication are better positioned to maintain trust with food manufacturers and foodservice customers. The regulatory environment is not merely a risk factor; it is also a filter that rewards organizations with disciplined operations and transparent supply practices.
Demand-Side Shifts in Consumer and Business Behavior
End-market demand is being shaped by changing consumer preferences and the operational needs of food manufacturers. Bakery products and confectionery remain central usage channels for industrial chocolate, but the way these categories evolve is changing. Consumers continue to seek indulgence, yet they also expect cleaner ingredient lists, consistent texture, and reliable flavor delivery. For industrial buyers, this translates into demand for ingredients that perform well in high-speed production while supporting product positioning around quality and simplicity. The rise of private label and contract manufacturing further influences demand, as retailers and brands look for suppliers capable of delivering consistent bulk formats with flexible customization. Beverage and frozen dessert applications, while smaller in share, are expanding in relevance as manufacturers explore new use occasions and flavor experiences. These demand-side shifts reward suppliers that can combine technical support with formulation flexibility, helping customers adapt products quickly to changing market expectations.
Supply Chain and Cost Structure Evolution
The cost structure of industrial chocolate is closely tied to cocoa supply dynamics, logistics, and processing capacity. Early 2026 data showed cocoa bean prices declining more than 10 percent year-on-year in some assessments, reflecting improved harvest expectations and changing supply balances in West Africa. At the same time, futures market movements indicated notable day-to-day and month-to-month swings, which reminds participants that even in periods of declining prices, volatility can persist. For industrial buyers, cost relief does not eliminate the need for strategic sourcing; rather, it shifts focus toward supplier reliability, hedging approaches, and contract structures that balance price and continuity. On the supply side, investments in processing capacity and regional facilities are shaping availability and service levels. For example, new pilot bakery and chocolate-related facilities in the United States reflect efforts to strengthen local support for industrial production and shorten response times for nearby customers. These developments suggest a gradual shift toward more regionally attuned service models, which can improve lead-time reliability and technical collaboration for manufacturers seeking closer supplier partnerships.
PW Consulting Health Care Research Center
- Cocoa price movements may ease some input costs, but volatility still demands disciplined sourcing, hedging, and inventory planning
- Food safety recalls reinforce the commercial value of traceability, supplier auditing, and rapid quality response across the industrial supply chain
- Demand for cleaner labels, formulation efficiency, and processing reliability is expanding the role of specialized ingredients and technical service
- Regional capacity additions and pilot facilities indicate a move toward closer supplier proximity and faster support for industrial customers
Competitive Landscape and Leading Strategies
The competitive field in industrial chocolate is defined by a mix of global cocoa processors, bulk ingredient suppliers, and specialists with strong formulation and application capabilities. Companies such as Barry Callebaut, Cargill, Blommer Chocolate Company, and Cémoi occupy prominent positions as large-scale suppliers of bulk dark, milk, and white chocolates, compounds, and cocoa-derived ingredients. Their scale provides advantages in sourcing, processing efficiency, and the ability to serve high-volume industrial and foodservice customers across multiple regions. At the same time, firms like Puratos, Fuji Oil, Guittard, and Natra compete with emphasis on specific application strengths, premium couverture options, and tailored ingredient solutions for bakery, patisserie, and professional manufacturing. A separate layer of competition comes from ingredient technology providers such as Kerry Group, which focuses on cocoa extracts and flavor boosters that help manufacturers achieve desired sensory outcomes while managing cocoa usage. This multi-layered structure means that competition is not only about price and volume; it is also about technical value, application expertise, and the ability to solve customer formulation challenges.
Leading players are pursuing distinct strategic positions. Global processors generally emphasize supply reliability, broad product portfolios, and the capacity to support large-scale manufacturing with consistent bulk formats. Their differentiation often rests on integrated sourcing, processing scale, and the ability to serve diverse end markets through a unified ingredient platform. Application-focused suppliers, by contrast, tend to compete on formulation support, specialty coatings, and solutions designed for specific production environments. Their advantage lies in helping customers achieve desired texture, stability, and flavor with greater precision, particularly in bakery and confectionery operations where processing conditions vary widely. Ingredient innovation specialists contribute another angle: by offering flavor modulation and cocoa-reduction solutions, they address cost and formulation efficiency directly, making them valuable partners for manufacturers looking to optimize recipes without compromising consumer appeal. These strategic differences suggest that the market is increasingly segmented by value proposition rather than by product category alone.
The competitive landscape is likely to evolve through a combination of consolidation, specialization, and selective new entry. Consolidation remains plausible among companies seeking broader geographic reach, ingredient breadth, or enhanced processing capacity. At the same time, specialization will continue to matter for suppliers that can deliver unique functional benefits, stronger application support, or more responsive regional service. New entrants may find opportunity in niche segments such as compound chocolate systems, bakery premix integration, or flavor-modulation ingredients, especially where they can address specific pain points in formulation, shelf stability, or cost control. Recent operational developments illustrate these dynamics: recalls have prompted renewed attention to safety and process control across multiple firms, while capacity additions such as new pilot bakery facilities in the United States indicate strategic investment in closer customer support. For decision-makers, the practical implication is that supplier selection should weigh not only price and availability, but also technical capability, compliance discipline, and the ability to adapt to product and process requirements.
- Global processors differentiate through scale, sourcing breadth, and consistent bulk supply across multiple industrial applications
- Application-focused suppliers compete on formulation precision, specialty coatings, and close support for bakery and confectionery production
- Flavor and ingredient technology providers create value by enabling cocoa usage optimization without sacrificing sensory quality
- Market evolution favors firms that combine compliance rigor, regional responsiveness, and technical service with competitive pricing
Forward Outlook: Three Trends to Watch
Cost Discipline and Ingredient Efficiency Will Become Central to Formulation Strategy
Even with periods of lower cocoa prices, the broader cost environment for food manufacturing remains sensitive to logistics, energy, labor, and compliance expenses. This means industrial chocolate buyers will continue to prioritize ingredient efficiency and formulation flexibility. Suppliers that can offer solutions designed to reduce cocoa dependence, improve handling characteristics, or streamline production steps are likely to capture stronger interest from cost-conscious manufacturers. Over the next three to five years, ingredient strategy will increasingly revolve around achieving target sensory profiles while controlling input costs and maintaining processing reliability. The commercial opportunity lies in partnerships that combine product performance with measurable efficiency gains, especially for high-volume bakery and confectionery operations. The risk is that cost pressure may intensify competition on price alone, squeezing margins for suppliers that cannot demonstrate differentiated value or technical support.
Food Safety, Traceability, and Compliance Will Act as Competitive Filters
Recent recall events have made it clear that food safety performance is not a back-office concern; it directly affects brand trust, supply continuity, and buyer willingness to commit to long-term supply arrangements. Over the coming years, buyers are likely to place greater weight on documented traceability, supplier quality systems, and rapid incident response. Companies that can provide transparent process controls, clear audit trails, and proactive communication will be better positioned to secure and retain industrial contracts. This trend benefits suppliers with mature quality infrastructure and creates headwinds for those with weaker controls. The commercial opportunity for well-prepared suppliers is to use compliance strength as a differentiator in procurement decisions. The uncertainty lies in the possibility of further regulatory scrutiny and the need to adapt quickly to new expectations around labeling, ingredient purity, and contamination prevention.
Regional Proximity and Application-Specific Service Will Gain Importance
Industrial chocolate buyers are increasingly looking for faster response, closer technical collaboration, and supply arrangements that align with local production needs. Capacity investments near key markets, along with pilot and application facilities, suggest that suppliers are responding to demand for more immediate support and better integration with customer workflows. In the next few years, regional service capability may become as important as product range, particularly for manufacturers that need formulation tweaks, troubleshooting, or shorter lead times. The opportunity is for suppliers to build regional footprints and application expertise that reduce friction in product development and production scaling. The risk is that regional expansion requires disciplined execution; without strong operational control, proximity alone will not deliver the reliability or technical value customers expect.
- Ingredient efficiency and formulation flexibility will be central as manufacturers balance sensory goals with cost and processing constraints
- Compliance and traceability capability will increasingly influence supplier selection and long-term contracting decisions
- Regional proximity and application support are likely to become stronger differentiators for suppliers serving industrial production environments
Strategic Actions for Decision-Makers
For Industrial Manufacturers and Formulators
Treat ingredient selection as a multidimensional decision rather than a simple price comparison. Evaluate suppliers on their ability to support formulation targets, maintain processing consistency, and respond quickly when products or production conditions change. Prioritize partners that can demonstrate strong quality systems, traceable sourcing, and clear communication around safety and compliance. Where possible, build relationships that include technical collaboration, whether for recipe optimization, compound chocolate handling, or coatings performance. In a market where volatility and regulatory attention remain elevated, the most resilient sourcing strategies combine cost awareness with reliability and application expertise.
For Investors and Corporate Strategists
Focus on business models that can convert technical value into durable competitive advantage. Scale alone is unlikely to guarantee outperformance if it is not paired with differentiated service, formulation capability, or strong compliance infrastructure. Look for companies that are expanding regional support, strengthening quality systems, and offering ingredient solutions that address cost efficiency or sensory optimization. Pay attention to how firms manage raw material volatility through hedging, contracting, and inventory discipline, as these capabilities influence margin stability. The most compelling opportunities are likely to emerge where suppliers can align product performance with the practical needs of high-volume manufacturing and evolving end-market expectations.
For Procurement and Supply Chain Leaders
Strengthen sourcing resilience by diversifying supplier options where feasible, while maintaining rigorous qualification standards. Incorporate food safety performance, traceability documentation, and incident response capability into supplier evaluation frameworks. Use contract structures that balance price exposure with supply continuity, especially in a market where raw material prices can move sharply over short periods. Establish clear expectations around audit access, documentation, and communication so that compliance becomes a shared operational standard rather than a reactive obligation. In practice, procurement teams that combine cost discipline with risk awareness are best positioned to protect production continuity and support product quality across changing market conditions.
Worldwide Chocolate Machines Market
- Evaluate suppliers on formulation support, processing reliability, and compliance discipline, not only on unit price
- Identify business models that combine scale, regional service, and technical differentiation to assess long-term resilience
- Build sourcing frameworks that integrate traceability, audit readiness, and flexible contracting to manage volatility and continuity risk
For executives seeking deeper segmentation, regional breakdowns, company-level benchmarks, and scenario-based planning inputs, a full research report can provide the detail needed to translate these market-wide observations into operational decisions. Access to more granular data on product forms, application flows, pricing dynamics, and supplier positioning enables more precise strategy design across manufacturing, sourcing, and investment priorities.
For detailed analysis of this topic, please visit the official page: Industrial Chocolate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com