

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Topical Skin Adhesive Market: Why 8.4% CAGR and Surgical Shift Redefine Growth

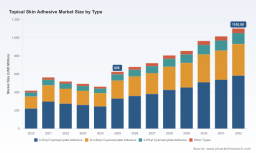
The Topical Skin Adhesive Market: Strategic Shifts and Commercial Opportunities Through 2032
The global market for topical skin adhesives has reached a pivotal inflection point, with 2025 baseline revenues establishing a valuation of USD 626.0 million and projected to climb to approximately USD 1.1 billion by 2032, reflecting a compound annual growth rate of 8.4 percent across the forecast horizon. This trajectory represents a meaningful recovery and acceleration from the volatility witnessed between 2020 and 2024, when revenue fluctuated between roughly USD 418 million and USD 564 million before consolidating near USD 462 million. The rebound underscores a structural shift rather than a cyclical correction: healthcare providers are increasingly viewing tissue adhesives as essential components of streamlined wound closure protocols, not merely as substitutes for sutures or staples. Yet beneath the headline growth lies a complex landscape where technological differentiation, regulatory navigation, and supply chain resilience will determine which participants capture lasting value.
Market Snapshot and the Weight Behind the Numbers
The market’s scale and institutional inertia are shaped by pronounced concentration dynamics. Three manufacturers command roughly 80 percent of global revenue, while five players account for close to 95 percent, creating an environment where incumbency confers significant advantages in distribution networks, clinical familiarity, and procurement relationships. At the same time, the product archetype remains relatively focused, with cyanoacrylate-based chemistries dominating clinical practice across surgical incisions, trauma-induced laceration repair, burn management, and skin grafting procedures. This concentration does not imply stagnation. On the contrary, it signals that meaningful growth will be captured by participants who can extend their reach through formulation innovation, application-specific differentiation, and strategic expansion into adjacent wound closure workflows.
Three Structural Challenges Defining the Next Phase of Growth
Several intersecting challenges will test market participants over the forecast period. First, the regulatory pathway for topical skin adhesives remains rigorous, with tissue adhesives for the topical approximation of skin classified as Class II devices under established FDA special controls frameworks. Manufacturers must demonstrate biocompatibility, sterility assurance, and consistent performance through controlled testing, while maintaining ongoing device registration and listing obligations. The clearance process is well-defined, but it imposes a persistent compliance burden and a timeline hurdle that can slow portfolio expansion, particularly for differentiated chemistries that fall outside legacy predicate pathways.
Worldwide Cosmetic Adhesive Market
Second, reimbursement mechanics introduce pricing and adoption friction. While topical skin adhesives are integral to wound closure procedures, billing structures for skin substitute grafts and related applications operate under separate CPT coding frameworks, meaning the economic case for adhesives must be built around procedural efficiency, reduced follow-up visits, and faster patient throughput rather than direct product reimbursement. In cost-conscious healthcare environments, demonstrating measurable impact on operating room efficiency and complication reduction becomes a commercial prerequisite, not a clinical nice-to-have.
Third, the market faces a structural tension between standardization and differentiation. A handful of legacy formulations have achieved broad clinical trust, creating high switching thresholds for new entrants and established competitors alike. At the same time, clinical needs vary considerably across incision types, tissue tension profiles, and practice settings ranging from high-volume surgical centers to emergency and outpatient environments. Companies that default to undifferentiated commodity positioning risk margin compression, while those that over-specialize without clear reimbursement or workflow integration may struggle to scale.
Innovation, Regulation, and Demand: The Forces Reshaping the Category
Technological innovation is expanding the functional envelope of topical skin adhesives. Recent regulatory milestones highlight a clear trend toward next-generation chemistries designed to address specific clinical pain points such as high-viscosity handling, controlled polymerization speed, and reduced tissue tension during closure. For example, a methylidene malonate-based formulation received FDA 510(k) clearance for incision and laceration closure, signaling interest in alternatives to traditional cyanoacrylate profiles. Around the same period, a high-viscosity topical skin adhesive and a companion skin closure system secured clearance, reflecting advances in application control and tissue sealing performance. Additional clearances for new cyanoacrylate-based variants further demonstrate that innovation is not limited to a single molecular pathway but spans formulation rheology, dispenser ergonomics, and procedural integration.
Policy and regulatory dynamics are simultaneously shaping the pace of commercialization. The Class II special controls framework establishes a predictable but demanding bar for market entry. Biocompatibility, sterility, and performance testing requirements create a baseline of safety and consistency that supports clinician confidence but also raise the cost of portfolio development. Manufacturers that build robust regulatory capabilities early are better positioned to introduce differentiated products with reduced delay, while those that rely on reactive compliance strategies face greater risk of rework and slower time to market. The regulatory environment also interacts with international market access, where CE marking and other regional clearances influence the sequence and geography of product launches.
Demand-side behavior is evolving as clinical and operational priorities shift. Surgical teams and emergency departments are increasingly optimizing for speed, reproducibility, and patient satisfaction. Topical adhesives that reduce closure time, minimize suture-related discomfort, and support cleaner wound edge approximation align well with these priorities. In parallel, outpatient and ambulatory surgical growth continues to redirect wound closure volume away from traditional inpatient settings, increasing demand for products that are easy to deploy, consistently perform under varied conditions, and fit into lean procedural workflows. The result is a demand profile that rewards both clinical reliability and practical usability, including dispenser design and application control features that influence day-to-day adoption.
Supply chain and cost structures add another layer of strategic importance. Concentration among top suppliers means that raw material availability, manufacturing scale, and quality control consistency can influence both product availability and margin stability. Geopolitical volatility, logistics constraints, and the cost of regulated-grade inputs can pressure pricing and complicate capacity planning. Participants who invest in resilient sourcing, disciplined manufacturing operations, and transparent quality systems are better positioned to protect service levels and sustain competitive pricing through periods of input cost fluctuation.
Competitive Landscape: Incumbency, Differentiation, and the Entry of New Players
The competitive field is anchored by a mix of large multinational portfolios and specialized device manufacturers, each pursuing a distinct route to relevance. One prominent incumbent maintains a market-leading position in 2-octyl cyanoacrylate formulations for surgical and trauma wound closure, leveraging long-standing clinical associations and broad procedural familiarity. This type of leadership is difficult to dislodge because it is reinforced by habit, surgeon comfort, and established procurement relationships, but it is not immune to erosion, especially where newer products offer materially improved handling, adhesion profiles, or deployment systems.
Another cluster of competitors competes through diversified wound closure portfolios and global distribution. These players often frame adhesives as part of broader surgical efficiency solutions, integrating topical adhesives with complementary consumables and procedural support. Their advantage lies in cross-selling opportunities across hospital systems and the ability to position products within institutional purchasing frameworks that value breadth and reliability. A third group focuses on specific product attributes, such as fast polymerization, high-viscosity control, or low-tension closure in minimal-tension scenarios. This specialization can create strong clinical niches, but success depends on translating a technical advantage into documented workflow benefits that procurement teams and clinicians can recognize and justify.
Recent development activity illustrates how the competitive frontier is moving. Multiple companies have secured FDA clearances over the past eighteen months for products spanning n-butyl cyanoacrylate, high-viscosity formulations, and methylidene malonate-based systems. Several of these launches emphasize ease of skin edge approximation, controlled application, or closure system compatibility. Taken together, these approvals indicate a market that is opening to more varied chemical options and application architectures, reducing the effective monopoly that any single formulation family might otherwise hold. The practical implication is that incumbents must continue to innovate or at least demonstrate consistent performance improvements to defend share, while new entrants can gain traction by solving specific procedural problems rather than competing on generic product claims.
The market structure is likely to evolve through a combination of consolidation and fragmentation. Concentration supports stability and scale at the top, but it also creates room for focused challengers that address unmet needs in specialized clinical areas or geographies. Potential M&A activity could unite complementary portfolios, particularly where a large platform seeks to deepen its wound closure offering or a specialized firm aims to gain global reach. At the same time, entrepreneurial entrants with differentiated chemistries or dispenser technologies may carve out segments in outpatient surgery, urgent care, or emerging markets where procedural efficiency and cost control are particularly acute.
Three Trends That Will Define the Next Three to Five Years
The first trend is formulation and delivery system convergence. Demand for improved handling, predictable bonding, and reduced operative time will encourage products that pair advanced chemistries with purpose-built dispensers and closure systems. The commercial winners will be those that integrate product and procedure, not just product alone. This creates opportunities for companies that can design around clinician workflow, minimize variability in application, and support consistent outcomes across different users and settings.
Worldwide Topical Dispenser Market
The second trend is geographic and setting expansion driven by procedural shift and access growth. As surgical volume continues to migrate toward ambulatory and outpatient environments, and as emerging markets broaden access to advanced wound closure options, topical skin adhesives will encounter new adoption pathways. Success in these channels will depend less on replicating the same hospital-centric sales models and more on packaging value propositions around ease of use, training support, and total cost of care. Manufacturers that adapt their go-to-market approach to these settings can unlock incremental volume without relying solely on large-institution contracts.
The third trend is intensified scrutiny of value and total procedural economics. With reimbursement structures separating adhesive application from related graft and substitute billing pathways, the burden of proof shifts toward demonstrated efficiency and clinical outcomes. Companies that can articulate how their products reduce closure time, lower the need for suture removal visits, or support faster discharge will be better positioned in procurement discussions. This trend also creates a risk: products that cannot clearly connect clinical performance to operational benefit may face pricing pressure or slower adoption despite strong regulatory clearance.
Strategic Implications for Decision Makers
For manufacturers, the priority is to balance portfolio breadth with credible differentiation. A broad catalog alone is unlikely to sustain premium positioning in a concentrated market. Instead, companies should identify the specific clinical problems where their chemistry or delivery system delivers a measurable advantage, then build the evidence, training, and system compatibility needed to reinforce that advantage. Regulatory strategy should be treated as a growth lever, not just a compliance checkpoint, with early planning for biocompatibility, sterility, and performance testing that aligns with intended launch geographies and indications. Supply chain resilience deserves equal attention, particularly for regulated inputs and critical components, because service continuity and quality consistency increasingly influence purchasing decisions.
For investors, the most promising opportunities lie at the intersection of innovation, workflow integration, and access expansion. Capital should favor companies with clear formulation or delivery differentiation, demonstrable regulatory execution, and business models that can scale beyond a single product cycle. Particular attention should be paid to how reimbursable procedural context influences adoption, since the economic case for adhesives often depends on operational benefits rather than direct product reimbursement. Investors should also monitor consolidation signals, as the concentrated structure of the market may incentivize platform acquisitions that reshape competitive dynamics and create new distribution advantages.
For procurement and clinical leaders, the decision framework should extend beyond unit price to total procedural impact. Evaluating adhesives through the lens of closure consistency, application ergonomics, training burden, and post-procedure follow-up can reveal value that is not visible in a simple cost comparison. Institutions should seek products that align with their patient flow, staff skill mix, and setting-specific requirements, while ensuring that supplier quality systems and supply reliability support ongoing operational stability. In concentrated markets, disciplined supplier evaluation and clear internal performance criteria help avoid overreliance on legacy familiarity alone.
PW Consulting Health Care Research Center
Why Timely Intelligence Matters
The topical skin adhesive market is at a stage where incremental advantages in formulation, regulatory execution, and workflow integration can translate into durable share gains, but the window to act is narrowing as more products enter the cleared pipeline and procurement teams reassess alternatives. Strategic decisions made today, whether around portfolio focus, launch sequencing, supply resilience, or sourcing criteria, will shape competitive positioning well into the latter part of the decade. For teams that need detailed segmentation data, competitive benchmarking, pricing dynamics, and customized scenario analysis, deeper intelligence is essential to convert these directional trends into precise execution plans. Comprehensive research resources are available to support that next step, offering the granular insight required to move from strategic direction to operational commitment.
For detailed analysis of this topic, please visit the official page: Topical Skin Adhesive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com