

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
LVT Flooring Market: Why 5.48% CAGR and Rigid Core Growth Shift the 2032 Outlook
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the LVT Flooring Market
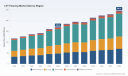
The global luxury vinyl tile (LVT) flooring market has matured from a niche alternative into a mainstream substrate for both residential and commercial interiors. Over the past five years, revenue growth has tracked consistent expansion, moving from approximately USD 117.5 million in 2020 to USD 169.6 million in 2025, with a projected trajectory reaching USD 246.4 million by 2032. The observed Compound Annual Growth Rate (CAGR) of 5.48 percent across the 2026–2032 forecast period signals that demand tailwinds remain intact, even as the market navigates structural volatility in raw materials, shifting trade policy, and evolving sustainability expectations. For executives, investors, and procurement teams, the critical question is no longer whether LVT will continue displacing traditional hard-surface alternatives, but how competing firms will navigate the next phase of differentiation, margin protection, and geographic rebalancing.
Market Snapshot and Structural Context
LVT flooring now operates in a landscape where growth is broad-based but uneven. Rigid-core formats dominate installed volume, while flexible variants maintain relevance in retrofit and performance-sensitive applications. Residential deployments continue to account for the largest share of end-use demand, yet commercial installations are gaining traction due to durability, maintenance economics, and design flexibility in hospitality, healthcare, and retail environments. Regional demand is distributed across mature and emerging markets, with Asia Pacific representing the largest revenue pool, North America and Europe holding substantial shares, and Latin America and the Middle East/Africa contributing smaller but increasingly strategic volumes as urbanization and renovation cycles accelerate.
PW Consulting Health Care Research Center
Market concentration remains relatively fragmented at the top, with the top three players holding roughly 12.0 percent and the top five around 15.0 percent of total revenue. That fragmentation is not a sign of immaturity; it reflects the presence of regional specialists, premium designers, and diversified building materials groups competing across price points, aesthetics, and sustainability credentials. In practice, the market rewards firms that can fuse product performance with supply chain resilience and regulatory readiness, rather than those that compete solely on footprint or price.
1. Market Status and Core Challenges
Robust headline growth masks several pressure points that are reshaping competitive dynamics. The LVT sector is entering a period in which incremental volume gains must be defended against cost volatility, trade disruption, and tightening environmental requirements. Three challenges stand out as especially consequential for strategic planning.
Raw Material Volatility and Margin Compression
Resilient flooring production is highly sensitive to the price and availability of PVC suspension resin, plasticizers, stabilizers, and reinforcing additives. Price movements in China—the benchmark hub for many resin transactions—have shown sharp swings driven by feedstock costs, logistics constraints, and regional supply adjustments. In early 2026, PVC suspension resin prices on a China FOB basis climbed to approximately USD 783.55 per metric ton by March, following an increase of roughly 20.90 percent from January, before easing later in the quarter as supply improved and spot pricing moderated to around 5.60 RMB/kg. These swings create a recurring margin squeeze for manufacturers who cannot pass through input costs quickly enough or who lack long-term contractual hedges. Larger players have responded with selective pricing actions, but sustained inflation in end-market prices can dampen demand elasticity, particularly in price-sensitive segments.
Trade Policy and Regional Cost Dislocation
Tariff escalation has added a second layer of complexity, particularly for markets that depend on cross-border sourcing. In the United States, baseline tariffs on Chinese LVT flooring imports rose to 145 percent effective April 2025, with additional country-specific surcharges applied to major source regions. This shift has re-weighted sourcing calculus for distributors and manufacturers, prompting re-evaluation of dual-sourcing strategies, regional capacity deployment, and logistics routing. For producers importing resin or finished goods, the cost base has become less predictable, and for buyers, landed cost comparisons across origins require more granular analysis than in prior years.
Luxury Vinyl Tile (LVT) Market
Sustainability Credentials as a Commercial Gatekeeper
Environmental performance is transitioning from a differentiator to a procurement prerequisite. Builders, architects, and property managers increasingly evaluate flooring on low-VOC emissions, recyclability, PVC-free options, and circular design attributes. Regulatory scrutiny is intensifying in parallel: India’s Directorate General of Trade Remedies initiated a countervailing duty investigation into Chinese PVC suspension resin imports in 2025, noting that Chinese PVC accounted for nearly 47 percent of domestic suspension resin imports. Such developments illustrate how material sourcing, trade policy, and environmental compliance are converging into a single strategic risk domain. Firms that lack credible sustainability narratives or traceable sourcing may face longer sales cycles, specification barriers, and heightened exposure to regulatory shifts.
2. Key Drivers Shaping the Market
Despite the challenges, the LVT market is being propelled by a set of durable drivers that create opportunities for companies willing to invest in product architecture, operational flexibility, and customer value propositions. Four forces are especially salient.
Technological Innovation in Core Architecture and Performance
Product engineering continues to expand the functional envelope of LVT. Rigid-core formats, including stone plastic composite and wood plastic composite constructions, provide improved dimensional stability, moisture resistance, and installation tolerance, making them suitable for basements, kitchens, and commercial spaces with elevated wear requirements. Hybrid offerings that blend rigid-core durability with flexible installation characteristics address a broader set of substrates and end-use conditions. Manufacturers are also advancing surface designs that more closely replicate wood, stone, and textured concrete, reducing the aesthetic gap that once limited LVT adoption in premium segments. The commercial effect is twofold: higher willingness to pay in design-led applications and reduced failure rates in demanding environments, both of which support margin and repeat purchase behavior.
Policy and Regulatory Signals Steering Material Choices
Policy is not merely a constraint; it is shaping demand toward specific material pathways. Low-VOC formulations, recyclable backing systems, and reduced reliance on conventional PVC are increasingly rewarded in specification processes and green-building frameworks. Product launches in 2025 and early 2026 reflect this direction. In March 2025, Armstrong Flooring introduced an eco-friendly LVT collection with 100 percent recyclable backing and low VOC emissions, signaling a focus on circularity and indoor air quality. In January 2026, Tarkett unveiled the ReNue hybrid non-PVC residential resilient flooring collection, expanding its LVT/SPC/WPC range with sustainability credentials. For commercial players, these moves indicate that compliance and certification are becoming part of the product’s value proposition, not just a regulatory checkbox.
Demand-Side Shifts in Residential and Commercial Environments
Consumer and enterprise behavior continues to favor resilient flooring for practical and aesthetic reasons. In residential settings, homeowners and renters seek waterproof, durable, and visually versatile surfaces that can accommodate active living, pet traffic, and easy maintenance. The renovation cycle in aging housing stock and the expansion of multifamily construction sustain demand for products that install efficiently and perform across moisture-prone areas. In commercial environments, facility managers prioritize lifecycle cost, hygiene, and design consistency. LVT’s capacity to deliver modular replacement, uniform appearance, and resilience under foot traffic supports its adoption in retail, hospitality, and healthcare. Notably, demand is not monolithic: premium designer collections appeal to specifiers looking for texture realism and brand-aligned aesthetics, while value-oriented rigid-core products serve volume-driven projects where total cost and durability dominate decisions.
Supply Chain Realignment and Capacity Investment
Capacity expansion and sourcing strategy are becoming competitive levers. In October 2024, Shaw Industries announced a USD 90 million investment at its Ringgold, Georgia Plant RP to double SPC and LVT production capacity by 2026, illustrating how producers are building regional manufacturing buffers to reduce exposure to import volatility and improve service reliability. At the same time, raw material dynamics are forcing more active procurement postures. Mohawk Industries initiated pricing increases across regions and product categories in 2025 to offset material cost rises, including tariff impacts, according to its 2025 Annual Report. These adjustments reflect a broader pattern: companies are balancing capacity investment with pricing discipline to protect margins without sacrificing volume. The strategic implication is clear—supply chain design is now inseparable from competitive positioning.
3. Competitive Landscape and Leading Strategies
The competitive field combines large diversified manufacturers, regionally anchored producers, and premium specialists. This mix creates a multi-layered market in which advantage depends on the alignment of product portfolio, manufacturing footprint, sustainability narrative, and commercial execution.
Strategic Positioning of Leading Players
Several companies illustrate distinct competitive postures that are shaping the market’s evolution.
- Mohawk Industries operates as one of the world’s largest flooring manufacturers, with PVC-free hybrid resilient offerings and SPC/LVT lines emphasizing high recycled content and waterproof performance. Its recent pricing actions across regions and categories underscore a strategy of protecting margins in the face of input cost and tariff pressure, while maintaining a broad portfolio that serves multiple price tiers.
- Shaw Industries produces SPC, flexible LVT, and rigid-core LVT with a strong emphasis on ecoWorx PVC-free and circular design solutions. Its USD 90 million capacity expansion in Georgia reflects a strategy centered on regional supply reliability, scale in resilient formats, and sustainability-aligned product architecture.
- Armstrong Flooring leads in LVT and modular resilient flooring, with eco-friendly collections featuring low-VOC formulations and recyclable backing. Its March 2025 product launch reinforces a positioning built around indoor environmental quality and end-of-life considerations, appealing to specifiers and buyers prioritizing health and circularity.
- Mannington Mills remains a family-owned producer known for ADURA luxury vinyl plank and tile collections with American-made options that stress innovation and quality. Its posture illustrates the value of brand trust, craftsmanship emphasis, and product consistency in premium and mid-premium segments.
- Tarkett is a global leader in resilient flooring, offering layered non-PVC LVT planks and tiles, SPC, WPC, and hybrid ReNue lines with sustainability certifications. Its January 2026 collection expansion highlights a strategy of broadening material alternatives while reinforcing environmental credentials across residential and commercial lines.
- Karndean Designflooring specializes in premium designer LVT with a focus on durable, aesthetically superior collections. Its positioning shows that design fidelity and texture realism can command loyalty in specification-driven projects where appearance is a primary decision factor.
- COREtec Floors focuses on rigid-core SPC and WPC LVT alternatives with advanced technology for moisture-prone areas. Its specialization demonstrates the commercial potential of targeted performance claims in segments where installation risk and environmental exposure are key concerns.
Differentiation Levers and Market Evolution
Across these profiles, differentiation is concentrating around several levers: material composition and environmental attributes, core technology and moisture performance, design realism and surface durability, regional manufacturing and supply continuity, and pricing strategy in response to input volatility. The market is not moving toward a single winner-takes-all structure. Instead, it is evolving through a combination of consolidation at the scale end and fragmentation at the specialty end. Larger players are expanding capacity and broadening eco-oriented portfolios to serve specification pipelines and national distribution networks. Specialists are deepening niche authority in premium design or performance-sensitive applications. At the same time, trade and material pressures are encouraging more regionalized sourcing and production, which can benefit locally anchored manufacturers while raising the entry bar for undifferentiated exporters.
A notable trend is the convergence of sustainability and performance in product messaging. The most resilient strategies pair credible environmental attributes with durable, installable, and maintainable products. Where sustainability is presented without performance credibility, it risks being discounted in commercial evaluations; where performance is advanced without environmental readiness, it may face growing specification friction. The leaders are therefore integrating both dimensions into product development, marketing, and supply chain decisions.
4. Future Trends and Commercial Opportunities
Looking ahead three to five years, the LVT market is likely to be shaped by several interconnected trends. Each carries explicit implications for strategy, investment, and procurement.
Trend 1: Material Diversification and PVC-Alternatives Gain Commercial Weight
As environmental scrutiny and regulatory attention intensify, material diversification will move from exploratory to mainstream. Non-PVC and PVC-reduced constructions, recyclable backing systems, and hybrid core designs will become more common across residential and commercial lines. This shift creates opportunities for manufacturers that can deliver comparable performance with alternative material architectures, as well as for distributors and specifiers who can offer clients a broader menu of compliant options. The commercial prize is not simply greener marketing; it is access to projects where material restrictions, indoor air quality targets, and circular economy goals influence specification and procurement. The uncertainty lies in verifying that alternative formulations maintain durability, moisture resistance, and cost competitiveness at scale.
Trend 2: Regionalization of Capacity and Sourcing as a Margin Defense
Tariff escalation, resin price volatility, and logistics uncertainty are likely to reinforce regionalization strategies. Producers will continue to invest in local or near-local capacity to reduce lead times, mitigate import cost shocks, and improve service levels. Buyers will increasingly favor suppliers with transparent sourcing, predictable landed costs, and contingency options across geographies. This trend favors firms that can combine capacity flexibility with disciplined procurement and pricing mechanisms. The risk is that regionalization may raise capital intensity and limit scale advantages for smaller players, potentially widening the gap between integrated manufacturers and niche producers unless the latter can secure differentiated positioning or partnership-based distribution.
Luxury Vinyl Flooring (LVT) Market
Trend 3: Premiumization in Design Coexisting with Value-Driven Volume Growth
The market will likely sustain a two-track dynamic. On one track, premium designer collections will grow by delivering superior aesthetics, texture realism, and brand-aligned experiences for specification-led projects. On the other, value-oriented rigid-core products will continue to capture volume in residential renovations, multifamily builds, and commercial renovations where total cost, durability, and installation efficiency matter most. This bifurcation creates opportunities for portfolios that can serve both tracks without cannibalizing brand equity. Manufacturers that can modularize platforms—sharing core technology while differentiating surface design, finish, and sustainability credentials—will be better positioned to capture share across segments. The uncertainty is that design-led premiumization depends on macroeconomic confidence and discretionary spending, while value-driven growth is more sensitive to raw material inflation and tariff-induced price increases.
5. Actionable Guidance for Decision-Makers
For executives and strategy teams, the practical implications of these trends can be translated into focused actions tailored by role.
For Manufacturers and Brand Owners
- Align product development with both performance and environmental credibility. Prioritize formulations and backing systems that reduce VOC emissions, improve recyclability, or offer PVC-reduced alternatives without sacrificing moisture resistance or dimensional stability.
- Build pricing and procurement flexibility into the operating model. Use a mix of long-term input contracts, regional sourcing options, and scenario-based pricing to manage resin volatility and tariff exposure, rather than relying on reactive price changes alone.
- Invest in capacity where service reliability and cost predictability matter most. Regional production can reduce lead-time risk and improve responsiveness to specification pipelines, especially in markets with elevated import costs.
For Investors and Corporate Development Teams
- Evaluate exposure to material and trade risk as part of valuation. Companies with diversified sourcing, regional manufacturing, and credible sustainability portfolios may show greater resilience to input shocks and specification barriers.
- Look for platforms that can serve both premium and value segments through shared core technology and differentiated surface or sustainability attributes. Such platforms can capture broader demand cycles while preserving margin structure.
- Monitor regulatory developments in material trade and environmental compliance, particularly where investigations or tariff actions affect resin imports and finished product flows. These dynamics can reshape cost structures and competitive positioning quickly.
For Procurement and Specification Teams
- Compare total cost of ownership rather than upfront price alone. Installation tolerance, moisture performance, maintenance requirements, and warranty terms can materially affect lifecycle economics in both residential and commercial deployments.
- Incorporate sustainability criteria early in specification and sourcing decisions. Recyclable backing, low-VOC emissions, and lower-PVC options increasingly influence project approval and stakeholder acceptance, especially in green-building contexts.
- Diversify supplier options to manage tariff and logistics risk. Dual-sourcing across regions, combined with clear landed-cost analysis, can reduce exposure to sudden duty changes or resin price spikes.
The LVT flooring market is at a point where growth is supported by durable demand, but the path to profitable growth is increasingly shaped by material volatility, trade policy, and environmental expectations. Firms that treat these forces as strategic variables—rather than external noise—will be better positioned to protect margins, win specifications, and expand share across segments. For decision-makers seeking a deeper view of segment-level dynamics, regional cost structures, and customized scenario planning, a comprehensive market research report offers the granularity needed to translate these trends into concrete operating choices.
For detailed analysis of this topic, please visit the official page: LVT Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Metformin Hydrochloride Market: The 6.3% CAGR Shift Reshaping Diabetes Care Through 2032
By pmarketresearch, 2026-09-21
Metformin Hydrochloride Market: Strategic Trends and Commercial Opportunities Through 2032
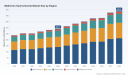
The global Metformin Hydrochloride market presents a compelling case study in mature therapeutic sectors navigating structural transition. Valued at approximately USD 289.5 million in 2025, the market has demonstrated steady growth from its 2020 baseline, reaching an expected USD 438.6 million by 2032. This trajectory reflects a compound annual growth rate of 6.3 percent over the forecast period spanning 2026 through 2032. Such figures underscore a sector that remains fundamentally sound while facing evolving competitive and regulatory pressures. The market's resilience stems from metformin's entrenched position as a first-line therapy, yet the growth narrative is increasingly shaped by formulation innovation, geographic demand shifts, and intensifying generic competition rather than pure volume expansion.
For executive decision-makers, understanding this market requires looking beyond headline revenue figures. The value distribution reveals distinct concentration patterns and therapeutic dependencies that shape strategic options. North America accounts for the largest regional share, followed by Europe, with Asia Pacific representing a smaller but increasingly dynamic segment. The immediate release formulation dominates the product landscape, while extended release variants capture a meaningful secondary position. Therapeutic application remains heavily anchored in Type 2 Diabetes Mellitus management, with polycystic ovary syndrome and other indications comprising the remainder. This structural profile suggests that growth opportunities lie less in unseating the core diabetes indication and more in expanding into adjacent therapeutic areas, optimizing delivery formats, and capturing value in emerging markets where prevalence rates continue to climb.
The competitive environment reflects pronounced concentration, with the top three manufacturers commanding over two-thirds of market revenue and the top five firms controlling nearly four-fifths of total sales. Such concentration indicates high barriers to entry, established supply chain relationships, and manufacturing scale advantages that favor incumbents. However, the presence of multiple certified producers across China and India, combined with regulatory tailwinds enabling continued generic approvals, suggests that competitive dynamics remain fluid beneath the surface. Companies that can balance scale efficiency with regulatory agility and formulation differentiation are best positioned to capture disproportionate value as the market evolves.
Market Landscape and Core Challenges
Navigating a Mature but Shifting Terrain
The metformin hydrochloride sector operates at the intersection of established clinical utility and evolving commercial realities. While demand fundamentals remain robust, several structural challenges are reshaping how value is created and captured. Recognizing these constraints is essential for developing strategies that avoid margin compression and instead target sustainable competitive advantage.
Challenge One: Sustained Generic Price Erosion and Reimbursement Pressure
Metformin hydrochloride generics operate in an environment of intense price competition across major markets. Reimbursement and formulary pressures continue to compress margins for manufacturers and suppliers, particularly in regions where multiple therapeutically equivalent products compete for the same patient populations. This dynamic rewards operators with lowest-cost production profiles, efficient distribution networks, and strong relationships with payers and pharmacy benefit managers. Companies that rely on commoditized positioning without clear differentiation face persistent headwinds, as price erosion outpaces volume growth in several mature markets. The strategic implication is clear: scale efficiency alone is no longer sufficient, and manufacturers must actively manage formulary positioning, supply chain economics, and customer segmentation to protect profitability.
Challenge Two: Regulatory Complexity Around Impurity Management and Quality Assurance
Ongoing regulatory requirements around nitrosamine impurity monitoring and reformulation remain active compliance priorities for all metformin hydrochloride manufacturers. FDA guidance continues to emphasize stability testing, risk assessment, and post-marketing surveillance as part of manufacturing oversight. Multiple manufacturers have addressed impurity concerns through voluntary recalls and updated testing protocols, reflecting an industry-wide focus on quality consistency and regulatory alignment. For market participants, this creates a dual imperative. Compliance is non-negotiable, yet it also represents a competitive differentiator. Manufacturers that invest in robust quality systems, transparent testing practices, and proactive regulatory engagement can reduce supply interruption risk while building trust with buyers who increasingly prioritize supply security alongside cost considerations.
Challenge Three: Balancing Volume Growth with Margin Preservation
The market's growth trajectory implies expanding demand, but translating volume increases into sustainable profitability requires deliberate strategy. Generic competition, reimbursement dynamics, and the concentration of market share among leading producers mean that new entrants and smaller suppliers must identify niches where they can command preferential positioning. This might include specialized extended release formats, particular regional supply roles, or value-added services that reduce total cost of ownership for buyers. The broader challenge is avoiding the trap of competing solely on price in a market where price leadership is increasingly contested by operators with deep manufacturing infrastructure and multi-market clearance.
Key Growth Drivers and Strategic Inflection Points
Formulation Innovation and Combination Therapy Dynamics
Innovation in metformin delivery and combination products continues to shape demand patterns and competitive positioning. Extended release formulations provide an important alternative to immediate release products, offering tolerability advantages and dosing convenience that can influence prescriber preference and patient adherence. Recent product launches illustrate this direction. In March 2026, Lupin Pharmaceuticals introduced generic dapagliflozin and metformin hydrochloride extended-release tablets in the United States following FDA approval, reflecting the market's move toward combination therapies that pair metformin with newer antidiabetic agents. Similarly, in June 2026, Apotex Corp. launched sitagliptin and sitagliptin/metformin hydrochloride tablets eligible for 180-day shared exclusivity, demonstrating how formulation strategy and regulatory timing can create temporary competitive windows. These developments indicate that value creation is increasingly tied to combination regimens, differentiated release profiles, and the ability to navigate exclusivity and approval pathways efficiently.
Regulatory Stability Enabling Continued Generic Access
Regulatory clarity around the availability of certain metformin formulations has supported continued generic approvals and market access. In March 2025, the FDA determined that metformin hydrochloride oral solution has not been withdrawn from sale for safety or effectiveness reasons, enabling continued generic approvals and preserving product variety in the market. This determination is significant because it reinforces the regulatory foundation for a broader range of delivery formats and reduces uncertainty for manufacturers planning formulation pipelines and market entry strategies. For decision-makers, such clarity lowers execution risk and supports long-term planning around product portfolios, capacity allocation, and regional launch sequencing.
Stable Input Economics and Supply Chain Resilience
API production economics for metformin hydrochloride have benefited from stable precursor pricing for key raw materials such as dimethylamine and cyanoguanidine, with no supply disruptions reported in 2026. This input stability supports more predictable manufacturing cost structures and allows producers to focus on operational efficiency, quality systems, and capacity optimization rather than absorbing volatility from raw material markets. For buyers and manufacturers alike, stable input costs reduce one layer of uncertainty and shift competitive emphasis toward execution quality, regulatory compliance, and commercial agility. The implication is that margin dynamics in the near term will be driven more by competitive strategy and pricing discipline than by raw material shocks, making operational excellence a primary source of differentiation.
Geographic Demand Evolution and Emerging Market Potential
Demand growth is increasingly influenced by geographic variation in disease prevalence, healthcare access, and generic penetration. While established markets continue to represent the largest revenue pools, emerging regions offer expansion potential as diagnosis rates improve, treatment guidelines broaden, and affordable generic supply becomes more accessible. Asia Pacific, in particular, reflects a dynamic where large patient populations, growing healthcare infrastructure, and competitive manufacturing presence intersect. Companies that build regional supply relationships, align product offerings with local formulary requirements, and invest in registration and compliance capabilities can position themselves to capture demand that outpaces mature market growth rates. This geographic dimension is not merely about sales expansion; it is about building durable market access in regions where long-term prevalence trends support sustained demand.
Competitive Landscape and Strategic Positioning
Scale, Certification, and Geographic Reach as Core Advantages
The competitive field features manufacturers with strong API production capabilities, regulatory certifications, and established export channels. Leading participants have built positions rooted in scale, certification, and supply reliability. Several Chinese and Indian producers operate FDA-approved and GMP-certified facilities, with some reporting substantial annual output capacity and dominant global supply shares. These characteristics matter because metformin hydrochloride remains a high-volume, quality-sensitive product where regulatory status and supply consistency directly influence buyer confidence. Manufacturers that combine scale with certified quality systems can secure long-term supply agreements and maintain preferred positions in global procurement processes.
Differentiation Through Combination Products and Formulation Expertise
Beyond API supply, competitive advantage is increasingly defined by formulation expertise and product portfolio breadth. Companies that can deliver extended release variants, combination tablets, and finished formulations alongside API supply are better positioned to serve integrated buyer needs. Recent launches underscore this pattern, as manufacturers introduce combination products that pair metformin with complementary therapies and seek exclusivity windows that create near-term commercial advantage. The strategic lesson is that value capture increasingly depends on moving beyond commodity API positioning into differentiated product offerings that address specific clinical and market needs. Companies that invest in formulation development, regulatory execution, and launch readiness can convert clinical utility into commercial differentiation.
Market Structure Evolution: Consolidation Pressure and Niche Opportunities
Market concentration suggests that consolidation pressures will persist, particularly as buyers favor suppliers that can provide reliable volume, regulatory assurance, and competitive pricing in a single relationship. At the same time, the presence of multiple certified producers and the continued launch of new generics indicate that niche opportunities remain for specialized suppliers, regional distributors, and companies targeting specific formulations or markets. The landscape is thus evolving along two tracks. On one hand, scale players are likely to strengthen their positions through capacity expansion, portfolio broadening, and integrated supply offerings. On the other hand, targeted entrants can find room by serving underserved geographic channels, specialized formats, or buyer segments that value responsiveness and tailored service over bulk commodity supply. The ability to read which track offers the most attractive risk-adjusted opportunity will separate successful strategies from commodity competition.
PW Consulting Health Care Research Center
Forward-Looking Trends and Strategic Implications
Trend One: Continued Emphasis on Combination Therapies and Extended Release Formats
The product launch activity observed in recent quarters points toward a broader trend in which metformin value is increasingly embedded in combination regimens and delivery formats that improve adherence and clinical outcomes. Over the next three to five years, opportunities will likely accrue to manufacturers and suppliers that can efficiently develop, approve, and commercialize combination products and extended release variants. This trend creates commercial opportunity for companies that align formulation pipelines with prescriber preferences, payer expectations, and exclusivity timing. It also introduces execution risk, since combination development and regulatory approval require coordinated capabilities across R&D, quality, and market access functions. Companies that treat formulation strategy as a core competency rather than a peripheral activity will be better placed to capture premium positioning within a generic market.
Trend Two: Regulatory Discipline as a Competitive Moat
Given persistent impurity monitoring requirements and ongoing post-marketing surveillance expectations, regulatory discipline will increasingly function as a competitive moat rather than a compliance baseline. Manufacturers that maintain transparent quality systems, proactive testing programs, and strong regulatory relationships will reduce the risk of supply interruptions and build credibility with procurement organizations that prioritize supply continuity. Over time, this could translate into preferential sourcing status, longer contract cycles, and greater resilience during regulatory scrutiny affecting the broader class. The strategic opportunity lies in converting quality and compliance investments into commercial trust, which can be a durable advantage in a market where buyers have multiple supplier options.
Minocycline Hydrochloride Market
Trend Three: Geographic Expansion and Supply Chain Localization
Demand growth in emerging markets, combined with buyer interest in resilient and regionally balanced supply chains, suggests that geographic expansion and supply chain localization will remain important themes. Companies that establish or strengthen regional manufacturing, distribution, and registration capabilities can position themselves closer to end demand, reduce lead-time risk, and align with procurement preferences for diversified sourcing. This trend is not without uncertainty, as regulatory requirements, pricing dynamics, and competitive intensity vary significantly across regions. The opportunity, however, is to build a balanced geographic footprint that captures higher-growth demand while managing the complexity of multi-market compliance and commercial execution.
Risk Considerations and Uncertainty Factors
Several risk factors warrant attention. Reimbursement and formulary pressures may continue to erode pricing power in key markets, particularly where generic competition is intense and substitution is routine. Regulatory expectations around impurity monitoring could evolve, creating compliance costs or requiring reformulation efforts that affect timelines and margins. Input cost stability may not persist indefinitely, and any disruption in precursor supply could alter cost structures quickly. In addition, concentration in the competitive landscape means that shifts in the strategy or capacity plans of leading producers could influence pricing and availability across the market. Decision-makers should therefore treat these factors as variables to monitor and manage rather than fixed assumptions, building flexibility into capacity planning, portfolio strategy, and supplier relationships.
Strategic Recommendations for Decision-Makers
For Manufacturers and API Suppliers
Prioritize formulation differentiation and regulatory agility as core strategic pillars. In a market where generic price erosion is persistent, competitive advantage increasingly comes from extended release capabilities, combination product readiness, and the ability to secure and maintain approvals across key markets. Manufacturers should also treat quality and impurity management as commercial assets, using robust compliance practices to strengthen buyer confidence and reduce supply interruption risk. Capacity decisions should balance scale efficiency with flexibility, ensuring that production infrastructure can support both high-volume API supply and more specialized formulation needs. Finally, building strong relationships with procurement organizations through reliability, transparency, and consistent quality can help protect positioning against price-based competition.
For Investors and Strategic Partners
Focus on operators with demonstrated regulatory compliance, diversified product capabilities, and exposure to both mature and higher-growth geographic demand. The market's growth trajectory is positive, but value creation will likely concentrate among companies that can combine scale with formulation differentiation and multi-market access. When evaluating opportunities, assess not only revenue potential but also the quality of regulatory standing, the durability of supply relationships, and the ability to manage reimbursement pressure without sacrificing margin integrity. Combination therapy launches and exclusivity-enabled product entries may create near-term commercial windows, but longer-term value will depend on sustainable cost structures and the capacity to navigate ongoing regulatory expectations.
Worldwide Berberine Hydrochloride API Market
For Procurement and Supply Chain Leaders
Diversify sourcing strategies while prioritizing suppliers with verified certifications, transparent quality practices, and demonstrated supply continuity. Given market concentration and ongoing regulatory oversight, relying on a narrow supplier base can increase vulnerability to disruption, while over-diversification without quality assurance can introduce compliance risk. A balanced approach involves qualifying multiple certified sources, monitoring regulatory developments that affect product availability, and integrating impurity monitoring and stability testing considerations into supplier evaluation. Procurement teams should also pay attention to formulation variety and combination product availability, as these can influence total cost of ownership, patient adherence, and downstream clinical outcomes. Building supplier relationships around reliability and quality, rather than price alone, can reduce long-term risk in a market where regulatory and competitive dynamics continue to shift.
Conclusion
The metformin hydrochloride market is entering a phase in which growth remains achievable, but the path to value creation is becoming more selective. Steady demand fundamentals, stable input economics, and regulatory clarity around certain formulations provide a supportive backdrop. At the same time, generic price erosion, impurity monitoring obligations, and concentrated competitive dynamics require deliberate strategy rather than passive participation. The companies and investors best positioned for the next several years will be those that treat formulation differentiation, regulatory discipline, and geographic agility as interconnected capabilities. For those seeking deeper segmentation data, regional breakdowns, company-level benchmarks, and customized scenario analysis, the full PW Consulting research report offers a more granular view of the market and the strategic options it presents.
For detailed analysis of this topic, please visit the official page: Metformin Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wireless Audio Device Market: Why 7.35% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-21
The Wireless Audio Device Market: Strategic Trends and Commercial Opportunities Through 2032
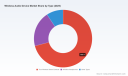
The global wireless audio device market has entered a phase of accelerated expansion. Valued at 40.0 million USD in 2020, the market has expanded steadily to reach 64.5 million USD by 2025, with projections indicating growth to 114.0 million USD by 2032. This trajectory reflects a compound annual growth rate of 7.35 percent across the 2026 to 2032 forecast period. Behind these figures lies a fundamental transformation in how consumers and enterprises consume audio, driven by evolving form factors, improved connectivity standards, and shifting usage patterns. For executives navigating hardware portfolios, supply chain investments, or product roadmaps, understanding the strategic inflection points shaping this market is essential.
Market Scale and Structural Realities
The recent expansion reflects more than cyclical demand recovery. It signals a structural shift in audio consumption habits. Consumers increasingly prioritize untethered listening experiences, while commercial environments deploy wireless audio for communications, entertainment, and specialized use cases. The market is not uniform. Premium audiophile segments coexist with highly price-sensitive mass markets, creating divergent profitability profiles and supply chain requirements. Manufacturers that treat wireless audio as a monolithic category risk misallocating resources across segments with fundamentally different demand dynamics.
Several structural challenges complicate this expansion. First, component cost volatility has introduced pronounced uncertainty into pricing strategies and margin management. Second, regulatory friction around trade flows and material sourcing is reshaping procurement pathways, particularly for companies dependent on cross-border component flows. Third, the market exhibits notable concentration among established players, which raises barriers for new entrants while simultaneously pressuring incumbents to defend differentiation as product features commoditize. These tensions define the competitive environment and determine which organizations will capture disproportionate value as the market matures.
Key Challenges and Inflection Points
Component supply constraints represent a primary pressure point. Specialized materials used in vibration motors and acoustic assemblies have experienced dramatic price movements. Neodymium and tungsten, critical to miniature transducer performance, have faced price surges linked to export controls and competing defense-sector demand. Tungsten prices, for example, have climbed more than 450 percent in a single year, fundamentally altering cost structures for manufacturers reliant on these inputs. Companies that have not diversified material sourcing or redesigned acoustic architectures around commodity alternatives face margin compression and production instability.
Trade policy adds a parallel layer of complexity. Effective tariff rates on electronics imports, including wireless audio components, have reached levels that materially affect landed costs. Average effective US tariff rates have hovered around 16.8 percent, with direct implications for procurement budgets and regional sourcing decisions. Simultaneously, export control adjustments in upstream material markets have introduced volatility. Temporary suspensions of export restrictions on rare earth metals and battery components have created short-term relief but also uncertainty about future supply continuity. These dynamics force manufacturers to treat geography as a strategic variable rather than a static procurement detail.
A third inflection point involves market concentration and the limits of feature-based differentiation. With the top three players holding over half of market share and the top five exceeding 60 percent collectively, incumbents benefit from scale, brand recognition, and ecosystem lock-in. Yet as core Bluetooth performance improves and noise-cancelling capabilities become standard across price tiers, differentiation increasingly depends on specialized use cases, audio architecture innovations, and integrated service ecosystems rather than incremental hardware upgrades. This shift raises the stakes for mid-tier manufacturers and creates openings for players that solve specific commercial or professional audio needs.
Home Audio Equipment Market
Key Demand and Supply Drivers
Technological Innovation and Acoustic Architecture Shifts
Technology leadership remains the most visible driver of market evolution. Research into MEMS-based speaker technology illustrates how component-level innovation can reshape product positioning. Recent product announcements have highlighted TWS earbuds incorporating MEMS speakers, establishing new benchmarks for acoustic performance in compact form factors. These developments matter because they address long-standing tradeoffs between size, sound quality, and power efficiency. As MEMS speakers move from niche applications to high-volume consumer products, manufacturers that integrate these components gain credible differentiation in a market where audio quality expectations continue to rise.
Digital audio resolution represents another frontier. Recent launches of USB-C wireless earbuds and headphones supporting 24-bit/96 kHz digital audio indicate that premium segments are beginning to treat wireless transmission as a platform for high-fidelity audio rather than a compromise. This trajectory aligns with broader consumer interest in immersive listening experiences and professional-grade audio quality at consumer price points. Manufacturers that ignore high-resolution wireless audio risk ceding premium positioning to competitors that align product architecture with evolving listener expectations.
Policy and Regulatory Environment
Regulatory and trade dynamics are reshaping the cost and risk landscape for wireless audio manufacturers. Tariff structures affecting electronics components have altered the economics of offshore sourcing, particularly for companies assembling products with globally distributed component chains. At the same time, export control adjustments on critical materials have created intermittent supply-side uncertainty. These forces do not simply raise costs; they change the calculus of where to design, source, and assemble. Companies that treat compliance and trade exposure as peripheral procurement issues face structural disadvantages compared to organizations that embed regulatory scenario planning into product development and supplier selection.
Regulatory developments also influence feature roadmaps. Standards around low-energy audio transmission, hearing-health compatibility, and connectivity interoperability create opportunities for manufacturers that align product design with emerging requirements. Rather than viewing regulation solely as a cost factor, forward-looking companies use compliance and interoperability as positioning tools, particularly in professional and commercial segments where reliability and standards adherence influence purchasing decisions.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer behavior continues to favor wireless personal audio for everyday use, but the composition of demand is broadening. Wireless audio devices are increasingly embedded in hybrid work environments, fitness ecosystems, travel scenarios, and smart-home interactions. This diversification means that product success depends less on generic listening features and more on context-specific performance, durability, and integration with broader device ecosystems. Manufacturers that design for specific usage environments gain stronger retention and willingness-to-pay than those competing solely on generic audio specifications.
Enterprise and commercial adoption introduces a separate demand vector. Wireless audio solutions for communications, customer-facing environments, and specialized professional workflows are expanding, driven by flexibility requirements and the declining cost of reliable wireless transmission. Commercial buyers evaluate audio devices through lenses that differ materially from consumer purchase behavior: total cost of ownership, serviceability, durability, and compatibility with existing communication infrastructure. Companies that address these criteria explicitly can access demand streams with different competitive dynamics than saturated consumer tiers.
Supply Chain and Cost Structure Reconfiguration
Supply chain strategy has moved from operational concern to strategic differentiator. Component volatility, trade exposure, and sourcing complexity reward manufacturers that build resilient material pipelines, dual-source critical assemblies, and design products with supplier flexibility in mind. The cost structure of wireless audio devices is increasingly defined not only by bill-of-materials optimization but also by geographic risk management, inventory buffering strategies, and design choices that reduce dependence on constrained materials.
This reconfiguration creates a competitive split. Organizations with diversified sourcing, local or nearshore assembly options, and acoustic designs that minimize exposure to scarce inputs can protect margins more effectively. Those locked into single-supplier relationships or concentrated material dependencies face greater vulnerability to price shocks and supply interruptions. The implication for strategy is clear: supply chain architecture is now a core element of product competitiveness, not a back-office function.
Competitive Landscape and Strategic Positioning
Incumbent Strengths and Differentiation Models
The market features a mix of ecosystem-driven incumbents, audio-specialist brands, and value-focused manufacturers. Leaders such as Apple, Samsung, and Sony leverage integrated device ecosystems, custom silicon, and strong brand recognition to sustain premium positioning. Their advantage lies not only in hardware performance but also in seamless connectivity, software integration, and user experience consistency. In this environment, wireless audio becomes part of a broader platform value proposition rather than an isolated product category.
Audio specialist brands including Bose, Sennheiser, and Shure pursue a different model. They compete on sound quality heritage, professional-grade reliability, and targeted product architectures for specific listening and performance environments. This approach allows them to command premium positioning in segments where audio fidelity, durability, or professional functionality outweigh ecosystem convenience. For these players, strategic focus on specialized use cases and acoustic expertise remains the foundation of differentiation.
Emerging and Regional Players Reshaping Price and Volume Dynamics
A second competitive layer includes manufacturers focused on value-oriented TWS products, regional market strength, and volume-driven growth. Companies such as Xiaomi, Anker, and boAt have expanded access to wireless audio by combining competitive pricing with functional feature sets. Their success reflects demand for functional wireless audio at accessible price points, particularly in price-sensitive markets and first-time wireless audio adopters. These players have also influenced industry expectations around feature availability at lower price tiers, pushing incumbents to justify premium pricing through meaningful performance or experience advantages.
The presence of strong regional players also complicates global competitive strategy. Manufacturers that succeed in one geography often face different brand dynamics, distribution structures, and price expectations in another. Global scale does not automatically translate into local relevance, and companies that underestimate regional competitive nuance risk losing share to adaptive local players.
Recent Product and Partnership Developments
Recent product movements highlight how competition is evolving at the feature and component level. Sennheiser's introduction of USB-C earbuds and headphones with 24-bit/96 kHz digital audio support reflects a push toward higher-resolution wireless listening in consumer-accessible form factors. Sony's announcement of next-generation wireless earbuds indicates continued investment in flagship performance and brand leadership in premium TWS segments. Meanwhile, product partnerships involving MEMS speaker technology in high-volume TWS earbuds point to a broader shift toward innovative acoustic components that can differentiate products without requiring complete platform redesigns.
PW Consulting Health Care Research Center
These developments matter strategically because they show differentiation migrating toward component architecture, digital audio capability, and targeted performance claims rather than generic connectivity. Manufacturers that align their roadmaps with these shifts can create defensible product positions; those that compete only on price or brand legacy face mounting pressure as feature parity increases.
Market Structure Evolution: Consolidation, Fragmentation, and Entry Dynamics
The market is simultaneously experiencing concentration among leading players and fragmentation in niche and regional segments. High concentration at the top reflects the advantages of scale, ecosystem integration, and sustained R&D investment. At the same time, specialized professional audio providers, hearing-focused device makers, and regional value brands continue to carve out distinct positions. This dual structure suggests that future competition will emphasize segmentation precision rather than blanket market coverage.
New entries are likely to succeed by solving specific audio problems rather than by launching generic wireless earbuds or headphones. Opportunities exist in commercial audio, hearing-compatible TWS designs, professional monitoring, and form factors tailored to particular usage contexts. Companies that approach the market with narrowly defined value propositions and strong component or acoustic differentiation have a more viable path than those attempting to compete broadly against entrenched ecosystem leaders.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Acoustic Component Innovation as a Differentiation Engine
The adoption of advanced acoustic components, including MEMS speakers and high-resolution digital audio architectures, is likely to accelerate through the next several years. As these technologies become more accessible, they will shift from premium differentiators to baseline expectations in mid-tier and premium segments. The commercial opportunity lies in early integration and in targeting use cases where improved acoustic performance translates directly into user value, such as compact devices with demanding sound quality expectations or professional listening applications that benefit from higher-resolution transmission.
The risk is that component innovation can be replicated faster than brand or ecosystem advantages. Manufacturers that treat new acoustic architectures as short-term marketing features rather than as part of a sustained product architecture strategy may find their differentiation eroded quickly. Sustainable advantage will depend on combining component innovation with tuning expertise, design integration, and use-case-specific validation.
Trend 2: Supply Chain Regionalization and Material Risk Management
Trade policy, material scarcity, and component price volatility are likely to drive incremental regionalization of sourcing and assembly. Manufacturers will increasingly evaluate suppliers not only on cost and quality but also on geographic resilience, material exposure, and tariff implications. The commercial opportunity lies in building procurement and design strategies that reduce vulnerability to single-source dependencies and constrained material inputs. Companies that proactively redesign products for supplier flexibility and material substitution can convert supply chain risk into a cost and reliability advantage.
Uncertainty remains around the trajectory of trade policy and export control decisions. Temporary suspensions or adjustments in material export rules can create short-term relief while leaving longer-term structures unchanged. Organizations that base planning on static assumptions risk repeated disruption. Scenario-based sourcing and flexible design architectures are more resilient approaches.
Trend 3: Segmentation Expansion in Commercial, Professional, and Hearing-Adjacent Use Cases
Demand is expanding beyond personal consumer listening into commercial workflows, professional monitoring, and hearing-supportive audio applications. This expansion creates opportunities for manufacturers that design with specific user environments in mind, rather than treating all wireless audio as interchangeable consumer products. Commercial buyers value durability, manageability, interoperability, and total cost of ownership; professional users prioritize reliability, acoustic consistency, and compatibility with existing systems; hearing-adjacent applications require attention to audio clarity, comfort, and standards alignment.
The strategic opportunity is to address these segments with product architectures and go-to-market models that differ from mass consumer strategies. This may involve stronger service and support models, application-specific tuning, compliance with relevant standards, and pricing structures that reflect usage value rather than only hardware cost. The risk is that these segments require different capabilities and partnerships, and companies without commercial or professional sales infrastructure may find adoption slower than in consumer channels.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Prioritize acoustic and component differentiation that is difficult to replicate through generic specification upgrades. High-resolution audio support, MEMS-based speaker integration, and use-case-specific tuning can create more durable positioning than incremental feature additions. Equally important, design products with supply chain flexibility in mind: reduce dependence on constrained materials where feasible, evaluate dual sourcing for critical assemblies, and model tariff exposure as part of product economics. In concentrated markets, success increasingly depends on solving specific user problems rather than competing across all segments simultaneously.
For Investors and Strategic Capital Allocators
Evaluate wireless audio exposure through the lens of differentiation durability and supply chain resilience rather than top-line growth alone. Companies with strong ecosystem integration, specialized acoustic expertise, or targeted commercial and professional positioning are better positioned to defend margins as feature parity increases. Also assess exposure to material cost volatility and tariff risk; business models that depend heavily on single-source components or concentrated geography-dependent sourcing carry higher disruption risk. Investment theses should account for segmentation strategy as a key indicator of long-term competitiveness.
For Procurement and Supply Chain Leaders
Treat sourcing strategy as a strategic lever, not only a cost exercise. Map exposure to constrained materials, tariff-impacted component flows, and single-supplier dependencies. Where possible, qualify alternative materials or suppliers for critical acoustic and electronic assemblies, and incorporate tariff and logistics scenarios into total cost models. Build flexibility into product specifications so that sourcing adjustments do not require full redesigns. In an environment where material and trade volatility is likely to persist, procurement decisions directly affect product economics and launch stability.
Bluetooth Audio Ic Market
Closing Perspective
The wireless audio device market is expanding, but expansion alone does not guarantee profitable positioning. The companies that will capture disproportionate value are those that treat differentiation as a function of acoustic innovation, supply chain resilience, and segmentation precision rather than scale alone. Component-level advances, regulatory and trade dynamics, and broadening demand contexts are reshaping the rules of competition. Executives who align product strategy, sourcing decisions, and market focus with these shifts will be better positioned to convert market growth into sustainable advantage. For organizations seeking deeper segmentation data, regional breakdowns, and tailored strategic recommendations, comprehensive research coverage is available to support more granular planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Wireless Audio Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Solar Shading Systems Market 2026: The Real Forces Behind 3.5% Growth Through 2032
By pmarketresearch, 2026-09-21
Strategic Horizons in the Solar Shading Systems Market: Navigating Growth, Regulation, and Material Shifts
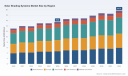
The solar shading systems market has matured into a critical intersection of building performance, energy efficiency, and architectural design. Valued at approximately $13.05 billion in 2020 and projected to reach $19.72 billion by 2032, the sector has demonstrated steady expansion across the historical period, reaching $15.50 billion in 2025. Forward projections indicate the market will scale to $16.52 billion by 2026, gradually climbing toward $16.81 billion by 2028 before accelerating into the $18.69 billion range by 2030. The implied compound annual growth rate of 3.5% over the forecast horizon reflects a market that is no longer defined by cyclical boom-and-bust patterns, but rather by structural shifts in building codes, consumer expectations, and supply chain restructuring. For executives and capital allocators, this trajectory signals a sector that has stabilized around baseline growth while simultaneously undergoing compositional changes that will separate value-creators from commoditized participants.
The market's growth profile is neither uniform nor predictable without context. Revenue has fluctuated modestly across recent years, with 2022 recording a slight contraction before rebounding in 2023 and plateauing near $14.97 billion in 2024. Such volatility underscores how the sector responds acutely to macroeconomic cooling, procurement delays, and regional construction cycles. Yet the broader arc remains upward, driven by the persistent need to manage solar heat gain, reduce HVAC loads, and meet increasingly stringent energy performance standards. Understanding where growth concentrates, what forces will reaccelerate or compress margins, and which competitive strategies will hold up under regulatory and material scrutiny is essential for anyone positioning around this market in the coming years.
Market Snapshot and Structural Challenges
At a macro level, the solar shading systems market is characterized by a relatively fragmented concentration structure. The top three participants account for roughly a quarter of total industry revenue, while the top five capture approximately one-third. This level of concentration suggests a market that remains accessible to regional specialists and niche innovators, but where scale, distribution breadth, and brand recognition still confer meaningful advantages. The baseline revenue size places the sector in a mature-middle tier of the building products landscape: large enough to support sustained investment and innovation, yet fragmented enough that acquisitions, partnerships, and product differentiators can shift regional standing quickly.
Three challenges currently define the industry's inflection point. The first is the tension between performance mandates and cost sensitivity. As energy codes tighten and building owners demand demonstrable efficiency gains, shading systems must prove measurable contributions to thermal comfort and load reduction. At the same time, residential and non-residential buyers continue to scrutinize upfront costs, especially in environments where interest rates or construction budgets constrain discretionary spending. Manufacturers that cannot articulate a clear return-on-investment narrative risk being relegated to price-based competition.
The second challenge lies in material compliance and supply chain predictability. Shading products increasingly operate within a regulatory and consumer environment that scrutinizes chemical inputs, recyclability, and embodied impacts. Formulations that rely on restricted substances or complex mixed-material constructions face higher compliance risk and potential end-market friction. Companies must navigate raw material variability, sourcing continuity, and de-risked formulations without sacrificing durability, aesthetics, or price competitiveness. This challenge is especially acute for products that integrate directly into glazing or facade systems, where material substitutions can affect certification timelines and installer confidence.
The third challenge is the growing expectation of integration and automation. Shading is no longer evaluated solely as a standalone component; it is increasingly part of broader building management, lighting control, and occupant experience ecosystems. That shift raises the bar for interoperability, software reliability, and service infrastructure. Firms that still approach shading as a purely mechanical or fabric-based product face a widening gap with competitors that can offer connected controls, adaptive responses to daylight, and seamless coordination with HVAC or lighting systems. Bridging that gap requires not only product engineering but also IT, firmware, and support capabilities that not every incumbent has cultivated.
Key Drivers Reshaping Demand and Competitive Dynamics
Technology Innovation and Embedded Performance
Technological progress in solar shading is increasingly defined by how effectively products manage heat, light, and ventilation in a single architecture. Rather than offering only blinds or awnings as discrete add-ons, leading solutions are moving toward integrated transparent systems that control passive heat while preserving daylight transmission. This evolution reflects a broader design priorities shift: architects and building owners want envelopes that perform passively, reduce dependence on active cooling, and maintain visual quality. Technologies that embed shading functionality directly into glazing or facade assemblies can lower 시공 complexity and improve long-term performance consistency, provided they meet durability and certification expectations.
Innovation is also extending into material design. The emergence of formulations that eliminate antimony and avoid PFAS-based chemistries indicates a direction where performance and environmental alignment are pursued together. Such developments matter because they reduce downstream compliance exposure, support specification into projects with strict material requirements, and position manufacturers to respond proactively rather than retroactively to shifting standards. In practical terms, a product that can demonstrate both thermal control efficacy and cleaner material composition gains an advantage in project approvals, procurement screening, and brand perception.
Policy and Building Energy Standards
Regulatory momentum remains one of the most reliable demand catalysts for solar shading. Energy-efficiency programs and building guidance increasingly treat window coverings and solar control measures as practical interventions to reduce heat loss, limit solar heat gain, and lower overall energy consumption. When government bodies promote these systems as part of broader building efficiency strategies, they not only validate the technology but also influence specification behavior among architects, contractors, and facility managers. The effect is especially pronounced in regions where new construction and retrofitting are both subject to tightening performance thresholds.
Policy impact, however, is uneven across geographies and project types. In some markets, incentives or code requirements accelerate adoption in residential new-builds and large commercial renovations. In others, the pace depends on local enforcement capacity and the availability of complementary incentives for envelope upgrades. For businesses operating across multiple regions, this variability means that policy tailwinds must be tracked market by market rather than treated as a uniform global force. The companies that benefit most are typically those that can adapt product portfolios and value propositions to where regulatory pressure is highest, while maintaining enough flexibility to serve less regulated segments without overinvesting in compliance features where they are not yet rewarded.
Demand-Side Behavior and Building Performance Expectations
Demand is shifting on both the residential and non-residential sides, but for related reasons. In residential contexts, homeowners and buyers are increasingly aware of comfort, glare control, and utility costs as part of the overall living experience. Shading systems are being evaluated not only for aesthetics but for their ability to improve indoor temperatures, reduce reliance on mechanical cooling, and support healthier daylight environments. This change in buyer mindset expands the addressable use case beyond decoration or privacy, turning shading into a functional building component with visible daily benefits.
In non-residential settings, the drivers are more institutional. Facility operators, developers, and property owners weigh shading systems against energy budgets, occupant productivity, and asset value. Commercial buildings that struggle with solar load often face compounding costs across HVAC operation, glare-related productivity losses, and tenant satisfaction. Solutions that combine shading with ventilation, facade integration, or automated control can help address several of these issues simultaneously, making them more compelling in project evaluations. The commercial demand story is therefore less about a single product feature and more about total building performance, which favors vendors that can speak the language of energy, comfort, and operational savings rather than simply hardware specifications.
Cost Structure and Supply Chain Realignment
The cost environment for solar shading systems is shaped by raw material dynamics, manufacturing footprint decisions, and the economics of customization versus standardization. Fabric-based systems continue to represent a substantial share of market value, reflecting longstanding demand for versatile, visually adaptable solutions. Metal and other type categories also hold meaningful positions, often associated with durability, architectural presence, and specific performance profiles. As material costs fluctuate and sourcing strategies evolve, companies must decide where to absorb volatility, where to pass through price changes, and where product design can reduce dependency on expensive or constrained inputs.
PW Consulting Health Care Research Center
Supply chain realignment is also being driven by the push toward cleaner material profiles and more predictable component sourcing. Where manufacturers can reduce formulation complexity, standardize core components, and streamline assembly, they typically gain margin stability and faster response times. Conversely, highly customized or multi-material products may face greater exposure to lead-time variability and compliance complexity. Over time, the cost structure winners are likely to be those that balance performance differentiation with manufacturing discipline, treating material innovation as a way to lower risk and total cost of ownership rather than as an isolated research objective.
Competitive Landscape and Leading Strategies
The competitive field includes manufacturers with distinctly different strategic emphases, ranging from architectural sun control and facade integration to interior shading breadth and smart control systems. Warema Renkhoff SE has built its identity around exterior and interior sun shading systems, louvers, awnings, and architectural solar control solutions. Its positioning suggests an emphasis on building-scale solar management and product breadth, appealing to projects where shading must coordinate with facade design and outdoor environmental conditions. Hunter Douglas N.V. offers a wide range of interior and exterior window shading systems, blinds, shades, and automated solutions, reflecting a strategy centered on brand reach, product variety, and consumer-facing distribution strength. Lutron Electronics Co., Inc. takes a more control-centric path, manufacturing smart shading and lighting control systems that integrate solar shading with automated performance and energy optimization. Its relevance lies in the growing overlap between shading hardware and building control infrastructure.
Fabric Solar Shading Systems Market
MicroShade A/S and DUCO Ventilation & Sun Control illustrate two other important strategic directions. MicroShade focuses on integrated transparent solar shading systems embedded in glazing for passive heat control, daylight transmission, and energy efficiency. This approach aligns with projects that seek envelope-level performance and reduced reliance on add-on components. DUCO produces natural ventilation and architectural solar shading systems, including louvers, screens, and facade solutions aimed at healthy, energy-efficient buildings. Its profile emphasizes the pairing of solar control with airflow management, a combination that resonates in settings where indoor environmental quality and passive performance are jointly prioritized.
These companies reflect a market in which differentiation is becoming more multidimensional. Some competitors compete on architectural integration and facade compatibility; others on consumer brand strength, automation, or material and environmental positioning. The presence of investment activity around advanced shading technology underscores that capital is flowing toward solutions with a clear performance narrative and potential for specification advantage. In August 2025, Nordic Alpha Partners invested in MicroShade's solar shading technology, an indication that integrated, material-forward approaches are attracting strategic interest. At the same time, market commentary in early 2026 highlighted a range of growth perspectives for the sector, with one estimate projecting the market from $15.79 billion in 2025 to $16.43 billion in 2026, and another forecasting expansion at a CAGR of 3.75% from $12.12 billion in 2025 to $15.12 billion by 2031. These differing frames reflect the normal variation in forecasting assumptions, but they also reinforce that the sector is being watched closely and that growth potential is real even if the exact magnitude depends on methodology and scope.
Worldwide Exterior Solar Shading Systems Market
The competitive landscape appears to be evolving along three axes. First, integration is creating a divide between firms that can deliver shading as part of a coordinated building system and those that offer shading more narrowly. Second, material and compliance readiness is becoming a differentiator, especially where projects face stricter procurement screening or where end-users value cleaner formulations. Third, scale and distribution continue to matter, but they are increasingly complemented by software, service, and specification support capabilities. The market has not consolidated to the point where only a few players dominate, yet the advantages of combining product depth with control integration, material differentiation, and strong architectural relationships are becoming clearer. New entrants and investors are likely to be drawn to niches where performance claims can be substantiated, where integration with glazing or controls creates stickier project relationships, or where material innovation reduces long-term risk.
Forward-Looking Trends and Commercial Implications
Trend One: Shading as an Envelope-Level Performance Layer
Over the next three to five years, solar shading is likely to be treated less as an accessory and more as a functional layer within the building envelope. The commercial logic is straightforward: if shading can contribute to passive heat control, daylight quality, and ventilation performance, it becomes part of the architectural and engineering conversation rather than a late-stage fit-out decision. For manufacturers, this trend opens opportunities to engage earlier in the design process, align product specifications with energy modeling outcomes, and position solutions as part of integrated facade or glazing strategies. It also raises the stakes for product validation, because envelope-level claims invite closer scrutiny of performance, durability, and certification.
Trend Two: Cleaner Materials and Specification-Led Advantage
Material alignment with evolving expectations around chemical restrictions and environmental responsibility is likely to become a more visible competitive factor. Formulations and product families that are antimony-free and PFAS-free can lower friction in specification, procurement, and compliance review, especially in projects where material lists are tightly managed. This does not mean that every customer will prioritize material attributes equally, but it does suggest that cleaner profiles can serve as a differentiator in certain segments, support brand positioning, and reduce legal or reputational risk if regulations or buyer expectations tighten further. The commercial opportunity here is not simply in making a cleaner product, but in using that attribute to strengthen specification wins and reduce time spent managing compliance objections.
Trend Three: Automation, Controls, and Total Cost of Ownership Positioning
Automation and control integration will continue to gain importance, particularly in commercial and multi-family settings where operational efficiency and centralized management matter. Shading combined with lighting control, automated scheduling, and responsive daylight management can be framed around total cost of ownership rather than initial hardware cost. That framing creates room for premium positioning, recurring service relationships, and closer ties with building management ecosystems. It also creates execution risk: products that promise connectivity and automation must deliver reliability, user-friendly interfaces, and support structures that many traditional shading manufacturers have not historically emphasized. Firms that overpromise on smart features without the corresponding software and service capability may find their differentiation eroding quickly.
These trends carry uncertainty. Growth trajectories can be affected by construction cycles, interest rate environments, and the pace at which energy codes are adopted and enforced. Material transitions can introduce cost or supply challenges if alternative inputs are not scaled efficiently. Automation expansion can stall if interoperability issues, cybersecurity concerns, or integration complexity slow adoption. None of these risks negate the broader growth direction, but they do suggest that the market's next phase will reward companies that can combine credible performance claims with disciplined execution.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
- Prioritize envelope-level positioning where it fits your capability base. Products that can be articulated as part of facade, glazing, or ventilation performance are better placed to enter specification discussions earlier and command value beyond price comparison.
- Treat material and compliance readiness as strategic, not cosmetic. Where feasible, reduce reliance on substances that create future regulatory or procurement friction. Document performance and compliance claims in ways that support specification confidence and shorten approval cycles.
- Strengthen the integration bridge. If automation, controls, or facade coordination are part of your roadmap, invest as much in reliability, interoperability, and service as in feature announcements. Differentiation holds only when the operational experience matches the promise.
For Investors and Capital Allocators
- Look for durable differentiation rather than short-lived novelty. In a market growing at a steady but moderate pace, value creation increasingly depends on specification advantage, material positioning, and integration capability, not simply product introductions.
- Assess regional exposure carefully. Policy intensity, construction activity, and procurement norms vary, and the same product narrative may translate into strong demand in one market and limited pull in another. Diligence should map competitive positioning to where regulatory and demand signals are strongest.
- Watch for consolidation pressure around control, material, and architectural integration. Capital may flow toward companies that can connect shading to building performance outcomes in a credible, repeatable way, especially where those capabilities create stickier customer relationships.
For Procurement and Specification Teams
- Evaluate shading systems against total building performance, not just unit cost. Consider contributions to thermal comfort, daylight quality, ventilation, and operational savings, and ask for evidence that supports those claims in contexts similar to your project.
- Screen for compliance and service readiness early. Material profiles, certification status, and integration requirements can become decisive later in the project timeline if not addressed up front. Early diligence reduces rework and specification risk.
- Match product complexity to operational capacity. Highly automated or integrated systems can deliver meaningful benefits, but they also require appropriate maintenance, controls management, and support. Selecting a solution that your team can operate confidently is often more valuable than selecting the most feature-rich option.
The solar shading systems market is entering a period in which growth is supported by building performance expectations, regulatory attention, and evolving product architectures, but where differentiation will be earned through credible performance, cleaner material strategies, and integration capability. For companies and investors, the most valuable intelligence is the kind that connects macro growth signals to segment-specific behavior, competitive positioning, and specification dynamics. Detailed research that maps revenue splits, regional variations, application patterns, and company-level developments can sharpen those decisions significantly. For readers seeking a deeper, structured view of the market's segments, competitive moves, and scenario considerations, the full PW Consulting report provides a more granular foundation for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Solar Shading Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Locks Market: How 14.5% CAGR and Residential Demand Reshape 2026–2032
By pmarketresearch, 2026-09-21
The Smart Locks Market: Strategic Trends and Commercial Opportunities Through 2032
The smart locks market has evolved from a niche convenience upgrade into a structural component of the broader connected home and commercial security ecosystem. Valued at approximately 1.67 billion USD in 2025, the sector has demonstrated consistent expansion, growing from 850 million USD in 2020 at a compound annual rate of 14.5% through the forecast horizon extending to 2032. By the end of the projection period, revenue is expected to surpass 4.28 billion USD, signaling a market that has moved past early adoption friction and entered a phase defined by standardization, ecosystem integration, and security formalization. This trajectory is not merely a function of consumer curiosity; it reflects convergent pressures from residential security expectations, commercial access modernization, and the maturation of low-power wireless protocols that make keyless entry reliable enough for daily use.
For executives and investors evaluating the space, the headline growth rate only tells part of the story. The market is simultaneously consolidating around interoperable standards, fragmenting across application-specific requirements, and facing regulatory scrutiny that will reshape product roadmaps. Understanding where value is created—and where margin compression or compliance risk emerges—requires looking beyond total market size and examining the structural forces that will determine which players scale profitably and which get squeezed by commoditization or certification bottlenecks.
Market Snapshot: Scale, Growth, and Structural Composition
The revenue trajectory from 2020 through 2025 reflects a market that accelerated as wireless connectivity, battery efficiency, and mobile credentialing became routine expectations rather than differentiators. The jump from 1.44 billion USD in 2024 to 1.67 billion USD in 2025 indicates that smart locks are increasingly treated as baseline infrastructure in new residential construction and retrofitting programs, rather than optional premium add-ons. The forecast period through 2032 points to a market that will more than double in size, with growth accelerating in the outer years as mainstream replacement cycles and commercial retrofit programs compound.
Segmentation patterns reveal where demand is concentrated and where strategic positioning matters most. By product architecture, deadbolt-style smart locks command the largest revenue share, reflecting their dominance in residential door retrofitting and new-build specifications. Lever handle variants represent a meaningful secondary stream, particularly in commercial and multi-family contexts where ergonomic and fire-code considerations favor that form factor. Padlocks and other specialized formats occupy a smaller but strategically distinct niche, often serving temporary access, asset protection, and outdoor use cases where standalone battery operation and offline credentialing are critical. By application, residential deployments account for the majority of revenue, yet commercial adoption is expanding at a notable pace as property managers, co-working operators, and enterprise facilities teams seek centralized access control without full wiring overhauls. Geographically, North America remains the largest revenue contributor, supported by high smart-home penetration, renovation activity, and a strong DIY installation culture. Europe follows as a substantial market shaped by regulatory-driven security certification and multi-family housing modernization. Asia Pacific represents a rapidly expanding region where urbanization, rising disposable income, and domestic manufacturing scale are reshaping supply dynamics. Latin America and the Middle East & Africa together form an earlier-stage but strategically relevant footprint, often characterized by pilot deployments, security-conscious premium segments, and gradual normalization of connected access as total cost of ownership improves.
Market concentration remains moderate, with the top three players accounting for roughly 45% of revenue and the top five reaching just over half. This level of concentration indicates a market that is neither dominated by a single hegemonic player nor completely fragmented. It is a field where incumbents with strong distribution, brand trust, and ecosystem alignment hold meaningful advantages, while agile entrants can still win in defined sub-segments by solving a specific user experience, design, or certification challenge. The presence of both retrofit specialists and full-lock manufacturers, alongside regional hardware brands expanding into connected access, suggests that competition will increasingly hinge on interoperability, installation friction, and the ability to meet unified physical-and-cyber security expectations.
Core Challenges and Inflection Points
Despite favorable growth fundamentals, the market is passing through several structural tension points that will separate durable strategies from reactive product launches.
The first challenge is the transition from standalone convenience to certified security. For years, smart locks were marketed primarily around ease of access, temporary credentialing, and app-based control. That value proposition is no longer sufficient as buyers, regulators, and installer networks increasingly expect evidence that a connected lock can withstand both physical attack vectors and digital compromise. Products that treat cybersecurity as an afterthought face growing friction in premium residential specifications and commercial procurement, where risk teams and insurance considerations are becoming more influential. The market is therefore moving toward a phase where trust is a purchasable attribute, not a marketing claim.
The second challenge is ecosystem fragmentation slowly giving way to interoperability pressure. Early smart lock adoption was constrained by questions about whether a lock would reliably communicate with a given hub, voice assistant, or mobile platform. The broader rollout of standards-aligned connectivity has reduced some of that uncertainty, but it has also raised the bar for product design. Manufacturers that built closed or partially closed ecosystems must now reconcile backward compatibility, credential portability, and long-term software support. This creates an execution challenge: interoperability expands the addressable user base, but it also exposes a product to broader integration testing, firmware lifecycle obligations, and competitive exposure once the lock becomes interchangeable with alternatives in the same ecosystem.
The third challenge lies in supply chain exposure for the semiconductor and radio components that underpin connectivity, biometric sensing, and secure credential storage. As smart locks become more feature-rich, they depend on a broader set of modules that are susceptible to concentration risk, lead-time variability, and cost swings. This matters because margin structures in consumer hardware are already sensitive to component volatility, and because security-oriented authentication hardware can create supply dependencies that are harder to reroute than commodity parts. Companies that treat component strategy as a procurement detail rather than a product architecture decision may find themselves exposed to both cost shocks and launch timing risk.
These challenges converge into a broader inflection point: the market is shifting from a phase where feature novelty drives purchases to one where reliability, certification, and integration depth determine repeat adoption and referral. That shift rewards organizations that can align product design, compliance planning, and ecosystem relationships early, while penalizing those that continue to compete primarily on price or isolated feature claims.
Key Demand Drivers Reshaping the Market
The growth trajectory is not accidental. It is being propelled by a set of reinforcing drivers that are changing both what buyers expect and what manufacturers must deliver.
Technological innovation remains the most visible driver, particularly in the areas of low-power wireless connectivity, credential diversity, and hands-free access. The move toward standards-aligned protocols has reduced friction for users who want a lock to function as part of a broader home or facility environment rather than as a standalone gadget. At the same time, biometric modalities and sensor fusion are expanding the definition of convenience and security at the door. Fingerprint recognition has become a familiar baseline, but newer deployments are exploring palm-vein and other liveness-aware modalities that can reduce false acceptance and improve usability in wet, cold, or high-traffic conditions. The commercial implications are significant: biometrics can lower reliance on shared credentials, improve auditability, and support access experiences that feel less like a trade-off between security and convenience. In parallel, ultra-wideband technology is gaining attention for proximity-based, hands-free unlocking that can preserve security while simplifying daily use. When implemented carefully, UWB can support short-range, direction-aware access that avoids some of the spoofing risks associated with simpler proximity methods.
Policy and regulatory developments are becoming an equally important driver, especially because smart locks sit at the intersection of physical security and connected-device risk. Cybersecurity labeling and trust-mark initiatives for wireless smart-home products are pressuring manufacturers to provide clearer baseline assurances around device security, update practices, and vulnerability handling. In parallel, certification bodies are increasingly combining mechanical attack testing with IoT cybersecurity specifications, creating a more unified expectation for what counts as a credible residential smart lock. These frameworks matter commercially because they influence spec-in decisions, insurer and property-manager confidence, and the willingness of installation partners to recommend a product. Compliance is becoming part of the competitive moat: products that proactively align with recognized physical-and-digital standards can shorten sales cycles in cautious segments, while those that lag may face longer evaluation periods or exclusion from certain procurement channels.
Demand-side behavior is shifting as well. In residential settings, consumers are increasingly treating connected access as part of a broader home security and convenience bundle rather than an isolated purchase. This is visible in the way smart lock adoption is influenced by neighboring devices, mobile ecosystem preferences, and the desire for seamless credential sharing with family members, guests, and service providers. In commercial contexts, the driver is different but equally powerful: facility operators want access solutions that reduce rekeying costs, improve audit trails, and support flexible occupancy without major wiring projects. The result is growing interest in battery-powered connected locks, retrofit devices that attach to existing hardware, and access systems that can be managed remotely while preserving offline functionality for resilience. Across both sectors, the emphasis is moving toward total experience—installation effort, day-to-day reliability, battery life, and the quality of the companion app—rather than a narrow set of lock features.
Smart Door Lock Market
Supply chain and cost structures are also reshaping the market. The increasing reliance on advanced modules for connectivity and authentication means that component availability and regional semiconductor dynamics can influence product timing, pricing, and feature roadmaps. This dynamic favors manufacturers that design with flexibility, maintain a disciplined bill of materials, and plan for continuity across multiple sourcing scenarios. It also creates a distinguishing advantage for companies that can balance feature ambition with realistic component strategy. In a market where many products are functionally similar at the point of installation, the ability to deliver consistent availability, stable pricing, and predictable firmware support can become a meaningful commercial differentiator.
Recent product activity illustrates how these drivers are being translated into market-facing moves. One major player released a smart lock built around ultra-wideband technology with hands-free mobile credentialing and standards-aligned thread compatibility, signaling a focus on frictionless access within a specific mobile ecosystem. Around the same period, another manufacturer expanded its portfolio at a major consumer technology event, introducing models certified for both UWB and interoperability standards, which suggests a push to position connected locks as part of a broader smart-home fabric rather than as isolated hardware. Separately, a large consumer-tech brand updated its lock lineup with palm-vein recognition and automatic locking features, underscoring the continuing push toward biometric differentiation and hands-free reliability. These developments are not isolated product launches; they reflect a market that is testing multiple avenues at once—ecosystem alignment, biometric refinement, and installation simplicity—while racing to meet expectations set by regulatory and security normalization.
Competitive Landscape and Strategic Positioning
The competitive field is shaped by a mix of established lock manufacturers, smart-home specialists, retrofit-focused brands, and larger consumer-tech companies extending into access control. Rather than competing solely on lock mechanics, players are differentiating through installation model, ecosystem alignment, biometric design, and the balance between connectivity and offline resilience.
Aqara has positioned itself around interoperability and hands-free convenience, with product designs that emphasize thread-compatible connectivity and mobile credentialing integrated with major platform ecosystems. This approach targets users who want a lock that behaves as part of a coordinated smart-home environment, reducing friction for platform-driven households. August Home has historically leaned into retrofit compatibility and Wi-Fi-based keyless entry, an approach that lowers installation barriers for consumers who want to upgrade existing hardware without replacing the entire lock assembly. Yale and Schlage continue to draw strength from brand trust, broader access-control heritage, and touchscreen or keypad-oriented designs that appeal to buyers prioritizing familiarity, durability, and integration with broader residential and commercial security expectations. Kwikset adds another angle with re-keying technology combined with Wi-Fi and standards-aligned smart locks, appealing to users who value both connected convenience and the ability to manage mechanical key control.
Eufy has carved a distinct position by fusing video and access functions into the lock form factor, combining fingerprint or palm-vein sensing with camera integration. That hybrid approach serves buyers who want visual verification at the door without installing separate devices, though it also raises product complexity and privacy expectations. CANDY HOUSE and igloohome illustrate a different strategic axis: CANDY HOUSE has emphasized fast Bluetooth-based access and tool-free installation, targeting convenience and ease of adoption, while igloohome has focused on offline access control for locks and padlocks, an approach that suits scenarios where internet dependency is undesirable or unreliable. Nuki specializes in retrofit electronic lock conversion with app and fingerprint access, competing on the ability to add connectivity to existing doors without full hardware replacement. Level has pursued a design-forward, “invisible” smart lock concept that integrates into the door aesthetic and supports major platform credentialing, which can be attractive in premium residential and design-sensitive projects.
On the broader manufacturing side, Dreame Technology has used major trade platforms to expand a full smart lock lineup with standards-aligned interoperability and UWB support, indicating a push to compete across feature tiers rather than in a narrow niche. TCL has extended into multi-biometric and fingerprint-based lock series, reinforcing the industry-wide emphasis on authentication variety and automated locking features. Taken together, these players show a market where strategy is increasingly defined by the tension between ecosystem alignment, biometric differentiation, installation simplicity, and offline resilience.
The landscape is evolving along three overlapping directions. First, there is a consolidation tendency among brands that can leverage distribution scale, installer relationships, and platform partnerships to create repeatable go-to-market patterns. Second, there is continued fragmentation in specialized sub-segments where design, offline functionality, or hybrid video-access value propositions can sustain differentiation. Third, new entrants and larger consumer-electronics groups are using smart locks as an entry point into connected home security, which increases competitive intensity but also expands awareness and retail presence. The net effect is a market where winning does not depend on being the largest player in every category, but on choosing a defensible positioning and executing it with disciplined product planning, certification readiness, and ecosystem compatibility.
Forward Outlook: Three Trends Likely to Shape the Next 3–5 Years
The next several years are likely to be defined by a shift from feature competition to trust, integration, and lifecycle competitiveness. Three trends stand out.
First, cybersecurity and physical-security certification will become central commercial requirements rather than optional credentials. As labeling initiatives and unified testing specifications become more familiar to buyers and procurement teams, smart locks that can demonstrate credible security baselines will gain an advantage in both retail and specification channels. This trend will likely raise the entry barrier for low-effort products and reward manufacturers that invest early in secure update pathways, transparent vulnerability handling, and compliance documentation. Commercial opportunity here lies in positioning certification as a selling point for spec-in, insurance-aligned, and multi-family deployments, where risk reduction is part of the purchase rationale.
PW Consulting Health Care Research Center
Second, biometric and hands-free access will broaden, but with a stronger emphasis on reliability, privacy, and contextual appropriateness. Fingerprint and palm-vein methods will continue to expand, especially where they reduce dependence on shared keys or codes and improve auditability. Ultra-wideband and proximity-based access will grow in premium and convenience-oriented segments, but adoption will depend on real-world performance, battery trade-offs, and the ability to avoid false unlocks or usability friction. The commercial opportunity is not simply adding sensors; it is designing access experiences that feel secure without becoming cumbersome, and that can be supported over the product lifecycle with firmware resilience and user-friendly recovery paths.
Third, smart locks will increasingly be evaluated as part of ecosystem and lifecycle economics rather than as isolated hardware purchases. Buyers will weigh platform compatibility, app quality, battery management, installer experience, and long-term software support alongside the lock itself. This creates opportunities for companies that can package hardware with dependable software, clear credential management, and integration support for property managers or platform-driven households. It also introduces risk for products that rely on short-term feature novelty without a credible plan for ongoing updates, compatibility maintenance, or serviceability. In this environment, sustained advantage will come from reducing total friction across purchase, installation, daily use, and long-term management.
Potential risks and uncertainties remain. Regulatory expectations may evolve faster than product roadmaps in some regions, especially where physical and digital certification requirements are harmonized through new specifications or national guidance. Component availability and semiconductor concentration could affect cost stability and launch timing for feature-rich models. Ecosystem dependence may create upside in the short term but can also expose manufacturers to platform policy shifts or competitive substitution if interoperability becomes widespread. Finally, consumer expectations around privacy, data handling, and app transparency will continue to rise, meaning that even technically capable products can lose traction if trust and transparency are not managed carefully.
Strategic Actions for Decision Makers
For manufacturers, the priority is to align product roadmaps with the emerging trust-and-interoperability baseline. That means designing for security documentation, update discipline, and cross-platform compatibility as first-class requirements rather than post-launch additions. It also means choosing biometric and hands-free features based on real usability and reliability rather than novelty, and building supply chain flexibility around connectivity and authentication components. Companies that can combine a clear installation advantage with credible certification readiness and consistent lifecycle support will be better positioned to win in both retail and specification-driven channels.
For investors, the opportunity is to distinguish between companies that are scaling through genuine ecosystem, distribution, and compliance advantages and those that are relying on short-term feature launches or price competition. Due diligence should weigh certification positioning, platform relationships, component strategy, and the durability of the installation model. Businesses that can demonstrate repeatable procurement in residential retrofitting, multi-family, or commercial access modernization—and that can manage security expectations without eroding margin—offer more resilient exposure than those whose growth depends primarily on promotional momentum.
Bike Locks Market
For procurement leaders and property operators, the practical move is to evaluate smart locks as part of an access strategy rather than as discrete hardware purchases. Criteria should include not only locking performance and credential options, but also installation complexity, offline resilience, app management, audit capabilities, and the depth of support for future platform or certification changes. In commercial and multi-family settings, centralized management, fallback behavior, and installer familiarity can matter as much as the marketed feature set. Selecting products that are already aligned with recognized security and interoperability expectations can reduce downstream evaluation risk and simplify future upgrades.
As the market expands toward the 4 billion USD range over the forecast period, the volume of opportunity will increasingly separate from the ease of capturing it. The companies and buyers that benefit most will be those who treat smart locks as a long-term access layer—shaped by security expectations, ecosystem realities, and lifecycle economics—rather than as a one-time convenience purchase. For organizations seeking segmented forecasts, competitive benchmarking, and tailored strategic pathways across product type, application, and region, the full research report provides the deeper data set and scenario detail needed to translate these trends into concrete plans.
For detailed analysis of this topic, please visit the official page: Smart Locks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Power Tool Accessories Market
Market Overview and Structural Challenges
Market Trajectory and Core Dynamics
The power tool accessories market has demonstrated consistent expansion over the past five years, transitioning from a mature, replacement-driven segment to a growth market influenced by tool electrification, application specialization, and tightened performance expectations. Total market revenue rose from approximately 161.5 million USD in 2020 to roughly 202.5 million USD in 2025, and forward projections indicate a continued upward path toward just under 300 million USD by 2032, reflecting a compound annual growth rate of 5.8 percent across the forecast window. This trajectory signals a market that is no longer solely dependent on consumables replacement cycles. Instead, the growth is increasingly shaped by accessory innovation, platform compatibility requirements, and the expansion of professional and semi-professional user bases that prioritize durability, precision, and productivity gains.
The segment has also developed clear concentration patterns that influence pricing power, innovation pacing, and channel relationships. A relatively small group of leading players commands a disproportionate share of revenue, which creates both stability and pressure for the remainder of the competitive field. High concentration tends to reward companies with strong brand equity, broad accessory portfolios, and reliable distribution networks, while making it harder for narrower players to compete on visibility alone. For decision-makers, this concentration means that strategic differentiation must come from features, materials, compatibility ecosystems, or service models rather than simple market entry.
Key Challenges and Inflection Points
Despite the favorable growth outlook, the industry faces several structural challenges that are reshaping how manufacturers and buyers think about accessories. One of the most pressing issues is the balance between performance and cost pressures. Accessory buyers increasingly expect longer service life, better cutting efficiency, and reduced tool vibration, yet raw material volatility and processing complexity can make premium formulations difficult to scale profitably. Companies that rely on traditional materials or legacy geometries are seeing margin compression as users become more selective and price-sensitive, particularly in price-conscious channels. This creates a tension where performance upgrades must be justified through measurable productivity improvements rather than incremental claims.
A second challenge is the growing complexity of compatibility and platform lock-in. As cordless tool platforms continue to expand, accessory design must account for torque profiles, battery ecosystems, shank specifications, and interface variations. Accessories that are not optimized for the tool’s operating conditions can reduce performance or create safety concerns. This complexity benefits large platforms with broad accessory ranges, but it also raises the stakes for smaller manufacturers that need to ensure fit, performance, and reliability across multiple tool models. The result is a market where technical coordination between tools and accessories is becoming as important as the accessory product itself.
A third inflection point is regulatory and safety standardization. Industry associations and certification bodies have been tightening expectations around performance consistency, durability, and safe usage under demanding conditions. These developments help protect end users and strengthen confidence in professional-grade accessories, but they also raise compliance costs and can slow time-to-market for new designs. Manufacturers that treat safety and certification as a strategic capability rather than a back-office requirement are better positioned to operate in regulated channels, especially where institutional buyers, rental fleets, or industrial customers require documented performance assurance.
Taken together, these challenges suggest that the market is entering a phase where growth will be earned through technical relevance and trust. The companies that can align material efficiency, platform compatibility, and compliance readiness with user-facing performance benefits are likely to capture a larger share of the expanding market, while those that compete only on generic specifications may face margin erosion and substitution pressure.
Core Drivers Shaping Market Change
Technology Innovation and Material Advancement
Material engineering and design optimization remain central to competitive advantage in power tool accessories. Improvements in carbide formulations, hardened steel treatments, coatings, and tooth geometry are enabling accessories to cut faster, last longer, and maintain accuracy over more operations. In practical terms, these gains matter because they reduce downtime, lower the frequency of replacement, and improve finishing quality. For professional users, that translates into measurable productivity rather than just product attributes. Innovation is also moving beyond raw hardness toward application-specific performance, with designs tailored to particular materials, cut styles, drilling conditions, or tool interfaces.
A notable example of how material strategy is evolving comes from the broader industry’s focus on cost and sustainability. One leading manufacturer has pursued recycling of hard metal tips recovered from grinding waste in order to lower raw material costs for accessories, illustrating how material recovery can support both economics and supply continuity. This approach highlights a broader trend: high-performance accessories are increasingly dependent on managing input costs and material availability as carefully as they are dependent on design quality. Companies that integrate material recovery, waste reduction, or alternative sourcing into their development processes may be able to sustain premium positioning while protecting margins.
Power Tools Market
Policy, Safety, and Certification Environment
Regulatory and industry-led standards are becoming a more visible force in the accessories market. Updated safety guidelines for power tool accessories have been issued by industry bodies, reinforcing expectations around consistency, safe operation, and performance validation. Alongside this, certification and testing organizations continue to evaluate accessories for safety, durability, and reliability, and trade associations are maintaining member compliance expectations for manufacturers. This framework is not simply procedural. In professional and institutional procurement, documented compliance can be a prerequisite for inclusion in bids, rental fleets, or job-site supply programs.
For companies, the implication is that standards are increasingly part of the value proposition. Accessory designs that are developed with clear testing pathways and compliance documentation can gain advantage in channels where risk management and accountability are prioritized. Conversely, products that are launched without adequate attention to certification or performance validation may face slower adoption in professional environments. The trend also rewards manufacturers who can communicate standardized performance clearly, because procurement teams and field supervisors often need evidence that an accessory meets the demands of heavy or repetitive use.
Demand-Side Shifts in User Behavior
The demand profile for power tool accessories is being reshaped by the continued shift toward cordless tool platforms and the expansion of user groups beyond traditional trades. Cordless adoption has broadened access to mobile, on-site work and has increased the importance of accessories that perform reliably under variable conditions. At the same time, users are becoming more discerning about fit and productivity. Drill-related applications remain especially significant in the broader usage landscape, reflecting the foundational role of drilling in construction, assembly, maintenance, and renovation activity. Miter saw applications and reciprocating saw setups also represent meaningful demand centers, and the accessory requirements in these applications often emphasize precision, controlled cutting, and blade life.
Another demand-side shift is the growing expectation that accessories support efficiency rather than merely perform a function. Users want accessories that help reduce rework, improve consistency, and minimize interruption. This is particularly relevant where time pressure, labor costs, and project schedules are high. As a result, marketing and product development are increasingly judged by real-world outcomes such as cleaner cuts, longer intervals between changes, less tool load, and easier blade or bit changes. Buyers are also more attentive to whether accessories are designed for specific tool platforms, since mismatched accessories can lead to reduced performance or premature wear.
Supply Chain and Cost Structure Pressures
Cost structures in the accessories market are being influenced by raw material availability, manufacturing complexity, and the need to scale performance improvements without sacrificing margin. The emphasis on hard metals, specialized steel, and engineered coatings means that supply disruptions or price swings can affect both cost and product consistency. In response, some companies are focusing on process efficiency, material recovery, and portfolio rationalization to keep production economically viable while preserving performance. This is not just a short-term cost issue; it is becoming an important strategic capability.
Supply chain stability also affects innovation speed. Companies that can develop, test, and launch accessory products efficiently are better positioned to respond to changing application needs and platform expansions. The most effective players tend to balance a core range of high-volume accessories with targeted specialty products that serve higher-value applications. That combination helps smooth demand cycles while still capturing premium segments where users are willing to pay for reliability and performance. For market participants, the operational goal is to link material strategy, manufacturing scale, and product differentiation in a way that supports both volume and value.
Competitive Landscape and Leading Strategies
Strategic Positioning of Major Players
The market is shaped by a group of well-established manufacturers that compete through brand strength, product breadth, platform integration, and professional-grade positioning. Bosch Power Tools offers a broad range of cordless and corded tools and accessories, including drill bits, hole saws, saw blades, and fasteners aimed at professional trades. Its scale and platform reach give it the ability to align accessories closely with tool ecosystems and to introduce new products in coordinated waves. In June 2026, the company expanded its North American offering with 39 new tools and accessories designed to extend its 18V cordless platform, an example of how accessory portfolios can be used to reinforce a tool system strategy and deepen user commitment.
Stanley Black & Decker competes through its tools portfolio, offering accessories such as drill bits, saw blades, and impact driver bits under established brands. Its strength lies in a wide consumer and professional presence, which supports visibility across multiple channels and price points. Makita Corporation has built a strong identity around cordless power tools with dedicated accessories, including drill bits, hole saws, and abrasive products. This focus on system coherence helps the company emphasize compatibility and reliability in cordless workflows. Techtronic Industries, through its branded portfolio, supplies accessories for professional and consumer segments, with offerings spanning drill bits, saw blades, and hole saws. Its multi-brand structure allows it to address different customer segments while leveraging shared development and supply capabilities.
Hilti Corporation remains strongly associated with professional-grade accessories for fasteners, drilling, and demolition applications. Its positioning is particularly relevant in demanding job-site environments where performance, support, and reliability are critical purchase criteria. Apex Tool Group and Snap-on Incorporated both maintain strong professional orientation, with Snap-on especially focused on industrial and automotive applications through bits and sockets. These companies illustrate how professional trust, application specificity, and service support can be just as important as product specifications.
PW Consulting Health Care Research Center
A different competitive angle is visible in companies that emphasize reusable or recyclable accessory design. EAB Tool Company, for example, produces exchangeable and recyclable accessories such as circular saw blades, oscillating tool accessories, hole saws, and drill bits. This approach appeals to users and organizations seeking to reduce waste and manage consumable costs over time. Lenox, Diablo Tools, and related suppliers similarly focus on high-performance cutting and drilling accessories, often with an emphasis on carbide-tipped construction and application-specific performance. Together, these players show that differentiation is increasingly built around material performance, application fit, and lifecycle economics rather than brand alone.
Market Evolution and Consolidation Dynamics
The competitive structure is evolving along a path that rewards scale, portfolio breadth, and technical integration, while also creating room for specialized entrants that solve a narrow problem exceptionally well. Large players benefit from the ability to invest in multiple accessory categories, align products with tool platforms, and supply both professional and broader user markets. Their advantage is not simply size; it is the capacity to offer a coordinated accessory ecosystem that reduces compatibility risk for buyers and supports repeat purchasing across tool lines.
At the same time, market concentration tends to encourage strategic consolidation and selective partnership activity. Smaller manufacturers may find growth easier by focusing on high-performance niches, unique materials, or application-specific designs rather than trying to match full-portfolio breadth. New entrants that can bring a compelling technical advantage, stronger sustainability characteristics, or better cost-quality balance may gain traction in specific channels, especially where existing offerings are perceived as incremental. However, entering the market successfully increasingly requires serious attention to compliance, testing, and platform compatibility, since these are now central to professional adoption.
A broader trend is the growing importance of brand trust in safety-critical and high-use environments. In rental, industrial, and trade contexts, buyers often prefer accessories from manufacturers with established reputations for consistency and support. This does not eliminate competition, but it does raise the threshold for credible market participation. Companies that can demonstrate dependable performance, clear documentation, and alignment with recognized standards are better positioned to secure durable demand, while those that compete primarily on short-term price may find it harder to build recurring relationships in professional channels.
Future Outlook: Trends to Watch Over the Next 3 to 5 Years
Trend 1: Platform-Integrated Accessories as a Standard Expectation
Over the next several years, accessories will be increasingly judged on their fit within cordless and corded tool ecosystems rather than on isolated specifications. Users and procurement teams are likely to favor accessories that are designed for specific torque ranges, battery platforms, and tool interfaces, because those designs tend to deliver more consistent performance and longer service life. This will reinforce the strategic value of platform-aligned product development and create stronger incentives for manufacturers to coordinate accessory launches with tool updates. The commercial opportunity lies in building accessory lines that function as part of a complete workflow solution, improving user retention and reducing the risk of substitution by mismatched alternatives.
Worldwide Cutting Tool and Machine Tool Accessory Market
Trend 2: Performance with Lower Waste and Lower Input Exposure
Material efficiency will become a more visible competitive attribute. As raw material cost exposure and sustainability expectations rise, manufacturers that can improve performance while reducing material waste or dependency on scarce inputs will have an advantage. This includes better geometry design, more efficient manufacturing processes, and approaches that recover or reuse valuable processing materials. In practical terms, this trend creates opportunities for products that combine durability with a smaller lifecycle footprint, particularly where users are sensitive to replacement frequency and total cost of ownership. Companies that treat material strategy as a core design priority rather than a sourcing detail will be better positioned to maintain margins while meeting evolving buyer expectations.
Trend 3: Compliance and Documentation as Purchase Criteria
Safety standards, certification processes, and industry-led compliance expectations are likely to remain a meaningful influence on purchasing, especially in professional, institutional, and rental channels. As these requirements become more familiar to buyers, documented performance and safety validation may move from being a baseline requirement to a differentiator. Products that can clearly demonstrate consistent performance under testing regimes and meet recognized standards will have an easier path into demanding applications. The risk for manufacturers is that compliance becomes a late-stage checkpoint rather than a design input, delaying launches and limiting channel access. The opportunity is to make standards alignment part of the product architecture, so that compliance strengthens credibility instead of simply adding cost.
Strategic Actions for Decision-Makers
For Manufacturers
Manufacturers should prioritize accessories that solve specific workflow problems rather than adding generic SKUs. That means focusing development on durability, application fit, platform compatibility, and user convenience in high-frequency tasks. Brands with strong professional credibility should consider expanding their accessory ecosystem in lockstep with tool platform updates, since coordinated launches can reinforce system loyalty and increase attachment rates. At the same time, companies should evaluate material sourcing and recovery strategies as part of long-term cost planning, particularly for hard-metal-dependent products where input exposure can affect both price and availability.
- Invest in application-specific designs that improve measurable outcomes such as cut quality, run time, and replacement intervals.
- Align accessory development with tool platform roadmaps to reduce compatibility risk and strengthen ecosystem value.
- Build compliance, testing, and documentation into product development to support professional and institutional demand.
- Explore material efficiency measures that protect cost structure without compromising performance.
For Investors
Investors evaluating this market should pay close attention to companies that combine portfolio breadth with technical differentiation and credible compliance capabilities. The most durable revenue models in this space tend to come from brands that can stay relevant across professional and broader user segments while maintaining consistent accessory demand through tool platform loyalty. Watch for signs that a company can manage cost exposure, improve product performance in a way users notice, and expand into higher-value applications without diluting brand positioning. Also monitor the extent to which a company can maintain product launch cadence and channel access, since these factors strongly influence market share over time.
- Assess whether a company’s accessory portfolio is aligned with high-usage applications and platform-driven demand.
- Look for evidence of margin discipline through material strategy, manufacturing efficiency, or portfolio focus.
- Consider whether the company has the credibility and compliance readiness to compete in professional channels.
- Track launch consistency and ecosystem coordination as indicators of future share resilience.
For Procurement and Channel Leaders
Procurement teams and channel operators should evaluate accessories not only by unit price but by total cost of ownership, compatibility, and the availability of documented performance assurance. In higher-use environments, the cost of downtime, rework, and premature replacement can outweigh small price differences between products. It is also wise to standardize around accessories that match the tool platforms in use, because mismatched products can create hidden performance and reliability costs. Where safety and compliance matter, prioritize suppliers that can provide clear testing and standards alignment, since this reduces operational risk in demanding job-site or industrial settings.
- Evaluate accessories based on service life, application fit, and workflow impact rather than sticker price alone.
- Standardize around accessories designed for the tool platforms in active use.
- Prioritize suppliers with demonstrated compliance and performance documentation in professional contexts.
- Track field performance and replacement cycles to identify where premium accessories deliver real savings.
Closing Perspective
The power tool accessories market is expanding within a structure that increasingly rewards technical relevance, compatibility, and trust. Growth to the end of the decade and beyond is supported by broader tool adoption, ongoing material and design improvements, and continued demand from professional and semi-professional users who value productivity and reliability. At the same time, the market is becoming more demanding in terms of platform fit, compliance readiness, and cost management. That combination creates opportunities for companies that can integrate performance, economics, and standards into a coherent strategy, while exposing those that rely on undifferentiated product lines or short-term pricing tactics.
For organizations making decisions in this space, the most useful next step is to connect broad market direction with detailed asset-level insight: which applications, accessory types, channels, and regional dynamics are shaping demand in a specific business context. Deeper segmentation data, company-level scenario analysis, and tailored strategy recommendations can help turn these market-level trends into precise action plans. Readers seeking that level of detail can explore the full PW Consulting research report for comprehensive segmentation, competitive benchmarking, and forward-looking guidance tailored to specific strategic objectives.
For detailed analysis of this topic, please visit the official page: Power Tool Accessories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Coconut Milk Powder Market: Why 9.94% CAGR Redefines Global Growth by 2032
By pmarketresearch, 2026-09-21
Coconut Milk Powder Market: Strategic Trends and Commercial Opportunities Through 2032
The coconut milk powder market has entered a phase of accelerated, structural growth. Over the historical period from 2020 to 2025, the market expanded from approximately USD 1.0 billion to USD 1.597 billion, reflecting a compound annual growth rate that signals durable demand rather than a temporary spike. During the forecast window from 2026 to 2032, the trajectory continues upward, with projected revenue reaching roughly USD 3.077 billion by the end of the period and a five-year CAGR of 9.94%. These figures place coconut milk powder among the more compelling ingredient categories in the broader plant-based and alternative dairy landscape. The growth is not evenly distributed across regions or applications, but the aggregate momentum is clear: manufacturers, investors, and procurement teams are facing a market that is scaling faster than legacy dairy substitutes in several consumer segments.
Behind the headline numbers lies a market that is still maturing in terms of supply discipline, quality standardization, and regulatory alignment. The concentration metrics underscore this reality: the top three players account for 44.5% of market revenue, while the top five hold 59.0%. This level of concentration indicates a competitive field where scale advantages matter, yet substantial room remains for regional specialists, niche organic suppliers, and vertically integrated processors to capture value. The market is large enough to support diversified strategies but fragmented enough that positioning, technology, and supply chain resilience now determine who wins margin rather than who simply participates.
1. Market Landscape and Core Challenges
A Market Growing on Two Parallel Tracks
The overall expansion reflects a dual dynamic. On one side, full-fat coconut milk powder continues to anchor demand in applications that prioritize richness, mouthfeel, and traditional flavor profiles. On the other, low-fat variants are gaining traction where formulation flexibility, calorie management, and downstream processing compatibility matter more than absolute fat content. The two segments are approaching comparable scale, which tells a story of diversification rather than reliance on a single product architecture. Beverage formulators, bakery developers, and savory sauce manufacturers are selectively choosing between these variants based on functional requirements, not just cost.
Geographically, Asia Pacific carries the largest absolute share of revenue, consistent with the region's production base, domestic consumption habits, and growing export-oriented processing capacity. Europe and North America follow as significant demand centers, driven by premiumization, clean-label expectations, and the ongoing shift toward plant-based alternatives in food service and retail. Latin America and the Middle East/Africa regions contribute meaningful volume, though from smaller bases, and their growth paths are increasingly influenced by cross-border supply arrangements and food safety compliance rather than domestic consumption alone.
Cheese Powder Market
Three Challenges Defining the Market's Next Chapter
First, raw material cost volatility is no longer a cyclical nuisance; it is a structural factor shaping pricing, contracts, and margin planning. Coconut feedstock prices have shown sensitivity to weather patterns, crop cycles, and regional supply tightness. In early 2026, coconut milk powder pricing rose by 3–4% as underlying coconut material costs increased, and earlier data points to ongoing volatility affecting production economics for processors. For manufacturers, this translates into the need for stronger hedging, forward contracting, and formulation strategies that can absorb input swings without eroding competitiveness. For buyers, it means shorter-term price stability can no longer be assumed, and dual-sourcing or specification flexibility may become part of routine procurement design.
Second, regulatory and labeling requirements are intensifying in the most profitable end markets. Food safety authorities in Europe and North America have reinforced labeling rules for powdered foods, including coconut milk powder, with clearer expectations around ingredient declarations, allergen handling, and packaging information. At the same time, government push toward sustainable packaging and plastic reduction is reshaping packaging roadmaps across food categories. Import requirements add another layer of complexity, with phytosanitary certificates and market-specific entry conditions becoming standard for coconut milk powder shipments. The practical effect is a rising compliance bar that rewards companies with disciplined documentation, traceable supply chains, and packaging strategies already aligned with destination-market expectations.
Third, the market is reaching an inflection point where consistency and functionality increasingly separate premium suppliers from commoditized participants. Spray-drying efficiency, particle uniformity, reconstitution behavior, and flavor stability are becoming differentiators rather than table stakes. As applications expand into beverages, bakery, confectionery, soups, sauces, and other formats, the ingredient must perform reliably across different processing environments. Companies that can deliver consistent technical performance while managing cost and compliance are better positioned to move up the value chain, whereas suppliers competing primarily on price face increasing pressure as specifications tighten and audits become more frequent.
2. Key Drivers Shaping Market Trajectory
Technology and Processing Innovation
Processing technology is a primary enabler of the market's next wave of growth. Advanced spray-drying and integrated processing investments are improving powder consistency, yield, and functional reliability. In April 2026, Thai Coconut Public Company Limited increased investment in advanced spray-drying and processing technologies aimed at improving coconut milk powder efficiency and consistency, a move that reflects a broader industry focus on turning production capability into a strategic advantage. Around the same time, Axelum Resources Corp. expanded integrated coconut processing capabilities with strengthened value-added ingredient production for export-focused coconut milk powder manufacturing. These developments matter because they do not simply increase capacity; they improve the economics of premium-grade output and reduce variability across batches, which is critical for industrial buyers who depend on repeatable formulation performance.
For the broader market, the technological trajectory points toward more tightly controlled particle characteristics, improved solubility profiles, and greater ability to tailor fat content without sacrificing sensory qualities. These improvements widen the range of applications where coconut milk powder can substitute or complement other ingredients, especially in plant-based dairy alternatives, ready-to-drink beverages, and formulated foods that require stable powders with predictable behavior during storage and reconstitution.
Consumer Demand and Corporate Procurement Behavior
Demand-side change is being driven by the continued expansion of plant-based eating, but also by more specific shifts in how food manufacturers and food service operators select ingredients. Coconut milk powder benefits from its positioning as a recognizable, consumer-friendly plant-based ingredient with a strong flavor association and broad acceptability. At the same time, corporate buyers are increasingly balancing functionality with clean-label expectations, sourcing transparency, and sustainability credentials. This creates a layered demand environment: one layer is volume-driven and price-sensitive, while another layer rewards suppliers who can document origin, processing standards, and packaging responsibility.
Worldwide Coconut Oil Fat Powder Market
The application spread reinforces this dynamic. Beverages remain a major demand node, but bakery, confectionery, soups, sauces, and other categories are not merely secondary users; they represent formulation problems that coconut milk powder can solve when the right fat level, solubility, and flavor profile are available. Suppliers that understand application-specific requirements are better able to move beyond commodity positioning and into partnership-based selling, where technical support and customization become part of the value proposition.
Supply Chain Realignment and Cost Structure Pressures
The supply chain for coconut milk powder is being reshaped by a combination of input volatility, export documentation requirements, and the search for more predictable sourcing. Raw coconut material price volatility has repeatedly affected production costs, which pushes manufacturers to strengthen relationships with growers, consider regional diversification, and improve inventory planning. Import requirements, including phytosanitary certificates and market-specific food import rules, add time and cost to cross-border transactions, especially for suppliers serving regulated markets in Europe and North America.
This environment favors companies with integrated operations, where control over processing reduces exposure to intermediaries and improves quality oversight. It also favors exporters who invest early in compliance readiness and documentation fluency, because these capabilities lower friction at border points and shorten time to market. For buyers, the practical takeaway is that supply resilience is increasingly a procurement criterion alongside price and quality, especially for manufacturers who cannot afford production interruptions or specification failures.
PW Consulting Health Care Research Center
Regulatory and Sustainability Pressures as Market Filters
Regulatory and sustainability expectations are increasingly acting as market filters rather than mere compliance tasks. Labeling mandates for powdered foods, sustainable packaging guidance, and plastic reduction targets are reshaping product design decisions. These requirements are not uniform across regions, which means that suppliers serving multiple markets must manage a patchwork of rules, but they also create advantages for companies that have already modernized packaging formats, documentation systems, and labeling processes. In effect, the regulatory environment is raising the cost of entry for poorly organized players while rewarding those with established quality and compliance infrastructure.
This dynamic is particularly relevant for premium and organic segments, where buyers expect both ingredient integrity and responsible packaging. Companies that can align product claims with verifiable practices are more likely to secure long-term contracts with brands that face their own consumer and retailer scrutiny.
3. Competitive Landscape and Leading Strategies
Differentiation Through Integration, Technology, and Positioning
The competitive set reflects a range of strategic models. Axelum Resources Corp. operates as a fully integrated manufacturer and exporter of premium coconut products, including coconut milk powder for global food and beverage brands, with a focus on export-oriented value-added production. Thai Coconut Public Company Limited stands out as a leading manufacturer with advanced spray-drying technology, an asset that supports consistency and scale in coconut milk and coconut milk powder production. Red V Foods serves North American food manufacturers, food service, and private label customers with premium coconut products, positioning itself within a mature demand center where specification and service reliability often matter as much as price.
Bata Food operates as an international supplier of organic and conventional coconut milk powder with offices in the Netherlands and the USA, a footprint that supports access to regulated Western markets and suggests a strategy built on trade connectivity and product range breadth. In the plant-based and dairy-alternative segment, Royal Grove Foods has launched plant-based coconut milk ranges for food manufacturing and home use, signaling movement toward end-use positioning rather than ingredient-only distribution. Jaindi Export Pvt. Ltd. and Omilco Exports represent Sri Lankan exporters with organic and premium organic coconut solutions respectively, both active in international food exhibitions and oriented toward export channels. Coco Factory Pvt. Ltd. emphasizes vegan coconut milk powder crafted from real coconut milk for plant-based dairy alternatives, an explicit product Narrative that aligns with consumer-facing positioning.
These profiles illustrate a market where leadership is being built through different paths: vertical integration, technology investment, organic certification, application-specific product narratives, and trade-network access. Few players are competing on a single dimension; instead, the stronger positions combine processing capability, market access, and a clear value proposition tied to either premium quality, organic integrity, or application performance.
Recent Moves That Signal Strategic Direction
The most recent industry activity reinforces the emphasis on capability, visibility, and market access. In April 2026, Axelum Resources Corp. expanded integrated coconut processing capabilities with strengthened value-added ingredient production for export-focused coconut milk powder manufacturing. Thai Coconut Public Company Limited increased investments in advanced spray-drying and processing technologies for improved efficiency and consistency. In May 2026, Omilco Exports appeared as a first-time exhibitor at Fine Food Australia, showcasing premium organic coconut milk powder, cream, and related products. Jaindi Export Pvt. Ltd. exhibited organic coconut milk powder at Gulfood 2026. These actions collectively indicate that companies are pursuing growth through both operational upgrades and direct market engagement, using trade platforms to reach buyers in high-value regions and using technology and integration to defend margin and quality.
How the Competitive Structure Is Evolving
The market is likely to continue evolving along three lines. Integration will deepen where scale and cost control matter most, especially among exporters serving regulated markets that demand consistency and documentation. Differentiation will intensify among organic, premium, and application-focused players who can justify higher price points through verified quality, technical support, and packaging compliance. At the same time, new entrants and regional specialists can still find openings if they focus on underserved applications, specific geographic routes, or certified organic supply that larger players do not fully address. The moderate concentration in the market means consolidation is possible over time, but it is not yet a foregone conclusion; the more immediate trend is a widening gap between suppliers with integrated, technology-enabled operations and those competing primarily on loose specifications and price.
4. Outlook: Three Trends Shaping the Next Three to Five Years
Premiumization and Functional Tailoring Will Drive Higher-Value Volume
As the market expands from roughly USD 1.7 billion in 2026 toward more than USD 3.0 billion by 2032, volume growth alone will not explain the gain. A meaningful portion of future growth will come from higher-value usage where coconut milk powder is selected for specific sensory and functional outcomes. Formulators will continue to differentiate between full-fat and low-fat options based on application needs, and suppliers that offer tailored specifications, reliable reconstitution, and stable flavor will capture more of the margin pool. This trend favors manufacturers that can support buyers with technical expertise and consistent batches, and it raises the stakes for commoditized suppliers whose products are easiest to replace.
Compliance and Packaging as Competitive Advantage
Over the next few years, regulatory expectations around labeling, food safety, and sustainable packaging are likely to become more embedded in procurement decisions rather than treated as separate compliance workstreams. Suppliers that align product design with destination-market rules and demonstrate credible packaging roadmaps will gain an edge in Europe, North America, and other regulated channels. Conversely, companies that lag on documentation, traceability, or packaging transition may find themselves constrained to less demanding channels, where price competition is more intense and brand visibility is lower. In this environment, compliance becomes a market-access tool as much as a legal obligation.
Regional Rebalancing and Export Route Optimization
The market's center of gravity will remain Asia Pacific-dominant in volume terms, but growth in demand from Europe, North America, and selected emerging regions will encourage more deliberate route-to-market planning. Recent exhibition activity in Australia and the Middle East, combined with ongoing investments in processing capability, suggests that suppliers are actively testing and strengthening distribution pathways beyond traditional channels. Over the forecast period, expect more emphasis on export readiness, phytosanitary and import compliance, and localized customer support. This rebalancing creates opportunities for intermediaries, specialized traders, and processors that can bridge production clusters with end-market requirements efficiently.
Risks and Uncertainties to Monitor
Several factors could alter the trajectory. Continued raw material price volatility may compress margins for operators without strong contracting or hedging flexibility. Tightening regulations, especially where labeling, packaging, and import requirements diverge across markets, could raise operating costs and slow product launches. If demand for plant-based alternatives softens in specific categories or price-sensitive segments, coconut milk powder could face sharper competition from other plant-based fats and powders. Finally, weather-related disruptions and crop variability in key producing regions could affect both supply reliability and pricing stability, making multi-region sourcing and inventory planning more important than ever.
5. Strategic Implications for Decision-Makers
For Manufacturers
Prioritize processing consistency and application-specific value over volume alone. Investments in spray-drying efficiency, quality control, and integrated processing are becoming decisive because they directly influence batch reliability, specification control, and the ability to serve demanding industrial buyers. At the same time, build compliance infrastructure early, including labeling readiness, documentation fluency, and packaging transitions, so that new market entry does not become a bottleneck. Where raw material exposure is significant, strengthen supplier relationships and consider forward arrangements that reduce vulnerability to price swings.
For Investors
Look for operators that combine credible technology or integration with clear market access and documentation capability. In a market where the top players already hold meaningful share but concentration is not absolute, value creation is likely to accrue to companies that can defend premium positioning, manage volatility, and expand into regulated channels with lower friction. Pay close attention to how suppliers are handling compliance, packaging, and organic or premium differentiation, because those factors increasingly determine customer stickiness and pricing power.
For Procurement and Sourcing Teams
Treat resilience as a core sourcing criterion. Dual sourcing, specification flexibility, and supplier qualification based on consistency and compliance can reduce exposure to both price volatility and supply interruption. When evaluating suppliers, assess not only price and basic quality but also documentation maturity, packaging alignment with destination-market expectations, and the ability to support application needs. Shorter-term price advantages can be outweighed by higher total cost if a supplier cannot meet audit, labeling, or reliability requirements.
Why Timing and Granularity Matter Now
The market is large enough to reward strategic commitment and fast enough that timing matters. With the forecast period extending through 2032 and a CAGR in the high single digits, decisions made now about product specifications, sourcing routes, compliance readiness, and application targeting will shape competitiveness for years. Companies that act on broad trends alone may capture some growth, but those that combine trend awareness with detailed segmentation insight, regional compliance nuance, and application-specific formulation considerations are more likely to secure durable advantage. For teams seeking to move from general market awareness to targeted operating decisions, more granular data on regional and application dynamics, competitive positioning, and scenario planning can materially improve the quality of strategy and execution.
For detailed analysis of this topic, please visit the official page: Coconut Milk Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Yerba Mate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The yerba mate market has entered a phase of steady, measured expansion. From 2020 through 2025, total revenue climbed from approximately $150.0 million to $194.0 million, reflecting a compound trajectory that suggests the category is moving beyond niche wellness circles into broader commercial relevance. The forecast period from 2026 to 2032 projects continued growth at a CAGR of 4.92%, with market size expected to reach $269.3 million by the end of the decade. This pace is neither explosive nor stagnant—it signals a maturing category where incremental gains depend increasingly on product innovation, channel expansion, and geographic diversification rather than raw volume alone.
Several structural challenges define the current inflection point. First, price volatility and regulatory intervention in key producing regions have disrupted long-standing cost assumptions. In August 2025, the removal of price controls on yerba mate in Argentina triggered immediate market adjustments, forcing producers and traders to recalibrate pricing models that had been artificially stabilized for years. Second, the category remains highly concentrated among a handful of traditional producers in South America, creating supply chain fragility and limited competitive pressure on product formats. Third, consumer perception in non-native markets still wrestles with familiarity barriers—yerba mate is often viewed through a narrow lens of traditional preparation methods or stimulant alternatives, rather than as a versatile ingredient platform across food, beverage, and personal care applications.
For executives and investors, the implication is clear: the next growth cycle will reward players who navigate regulatory shifts proactively, diversify sourcing and format strategies, and reposition yerba mate beyond its historical consumption patterns. The market is large enough to support specialization, but small enough that execution speed and format innovation will separate winners from complacent incumbents.
Stevia Market
Key Structural Headwinds and Turning Points
The post-control pricing environment in Argentina represents more than a short-term adjustment; it reshapes the economics of production and export. Without administrative price floors, market participants must contend with fluctuating input costs, labor negotiations, and export competitiveness. The National Institute of the Yerba Mate has historically convened stakeholders twice annually to set minimum prices for fresh and dry leaves, but the broader deregulation trend introduces both risk and opportunity. Producers with vertically integrated operations or long-term farm contracts gain margin predictability, while smaller processors may face squeeze during periods of input inflation.
Simultaneously, the category stands at a product format crossroads. Traditional loose-leaf consumption dominates current revenue composition, but powder and extract formats remain comparatively small. This gap represents both a limitation and an untapped pathway. Powdered and concentrated forms enable incorporation into RTD beverages, functional snacks, cosmetic formulations, and dietary supplements—segments where convenience and intake flexibility drive adoption. The challenge lies in maintaining sensory authenticity and perceived quality while adapting production processes for scalable extraction and stabilization.
A third turning point involves geographic perception and export positioning. Latin American producers have long supplied traditional markets, but international expansion requires navigating certification expectations, sustainability narratives, and local regulatory frameworks for novel food ingredients. The recent FAO recognition of shade-grown yerba mate cultivation in Paraná, Brazil as a Globally Important Agricultural Heritage System provides a credible sustainability anchor that can be leveraged in premium positioning and export marketing. Yet translating heritage recognition into commercial advantage requires consistent storytelling, third-party verification, and distribution partnerships that understand how to communicate complex sourcing claims to end consumers.
Key Drivers Shaping Market Evolution
Technological and Format Innovation
Format innovation is emerging as a primary lever for category expansion. The shift from loose-leaf dominance toward powder, extracts, and ready-to-drink formulations reflects broader beverage and functional ingredient trends: convenience, dose consistency, and cross-category integration. Powder formats enable easier incorporation into dairy alternatives, baking mixes, and instant beverage bases, while extracts and concentrates open pathways into dietary supplements and cosmetic actives. These formats also support brand experimentation with flavor layering, sweetness reduction, and functional claim integration.
Recent product launches illustrate how incumbents and new entrants are using format and flavor innovation to capture convenience-oriented consumers. In February 2026, a leading North American organic yerba mate brand introduced a refreshed sparkling line with a lower-sugar mint variant, alongside seasonal limited-edition flavors positioned for convenience channel exclusivity. These moves signal a deliberate push into RTD sparkling categories where sugar reduction and channel-specific flavor differentiation are becoming table stakes. For manufacturers, the lesson is that format adaptation is not merely about processing capability; it is about aligning sensory profiles, packaging, and distribution format with the consumption occasion the target segment expects.
Regulatory and Policy Dynamics
Policy shifts in producing countries are reshaping cost structures and competitive positioning. The August 2025 removal of price controls in Argentina altered the pricing baseline for fresh and dry leaves, prompting market participants to revisit procurement strategies, inventory timing, and export pricing. While deregulation introduces volatility, it also rewards operational discipline. Companies with transparent cost models, long-term supplier relationships, and flexible contract structures can absorb price fluctuations more effectively than those relying on administrative stability.
Beyond national price policy, institutional frameworks continue to shape market legitimacy and export readiness. The National Institute of the Yerba Mate in Argentina coordinates production, processing, marketing, and consumption promotion, and its periodic stakeholder convenings influence minimum pricing expectations and sector coordination. In parallel, international recognition of sustainable cultivation systems—such as the FAO designation for shade-grown practices in Paraná—provides a policy-adjacent signal that can strengthen premium positioning and facilitate entry into markets where sustainability credentials influence procurement decisions. For market participants, regulatory literacy is no longer optional; it is a commercial capability that affects sourcing, compliance, and brand narrative.
Demand-Side Shifts in Consumer and Corporate Behavior
Consumer demand is gradually broadening the category’s application footprint. In food and beverage, yerba mate is increasingly treated as a functional base rather than a standalone traditional drink. This shift supports use in energy-adjacent beverages, wellness teas, flavored sparkling formats, and mixed-format consumption occasions. The functional beverage segment, in particular, benefits from yerba mate’s stimulant profile and cultural association with sustained energy, but growth depends on reducing barriers related to taste familiarity and preparation complexity.
Corporate procurement behavior is also evolving. As brands seek ingredient diversification and natural stimulant alternatives, yerba mate appears in portfolio discussions alongside tea, coffee, and botanical adaptogens. Dietary supplement and cosmetic applications remain comparatively small in absolute terms, but they represent high-margin pathways where concentrated extracts and standardized formats can command premium pricing. The strategic opportunity lies in matching format and certification to the expectations of each application segment rather than treating yerba mate as a single product category with uniform positioning.
Supply Chain and Cost Structure Dynamics
Yerba mate’s supply chain remains anchored in South American cultivation, with Argentina, Brazil, and Paraguay playing central roles. This geographic concentration creates both efficiency advantages and vulnerability. Production relies on agricultural cycles, labor coordination, and processing infrastructure that can be sensitive to weather variability, labor negotiations, and export logistics. The historical use of minimum price mechanisms reflects the sector’s need for coordination between farmworkers, government officials, and industry representatives, and the evolving policy environment means that pricing predictability must increasingly be engineered through contracts and vertical integration rather than administrative guidance.
Cost structures are also influenced by the premiumization pathway. Organic certification, shade-grown cultivation, and regenerative sourcing narratives add value but also raise production and verification costs. Brands that successfully institutionalize these claims can differentiate in export markets and premium retail channels, but they must maintain consistency across batches, seasons, and sourcing origins. For buyers and distributors, this creates a due diligence requirement: provenance claims need traceable documentation, and premium pricing needs demonstrable quality or sustainability differentiation that survives retailer and consumer scrutiny.
Competitive Landscape and Strategic Positioning
The competitive field is anchored by established South American producers alongside a growing set of North American and cross-border brands focused on organic, RTD, and premium-positioned products. Traditional manufacturers maintain strong domestic and export presence in loose-leaf and processed formats, while newer market participants compete through organic certification, regenerative sourcing narratives, flavor innovation, and channel-specific RTD distribution. This dual structure creates a differentiated landscape where incumbents leverage scale, long-standing farm relationships, and broad distribution, and challengers compete on format modernity, ingredient storytelling, and convenience-channel execution.
Leading producers in Argentina and Uruguay continue to benefit from deep-rooted processing expertise, established export channels, and brand recognition across traditional markets. Their strategic advantage lies in supply scale, processing flexibility across loose-leaf and milled formats, and relationships with institutional bodies that influence sector coordination. Several of these manufacturers also operate across multiple brands and private-label arrangements, allowing them to serve both consumer-facing and B2B demand. Their challenge is to extend into newer format segments without eroding core brand equity or compromising cost discipline during periods of input price volatility.
North American and export-oriented brands are pursuing a different playbook. Emphasis on organic certification, shade-grown sourcing, lower-sugar RTD formulations, and seasonal or channel-exclusive flavor launches reflects a strategy built around convenience retail, wellness positioning, and differentiation through ingredient claims. By targeting c-stores, convenience chains, and specialty channels with tailored SKUs, these brands aim to capture consumption occasions that traditional loose-leaf formats do not easily address. Their differentiation depends on consistent execution of sustainability narratives, flavor innovation cadence, and retail relationships that support rapid shelf turnover and limited-edition visibility.
Market Structure Evolution: Consolidation, Fragmentation, and New Entry
Market concentration remains notable, with the top three competitors estimated to hold roughly 40% of revenue and the top five closer to 50%. This level of concentration indicates that scale advantages and brand heritage matter, but it also leaves substantial room for specialized players in organic, RTD, powder, and premium supplement segments. The landscape is likely to evolve through a combination of selective consolidation among regional processors and continued fragmentation in consumer-facing formats, where brand, flavor, and channel strategy matter more than raw production scale.
New entrants are most likely to succeed where they combine format innovation with credible sourcing claims and channel-specific distribution. RTD sparkling, functional botanical blends, and standardized extract supply for supplement and cosmetic use represent spaces where smaller, agile players can build defensible positions without directly challenging traditional loose-leaf incumbents. At the same time, established producers may pursue acquisitions, brand extensions, or B2B ingredient partnerships to accelerate format diversification and reduce reliance on traditional consumption patterns. The strategic question for all players is whether to compete on heritage and scale, on modern format and wellness positioning, or on ingredient supply and B2B relationships—because each path requires a different operating model.
Forward Outlook: Three Strategic Trends for 2027–2032
Trend 1: Format Diversification as the Primary Growth Engine
Over the next several years, revenue growth is likely to be increasingly driven by non-loose-leaf formats, particularly powder, extracts, and RTD beverage expressions. These formats align with convenience, functional integration, and cross-category usage, and they enable yerba mate to appear in product portfolios beyond traditional brewing. The commercial implication is that producers and brands should treat format capability as a strategic asset, not a downstream processing decision. Investment in extraction stability, flavor compatibility, packaging formats, and application testing will determine which players can credibly serve beverage, supplement, and personal care demand without compromising sensory quality or cost efficiency.
The opportunity is not uniform across formats. RTD and sparkling segments offer high visibility and rapid consumer feedback, but they also demand consistent shelf performance, sugar-reduction strategies, and channel-appropriate flavor portfolios. Powder and extract segments offer B2B scalability and ingredient flexibility, but they require specification support, batch consistency, and application knowledge that downstream manufacturers can rely on. Brands that can bridge consumer-facing appeal with ingredient reliability will capture value across both retail and B2B pathways.
Trend 2: Sustainability and Heritage Narratives as Commercial Signals
Sustainability claims are moving from marketing add-ons to commercial prerequisites in several export and premium retail contexts. The FAO recognition of shade-grown cultivation in Paraná provides a concrete reference point for heritage-based sustainability positioning, and similar institutional acknowledgments can strengthen credibility when paired with traceable sourcing and verifiable practice standards. For exporters and brand owners, the strategic value lies in converting recognition into repeatable storytelling, certification consistency, and retailer-ready documentation that survives procurement review.
This trend also introduces a risk dimension. Narrative inflation without operational backing can erode trust quickly, especially in categories where consumers and retailers increasingly scrutinize ingredient provenance. Companies that embed sustainability into sourcing contracts, farmer support programs, and batch-level traceability will be better positioned to sustain premium pricing and export access than those relying primarily on label claims. The trend therefore favors participants who can make sustainability measurable and auditable rather than purely aspirational.
Trend 3: Pricing Detachment and Procurement Discipline
As regulatory price controls recede in key producing markets, the category will increasingly price through market mechanisms, contracts, and vertical coordination. This shift rewards procurement discipline, inventory timing, and supplier relationship depth. For manufacturers and distributors, the commercial implication is that cost planning must account for periodic volatility rather than assume administrative stability. Hedging through forward contracts, diversified sourcing, or processing flexibility can protect margin during adjustment periods, while overly rigid pricing architectures may leave players exposed when input costs move quickly.
This trend also creates a competitive filter. Players with strong farm relationships, transparent cost structures, and flexible processing can adapt faster and preserve export competitiveness. Those without such capabilities may face margin pressure or reduced agility in responding to demand shifts. For buyers in non-producing markets, the trend underscores the importance of supplier diversification and specification lock-in, especially when sourcing for premium or certified product lines where consistency is a purchase criterion.
Strategic Recommendations for Decision Makers
For manufacturers and brand owners, the priority is to align format strategy with consumption occasion rather than treating product forms as interchangeable. Loose-leaf will likely remain a core revenue base, but growth leverage increasingly sits in powder, extract, and RTD applications where convenience and functional integration drive adoption. Leaders should evaluate processing capabilities against target formats, define flavor and sweetness strategies that match channel expectations, and build specification support for B2B customers who need consistency and application guidance. Where sustainability or heritage claims are part of the brand architecture, those claims should be backed by traceable sourcing and documentation that can withstand retailer and consumer scrutiny.
For investors, the most relevant question is whether a target’s competitive advantage is durable under market pricing and format competition. Vertical integration, long-term farm relationships, and flexible processing provide resilience when input prices fluctuate. Strong brand positioning in organic, RTD, or premium segments can support margin even in a moderately concentrated market, but only if innovation cadence and channel execution remain consistent. Due diligence should therefore assess format pipeline, sourcing stability, certification credibility, and distribution access rather than relying solely on historical revenue trajectory or brand recognition.
Matcha Tea Market
For procurement and supply chain leaders, diversification and specification discipline are the key safeguards. Relying on a single sourcing origin or a single price mechanism increases exposure to volatility, especially as regulatory frameworks evolve in producing regions. Defining clear quality specifications, verifying certification and traceability documentation, and establishing backup sourcing options can reduce disruption risk while preserving access to premium or certified material. Procurement strategies should also consider format requirements early, because powder, extract, and loose-leaf sourcing involve different supplier capabilities, quality controls, and cost structures.
For organizations seeking to move from broad market awareness to precise segmentation, pricing strategy, and channel-specific planning, a comprehensive research dossier can help translate these trends into targeted decisions. Detailed breakdowns by region, type, application, concentration metrics, and company-level tracking provide the granularity needed to prioritize investments, evaluate competitors, and stress-test sourcing and pricing assumptions under different regulatory and demand scenarios. Access to that level of structured intelligence allows decision makers to convert category outlooks into executable plans with clearer risk boundaries and more realistic growth pathways.
The yerba mate market is positioned for steady, format-led expansion through the end of the decade, but the distribution of value will depend on how effectively companies manage pricing volatility, credibility of sustainability claims, and the operational demands of new product forms. The players who treat format innovation, sourcing discipline, and channel-specific positioning as interconnected strategic choices—rather than isolated product decisions—are most likely to capture disproportionate share of the next growth cycle.
PW Consulting Health Care Research Center
For detailed analysis of this topic, please visit the official page: Yerba Mate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hotel Furniture Market Outlook: Decoding the 4.92% CAGR Growth Path to 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Hotel Furniture Market
Market Overview and Core Challenges
The hotel furniture market has demonstrated steady expansion over the past five years, growing from approximately 18.9 billion USD in 2020 to an estimated 23.15 billion USD in 2025. Looking ahead, the market is projected to reach 32.66 billion USD by 2032, expanding at a compound annual growth rate of 4.92 percent during the 2026 to 2032 forecast period. This trajectory reflects a mature but still growing sector fueled by hospitality recovery, renovation cycles, and evolving guest expectations. The moderate pace of growth signals a market that is expanding reliably rather than surging unpredictably, which makes strategic positioning and cost discipline especially important for participants.
Several structural challenges are reshaping how operators, manufacturers, and investors approach this landscape. The first challenge centers on pricing volatility and tariff exposure. The cost environment for imported wooden furniture, fixtures, and equipment has shifted dramatically, introducing uncertainty into project budgeting and renovation timelines. The second challenge involves the tension between standardization and customization. Large hotel brands seek repeatable, cost-efficient designs for scaled deployment, while boutique and luxury properties demand bespoke aesthetics and material quality. Navigating both demands simultaneously creates operational and design complexity. The third challenge relates to supply chain resilience and lead time predictability. Post-pandemic normalization has improved, but localized disruptions, freight fluctuations, and raw material constraints still affect the reliability of large FF&E deployments. These challenges are not temporary headwinds. They are structural forces that will influence margin profiles, sourcing strategies, and product development priorities through the rest of the decade.
Office Furniture Market
Key Drivers Shaping Market Dynamics
Technology and Design Innovation
Innovation in hotel furniture is increasingly driven by durability, multifunctionality, and material efficiency rather than novelty alone. Manufacturers are prioritizing designs that withstand high turnover, simplify maintenance, and support space optimization in guestrooms and common areas. Improved finishing processes, reinforced joinery, and modular components are enabling products that can be refurbished or reconfigured with less downtime. Digital tools in design and prototyping are also accelerating custom execution, allowing shorter feedback loops between hotel operators and suppliers during fit-out or renovation phases. For high-volume business hotels, efficiency-focused design reduces total cost of ownership. For luxury and boutique properties, advanced casegoods and upholstered solutions support distinctive branding without sacrificing longevity.
Wood Furniture Market
Policy and Regulatory Environment
Trade policy and regulatory changes are now a central factor in hotel furniture sourcing decisions. Tariff adjustments have altered the cost structure for imported upholstered wooden furniture and cabinetry, with some categories facing substantial rate increases during recent periods. These shifts matter because FF&E can represent a meaningful share of hotel renovation budgets, so pricing shock in this segment directly affects project feasibility. At the same time, selective policy actions have provided temporary relief or clarified the scope of certain duties on wooden furniture products, creating a moving landscape rather than a fixed cost baseline. For hoteliers and manufacturers, the practical implication is that sourcing strategies must account for potential tariff volatility, not just current pricing. This has increased interest in domestic production options, multi-source procurement, and earlier procurement timing to reduce exposure to mid-project cost escalation.
Demand-Side Evolution in Hospitality
Demand patterns are changing the type of furniture that properties need to procure. Business hotels continue to prioritize durable, standardized solutions that support rapid room turnover and consistent guest experience across multiple locations. Luxury hotels are pursuing higher specification materials, layered textures, and refined upholstery that communicate premium positioning. Boutique hotels often require smaller production runs with stronger design personality, which places pressure on manufacturers to offer flexibility without excessive minimum order constraints. Another important shift is the growing attention to outdoor and semi-outdoor hospitality spaces, especially in destinations where weather-resistant furnishings can extend usable property area and improve guest experience. Across these segments, the underlying trend is a demand for furniture that supports both brand expression and operational durability.
Supply Chain and Cost Structure Adjustments
Supply chain strategy is becoming a differentiator rather than a back-office function. Cost structures are being reshaped by raw material movements, including changes in softwood lumber pricing and related derivatives, which have influenced the economics of upholstered furniture and casegoods production. Manufacturers are responding with a combination of sourcing diversification, inventory anticipation for high-priority product lines, and closer coordination with project schedules to reduce rush exposure. For buyers, this environment rewards earlier planning and clearer specification packages. For suppliers, it creates opportunity for manufacturers that can demonstrate reliable lead times, transparent cost communication, and the ability to provide realistic alternatives when material constraints appear. The companies gaining ground are those that treat procurement continuity as part of product value, not just logistics.
Competitive Landscape and Leading Strategies
The competitive field includes established U.S. manufacturers with deep hospitality specialization, international producers with scale and customization capacity, and niche players focused on specific product categories or environments. Leading firms typically differentiate through product breadth, design expertise, customization capability, and the ability to support large project deployments with consistent quality. In this market, scale alone is not the deciding advantage. The more durable advantage comes from combining dependable execution with the flexibility to meet varying brand standards, from business hotel standardization to luxury custom casegoods and upholstered collections.
Several competitive patterns are visible across the leading participants. One is the emphasis on hotel-specific product families. Suppliers such as Kimball Hospitality, Bernhardt Hospitality, Charter Furniture, and Dickson Furniture have built reputations around casegoods, beds, seating, and upholstered solutions designed directly for commercial hospitality use. Their positioning is strongest when they can offer repeatable designs that still allow room for customization by brand or property type. A second pattern is the role of international manufacturers in providing breadth and project-scale capability. Companies such as Mingsun Group, RON Group, Fulilai Hotel Furniture, and Harman Furniture Group illustrate the growing importance of suppliers that can handle multi-room packages, custom casegoods, and FF&E coordination for larger hospitality projects. Their value often lies in combining volume capacity with design responsiveness, especially when hoteliers are managing complex fit-outs or renovation programs. A third pattern is category specialization. MityLite’s focus on durable tables and chairs for hotel and hospitality settings, Abel Corporation’s architectural millwork and live mockup capabilities, and Grosfillex’s specialization in outdoor and durable hospitality furniture show that targeted expertise can create strong competitive moats, particularly when a property type or environment demands specific performance characteristics.
Recent developments reinforce the importance of visibility and market engagement. Trade show participation and new product catalog releases remain central tools for launching hospitality collections and signaling design direction to buyers. These activities are not merely promotional. They are practical mechanisms for testing market interest, refining product offerings, and aligning manufacturers with the specifications hotel buyers are prioritizing in the current cycle. At the same time, the broader competitive landscape is likely to evolve through selective consolidation among mid-tier suppliers, increased emergence of design-led smaller brands in the boutique and lifestyle segments, and continued pressure on cost and delivery reliability across the supply base. The winners will be those that can combine a credible design narrative with dependable execution and adaptable sourcing strategies.
Forward-Looking Trends and Commercial Opportunities
Trend One: Greater Sourcing Flexibility and Risk-Adjusted Procurement
Over the next three to five years, procurement strategies are likely to place greater weight on trade-policy resilience and cost predictability. Hoteliers and developers will increasingly favor suppliers that can offer alternative sourcing paths, transparent lead times, and proactive communication about cost exposure. For manufacturers, this creates an opportunity to differentiate through supply continuity, regional production options, and stronger project planning support. For investors and operators, it suggests that supplier relationships with demonstrated flexibility may reduce downstream cost surprises and timeline risk, especially in renovation programs where FF&E decisions intersect with broader capital planning.
Trend Two: Durability and Multifunctionality as Core Value Drivers
As hotel operators balance aesthetic ambition with operational realism, furniture that performs well under heavy use and supports multiple functions will continue to gain relevance. This includes products that simplify cleaning, reduce replacement frequency, and adapt to changing room layouts or hospitality concepts. The commercial opportunity lies in product lines that can lower lifecycle costs without sacrificing guest-facing quality. Manufacturers that can articulate total cost of ownership, not just upfront price, will be better positioned in both business hotel and luxury environments, because both segments need to justify spend under tighter capital discipline.
Trend Three: Outsourced Design Differentiation for Distinctive Guest Experiences
A further trend is the continued demand for furniture that helps properties create memorable environments. Boutique and luxury hotels are likely to persist in seeking casegoods and upholstered pieces that contribute to a coherent design story, while business hotels will continue to prioritize scalable but refined solutions. The opportunity here is for manufacturers and suppliers that can offer modular customization, consistent quality across batches, and faster turnaround on variation orders. This is especially relevant for properties trying to stand out in competitive markets without committing to fully bespoke programs for every item.
These trends carry risks and uncertainties. Tariff and trade policy volatility can shift cost assumptions quickly, affecting margin planning and project economics. Raw material availability and freight dynamics may continue to create intermittent lead-time pressure. In addition, differentiation strategies that depend heavily on custom production can become expensive if order volumes are uneven or if project pipelines are delayed. Navigating these risks requires a balance between design ambition, operational efficiency, and procurement discipline.
Actionable Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to strengthen resilience and clarity in what is offered to hospitality clients. Product portfolios should be evaluated for durability, lead-time reliability, and the ability to support both standardized and customized orders without excessive complexity. It is equally important to communicate cost structure and sourcing options transparently, because trade-policy volatility has made uncertainty a real planning concern for buyers. Companies that can provide reliable alternatives, earlier visibility into supply constraints, and credible project support will be better positioned to win and retain hospitality contracts over the forecast period.
For investors, the key is to assess which business models are built for durability rather than short-term pricing advantage. Look for suppliers with demonstrated capability in hospitality-specific product families, strong execution around lead times and project coordination, and sourcing flexibility that can absorb trade or material shocks. Businesses that rely heavily on single-source exposure or that lack clear differentiation in quality and service may face greater volatility as procurement teams seek more predictable partners. In a market growing at a moderate but consistent pace, value creation is likely to accrue to companies that can combine product relevance with operational reliability.
For hotel operators, developers, and procurement teams, the most practical move is to treat furniture sourcing as an integrated part of project planning rather than a last-stage purchase decision. Earlier involvement of suppliers, clearer specification packages, and evaluation of total lifecycle cost can reduce exposure to tariff-driven price changes and lead-time uncertainty. Properties should also weigh the balance between standardization and customization based on brand strategy and renovation timeline, because over-customization can introduce cost and schedule risk while over-standardization may weaken the guest experience. Selecting partners based on design capability, delivery reliability, and risk communication can improve project outcomes across business, luxury, and boutique segments.
PW Consulting Health Care Research Center
For decision-makers seeking more granular segmentation data, regional demand patterns, and tailored scenario planning, deeper commercial research can provide sharper inputs for procurement strategy, capacity planning, and investment evaluation. A more detailed review of product-level splits, competitive positioning by segment, and policy-sensitive cost scenarios can help translate these market themes into specific action plans for individual portfolios and projects.
For detailed analysis of this topic, please visit the official page: Hotel Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The IV Bags Market: Strategic Shifts and Commercial Opportunities Through 2032
The global market for intravenous (IV) bags has evolved from a commoditized supply chain component into a strategically sensitive segment of medical device manufacturing. Valued at approximately $2.94 billion in 2020, the market reached $3.9 billion by 2025 and is projected to expand to $5.79 billion by 2032, reflecting a compound annual growth rate of 5.8 percent. This trajectory is not merely a function of population growth or hospital bed expansion. It reflects a convergence of regulatory pressure, material science innovation, clinical workflow transformation, and supply chain recalibration. For executives navigating healthcare procurement, manufacturing investments, or portfolio allocation, the IV bag segment offers a clear lens into how medical device markets reward precision, compliance readiness, and manufacturing agility.
At its core, the market serves as the primary delivery vehicle for parenteral therapies, electrolyte replacement, and medication administration across acute care, outpatient, and increasingly decentralized settings. The revenue trajectory indicates steady expansion, yet the growth is uneven across product architectures, clinical channels, and geographic maturity. Understanding where value is being created—and where margin compression or compliance risk is emerging—requires moving beyond headline figures and examining the structural forces reshaping competitive positioning.
Market Landscape and Core Challenges
The IV bag market is characterized by high concentration, material transition friction, and a regulatory environment that is actively rewriting product specifications. These forces are not isolated; they interact to create both execution risk and differentiation opportunity.
Structural Concentration and the Limits of Scale
Market leadership is heavily concentrated, with the top three players accounting for roughly 65 percent of global revenue and the top five capturing approximately 78 percent. This concentration is not accidental. It reflects the capital intensity of sterile manufacturing, the clinical preference for validated supply continuity, and the procurement leverage exercised by large hospital networks and group purchasing organizations. Incumbents benefit from entrenched distribution relationships, regulatory filing histories, and integrated solution offerings that pair containers with premixed fluids or delivery systems. However, scale alone is increasingly insufficient. The market is entering a phase where compliance differentiation, material substitution readiness, and regional capacity alignment matter as much as volume economics.
The DEHP and PVC Transition as a Margin and Compliance Stress Test
The most consequential shift in the segment is the move away from PVC and DEHP-containing formulations toward non-PVC, DEHP-free alternatives. This transition is being driven by patient safety concerns, environmental regulation, and institutional procurement policies, but it carries material economic consequences. Industry analysis indicates that shifting to DEHP-free and non-PVC constructions raises average product costs by 15 to 20 percent compared with traditional PVC bags. That cost increment flows through procurement budgets, squeezes price-sensitive segments, and forces manufacturers to balance compliance compliance, performance validation, and pricing strategy.
The pressure is not theoretical. North Carolina Senate Bill 600, the Toxic-Free Medical Devices Act of 2025, explicitly bans IV bags and tubing made with DEHP, signaling how state-level policy can accelerate material substitution even before federal harmonization. In parallel, EU MDR 2017/745 and evolving FDA guidance are accelerating adoption of autoclave-compatible non-PVC polymer alternatives, effectively redefining acceptable product architectures for sterile fluid delivery.
Quality, Recall Exposure, and the Cost of Execution
Regulatory and quality events have become a recurring theme in the segment, underscoring the operational complexity of sterile fluid container manufacturing and filling. In April 2025, the FDA issued a nationwide recall of certain ropivacaine hydrochloride injection IV bags due to potential polypropylene fibers. In August 2025, B. Braun Medical issued a voluntary nationwide recall of two lots of Lactated Ringer’s Injection USP and 0.9% Sodium Chloride Injection USP 1000 mL IV fluids due to particulate matter. These events are not merely compliance footnotes; they illustrate how material selection, filtration control, and sterilization integrity directly affect market trust, hospital sourcing decisions, and liability exposure. For executives, recall risk is a reminder that the IV bag market punishes execution gaps quickly and rewards process discipline.
PW Consulting Health Care Research Center
Key Drivers Reshaping the Market
The growth trajectory is being shaped by four reinforcing forces: material and manufacturing innovation, regulatory acceleration, demand-side reconfiguration, and supply chain cost dynamics. Together, these drivers are redefining where margin resides and how competitive advantage is built.
Material Innovation and Sterile Processing Compatibility
The transition to non-PVC and DEHP-free constructions is more than a regulatory response; it is becoming a performance and compatibility standard. Autoclave-compatible polymer alternatives are gaining ground because they support sterilization workflows without compromising container integrity or drug compatibility. This is particularly relevant as pharmaceutical manufacturers and providers seek to standardize on materials that perform across multiple processing environments. Companies that can validate sterile filling, particle control, and mechanical durability in non-PVC architectures are positioning themselves to capture premium segments where compliance and clinical confidence are prioritized over unit cost minimization.
Product launches in this direction are already visible. In March 2026, Fresenius Kabi introduced eco-friendly IV bags in Europe utilizing PVC-free and DEHP-free materials, explicitly aligned with evolving environmental and patient safety regulations. This move reflects a broader pattern: leading manufacturers are treating material substitution as a platform strategy rather than a discrete product update, enabling them to meet regional requirements while preserving fill-and-delivery performance.
Regulatory Momentum and Regional Policy Fragmentation
Regulation is no longer a background condition; it is an active market driver. The combination of EU MDR expectations, FDA guidance on material safety and particulate control, and state-level legislative action in the United States is compressing the timeline for material transition. For manufacturers, this creates a dual imperative: maintain compliance across jurisdictions with different timetables, and ensure that product portfolios can adapt without sacrificing fill accuracy, shelf stability, or compatibility with common medications.
Intravenous Fluid Bags Market
Policy fragmentation also creates regional variation in adoption speed. Markets with stricter material mandates will see faster substitution but also higher cost structures and potentially shorter supplier qualification windows. In contrast, regions where procurement remains cost-led may experience slower transition, creating a bifurcated landscape where premium, compliance-forward products coexist with legacy PVC-based offerings for a defined period. Executives must plan for this unevenness rather than assume uniform global adoption.
Demand-Side Shifts: Hospital Volume, Clinical Efficiency, and Home Healthcare
Demand is expanding across multiple clinical channels, but the composition of that demand is changing. Hospital settings remain the dominant consumption base, reflecting the continued centrality of IV therapy in acute care, perioperative settings, and inpatient medication administration. At the same time, clinics and home healthcare channels are gaining relative importance as care delivery shifts toward lower-acuity and decentralized models. This shift is not just a volume story; it alters package size preferences, sterility expectations, ease-of-use requirements, and logistics assumptions.
In hospital environments, procurement is increasingly influenced by total cost of care, supply reliability, and compatibility with closed-system transfer workflows. Premixed IV solutions and ready-to-use configurations are gaining traction because they reduce preparation time, lower error risk, and support nursing efficiency. In home and outpatient settings, the emphasis shifts toward portability, patient-friendly handling, and consistent fluid delivery. The market is therefore developing along multiple demand vectors, each with distinct value drivers.
Supply Chain Reconfiguration and Manufacturing Capacity Investments
Supply chain dynamics are being reshaped by capacity expansion, regionalization, and the economics of sterile production. Baxter International’s February 2026 announcement of expanded U.S. IV solutions manufacturing capacity illustrates how incumbents are responding to rising hospital demand by upgrading sterile fluid production lines and increasing output of premixed IV bags. This type of investment signals a strategic bet on supply continuity, proximity to end markets, and the ability to reduce lead-time risk in critical care supply chains.
At the same time, the material transition is altering cost structures. Non-PVC formulations, specialized multilayer constructions, and enhanced sterilization requirements increase production complexity and input costs. Suppliers that can manage these cost increments through process optimization, regional sourcing, and scaled sterile manufacturing will be better positioned to protect margins while meeting compliance expectations. For procurement teams, this environment demands a more nuanced sourcing strategy that balances price, material compliance, and supply resilience rather than optimizing solely on unit cost.
Competitive Landscape and Leading Strategies
The IV bag market is defined by a concentrated group of manufacturers that have built advantage through material portfolios, sterile processing expertise, regional capacity, and solution-level positioning. The competitive field is not static; it is evolving around compliance readiness, product architecture, and the ability to align manufacturing with demand geography.
Incumbent Positioning and Differentiation
Baxter International Inc., headquartered in Deerfield, Illinois, remains a dominant force as a leading manufacturer of flexible IV bags and IV solutions, including Viaflo containers, supplying the majority of empty IV bags globally. Its scale advantage is complemented by recent manufacturing expansion aimed at higher premixed bag output, reinforcing a strategy that connects container supply with solution availability and hospital demand continuity. For Baxter, the strategic priority is likely to remain supply reliability, capacity alignment, and integration across containers and fluids.
B. Braun Melsungen AG, based in Melsungen, Germany, has built a differentiated profile around EXCEL and E3 IV containers in PVC and non-PVC materials, with an emphasis on DEHP-free and sustainability-certified offerings. This positioning aligns closely with the regulatory and procurement trends driving material substitution. Its sustainability-certified framing also supports institutional buyers seeking documented compliance and environmental performance, which is increasingly relevant in European markets and among U.S. health systems responding to state-level mandates.
Fresenius Kabi AG, headquartered in Bad Homburg, Germany, competes through proprietary technologies such as freeflex® and freeflex®+ IV bags, emphasizing sterile filling and drug delivery performance. Its March 2026 launch of eco-friendly, PVC-free and DEHP-free IV bags in Europe demonstrates a strategy that couples material compliance with platform innovation, allowing the company to address regulatory expectations while maintaining clinical utility.
The competitive set also includes specialist and regional players with distinct positioning. Sippex SAS, based in La Seyne-sur-Mer, France, specializes in PVC, multilayer PP, and EVA empty IV bags plus connectors for pharmaceutical use, giving it a strong fit with pharma-facing fill and packaging requirements. ICU Medical, Inc., in San Clemente, California, produces flexible IV solution containers with non-PVC/non-DEHP options and closed-system transfer systems, aligning with safety-centered procurement and medication administration workflows. Nipro Corporation, based in Osaka, Japan, offers dual-chamber PLW® bags and high-volume empty IV bags for pharmaceutical mixing and injection, serving segments where multi-component configurations and large-volume capacities matter.
Strategic Themes Across the Competitive Set
Several strategic themes emerge when comparing these players:
Worldwide Glucose IV Bag Market
- Material compliance as a platform: Leading manufacturers are treating DEHP-free and non-PVC formulations as core product architectures rather than niche variants, enabling faster response to regulation and procurement mandates.
- Sterile processing and fill integration: Companies with proprietary sterile filling technologies or integrated solution offerings are better positioned to capture value in premixed and ready-to-use segments where workflow efficiency and error reduction are prioritized.
- Regional capacity alignment: Manufacturing expansion in key demand regions reduces lead-time exposure and supports supply continuity for acute care customers, which is increasingly a differentiating factor in procurement decisions.
- Specialization versus scale: Specialist manufacturers compete on pharma-compatible materials, dual-chamber designs, and connector integration, while scale players compete on volume reliability, broad distribution, and solution breadth. Both models can be viable, but they require different operating capabilities.
Market Evolution: Consolidation Pressure and Niche Resilience
The market is likely to continue favoring well-capitalized incumbents with compliance-ready portfolios and scalable sterile manufacturing. Consolidation pressure will remain where acquisition targets offer material technology, regional distribution, or specialized product designs that accelerate portfolio upgrade. At the same time, niche resilience will persist in pharma-adjacent manufacturing, closed-system transfer, and regional suppliers that can meet localized compliance requirements with differentiated materials or service models. New entrants will find the highest barriers in general-purpose commodity segments, but targeted opportunities may exist in specialized bag architectures, regional capacity gaps, and compliance-first product lines for markets undergoing rapid regulatory transition.
Forward Outlook: Trends and Opportunities Through 2032
Looking ahead, three trends are likely to shape the IV bag market over the next three to five years. Each carries distinct implications for strategy, investment, and procurement.
Material Substitution Becomes a Baseline Expectation
The shift toward DEHP-free and non-PVC constructions will increasingly be treated as standard rather than premium. As EU MDR expectations, FDA guidance, and state-level legislation tighten, procurement specifications will more routinely require autoclave-compatible, non-PVC alternatives. This will compress the addressable market for legacy PVC-based products in regulated channels and raise the relative value of compliance-validated portfolios. The commercial opportunity lies in developing material platforms that can scale across regions while managing the 15 to 20 percent cost increment through process efficiency, design optimization, and differentiated service packaging.
Premixed and Workflow-Integrated Solutions Gain Share
Demand for premixed IV solutions and ready-to-use configurations is likely to grow as hospitals prioritize nursing efficiency, medication safety, and supply simplicity. In this context, the IV bag is not just a container; it becomes part of a workflow solution that reduces preparation steps and supports sterile delivery. Manufacturers that can connect container design, fill reliability, and compatibility with common therapies will be better positioned to capture margin in hospital and clinic channels. The strategic risk is underinvesting in validation, packaging integrity, and regional supply alignment, which can quickly erode trust in a market sensitive to quality events.
Regionalization and Supply Resilience Redefine Sourcing Logic
Capacity expansion in key demand regions, combined with heightened sensitivity to recall risk and material compliance, will push procurement toward regionalized supply strategies. Health systems and pharmaceutical buyers are likely to place greater weight on lead-time reliability, audit readiness, and documented quality control. For manufacturers, regional capacity and transparent quality systems will be competitive assets. For investors, the opportunity is to identify producers whose operating models align with supply resilience rather than purely cost-based globalization. The uncertainty lies in the pace of policy harmonization; uneven adoption across regions could create temporary arbitrage but also complicate multi-market product planning.
Strategic Implications for Decision Makers
The IV bag market rewards decisions grounded in compliance readiness, material strategy, and supply alignment. The following actions are most relevant depending on role and objectives.
For Manufacturers
Treat material transition as a platform decision. Develop non-PVC, DEHP-free architectures that support autoclave compatibility and sterile filling validation across multiple regions, rather than managing substitutions as isolated product changes. Invest in process control and particulate management to reduce recall exposure, since quality events can rapidly alter buyer confidence. Align capacity expansion with regional demand intensity and procurement specifications, particularly where premixed and ready-to-use solutions are gaining relevance. Where cost pressure is acute, seek margin protection through design efficiency and localized sourcing rather than compromising compliance positioning.
For Investors
Focus on companies with clear compliance roadmaps, scalable sterile manufacturing, and solution-level differentiation rather than those competing solely on volume pricing. Material transition, regulatory readiness, and regional capacity investments are likely to become increasingly important value drivers. Monitor recall and quality history as leading indicators of execution discipline, since the market punishes supply and particle-control failures disproportionately. In a concentrated market, selective consolidation may create value for platforms that can integrate complementary material technologies or fill capabilities, but the durability of that value depends on how well acquired assets fit compliance and regional demand strategies.
For Procurement and Supply Chain Leaders
Move beyond unit-cost optimization to a sourcing framework that includes material compliance, sterilization compatibility, fill integrity, and regional supply resilience. In markets where DEHP bans and non-PVC mandates are advancing, procurement specifications should be updated proactively to avoid qualification delays and specification mismatches. Evaluate suppliers on documented quality systems, recall responsiveness, and capacity alignment with your service settings, especially if home healthcare, clinic, or premixed workflows are expanding in your portfolio. Where feasible, diversify across material platforms and geographies to reduce exposure to single-source risk during transition periods.
The strategic landscape of the IV bag market is being reshaped by material science, regulatory momentum, workflow-driven demand, and supply chain recalibration. Growth is real, but value capture will favor participants who align product architecture with compliance reality and who treat supply reliability as a strategic asset. Detailed regional splits, application-level demand dynamics, material cost scenarios, and company-level competitive indicators can sharpen these decisions further. For decision makers seeking deeper segmentation, scenario analysis, and tailored commercial guidance, the full PW Consulting research report provides expanded data and customized strategic context to support execution.
For detailed analysis of this topic, please visit the official page: IV Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com