

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Smart Locks Market: How 14.5% CAGR and Residential Demand Reshape 2026–2032

The Smart Locks Market: Strategic Trends and Commercial Opportunities Through 2032
The smart locks market has evolved from a niche convenience upgrade into a structural component of the broader connected home and commercial security ecosystem. Valued at approximately 1.67 billion USD in 2025, the sector has demonstrated consistent expansion, growing from 850 million USD in 2020 at a compound annual rate of 14.5% through the forecast horizon extending to 2032. By the end of the projection period, revenue is expected to surpass 4.28 billion USD, signaling a market that has moved past early adoption friction and entered a phase defined by standardization, ecosystem integration, and security formalization. This trajectory is not merely a function of consumer curiosity; it reflects convergent pressures from residential security expectations, commercial access modernization, and the maturation of low-power wireless protocols that make keyless entry reliable enough for daily use.
For executives and investors evaluating the space, the headline growth rate only tells part of the story. The market is simultaneously consolidating around interoperable standards, fragmenting across application-specific requirements, and facing regulatory scrutiny that will reshape product roadmaps. Understanding where value is created—and where margin compression or compliance risk emerges—requires looking beyond total market size and examining the structural forces that will determine which players scale profitably and which get squeezed by commoditization or certification bottlenecks.
Market Snapshot: Scale, Growth, and Structural Composition
The revenue trajectory from 2020 through 2025 reflects a market that accelerated as wireless connectivity, battery efficiency, and mobile credentialing became routine expectations rather than differentiators. The jump from 1.44 billion USD in 2024 to 1.67 billion USD in 2025 indicates that smart locks are increasingly treated as baseline infrastructure in new residential construction and retrofitting programs, rather than optional premium add-ons. The forecast period through 2032 points to a market that will more than double in size, with growth accelerating in the outer years as mainstream replacement cycles and commercial retrofit programs compound.
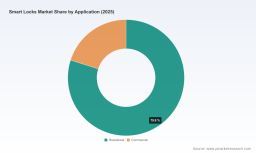
Segmentation patterns reveal where demand is concentrated and where strategic positioning matters most. By product architecture, deadbolt-style smart locks command the largest revenue share, reflecting their dominance in residential door retrofitting and new-build specifications. Lever handle variants represent a meaningful secondary stream, particularly in commercial and multi-family contexts where ergonomic and fire-code considerations favor that form factor. Padlocks and other specialized formats occupy a smaller but strategically distinct niche, often serving temporary access, asset protection, and outdoor use cases where standalone battery operation and offline credentialing are critical. By application, residential deployments account for the majority of revenue, yet commercial adoption is expanding at a notable pace as property managers, co-working operators, and enterprise facilities teams seek centralized access control without full wiring overhauls. Geographically, North America remains the largest revenue contributor, supported by high smart-home penetration, renovation activity, and a strong DIY installation culture. Europe follows as a substantial market shaped by regulatory-driven security certification and multi-family housing modernization. Asia Pacific represents a rapidly expanding region where urbanization, rising disposable income, and domestic manufacturing scale are reshaping supply dynamics. Latin America and the Middle East & Africa together form an earlier-stage but strategically relevant footprint, often characterized by pilot deployments, security-conscious premium segments, and gradual normalization of connected access as total cost of ownership improves.
Market concentration remains moderate, with the top three players accounting for roughly 45% of revenue and the top five reaching just over half. This level of concentration indicates a market that is neither dominated by a single hegemonic player nor completely fragmented. It is a field where incumbents with strong distribution, brand trust, and ecosystem alignment hold meaningful advantages, while agile entrants can still win in defined sub-segments by solving a specific user experience, design, or certification challenge. The presence of both retrofit specialists and full-lock manufacturers, alongside regional hardware brands expanding into connected access, suggests that competition will increasingly hinge on interoperability, installation friction, and the ability to meet unified physical-and-cyber security expectations.
Core Challenges and Inflection Points
Despite favorable growth fundamentals, the market is passing through several structural tension points that will separate durable strategies from reactive product launches.
The first challenge is the transition from standalone convenience to certified security. For years, smart locks were marketed primarily around ease of access, temporary credentialing, and app-based control. That value proposition is no longer sufficient as buyers, regulators, and installer networks increasingly expect evidence that a connected lock can withstand both physical attack vectors and digital compromise. Products that treat cybersecurity as an afterthought face growing friction in premium residential specifications and commercial procurement, where risk teams and insurance considerations are becoming more influential. The market is therefore moving toward a phase where trust is a purchasable attribute, not a marketing claim.
The second challenge is ecosystem fragmentation slowly giving way to interoperability pressure. Early smart lock adoption was constrained by questions about whether a lock would reliably communicate with a given hub, voice assistant, or mobile platform. The broader rollout of standards-aligned connectivity has reduced some of that uncertainty, but it has also raised the bar for product design. Manufacturers that built closed or partially closed ecosystems must now reconcile backward compatibility, credential portability, and long-term software support. This creates an execution challenge: interoperability expands the addressable user base, but it also exposes a product to broader integration testing, firmware lifecycle obligations, and competitive exposure once the lock becomes interchangeable with alternatives in the same ecosystem.
The third challenge lies in supply chain exposure for the semiconductor and radio components that underpin connectivity, biometric sensing, and secure credential storage. As smart locks become more feature-rich, they depend on a broader set of modules that are susceptible to concentration risk, lead-time variability, and cost swings. This matters because margin structures in consumer hardware are already sensitive to component volatility, and because security-oriented authentication hardware can create supply dependencies that are harder to reroute than commodity parts. Companies that treat component strategy as a procurement detail rather than a product architecture decision may find themselves exposed to both cost shocks and launch timing risk.
These challenges converge into a broader inflection point: the market is shifting from a phase where feature novelty drives purchases to one where reliability, certification, and integration depth determine repeat adoption and referral. That shift rewards organizations that can align product design, compliance planning, and ecosystem relationships early, while penalizing those that continue to compete primarily on price or isolated feature claims.
Key Demand Drivers Reshaping the Market
The growth trajectory is not accidental. It is being propelled by a set of reinforcing drivers that are changing both what buyers expect and what manufacturers must deliver.
Technological innovation remains the most visible driver, particularly in the areas of low-power wireless connectivity, credential diversity, and hands-free access. The move toward standards-aligned protocols has reduced friction for users who want a lock to function as part of a broader home or facility environment rather than as a standalone gadget. At the same time, biometric modalities and sensor fusion are expanding the definition of convenience and security at the door. Fingerprint recognition has become a familiar baseline, but newer deployments are exploring palm-vein and other liveness-aware modalities that can reduce false acceptance and improve usability in wet, cold, or high-traffic conditions. The commercial implications are significant: biometrics can lower reliance on shared credentials, improve auditability, and support access experiences that feel less like a trade-off between security and convenience. In parallel, ultra-wideband technology is gaining attention for proximity-based, hands-free unlocking that can preserve security while simplifying daily use. When implemented carefully, UWB can support short-range, direction-aware access that avoids some of the spoofing risks associated with simpler proximity methods.
Policy and regulatory developments are becoming an equally important driver, especially because smart locks sit at the intersection of physical security and connected-device risk. Cybersecurity labeling and trust-mark initiatives for wireless smart-home products are pressuring manufacturers to provide clearer baseline assurances around device security, update practices, and vulnerability handling. In parallel, certification bodies are increasingly combining mechanical attack testing with IoT cybersecurity specifications, creating a more unified expectation for what counts as a credible residential smart lock. These frameworks matter commercially because they influence spec-in decisions, insurer and property-manager confidence, and the willingness of installation partners to recommend a product. Compliance is becoming part of the competitive moat: products that proactively align with recognized physical-and-digital standards can shorten sales cycles in cautious segments, while those that lag may face longer evaluation periods or exclusion from certain procurement channels.
Demand-side behavior is shifting as well. In residential settings, consumers are increasingly treating connected access as part of a broader home security and convenience bundle rather than an isolated purchase. This is visible in the way smart lock adoption is influenced by neighboring devices, mobile ecosystem preferences, and the desire for seamless credential sharing with family members, guests, and service providers. In commercial contexts, the driver is different but equally powerful: facility operators want access solutions that reduce rekeying costs, improve audit trails, and support flexible occupancy without major wiring projects. The result is growing interest in battery-powered connected locks, retrofit devices that attach to existing hardware, and access systems that can be managed remotely while preserving offline functionality for resilience. Across both sectors, the emphasis is moving toward total experience—installation effort, day-to-day reliability, battery life, and the quality of the companion app—rather than a narrow set of lock features.
Smart Door Lock Market
Supply chain and cost structures are also reshaping the market. The increasing reliance on advanced modules for connectivity and authentication means that component availability and regional semiconductor dynamics can influence product timing, pricing, and feature roadmaps. This dynamic favors manufacturers that design with flexibility, maintain a disciplined bill of materials, and plan for continuity across multiple sourcing scenarios. It also creates a distinguishing advantage for companies that can balance feature ambition with realistic component strategy. In a market where many products are functionally similar at the point of installation, the ability to deliver consistent availability, stable pricing, and predictable firmware support can become a meaningful commercial differentiator.
Recent product activity illustrates how these drivers are being translated into market-facing moves. One major player released a smart lock built around ultra-wideband technology with hands-free mobile credentialing and standards-aligned thread compatibility, signaling a focus on frictionless access within a specific mobile ecosystem. Around the same period, another manufacturer expanded its portfolio at a major consumer technology event, introducing models certified for both UWB and interoperability standards, which suggests a push to position connected locks as part of a broader smart-home fabric rather than as isolated hardware. Separately, a large consumer-tech brand updated its lock lineup with palm-vein recognition and automatic locking features, underscoring the continuing push toward biometric differentiation and hands-free reliability. These developments are not isolated product launches; they reflect a market that is testing multiple avenues at once—ecosystem alignment, biometric refinement, and installation simplicity—while racing to meet expectations set by regulatory and security normalization.
Competitive Landscape and Strategic Positioning
The competitive field is shaped by a mix of established lock manufacturers, smart-home specialists, retrofit-focused brands, and larger consumer-tech companies extending into access control. Rather than competing solely on lock mechanics, players are differentiating through installation model, ecosystem alignment, biometric design, and the balance between connectivity and offline resilience.
Aqara has positioned itself around interoperability and hands-free convenience, with product designs that emphasize thread-compatible connectivity and mobile credentialing integrated with major platform ecosystems. This approach targets users who want a lock that behaves as part of a coordinated smart-home environment, reducing friction for platform-driven households. August Home has historically leaned into retrofit compatibility and Wi-Fi-based keyless entry, an approach that lowers installation barriers for consumers who want to upgrade existing hardware without replacing the entire lock assembly. Yale and Schlage continue to draw strength from brand trust, broader access-control heritage, and touchscreen or keypad-oriented designs that appeal to buyers prioritizing familiarity, durability, and integration with broader residential and commercial security expectations. Kwikset adds another angle with re-keying technology combined with Wi-Fi and standards-aligned smart locks, appealing to users who value both connected convenience and the ability to manage mechanical key control.
Eufy has carved a distinct position by fusing video and access functions into the lock form factor, combining fingerprint or palm-vein sensing with camera integration. That hybrid approach serves buyers who want visual verification at the door without installing separate devices, though it also raises product complexity and privacy expectations. CANDY HOUSE and igloohome illustrate a different strategic axis: CANDY HOUSE has emphasized fast Bluetooth-based access and tool-free installation, targeting convenience and ease of adoption, while igloohome has focused on offline access control for locks and padlocks, an approach that suits scenarios where internet dependency is undesirable or unreliable. Nuki specializes in retrofit electronic lock conversion with app and fingerprint access, competing on the ability to add connectivity to existing doors without full hardware replacement. Level has pursued a design-forward, “invisible” smart lock concept that integrates into the door aesthetic and supports major platform credentialing, which can be attractive in premium residential and design-sensitive projects.
On the broader manufacturing side, Dreame Technology has used major trade platforms to expand a full smart lock lineup with standards-aligned interoperability and UWB support, indicating a push to compete across feature tiers rather than in a narrow niche. TCL has extended into multi-biometric and fingerprint-based lock series, reinforcing the industry-wide emphasis on authentication variety and automated locking features. Taken together, these players show a market where strategy is increasingly defined by the tension between ecosystem alignment, biometric differentiation, installation simplicity, and offline resilience.
The landscape is evolving along three overlapping directions. First, there is a consolidation tendency among brands that can leverage distribution scale, installer relationships, and platform partnerships to create repeatable go-to-market patterns. Second, there is continued fragmentation in specialized sub-segments where design, offline functionality, or hybrid video-access value propositions can sustain differentiation. Third, new entrants and larger consumer-electronics groups are using smart locks as an entry point into connected home security, which increases competitive intensity but also expands awareness and retail presence. The net effect is a market where winning does not depend on being the largest player in every category, but on choosing a defensible positioning and executing it with disciplined product planning, certification readiness, and ecosystem compatibility.
Forward Outlook: Three Trends Likely to Shape the Next 3–5 Years
The next several years are likely to be defined by a shift from feature competition to trust, integration, and lifecycle competitiveness. Three trends stand out.
First, cybersecurity and physical-security certification will become central commercial requirements rather than optional credentials. As labeling initiatives and unified testing specifications become more familiar to buyers and procurement teams, smart locks that can demonstrate credible security baselines will gain an advantage in both retail and specification channels. This trend will likely raise the entry barrier for low-effort products and reward manufacturers that invest early in secure update pathways, transparent vulnerability handling, and compliance documentation. Commercial opportunity here lies in positioning certification as a selling point for spec-in, insurance-aligned, and multi-family deployments, where risk reduction is part of the purchase rationale.
PW Consulting Health Care Research Center
Second, biometric and hands-free access will broaden, but with a stronger emphasis on reliability, privacy, and contextual appropriateness. Fingerprint and palm-vein methods will continue to expand, especially where they reduce dependence on shared keys or codes and improve auditability. Ultra-wideband and proximity-based access will grow in premium and convenience-oriented segments, but adoption will depend on real-world performance, battery trade-offs, and the ability to avoid false unlocks or usability friction. The commercial opportunity is not simply adding sensors; it is designing access experiences that feel secure without becoming cumbersome, and that can be supported over the product lifecycle with firmware resilience and user-friendly recovery paths.
Third, smart locks will increasingly be evaluated as part of ecosystem and lifecycle economics rather than as isolated hardware purchases. Buyers will weigh platform compatibility, app quality, battery management, installer experience, and long-term software support alongside the lock itself. This creates opportunities for companies that can package hardware with dependable software, clear credential management, and integration support for property managers or platform-driven households. It also introduces risk for products that rely on short-term feature novelty without a credible plan for ongoing updates, compatibility maintenance, or serviceability. In this environment, sustained advantage will come from reducing total friction across purchase, installation, daily use, and long-term management.
Potential risks and uncertainties remain. Regulatory expectations may evolve faster than product roadmaps in some regions, especially where physical and digital certification requirements are harmonized through new specifications or national guidance. Component availability and semiconductor concentration could affect cost stability and launch timing for feature-rich models. Ecosystem dependence may create upside in the short term but can also expose manufacturers to platform policy shifts or competitive substitution if interoperability becomes widespread. Finally, consumer expectations around privacy, data handling, and app transparency will continue to rise, meaning that even technically capable products can lose traction if trust and transparency are not managed carefully.
Strategic Actions for Decision Makers
For manufacturers, the priority is to align product roadmaps with the emerging trust-and-interoperability baseline. That means designing for security documentation, update discipline, and cross-platform compatibility as first-class requirements rather than post-launch additions. It also means choosing biometric and hands-free features based on real usability and reliability rather than novelty, and building supply chain flexibility around connectivity and authentication components. Companies that can combine a clear installation advantage with credible certification readiness and consistent lifecycle support will be better positioned to win in both retail and specification-driven channels.
For investors, the opportunity is to distinguish between companies that are scaling through genuine ecosystem, distribution, and compliance advantages and those that are relying on short-term feature launches or price competition. Due diligence should weigh certification positioning, platform relationships, component strategy, and the durability of the installation model. Businesses that can demonstrate repeatable procurement in residential retrofitting, multi-family, or commercial access modernization—and that can manage security expectations without eroding margin—offer more resilient exposure than those whose growth depends primarily on promotional momentum.
Bike Locks Market
For procurement leaders and property operators, the practical move is to evaluate smart locks as part of an access strategy rather than as discrete hardware purchases. Criteria should include not only locking performance and credential options, but also installation complexity, offline resilience, app management, audit capabilities, and the depth of support for future platform or certification changes. In commercial and multi-family settings, centralized management, fallback behavior, and installer familiarity can matter as much as the marketed feature set. Selecting products that are already aligned with recognized security and interoperability expectations can reduce downstream evaluation risk and simplify future upgrades.
As the market expands toward the 4 billion USD range over the forecast period, the volume of opportunity will increasingly separate from the ease of capturing it. The companies and buyers that benefit most will be those who treat smart locks as a long-term access layer—shaped by security expectations, ecosystem realities, and lifecycle economics—rather than as a one-time convenience purchase. For organizations seeking segmented forecasts, competitive benchmarking, and tailored strategic pathways across product type, application, and region, the full research report provides the deeper data set and scenario detail needed to translate these trends into concrete plans.
For detailed analysis of this topic, please visit the official page: Smart Locks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com