

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Yerba Mate Market 2026: Why a 4.92% CAGR Signals Real Demand Shifts

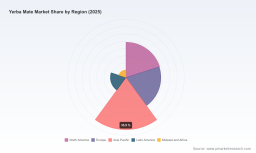
Yerba Mate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The yerba mate market has entered a phase of steady, measured expansion. From 2020 through 2025, total revenue climbed from approximately $150.0 million to $194.0 million, reflecting a compound trajectory that suggests the category is moving beyond niche wellness circles into broader commercial relevance. The forecast period from 2026 to 2032 projects continued growth at a CAGR of 4.92%, with market size expected to reach $269.3 million by the end of the decade. This pace is neither explosive nor stagnant—it signals a maturing category where incremental gains depend increasingly on product innovation, channel expansion, and geographic diversification rather than raw volume alone.
Several structural challenges define the current inflection point. First, price volatility and regulatory intervention in key producing regions have disrupted long-standing cost assumptions. In August 2025, the removal of price controls on yerba mate in Argentina triggered immediate market adjustments, forcing producers and traders to recalibrate pricing models that had been artificially stabilized for years. Second, the category remains highly concentrated among a handful of traditional producers in South America, creating supply chain fragility and limited competitive pressure on product formats. Third, consumer perception in non-native markets still wrestles with familiarity barriers—yerba mate is often viewed through a narrow lens of traditional preparation methods or stimulant alternatives, rather than as a versatile ingredient platform across food, beverage, and personal care applications.
For executives and investors, the implication is clear: the next growth cycle will reward players who navigate regulatory shifts proactively, diversify sourcing and format strategies, and reposition yerba mate beyond its historical consumption patterns. The market is large enough to support specialization, but small enough that execution speed and format innovation will separate winners from complacent incumbents.
Stevia Market
Key Structural Headwinds and Turning Points
The post-control pricing environment in Argentina represents more than a short-term adjustment; it reshapes the economics of production and export. Without administrative price floors, market participants must contend with fluctuating input costs, labor negotiations, and export competitiveness. The National Institute of the Yerba Mate has historically convened stakeholders twice annually to set minimum prices for fresh and dry leaves, but the broader deregulation trend introduces both risk and opportunity. Producers with vertically integrated operations or long-term farm contracts gain margin predictability, while smaller processors may face squeeze during periods of input inflation.
Simultaneously, the category stands at a product format crossroads. Traditional loose-leaf consumption dominates current revenue composition, but powder and extract formats remain comparatively small. This gap represents both a limitation and an untapped pathway. Powdered and concentrated forms enable incorporation into RTD beverages, functional snacks, cosmetic formulations, and dietary supplements—segments where convenience and intake flexibility drive adoption. The challenge lies in maintaining sensory authenticity and perceived quality while adapting production processes for scalable extraction and stabilization.
A third turning point involves geographic perception and export positioning. Latin American producers have long supplied traditional markets, but international expansion requires navigating certification expectations, sustainability narratives, and local regulatory frameworks for novel food ingredients. The recent FAO recognition of shade-grown yerba mate cultivation in Paraná, Brazil as a Globally Important Agricultural Heritage System provides a credible sustainability anchor that can be leveraged in premium positioning and export marketing. Yet translating heritage recognition into commercial advantage requires consistent storytelling, third-party verification, and distribution partnerships that understand how to communicate complex sourcing claims to end consumers.
Key Drivers Shaping Market Evolution
Technological and Format Innovation
Format innovation is emerging as a primary lever for category expansion. The shift from loose-leaf dominance toward powder, extracts, and ready-to-drink formulations reflects broader beverage and functional ingredient trends: convenience, dose consistency, and cross-category integration. Powder formats enable easier incorporation into dairy alternatives, baking mixes, and instant beverage bases, while extracts and concentrates open pathways into dietary supplements and cosmetic actives. These formats also support brand experimentation with flavor layering, sweetness reduction, and functional claim integration.
Recent product launches illustrate how incumbents and new entrants are using format and flavor innovation to capture convenience-oriented consumers. In February 2026, a leading North American organic yerba mate brand introduced a refreshed sparkling line with a lower-sugar mint variant, alongside seasonal limited-edition flavors positioned for convenience channel exclusivity. These moves signal a deliberate push into RTD sparkling categories where sugar reduction and channel-specific flavor differentiation are becoming table stakes. For manufacturers, the lesson is that format adaptation is not merely about processing capability; it is about aligning sensory profiles, packaging, and distribution format with the consumption occasion the target segment expects.
Regulatory and Policy Dynamics
Policy shifts in producing countries are reshaping cost structures and competitive positioning. The August 2025 removal of price controls in Argentina altered the pricing baseline for fresh and dry leaves, prompting market participants to revisit procurement strategies, inventory timing, and export pricing. While deregulation introduces volatility, it also rewards operational discipline. Companies with transparent cost models, long-term supplier relationships, and flexible contract structures can absorb price fluctuations more effectively than those relying on administrative stability.
Beyond national price policy, institutional frameworks continue to shape market legitimacy and export readiness. The National Institute of the Yerba Mate in Argentina coordinates production, processing, marketing, and consumption promotion, and its periodic stakeholder convenings influence minimum pricing expectations and sector coordination. In parallel, international recognition of sustainable cultivation systems—such as the FAO designation for shade-grown practices in Paraná—provides a policy-adjacent signal that can strengthen premium positioning and facilitate entry into markets where sustainability credentials influence procurement decisions. For market participants, regulatory literacy is no longer optional; it is a commercial capability that affects sourcing, compliance, and brand narrative.
Demand-Side Shifts in Consumer and Corporate Behavior
Consumer demand is gradually broadening the category’s application footprint. In food and beverage, yerba mate is increasingly treated as a functional base rather than a standalone traditional drink. This shift supports use in energy-adjacent beverages, wellness teas, flavored sparkling formats, and mixed-format consumption occasions. The functional beverage segment, in particular, benefits from yerba mate’s stimulant profile and cultural association with sustained energy, but growth depends on reducing barriers related to taste familiarity and preparation complexity.
Corporate procurement behavior is also evolving. As brands seek ingredient diversification and natural stimulant alternatives, yerba mate appears in portfolio discussions alongside tea, coffee, and botanical adaptogens. Dietary supplement and cosmetic applications remain comparatively small in absolute terms, but they represent high-margin pathways where concentrated extracts and standardized formats can command premium pricing. The strategic opportunity lies in matching format and certification to the expectations of each application segment rather than treating yerba mate as a single product category with uniform positioning.
Supply Chain and Cost Structure Dynamics
Yerba mate’s supply chain remains anchored in South American cultivation, with Argentina, Brazil, and Paraguay playing central roles. This geographic concentration creates both efficiency advantages and vulnerability. Production relies on agricultural cycles, labor coordination, and processing infrastructure that can be sensitive to weather variability, labor negotiations, and export logistics. The historical use of minimum price mechanisms reflects the sector’s need for coordination between farmworkers, government officials, and industry representatives, and the evolving policy environment means that pricing predictability must increasingly be engineered through contracts and vertical integration rather than administrative guidance.
Cost structures are also influenced by the premiumization pathway. Organic certification, shade-grown cultivation, and regenerative sourcing narratives add value but also raise production and verification costs. Brands that successfully institutionalize these claims can differentiate in export markets and premium retail channels, but they must maintain consistency across batches, seasons, and sourcing origins. For buyers and distributors, this creates a due diligence requirement: provenance claims need traceable documentation, and premium pricing needs demonstrable quality or sustainability differentiation that survives retailer and consumer scrutiny.
Competitive Landscape and Strategic Positioning
The competitive field is anchored by established South American producers alongside a growing set of North American and cross-border brands focused on organic, RTD, and premium-positioned products. Traditional manufacturers maintain strong domestic and export presence in loose-leaf and processed formats, while newer market participants compete through organic certification, regenerative sourcing narratives, flavor innovation, and channel-specific RTD distribution. This dual structure creates a differentiated landscape where incumbents leverage scale, long-standing farm relationships, and broad distribution, and challengers compete on format modernity, ingredient storytelling, and convenience-channel execution.
Leading producers in Argentina and Uruguay continue to benefit from deep-rooted processing expertise, established export channels, and brand recognition across traditional markets. Their strategic advantage lies in supply scale, processing flexibility across loose-leaf and milled formats, and relationships with institutional bodies that influence sector coordination. Several of these manufacturers also operate across multiple brands and private-label arrangements, allowing them to serve both consumer-facing and B2B demand. Their challenge is to extend into newer format segments without eroding core brand equity or compromising cost discipline during periods of input price volatility.
North American and export-oriented brands are pursuing a different playbook. Emphasis on organic certification, shade-grown sourcing, lower-sugar RTD formulations, and seasonal or channel-exclusive flavor launches reflects a strategy built around convenience retail, wellness positioning, and differentiation through ingredient claims. By targeting c-stores, convenience chains, and specialty channels with tailored SKUs, these brands aim to capture consumption occasions that traditional loose-leaf formats do not easily address. Their differentiation depends on consistent execution of sustainability narratives, flavor innovation cadence, and retail relationships that support rapid shelf turnover and limited-edition visibility.
Market Structure Evolution: Consolidation, Fragmentation, and New Entry
Market concentration remains notable, with the top three competitors estimated to hold roughly 40% of revenue and the top five closer to 50%. This level of concentration indicates that scale advantages and brand heritage matter, but it also leaves substantial room for specialized players in organic, RTD, powder, and premium supplement segments. The landscape is likely to evolve through a combination of selective consolidation among regional processors and continued fragmentation in consumer-facing formats, where brand, flavor, and channel strategy matter more than raw production scale.
New entrants are most likely to succeed where they combine format innovation with credible sourcing claims and channel-specific distribution. RTD sparkling, functional botanical blends, and standardized extract supply for supplement and cosmetic use represent spaces where smaller, agile players can build defensible positions without directly challenging traditional loose-leaf incumbents. At the same time, established producers may pursue acquisitions, brand extensions, or B2B ingredient partnerships to accelerate format diversification and reduce reliance on traditional consumption patterns. The strategic question for all players is whether to compete on heritage and scale, on modern format and wellness positioning, or on ingredient supply and B2B relationships—because each path requires a different operating model.
Forward Outlook: Three Strategic Trends for 2027–2032
Trend 1: Format Diversification as the Primary Growth Engine
Over the next several years, revenue growth is likely to be increasingly driven by non-loose-leaf formats, particularly powder, extracts, and RTD beverage expressions. These formats align with convenience, functional integration, and cross-category usage, and they enable yerba mate to appear in product portfolios beyond traditional brewing. The commercial implication is that producers and brands should treat format capability as a strategic asset, not a downstream processing decision. Investment in extraction stability, flavor compatibility, packaging formats, and application testing will determine which players can credibly serve beverage, supplement, and personal care demand without compromising sensory quality or cost efficiency.
The opportunity is not uniform across formats. RTD and sparkling segments offer high visibility and rapid consumer feedback, but they also demand consistent shelf performance, sugar-reduction strategies, and channel-appropriate flavor portfolios. Powder and extract segments offer B2B scalability and ingredient flexibility, but they require specification support, batch consistency, and application knowledge that downstream manufacturers can rely on. Brands that can bridge consumer-facing appeal with ingredient reliability will capture value across both retail and B2B pathways.
Trend 2: Sustainability and Heritage Narratives as Commercial Signals
Sustainability claims are moving from marketing add-ons to commercial prerequisites in several export and premium retail contexts. The FAO recognition of shade-grown cultivation in Paraná provides a concrete reference point for heritage-based sustainability positioning, and similar institutional acknowledgments can strengthen credibility when paired with traceable sourcing and verifiable practice standards. For exporters and brand owners, the strategic value lies in converting recognition into repeatable storytelling, certification consistency, and retailer-ready documentation that survives procurement review.
This trend also introduces a risk dimension. Narrative inflation without operational backing can erode trust quickly, especially in categories where consumers and retailers increasingly scrutinize ingredient provenance. Companies that embed sustainability into sourcing contracts, farmer support programs, and batch-level traceability will be better positioned to sustain premium pricing and export access than those relying primarily on label claims. The trend therefore favors participants who can make sustainability measurable and auditable rather than purely aspirational.
Trend 3: Pricing Detachment and Procurement Discipline
As regulatory price controls recede in key producing markets, the category will increasingly price through market mechanisms, contracts, and vertical coordination. This shift rewards procurement discipline, inventory timing, and supplier relationship depth. For manufacturers and distributors, the commercial implication is that cost planning must account for periodic volatility rather than assume administrative stability. Hedging through forward contracts, diversified sourcing, or processing flexibility can protect margin during adjustment periods, while overly rigid pricing architectures may leave players exposed when input costs move quickly.
This trend also creates a competitive filter. Players with strong farm relationships, transparent cost structures, and flexible processing can adapt faster and preserve export competitiveness. Those without such capabilities may face margin pressure or reduced agility in responding to demand shifts. For buyers in non-producing markets, the trend underscores the importance of supplier diversification and specification lock-in, especially when sourcing for premium or certified product lines where consistency is a purchase criterion.
Strategic Recommendations for Decision Makers
For manufacturers and brand owners, the priority is to align format strategy with consumption occasion rather than treating product forms as interchangeable. Loose-leaf will likely remain a core revenue base, but growth leverage increasingly sits in powder, extract, and RTD applications where convenience and functional integration drive adoption. Leaders should evaluate processing capabilities against target formats, define flavor and sweetness strategies that match channel expectations, and build specification support for B2B customers who need consistency and application guidance. Where sustainability or heritage claims are part of the brand architecture, those claims should be backed by traceable sourcing and documentation that can withstand retailer and consumer scrutiny.
For investors, the most relevant question is whether a target’s competitive advantage is durable under market pricing and format competition. Vertical integration, long-term farm relationships, and flexible processing provide resilience when input prices fluctuate. Strong brand positioning in organic, RTD, or premium segments can support margin even in a moderately concentrated market, but only if innovation cadence and channel execution remain consistent. Due diligence should therefore assess format pipeline, sourcing stability, certification credibility, and distribution access rather than relying solely on historical revenue trajectory or brand recognition.
Matcha Tea Market
For procurement and supply chain leaders, diversification and specification discipline are the key safeguards. Relying on a single sourcing origin or a single price mechanism increases exposure to volatility, especially as regulatory frameworks evolve in producing regions. Defining clear quality specifications, verifying certification and traceability documentation, and establishing backup sourcing options can reduce disruption risk while preserving access to premium or certified material. Procurement strategies should also consider format requirements early, because powder, extract, and loose-leaf sourcing involve different supplier capabilities, quality controls, and cost structures.
For organizations seeking to move from broad market awareness to precise segmentation, pricing strategy, and channel-specific planning, a comprehensive research dossier can help translate these trends into targeted decisions. Detailed breakdowns by region, type, application, concentration metrics, and company-level tracking provide the granularity needed to prioritize investments, evaluate competitors, and stress-test sourcing and pricing assumptions under different regulatory and demand scenarios. Access to that level of structured intelligence allows decision makers to convert category outlooks into executable plans with clearer risk boundaries and more realistic growth pathways.
The yerba mate market is positioned for steady, format-led expansion through the end of the decade, but the distribution of value will depend on how effectively companies manage pricing volatility, credibility of sustainability claims, and the operational demands of new product forms. The players who treat format innovation, sourcing discipline, and channel-specific positioning as interconnected strategic choices—rather than isolated product decisions—are most likely to capture disproportionate share of the next growth cycle.
PW Consulting Health Care Research Center
For detailed analysis of this topic, please visit the official page: Yerba Mate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com