

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Power Tool Accessories Market: Why 5.8% CAGR Drives $297M by 2032

Strategic Trends and Commercial Opportunities in the Power Tool Accessories Market
Market Overview and Structural Challenges
Market Trajectory and Core Dynamics
The power tool accessories market has demonstrated consistent expansion over the past five years, transitioning from a mature, replacement-driven segment to a growth market influenced by tool electrification, application specialization, and tightened performance expectations. Total market revenue rose from approximately 161.5 million USD in 2020 to roughly 202.5 million USD in 2025, and forward projections indicate a continued upward path toward just under 300 million USD by 2032, reflecting a compound annual growth rate of 5.8 percent across the forecast window. This trajectory signals a market that is no longer solely dependent on consumables replacement cycles. Instead, the growth is increasingly shaped by accessory innovation, platform compatibility requirements, and the expansion of professional and semi-professional user bases that prioritize durability, precision, and productivity gains.
The segment has also developed clear concentration patterns that influence pricing power, innovation pacing, and channel relationships. A relatively small group of leading players commands a disproportionate share of revenue, which creates both stability and pressure for the remainder of the competitive field. High concentration tends to reward companies with strong brand equity, broad accessory portfolios, and reliable distribution networks, while making it harder for narrower players to compete on visibility alone. For decision-makers, this concentration means that strategic differentiation must come from features, materials, compatibility ecosystems, or service models rather than simple market entry.
Key Challenges and Inflection Points
Despite the favorable growth outlook, the industry faces several structural challenges that are reshaping how manufacturers and buyers think about accessories. One of the most pressing issues is the balance between performance and cost pressures. Accessory buyers increasingly expect longer service life, better cutting efficiency, and reduced tool vibration, yet raw material volatility and processing complexity can make premium formulations difficult to scale profitably. Companies that rely on traditional materials or legacy geometries are seeing margin compression as users become more selective and price-sensitive, particularly in price-conscious channels. This creates a tension where performance upgrades must be justified through measurable productivity improvements rather than incremental claims.
A second challenge is the growing complexity of compatibility and platform lock-in. As cordless tool platforms continue to expand, accessory design must account for torque profiles, battery ecosystems, shank specifications, and interface variations. Accessories that are not optimized for the tool’s operating conditions can reduce performance or create safety concerns. This complexity benefits large platforms with broad accessory ranges, but it also raises the stakes for smaller manufacturers that need to ensure fit, performance, and reliability across multiple tool models. The result is a market where technical coordination between tools and accessories is becoming as important as the accessory product itself.
A third inflection point is regulatory and safety standardization. Industry associations and certification bodies have been tightening expectations around performance consistency, durability, and safe usage under demanding conditions. These developments help protect end users and strengthen confidence in professional-grade accessories, but they also raise compliance costs and can slow time-to-market for new designs. Manufacturers that treat safety and certification as a strategic capability rather than a back-office requirement are better positioned to operate in regulated channels, especially where institutional buyers, rental fleets, or industrial customers require documented performance assurance.
Taken together, these challenges suggest that the market is entering a phase where growth will be earned through technical relevance and trust. The companies that can align material efficiency, platform compatibility, and compliance readiness with user-facing performance benefits are likely to capture a larger share of the expanding market, while those that compete only on generic specifications may face margin erosion and substitution pressure.
Core Drivers Shaping Market Change
Technology Innovation and Material Advancement
Material engineering and design optimization remain central to competitive advantage in power tool accessories. Improvements in carbide formulations, hardened steel treatments, coatings, and tooth geometry are enabling accessories to cut faster, last longer, and maintain accuracy over more operations. In practical terms, these gains matter because they reduce downtime, lower the frequency of replacement, and improve finishing quality. For professional users, that translates into measurable productivity rather than just product attributes. Innovation is also moving beyond raw hardness toward application-specific performance, with designs tailored to particular materials, cut styles, drilling conditions, or tool interfaces.
A notable example of how material strategy is evolving comes from the broader industry’s focus on cost and sustainability. One leading manufacturer has pursued recycling of hard metal tips recovered from grinding waste in order to lower raw material costs for accessories, illustrating how material recovery can support both economics and supply continuity. This approach highlights a broader trend: high-performance accessories are increasingly dependent on managing input costs and material availability as carefully as they are dependent on design quality. Companies that integrate material recovery, waste reduction, or alternative sourcing into their development processes may be able to sustain premium positioning while protecting margins.
Power Tools Market
Policy, Safety, and Certification Environment
Regulatory and industry-led standards are becoming a more visible force in the accessories market. Updated safety guidelines for power tool accessories have been issued by industry bodies, reinforcing expectations around consistency, safe operation, and performance validation. Alongside this, certification and testing organizations continue to evaluate accessories for safety, durability, and reliability, and trade associations are maintaining member compliance expectations for manufacturers. This framework is not simply procedural. In professional and institutional procurement, documented compliance can be a prerequisite for inclusion in bids, rental fleets, or job-site supply programs.
For companies, the implication is that standards are increasingly part of the value proposition. Accessory designs that are developed with clear testing pathways and compliance documentation can gain advantage in channels where risk management and accountability are prioritized. Conversely, products that are launched without adequate attention to certification or performance validation may face slower adoption in professional environments. The trend also rewards manufacturers who can communicate standardized performance clearly, because procurement teams and field supervisors often need evidence that an accessory meets the demands of heavy or repetitive use.
Demand-Side Shifts in User Behavior
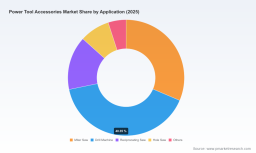
The demand profile for power tool accessories is being reshaped by the continued shift toward cordless tool platforms and the expansion of user groups beyond traditional trades. Cordless adoption has broadened access to mobile, on-site work and has increased the importance of accessories that perform reliably under variable conditions. At the same time, users are becoming more discerning about fit and productivity. Drill-related applications remain especially significant in the broader usage landscape, reflecting the foundational role of drilling in construction, assembly, maintenance, and renovation activity. Miter saw applications and reciprocating saw setups also represent meaningful demand centers, and the accessory requirements in these applications often emphasize precision, controlled cutting, and blade life.
Another demand-side shift is the growing expectation that accessories support efficiency rather than merely perform a function. Users want accessories that help reduce rework, improve consistency, and minimize interruption. This is particularly relevant where time pressure, labor costs, and project schedules are high. As a result, marketing and product development are increasingly judged by real-world outcomes such as cleaner cuts, longer intervals between changes, less tool load, and easier blade or bit changes. Buyers are also more attentive to whether accessories are designed for specific tool platforms, since mismatched accessories can lead to reduced performance or premature wear.
Supply Chain and Cost Structure Pressures
Cost structures in the accessories market are being influenced by raw material availability, manufacturing complexity, and the need to scale performance improvements without sacrificing margin. The emphasis on hard metals, specialized steel, and engineered coatings means that supply disruptions or price swings can affect both cost and product consistency. In response, some companies are focusing on process efficiency, material recovery, and portfolio rationalization to keep production economically viable while preserving performance. This is not just a short-term cost issue; it is becoming an important strategic capability.
Supply chain stability also affects innovation speed. Companies that can develop, test, and launch accessory products efficiently are better positioned to respond to changing application needs and platform expansions. The most effective players tend to balance a core range of high-volume accessories with targeted specialty products that serve higher-value applications. That combination helps smooth demand cycles while still capturing premium segments where users are willing to pay for reliability and performance. For market participants, the operational goal is to link material strategy, manufacturing scale, and product differentiation in a way that supports both volume and value.
Competitive Landscape and Leading Strategies
Strategic Positioning of Major Players
The market is shaped by a group of well-established manufacturers that compete through brand strength, product breadth, platform integration, and professional-grade positioning. Bosch Power Tools offers a broad range of cordless and corded tools and accessories, including drill bits, hole saws, saw blades, and fasteners aimed at professional trades. Its scale and platform reach give it the ability to align accessories closely with tool ecosystems and to introduce new products in coordinated waves. In June 2026, the company expanded its North American offering with 39 new tools and accessories designed to extend its 18V cordless platform, an example of how accessory portfolios can be used to reinforce a tool system strategy and deepen user commitment.
Stanley Black & Decker competes through its tools portfolio, offering accessories such as drill bits, saw blades, and impact driver bits under established brands. Its strength lies in a wide consumer and professional presence, which supports visibility across multiple channels and price points. Makita Corporation has built a strong identity around cordless power tools with dedicated accessories, including drill bits, hole saws, and abrasive products. This focus on system coherence helps the company emphasize compatibility and reliability in cordless workflows. Techtronic Industries, through its branded portfolio, supplies accessories for professional and consumer segments, with offerings spanning drill bits, saw blades, and hole saws. Its multi-brand structure allows it to address different customer segments while leveraging shared development and supply capabilities.
Hilti Corporation remains strongly associated with professional-grade accessories for fasteners, drilling, and demolition applications. Its positioning is particularly relevant in demanding job-site environments where performance, support, and reliability are critical purchase criteria. Apex Tool Group and Snap-on Incorporated both maintain strong professional orientation, with Snap-on especially focused on industrial and automotive applications through bits and sockets. These companies illustrate how professional trust, application specificity, and service support can be just as important as product specifications.
PW Consulting Health Care Research Center
A different competitive angle is visible in companies that emphasize reusable or recyclable accessory design. EAB Tool Company, for example, produces exchangeable and recyclable accessories such as circular saw blades, oscillating tool accessories, hole saws, and drill bits. This approach appeals to users and organizations seeking to reduce waste and manage consumable costs over time. Lenox, Diablo Tools, and related suppliers similarly focus on high-performance cutting and drilling accessories, often with an emphasis on carbide-tipped construction and application-specific performance. Together, these players show that differentiation is increasingly built around material performance, application fit, and lifecycle economics rather than brand alone.
Market Evolution and Consolidation Dynamics
The competitive structure is evolving along a path that rewards scale, portfolio breadth, and technical integration, while also creating room for specialized entrants that solve a narrow problem exceptionally well. Large players benefit from the ability to invest in multiple accessory categories, align products with tool platforms, and supply both professional and broader user markets. Their advantage is not simply size; it is the capacity to offer a coordinated accessory ecosystem that reduces compatibility risk for buyers and supports repeat purchasing across tool lines.
At the same time, market concentration tends to encourage strategic consolidation and selective partnership activity. Smaller manufacturers may find growth easier by focusing on high-performance niches, unique materials, or application-specific designs rather than trying to match full-portfolio breadth. New entrants that can bring a compelling technical advantage, stronger sustainability characteristics, or better cost-quality balance may gain traction in specific channels, especially where existing offerings are perceived as incremental. However, entering the market successfully increasingly requires serious attention to compliance, testing, and platform compatibility, since these are now central to professional adoption.
A broader trend is the growing importance of brand trust in safety-critical and high-use environments. In rental, industrial, and trade contexts, buyers often prefer accessories from manufacturers with established reputations for consistency and support. This does not eliminate competition, but it does raise the threshold for credible market participation. Companies that can demonstrate dependable performance, clear documentation, and alignment with recognized standards are better positioned to secure durable demand, while those that compete primarily on short-term price may find it harder to build recurring relationships in professional channels.
Future Outlook: Trends to Watch Over the Next 3 to 5 Years
Trend 1: Platform-Integrated Accessories as a Standard Expectation
Over the next several years, accessories will be increasingly judged on their fit within cordless and corded tool ecosystems rather than on isolated specifications. Users and procurement teams are likely to favor accessories that are designed for specific torque ranges, battery platforms, and tool interfaces, because those designs tend to deliver more consistent performance and longer service life. This will reinforce the strategic value of platform-aligned product development and create stronger incentives for manufacturers to coordinate accessory launches with tool updates. The commercial opportunity lies in building accessory lines that function as part of a complete workflow solution, improving user retention and reducing the risk of substitution by mismatched alternatives.
Worldwide Cutting Tool and Machine Tool Accessory Market
Trend 2: Performance with Lower Waste and Lower Input Exposure
Material efficiency will become a more visible competitive attribute. As raw material cost exposure and sustainability expectations rise, manufacturers that can improve performance while reducing material waste or dependency on scarce inputs will have an advantage. This includes better geometry design, more efficient manufacturing processes, and approaches that recover or reuse valuable processing materials. In practical terms, this trend creates opportunities for products that combine durability with a smaller lifecycle footprint, particularly where users are sensitive to replacement frequency and total cost of ownership. Companies that treat material strategy as a core design priority rather than a sourcing detail will be better positioned to maintain margins while meeting evolving buyer expectations.
Trend 3: Compliance and Documentation as Purchase Criteria
Safety standards, certification processes, and industry-led compliance expectations are likely to remain a meaningful influence on purchasing, especially in professional, institutional, and rental channels. As these requirements become more familiar to buyers, documented performance and safety validation may move from being a baseline requirement to a differentiator. Products that can clearly demonstrate consistent performance under testing regimes and meet recognized standards will have an easier path into demanding applications. The risk for manufacturers is that compliance becomes a late-stage checkpoint rather than a design input, delaying launches and limiting channel access. The opportunity is to make standards alignment part of the product architecture, so that compliance strengthens credibility instead of simply adding cost.
Strategic Actions for Decision-Makers
For Manufacturers
Manufacturers should prioritize accessories that solve specific workflow problems rather than adding generic SKUs. That means focusing development on durability, application fit, platform compatibility, and user convenience in high-frequency tasks. Brands with strong professional credibility should consider expanding their accessory ecosystem in lockstep with tool platform updates, since coordinated launches can reinforce system loyalty and increase attachment rates. At the same time, companies should evaluate material sourcing and recovery strategies as part of long-term cost planning, particularly for hard-metal-dependent products where input exposure can affect both price and availability.
- Invest in application-specific designs that improve measurable outcomes such as cut quality, run time, and replacement intervals.
- Align accessory development with tool platform roadmaps to reduce compatibility risk and strengthen ecosystem value.
- Build compliance, testing, and documentation into product development to support professional and institutional demand.
- Explore material efficiency measures that protect cost structure without compromising performance.
For Investors
Investors evaluating this market should pay close attention to companies that combine portfolio breadth with technical differentiation and credible compliance capabilities. The most durable revenue models in this space tend to come from brands that can stay relevant across professional and broader user segments while maintaining consistent accessory demand through tool platform loyalty. Watch for signs that a company can manage cost exposure, improve product performance in a way users notice, and expand into higher-value applications without diluting brand positioning. Also monitor the extent to which a company can maintain product launch cadence and channel access, since these factors strongly influence market share over time.
- Assess whether a company’s accessory portfolio is aligned with high-usage applications and platform-driven demand.
- Look for evidence of margin discipline through material strategy, manufacturing efficiency, or portfolio focus.
- Consider whether the company has the credibility and compliance readiness to compete in professional channels.
- Track launch consistency and ecosystem coordination as indicators of future share resilience.
For Procurement and Channel Leaders
Procurement teams and channel operators should evaluate accessories not only by unit price but by total cost of ownership, compatibility, and the availability of documented performance assurance. In higher-use environments, the cost of downtime, rework, and premature replacement can outweigh small price differences between products. It is also wise to standardize around accessories that match the tool platforms in use, because mismatched products can create hidden performance and reliability costs. Where safety and compliance matter, prioritize suppliers that can provide clear testing and standards alignment, since this reduces operational risk in demanding job-site or industrial settings.
- Evaluate accessories based on service life, application fit, and workflow impact rather than sticker price alone.
- Standardize around accessories designed for the tool platforms in active use.
- Prioritize suppliers with demonstrated compliance and performance documentation in professional contexts.
- Track field performance and replacement cycles to identify where premium accessories deliver real savings.
Closing Perspective
The power tool accessories market is expanding within a structure that increasingly rewards technical relevance, compatibility, and trust. Growth to the end of the decade and beyond is supported by broader tool adoption, ongoing material and design improvements, and continued demand from professional and semi-professional users who value productivity and reliability. At the same time, the market is becoming more demanding in terms of platform fit, compliance readiness, and cost management. That combination creates opportunities for companies that can integrate performance, economics, and standards into a coherent strategy, while exposing those that rely on undifferentiated product lines or short-term pricing tactics.
For organizations making decisions in this space, the most useful next step is to connect broad market direction with detailed asset-level insight: which applications, accessory types, channels, and regional dynamics are shaping demand in a specific business context. Deeper segmentation data, company-level scenario analysis, and tailored strategy recommendations can help turn these market-level trends into precise action plans. Readers seeking that level of detail can explore the full PW Consulting research report for comprehensive segmentation, competitive benchmarking, and forward-looking guidance tailored to specific strategic objectives.
For detailed analysis of this topic, please visit the official page: Power Tool Accessories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com