

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Metformin Hydrochloride Market: The 6.3% CAGR Shift Reshaping Diabetes Care Through 2032

Metformin Hydrochloride Market: Strategic Trends and Commercial Opportunities Through 2032
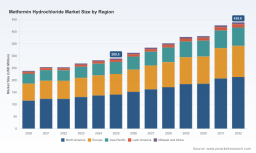
The global Metformin Hydrochloride market presents a compelling case study in mature therapeutic sectors navigating structural transition. Valued at approximately USD 289.5 million in 2025, the market has demonstrated steady growth from its 2020 baseline, reaching an expected USD 438.6 million by 2032. This trajectory reflects a compound annual growth rate of 6.3 percent over the forecast period spanning 2026 through 2032. Such figures underscore a sector that remains fundamentally sound while facing evolving competitive and regulatory pressures. The market's resilience stems from metformin's entrenched position as a first-line therapy, yet the growth narrative is increasingly shaped by formulation innovation, geographic demand shifts, and intensifying generic competition rather than pure volume expansion.
For executive decision-makers, understanding this market requires looking beyond headline revenue figures. The value distribution reveals distinct concentration patterns and therapeutic dependencies that shape strategic options. North America accounts for the largest regional share, followed by Europe, with Asia Pacific representing a smaller but increasingly dynamic segment. The immediate release formulation dominates the product landscape, while extended release variants capture a meaningful secondary position. Therapeutic application remains heavily anchored in Type 2 Diabetes Mellitus management, with polycystic ovary syndrome and other indications comprising the remainder. This structural profile suggests that growth opportunities lie less in unseating the core diabetes indication and more in expanding into adjacent therapeutic areas, optimizing delivery formats, and capturing value in emerging markets where prevalence rates continue to climb.
The competitive environment reflects pronounced concentration, with the top three manufacturers commanding over two-thirds of market revenue and the top five firms controlling nearly four-fifths of total sales. Such concentration indicates high barriers to entry, established supply chain relationships, and manufacturing scale advantages that favor incumbents. However, the presence of multiple certified producers across China and India, combined with regulatory tailwinds enabling continued generic approvals, suggests that competitive dynamics remain fluid beneath the surface. Companies that can balance scale efficiency with regulatory agility and formulation differentiation are best positioned to capture disproportionate value as the market evolves.
Market Landscape and Core Challenges
Navigating a Mature but Shifting Terrain
The metformin hydrochloride sector operates at the intersection of established clinical utility and evolving commercial realities. While demand fundamentals remain robust, several structural challenges are reshaping how value is created and captured. Recognizing these constraints is essential for developing strategies that avoid margin compression and instead target sustainable competitive advantage.
Challenge One: Sustained Generic Price Erosion and Reimbursement Pressure
Metformin hydrochloride generics operate in an environment of intense price competition across major markets. Reimbursement and formulary pressures continue to compress margins for manufacturers and suppliers, particularly in regions where multiple therapeutically equivalent products compete for the same patient populations. This dynamic rewards operators with lowest-cost production profiles, efficient distribution networks, and strong relationships with payers and pharmacy benefit managers. Companies that rely on commoditized positioning without clear differentiation face persistent headwinds, as price erosion outpaces volume growth in several mature markets. The strategic implication is clear: scale efficiency alone is no longer sufficient, and manufacturers must actively manage formulary positioning, supply chain economics, and customer segmentation to protect profitability.
Challenge Two: Regulatory Complexity Around Impurity Management and Quality Assurance
Ongoing regulatory requirements around nitrosamine impurity monitoring and reformulation remain active compliance priorities for all metformin hydrochloride manufacturers. FDA guidance continues to emphasize stability testing, risk assessment, and post-marketing surveillance as part of manufacturing oversight. Multiple manufacturers have addressed impurity concerns through voluntary recalls and updated testing protocols, reflecting an industry-wide focus on quality consistency and regulatory alignment. For market participants, this creates a dual imperative. Compliance is non-negotiable, yet it also represents a competitive differentiator. Manufacturers that invest in robust quality systems, transparent testing practices, and proactive regulatory engagement can reduce supply interruption risk while building trust with buyers who increasingly prioritize supply security alongside cost considerations.
Challenge Three: Balancing Volume Growth with Margin Preservation
The market's growth trajectory implies expanding demand, but translating volume increases into sustainable profitability requires deliberate strategy. Generic competition, reimbursement dynamics, and the concentration of market share among leading producers mean that new entrants and smaller suppliers must identify niches where they can command preferential positioning. This might include specialized extended release formats, particular regional supply roles, or value-added services that reduce total cost of ownership for buyers. The broader challenge is avoiding the trap of competing solely on price in a market where price leadership is increasingly contested by operators with deep manufacturing infrastructure and multi-market clearance.
Key Growth Drivers and Strategic Inflection Points
Formulation Innovation and Combination Therapy Dynamics
Innovation in metformin delivery and combination products continues to shape demand patterns and competitive positioning. Extended release formulations provide an important alternative to immediate release products, offering tolerability advantages and dosing convenience that can influence prescriber preference and patient adherence. Recent product launches illustrate this direction. In March 2026, Lupin Pharmaceuticals introduced generic dapagliflozin and metformin hydrochloride extended-release tablets in the United States following FDA approval, reflecting the market's move toward combination therapies that pair metformin with newer antidiabetic agents. Similarly, in June 2026, Apotex Corp. launched sitagliptin and sitagliptin/metformin hydrochloride tablets eligible for 180-day shared exclusivity, demonstrating how formulation strategy and regulatory timing can create temporary competitive windows. These developments indicate that value creation is increasingly tied to combination regimens, differentiated release profiles, and the ability to navigate exclusivity and approval pathways efficiently.
Regulatory Stability Enabling Continued Generic Access
Regulatory clarity around the availability of certain metformin formulations has supported continued generic approvals and market access. In March 2025, the FDA determined that metformin hydrochloride oral solution has not been withdrawn from sale for safety or effectiveness reasons, enabling continued generic approvals and preserving product variety in the market. This determination is significant because it reinforces the regulatory foundation for a broader range of delivery formats and reduces uncertainty for manufacturers planning formulation pipelines and market entry strategies. For decision-makers, such clarity lowers execution risk and supports long-term planning around product portfolios, capacity allocation, and regional launch sequencing.
Stable Input Economics and Supply Chain Resilience
API production economics for metformin hydrochloride have benefited from stable precursor pricing for key raw materials such as dimethylamine and cyanoguanidine, with no supply disruptions reported in 2026. This input stability supports more predictable manufacturing cost structures and allows producers to focus on operational efficiency, quality systems, and capacity optimization rather than absorbing volatility from raw material markets. For buyers and manufacturers alike, stable input costs reduce one layer of uncertainty and shift competitive emphasis toward execution quality, regulatory compliance, and commercial agility. The implication is that margin dynamics in the near term will be driven more by competitive strategy and pricing discipline than by raw material shocks, making operational excellence a primary source of differentiation.
Geographic Demand Evolution and Emerging Market Potential
Demand growth is increasingly influenced by geographic variation in disease prevalence, healthcare access, and generic penetration. While established markets continue to represent the largest revenue pools, emerging regions offer expansion potential as diagnosis rates improve, treatment guidelines broaden, and affordable generic supply becomes more accessible. Asia Pacific, in particular, reflects a dynamic where large patient populations, growing healthcare infrastructure, and competitive manufacturing presence intersect. Companies that build regional supply relationships, align product offerings with local formulary requirements, and invest in registration and compliance capabilities can position themselves to capture demand that outpaces mature market growth rates. This geographic dimension is not merely about sales expansion; it is about building durable market access in regions where long-term prevalence trends support sustained demand.
Competitive Landscape and Strategic Positioning
Scale, Certification, and Geographic Reach as Core Advantages
The competitive field features manufacturers with strong API production capabilities, regulatory certifications, and established export channels. Leading participants have built positions rooted in scale, certification, and supply reliability. Several Chinese and Indian producers operate FDA-approved and GMP-certified facilities, with some reporting substantial annual output capacity and dominant global supply shares. These characteristics matter because metformin hydrochloride remains a high-volume, quality-sensitive product where regulatory status and supply consistency directly influence buyer confidence. Manufacturers that combine scale with certified quality systems can secure long-term supply agreements and maintain preferred positions in global procurement processes.
Differentiation Through Combination Products and Formulation Expertise
Beyond API supply, competitive advantage is increasingly defined by formulation expertise and product portfolio breadth. Companies that can deliver extended release variants, combination tablets, and finished formulations alongside API supply are better positioned to serve integrated buyer needs. Recent launches underscore this pattern, as manufacturers introduce combination products that pair metformin with complementary therapies and seek exclusivity windows that create near-term commercial advantage. The strategic lesson is that value capture increasingly depends on moving beyond commodity API positioning into differentiated product offerings that address specific clinical and market needs. Companies that invest in formulation development, regulatory execution, and launch readiness can convert clinical utility into commercial differentiation.
Market Structure Evolution: Consolidation Pressure and Niche Opportunities
Market concentration suggests that consolidation pressures will persist, particularly as buyers favor suppliers that can provide reliable volume, regulatory assurance, and competitive pricing in a single relationship. At the same time, the presence of multiple certified producers and the continued launch of new generics indicate that niche opportunities remain for specialized suppliers, regional distributors, and companies targeting specific formulations or markets. The landscape is thus evolving along two tracks. On one hand, scale players are likely to strengthen their positions through capacity expansion, portfolio broadening, and integrated supply offerings. On the other hand, targeted entrants can find room by serving underserved geographic channels, specialized formats, or buyer segments that value responsiveness and tailored service over bulk commodity supply. The ability to read which track offers the most attractive risk-adjusted opportunity will separate successful strategies from commodity competition.
PW Consulting Health Care Research Center
Forward-Looking Trends and Strategic Implications
Trend One: Continued Emphasis on Combination Therapies and Extended Release Formats
The product launch activity observed in recent quarters points toward a broader trend in which metformin value is increasingly embedded in combination regimens and delivery formats that improve adherence and clinical outcomes. Over the next three to five years, opportunities will likely accrue to manufacturers and suppliers that can efficiently develop, approve, and commercialize combination products and extended release variants. This trend creates commercial opportunity for companies that align formulation pipelines with prescriber preferences, payer expectations, and exclusivity timing. It also introduces execution risk, since combination development and regulatory approval require coordinated capabilities across R&D, quality, and market access functions. Companies that treat formulation strategy as a core competency rather than a peripheral activity will be better placed to capture premium positioning within a generic market.
Trend Two: Regulatory Discipline as a Competitive Moat
Given persistent impurity monitoring requirements and ongoing post-marketing surveillance expectations, regulatory discipline will increasingly function as a competitive moat rather than a compliance baseline. Manufacturers that maintain transparent quality systems, proactive testing programs, and strong regulatory relationships will reduce the risk of supply interruptions and build credibility with procurement organizations that prioritize supply continuity. Over time, this could translate into preferential sourcing status, longer contract cycles, and greater resilience during regulatory scrutiny affecting the broader class. The strategic opportunity lies in converting quality and compliance investments into commercial trust, which can be a durable advantage in a market where buyers have multiple supplier options.
Minocycline Hydrochloride Market
Trend Three: Geographic Expansion and Supply Chain Localization
Demand growth in emerging markets, combined with buyer interest in resilient and regionally balanced supply chains, suggests that geographic expansion and supply chain localization will remain important themes. Companies that establish or strengthen regional manufacturing, distribution, and registration capabilities can position themselves closer to end demand, reduce lead-time risk, and align with procurement preferences for diversified sourcing. This trend is not without uncertainty, as regulatory requirements, pricing dynamics, and competitive intensity vary significantly across regions. The opportunity, however, is to build a balanced geographic footprint that captures higher-growth demand while managing the complexity of multi-market compliance and commercial execution.
Risk Considerations and Uncertainty Factors
Several risk factors warrant attention. Reimbursement and formulary pressures may continue to erode pricing power in key markets, particularly where generic competition is intense and substitution is routine. Regulatory expectations around impurity monitoring could evolve, creating compliance costs or requiring reformulation efforts that affect timelines and margins. Input cost stability may not persist indefinitely, and any disruption in precursor supply could alter cost structures quickly. In addition, concentration in the competitive landscape means that shifts in the strategy or capacity plans of leading producers could influence pricing and availability across the market. Decision-makers should therefore treat these factors as variables to monitor and manage rather than fixed assumptions, building flexibility into capacity planning, portfolio strategy, and supplier relationships.
Strategic Recommendations for Decision-Makers
For Manufacturers and API Suppliers
Prioritize formulation differentiation and regulatory agility as core strategic pillars. In a market where generic price erosion is persistent, competitive advantage increasingly comes from extended release capabilities, combination product readiness, and the ability to secure and maintain approvals across key markets. Manufacturers should also treat quality and impurity management as commercial assets, using robust compliance practices to strengthen buyer confidence and reduce supply interruption risk. Capacity decisions should balance scale efficiency with flexibility, ensuring that production infrastructure can support both high-volume API supply and more specialized formulation needs. Finally, building strong relationships with procurement organizations through reliability, transparency, and consistent quality can help protect positioning against price-based competition.
For Investors and Strategic Partners
Focus on operators with demonstrated regulatory compliance, diversified product capabilities, and exposure to both mature and higher-growth geographic demand. The market's growth trajectory is positive, but value creation will likely concentrate among companies that can combine scale with formulation differentiation and multi-market access. When evaluating opportunities, assess not only revenue potential but also the quality of regulatory standing, the durability of supply relationships, and the ability to manage reimbursement pressure without sacrificing margin integrity. Combination therapy launches and exclusivity-enabled product entries may create near-term commercial windows, but longer-term value will depend on sustainable cost structures and the capacity to navigate ongoing regulatory expectations.
Worldwide Berberine Hydrochloride API Market
For Procurement and Supply Chain Leaders
Diversify sourcing strategies while prioritizing suppliers with verified certifications, transparent quality practices, and demonstrated supply continuity. Given market concentration and ongoing regulatory oversight, relying on a narrow supplier base can increase vulnerability to disruption, while over-diversification without quality assurance can introduce compliance risk. A balanced approach involves qualifying multiple certified sources, monitoring regulatory developments that affect product availability, and integrating impurity monitoring and stability testing considerations into supplier evaluation. Procurement teams should also pay attention to formulation variety and combination product availability, as these can influence total cost of ownership, patient adherence, and downstream clinical outcomes. Building supplier relationships around reliability and quality, rather than price alone, can reduce long-term risk in a market where regulatory and competitive dynamics continue to shift.
Conclusion
The metformin hydrochloride market is entering a phase in which growth remains achievable, but the path to value creation is becoming more selective. Steady demand fundamentals, stable input economics, and regulatory clarity around certain formulations provide a supportive backdrop. At the same time, generic price erosion, impurity monitoring obligations, and concentrated competitive dynamics require deliberate strategy rather than passive participation. The companies and investors best positioned for the next several years will be those that treat formulation differentiation, regulatory discipline, and geographic agility as interconnected capabilities. For those seeking deeper segmentation data, regional breakdowns, company-level benchmarks, and customized scenario analysis, the full PW Consulting research report offers a more granular view of the market and the strategic options it presents.
For detailed analysis of this topic, please visit the official page: Metformin Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com