

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Wireless Audio Device Market: Why 7.35% CAGR Through 2032 Changes Everything

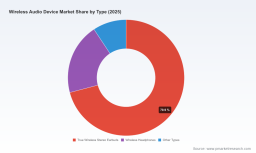
The Wireless Audio Device Market: Strategic Trends and Commercial Opportunities Through 2032
The global wireless audio device market has entered a phase of accelerated expansion. Valued at 40.0 million USD in 2020, the market has expanded steadily to reach 64.5 million USD by 2025, with projections indicating growth to 114.0 million USD by 2032. This trajectory reflects a compound annual growth rate of 7.35 percent across the 2026 to 2032 forecast period. Behind these figures lies a fundamental transformation in how consumers and enterprises consume audio, driven by evolving form factors, improved connectivity standards, and shifting usage patterns. For executives navigating hardware portfolios, supply chain investments, or product roadmaps, understanding the strategic inflection points shaping this market is essential.
Market Scale and Structural Realities
The recent expansion reflects more than cyclical demand recovery. It signals a structural shift in audio consumption habits. Consumers increasingly prioritize untethered listening experiences, while commercial environments deploy wireless audio for communications, entertainment, and specialized use cases. The market is not uniform. Premium audiophile segments coexist with highly price-sensitive mass markets, creating divergent profitability profiles and supply chain requirements. Manufacturers that treat wireless audio as a monolithic category risk misallocating resources across segments with fundamentally different demand dynamics.
Several structural challenges complicate this expansion. First, component cost volatility has introduced pronounced uncertainty into pricing strategies and margin management. Second, regulatory friction around trade flows and material sourcing is reshaping procurement pathways, particularly for companies dependent on cross-border component flows. Third, the market exhibits notable concentration among established players, which raises barriers for new entrants while simultaneously pressuring incumbents to defend differentiation as product features commoditize. These tensions define the competitive environment and determine which organizations will capture disproportionate value as the market matures.
Key Challenges and Inflection Points
Component supply constraints represent a primary pressure point. Specialized materials used in vibration motors and acoustic assemblies have experienced dramatic price movements. Neodymium and tungsten, critical to miniature transducer performance, have faced price surges linked to export controls and competing defense-sector demand. Tungsten prices, for example, have climbed more than 450 percent in a single year, fundamentally altering cost structures for manufacturers reliant on these inputs. Companies that have not diversified material sourcing or redesigned acoustic architectures around commodity alternatives face margin compression and production instability.
Trade policy adds a parallel layer of complexity. Effective tariff rates on electronics imports, including wireless audio components, have reached levels that materially affect landed costs. Average effective US tariff rates have hovered around 16.8 percent, with direct implications for procurement budgets and regional sourcing decisions. Simultaneously, export control adjustments in upstream material markets have introduced volatility. Temporary suspensions of export restrictions on rare earth metals and battery components have created short-term relief but also uncertainty about future supply continuity. These dynamics force manufacturers to treat geography as a strategic variable rather than a static procurement detail.
A third inflection point involves market concentration and the limits of feature-based differentiation. With the top three players holding over half of market share and the top five exceeding 60 percent collectively, incumbents benefit from scale, brand recognition, and ecosystem lock-in. Yet as core Bluetooth performance improves and noise-cancelling capabilities become standard across price tiers, differentiation increasingly depends on specialized use cases, audio architecture innovations, and integrated service ecosystems rather than incremental hardware upgrades. This shift raises the stakes for mid-tier manufacturers and creates openings for players that solve specific commercial or professional audio needs.
Home Audio Equipment Market
Key Demand and Supply Drivers
Technological Innovation and Acoustic Architecture Shifts
Technology leadership remains the most visible driver of market evolution. Research into MEMS-based speaker technology illustrates how component-level innovation can reshape product positioning. Recent product announcements have highlighted TWS earbuds incorporating MEMS speakers, establishing new benchmarks for acoustic performance in compact form factors. These developments matter because they address long-standing tradeoffs between size, sound quality, and power efficiency. As MEMS speakers move from niche applications to high-volume consumer products, manufacturers that integrate these components gain credible differentiation in a market where audio quality expectations continue to rise.
Digital audio resolution represents another frontier. Recent launches of USB-C wireless earbuds and headphones supporting 24-bit/96 kHz digital audio indicate that premium segments are beginning to treat wireless transmission as a platform for high-fidelity audio rather than a compromise. This trajectory aligns with broader consumer interest in immersive listening experiences and professional-grade audio quality at consumer price points. Manufacturers that ignore high-resolution wireless audio risk ceding premium positioning to competitors that align product architecture with evolving listener expectations.
Policy and Regulatory Environment
Regulatory and trade dynamics are reshaping the cost and risk landscape for wireless audio manufacturers. Tariff structures affecting electronics components have altered the economics of offshore sourcing, particularly for companies assembling products with globally distributed component chains. At the same time, export control adjustments on critical materials have created intermittent supply-side uncertainty. These forces do not simply raise costs; they change the calculus of where to design, source, and assemble. Companies that treat compliance and trade exposure as peripheral procurement issues face structural disadvantages compared to organizations that embed regulatory scenario planning into product development and supplier selection.
Regulatory developments also influence feature roadmaps. Standards around low-energy audio transmission, hearing-health compatibility, and connectivity interoperability create opportunities for manufacturers that align product design with emerging requirements. Rather than viewing regulation solely as a cost factor, forward-looking companies use compliance and interoperability as positioning tools, particularly in professional and commercial segments where reliability and standards adherence influence purchasing decisions.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer behavior continues to favor wireless personal audio for everyday use, but the composition of demand is broadening. Wireless audio devices are increasingly embedded in hybrid work environments, fitness ecosystems, travel scenarios, and smart-home interactions. This diversification means that product success depends less on generic listening features and more on context-specific performance, durability, and integration with broader device ecosystems. Manufacturers that design for specific usage environments gain stronger retention and willingness-to-pay than those competing solely on generic audio specifications.
Enterprise and commercial adoption introduces a separate demand vector. Wireless audio solutions for communications, customer-facing environments, and specialized professional workflows are expanding, driven by flexibility requirements and the declining cost of reliable wireless transmission. Commercial buyers evaluate audio devices through lenses that differ materially from consumer purchase behavior: total cost of ownership, serviceability, durability, and compatibility with existing communication infrastructure. Companies that address these criteria explicitly can access demand streams with different competitive dynamics than saturated consumer tiers.
Supply Chain and Cost Structure Reconfiguration
Supply chain strategy has moved from operational concern to strategic differentiator. Component volatility, trade exposure, and sourcing complexity reward manufacturers that build resilient material pipelines, dual-source critical assemblies, and design products with supplier flexibility in mind. The cost structure of wireless audio devices is increasingly defined not only by bill-of-materials optimization but also by geographic risk management, inventory buffering strategies, and design choices that reduce dependence on constrained materials.
This reconfiguration creates a competitive split. Organizations with diversified sourcing, local or nearshore assembly options, and acoustic designs that minimize exposure to scarce inputs can protect margins more effectively. Those locked into single-supplier relationships or concentrated material dependencies face greater vulnerability to price shocks and supply interruptions. The implication for strategy is clear: supply chain architecture is now a core element of product competitiveness, not a back-office function.
Competitive Landscape and Strategic Positioning
Incumbent Strengths and Differentiation Models
The market features a mix of ecosystem-driven incumbents, audio-specialist brands, and value-focused manufacturers. Leaders such as Apple, Samsung, and Sony leverage integrated device ecosystems, custom silicon, and strong brand recognition to sustain premium positioning. Their advantage lies not only in hardware performance but also in seamless connectivity, software integration, and user experience consistency. In this environment, wireless audio becomes part of a broader platform value proposition rather than an isolated product category.
Audio specialist brands including Bose, Sennheiser, and Shure pursue a different model. They compete on sound quality heritage, professional-grade reliability, and targeted product architectures for specific listening and performance environments. This approach allows them to command premium positioning in segments where audio fidelity, durability, or professional functionality outweigh ecosystem convenience. For these players, strategic focus on specialized use cases and acoustic expertise remains the foundation of differentiation.
Emerging and Regional Players Reshaping Price and Volume Dynamics
A second competitive layer includes manufacturers focused on value-oriented TWS products, regional market strength, and volume-driven growth. Companies such as Xiaomi, Anker, and boAt have expanded access to wireless audio by combining competitive pricing with functional feature sets. Their success reflects demand for functional wireless audio at accessible price points, particularly in price-sensitive markets and first-time wireless audio adopters. These players have also influenced industry expectations around feature availability at lower price tiers, pushing incumbents to justify premium pricing through meaningful performance or experience advantages.
The presence of strong regional players also complicates global competitive strategy. Manufacturers that succeed in one geography often face different brand dynamics, distribution structures, and price expectations in another. Global scale does not automatically translate into local relevance, and companies that underestimate regional competitive nuance risk losing share to adaptive local players.
Recent Product and Partnership Developments
Recent product movements highlight how competition is evolving at the feature and component level. Sennheiser's introduction of USB-C earbuds and headphones with 24-bit/96 kHz digital audio support reflects a push toward higher-resolution wireless listening in consumer-accessible form factors. Sony's announcement of next-generation wireless earbuds indicates continued investment in flagship performance and brand leadership in premium TWS segments. Meanwhile, product partnerships involving MEMS speaker technology in high-volume TWS earbuds point to a broader shift toward innovative acoustic components that can differentiate products without requiring complete platform redesigns.
PW Consulting Health Care Research Center
These developments matter strategically because they show differentiation migrating toward component architecture, digital audio capability, and targeted performance claims rather than generic connectivity. Manufacturers that align their roadmaps with these shifts can create defensible product positions; those that compete only on price or brand legacy face mounting pressure as feature parity increases.
Market Structure Evolution: Consolidation, Fragmentation, and Entry Dynamics
The market is simultaneously experiencing concentration among leading players and fragmentation in niche and regional segments. High concentration at the top reflects the advantages of scale, ecosystem integration, and sustained R&D investment. At the same time, specialized professional audio providers, hearing-focused device makers, and regional value brands continue to carve out distinct positions. This dual structure suggests that future competition will emphasize segmentation precision rather than blanket market coverage.
New entries are likely to succeed by solving specific audio problems rather than by launching generic wireless earbuds or headphones. Opportunities exist in commercial audio, hearing-compatible TWS designs, professional monitoring, and form factors tailored to particular usage contexts. Companies that approach the market with narrowly defined value propositions and strong component or acoustic differentiation have a more viable path than those attempting to compete broadly against entrenched ecosystem leaders.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Acoustic Component Innovation as a Differentiation Engine
The adoption of advanced acoustic components, including MEMS speakers and high-resolution digital audio architectures, is likely to accelerate through the next several years. As these technologies become more accessible, they will shift from premium differentiators to baseline expectations in mid-tier and premium segments. The commercial opportunity lies in early integration and in targeting use cases where improved acoustic performance translates directly into user value, such as compact devices with demanding sound quality expectations or professional listening applications that benefit from higher-resolution transmission.
The risk is that component innovation can be replicated faster than brand or ecosystem advantages. Manufacturers that treat new acoustic architectures as short-term marketing features rather than as part of a sustained product architecture strategy may find their differentiation eroded quickly. Sustainable advantage will depend on combining component innovation with tuning expertise, design integration, and use-case-specific validation.
Trend 2: Supply Chain Regionalization and Material Risk Management
Trade policy, material scarcity, and component price volatility are likely to drive incremental regionalization of sourcing and assembly. Manufacturers will increasingly evaluate suppliers not only on cost and quality but also on geographic resilience, material exposure, and tariff implications. The commercial opportunity lies in building procurement and design strategies that reduce vulnerability to single-source dependencies and constrained material inputs. Companies that proactively redesign products for supplier flexibility and material substitution can convert supply chain risk into a cost and reliability advantage.
Uncertainty remains around the trajectory of trade policy and export control decisions. Temporary suspensions or adjustments in material export rules can create short-term relief while leaving longer-term structures unchanged. Organizations that base planning on static assumptions risk repeated disruption. Scenario-based sourcing and flexible design architectures are more resilient approaches.
Trend 3: Segmentation Expansion in Commercial, Professional, and Hearing-Adjacent Use Cases
Demand is expanding beyond personal consumer listening into commercial workflows, professional monitoring, and hearing-supportive audio applications. This expansion creates opportunities for manufacturers that design with specific user environments in mind, rather than treating all wireless audio as interchangeable consumer products. Commercial buyers value durability, manageability, interoperability, and total cost of ownership; professional users prioritize reliability, acoustic consistency, and compatibility with existing systems; hearing-adjacent applications require attention to audio clarity, comfort, and standards alignment.
The strategic opportunity is to address these segments with product architectures and go-to-market models that differ from mass consumer strategies. This may involve stronger service and support models, application-specific tuning, compliance with relevant standards, and pricing structures that reflect usage value rather than only hardware cost. The risk is that these segments require different capabilities and partnerships, and companies without commercial or professional sales infrastructure may find adoption slower than in consumer channels.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Prioritize acoustic and component differentiation that is difficult to replicate through generic specification upgrades. High-resolution audio support, MEMS-based speaker integration, and use-case-specific tuning can create more durable positioning than incremental feature additions. Equally important, design products with supply chain flexibility in mind: reduce dependence on constrained materials where feasible, evaluate dual sourcing for critical assemblies, and model tariff exposure as part of product economics. In concentrated markets, success increasingly depends on solving specific user problems rather than competing across all segments simultaneously.
For Investors and Strategic Capital Allocators
Evaluate wireless audio exposure through the lens of differentiation durability and supply chain resilience rather than top-line growth alone. Companies with strong ecosystem integration, specialized acoustic expertise, or targeted commercial and professional positioning are better positioned to defend margins as feature parity increases. Also assess exposure to material cost volatility and tariff risk; business models that depend heavily on single-source components or concentrated geography-dependent sourcing carry higher disruption risk. Investment theses should account for segmentation strategy as a key indicator of long-term competitiveness.
For Procurement and Supply Chain Leaders
Treat sourcing strategy as a strategic lever, not only a cost exercise. Map exposure to constrained materials, tariff-impacted component flows, and single-supplier dependencies. Where possible, qualify alternative materials or suppliers for critical acoustic and electronic assemblies, and incorporate tariff and logistics scenarios into total cost models. Build flexibility into product specifications so that sourcing adjustments do not require full redesigns. In an environment where material and trade volatility is likely to persist, procurement decisions directly affect product economics and launch stability.
Bluetooth Audio Ic Market
Closing Perspective
The wireless audio device market is expanding, but expansion alone does not guarantee profitable positioning. The companies that will capture disproportionate value are those that treat differentiation as a function of acoustic innovation, supply chain resilience, and segmentation precision rather than scale alone. Component-level advances, regulatory and trade dynamics, and broadening demand contexts are reshaping the rules of competition. Executives who align product strategy, sourcing decisions, and market focus with these shifts will be better positioned to convert market growth into sustainable advantage. For organizations seeking deeper segmentation data, regional breakdowns, and tailored strategic recommendations, comprehensive research coverage is available to support more granular planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Wireless Audio Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com