

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Coconut Milk Powder Market: Why 9.94% CAGR Redefines Global Growth by 2032

Coconut Milk Powder Market: Strategic Trends and Commercial Opportunities Through 2032
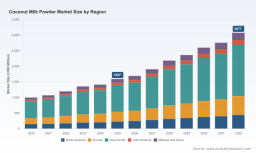
The coconut milk powder market has entered a phase of accelerated, structural growth. Over the historical period from 2020 to 2025, the market expanded from approximately USD 1.0 billion to USD 1.597 billion, reflecting a compound annual growth rate that signals durable demand rather than a temporary spike. During the forecast window from 2026 to 2032, the trajectory continues upward, with projected revenue reaching roughly USD 3.077 billion by the end of the period and a five-year CAGR of 9.94%. These figures place coconut milk powder among the more compelling ingredient categories in the broader plant-based and alternative dairy landscape. The growth is not evenly distributed across regions or applications, but the aggregate momentum is clear: manufacturers, investors, and procurement teams are facing a market that is scaling faster than legacy dairy substitutes in several consumer segments.
Behind the headline numbers lies a market that is still maturing in terms of supply discipline, quality standardization, and regulatory alignment. The concentration metrics underscore this reality: the top three players account for 44.5% of market revenue, while the top five hold 59.0%. This level of concentration indicates a competitive field where scale advantages matter, yet substantial room remains for regional specialists, niche organic suppliers, and vertically integrated processors to capture value. The market is large enough to support diversified strategies but fragmented enough that positioning, technology, and supply chain resilience now determine who wins margin rather than who simply participates.
1. Market Landscape and Core Challenges
A Market Growing on Two Parallel Tracks
The overall expansion reflects a dual dynamic. On one side, full-fat coconut milk powder continues to anchor demand in applications that prioritize richness, mouthfeel, and traditional flavor profiles. On the other, low-fat variants are gaining traction where formulation flexibility, calorie management, and downstream processing compatibility matter more than absolute fat content. The two segments are approaching comparable scale, which tells a story of diversification rather than reliance on a single product architecture. Beverage formulators, bakery developers, and savory sauce manufacturers are selectively choosing between these variants based on functional requirements, not just cost.
Geographically, Asia Pacific carries the largest absolute share of revenue, consistent with the region's production base, domestic consumption habits, and growing export-oriented processing capacity. Europe and North America follow as significant demand centers, driven by premiumization, clean-label expectations, and the ongoing shift toward plant-based alternatives in food service and retail. Latin America and the Middle East/Africa regions contribute meaningful volume, though from smaller bases, and their growth paths are increasingly influenced by cross-border supply arrangements and food safety compliance rather than domestic consumption alone.
Cheese Powder Market
Three Challenges Defining the Market's Next Chapter
First, raw material cost volatility is no longer a cyclical nuisance; it is a structural factor shaping pricing, contracts, and margin planning. Coconut feedstock prices have shown sensitivity to weather patterns, crop cycles, and regional supply tightness. In early 2026, coconut milk powder pricing rose by 3–4% as underlying coconut material costs increased, and earlier data points to ongoing volatility affecting production economics for processors. For manufacturers, this translates into the need for stronger hedging, forward contracting, and formulation strategies that can absorb input swings without eroding competitiveness. For buyers, it means shorter-term price stability can no longer be assumed, and dual-sourcing or specification flexibility may become part of routine procurement design.
Second, regulatory and labeling requirements are intensifying in the most profitable end markets. Food safety authorities in Europe and North America have reinforced labeling rules for powdered foods, including coconut milk powder, with clearer expectations around ingredient declarations, allergen handling, and packaging information. At the same time, government push toward sustainable packaging and plastic reduction is reshaping packaging roadmaps across food categories. Import requirements add another layer of complexity, with phytosanitary certificates and market-specific entry conditions becoming standard for coconut milk powder shipments. The practical effect is a rising compliance bar that rewards companies with disciplined documentation, traceable supply chains, and packaging strategies already aligned with destination-market expectations.
Third, the market is reaching an inflection point where consistency and functionality increasingly separate premium suppliers from commoditized participants. Spray-drying efficiency, particle uniformity, reconstitution behavior, and flavor stability are becoming differentiators rather than table stakes. As applications expand into beverages, bakery, confectionery, soups, sauces, and other formats, the ingredient must perform reliably across different processing environments. Companies that can deliver consistent technical performance while managing cost and compliance are better positioned to move up the value chain, whereas suppliers competing primarily on price face increasing pressure as specifications tighten and audits become more frequent.
2. Key Drivers Shaping Market Trajectory
Technology and Processing Innovation
Processing technology is a primary enabler of the market's next wave of growth. Advanced spray-drying and integrated processing investments are improving powder consistency, yield, and functional reliability. In April 2026, Thai Coconut Public Company Limited increased investment in advanced spray-drying and processing technologies aimed at improving coconut milk powder efficiency and consistency, a move that reflects a broader industry focus on turning production capability into a strategic advantage. Around the same time, Axelum Resources Corp. expanded integrated coconut processing capabilities with strengthened value-added ingredient production for export-focused coconut milk powder manufacturing. These developments matter because they do not simply increase capacity; they improve the economics of premium-grade output and reduce variability across batches, which is critical for industrial buyers who depend on repeatable formulation performance.
For the broader market, the technological trajectory points toward more tightly controlled particle characteristics, improved solubility profiles, and greater ability to tailor fat content without sacrificing sensory qualities. These improvements widen the range of applications where coconut milk powder can substitute or complement other ingredients, especially in plant-based dairy alternatives, ready-to-drink beverages, and formulated foods that require stable powders with predictable behavior during storage and reconstitution.
Consumer Demand and Corporate Procurement Behavior
Demand-side change is being driven by the continued expansion of plant-based eating, but also by more specific shifts in how food manufacturers and food service operators select ingredients. Coconut milk powder benefits from its positioning as a recognizable, consumer-friendly plant-based ingredient with a strong flavor association and broad acceptability. At the same time, corporate buyers are increasingly balancing functionality with clean-label expectations, sourcing transparency, and sustainability credentials. This creates a layered demand environment: one layer is volume-driven and price-sensitive, while another layer rewards suppliers who can document origin, processing standards, and packaging responsibility.
Worldwide Coconut Oil Fat Powder Market
The application spread reinforces this dynamic. Beverages remain a major demand node, but bakery, confectionery, soups, sauces, and other categories are not merely secondary users; they represent formulation problems that coconut milk powder can solve when the right fat level, solubility, and flavor profile are available. Suppliers that understand application-specific requirements are better able to move beyond commodity positioning and into partnership-based selling, where technical support and customization become part of the value proposition.
Supply Chain Realignment and Cost Structure Pressures
The supply chain for coconut milk powder is being reshaped by a combination of input volatility, export documentation requirements, and the search for more predictable sourcing. Raw coconut material price volatility has repeatedly affected production costs, which pushes manufacturers to strengthen relationships with growers, consider regional diversification, and improve inventory planning. Import requirements, including phytosanitary certificates and market-specific food import rules, add time and cost to cross-border transactions, especially for suppliers serving regulated markets in Europe and North America.
This environment favors companies with integrated operations, where control over processing reduces exposure to intermediaries and improves quality oversight. It also favors exporters who invest early in compliance readiness and documentation fluency, because these capabilities lower friction at border points and shorten time to market. For buyers, the practical takeaway is that supply resilience is increasingly a procurement criterion alongside price and quality, especially for manufacturers who cannot afford production interruptions or specification failures.
PW Consulting Health Care Research Center
Regulatory and Sustainability Pressures as Market Filters
Regulatory and sustainability expectations are increasingly acting as market filters rather than mere compliance tasks. Labeling mandates for powdered foods, sustainable packaging guidance, and plastic reduction targets are reshaping product design decisions. These requirements are not uniform across regions, which means that suppliers serving multiple markets must manage a patchwork of rules, but they also create advantages for companies that have already modernized packaging formats, documentation systems, and labeling processes. In effect, the regulatory environment is raising the cost of entry for poorly organized players while rewarding those with established quality and compliance infrastructure.
This dynamic is particularly relevant for premium and organic segments, where buyers expect both ingredient integrity and responsible packaging. Companies that can align product claims with verifiable practices are more likely to secure long-term contracts with brands that face their own consumer and retailer scrutiny.
3. Competitive Landscape and Leading Strategies
Differentiation Through Integration, Technology, and Positioning
The competitive set reflects a range of strategic models. Axelum Resources Corp. operates as a fully integrated manufacturer and exporter of premium coconut products, including coconut milk powder for global food and beverage brands, with a focus on export-oriented value-added production. Thai Coconut Public Company Limited stands out as a leading manufacturer with advanced spray-drying technology, an asset that supports consistency and scale in coconut milk and coconut milk powder production. Red V Foods serves North American food manufacturers, food service, and private label customers with premium coconut products, positioning itself within a mature demand center where specification and service reliability often matter as much as price.
Bata Food operates as an international supplier of organic and conventional coconut milk powder with offices in the Netherlands and the USA, a footprint that supports access to regulated Western markets and suggests a strategy built on trade connectivity and product range breadth. In the plant-based and dairy-alternative segment, Royal Grove Foods has launched plant-based coconut milk ranges for food manufacturing and home use, signaling movement toward end-use positioning rather than ingredient-only distribution. Jaindi Export Pvt. Ltd. and Omilco Exports represent Sri Lankan exporters with organic and premium organic coconut solutions respectively, both active in international food exhibitions and oriented toward export channels. Coco Factory Pvt. Ltd. emphasizes vegan coconut milk powder crafted from real coconut milk for plant-based dairy alternatives, an explicit product Narrative that aligns with consumer-facing positioning.
These profiles illustrate a market where leadership is being built through different paths: vertical integration, technology investment, organic certification, application-specific product narratives, and trade-network access. Few players are competing on a single dimension; instead, the stronger positions combine processing capability, market access, and a clear value proposition tied to either premium quality, organic integrity, or application performance.
Recent Moves That Signal Strategic Direction
The most recent industry activity reinforces the emphasis on capability, visibility, and market access. In April 2026, Axelum Resources Corp. expanded integrated coconut processing capabilities with strengthened value-added ingredient production for export-focused coconut milk powder manufacturing. Thai Coconut Public Company Limited increased investments in advanced spray-drying and processing technologies for improved efficiency and consistency. In May 2026, Omilco Exports appeared as a first-time exhibitor at Fine Food Australia, showcasing premium organic coconut milk powder, cream, and related products. Jaindi Export Pvt. Ltd. exhibited organic coconut milk powder at Gulfood 2026. These actions collectively indicate that companies are pursuing growth through both operational upgrades and direct market engagement, using trade platforms to reach buyers in high-value regions and using technology and integration to defend margin and quality.
How the Competitive Structure Is Evolving
The market is likely to continue evolving along three lines. Integration will deepen where scale and cost control matter most, especially among exporters serving regulated markets that demand consistency and documentation. Differentiation will intensify among organic, premium, and application-focused players who can justify higher price points through verified quality, technical support, and packaging compliance. At the same time, new entrants and regional specialists can still find openings if they focus on underserved applications, specific geographic routes, or certified organic supply that larger players do not fully address. The moderate concentration in the market means consolidation is possible over time, but it is not yet a foregone conclusion; the more immediate trend is a widening gap between suppliers with integrated, technology-enabled operations and those competing primarily on loose specifications and price.
4. Outlook: Three Trends Shaping the Next Three to Five Years
Premiumization and Functional Tailoring Will Drive Higher-Value Volume
As the market expands from roughly USD 1.7 billion in 2026 toward more than USD 3.0 billion by 2032, volume growth alone will not explain the gain. A meaningful portion of future growth will come from higher-value usage where coconut milk powder is selected for specific sensory and functional outcomes. Formulators will continue to differentiate between full-fat and low-fat options based on application needs, and suppliers that offer tailored specifications, reliable reconstitution, and stable flavor will capture more of the margin pool. This trend favors manufacturers that can support buyers with technical expertise and consistent batches, and it raises the stakes for commoditized suppliers whose products are easiest to replace.
Compliance and Packaging as Competitive Advantage
Over the next few years, regulatory expectations around labeling, food safety, and sustainable packaging are likely to become more embedded in procurement decisions rather than treated as separate compliance workstreams. Suppliers that align product design with destination-market rules and demonstrate credible packaging roadmaps will gain an edge in Europe, North America, and other regulated channels. Conversely, companies that lag on documentation, traceability, or packaging transition may find themselves constrained to less demanding channels, where price competition is more intense and brand visibility is lower. In this environment, compliance becomes a market-access tool as much as a legal obligation.
Regional Rebalancing and Export Route Optimization
The market's center of gravity will remain Asia Pacific-dominant in volume terms, but growth in demand from Europe, North America, and selected emerging regions will encourage more deliberate route-to-market planning. Recent exhibition activity in Australia and the Middle East, combined with ongoing investments in processing capability, suggests that suppliers are actively testing and strengthening distribution pathways beyond traditional channels. Over the forecast period, expect more emphasis on export readiness, phytosanitary and import compliance, and localized customer support. This rebalancing creates opportunities for intermediaries, specialized traders, and processors that can bridge production clusters with end-market requirements efficiently.
Risks and Uncertainties to Monitor
Several factors could alter the trajectory. Continued raw material price volatility may compress margins for operators without strong contracting or hedging flexibility. Tightening regulations, especially where labeling, packaging, and import requirements diverge across markets, could raise operating costs and slow product launches. If demand for plant-based alternatives softens in specific categories or price-sensitive segments, coconut milk powder could face sharper competition from other plant-based fats and powders. Finally, weather-related disruptions and crop variability in key producing regions could affect both supply reliability and pricing stability, making multi-region sourcing and inventory planning more important than ever.
5. Strategic Implications for Decision-Makers
For Manufacturers
Prioritize processing consistency and application-specific value over volume alone. Investments in spray-drying efficiency, quality control, and integrated processing are becoming decisive because they directly influence batch reliability, specification control, and the ability to serve demanding industrial buyers. At the same time, build compliance infrastructure early, including labeling readiness, documentation fluency, and packaging transitions, so that new market entry does not become a bottleneck. Where raw material exposure is significant, strengthen supplier relationships and consider forward arrangements that reduce vulnerability to price swings.
For Investors
Look for operators that combine credible technology or integration with clear market access and documentation capability. In a market where the top players already hold meaningful share but concentration is not absolute, value creation is likely to accrue to companies that can defend premium positioning, manage volatility, and expand into regulated channels with lower friction. Pay close attention to how suppliers are handling compliance, packaging, and organic or premium differentiation, because those factors increasingly determine customer stickiness and pricing power.
For Procurement and Sourcing Teams
Treat resilience as a core sourcing criterion. Dual sourcing, specification flexibility, and supplier qualification based on consistency and compliance can reduce exposure to both price volatility and supply interruption. When evaluating suppliers, assess not only price and basic quality but also documentation maturity, packaging alignment with destination-market expectations, and the ability to support application needs. Shorter-term price advantages can be outweighed by higher total cost if a supplier cannot meet audit, labeling, or reliability requirements.
Why Timing and Granularity Matter Now
The market is large enough to reward strategic commitment and fast enough that timing matters. With the forecast period extending through 2032 and a CAGR in the high single digits, decisions made now about product specifications, sourcing routes, compliance readiness, and application targeting will shape competitiveness for years. Companies that act on broad trends alone may capture some growth, but those that combine trend awareness with detailed segmentation insight, regional compliance nuance, and application-specific formulation considerations are more likely to secure durable advantage. For teams seeking to move from general market awareness to targeted operating decisions, more granular data on regional and application dynamics, competitive positioning, and scenario planning can materially improve the quality of strategy and execution.
For detailed analysis of this topic, please visit the official page: Coconut Milk Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com