

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Solar Shading Systems Market 2026: The Real Forces Behind 3.5% Growth Through 2032

Strategic Horizons in the Solar Shading Systems Market: Navigating Growth, Regulation, and Material Shifts
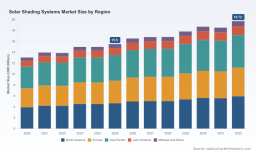
The solar shading systems market has matured into a critical intersection of building performance, energy efficiency, and architectural design. Valued at approximately $13.05 billion in 2020 and projected to reach $19.72 billion by 2032, the sector has demonstrated steady expansion across the historical period, reaching $15.50 billion in 2025. Forward projections indicate the market will scale to $16.52 billion by 2026, gradually climbing toward $16.81 billion by 2028 before accelerating into the $18.69 billion range by 2030. The implied compound annual growth rate of 3.5% over the forecast horizon reflects a market that is no longer defined by cyclical boom-and-bust patterns, but rather by structural shifts in building codes, consumer expectations, and supply chain restructuring. For executives and capital allocators, this trajectory signals a sector that has stabilized around baseline growth while simultaneously undergoing compositional changes that will separate value-creators from commoditized participants.
The market's growth profile is neither uniform nor predictable without context. Revenue has fluctuated modestly across recent years, with 2022 recording a slight contraction before rebounding in 2023 and plateauing near $14.97 billion in 2024. Such volatility underscores how the sector responds acutely to macroeconomic cooling, procurement delays, and regional construction cycles. Yet the broader arc remains upward, driven by the persistent need to manage solar heat gain, reduce HVAC loads, and meet increasingly stringent energy performance standards. Understanding where growth concentrates, what forces will reaccelerate or compress margins, and which competitive strategies will hold up under regulatory and material scrutiny is essential for anyone positioning around this market in the coming years.
Market Snapshot and Structural Challenges
At a macro level, the solar shading systems market is characterized by a relatively fragmented concentration structure. The top three participants account for roughly a quarter of total industry revenue, while the top five capture approximately one-third. This level of concentration suggests a market that remains accessible to regional specialists and niche innovators, but where scale, distribution breadth, and brand recognition still confer meaningful advantages. The baseline revenue size places the sector in a mature-middle tier of the building products landscape: large enough to support sustained investment and innovation, yet fragmented enough that acquisitions, partnerships, and product differentiators can shift regional standing quickly.
Three challenges currently define the industry's inflection point. The first is the tension between performance mandates and cost sensitivity. As energy codes tighten and building owners demand demonstrable efficiency gains, shading systems must prove measurable contributions to thermal comfort and load reduction. At the same time, residential and non-residential buyers continue to scrutinize upfront costs, especially in environments where interest rates or construction budgets constrain discretionary spending. Manufacturers that cannot articulate a clear return-on-investment narrative risk being relegated to price-based competition.
The second challenge lies in material compliance and supply chain predictability. Shading products increasingly operate within a regulatory and consumer environment that scrutinizes chemical inputs, recyclability, and embodied impacts. Formulations that rely on restricted substances or complex mixed-material constructions face higher compliance risk and potential end-market friction. Companies must navigate raw material variability, sourcing continuity, and de-risked formulations without sacrificing durability, aesthetics, or price competitiveness. This challenge is especially acute for products that integrate directly into glazing or facade systems, where material substitutions can affect certification timelines and installer confidence.
The third challenge is the growing expectation of integration and automation. Shading is no longer evaluated solely as a standalone component; it is increasingly part of broader building management, lighting control, and occupant experience ecosystems. That shift raises the bar for interoperability, software reliability, and service infrastructure. Firms that still approach shading as a purely mechanical or fabric-based product face a widening gap with competitors that can offer connected controls, adaptive responses to daylight, and seamless coordination with HVAC or lighting systems. Bridging that gap requires not only product engineering but also IT, firmware, and support capabilities that not every incumbent has cultivated.
Key Drivers Reshaping Demand and Competitive Dynamics
Technology Innovation and Embedded Performance
Technological progress in solar shading is increasingly defined by how effectively products manage heat, light, and ventilation in a single architecture. Rather than offering only blinds or awnings as discrete add-ons, leading solutions are moving toward integrated transparent systems that control passive heat while preserving daylight transmission. This evolution reflects a broader design priorities shift: architects and building owners want envelopes that perform passively, reduce dependence on active cooling, and maintain visual quality. Technologies that embed shading functionality directly into glazing or facade assemblies can lower 시공 complexity and improve long-term performance consistency, provided they meet durability and certification expectations.
Innovation is also extending into material design. The emergence of formulations that eliminate antimony and avoid PFAS-based chemistries indicates a direction where performance and environmental alignment are pursued together. Such developments matter because they reduce downstream compliance exposure, support specification into projects with strict material requirements, and position manufacturers to respond proactively rather than retroactively to shifting standards. In practical terms, a product that can demonstrate both thermal control efficacy and cleaner material composition gains an advantage in project approvals, procurement screening, and brand perception.
Policy and Building Energy Standards
Regulatory momentum remains one of the most reliable demand catalysts for solar shading. Energy-efficiency programs and building guidance increasingly treat window coverings and solar control measures as practical interventions to reduce heat loss, limit solar heat gain, and lower overall energy consumption. When government bodies promote these systems as part of broader building efficiency strategies, they not only validate the technology but also influence specification behavior among architects, contractors, and facility managers. The effect is especially pronounced in regions where new construction and retrofitting are both subject to tightening performance thresholds.
Policy impact, however, is uneven across geographies and project types. In some markets, incentives or code requirements accelerate adoption in residential new-builds and large commercial renovations. In others, the pace depends on local enforcement capacity and the availability of complementary incentives for envelope upgrades. For businesses operating across multiple regions, this variability means that policy tailwinds must be tracked market by market rather than treated as a uniform global force. The companies that benefit most are typically those that can adapt product portfolios and value propositions to where regulatory pressure is highest, while maintaining enough flexibility to serve less regulated segments without overinvesting in compliance features where they are not yet rewarded.
Demand-Side Behavior and Building Performance Expectations
Demand is shifting on both the residential and non-residential sides, but for related reasons. In residential contexts, homeowners and buyers are increasingly aware of comfort, glare control, and utility costs as part of the overall living experience. Shading systems are being evaluated not only for aesthetics but for their ability to improve indoor temperatures, reduce reliance on mechanical cooling, and support healthier daylight environments. This change in buyer mindset expands the addressable use case beyond decoration or privacy, turning shading into a functional building component with visible daily benefits.
In non-residential settings, the drivers are more institutional. Facility operators, developers, and property owners weigh shading systems against energy budgets, occupant productivity, and asset value. Commercial buildings that struggle with solar load often face compounding costs across HVAC operation, glare-related productivity losses, and tenant satisfaction. Solutions that combine shading with ventilation, facade integration, or automated control can help address several of these issues simultaneously, making them more compelling in project evaluations. The commercial demand story is therefore less about a single product feature and more about total building performance, which favors vendors that can speak the language of energy, comfort, and operational savings rather than simply hardware specifications.
Cost Structure and Supply Chain Realignment
The cost environment for solar shading systems is shaped by raw material dynamics, manufacturing footprint decisions, and the economics of customization versus standardization. Fabric-based systems continue to represent a substantial share of market value, reflecting longstanding demand for versatile, visually adaptable solutions. Metal and other type categories also hold meaningful positions, often associated with durability, architectural presence, and specific performance profiles. As material costs fluctuate and sourcing strategies evolve, companies must decide where to absorb volatility, where to pass through price changes, and where product design can reduce dependency on expensive or constrained inputs.
PW Consulting Health Care Research Center
Supply chain realignment is also being driven by the push toward cleaner material profiles and more predictable component sourcing. Where manufacturers can reduce formulation complexity, standardize core components, and streamline assembly, they typically gain margin stability and faster response times. Conversely, highly customized or multi-material products may face greater exposure to lead-time variability and compliance complexity. Over time, the cost structure winners are likely to be those that balance performance differentiation with manufacturing discipline, treating material innovation as a way to lower risk and total cost of ownership rather than as an isolated research objective.
Competitive Landscape and Leading Strategies
The competitive field includes manufacturers with distinctly different strategic emphases, ranging from architectural sun control and facade integration to interior shading breadth and smart control systems. Warema Renkhoff SE has built its identity around exterior and interior sun shading systems, louvers, awnings, and architectural solar control solutions. Its positioning suggests an emphasis on building-scale solar management and product breadth, appealing to projects where shading must coordinate with facade design and outdoor environmental conditions. Hunter Douglas N.V. offers a wide range of interior and exterior window shading systems, blinds, shades, and automated solutions, reflecting a strategy centered on brand reach, product variety, and consumer-facing distribution strength. Lutron Electronics Co., Inc. takes a more control-centric path, manufacturing smart shading and lighting control systems that integrate solar shading with automated performance and energy optimization. Its relevance lies in the growing overlap between shading hardware and building control infrastructure.
Fabric Solar Shading Systems Market
MicroShade A/S and DUCO Ventilation & Sun Control illustrate two other important strategic directions. MicroShade focuses on integrated transparent solar shading systems embedded in glazing for passive heat control, daylight transmission, and energy efficiency. This approach aligns with projects that seek envelope-level performance and reduced reliance on add-on components. DUCO produces natural ventilation and architectural solar shading systems, including louvers, screens, and facade solutions aimed at healthy, energy-efficient buildings. Its profile emphasizes the pairing of solar control with airflow management, a combination that resonates in settings where indoor environmental quality and passive performance are jointly prioritized.
These companies reflect a market in which differentiation is becoming more multidimensional. Some competitors compete on architectural integration and facade compatibility; others on consumer brand strength, automation, or material and environmental positioning. The presence of investment activity around advanced shading technology underscores that capital is flowing toward solutions with a clear performance narrative and potential for specification advantage. In August 2025, Nordic Alpha Partners invested in MicroShade's solar shading technology, an indication that integrated, material-forward approaches are attracting strategic interest. At the same time, market commentary in early 2026 highlighted a range of growth perspectives for the sector, with one estimate projecting the market from $15.79 billion in 2025 to $16.43 billion in 2026, and another forecasting expansion at a CAGR of 3.75% from $12.12 billion in 2025 to $15.12 billion by 2031. These differing frames reflect the normal variation in forecasting assumptions, but they also reinforce that the sector is being watched closely and that growth potential is real even if the exact magnitude depends on methodology and scope.
Worldwide Exterior Solar Shading Systems Market
The competitive landscape appears to be evolving along three axes. First, integration is creating a divide between firms that can deliver shading as part of a coordinated building system and those that offer shading more narrowly. Second, material and compliance readiness is becoming a differentiator, especially where projects face stricter procurement screening or where end-users value cleaner formulations. Third, scale and distribution continue to matter, but they are increasingly complemented by software, service, and specification support capabilities. The market has not consolidated to the point where only a few players dominate, yet the advantages of combining product depth with control integration, material differentiation, and strong architectural relationships are becoming clearer. New entrants and investors are likely to be drawn to niches where performance claims can be substantiated, where integration with glazing or controls creates stickier project relationships, or where material innovation reduces long-term risk.
Forward-Looking Trends and Commercial Implications
Trend One: Shading as an Envelope-Level Performance Layer
Over the next three to five years, solar shading is likely to be treated less as an accessory and more as a functional layer within the building envelope. The commercial logic is straightforward: if shading can contribute to passive heat control, daylight quality, and ventilation performance, it becomes part of the architectural and engineering conversation rather than a late-stage fit-out decision. For manufacturers, this trend opens opportunities to engage earlier in the design process, align product specifications with energy modeling outcomes, and position solutions as part of integrated facade or glazing strategies. It also raises the stakes for product validation, because envelope-level claims invite closer scrutiny of performance, durability, and certification.
Trend Two: Cleaner Materials and Specification-Led Advantage
Material alignment with evolving expectations around chemical restrictions and environmental responsibility is likely to become a more visible competitive factor. Formulations and product families that are antimony-free and PFAS-free can lower friction in specification, procurement, and compliance review, especially in projects where material lists are tightly managed. This does not mean that every customer will prioritize material attributes equally, but it does suggest that cleaner profiles can serve as a differentiator in certain segments, support brand positioning, and reduce legal or reputational risk if regulations or buyer expectations tighten further. The commercial opportunity here is not simply in making a cleaner product, but in using that attribute to strengthen specification wins and reduce time spent managing compliance objections.
Trend Three: Automation, Controls, and Total Cost of Ownership Positioning
Automation and control integration will continue to gain importance, particularly in commercial and multi-family settings where operational efficiency and centralized management matter. Shading combined with lighting control, automated scheduling, and responsive daylight management can be framed around total cost of ownership rather than initial hardware cost. That framing creates room for premium positioning, recurring service relationships, and closer ties with building management ecosystems. It also creates execution risk: products that promise connectivity and automation must deliver reliability, user-friendly interfaces, and support structures that many traditional shading manufacturers have not historically emphasized. Firms that overpromise on smart features without the corresponding software and service capability may find their differentiation eroding quickly.
These trends carry uncertainty. Growth trajectories can be affected by construction cycles, interest rate environments, and the pace at which energy codes are adopted and enforced. Material transitions can introduce cost or supply challenges if alternative inputs are not scaled efficiently. Automation expansion can stall if interoperability issues, cybersecurity concerns, or integration complexity slow adoption. None of these risks negate the broader growth direction, but they do suggest that the market's next phase will reward companies that can combine credible performance claims with disciplined execution.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
- Prioritize envelope-level positioning where it fits your capability base. Products that can be articulated as part of facade, glazing, or ventilation performance are better placed to enter specification discussions earlier and command value beyond price comparison.
- Treat material and compliance readiness as strategic, not cosmetic. Where feasible, reduce reliance on substances that create future regulatory or procurement friction. Document performance and compliance claims in ways that support specification confidence and shorten approval cycles.
- Strengthen the integration bridge. If automation, controls, or facade coordination are part of your roadmap, invest as much in reliability, interoperability, and service as in feature announcements. Differentiation holds only when the operational experience matches the promise.
For Investors and Capital Allocators
- Look for durable differentiation rather than short-lived novelty. In a market growing at a steady but moderate pace, value creation increasingly depends on specification advantage, material positioning, and integration capability, not simply product introductions.
- Assess regional exposure carefully. Policy intensity, construction activity, and procurement norms vary, and the same product narrative may translate into strong demand in one market and limited pull in another. Diligence should map competitive positioning to where regulatory and demand signals are strongest.
- Watch for consolidation pressure around control, material, and architectural integration. Capital may flow toward companies that can connect shading to building performance outcomes in a credible, repeatable way, especially where those capabilities create stickier customer relationships.
For Procurement and Specification Teams
- Evaluate shading systems against total building performance, not just unit cost. Consider contributions to thermal comfort, daylight quality, ventilation, and operational savings, and ask for evidence that supports those claims in contexts similar to your project.
- Screen for compliance and service readiness early. Material profiles, certification status, and integration requirements can become decisive later in the project timeline if not addressed up front. Early diligence reduces rework and specification risk.
- Match product complexity to operational capacity. Highly automated or integrated systems can deliver meaningful benefits, but they also require appropriate maintenance, controls management, and support. Selecting a solution that your team can operate confidently is often more valuable than selecting the most feature-rich option.
The solar shading systems market is entering a period in which growth is supported by building performance expectations, regulatory attention, and evolving product architectures, but where differentiation will be earned through credible performance, cleaner material strategies, and integration capability. For companies and investors, the most valuable intelligence is the kind that connects macro growth signals to segment-specific behavior, competitive positioning, and specification dynamics. Detailed research that maps revenue splits, regional variations, application patterns, and company-level developments can sharpen those decisions significantly. For readers seeking a deeper, structured view of the market's segments, competitive moves, and scenario considerations, the full PW Consulting report provides a more granular foundation for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Solar Shading Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com