

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
LVT Flooring Market: Why 5.48% CAGR and Rigid Core Growth Shift the 2032 Outlook

Strategic Trends and Commercial Opportunities in the LVT Flooring Market
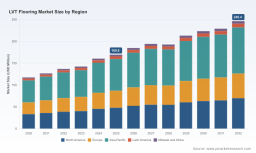
The global luxury vinyl tile (LVT) flooring market has matured from a niche alternative into a mainstream substrate for both residential and commercial interiors. Over the past five years, revenue growth has tracked consistent expansion, moving from approximately USD 117.5 million in 2020 to USD 169.6 million in 2025, with a projected trajectory reaching USD 246.4 million by 2032. The observed Compound Annual Growth Rate (CAGR) of 5.48 percent across the 2026–2032 forecast period signals that demand tailwinds remain intact, even as the market navigates structural volatility in raw materials, shifting trade policy, and evolving sustainability expectations. For executives, investors, and procurement teams, the critical question is no longer whether LVT will continue displacing traditional hard-surface alternatives, but how competing firms will navigate the next phase of differentiation, margin protection, and geographic rebalancing.
Market Snapshot and Structural Context
LVT flooring now operates in a landscape where growth is broad-based but uneven. Rigid-core formats dominate installed volume, while flexible variants maintain relevance in retrofit and performance-sensitive applications. Residential deployments continue to account for the largest share of end-use demand, yet commercial installations are gaining traction due to durability, maintenance economics, and design flexibility in hospitality, healthcare, and retail environments. Regional demand is distributed across mature and emerging markets, with Asia Pacific representing the largest revenue pool, North America and Europe holding substantial shares, and Latin America and the Middle East/Africa contributing smaller but increasingly strategic volumes as urbanization and renovation cycles accelerate.
PW Consulting Health Care Research Center
Market concentration remains relatively fragmented at the top, with the top three players holding roughly 12.0 percent and the top five around 15.0 percent of total revenue. That fragmentation is not a sign of immaturity; it reflects the presence of regional specialists, premium designers, and diversified building materials groups competing across price points, aesthetics, and sustainability credentials. In practice, the market rewards firms that can fuse product performance with supply chain resilience and regulatory readiness, rather than those that compete solely on footprint or price.
1. Market Status and Core Challenges
Robust headline growth masks several pressure points that are reshaping competitive dynamics. The LVT sector is entering a period in which incremental volume gains must be defended against cost volatility, trade disruption, and tightening environmental requirements. Three challenges stand out as especially consequential for strategic planning.
Raw Material Volatility and Margin Compression
Resilient flooring production is highly sensitive to the price and availability of PVC suspension resin, plasticizers, stabilizers, and reinforcing additives. Price movements in China—the benchmark hub for many resin transactions—have shown sharp swings driven by feedstock costs, logistics constraints, and regional supply adjustments. In early 2026, PVC suspension resin prices on a China FOB basis climbed to approximately USD 783.55 per metric ton by March, following an increase of roughly 20.90 percent from January, before easing later in the quarter as supply improved and spot pricing moderated to around 5.60 RMB/kg. These swings create a recurring margin squeeze for manufacturers who cannot pass through input costs quickly enough or who lack long-term contractual hedges. Larger players have responded with selective pricing actions, but sustained inflation in end-market prices can dampen demand elasticity, particularly in price-sensitive segments.
Trade Policy and Regional Cost Dislocation
Tariff escalation has added a second layer of complexity, particularly for markets that depend on cross-border sourcing. In the United States, baseline tariffs on Chinese LVT flooring imports rose to 145 percent effective April 2025, with additional country-specific surcharges applied to major source regions. This shift has re-weighted sourcing calculus for distributors and manufacturers, prompting re-evaluation of dual-sourcing strategies, regional capacity deployment, and logistics routing. For producers importing resin or finished goods, the cost base has become less predictable, and for buyers, landed cost comparisons across origins require more granular analysis than in prior years.
Luxury Vinyl Tile (LVT) Market
Sustainability Credentials as a Commercial Gatekeeper
Environmental performance is transitioning from a differentiator to a procurement prerequisite. Builders, architects, and property managers increasingly evaluate flooring on low-VOC emissions, recyclability, PVC-free options, and circular design attributes. Regulatory scrutiny is intensifying in parallel: India’s Directorate General of Trade Remedies initiated a countervailing duty investigation into Chinese PVC suspension resin imports in 2025, noting that Chinese PVC accounted for nearly 47 percent of domestic suspension resin imports. Such developments illustrate how material sourcing, trade policy, and environmental compliance are converging into a single strategic risk domain. Firms that lack credible sustainability narratives or traceable sourcing may face longer sales cycles, specification barriers, and heightened exposure to regulatory shifts.
2. Key Drivers Shaping the Market
Despite the challenges, the LVT market is being propelled by a set of durable drivers that create opportunities for companies willing to invest in product architecture, operational flexibility, and customer value propositions. Four forces are especially salient.
Technological Innovation in Core Architecture and Performance
Product engineering continues to expand the functional envelope of LVT. Rigid-core formats, including stone plastic composite and wood plastic composite constructions, provide improved dimensional stability, moisture resistance, and installation tolerance, making them suitable for basements, kitchens, and commercial spaces with elevated wear requirements. Hybrid offerings that blend rigid-core durability with flexible installation characteristics address a broader set of substrates and end-use conditions. Manufacturers are also advancing surface designs that more closely replicate wood, stone, and textured concrete, reducing the aesthetic gap that once limited LVT adoption in premium segments. The commercial effect is twofold: higher willingness to pay in design-led applications and reduced failure rates in demanding environments, both of which support margin and repeat purchase behavior.
Policy and Regulatory Signals Steering Material Choices
Policy is not merely a constraint; it is shaping demand toward specific material pathways. Low-VOC formulations, recyclable backing systems, and reduced reliance on conventional PVC are increasingly rewarded in specification processes and green-building frameworks. Product launches in 2025 and early 2026 reflect this direction. In March 2025, Armstrong Flooring introduced an eco-friendly LVT collection with 100 percent recyclable backing and low VOC emissions, signaling a focus on circularity and indoor air quality. In January 2026, Tarkett unveiled the ReNue hybrid non-PVC residential resilient flooring collection, expanding its LVT/SPC/WPC range with sustainability credentials. For commercial players, these moves indicate that compliance and certification are becoming part of the product’s value proposition, not just a regulatory checkbox.
Demand-Side Shifts in Residential and Commercial Environments
Consumer and enterprise behavior continues to favor resilient flooring for practical and aesthetic reasons. In residential settings, homeowners and renters seek waterproof, durable, and visually versatile surfaces that can accommodate active living, pet traffic, and easy maintenance. The renovation cycle in aging housing stock and the expansion of multifamily construction sustain demand for products that install efficiently and perform across moisture-prone areas. In commercial environments, facility managers prioritize lifecycle cost, hygiene, and design consistency. LVT’s capacity to deliver modular replacement, uniform appearance, and resilience under foot traffic supports its adoption in retail, hospitality, and healthcare. Notably, demand is not monolithic: premium designer collections appeal to specifiers looking for texture realism and brand-aligned aesthetics, while value-oriented rigid-core products serve volume-driven projects where total cost and durability dominate decisions.
Supply Chain Realignment and Capacity Investment
Capacity expansion and sourcing strategy are becoming competitive levers. In October 2024, Shaw Industries announced a USD 90 million investment at its Ringgold, Georgia Plant RP to double SPC and LVT production capacity by 2026, illustrating how producers are building regional manufacturing buffers to reduce exposure to import volatility and improve service reliability. At the same time, raw material dynamics are forcing more active procurement postures. Mohawk Industries initiated pricing increases across regions and product categories in 2025 to offset material cost rises, including tariff impacts, according to its 2025 Annual Report. These adjustments reflect a broader pattern: companies are balancing capacity investment with pricing discipline to protect margins without sacrificing volume. The strategic implication is clear—supply chain design is now inseparable from competitive positioning.
3. Competitive Landscape and Leading Strategies
The competitive field combines large diversified manufacturers, regionally anchored producers, and premium specialists. This mix creates a multi-layered market in which advantage depends on the alignment of product portfolio, manufacturing footprint, sustainability narrative, and commercial execution.
Strategic Positioning of Leading Players
Several companies illustrate distinct competitive postures that are shaping the market’s evolution.
- Mohawk Industries operates as one of the world’s largest flooring manufacturers, with PVC-free hybrid resilient offerings and SPC/LVT lines emphasizing high recycled content and waterproof performance. Its recent pricing actions across regions and categories underscore a strategy of protecting margins in the face of input cost and tariff pressure, while maintaining a broad portfolio that serves multiple price tiers.
- Shaw Industries produces SPC, flexible LVT, and rigid-core LVT with a strong emphasis on ecoWorx PVC-free and circular design solutions. Its USD 90 million capacity expansion in Georgia reflects a strategy centered on regional supply reliability, scale in resilient formats, and sustainability-aligned product architecture.
- Armstrong Flooring leads in LVT and modular resilient flooring, with eco-friendly collections featuring low-VOC formulations and recyclable backing. Its March 2025 product launch reinforces a positioning built around indoor environmental quality and end-of-life considerations, appealing to specifiers and buyers prioritizing health and circularity.
- Mannington Mills remains a family-owned producer known for ADURA luxury vinyl plank and tile collections with American-made options that stress innovation and quality. Its posture illustrates the value of brand trust, craftsmanship emphasis, and product consistency in premium and mid-premium segments.
- Tarkett is a global leader in resilient flooring, offering layered non-PVC LVT planks and tiles, SPC, WPC, and hybrid ReNue lines with sustainability certifications. Its January 2026 collection expansion highlights a strategy of broadening material alternatives while reinforcing environmental credentials across residential and commercial lines.
- Karndean Designflooring specializes in premium designer LVT with a focus on durable, aesthetically superior collections. Its positioning shows that design fidelity and texture realism can command loyalty in specification-driven projects where appearance is a primary decision factor.
- COREtec Floors focuses on rigid-core SPC and WPC LVT alternatives with advanced technology for moisture-prone areas. Its specialization demonstrates the commercial potential of targeted performance claims in segments where installation risk and environmental exposure are key concerns.
Differentiation Levers and Market Evolution
Across these profiles, differentiation is concentrating around several levers: material composition and environmental attributes, core technology and moisture performance, design realism and surface durability, regional manufacturing and supply continuity, and pricing strategy in response to input volatility. The market is not moving toward a single winner-takes-all structure. Instead, it is evolving through a combination of consolidation at the scale end and fragmentation at the specialty end. Larger players are expanding capacity and broadening eco-oriented portfolios to serve specification pipelines and national distribution networks. Specialists are deepening niche authority in premium design or performance-sensitive applications. At the same time, trade and material pressures are encouraging more regionalized sourcing and production, which can benefit locally anchored manufacturers while raising the entry bar for undifferentiated exporters.
A notable trend is the convergence of sustainability and performance in product messaging. The most resilient strategies pair credible environmental attributes with durable, installable, and maintainable products. Where sustainability is presented without performance credibility, it risks being discounted in commercial evaluations; where performance is advanced without environmental readiness, it may face growing specification friction. The leaders are therefore integrating both dimensions into product development, marketing, and supply chain decisions.
4. Future Trends and Commercial Opportunities
Looking ahead three to five years, the LVT market is likely to be shaped by several interconnected trends. Each carries explicit implications for strategy, investment, and procurement.
Trend 1: Material Diversification and PVC-Alternatives Gain Commercial Weight
As environmental scrutiny and regulatory attention intensify, material diversification will move from exploratory to mainstream. Non-PVC and PVC-reduced constructions, recyclable backing systems, and hybrid core designs will become more common across residential and commercial lines. This shift creates opportunities for manufacturers that can deliver comparable performance with alternative material architectures, as well as for distributors and specifiers who can offer clients a broader menu of compliant options. The commercial prize is not simply greener marketing; it is access to projects where material restrictions, indoor air quality targets, and circular economy goals influence specification and procurement. The uncertainty lies in verifying that alternative formulations maintain durability, moisture resistance, and cost competitiveness at scale.
Trend 2: Regionalization of Capacity and Sourcing as a Margin Defense
Tariff escalation, resin price volatility, and logistics uncertainty are likely to reinforce regionalization strategies. Producers will continue to invest in local or near-local capacity to reduce lead times, mitigate import cost shocks, and improve service levels. Buyers will increasingly favor suppliers with transparent sourcing, predictable landed costs, and contingency options across geographies. This trend favors firms that can combine capacity flexibility with disciplined procurement and pricing mechanisms. The risk is that regionalization may raise capital intensity and limit scale advantages for smaller players, potentially widening the gap between integrated manufacturers and niche producers unless the latter can secure differentiated positioning or partnership-based distribution.
Luxury Vinyl Flooring (LVT) Market
Trend 3: Premiumization in Design Coexisting with Value-Driven Volume Growth
The market will likely sustain a two-track dynamic. On one track, premium designer collections will grow by delivering superior aesthetics, texture realism, and brand-aligned experiences for specification-led projects. On the other, value-oriented rigid-core products will continue to capture volume in residential renovations, multifamily builds, and commercial renovations where total cost, durability, and installation efficiency matter most. This bifurcation creates opportunities for portfolios that can serve both tracks without cannibalizing brand equity. Manufacturers that can modularize platforms—sharing core technology while differentiating surface design, finish, and sustainability credentials—will be better positioned to capture share across segments. The uncertainty is that design-led premiumization depends on macroeconomic confidence and discretionary spending, while value-driven growth is more sensitive to raw material inflation and tariff-induced price increases.
5. Actionable Guidance for Decision-Makers
For executives and strategy teams, the practical implications of these trends can be translated into focused actions tailored by role.
For Manufacturers and Brand Owners
- Align product development with both performance and environmental credibility. Prioritize formulations and backing systems that reduce VOC emissions, improve recyclability, or offer PVC-reduced alternatives without sacrificing moisture resistance or dimensional stability.
- Build pricing and procurement flexibility into the operating model. Use a mix of long-term input contracts, regional sourcing options, and scenario-based pricing to manage resin volatility and tariff exposure, rather than relying on reactive price changes alone.
- Invest in capacity where service reliability and cost predictability matter most. Regional production can reduce lead-time risk and improve responsiveness to specification pipelines, especially in markets with elevated import costs.
For Investors and Corporate Development Teams
- Evaluate exposure to material and trade risk as part of valuation. Companies with diversified sourcing, regional manufacturing, and credible sustainability portfolios may show greater resilience to input shocks and specification barriers.
- Look for platforms that can serve both premium and value segments through shared core technology and differentiated surface or sustainability attributes. Such platforms can capture broader demand cycles while preserving margin structure.
- Monitor regulatory developments in material trade and environmental compliance, particularly where investigations or tariff actions affect resin imports and finished product flows. These dynamics can reshape cost structures and competitive positioning quickly.
For Procurement and Specification Teams
- Compare total cost of ownership rather than upfront price alone. Installation tolerance, moisture performance, maintenance requirements, and warranty terms can materially affect lifecycle economics in both residential and commercial deployments.
- Incorporate sustainability criteria early in specification and sourcing decisions. Recyclable backing, low-VOC emissions, and lower-PVC options increasingly influence project approval and stakeholder acceptance, especially in green-building contexts.
- Diversify supplier options to manage tariff and logistics risk. Dual-sourcing across regions, combined with clear landed-cost analysis, can reduce exposure to sudden duty changes or resin price spikes.
The LVT flooring market is at a point where growth is supported by durable demand, but the path to profitable growth is increasingly shaped by material volatility, trade policy, and environmental expectations. Firms that treat these forces as strategic variables—rather than external noise—will be better positioned to protect margins, win specifications, and expand share across segments. For decision-makers seeking a deeper view of segment-level dynamics, regional cost structures, and customized scenario planning, a comprehensive market research report offers the granularity needed to translate these trends into concrete operating choices.
For detailed analysis of this topic, please visit the official page: LVT Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com