

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hotel Furniture Market Outlook: Decoding the 4.92% CAGR Growth Path to 2032

Strategic Trends and Commercial Opportunities in the Hotel Furniture Market
Market Overview and Core Challenges
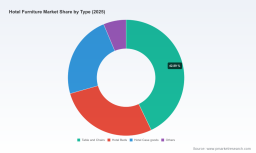
The hotel furniture market has demonstrated steady expansion over the past five years, growing from approximately 18.9 billion USD in 2020 to an estimated 23.15 billion USD in 2025. Looking ahead, the market is projected to reach 32.66 billion USD by 2032, expanding at a compound annual growth rate of 4.92 percent during the 2026 to 2032 forecast period. This trajectory reflects a mature but still growing sector fueled by hospitality recovery, renovation cycles, and evolving guest expectations. The moderate pace of growth signals a market that is expanding reliably rather than surging unpredictably, which makes strategic positioning and cost discipline especially important for participants.
Several structural challenges are reshaping how operators, manufacturers, and investors approach this landscape. The first challenge centers on pricing volatility and tariff exposure. The cost environment for imported wooden furniture, fixtures, and equipment has shifted dramatically, introducing uncertainty into project budgeting and renovation timelines. The second challenge involves the tension between standardization and customization. Large hotel brands seek repeatable, cost-efficient designs for scaled deployment, while boutique and luxury properties demand bespoke aesthetics and material quality. Navigating both demands simultaneously creates operational and design complexity. The third challenge relates to supply chain resilience and lead time predictability. Post-pandemic normalization has improved, but localized disruptions, freight fluctuations, and raw material constraints still affect the reliability of large FF&E deployments. These challenges are not temporary headwinds. They are structural forces that will influence margin profiles, sourcing strategies, and product development priorities through the rest of the decade.
Office Furniture Market
Key Drivers Shaping Market Dynamics
Technology and Design Innovation
Innovation in hotel furniture is increasingly driven by durability, multifunctionality, and material efficiency rather than novelty alone. Manufacturers are prioritizing designs that withstand high turnover, simplify maintenance, and support space optimization in guestrooms and common areas. Improved finishing processes, reinforced joinery, and modular components are enabling products that can be refurbished or reconfigured with less downtime. Digital tools in design and prototyping are also accelerating custom execution, allowing shorter feedback loops between hotel operators and suppliers during fit-out or renovation phases. For high-volume business hotels, efficiency-focused design reduces total cost of ownership. For luxury and boutique properties, advanced casegoods and upholstered solutions support distinctive branding without sacrificing longevity.
Wood Furniture Market
Policy and Regulatory Environment
Trade policy and regulatory changes are now a central factor in hotel furniture sourcing decisions. Tariff adjustments have altered the cost structure for imported upholstered wooden furniture and cabinetry, with some categories facing substantial rate increases during recent periods. These shifts matter because FF&E can represent a meaningful share of hotel renovation budgets, so pricing shock in this segment directly affects project feasibility. At the same time, selective policy actions have provided temporary relief or clarified the scope of certain duties on wooden furniture products, creating a moving landscape rather than a fixed cost baseline. For hoteliers and manufacturers, the practical implication is that sourcing strategies must account for potential tariff volatility, not just current pricing. This has increased interest in domestic production options, multi-source procurement, and earlier procurement timing to reduce exposure to mid-project cost escalation.
Demand-Side Evolution in Hospitality
Demand patterns are changing the type of furniture that properties need to procure. Business hotels continue to prioritize durable, standardized solutions that support rapid room turnover and consistent guest experience across multiple locations. Luxury hotels are pursuing higher specification materials, layered textures, and refined upholstery that communicate premium positioning. Boutique hotels often require smaller production runs with stronger design personality, which places pressure on manufacturers to offer flexibility without excessive minimum order constraints. Another important shift is the growing attention to outdoor and semi-outdoor hospitality spaces, especially in destinations where weather-resistant furnishings can extend usable property area and improve guest experience. Across these segments, the underlying trend is a demand for furniture that supports both brand expression and operational durability.
Supply Chain and Cost Structure Adjustments
Supply chain strategy is becoming a differentiator rather than a back-office function. Cost structures are being reshaped by raw material movements, including changes in softwood lumber pricing and related derivatives, which have influenced the economics of upholstered furniture and casegoods production. Manufacturers are responding with a combination of sourcing diversification, inventory anticipation for high-priority product lines, and closer coordination with project schedules to reduce rush exposure. For buyers, this environment rewards earlier planning and clearer specification packages. For suppliers, it creates opportunity for manufacturers that can demonstrate reliable lead times, transparent cost communication, and the ability to provide realistic alternatives when material constraints appear. The companies gaining ground are those that treat procurement continuity as part of product value, not just logistics.
Competitive Landscape and Leading Strategies
The competitive field includes established U.S. manufacturers with deep hospitality specialization, international producers with scale and customization capacity, and niche players focused on specific product categories or environments. Leading firms typically differentiate through product breadth, design expertise, customization capability, and the ability to support large project deployments with consistent quality. In this market, scale alone is not the deciding advantage. The more durable advantage comes from combining dependable execution with the flexibility to meet varying brand standards, from business hotel standardization to luxury custom casegoods and upholstered collections.
Several competitive patterns are visible across the leading participants. One is the emphasis on hotel-specific product families. Suppliers such as Kimball Hospitality, Bernhardt Hospitality, Charter Furniture, and Dickson Furniture have built reputations around casegoods, beds, seating, and upholstered solutions designed directly for commercial hospitality use. Their positioning is strongest when they can offer repeatable designs that still allow room for customization by brand or property type. A second pattern is the role of international manufacturers in providing breadth and project-scale capability. Companies such as Mingsun Group, RON Group, Fulilai Hotel Furniture, and Harman Furniture Group illustrate the growing importance of suppliers that can handle multi-room packages, custom casegoods, and FF&E coordination for larger hospitality projects. Their value often lies in combining volume capacity with design responsiveness, especially when hoteliers are managing complex fit-outs or renovation programs. A third pattern is category specialization. MityLite’s focus on durable tables and chairs for hotel and hospitality settings, Abel Corporation’s architectural millwork and live mockup capabilities, and Grosfillex’s specialization in outdoor and durable hospitality furniture show that targeted expertise can create strong competitive moats, particularly when a property type or environment demands specific performance characteristics.
Recent developments reinforce the importance of visibility and market engagement. Trade show participation and new product catalog releases remain central tools for launching hospitality collections and signaling design direction to buyers. These activities are not merely promotional. They are practical mechanisms for testing market interest, refining product offerings, and aligning manufacturers with the specifications hotel buyers are prioritizing in the current cycle. At the same time, the broader competitive landscape is likely to evolve through selective consolidation among mid-tier suppliers, increased emergence of design-led smaller brands in the boutique and lifestyle segments, and continued pressure on cost and delivery reliability across the supply base. The winners will be those that can combine a credible design narrative with dependable execution and adaptable sourcing strategies.
Forward-Looking Trends and Commercial Opportunities
Trend One: Greater Sourcing Flexibility and Risk-Adjusted Procurement
Over the next three to five years, procurement strategies are likely to place greater weight on trade-policy resilience and cost predictability. Hoteliers and developers will increasingly favor suppliers that can offer alternative sourcing paths, transparent lead times, and proactive communication about cost exposure. For manufacturers, this creates an opportunity to differentiate through supply continuity, regional production options, and stronger project planning support. For investors and operators, it suggests that supplier relationships with demonstrated flexibility may reduce downstream cost surprises and timeline risk, especially in renovation programs where FF&E decisions intersect with broader capital planning.
Trend Two: Durability and Multifunctionality as Core Value Drivers
As hotel operators balance aesthetic ambition with operational realism, furniture that performs well under heavy use and supports multiple functions will continue to gain relevance. This includes products that simplify cleaning, reduce replacement frequency, and adapt to changing room layouts or hospitality concepts. The commercial opportunity lies in product lines that can lower lifecycle costs without sacrificing guest-facing quality. Manufacturers that can articulate total cost of ownership, not just upfront price, will be better positioned in both business hotel and luxury environments, because both segments need to justify spend under tighter capital discipline.
Trend Three: Outsourced Design Differentiation for Distinctive Guest Experiences
A further trend is the continued demand for furniture that helps properties create memorable environments. Boutique and luxury hotels are likely to persist in seeking casegoods and upholstered pieces that contribute to a coherent design story, while business hotels will continue to prioritize scalable but refined solutions. The opportunity here is for manufacturers and suppliers that can offer modular customization, consistent quality across batches, and faster turnaround on variation orders. This is especially relevant for properties trying to stand out in competitive markets without committing to fully bespoke programs for every item.
These trends carry risks and uncertainties. Tariff and trade policy volatility can shift cost assumptions quickly, affecting margin planning and project economics. Raw material availability and freight dynamics may continue to create intermittent lead-time pressure. In addition, differentiation strategies that depend heavily on custom production can become expensive if order volumes are uneven or if project pipelines are delayed. Navigating these risks requires a balance between design ambition, operational efficiency, and procurement discipline.
Actionable Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to strengthen resilience and clarity in what is offered to hospitality clients. Product portfolios should be evaluated for durability, lead-time reliability, and the ability to support both standardized and customized orders without excessive complexity. It is equally important to communicate cost structure and sourcing options transparently, because trade-policy volatility has made uncertainty a real planning concern for buyers. Companies that can provide reliable alternatives, earlier visibility into supply constraints, and credible project support will be better positioned to win and retain hospitality contracts over the forecast period.
For investors, the key is to assess which business models are built for durability rather than short-term pricing advantage. Look for suppliers with demonstrated capability in hospitality-specific product families, strong execution around lead times and project coordination, and sourcing flexibility that can absorb trade or material shocks. Businesses that rely heavily on single-source exposure or that lack clear differentiation in quality and service may face greater volatility as procurement teams seek more predictable partners. In a market growing at a moderate but consistent pace, value creation is likely to accrue to companies that can combine product relevance with operational reliability.
For hotel operators, developers, and procurement teams, the most practical move is to treat furniture sourcing as an integrated part of project planning rather than a last-stage purchase decision. Earlier involvement of suppliers, clearer specification packages, and evaluation of total lifecycle cost can reduce exposure to tariff-driven price changes and lead-time uncertainty. Properties should also weigh the balance between standardization and customization based on brand strategy and renovation timeline, because over-customization can introduce cost and schedule risk while over-standardization may weaken the guest experience. Selecting partners based on design capability, delivery reliability, and risk communication can improve project outcomes across business, luxury, and boutique segments.
PW Consulting Health Care Research Center
For decision-makers seeking more granular segmentation data, regional demand patterns, and tailored scenario planning, deeper commercial research can provide sharper inputs for procurement strategy, capacity planning, and investment evaluation. A more detailed review of product-level splits, competitive positioning by segment, and policy-sensitive cost scenarios can help translate these market themes into specific action plans for individual portfolios and projects.
For detailed analysis of this topic, please visit the official page: Hotel Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com