
Blogs
PW Consulting Report: Die Cutting Market Hits $6.55 Billion in 2025, Forecasted to Reach $9.12 Billion by 2032
By pmarketresearch, 2026-09-16
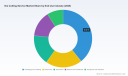
Strategic Intelligence for a Transforming Market: Introducing the Worldwide Die Cutting Service Market Research
The global die cutting service industry stands at a critical inflection point. With the market projected to reach approximately $9.12 billion by 2032 and a compound annual growth rate of 4.85 percent across the forecast horizon, the sector is no longer defined solely by mechanical precision or steady manufacturing demand. It is being reshaped by material cost volatility, sustainability mandates, accelerated technology adoption, and an increasingly fragmented competitive landscape. For executives navigating procurement strategy, capacity planning, or market entry decisions in 2026, superficial summaries are no longer sufficient. This article previews the strategic architecture of our latest Worldwide Die Cutting Service Market research and outlines why this intelligence is essential for decisive, future-ready corporate action.
A Data-Backed View of Market Momentum: 2020 Through 2032
Our analysis tracks a clear upward trajectory across the historical and forecast periods. From 2020 through 2025, the market expanded from roughly $5.12 billion to $6.55 billion, reflecting resilience despite macroeconomic pressures, supply chain realignment, and raw material price fluctuations. The forecast period from 2026 to 2032 extends that momentum, with revenue climbing through 2028 before a notable acceleration drives the market toward its 2032 endpoint. The overall trajectory underscores a structurally growing demand environment rather than a cyclical spike, but growth is not uniform. It is being pulled forward by specific process innovations, regional production shifts, and end-use industries that demand tighter tolerances, faster turnaround, and increasingly sustainable material formats.
Worldwide Die Cutting Service Market
For corporate strategists, this pattern matters because it reveals where investment and differentiation are likely to compound. The forecast period does not simply show higher aggregate revenue; it highlights a market in which operational capability, technological readiness, and regulatory compliance will increasingly separate winners from commoditized service providers. Decision-makers who understand the underlying drivers early can align capacity, vendor selection, and product-development roadmaps accordingly, rather than reacting after cost structures or customer expectations have already shifted.
Why This Research Is Designed for 2026 Decision-Makers
The Worldwide Die Cutting Service Market research is built around actionable clarity, not abstract market description. It is structured to support board-level planning, operations leadership, procurement strategy, and competitive positioning. The report integrates market sizing, segmentation, competitive profiling, and recent industry developments into a single decision-oriented framework. Readers will find a detailed mapping of process types, end-use applications, and regional demand patterns, alongside practical insights on how technology adoption and regulatory change are altering cost dynamics and service expectations.
Beyond descriptive market structure, the study examines the strategic implications of recent capital investments, equipment launches, and corporate transactions that are reshaping service capabilities. It also contextualizes raw material pricing trends and policy developments that directly affect conversion economics and compliance planning. The goal is to give executives a defensible basis for evaluating supplier partnerships, assessing technology upgrade priorities, and anticipating where service requirements will tighten over the next several years. Rather than delivering a static snapshot, the research is designed to support scenario planning in an environment where pricing, capacity, and sustainability expectations are all moving at once.
Segmentation and Demand Drivers: Where Value Is Concentrating
The market is shaped by three structural dimensions: process type, end-use industry, and regional demand. Each dimension carries distinct implications for service providers and buyers.
Process Landscape and Capability Shifts
Die cutting services are delivered through multiple conversion methods, each with different throughput characteristics, precision profiles, and capital requirements. Rotary die cutting remains a dominant pathway for high-volume production, particularly where speed, repeatability, and integrated printing or converting capabilities are essential. Flatbed die cutting continues to serve applications that demand flexibility, precision geometry, and lower setup friction for shorter runs or more complex layouts. Laser die cutting adds a further dimension by enabling intricate cuts and reducing tooling dependency in specialized use cases. Alongside these established approaches, additional process variants support niche requirements and hybrid converting workflows.
From a strategic standpoint, the relevant question is not which process is largest in isolation, but where demand is migrating as customers balance volume efficiency against customization, waste reduction, and compliance-driven material changes. The report evaluates how service providers are positioning themselves across these process categories and where equipment investment is likely to widen competitive gaps.
End-Use Industries as Demand Anchors
Demand for die cutting services is distributed across a diversified set of end-use industries, each with different performance requirements and procurement cycles. Packaging and labeling continues to be a central demand driver, reflecting the ongoing need for precise blanks, inserts, protective structures, and labeled components across consumer goods, e-commerce, and industrial supply chains. Electronics represents another significant demand pool, where tight tolerances, clean processing, and specialized material handling are increasingly important. Automotive applications add further volume and complexity, particularly as component specification and lightweighting requirements tighten. Medical and healthcare demand introduces strict quality, traceability, and material-compatibility expectations. Aerospace and industrial applications complete the picture with specialized performance thresholds and lower-volume but higher-value part requirements.
Importantly, these end-use segments do not grow in lockstep. Their relative influence on market expansion depends on production localization, regulatory pressure on materials, and the pace of product innovation. The research dissects how each vertical shapes service expectations and where suppliers can capture differentiation through process control, material expertise, or integrated converting capabilities.
Regional Demand and the Geography of Service Delivery
Regional demand patterns reflect broader manufacturing footprints, packaging consumption habits, and local regulatory environments. North America and Europe remain major demand centers with mature service ecosystems, while Asia Pacific stands out for its scale and ongoing production-network expansion. Latin America and the Middle East and Africa contribute additional regional demand, though from smaller bases, and are influenced by import dynamics, localized manufacturing strategies, and evolving logistics patterns.
Because regional markets differ in cost structures, supplier density, and compliance obligations, a single global strategy rarely fits all operating contexts. The report maps these regional differences in a way that helps organizations assess where to consolidate sourcing, where to diversify supply, and where regional capability gaps may create strategic risk or opportunity.
Competitive Landscape and Strategic Positioning
The competitive environment in die cutting services is characterized by a wide mix of specialized converters, packaging-focused service providers, and broader industrial material suppliers. Market concentration remains relatively modest at the top tier, with the top three firms holding a combined share in the low double digits and the top five firms still occupying a limited portion of total market revenue. This fragmentation suggests that scale alone is not the only route to advantage. Service quality, material versatility, process flexibility, and customer-specific engineering capability continue to matter deeply, especially in applications where precision, turnaround speed, and compliance are decisive.
Several U.S.-based specialists illustrate the depth of capability across the market. Colvin-Friedman Company has built a long-standing reputation for precision custom die cutting across more than twelve industries, emphasizing material versatility and decades of converting experience. Mills Industries focuses on precision die cutting for custom plastic corrugated packaging, including inserts, dividers, dunnage, bins, and protective solutions. LMI Packaging concentrates on precision die-cutting for lids and labels in packaging applications, with an emphasis on quality and strict specification requirements. Janco, Inc. delivers custom die cutting services for foam, plastic, and related materials across packaging, industrial, and medical sectors using rotary, flatbed, and steel rule methods. MCL Industries Inc. operates as a leading provider of rotary and flatbed die cutting services for plastics, foams, and related materials, offering turnkey converting for high-volume packaging production. Best Cutting Die supplies custom dies and die cutting solutions designed specifically for packaging processes, aiming to minimize downtime and support efficient production. The Strouse Corporation, American Industrial Company, and Gardico Inc each bring additional depth in custom parts, precision components, and long-standing service orientation across packaging and industrial applications.
At the same time, larger international players are shaping the broader market through scale, capital investment, and sustainability-focused innovation. DS Smith has moved aggressively into advanced rotary die-cutting capacity, including recent investment in high-precision corrugated board conversion. Mondi emphasizes die-cut carton and board solutions tied to sustainable packaging applications, while Smurfit Westrock continues to compete as a leading provider of die-cut boxes and cartons in corrugated and folding carton markets. Equipment and converting-technology suppliers also influence service capabilities indirectly by setting performance standards and enabling faster, more precise production. BOBST supports converting services and supplies advanced flatbed and rotary die-cutting equipment for folding carton and corrugated board packaging. MM Packaging specializes in die-cutting and creasing processes for cartonboard packaging to produce precise blanks for efficient forming.
The strategic takeaway is that competitive advantage in this market is increasingly multidimensional. Providers are competing not only on price, but on process reliability, material breadth, sustainability alignment, and the ability to integrate die cutting into broader converting and packaging workflows.
Recent Developments Reshaping Market Dynamics
Recent corporate and technology developments underscore how quickly the operational baseline is changing. In March 2026, DS Smith invested DKK 100 million to install an advanced rotary die-cutting line with flexographic printing at its Grenaa facility in Denmark, increasing corrugated board capacity by up to 15 million square meters annually while improving precision on complex die cuts and reducing waste. This kind of investment signals the market's direction: higher throughput, better precision, and stronger emphasis on material efficiency.
In May 2025, Winkler+Dünnebier completed the acquisition of Sysco Machinery Corporation, adding advanced rotary die-cutting, slitting, and rewinding technologies for converting and packaging applications. The transaction illustrates how equipment and converting capability are being consolidated to strengthen integrated service offerings. In March 2025, BOBST launched the MASTERCUT 106 PER flatbed die-cutter at drupa 2025, showcasing 8,000 sheets per hour speed, quick-change capabilities, and a digital performance platform for folding carton and packaging production. Product launches like this expand the practical ceiling for conversion speed and flexibility, raising expectations for service providers who rely on or partner with equipment suppliers.
These developments matter because they affect more than individual companies. They shift customer expectations around lead times, precision, waste reduction, and integrated capability. They also influence the cost and risk profile of maintaining competitive service quality, especially for organizations that must meet increasingly demanding specifications without sacrificing throughput.
Raw Material Pressure and Regulatory Disruption
Market dynamics are not driven only by equipment and competition. Cost volatility and regulatory change are reshaping the operating environment at the same time. Recent pricing data shows continued pressure in corrugated and solid fiber box manufacturing inputs. The U.S. Producer Price Index for corrugated and solid fiber box manufacturing, specifically corrugated paperboard in sheets and rolls, reached 390.002 in March 2026. At the same time, corrugated paper prices in Northeast Asia were reported at 0.41 USD per kilogram in March 2026, compared with around 0.30 USD per kilogram in North America. These differences matter for sourcing strategy, margin planning, and regional service economics, especially for organizations exposed to cross-border supply chains or multi-site procurement.
On the regulatory side, packaging and paper product responsibility is advancing rapidly in the United States. Seven states, including California, Colorado, Maryland, Maine, Minnesota, Oregon, and Washington, have enacted Extended Producer Responsibility laws for packaging and paper products, with ongoing implementation through 2026. In early 2026, Wisconsin and New Hampshire introduced EPR bills covering packaging, paper products, and beverage containers. Minnesota's packaging EPR framework requires producers to participate through a producer responsibility organization, with a needs assessment due by December 2026.
For die cutting service buyers and providers, these policies are not background noise. They influence material selection, waste-reduction priorities, reporting obligations, and the relative attractiveness of sustainable packaging formats. In practical terms, they can alter demand patterns for certain substrates, affect the cost of compliance, and reward service partners that can support material reduction, recyclability, or responsible sourcing claims with credible operational execution.
What the Full Report Delivers
The Worldwide Die Cutting Service Market research is designed to turn these forces into usable strategy. It combines market sizing and forecast context with segmentation analysis across process types, end-use industries, and regions. It profiles the competitive landscape and recent developments that are actively reshaping service capabilities. It also embeds the cost and regulatory environment into the analysis so that executives can evaluate not only where the market is heading, but what it will take to compete effectively within it.
Personal Electronic Die Cutting Market
Because this is a fast-moving market, the report is intended to support concrete decisions: how to structure supplier relationships, where to invest in process flexibility, how to anticipate compliance-driven material shifts, and how to position offerings in a fragmented but increasingly capability-sensitive market. The full dataset, segmentation detail, company profiles, and forward-looking scenario framing are available in the complete study.
Next Steps for Strategic Readers
If your organization is evaluating market entry, supplier consolidation, capacity expansion, or packaging and converting strategy for the 2026 to 2032 period, this research is built to inform those choices with rigor and commercial relevance. The executive summary and full market framework provide the level of detail required to move from general awareness to actionable intelligence. Readers seeking a complete view of segmentation splits, competitive positioning, regional dynamics, and the latest market developments are encouraged to access the full report through the source page, where the underlying data, profiles, and scenario context are presented in full.
For detailed analysis of this topic, please visit the official page: Worldwide Die Cutting Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Civil Engineering Shape Memory Alloys Hit $245.5M in 2025, Growing 8.5% to $434.58M by 2032
By pmarketresearch, 2026-09-16
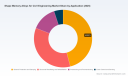
Unlocking the Future of Structural Resilience: A Strategic Overview of the Shape Memory Alloys in Civil Engineering Market 2026-2032
The global civil infrastructure landscape is undergoing a fundamental transformation. Driven by aging assets, increasing seismic risks, and the urgent demand for sustainable construction methodologies, engineers and investors are turning toward advanced material sciences to redefine structural integrity. At the forefront of this technological shift is the Shape Memory Alloys (SMA) sector. As we move further into 2026, the convergence of material innovation and structural engineering necessity presents a compelling investment thesis.
PW Consulting has released our comprehensive Worldwide Shape Memory Alloys for Civil Engineering Market research to provide stakeholders with the granular intelligence required to navigate this evolving terrain. This article serves as a strategic preview of the findings, highlighting the macro-economic trajectory, competitive dynamics, and technological catalysts that will define the market through 2032.
The Macro-Economic Trajectory: Growth Amidst Complexity
The expansion of the SMA civil engineering market is not merely incremental; it represents a structural recalibration of how infrastructure is built and maintained. Our analysis tracks revenue developments from 2020 through the forecast period ending in 2032. The historical data indicates a steady climb in market valuation, reflecting early adoption phases transitioning into broader commercial viability. Starting from a baseline in the mid-2020s, the market has demonstrated resilience despite global supply chain volatility.
Looking forward, the growth curve is projected to accelerate. The overall market size trajectory suggests a significant uplift in capital allocation toward SMA-integrated projects over the next decade. This growth is underpinned by a compound annual growth rate (CAGR) that signals robust demand penetration across multiple civil engineering verticals. For decision-makers, this implies that timing is critical. Entering the market or expanding existing portfolios now allows organizations to capture share during the steep ascent of the adoption curve. The revenue figures forecast for the late 2020s and early 2030s indicate a mature market phase where early movers will likely consolidate their technological lead.
However, growth is not uniform. It is mediated by material costs, regulatory frameworks, and geographical readiness. Understanding the interplay between these macro drivers and the specific revenue streams is essential for accurate budgeting and strategic planning.
Key Drivers Shaping the 2026 Landscape
Several converging factors are catalyzing demand for shape memory technologies in infrastructure. First, the imperative for seismic resilience is paramount. Traditional reinforcement methods are often heavy, labor-intensive, and reactive. SMAs offer superelastic properties that dissipate energy during seismic events, potentially reducing structural damage and lifecycle costs. This capability is shifting SMAs from experimental novelties to viable components in high-risk zones.
Shape Memory Alloys Market
Second, the focus on structural retrofitting and rehabilitation is intensifying. With vast networks of bridges and buildings reaching the end of their design lives, the industry requires solutions that can be deployed with minimal disruption to ongoing operations. SMA-based strengthening methods, particularly those involving iron-based alloys, offer advantages in terms of weight and corrosion resistance compared to traditional steel, facilitating easier installation and long-term durability.
Third, sustainability and efficiency are driving material innovation. The construction industry is under pressure to reduce carbon footprints. SMAs can contribute to lighter structures, reduced material usage, and extended service life. Furthermore, recent developments in digital fabrication and smart infrastructure integration are creating new use cases. For instance, the integration of SMA actuators in building technology for ventilation, shading, and fire protection systems represents an adjacent growth vector that complements core structural applications.
Finally, standardization is reducing market friction. The establishment of ASTM standards, including F2516 for shape memory alloys and related test methods, provides a framework for quality evaluation. This regulatory clarity supports procurement confidence and accelerates adoption among conservative engineering firms and government entities.
Competitive Dynamics and Vendor Landscape
The market structure is characterized by a mix of specialized material manufacturers and diversified engineering solution providers. Our research indicates a consolidated competitive environment where a core group of players holds a significant share of the revenue. The concentration ratio among the top firms highlights the technical barriers to entry and the importance of established supply chains and intellectual property.
Leading entities are not merely suppliers of raw materials; they are evolving into solution partners. Companies with vertically integrated operations, capable of managing the process from melting to component fabrication, are positioned to control quality and cost more effectively. For example, manufacturers specializing in nickel-titanium based alloys leverage high-performance properties for actuator and damping systems. Simultaneously, firms focusing on iron-based shape memory alloys are gaining traction for large-scale civil infrastructure elements due to advantages in mass production using conventional metallurgical equipment. This dual-track development suggests that the market will segment based on specific application requirements, with nickel-titanium dominating high-precision actuation and iron-based variants scaling for heavy structural strengthening.
Regional presence and application specialization further differentiate competitors. Some players have established strong footholds in structural strengthening and repair of concrete and masonry structures, including bridges, buildings, and silos. Others are integrating SMAs into building technology systems, offering full value chains from specification to assembly. Recent real-world applications demonstrate the transition from pilot projects to commercial deployment. Demonstrations of heat-activated strengthening methods for aging bridge decks and the use of memory-alloy steel in digitally fabricated concrete structures highlight the practical viability of these technologies.
Furthermore, collaborative research efforts are expanding the horizon. Upcoming international symposia focused on shape memory alloys in infrastructure are bringing together researchers and practitioners to discuss future directions. These knowledge exchanges are critical for aligning academic innovation with industrial application, ensuring that emerging technologies meet the rigorous demands of civil engineering practice.
For investors and procurement leaders, the key takeaway is that vendor selection must align with project-specific technical requirements. The optimal partner depends on whether the priority is high-performance actuation, cost-effective mass production for large elements, or integrated system solutions. The market offers diverse capabilities, but due diligence regarding supply chain stability and technical support is essential.
Strategic Implications for Stakeholders
The findings of this report have direct implications for various stakeholders in the construction and infrastructure ecosystem.
- Infrastructure Owners and Operators: Understanding the lifecycle cost benefits of SMA integration is crucial. While initial material costs may be higher, the potential for reduced maintenance, enhanced seismic performance, and extended service life can yield favorable total cost of ownership outcomes. Strategic planning should consider pilot projects in critical assets where performance gains justify material premiums.
- Engineering Firms: Incorporating SMA technologies into design capabilities can differentiate service offerings. Firms that master the specification, detailing, and construction methods for SMA applications will be well-positioned to lead projects that demand advanced resilience features. Continuous training and knowledge acquisition regarding standards and best practices are recommended.
- Material Suppliers and Manufacturers: The projected growth trajectory supports capacity expansion and R&D investment. However, attention to raw material volatility is necessary. Feedstocks such as nickel and titanium are subject to price fluctuations influenced by mining restrictions and geopolitical factors. Developing robust supply chain strategies and exploring alternative alloy formulations, such as iron-based variants, can mitigate exposure.
- Investors: The market shows promise, but due diligence is required. Focusing on companies with proven application records, vertical integration, and strong IP positions offers a pathway to capturing value. Monitoring the evolution of regional demand and regulatory support can provide leading indicators of market shifts.
The Value of PW Consulting's Deep Dive
While the trends outlined above provide the strategic context, execution requires precision. Market growth rates, competitive positioning, and application-specific revenue streams vary significantly across regions and segments. Generalizations can obscure the specific opportunities and risks relevant to your organization.
PW Consulting's Worldwide Shape Memory Alloys for Civil Engineering Market report offers the depth required to move from strategy to action. The report provides a detailed segmentation analysis, examining the market through lenses such as alloy type, application focus, and geography. It includes granular data on demand drivers, restraints, and opportunities that enable accurate forecasting and scenario planning.
Moreover, the competitive analysis goes beyond company profiles. It evaluates market share dynamics, strategic moves, and the implications of recent developments, such as new strengthening methods and symposia that shape industry consensus. The report also contextualizes regulatory environments, including the impact of standards and material availability, helping stakeholders anticipate compliance costs and supply constraints.
Worldwide Shape Memory Alloys for Civil Engineering Market
Readers interested in leveraging this intelligence for their 2026 decision-making are encouraged to access the full report. The detailed data tables, segmentation splits, and competitive assessments contained within the document provide the granularity necessary to refine market entry strategies, optimize procurement negotiations, and identify high-potential niches. Access to the complete analysis ensures that your strategic initiatives are built on a foundation of verified, up-to-date market intelligence.
Conclusion
The intersection of advanced materials and civil engineering is creating a new paradigm for infrastructure resilience. Shape memory alloys are moving from the laboratory to the construction site, driven by seismic needs, aging infrastructure, and the pursuit of efficiency. The market outlook through 2032 indicates substantial growth, supported by technological maturation and increasing standardization.
As the industry navigates this transition, informed decision-making will be the differentiator between leaders and laggards. PW Consulting remains committed to providing the analytical rigor and strategic insight necessary to thrive in this dynamic environment. The full market study offers the detailed roadmap required to capitalize on the opportunities presented by the evolving shape memory alloys landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Shape Memory Alloys for Civil Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MLCC Dielectric Materials Market Hits $1.86 Billion in 2025, Growing at 7.05% CAGR Through 2032
By pmarketresearch, 2026-09-16
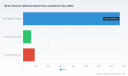
Navigating the Future of Electronic Performance: The Strategic Imperative of the Global MLCC Dielectric Materials Market
For procurement leaders, R&D directors, and corporate strategists operating in the electronics value chain, the materials that enable miniaturization and reliability are no longer a back-office concern. They are a front-line competitive differentiator. As multilayer ceramic capacitors (MLCCs) continue to anchor everything from 5G infrastructure and electric vehicles to medical implants and aerospace systems, the underlying dielectric materials that dictate capacitance density, stability, and thermal resilience have become the nucleus of supply chain resilience and product differentiation. Our newly released Worldwide MLCC Dielectric Materials Market research delivers a comprehensive, data-backed roadmap for organizations that must align material sourcing, product roadmaps, and capacity investments with the trajectory of a rapidly evolving landscape.
The global market for MLCC dielectric materials has demonstrated remarkable resilience and structural growth over the past half-decade. Valued at approximately 1,856.40 million USD in the base year of 2025, the sector has navigated cyclical demand fluctuations, raw material volatility, and shifting end-market appetites to sustain a robust compound annual growth rate of 7.05 percent through the forecast horizon extending to 2032. This trajectory underscores a fundamental reality: the demand for advanced dielectric formulations is not merely cyclical but structurally embedded in the electrification of transportation, the densification of consumer electronics, and the proliferation of high-frequency communication networks. For decision-makers, understanding where this growth concentrates, which material architectures are gaining share, and how legacy supply chains are adapting is the difference between reacting to market shifts and shaping them.
Why This Research Matters for 2026 Strategic Planning
The 2026 planning cycle arrives at a critical inflection point. Supply chain architects are recalibrating tier-two and tier-three supplier dependencies in the wake of geopolitical realignment and regional manufacturing incentives. Simultaneously, product developers are pushing capacitance targets higher while shrinking form factors to the limits of ceramic processing science. The dielectric material layer sits precisely at the intersection of these pressures.
Our forecast model maps a clear acceleration pathway for the sector, with revenue projections climbing from 1,923.77 million USD in 2026 toward 2,980.98 million USD by 2032. More importantly, the analysis isolates the inflection triggers that will separate transient demand spikes from durable structural shifts. By synthesizing historical pricing behavior, capacity commissioning timelines, and application-driven material specification trends, the report equips strategists with a decision framework that extends well beyond headline growth figures. Whether you are evaluating vertical integration opportunities, assessing supplier qualification pipelines, or modeling the cost implications of next-generation dielectric formulations, this research converts macro trends into actionable intelligence.
Market Architecture: Materials, Classes, and the Forces Shaping Demand
The composition of the MLCC dielectric market reflects decades of materials engineering evolution, yet its present structure is being rewritten by application requirements that demand simultaneously higher performance and lower environmental impact. Barium titanate remains the foundational dielectric compound for both Class I and Class II capacitors, enabling high capacitance density within ultra-thin ceramic layers. However, the market segmentation reveals a nuanced hierarchy of material technologies, each serving distinct performance envelopes and end-use priorities.
- High Purity Barium Titanate continues to dominate as the primary dielectric material, driven by its proven balance of permittivity, manufacturability, and compatibility with high-volume multilayer processing. Japanese suppliers in particular have advanced hydrothermal synthesis routes to deliver grades optimized for precision capacitance stability and ultra-fine grain structures.
- Zirconates and Stannates occupy a strategic niche, offering tailored electrical and mechanical properties that complement barium titanate-based systems in specialized high-reliability and high-voltage applications.
- Rare Earth Doping Oxides represent a more specialized formulation pathway, supporting capacitance tuning and temperature stability for applications where marginal gains in dielectric performance translate into meaningful system-level advantages.
Equally important is the division between dielectric classes, which directly informs material selection and supplier strategy:
- Class II formulations, encompassing X7R, X5R, and Y5V characteristics, command the largest share of material demand due to their prevalence in consumer electronics, automotive electronics, and power management circuits where high volumetric efficiency is paramount.
- Class I materials, including C0G and NP0 types, serve applications demanding exceptional temperature stability, low loss, and long-term reliability, making them indispensable for RF front-ends, precision timing circuits, medical devices, and defense-grade systems.
The market is also defined by notable concentration dynamics. With the top three players commanding 62.45 percent of market share and the top five reaching 78.9 percent, the competitive landscape reflects a mature, technology-intensive ecosystem where formulation expertise, process control, and customer qualification cycles create formidable barriers to entry. For buyers and investors alike, this concentration signals both supply assurance risks and the strategic value of locking in qualified supplier relationships before capacity tightens.
Competitive Landscape: Incumbents, Integrators, and Enabling Material Specialists
The companies profiled in this research illustrate the full spectrum of the dielectric value chain, from powder synthesis and formulated material supply to finished capacitor manufacturing and high-reliability application specialization. Understanding who competes where, and how their material capabilities differentiate their product portfolios, is essential for mapping partnership opportunities and evaluating substitution threats.
Among the leading integrated capacitor manufacturers, Murata Manufacturing Co., Ltd. continues to leverage advanced in-house dielectric material formulations, with recent emphasis on high-capacitance X7R architectures and ultra-miniature dielectric layers that support consumer electronics, automotive, and high-reliability applications. Murata’s July 2025 commencement of mass production for 0402-inch high-capacitance MLCCs at 47 µF, enabled by upgraded dielectric layering technology, exemplifies the pace at which formulation and process innovation are compressing performance boundaries.
Samsung Electro-Mechanics Co., Ltd. maintains a prominent position through proprietary dielectric materials optimized for high capacitance, automotive-grade reliability, and miniaturized components deployed across smartphones, electric vehicles, and 5G infrastructure. TDK Corporation remains a defining force in advanced fine-particle dielectric technologies, with recent moves including the expansion of its CN series to deliver low-resistance soft-termination MLCCs in the 3225 case size, offering 22 nF capacitance and C0G characteristics at 1000 V. TDK’s September 2024 automotive lineup expansion further underscored its focus on industry-leading capacitance at 100 V in 2012 and 3216 sizes, alongside new low-resistance soft termination types built on advanced dielectric formulations.
Yageo Corporation, through its broader portfolio including KEMET and AVX, supplies MLCCs anchored in barium titanate-based dielectrics with emphasis on high-voltage, automotive, and high-reliability segments. Taiyo Yuden Co., Ltd. specializes in high-performance MLCCs with customized dielectric materials spanning automotive, industrial, and consumer electronics use cases. Kyocera Corporation, including its AVX subsidiary, continues to manufacture high-reliability MLCCs using advanced ceramic dielectric formulations targeted at automotive, medical, and aerospace sectors, while Walsin Technology Corporation provides MLCCs incorporating dielectric materials tailored for both general-purpose and specialized electronic applications.
Worldwide MLCC Dielectric Materials Market
On the materials supply side, the competitive dynamics shift toward companies whose core competency lies in dielectric powder engineering and formulation technology. Knowles Precision Devices focuses on high-reliability and high-performance MLCCs with specialized dielectric formulations for medical, military, and 5G markets. Prosperity Dielectrics Co., Ltd. supplies ceramic dielectric powders and formulations across PME and BME series for NP0, X7R, and Y5V applications, directly feeding MLCC production pipelines. Vibrantz Technologies provides engineered dielectric powders and formulated materials for multilayer ceramic components, including both Class I C0G-type and Class 2 X7R-type materials. Sakai Chemical Industry Co., Ltd. has established itself as a key supplier of high-purity barium titanate dielectric powders produced via hydrothermal synthesis for premium MLCC applications, while Nippon Chemical Industrial Co., Ltd., Fuji Titanium Industry Co., Ltd., and Toho Titanium Co., Ltd. round out a robust Japanese supply base producing barium titanate and titanium-based materials critical to electronic dielectric applications.
This interplay between integrated capacitor makers and specialized dielectric material suppliers creates a layered competitive field. For strategists, the implication is clear: material sourcing decisions cannot be made in isolation from the product architecture strategies of the companies that consume them, and vice versa.
Multilayer Ceramic Capacitors (MLCCs) Market
Technology, Regulation, and Supply Chain Dynamics Reshaping the Market
The trajectory of the MLCC dielectric materials market is being shaped not only by performance demands but also by environmental compliance and raw material processing strategies. Manufacturers across the value chain continue to advance lead-free and RoHS-compliant dielectric formulations to meet global environmental standards. This regulatory momentum is not merely a compliance exercise; it is reshaping formulation roadmaps, supplier qualification timelines, and long-term cost structures. Organizations that treat regulatory adaptation as a strategic variable rather than a procedural checkbox will secure advantages in time-to-market and supply continuity.
Raw material dynamics further reinforce the need for strategic foresight. Barium titanate remains the workhorse dielectric for both Class I and Class II capacitors, and the availability of high-purity grades produced through controlled synthesis routes directly influences capacitance consistency, mechanical integrity, and yield performance. Suppliers that have invested in advanced powder processing and particle size control are positioning themselves to serve the most demanding applications, while downstream manufacturers increasingly prioritize qualification partnerships that guarantee batch-to-batch reproducibility. As electrification, connectivity, and miniaturization drive demand toward tighter tolerances, the quality of the dielectric material input becomes a direct determinant of end-product performance and warranty risk.
What the Research Delivers: An Operational Blueprint for Decision-Makers
This report is designed to move beyond descriptive market summaries and into the operational detail that strategic teams require. It integrates historical analysis from 2020 through 2025 with a forward-looking forecast spanning 2026 to 2032, enabling readers to benchmark current positioning against projected growth corridors and identify where capacity, formulation, and qualification investments will yield the greatest returns.
Within the analysis, readers will find:
- A structured assessment of material type segmentation, clarifying how barium titanate-based systems, zirconates and stannates, and rare earth doping oxides each contribute to revenue composition and where application pull is accelerating adoption.
- A detailed evaluation of dielectric class dynamics between Class II and Class I materials, including the performance-driven demand patterns that influence formulation priorities and supplier selection.
- A competitive profiling framework covering leading integrated manufacturers and specialized dielectric material suppliers, with attention to geographic footprints, technological positioning, and recent product and capacity developments.
- Contextual analysis of industry dynamics, including raw material sourcing considerations, formulation trends, and regulatory drivers that influence cost structures and supply chain design.
- Forecast scenarios and market sizing that translate top-line growth into interpretable guidance for capacity planning, sourcing strategy, and investment prioritization.
Crucially, the full report provides the granular segmentation detail, regional revenue distributions, and application-level breakdowns that executive summaries cannot accommodate. These deeper layers enable teams to model localized supply-demand balance, evaluate supplier concentration risk within specific material categories, and align product roadmap milestones with realistic material availability timelines.
Strategic Takeaways for 2026 and Beyond
The Worldwide MLCC Dielectric Materials Market research is built for leaders who need to convert complex material science trends into executable strategy. It frames the market not as a static size estimate but as a dynamic system in which formulation capability, regulatory adaptation, regional manufacturing footprints, and application-driven performance requirements continuously reshape competitive advantage.
In practical terms, the insights contained in this study support several priority actions for 2026 planning:
- Evaluate supplier qualification pipelines against material class requirements, distinguishing between high-volume Class II needs and stability-critical Class I demands.
- Assess the strategic implications of market concentration, particularly where top-tier suppliers hold disproportionate influence over qualified material supply and lead times.
- Integrate environmental compliance and lead-free formulation roadmaps into sourcing decisions, recognizing that regulatory momentum will affect cost, availability, and qualification cycles.
- Align internal R&D and procurement roadmaps with the material technologies most likely to support next-generation capacitance density, miniaturization, and high-reliability performance targets.
The full intelligence behind these recommendations, including the segment-level data, regional breakdowns, and detailed company assessments that enable precise planning, is available in the complete report. For organizations ready to move from general market awareness to targeted, evidence-based decision-making, the complete Worldwide MLCC Dielectric Materials Market research provides the depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide MLCC Dielectric Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Wood Briquettes Hit $925.4M in 2025, Projected to Surge to $1,520M by 2032
By pmarketresearch, 2026-09-16
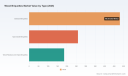
Global Wood Briquettes Market: Strategic Intelligence for 2026 Investment and Operational Planning
Executive Overview of Market Trajectory
The Worldwide Wood Briquettes Market represents a critical intersection of renewable energy policy, industrial decarbonization, and residential heating demand. As organizations navigate the complex energy transition landscape, understanding the quantitative and qualitative dimensions of this sector is paramount for strategic positioning. This market research study provides a comprehensive analysis of market size, growth trajectories, and competitive forces shaping the industry through the forecast period ending in 2032.
Having attained a valuation of approximately 925 million USD in the base year of 2025, the market has demonstrated consistent resilience. Historical data from 2020 through 2025 illustrates a steady accumulation of value, reflecting both organic growth and increased adoption rates across diverse geographical zones. Looking forward, the market is projected to reach 997.6 million USD in 2026, marking a significant step in its expansion curve. This growth is not merely linear but compounds over time, driven by entrenched policy frameworks and shifting consumer preferences toward sustainable biomass solutions. The compound annual growth rate is estimated at 7.35 percent during the forecast period, indicating a robust opportunity for stakeholders who can align their operations with emerging demand patterns.
To fully capitalize on this momentum, decision-makers require more than aggregate figures. They need granular intelligence on segment performance, regional divergences, and the specific regulatory headwinds or tailwinds that will define profitability in the coming years. This report is designed to bridge that gap, offering an evidence-based roadmap for navigating the wood briquettes value chain.
Core Segmentation and Structural Dynamics
Product Type and Material Inputs
The market structure is defined by distinct product categories that cater to varying combustion requirements and feedstock availability. Analysis within this study differentiates between sawdust-based formulations, agro-waste derivatives, and wood residue or chip-based briquettes. Each type possesses unique characteristics regarding energy density, ash content, and production economics. Sawdust briquettes often dominate in terms of volume due to their prevalence in processing streams, while agro-waste variants present opportunities in regions where agricultural biomass is abundant. Wood residue and chips briquettes serve specialized industrial applications where specific burning characteristics are required.
Understanding the cost implications of raw material sourcing is critical. For instance, sawmill residues and wood chips for briquette production have shown price volatility in key markets, with averages in the EU reaching specific levels during late 2023. These input costs directly affect margin structures and pricing strategies. The report delves into how manufacturers mitigate these fluctuations through supply chain optimization and long-term contracting, ensuring that production remains viable even when feedstock prices fluctuate.
Application Segments and Demand Centers
Demand is distributed across several key application verticals, each with distinct growth drivers. Industrial boilers represent a significant portion of consumption, driven by large-scale manufacturing entities seeking cost-effective and compliant heating solutions. Residential heating remains a cornerstone of the market, fueled by consumer desire for carbon-neutral heating options and the aesthetic value of wood-burning stoves. Power generation applications are gaining traction as utilities seek to diversify energy portfolios with biomass feedstocks. Commercial and other applications round out the demand landscape, encompassing hospitality, education, and municipal heating projects.
The interaction between these application segments and regional policies creates a complex web of opportunity. In some jurisdictions, subsidies for biomass boilers significantly enhance residential adoption rates, while in others, industrial regulations mandate specific emission savings that favor high-quality briquettes over raw wood. This study dissects these application-led demand vectors to identify where volume growth is most concentrated and where margin profiles are most favorable.
Regional Market Architecture
Geographically, the market exhibits pronounced differences in maturity, demand volume, and growth speed. Europe currently holds a substantial share of the global market, supported by stringent carbon reduction targets and established biomass infrastructure. Asia Pacific follows as a significant region, characterized by rapid industrialization and increasing awareness of renewable energy alternatives. North America maintains a steady presence, driven by residential heating trends and industrial usage. Latin America and the Middle East and Africa represent emerging territories where market penetration is still developing but holds latent potential.
Regional analysis in this report goes beyond simple revenue allocation. It examines the regulatory environments, logistical constraints, and competitive intensities specific to each zone. For example, the European landscape is heavily influenced by directives such as RED III, which requires solid biomass to meet minimum greenhouse gas emission savings compared to fossil fuels. Such regulations shape not only demand but also the types of products that can be legally sold and subsidized. Similarly, the UK Boiler Upgrade Scheme provides financial incentives for biomass boiler installations, directly stimulating downstream demand in that region. Understanding these regional nuances is essential for any firm planning cross-border expansion or supply chain adjustments.
Competitive Landscape and Strategic Positioning
Key Enterprise Profiles and Operational Focus
The competitive arena is populated by a mix of established manufacturers and specialized producers, each carving out niches based on product quality, geographic reach, and operational scale. Prominent players include Lignetics International, headquartered in Louisville, Colorado, which manufactures premium wood briquettes and compressed logs for residential heating, BBQ, and commercial fireplaces. Their focus on consumer-facing quality highlights one end of the market spectrum.
In Europe, Binderholz GmbH, based in Sankt Johann in Tirol, Austria, produces high-quality wood briquettes from sawmill residues for sustainable heating solutions. Their operations are closely tied to regional milling capacity and EU demand trends. Pfeifer Group, located in Imst, Austria, offers RUF-type wood briquettes as part of its broader range of renewable wood energy products for industrial and residential use, demonstrating the integration of briquette production within larger timber and energy portfolios.
German manufacturers also play a pivotal role. Holzindustrie Torgau GmbH & Co. KG, based in Torgau, specializes in manufacturing pressed wood briquettes certified under DINplus for efficient biomass heating. Südruss Holz GmbH, situated in Unterkirnach, produces natural wood briquettes without additives for export and domestic heating markets, emphasizing purity and export capability. In North America, Bear Mountain Forest Products, located in Eagle River, Wisconsin, supplies dense hardwood briquettes designed for long-burning residential stoves and fireplaces, catering to the premium residential segment.
On the global export front, Jay Khodiyar Industries, headquartered in Rajkot, Gujarat, India, exports 100 percent wood briquettes and biomass variants to global markets for industrial boilers and heating. This company exemplifies the growing role of Asian producers in supplying international markets, leveraging cost advantages and robust manufacturing capabilities.
Strategic Developments and Market Moves
Recent developments among these key entities reveal the strategic priorities shaping the industry. In June 2024, Binderholz GmbH announced an expansion of wood briquette production capacity at its Austrian facilities to meet rising EU demand. This move underscores the confidence major players have in the growth trajectory of the European market and their willingness to invest in capacity when regulatory and demand signals are positive.
Earlier, in November 2023, Holzindustrie Torgau achieved updated DINplus certification for a new briquette product line. Certifications such as DINplus are critical in the wood briquettes market, as they signal compliance with rigorous standards regarding ash content, fines, and overall combustion performance. DIN 51731, for instance, mandates a maximum of 10 percent ash content and 0.5 percent fines for premium wood briquettes. Achieving and maintaining such certifications is a barrier to entry and a competitive differentiator, allowing firms to command premium pricing, such as the levels observed in Central Europe during the 2024 heating season where ENplus A1 wood briquettes retailed at specific price points per tonne.
The market concentration remains relatively fragmented, with top three players holding approximately 18.45 percent of revenue and the top five holding about 26.32 percent. This fragmentation suggests that while leading brands have strong positions, there is ample room for consolidation, niche specialization, or regional dominance strategies.
Regulatory, Standardization, and Economic Drivers
Policy Frameworks and Emission Requirements
Regulatory environments are among the most powerful drivers in the wood briquettes market. In the European Union, the RED III directive requires solid biomass like wood briquettes to meet greenhouse gas emission savings of at least 70 percent versus fossil fuels. This mandate forces both producers and consumers to ensure that biomass products are sourced and processed in ways that demonstrably reduce carbon footprints. It influences everything from feedstock selection to logistics and end-use verification.
Beyond emission targets, subsidy Schemes play a direct role in stimulating demand. The UK Boiler Upgrade Scheme, for instance, provides up to £7,500 grants for biomass boilers compatible with wood briquettes. Such financial mechanisms lower the capital barrier for end-users, accelerating the transition from fossil-fuel heating to biomass systems. The interplay between subsidies, certification standards, and carbon targets creates a multi-layered incentive structure that the report analyzes in detail to help stakeholders predict policy-driven demand shifts.
Quality Standards and Pricing Dynamics
Product quality is not merely a marketing claim; it is a regulatory and commercial necessity. Standards like DIN 51731 set benchmarks that protect consumers and ensure efficient combustion, reducing maintenance issues and emissions. Market data indicates that premium certified briquettes command specific price premiums in key markets. For example, during the 2024 heating season, ENplus A1 wood briquettes achieved retail prices in a defined range per tonne in Central Europe. These pricing dynamics reflect the value that consumers and industrial buyers place on reliability, consistency, and compliance.
Manufacturers must navigate the tension between production costs, which are sensitive to raw material prices and energy inputs, and the price ceilings imposed by market acceptance and competitive pressure. The report provides a framework for analyzing how shifts in input costs, such as the average European price for sawmill residues and wood chips, translate into margin impacts and pricing strategies across different product types and application segments.
Strategic Value of This Market Research Study
Comprehensive Data Coverage and Forecasting Rigor
This study is constructed to provide actionable intelligence for strategic planning. It covers historical data from 2020 through 2025, offering a robust baseline for trend analysis, and extends forecasts through 2032. The projection period allows organizations to stress-test their strategies against multiple growth scenarios and to align capital expenditure cycles with anticipated market expansion.
The report integrates quantitative forecasts with qualitative assessments of the factors driving those numbers. Rather than presenting isolated figures, the analysis contextualizes market size and growth rates within the broader ecosystem of feedstock availability, regulatory requirements, technological advancements in briquetting, and shifting consumer preferences. This holistic approach ensures that the data is interpretable and applicable to real-world decision-making.
Briquette Market
Segmentation Analysis for Targeted Strategy
One of the core strengths of this research is its detailed segmentation framework. By breaking down the market by region, type, and application, the study enables stakeholders to identify their most relevant growth pockets. A manufacturer focused on premium residential products can assess the health and growth potential of the residential heating segment across key regions. An industrial supplier can evaluate the demand outlook for industrial boilers and power generation applications. This granularity supports targeted marketing, production planning, and distribution strategies.
It is important to note that while this article highlights the breadth and depth of the analysis available, the full report contains the precise quantitative allocations and detailed forecasts for each segment and region. These specifics are essential for building financial models, setting sales targets, and evaluating investment returns with precision. Readers seeking the complete segment-level data, including exact historical and projected revenue breakdowns, are encouraged to access the full report through the source webpage.
Competitive Intelligence and Strategic Benchmarking
Understanding the competitive landscape is vital for positioning. This study profiles key companies, analyzing their strategic moves, product focus, geographic presence, and recent developments. By examining events such as capacity expansions, certification achievements, and export initiatives, the report helps firms benchmark their own strategies against industry leaders. It also sheds light on the nature of competition in a fragmented market, highlighting where consolidation is likely and where niche players can thrive.
The inclusion of recent developments, such as the capacity expansion by Binderholz and the certification update by Holzindustrie Torgau, provides timely insights into the operational priorities of major actors. These case examples, combined with broader competitive metrics, offer a practical view of how firms are responding to market opportunities and regulatory demands. For organizations evaluating partnership opportunities, acquisition targets, or competitive threats, this intelligence is invaluable.
Operational and Investment Decision Support
Ultimately, the purpose of this market research is to reduce uncertainty and improve the quality of strategic decisions. For investors, the report provides the data needed to assess market attractiveness, growth sustainability, and risk factors. For manufacturers and suppliers, it offers insights into demand trends, pricing environments, and competitive pressures that inform production planning, capacity investment, and product development. For policymakers and industry associations, it contributes to a clearer understanding of market dynamics and the impact of regulatory measures.
Worldwide Wood Briquettes Market
The study is designed to be a living reference that supports ongoing strategic dialogue. As the market evolves, with changes in feedstock markets, regulatory updates, and technological innovations, the framework provided by this research helps stakeholders adapt and respond proactively. The forecast period through 2032 offers a long enough horizon to plan for structural shifts while remaining specific enough to guide near-term actions in 2026 and beyond.
Detailed data tables, segment-specific growth rates, regional revenue projections, and comprehensive company profiles are available in the full downloadable report. Accessing these resources will enable your organization to conduct a thorough internal analysis and develop strategies that are precisely calibrated to the opportunities and challenges of the Worldwide Wood Briquettes Market.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Briquettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Global DC Power Supplies Market to Hit $5.9B by 2032, 6.42% CAGR Through 2032
By pmarketresearch, 2026-09-16
Global DC Power Supply and Electronic Load Markets: Strategic Intelligence for 2026 Corporate Decision-Making
The worldwide DC power supply and electronic power load industry stands at a critical inflection point. Between 2020 and 2032, global market revenue is projected to expand from approximately USD 2,780 million to nearly USD 5,945 million, representing a compound annual growth rate of 6.42 percent across the forecast horizon. This structural upward trajectory is not merely a function of incremental demand recovery; it reflects a fundamental realignment in how enterprises design, validate, and manufacture power electronics across automotive, semiconductor, industrial automation, aerospace, and renewable energy verticals. The Worldwide DC Power Supplies and Electronic Power Loads Market research publication arrives precisely when executive leadership teams require defensible, scenario-ready intelligence to navigate supply chain reconfiguration, component cost volatility, and accelerating technology substitution cycles.
For corporate strategists, procurement directors, product planners, and venture investors, this report functions as a decision architecture rather than a static sizing exercise. It maps historical revenue behavior from 2020 through 2025, establishes a rigorous baseline for 2025, and projects forward through 2032 with transparent methodological scaffolding. By deliberately separating macro trajectory from segment-level granularity, the study equips leadership teams to calibrate capital allocation, capacity expansion, vendor partnerships, and technology roadmaps without prematurely exposing sensitive forecasting assumptions.
Macro Trajectory and the Mechanics of Growth Through 2032
The revenue arc captured in this study demonstrates a pattern of recovery, consolidation, and renewed acceleration. After modest contraction in 2023, the market rebounded decisively, with 2024 and 2025 reflecting strong demand pull across multiple end-user ecosystems. The forecast window extending to 2032 positions cumulative growth above historical baselines, driven by electrification mandates, data infrastructure expansion, advanced manufacturing test requirements, and sustained defense modernization programs. The reported CAGR of 6.42 percent consolidates these dynamics into a disciplined growth framework that balances demand-side momentum with practical constraints on component availability, pricing pressure, and regional manufacturing shifts.
Importantly, the study does not treat growth as a uniform linear progression. Revenue expansion is shaped by divergent adoption curves across programmable versus non-programmable architectures, the expanding role of electronic power loads in automated test and validation environments, and the intensifying interplay between semiconductor content, thermal management requirements, and system-level power density targets. Corporate readers will find value in understanding how these structural forces interact to influence market velocity without relying on superficial headline figures that obscure execution risk.
Report Architecture and Actionable Intelligence for Planning Teams
The publication is structured to support multi-function decision-making. Executive summaries convert complex modeling outputs into strategic narratives suitable for board-level review and capital committee discussions. Detailed market sizing sections establish historical baselines, validate demand drivers, and explain the forward-looking assumptions that underpin the forecast period. Rather than presenting aggregate numbers in isolation, the analysis contextualizes revenue evolution within product architecture shifts, application-specific testing requirements, and end-user procurement behavior across industrial, commercial, and government domains.
Beyond sizing, the report delivers operational intelligence that directly informs product strategy and supply chain planning. Coverage includes technology transition pathways, regional manufacturing dynamics, competitive positioning logic, and the practical implications of component cost escalation on product economics. Procurement and engineering leaders will gain clarity on where sourcing vulnerabilities are likely to concentrate, how test equipment requirements are reshaping load and supply specifications, and which application segments are generating the strongest pull for high-reliability, high-density power solutions. Product managers can use these insights to prioritize feature investments, platform consolidation, and portfolio alignment with emerging validation standards.
The study also addresses ecosystem interdependencies that typical market summaries overlook. Coverage of supplier behavior, testing workflow evolution, and application-specific power quality requirements helps organizations translate market momentum into concrete planning assumptions. For enterprises navigating multi-year development cycles or long-term vendor agreements, this level of contextual depth reduces the probability of strategic misalignment and supports more resilient operating models.
Worldwide DC Power Supplies and Electronic Power Loads Market
Competitive Landscape: Positioning, Specialization, and Strategic Implications
The competitive environment is characterized by a mix of broad-platform manufacturers, technology specialists, and application-focused innovators. Market concentration metrics indicate that leading incumbents hold meaningful share, but the landscape remains sufficiently fragmented and dynamic to reward differentiated positioning. The report evaluates core participants across multiple strategic dimensions, including product breadth, precision and programmability capabilities, thermal and power density engineering, and vertical-specific validation expertise.
DC Electronic Load Market
Firms such as TDK-Lambda, Keysight Technologies, Chroma ATE Inc., XP Power, Mean Well Enterprises, EA Elektro-Automatik, Advanced Energy Industries, Magna-Power Electronics, B&K Precision Corporation, Vicor Corporation, Delta Electronics, Murata Manufacturing, and Acopian Power Supplies each occupy distinct strategic coordinates within the market. Several organizations emphasize high-efficiency, compact architectures leveraging advanced semiconductor materials and topologies. Others differentiate through precision programmable platforms designed for R&D validation, production test, battery simulation, and power supply characterization. A further cohort competes on reliability, rapid fulfillment, broad voltage and current ranges, and cost-effective industrial deployment.
Recent vendor activity underscores how aggressively companies are reshaping their portfolios to capture emerging demand. In early 2026, Magna-Power Electronics introduced new high-voltage 1U DC power supply models reaching up to 3000 Vdc, signaling continued investment in high-voltage test and industrial applications. North Atlantic Industries released a 600W DC/DC supply for SOSA-aligned VPX systems, directly targeting aerospace and defense modernization requirements. P-DUKE launched a 150W high-efficiency industrial AC/DC unit for demanding environments, while Jetronl Instruments introduced next-generation programmable solutions aimed at high-end electronics manufacturing across automotive, new energy, and communications testing. ActionPower expanded its automated test equipment portfolio with PCL-series DC electronic loads, reinforcing the growing integration of load instrumentation into validation workflows.
These developments illustrate a broader pattern: competitors are not merely expanding product counts, they are repositioning around application specificity, test integration, power density, and reliability assurance. For enterprise buyers and investors, the strategic question is no longer which supplier is largest, but which portfolio logic best matches an organization's validation needs, procurement constraints, and long-term technology roadmap.
Supply Chain Pressures, Material Constraints, and Component Cost Dynamics
Market growth does not unfold in a vacuum. External shocks and structural material constraints are reshaping cost assumptions, lead-time expectations, and sourcing strategies across the power electronics value chain. In 2025, export controls on rare earth elements and related magnet technologies expanded, with downstream implications for components used in DC power supplies and electronic loads. Around the same period, U.S. actions under Section 232 highlighted national security concerns tied to processed critical minerals and derivative products, reinforcing the strategic importance of supply diversification and regional sourcing resilience.
Component-level pricing pressures have compounded these sourcing complexities. In the first quarter of 2026, tantalum capacitors and MLCCs experienced price increases in the range of 15 to 30 percent, influenced in part by demand associated with AI server power regulation. Power MOSFET and IGBT producers also raised prices by 10 to 20 percent in early 2026 as copper and silicon input costs escalated, while high-voltage MOSFET lead times lengthened meaningfully. These dynamics create a dual challenge for product planners: managing unit cost inflation while maintaining performance and reliability targets in increasingly density-sensitive applications.
At the same time, technology substitution trends are accelerating. Industry analysis points to sustained momentum behind higher efficiency and higher power density designs in electric vehicles and data center infrastructure, with advanced wide-bandgap devices expected to play a growing role in traction inverters and DC-DC converters. This technological trajectory reinforces demand for power supplies and electronic loads that can validate, simulate, and stress next-generation architectures under realistic operating conditions. For organizations operating in this environment, resilience depends on anticipating cost transmission mechanisms, qualifying alternative component sources, and aligning product specifications with the longer-term direction of semiconductor and magnet supply chains.
Strategic Value for 2026 Decision-Making
The 2026 market environment rewards organizations that combine forward-looking demand intelligence with disciplined supply chain and technology planning. This study is designed to support exactly that posture. For strategic planning teams, it provides a structured basis for evaluating revenue opportunity, prioritizing market entry or expansion, and aligning product roadmaps with verifiable demand signals. For procurement and supply chain leaders, it highlights where material constraints, pricing momentum, and regulatory actions are most likely to affect sourcing strategy and total cost of ownership. For technology and engineering leadership, it clarifies how test, validation, and simulation requirements are evolving as power architectures grow more complex and performance expectations intensify.
The analysis also helps organizations separate cyclical noise from durable structural shifts. Not every price increase or product launch signals long-term opportunity; some reflect temporary supply tightness, regional policy reactions, or short-term customer urgency. By grounding interpretation in macro trajectory, segmentation logic, and competitive behavior patterns, the report enables decision-makers to allocate attention and capital more efficiently, avoiding overreaction to isolated events while remaining responsive to genuine demand transformation.
Why Executive Teams Should Access the Full Study
While this preview outlines the strategic contours of the market and the reasoning behind the forecast, the full Worldwide DC Power Supplies and Electronic Power Loads Market research delivers the deeper intelligence required for precise execution. Complete segmentation coverage, detailed regional and application-level breakdowns, competitive positioning maps, and scenario-ready forecast structures are essential for organizations making investment commitments, vendor selections, capacity decisions, or product launch plans. Aggregate market direction establishes confidence; segment-level evidence enables precision.
For leadership teams preparing for 2026 and beyond, the study offers more than market size and growth rates. It provides a coherent framework for interpreting material constraints, competitive responses, and application-driven demand evolution in a market where performance, reliability, and supply resilience increasingly determine competitive outcomes. Readers seeking the full analytical backbone behind these conclusions are encouraged to access the complete report through the source page, where detailed segmentation, company profiles, and forward forecasts are available for immediate strategic application.
For detailed analysis of this topic, please visit the official page: Worldwide DC Power Supplies and Electronic Power Loads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Zero Gravity Bed Market Size Hits $1.8B in 2025, projected 11.85% CAGR to $3.9B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Frontier: Inside the Worldwide Smart Zero Gravity Bed Market
The convergence of sleep technology, wellness economics, and clinical care delivery is reshaping how households, healthcare providers, and hospitality operators approach rest and recovery. At the center of this transformation lies the smart zero gravity bed category—a segment where ergonomic positioning, connected firmware, and therapeutic functionality intersect to deliver measurable outcomes in circulation, pressure distribution, and sleep quality. Understanding this landscape requires more than product familiarization; it demands a structured view of adoption velocity, regional intensity, competitive positioning, and the regulatory and reimbursement frameworks that shape purchasing behavior.
PW Consulting's latest Worldwide Smart Zero Gravity Bed Market study has been engineered to serve precisely that need. Designed for executives, product leaders, distribution strategists, and investment teams navigating the 2026–2032 planning horizon, the report translates historical momentum and forward-looking indicators into decision-ready intelligence. Rather than presenting a static snapshot, the analysis maps how value is being created, contested, and captured across a rapidly maturing ecosystem of manufacturers, retailers, care facilities, and end users.
Why 2026 Is a Decisive Baseline for Strategic Planning
Market dynamics entering 2026 reflect a phase of consolidation and acceleration. After a period of adoption driven by pilot programs, premium consumer experimentation, and targeted healthcare procurement, the category is transitioning into a more structured growth trajectory. Reported market revenue expanded from 1,452.4 million USD in 2023 to 1,623.78 million USD in 2024, and reached 1,815.39 million USD in 2025. The trajectory continues upward, with 2026 positioned at 2,030.51 million USD and a projected climb toward 3,975.76 million USD by 2032.
Worldwide Infrared Massage Therapy Bed Market
This expansion is supported by a forecast CAGR of 11.85 percent across the 2026–2032 period, a rate that signals durable demand rather than short-cycle enthusiasm. For leadership teams, that trajectory has direct consequences. It informs capacity planning, guides channel investment, shapes partnership prioritization, and clarifies where incremental innovation can yield disproportionate returns. The report uses this macroeconomic arc as the structural backbone for deeper examinations of segment behavior, competitive intensity, and regional demand patterns, ensuring that every tactical recommendation is anchored in measurable momentum.
What the Research Delivers: Operational Depth Over Surface-Level Summaries
A market study earns its place in the executive workflow when it answers not only what is happening, but how to act on it. This publication is organized to support cross-functional decision-making, combining quantitative foundations with qualitative context that explains the forces behind the numbers. The analysis is built around several practical dimensions:
- Macro market sizing and growth mapping across the 2020–2025 historical window and the 2026–2032 forecast period, with a consistent USD million framework that supports scenario modeling and investment prioritization.
- Category and application perspectives that distinguish how demand differs across product configurations and end-use environments, helping teams align product portfolios, messaging, and channel strategy with the most relevant buying drivers.
- Regional demand intensity that reveals where adoption is most concentrated and where latent opportunity remains, enabling smarter prioritization of sales coverage, logistics footprint, and localized product adaptation.
- Competitive profiling of leading manufacturers and technology suppliers, examining positioning, product architecture, commercial reach, and recent strategic moves that signal where the market is heading.
- Regulatory and reimbursement context that clarifies how coverage policy, medical necessity criteria, and procurement rules influence accessibility, pricing tolerance, and channel behavior in healthcare-adjacent demand.
Importantly, the report does not stop at description. It is structured to help teams pressure-test assumptions: which product sizes command the strongest uptake, which applications are expanding fastest, where regional saturation is emerging, and how major players are differentiating through firmware, positioning presets, and integration features. That combination of breadth and specificity is what allows the study to support both strategic visioning and near-term execution.
Competitive Landscape: Differentiation as the New Battleground
The smart zero gravity bed market is shaped by a diverse set of participants, each bringing a distinct route to market and a different emphasis in product design. The leader group reflects a blend of specialized home-care manufacturers, adjustable-base technology suppliers, consumer sleep brands, and regional medical equipment producers. Their collective activity defines the pace of innovation and the standards buyers increasingly expect.
SonderCare, based in London, Ontario, Canada, has built its positioning around premium home hospital beds with therapeutic positioning capabilities, including zero gravity, Trendelenburg, comfort chair, and boost positions. Its focus on long-term care and recovery environments highlights the importance of clinical-grade functionality within residential and transitional care settings. Ergomotion, headquartered in Santa Barbara, California, operates as a global supplier of adjustable bases for smart beds, manufacturing high-volume bases with zero-gravity presets and broad mattress integration. Its continued scale and retail partnerships make it a central force in normalizing zero-gravity presets across mainstream channels. Leggett & Platt, through its adjustable beds division in the United States, stands as a major manufacturer of adjustable bed bases featuring zero-gravity presets, massage functions, wall-hugger design, and programmable positions for both consumer and medical applications, reinforcing the multi-use identity of the category.
Tempur-Pedic contributes a premium smart-sleep angle with TEMPUR-Ergo Smart Bases that combine zero-gravity positioning with automatic snore response, lumbar support, massage, and Sleeptracker-AI integration. This approach underscores how connected features and automated response systems are becoming part of the value narrative in higher-tier offerings. On the medical-equipment side, Hebei Chibang Medical Equipment Co., Ltd., based in Hengshui, Hebei Province, China, manufactures electric hospital beds for elderly and post-operative care with zero-gravity mode, adjustable back, leg, and height settings, and smart functions designed for clinical and home-care use. Zero-G Beds, operating as ZERO-G BEDS LLP and D4 Surgicals in Mumbai, Maharashtra, India, adds a regional manufacturing perspective with electric adjustable homecare and hospital beds that integrate zero-gravity positioning, remote control, and medical-grade features for elderly and home-care applications.
Recent developments reinforce the strategic weight of this cohort. In October 2025, Ergomotion marked its 20th anniversary with the opening of a new design showroom, underscoring continued investment in adjustable base technology and zero-gravity feature leadership. Moves like these matter because they signal where established suppliers are placing bets on future category expectations: refined ergonomics, smarter controls, and broader ecosystem compatibility.
Market structure also deserves attention. The category is not overwhelmingly consolidated, yet a meaningful share of revenue flows through a relatively concentrated set of influential participants. This balance creates both opportunity and risk. New entrants and regional specialists can still carve out positions through cost competitiveness, localized service, or application-specific design, while larger players leverage scale, integration, and brand trust to defend share. The report examines these dynamics in detail, giving teams a clearer view of who controls which value points and where white space may still exist.
Worldwide Smart Zero Gravity Bed Market
Market Dynamics: Policy, Reimbursement, and Use-Case Realities
Growth in this category does not happen in a vacuum. Purchasing decisions are influenced by clinical requirements, coverage pathways, procurement rules, and the practical demands of end users. For healthcare-adjacent demand, reimbursement and regulation can be as important as product performance. Medicare Part B covers hospital beds as durable medical equipment when prescribed for home use and deemed medically necessary, including adjustable models that meet positioning criteria. Coverage follows HCPCS codes such as E0265 and E0266 for total electric beds, which directly affects what buyers can access and how suppliers structure their offering language and documentation.
At the same time, hospital beds must meet medical necessity criteria for coverage, including the inability to achieve required positioning through an ordinary bed. Requirements such as head and foot elevation, height adjustment, and a face-to-face practitioner examination prior to ordering shape demand pipelines and procurement timelines. These safeguards are not obstacles to ignore; they are operational prerequisites that influence product design, sales enablement, and the way manufacturers and distributors support clinicians and patients through the approval process.
Beyond policy, the use-case logic continues to broaden. Adjustable hospital and homecare beds with zero-gravity positioning are increasingly targeted toward elderly users, post-operative patients, and long-term care needs, with the explicit aim of reducing pressure points and improving circulation. That clinical rationale strengthens the case for adoption in residential care, rehabilitation, and aging-in-place contexts, while also informing product features such as ease of remote control, adjustable height, and positioning precision. The report integrates these dynamics into the broader market narrative so that teams can evaluate demand with a realistic understanding of what enables purchase, what slows it, and where service and documentation can become competitive advantages.
Reading the Trajectory: What This Means for 2026 Decision-Makers
For executives planning around the smart zero gravity bed market, the strategic question is no longer whether the category is gaining traction, but how to position for sustained, structurally supported growth. The numbers point to a market that has moved past early experimentation and is now scaling along a defined path. That shift has several practical implications.
First, product strategy should be assessed against real demand distribution rather than assumption. The mix of sizes, applications, and feature sets matters because different buyer groups prioritize different outcomes, from consumer comfort and sleep quality to clinical positioning and caregiver support. Second, regional strategy should be informed by where intensity is highest and where incremental investment can unlock faster returns. Third, competitive positioning should account for the growing importance of integration, automation, and serviceability, since these attributes increasingly differentiate otherwise similar bases and bed systems.
Finally, companies operating in or adjacent to healthcare demand should treat reimbursement and medical necessity requirements as core components of the go-to-market design, not as back-office details. Documentation, coding alignment, and clinician-friendly product language can determine whether a solution reaches the right buyers efficiently. The full study provides the structured detail needed to turn these general principles into region-specific, segment-specific, and competitor-specific action plans.
Begin With the Complete Intelligence Package
This article offers a strategic preview of the market environment and the analytical framework behind PW Consulting's Worldwide Smart Zero Gravity Bed Market study. It is designed to show the depth, structure, and decision orientation of the research while preserving the detailed segmentation data, regional value breakdowns, application-specific revenue figures, and granular competitive metrics for the full report. Those core elements are where the most precise planning insights reside.
For teams preparing for 2026 and beyond, the complete study provides the supporting detail required to align product roadmaps, channel investments, partnership strategies, and market-entry judgments with a rigorously documented view of the category. To access the full market size progression, segmentation analysis, competitive profiles, and policy context in their complete form, visit the official PW Consulting report page and download the full Worldwide Smart Zero Gravity Bed Market research.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Zero Gravity Bed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Whetstones Market to Expand at 4.25% CAGR, Reaching $198.73M by 2032
By pmarketresearch, 2026-09-16
The Whetstones Market in 2026: Strategic Intelligence for Precision and Edge Maintenance Industries
The global whetstones market is entering a phase of measured yet structurally significant expansion. As manufacturing floors, professional kitchens, and home hobbyists increasingly prioritize tool longevity and surface precision, sharpening stones have evolved from peripheral consumables into strategic SKUs that signal quality, consistency, and operational discipline. Our latest market research on the whetstones industry offers decision-makers a comprehensive, data-grounded map of where this category stands today and where it is headed through the end of the decade. Published with a 2025 base year and a forecast horizon extending to 2032, the study translates historical performance, material innovation, and competitive signaling into actionable intelligence for product strategy, sourcing, and market entry planning.
Why This Research Matters for 2026 Decision-Making
Strategic planning in 2026 requires more than top-line projections. Companies need to understand how demand is shifting across use cases, how material science is reshaping product performance expectations, and which competitive dynamics will determine pricing power and channel control in the years ahead. The whetstones market illustrates these pressures vividly. Historical data from 2020 through 2025 reveals a market that weathered volatility yet consistently rebounded toward growth, culminating in a global revenue base measured in the high hundred millions of U.S. dollars by 2025. Looking forward, our forecast models project a steady compound annual growth trajectory of 4.25 percent across the 2026 to 2032 window, with total market value climbing toward the vicinity of 200 million dollars by the close of the forecast period.
These figures are not merely descriptive. They serve as a strategic compass. A mid-single-digit CAGR in a mature, low-tech-adjacent category signals that growth will increasingly come from differentiation rather than broad category expansion. Manufacturers and distributors that rely on undifferentiated assortments will find themselves squeezed by margin pressure and channel consolidation. Conversely, organizations that align their portfolios with emerging performance standards, regional demand rhythms, and application-specific preferences will be positioned to capture share without relying on aggressive discounting. Our report is designed to help leadership teams make that distinction clear before capital is committed.
Equally important is what the research deliberately preserves for deeper analysis. While this overview communicates the trajectory and structural forces shaping the market, the full study reserves granular segmentation detail, regional volume and revenue distributions, and application-level breakdowns for readers who need to model entry strategies, allocation decisions, and competitive response scenarios. The intent is to provide enough rigor to establish credibility while ensuring that the most decision-critical intelligence remains within the complete report, accessible through our primary research portal.
Market Trajectory and Structural Signals
The historical record from 2020 to 2025 underscores a category that has matured without stagnating. Revenue moved from the 120 million-dollar range in 2020 into a tighter band through 2022 and 2023 before resuming a clearer upward path in 2024 and 2025. This pattern is consistent with a market absorbing supply-chain normalization, shifting procurement rhythms, and gradual demand recovery in both professional and consumer segments. The rebound in the most recent base-year figures reinforces the view that whetstones are no longer treated as discretionary gadgets but as maintenance essentials across multiple end-use environments.
Forward-looking, the forecast period from 2026 through 2032 projects incremental but durable expansion. The modeled trajectory points toward a total market value approaching roughly 199 million dollars by 2032, with year-over-year movement shaped by product innovation, application-driven demand, and regional purchasing patterns. Importantly, this expansion is not uniform across the board. Growth will be concentrated where performance benefits are most visible, where replacement cycles align with sharpening frequency, and where channel execution translates product quality into repeat purchases. Decision-makers should therefore interpret the headline CAGR as a directional anchor, not a guarantee of equal opportunity across all product types or customer groups.
A defining structural feature of this market is its moderate fragmentation. The top three competitors collectively hold approximately 21.4 percent of revenue, while the top five command around 29.8 percent. This concentration profile suggests a landscape where incumbents enjoy meaningful brand and supply advantages, yet there remains sufficient room for specialized players to win in niche applications or geographic pockets. For strategists, the implication is clear: competitive advantage in whetstones will increasingly depend on authenticity of material claims, consistency of sharpening performance, and the ability to serve distinct use cases rather than on scale alone.
What the Whetstones Market Report Covers
Our study is built around practical utility. It is intended to support product planners, category managers, sourcing leaders, and investor analysts who need a coherent narrative from raw material economics through end-user demand behavior. The report integrates the following functional layers:
- Historical performance data spanning 2020 to 2025, providing context for demand rhythm, recovery patterns, and base-year valuation.
- A forward forecast from 2026 to 2032 that models revenue progression, highlights inflection points, and clarifies the pace of category expansion.
- A structured segmentation framework that examines the market by region, material type, and application, with interpretive guidance on where demand intensity and product mix are likely to diverge.
- A competitive landscape assessment that maps key manufacturers, their positioning, and the strategic implications of concentration and differentiation.
- An industry dynamics section that addresses raw material availability, regulatory considerations, and emerging product-testing signals influencing buyer behavior.
- Recent market developments and evaluation activity that reflect how consumer media, professional reviewers, and end users are shaping perceived product leadership.
Readers should note that while the overview presented here describes the architecture of the study, the full report contains the detailed split data and interpretive matrices needed to build region-specific entry plans, allocate SKUs across channels, and benchmark product strategies against peers. The complete segmentation values, regional revenue contributions, and application-level breakdowns are reserved for the report itself to ensure that strategic decisions are made with the full evidentiary context.
Competitive Landscape: Established Players and Specialized Entrants
The whetstones competitive field is defined by a blend of broad-abrasive manufacturers, heritage natural-stone producers, and precision-oriented specialists. This mix shapes both pricing logic and brand perception. On one side are companies with extensive abrasives portfolios that treat whetstones as part of a broader industrial and consumer sharpening ecosystem. On the other are organizations whose identity is anchored in geological sourcing, craftsmanship, or performance engineering, often commanding loyalty through perceived authenticity and consistency.
Major manufacturers with synthetic and natural sharpening portfolios play a pivotal role in setting performance expectations across industrial, professional, and consumer channels. Their scale, distribution reach, and ability to supply multiple material formats allow them to compete on availability, technical support, and product range. Alongside them, natural-stone specialists rooted in specific geological deposits maintain a differentiated value proposition based on material origin, grade consistency, and domestic manufacturing credibility. In certain segments, the control of quarry access and reserve longevity functions as a strategic moat, reinforcing both supply security and narrative authority around traditional performance.
The Japanese manufacturing cohort deserves particular attention. Firms specializing in high-performance ceramic stones, water whetstones, and precision abrasives have influenced global sharpening standards by emphasizing fast cutting behavior, user-friendly maintenance characteristics, and repeatable grit performance. Their product architecture has raised the bar for what buyers expect from a sharpening stone, particularly in professional culinary and precision tool contexts. As a result, competitive positioning increasingly hinges on how well a product communicates edge refinement quality, ease of use, and reliability under repeated sharpening cycles.
Further down the field, regional suppliers and distributors of specialized stones contribute to the market's mosaic by serving jewelry making, tool making, and other precision applications. Their role is often less about headline volume and more about enabling high-value craftsmanship workflows where consistency and surface finish matter disproportionately. For strategists evaluating partnerships, distribution agreements, or private-label opportunities, this layered competitive structure means that the right fit depends on application requirements, claim substantiation, and channel expectations rather than on a single dominant formula for success.
Industry Dynamics Shaping Demand and Supply
Several structural forces are influencing how the whetstones market will evolve over the forecast window. Raw material provenance remains central. For natural stones, the availability of specific deposits and the long-term control of reserves affect both supply continuity and brand storytelling. Where producers maintain secure access to high-quality geological sources, they can support consistent product grades and reinforce heritage positioning. In synthetic categories, the use of abrasives such as aluminum oxide or silicon carbide, bonded for stable grit performance across ceramic and resin-bonded formats, governs consistency and repeatability. Performance reliability in synthetic lines is becoming a key purchase criterion as users compare labor, maintenance, and sharpening outcomes across material types.
Regulatory and claim-substantiation dynamics also matter. In markets where domestic manufacturing claims carry legal and consumer-trust weight, producers must align sourcing, processing, and labeling with applicable standards. Compliance with recognized domestic content requirements can influence procurement decisions in government, institutional, and quality-conscious commercial settings, while also shaping brand perception among consumers who value origin transparency. Companies that proactively manage these claims while maintaining visible quality assurance processes can turn compliance into a differentiator rather than a constraint.
Demand-side signals from recent evaluation activity further illuminate where attention is flowing. Updated 2026 product testing and recommendation coverage has highlighted specific collaboration sets and starter systems as top performers based on edge performance metrics and practical usability. These independent assessments do more than endorse individual products; they reinforce consumer expectations around sharpening quality, ease of use, and system completeness. For manufacturers and retailers, such coverage functions as a market signal about which attributes are gaining salience and which product configurations are resonating with buyers in the current cycle.
Together, these dynamics suggest that the whetstones market will reward organizations that treat sharpening performance as a measurable value driver, that protect their material supply narratives with verifiable sourcing, and that stay responsive to how review ecosystems and professional testing influence buying criteria.
Winches Market
Strategic Implications for Product, Channel, and Sourcing Decisions
For companies operating in or entering the whetstones market, the strategic agenda in 2026 should center on three questions. First, how will the portfolio balance heritage and performance claims without diluting either? Natural-stone narratives and synthetic-consistency arguments can coexist in a single company's offering, but they require distinct positioning, quality documentation, and channel messaging. Blurring the two risks weakening trust with buyers who are increasingly attentive to material identity and claim accuracy.
Second, how should assortments be built for application reality rather than category averages? The whetstones market includes domestic and hobbyist use, professional culinary sharpening, and industrial or woodworking maintenance. Each environment places different demands on grit progression, surface behavior, durability, and ease of maintenance. A portfolio strategy that recognizes these distinctions will create more reliable repeat purchase behavior than one that relies on generic one-size assortments.
Third, where should growth be pursued given moderate concentration and uneven regional demand? The market's concentration profile leaves space for targeted expansion, but the most efficient path will vary by company capabilities. Some players will find value in deepening presence where their material identity and manufacturing footprint provide the strongest credibility. Others will benefit from aligning product offerings with the expectations set by recent testing and professional recommendations, using performance evidence to justify premium positioning or to accelerate adoption in underpenetrated user groups.
What the Full Report Delivers
This overview is intended to give executives a clear sense of the market's direction and the analytical depth available in the complete study. The full report extends this foundation into detailed segmentation figures, interpretive regional and application analyses, and a structured competitive assessment that links company profiles to strategic implications. It also integrates raw material context, regulatory considerations, and recent evaluation activity into a unified narrative that supports product roadmapping, channel planning, and sourcing strategy.
Whetstones Market
For teams that need to commit budget, define SKU architecture, assess partnership opportunities, or evaluate competitive response, the complete report provides the specificity required to move from directional confidence to executed strategy. The headline trajectory, structural signals, and competitive logic described here are only the starting point. The detailed intelligence behind them is available through our primary research page, where the full dataset and analytical commentary can be accessed in context.
Closing Perspective
The whetstones market in 2026 is best understood as a category where consistency, provenance, and performance perception now matter as much as price. Historical resilience, a mid-single-digit growth path, and a moderately concentrated competitive field create a landscape that rewards precise positioning and disciplined execution. Organizations that understand how material types, application needs, and claim standards interact will be better placed to build portfolios that hold their value as the market matures. Our research is designed to make that understanding operational, giving decision-makers the clarity required to act with confidence throughout the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Whetstones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Epoxy Electrocoating Market Hits $1,850M in 2025, Projected to Reach $2,517.6M by 2032 at 4.5% CAGR
By pmarketresearch, 2026-09-16
Navigating the Epoxy Electrocoating Market: Strategic Intelligence for 2026 and Beyond
The global manufacturing landscape is undergoing a structural shift where corrosion protection is no longer viewed as a mere finishing step but as a critical determinant of asset longevity, regulatory compliance, and total cost of ownership. Within this evolving environment, epoxy electrocoating has cemented its position as a cornerstone technology for industrial and automotive applications. As we move through 2026, enterprise leaders across coatings, original equipment manufacturing, and supply chain management face a complex matrix of feedstock volatility, regional capacity realignments, and intensifying competitive pressures. This analysis serves as a strategic preview of our newly released Epoxy Electrocoating Market study, designed to equip decision-makers with the contextual depth and forward-looking frameworks necessary to navigate the forecast period through 2032.
Macro Trajectory and Growth Architecture
The market has demonstrated consistent expansion over the past half-decade, building on a baseline that exceeded 1.5 billion USD in 2020 and progressed through a series of steady annual increments to reach approximately 1.85 billion USD by 2025. This historical arc reflects sustained demand from metal substrate protection, automotive OEM electrophoretic processes, and heavy-duty industrial equipment manufacturing. Looking ahead, the forecast window projects the market to approach 2.5 billion USD by 2032, anchored by a compound annual growth rate of 4.5 percent. While these headline figures establish a clear growth trajectory, the underlying value creation is unevenly distributed across formulations, application verticals, and geographic corridors. Our full report deconstructs these layers with granular revenue flows, volume-to-value conversions, and scenario-based sensitivity models that allow readers to stress-test assumptions against shifting raw material baskets and regional trade dynamics.
Epoxy Electrocoating Market
Competitive Arena and Strategic Positioning
The epoxy electrocoating ecosystem is characterized by pronounced concentration, with the top three players accounting for more than half of total market revenue and the top five collectively commanding nearly three-quarters of industry value. This concentration underscores the scale advantages, formulation expertise, and long-term OEM relationships that define market leadership. PPG Industries, headquartered in Pittsburgh, maintains a dominant footprint through its Powercron cathodic epoxy electrocoats, which are engineered for high corrosion resistance and uniform film build across industrial, automotive, and heavy-duty applications. Axalta Coating Systems, based in Philadelphia, competes with its AquaEC series, emphasizing superior corrosion protection and mechanical properties tailored for automotive OEM and industrial customers. BASF SE, operating from Ludwigshafen, leverages the CathoGuard family of cathodic epoxy e-coats, differentiating on high throw power, application efficiency, and sustainability attributes for automotive and industrial corrosion protection.
The competitive field extends across multiple geographies and capability sets. The Sherwin-Williams Company, headquartered in Cleveland, supplies Vectrogard cathodic epoxy electrocoats designed for excellent edge coverage and corrosion resistance on metal substrates in heavy machinery and industrial markets. Nippon Paint Holdings and Kansai Paint, both headquartered in Osaka, bring distinct electrochemical expertise to the table, with Nippon Paint focusing on efficient, eco-friendly corrosion protection through epoxy chemistry, and Kansai Paint developing ELECRON epoxy-based e-coat products that emphasize low-temperature curing, low-voltage application, and high performance for industrial use. KCC Corporation, based in Seoul, holds a strong market position in Asia, particularly in automotive OEM electrophoretic paints, while Tatung Fine Chemicals serves industrial and automotive sectors as a specialized manufacturer of epoxy electrocoats.
Strategic maneuvering in this arena is intensifying. BASF exemplifies the multi-axis approach many leaders are adopting, having commissioned a new state-of-the-art production plant for automotive OEM coatings, including e-coat capabilities, at its Muenster site in Germany in late 2025, and subsequently expanding its e-coat manufacturing facility in Mangalore, India, to meet growing automotive OEM demand in South Asia and ASEAN. These capital deployments signal a clear intent to align capacity with regional demand gravity while strengthening supply chain resilience. In parallel, pricing and formulation strategies are being recalibrated across the value chain, as detailed in the sections that follow.
Raw Material Pressure and Cost Structure Dynamics
Input cost trajectories have become a decisive factor in margin management and pricing architecture. Epoxy resin prices in April 2026 reached approximately 2.62 USD per kilogram in Northeast Asia, reflecting a year-over-year increase of 23 percent, while European benchmarks climbed to about 5.23 USD per kilogram, up 13 percent, under sustained global upward pressure from feedstock costs. The Middle East segment experienced an even sharper escalation, with resin prices surging nearly 32 percent between late 2025 and March 2026 as costs for Bisphenol A and Epichlorohydrin climbed. These movements are not isolated commodity fluctuations; they directly influence formulation economics, inventory strategy, and downstream price transmission.
DIC Corporation formally recognized these pressures by announcing sales price increases for epoxy resins and curing agents effective mid-April 2026, citing rising crude oil and petrochemical feedstock costs alongside Middle East tensions. The convergence of regional price divergences, feedstock sensitivity, and logistics complexity creates a landscape where static cost assumptions quickly erode competitiveness. Our report provides a structured framework for tracking these cost vectors, mapping regional arbitrage opportunities, and evaluating hedging or sourcing reconfiguration options without relying on simplistic average-cost narratives.
Regulatory and Trade Environment Considerations
Trade policy and antidumping frameworks add another layer of complexity to market planning. In 2025, the U.S. Department of Commerce issued final affirmative determinations in antidumping and countervailing duty investigations on epoxy resins originating from China, India, Korea, Taiwan, and Thailand. These determinations reshape the cost baseline for imported resin inputs and influence the relative attractiveness of domestic or alternative sourcing pathways. For manufacturers and converters that depend on cross-border resin flows, the implications extend beyond tariff calculations to include supplier qualification timelines, inventory buffer strategies, and contract renegotiation cycles. The study integrates these regulatory shifts into a broader risk-matrix approach, helping readers align procurement posture with compliance requirements and regional demand patterns.
Formulation and Application Architecture
The market's structural composition reflects a clear preference for single-component systems, which command a larger revenue share, while two-component formulations maintain a significant but smaller footprint. This distribution is not merely a technical preference; it carries implications for application efficiency, cure profiles, storage stability, and end-user handling requirements. In application terms, automotive demand represents the largest revenue pool, driven by the continued reliance on electrophoretic deposition for consistent film thickness, uniform coverage, and corrosion protection across complex metal geometries. Industrial machinery follows as a substantial secondary vertical, with appliances and other end-use categories contributing additional demand streams.
Regional revenue distribution further illustrates the market's geographic concentration, with Asia Pacific holding the largest share, followed by North America and Europe, while Latin America and the Middle East and Africa represent smaller but strategically important corridors. These regional profiles are shaped by local automotive production intensities, heavy equipment manufacturing bases, and varying regulatory expectations around corrosion protection and environmental performance. Rather than presenting static percentage splits, our analysis contextualizes these regional dynamics through capacity location decisions, OEM localization trends, and feedstock proximity advantages, enabling readers to interpret where growth is likely to materialize and why.
What the Study Delivers for 2026 Decision-Making
The full Epoxy Electrocoating Market report is structured to move beyond top-line forecasts and deliver operational intelligence that can be embedded directly into strategy, procurement, and commercial planning. The study includes a detailed segmentation analysis across formulation types and application verticals, with revenue trajectories, volume indicators, and relative share evolution that clarify where value is accumulating and where competitive intensity is rising. Regional assessments go beyond headline sizes to examine capacity footprints, demand drivers, and trade flow implications, providing a multi-dimensional view of market geography.
Competitive profiling extends to strategic positioning, capability differentiation, recent facility investments, and pricing behavior, allowing readers to benchmark their own portfolios against the actions of leading participants. The report also integrates raw material tracking, regulatory developments, and macroeconomic linkages into a cohesive dynamics section that explains how cost shocks, duty determinations, and capacity expansions interact to shape margin outcomes and market access. Scenario frameworks are included to test growth paths under different feedstock price environments, demand cadence assumptions, and regional policy shifts, giving planners a practical tool for contingency preparation.
For enterprise teams operating in 2026, the study is designed to answer several pressing questions: How should procurement strategies adapt to divergent regional resin pricing? Which application verticals are likely to drive incremental volume versus those where value growth will be margin-led? Where do capacity expansions and localization moves by major players alter competitive access? How do trade determinations influence sourcing flexibility and cost baselines? By addressing these questions with data-grounded analysis and forward-looking scenarios, the report provides a reference point for investment prioritization, commercial messaging, and risk calibration.
Strategic Implications and Forward Look
The epoxy electrocoating market is entering a phase where growth is real but increasingly conditional on how well organizations manage cost volatility, regional capacity shifts, and competitive concentration. The 4.5 percent CAGR projected through 2032 offers a credible expansion pathway, yet capturing disproportionate value will depend on formulation leadership, application-specific performance credentials, and the ability to navigate raw material and trade complexities. Companies that treat epoxy electrocoating as a strategic capability rather than a commodity input will be better positioned to secure OEM relationships, optimize total cost of ownership for end customers, and sustain margins amid fluctuating feedstock economics.
This preview has outlined the structural contours of the market, the competitive forces shaping it, and the operational dynamics that will define decision-making in 2026 and beyond. The complete study builds on this foundation with detailed segmentation revenue flows, regional capacity and demand mappings, competitive benchmarking, raw material tracking, and scenario-based planning tools. For leadership teams seeking to align strategy with the market's actual growth architecture, the full report provides the depth required to move from directional confidence to precise action.
Electrocoating Market
For detailed analysis of this topic, please visit the official page: Epoxy Electrocoating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Musk Aroma Chemicals Market Hits $1.15B in 2025, Poised to Reach $1.54B by 2032 at 4.25% CAGR
By pmarketresearch, 2026-09-16
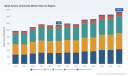
Navigating the Global Musk Aroma Chemicals Market: Strategic Intelligence for 2026 and Beyond
As the global fragrance and personal care industries evolve, the demand for musk aroma chemicals remains a foundational element of product formulation. However, the landscape is undergoing a significant transformation driven by regulatory shifts, sustainability mandates, and changing consumer preferences. For stakeholders operating in this sector, relying on historical data alone is insufficient. The newly released Worldwide Musk Aroma Chemicals Market research by PW Consulting offers a comprehensive, forward-looking analysis designed to empower enterprise decision-making through 2032. This article outlines the strategic value of this intelligence, highlighting key market dynamics, competitive structures, and the operational insights contained within the full report.
Market Trajectory and Structural Shifts
The economic trajectory of the musk aroma chemicals sector reveals a resilient yet complex growth pattern. Analyzing historical data from 2020 through 2025 shows a market that has navigated volatility while maintaining a clear upward trend. Following a valuation of approximately 975 million USD in 2020, the market experienced fluctuations, dipping slightly in 2021 before accelerating growth in 2022 and 2023. While 2024 saw a marginal contraction, the market rebounded to an estimated 1150 million USD in 2025.
Looking ahead, the forecast period from 2026 to 2032 projects a steady compound annual growth rate of 4.25 percent. By 2032, the global revenue is anticipated to reach 1539.03 million USD. This growth is not merely a function of volume but reflects a strategic shift in the types of musks being utilized and the regions where consumption is expanding. Understanding the nuances behind these aggregate figures is critical for capacity planning and investment allocation, details of which are fully elaborated in the proprietary dataset accompanying this study.
Regulatory Pressures and Raw Material Dynamics
Regulatory compliance remains one of the most potent forces shaping the market landscape. The industry is currently navigating a tightening framework governed by institutions such as IFRA and REACH. The IFRA 51st Amendment, for instance, imposes specific restrictions on certain musk compounds, including concentration limits for specific categories. Compliance deadlines for existing creations extend into October 2025, creating an immediate imperative for reformulations.
Simultaneously, legacy nitro-musk and certain polycyclic musk compounds face increasing scrutiny due to concerns over bioaccumulation and environmental persistence. This regulatory environment is actively driving reformulation toward macrocyclic and more biodegradable musk chemistries. In terms of raw materials, synthetic musks dominate supply, accounting for approximately 85 percent of the market. This dominance is supported by cost efficiency, consistent quality, and better regulatory adaptability compared to natural alternatives. For manufacturers, the ability to navigate these constraints while maintaining performance and cost-effectiveness is a key differentiator. Our report provides a deep dive into how these regulatory factors are influencing sourcing strategies and product development pipelines across key regions.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate concentration, with the top three companies holding a combined share of 48.5 percent and the top five holding 62.1 percent. This consolidation indicates that while major players dominate, there is still significant room for specialized suppliers and niche innovators to capture value through differentiation.
Worldwide Musk Aroma Chemicals Market
Leading the landscape are global fragrance ingredient leaders such as Givaudan and dsm-firmenich. Givaudan, headquartered in Vernier, Switzerland, offers a broad portfolio of synthetic and macrocyclic musk aroma chemicals, with a strong emphasis on biodegradable and regulatory-compliant variants. Similarly, dsm-firmenich, based in Switzerland, is a major producer of perfumery ingredients including advanced synthetic musks like Habanolide. Their focus on sustainable macrocyclic musks was highlighted by a significant capacity expansion in March 2024, where they commissioned two new manufacturing facilities in France, including a specialized unit for biodegradable musk ingredients.
Other key players include Symrise AG from Germany, which emphasizes innovation in performance and regulatory compliance for personal care and fine fragrance applications, and International Flavors and Fragrances Inc. (IFF) from New York, USA, which leverages integrated supply chains and biotechnology approaches for cost-effective, high-performance musk fixatives. Regional specialists also play a crucial role. MANE SA in France specializes in custom fragrance creation with proprietary macrocyclic musk synthesis for premium formulations, while Takasago International Corporation and SODA AROMATIC Co., Ltd. in Japan provide essential synthetic aroma ingredients. Additionally, companies like LANXESS in Germany and Privi Speciality Chemicals Limited in India contribute to the industrial and global fragrance markets respectively.
Aroma Chemicals Market
These competitors are not merely competing on price but are increasingly differentiating through sustainability credentials, intellectual property in synthesis methods, and agility in meeting regulatory standards. The full strategic profiles, including competitive benchmarking and recent development timelines, are detailed within the report to help identify partnership opportunities and threat vectors.
Detailed Content Overview and Operational Utility
This market research study is designed to be a practical tool for strategic planning rather than a static snapshot of data. The report encompasses a wide range of analytical sections tailored to different functional needs within an organization.
-
Segmentation Analysis: The document breaks down the market by type, including macrocyclic, polycyclic, and alicyclic musks, as well as by application across fine fragrances, personal care, and home care products. This allows businesses to identify high-growth sub-segments specific to their product portfolios.
-
Regional Dynamics: Geographic performance is analyzed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. This helps in identifying regional demand pockets and supply chain vulnerabilities.
-
Supply Chain and Production: Insights into manufacturing dynamics, capacity expansions, and raw material sourcing strategies are provided, offering clarity on potential bottlenecks or opportunities for vertical integration.
-
Regulatory Impact Assessment: Beyond general trends, the report includes specific assessments of how current and upcoming regulations, such as IFRA amendments and REACH restrictions, are reshaping the market entry barriers and product lifecycles.
-
Company Profiles and Developments: In-depth profiles of key market participants cover their strategic moves, recent developments, and market positioning, enabling competitive intelligence gathering.
Strategic Imperatives for Enterprise Leaders
For executives and strategists, the value of this report lies in its ability to convert complex market signals into actionable intelligence. As the market moves toward 2032, the 4.25 percent CAGR suggests a steady expansion, but the underlying drivers are shifting. Growth will increasingly be tied to sustainability compliance and innovation in biosynthetic alternatives rather than traditional volume expansion.
Companies must evaluate their portfolios against the backdrop of the 85 percent dominance of synthetic musks and the regulatory pressure on legacy compounds. Investment decisions regarding R&D should prioritize biodegradable macrocyclic options, as evidenced by the strategic moves of key players like dsm-firmenich. Furthermore, supply chain resilience is paramount given the regulatory complexities and regional concentration variations.
The data provided in this study serves as a baseline for scenario planning. Whether assessing the viability of entering new geographic markets, evaluating potential M&A targets, or optimizing formulation strategies to meet IFRA standards, the granular data points and qualitative analysis contained in the full report are essential. The hidden nuances within the segmentation splits and regional performance metrics offer the competitive edge necessary to outmaneuver rivals who rely on public, aggregated data.
Conclusion
The Worldwide Musk Aroma Chemicals Market is at a pivotal juncture where sustainability, regulation, and performance converge. PW Consulting's latest market research provides the depth and breadth of analysis required to navigate this complexity successfully. By leveraging the insights contained in this study, organizations can align their strategies with the market trajectory, mitigate regulatory risks, and capitalize on the growth opportunities presented by the evolving demand for advanced musk aroma chemicals. To access the complete dataset, specific regional valuations, and detailed competitive benchmarking, stakeholders are invited to explore the full report resources.
For detailed analysis of this topic, please visit the official page: Worldwide Musk Aroma Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Image Signal Processor Market to Hit $8,800 Million by 2032 at 13.01% CAGR
By pmarketresearch, 2026-09-16
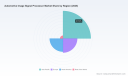
Strategic Intelligence in the Automotive Image Signal Processor Market: A 2026 Decision Framework
Driving Vision Through Data: The PW Consulting Market Research Introduction
The automotive industry is currently undergoing one of the most significant technological shifts in its history, moving rapidly from mechanical dominance to software-defined, sensor-rich architectures. At the heart of this transformation lies the Image Signal Processor (ISP), the critical component responsible for converting raw sensor data into actionable visual intelligence. As vehicles evolve towards higher levels of autonomy and enhanced safety features, the demand for sophisticated image processing has never been more critical. PW Consulting is pleased to introduce our latest comprehensive study, the Worldwide Automotive Image Signal Processor Market research report, designed specifically to equip stakeholders with the strategic foresight required for navigating the 2026 landscape and beyond.
This report is not merely a collection of statistics; it is a strategic decision-making tool built upon rigorous primary and secondary research. Our analysis covers the historical trajectory from 2020 through the base year of 2025, while projecting market dynamics through the forecast period ending in 2032. For executives, investors, and product strategists, understanding the magnitude of this growth is the first step toward capitalizing on the opportunities within the semiconductor value chain. The data indicates a robust expansion trajectory, reflecting the increasing integration of cameras in various vehicle domains, from exterior sensing to interior monitoring.
Our objective with this publication is to provide a clear lens through which companies can assess their competitive positioning. The market has reached a inflection point where traditional growth drivers are being compounded by new regulatory requirements and technological breakthroughs in artificial intelligence. By synthesizing historical performance with future projections, this study offers a nuanced view of where capital should be allocated and which technological pathways are likely to yield the highest returns in the coming cycle.
Market Trajectory and Growth Catalysts
Understanding the scale of the opportunity is essential for long-term strategic planning. The automotive ISP market has demonstrated resilience and significant upward momentum over the past five years. From a baseline established in the early 2020s, the market has compounded steadily, driven by the adoption of Advanced Driver Assistance Systems (ADAS) and the gradual rollout of autonomous driving features. Our analysis projects that this momentum will accelerate, with the market expanding from recent valuations to reach substantial milestones by the end of the decade. The Compound Annual Growth Rate (CAGR) reflects a strong double-digit expansion, signaling a high-demand environment for ISP manufacturers and integrators.
Several key factors are underpinning this growth trajectory. First, the regulatory push for safety standards across major automotive markets is mandating more sophisticated camera systems. Second, the consumer demand for enhanced in-cabin experiences, including monitoring systems for driver distraction and occupant comfort, is opening new revenue streams for ISPs beyond traditional exterior viewing. Third, the technological arms race among original equipment manufacturers (OEMs) to deploy high-level autonomous features is increasing the pixel throughput and processing power requirements of these components.
Image Signal Processor And Vision Processor Market
While the overall market size is compelling, the distribution of value across different segments tells a more complex story. The shift towards integrated solutions versus standalone components is reshaping supply chain dynamics. Similarly, regional variations in adoption rates and manufacturing capabilities influence where strategic partnerships are most viable. Our report dissects these macro trends without losing sight of the granular operational realities faced by industry players. We analyze how these macro forces translate into procurement strategies, production planning, and R&D focus areas for the upcoming fiscal years.
Product Architecture and Application Segments
The architecture of image signal processing solutions is diverging as application requirements become more specialized. The market is currently segmented by product type, primarily distinguishing between integrated ISPs and standalone units. Integrated ISPs, often embedded within larger system-on-chip (SoC) architectures, are gaining traction due to their ability to optimize space and power consumption within the vehicle. These solutions are particularly favored in applications where processing latency must be minimized, such as real-time obstacle detection. Conversely, standalone ISPs continue to hold significant value in scenarios requiring modular flexibility or where legacy architectures are still being serviced. The balance between these two types is shifting, and our report provides detailed insight into which configuration is favored across different vehicle tiers and price points.
Application segmentation further reveals where the highest value is being generated. ADAS and autonomous driving remain the dominant drivers of ISP demand. The need for high dynamic range (HDR), LED flicker mitigation, and low-light performance in safety-critical systems ensures that this segment commands a premium. Viewing cameras, including surround-view and rear-view systems, represent a stable and growing portion of the market, essential for regulatory compliance and basic vehicle functionality. However, a rapidly emerging segment is in-cabin monitoring. As regulations regarding driver monitoring systems (DMS) become stricter, the requirement for ISPs capable of processing interior camera feeds for gesture recognition and vital monitoring is creating a new frontier for growth.
The interplay between these segments is critical for suppliers. A product line that excels in ADAS may not be optimal for in-cabin applications, which have different power and thermal constraints. Our analysis maps these requirements against current product portfolios, helping companies identify gaps in their offerings. We examine how leading architectures are evolving to handle multi-camera inputs and higher resolutions, ensuring that the processing pipeline does not become a bottleneck as sensor technology advances. This section of the report serves as a technical benchmark for evaluating current capabilities against future market needs.
Competitive Landscape and Key Players
The competitive environment in the automotive ISP market is characterized by a mix of established semiconductor giants and specialized innovators. Concentration among the top players is significant, indicating a market where scale, technology leadership, and strategic partnerships dictate market share. The top three companies command a substantial portion of the market revenue, while the top five firms control the majority of the industry's value. This concentration suggests high barriers to entry and the importance of maintaining a robust roadmap to stay relevant.
Key companies shaping this landscape include onsemi, known for their dedicated automotive ISPs optimized for high-performance HDR CMOS image sensors. Their focus on ADAS and surround-view applications positions them strongly in the safety-critical segment. OmniVision Technologies competes aggressively with AI-enabled ASICs and companion processors that integrate NPU capabilities, catering to the growing need for edge intelligence within camera modules. STMicroelectronics continues to leverage its integrated vision and sensor technologies, particularly for ADAS and in-cabin monitoring, benefiting from a broad automotive portfolio.
Texas Instruments and NXP Semiconductors remain pivotal players, with TI supplying essential analog and digital solutions and NXP offering integrated ISPs within their i.MX series processors. Renesas Electronics contributes with vision processors like the V3H series, specifically targeted at ADAS perception. Notably, regional specialists are also making an impact. Nextchip Co., Ltd. in South Korea specializes in ADAS SoCs for L2+ to L3 autonomous driving, while VeriSilicon Microelectronics in China focuses on ISP IP series with rigorous functional safety certifications. Sony Semiconductor Solutions leads in the sensor side with innovations like the IMX828 featuring built-in MIPI A-PHY interfaces, often paired with ISP pipelines. Ambarella and Qualcomm round out the competitive field with computer vision SoCs and Snapdragon platforms that incorporate advanced image processing for connected vehicles.
Understanding the strategies of these players is vital. For instance, VeriSilicon recently achieved ISO 26262 ASIL-B and ASIL-D certifications for their second-generation ISP IP, highlighting the industry's focus on functional safety. Sony's announcement of the IMX828 in late 2025 underscores the trend towards higher bandwidth interfaces and HDR performance. These developments are not isolated; they are indicators of where the market is heading. Our report analyzes the recent activities, product launches, and strategic moves of these key entities to provide a clear picture of the competitive intensity and potential consolidation opportunities.
Industry Dynamics and Regulatory Impact
The operational environment for automotive ISPs is increasingly influenced by external dynamics ranging from supply chain constraints to regulatory mandates. In late 2025 and early 2026, the industry faced notable shifts. Average automotive semiconductor lead times lengthened amid rising demand for vision-related components, putting pressure on supply chain resilience. This lengthening of lead times requires manufacturers to adopt more cautious inventory strategies and strengthen relationships with foundries and packaging suppliers.
Regulatory factors are also reshaping the market. The emphasis on functional safety, exemplified by ISO 26262 certifications, is becoming a prerequisite for participation in high-value ADAS contracts. Components that cannot demonstrate compliance with safety integrity levels are increasingly being excluded from critical systems. Furthermore, geopolitical factors are influencing trade flows. Recent investigations and tariffs involving critical minerals and semiconductor products in the United States introduce potential cost volatility and supply chain rerouting considerations. These factors necessitate a agile approach to sourcing and manufacturing location decisions.
Additionally, broader industry analysis suggests that the complexity of image-signal processors within automotive SoCs is increasing. Driven by the need for AI accelerators and zonal architectures, the semiconductor content per vehicle is rising. This trend aligns with projections that automotive semiconductor demand will continue to grow at a double-digit CAGR through 2030. For ISPs specifically, this means that value is shifting towards solutions that can integrate more functionality, support higher data throughputs, and interface seamlessly with central vehicle computers. Our report evaluates how these dynamics impact pricing power, margin structures, and long-term contract negotiations.
Worldwide Automotive Image Signal Processor Market
Strategic Value for 2026 Decision Making
Why is this research critical for 2026 decision-making? The answer lies in the convergence of timing and technology. Companies entering or expanding in this market in 2026 must align their product development cycles with the rapid adoption curves of ADAS and autonomous features. Decisions made today regarding IP licensing, manufacturing partnerships, or product portfolio focus will determine competitiveness in 2028 and beyond. The data provided in this report allows stakeholders to model various scenarios, assessing risk and opportunity under different adoption rates and regulatory environments.
For investors, the market concentration data and growth projections offer a framework for evaluating potential returns and identifying companies with sustainable competitive advantages. For OEMs and Tier 1 suppliers, the segmentation analysis helps in specifying the right components for different vehicle platforms, balancing cost against performance requirements. For semiconductor manufacturers, the insights into regional demand and product type preferences inform capacity planning and R&D prioritization. The report serves as a single source of truth that aligns these diverse stakeholders around a common understanding of market realities.
Furthermore, the forward-looking nature of the forecast period allows companies to anticipate inflection points. Knowing when certain segments are expected to accelerate enables proactive rather than reactive strategy formulation. Whether it is preparing for the surge in in-cabin monitoring demands or positioning for the next generation of high-pixel-throughput sensors, timing is everything. PW Consulting's analysis removes the ambiguity from these projections, providing a validated basis for budget allocation and strategic planning.
Unlocking Full Market Intelligence
While this overview highlights the significant trends, competitive stakes, and macroeconomic drivers within the Worldwide Automotive Image Signal Processor Market, it represents only a fraction of the intelligence available in our full report. The strategic advantage lies in the details: the specific revenue splits across regions, the granular breakdown of application segments, and the deep-dive profiles of each key company's technology roadmap. To make fully informed decisions, stakeholders need access to the comprehensive data sets that underpin our high-level conclusions.
Our complete market research product offers detailed tables, extensive competitive benchmarking, and scenario-based forecasting that goes beyond the summaries provided here. We invite industry leaders, investors, and strategic planners to access the full Worldwide Automotive Image Signal Processor Market report. By doing so, you will gain the granular intelligence necessary to secure your position in this rapidly evolving sector. Visit our source webpage to download the full executive summary and acquire the detailed market intelligence needed to navigate the automotive semiconductor landscape of 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Image Signal Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com