

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Epoxy Electrocoating Market Hits $1,850M in 2025, Projected to Reach $2,517.6M by 2032 at 4.5% CAGR

Navigating the Epoxy Electrocoating Market: Strategic Intelligence for 2026 and Beyond
The global manufacturing landscape is undergoing a structural shift where corrosion protection is no longer viewed as a mere finishing step but as a critical determinant of asset longevity, regulatory compliance, and total cost of ownership. Within this evolving environment, epoxy electrocoating has cemented its position as a cornerstone technology for industrial and automotive applications. As we move through 2026, enterprise leaders across coatings, original equipment manufacturing, and supply chain management face a complex matrix of feedstock volatility, regional capacity realignments, and intensifying competitive pressures. This analysis serves as a strategic preview of our newly released Epoxy Electrocoating Market study, designed to equip decision-makers with the contextual depth and forward-looking frameworks necessary to navigate the forecast period through 2032.
Macro Trajectory and Growth Architecture
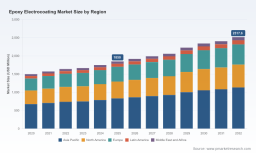
The market has demonstrated consistent expansion over the past half-decade, building on a baseline that exceeded 1.5 billion USD in 2020 and progressed through a series of steady annual increments to reach approximately 1.85 billion USD by 2025. This historical arc reflects sustained demand from metal substrate protection, automotive OEM electrophoretic processes, and heavy-duty industrial equipment manufacturing. Looking ahead, the forecast window projects the market to approach 2.5 billion USD by 2032, anchored by a compound annual growth rate of 4.5 percent. While these headline figures establish a clear growth trajectory, the underlying value creation is unevenly distributed across formulations, application verticals, and geographic corridors. Our full report deconstructs these layers with granular revenue flows, volume-to-value conversions, and scenario-based sensitivity models that allow readers to stress-test assumptions against shifting raw material baskets and regional trade dynamics.
Epoxy Electrocoating Market
Competitive Arena and Strategic Positioning
The epoxy electrocoating ecosystem is characterized by pronounced concentration, with the top three players accounting for more than half of total market revenue and the top five collectively commanding nearly three-quarters of industry value. This concentration underscores the scale advantages, formulation expertise, and long-term OEM relationships that define market leadership. PPG Industries, headquartered in Pittsburgh, maintains a dominant footprint through its Powercron cathodic epoxy electrocoats, which are engineered for high corrosion resistance and uniform film build across industrial, automotive, and heavy-duty applications. Axalta Coating Systems, based in Philadelphia, competes with its AquaEC series, emphasizing superior corrosion protection and mechanical properties tailored for automotive OEM and industrial customers. BASF SE, operating from Ludwigshafen, leverages the CathoGuard family of cathodic epoxy e-coats, differentiating on high throw power, application efficiency, and sustainability attributes for automotive and industrial corrosion protection.
The competitive field extends across multiple geographies and capability sets. The Sherwin-Williams Company, headquartered in Cleveland, supplies Vectrogard cathodic epoxy electrocoats designed for excellent edge coverage and corrosion resistance on metal substrates in heavy machinery and industrial markets. Nippon Paint Holdings and Kansai Paint, both headquartered in Osaka, bring distinct electrochemical expertise to the table, with Nippon Paint focusing on efficient, eco-friendly corrosion protection through epoxy chemistry, and Kansai Paint developing ELECRON epoxy-based e-coat products that emphasize low-temperature curing, low-voltage application, and high performance for industrial use. KCC Corporation, based in Seoul, holds a strong market position in Asia, particularly in automotive OEM electrophoretic paints, while Tatung Fine Chemicals serves industrial and automotive sectors as a specialized manufacturer of epoxy electrocoats.
Strategic maneuvering in this arena is intensifying. BASF exemplifies the multi-axis approach many leaders are adopting, having commissioned a new state-of-the-art production plant for automotive OEM coatings, including e-coat capabilities, at its Muenster site in Germany in late 2025, and subsequently expanding its e-coat manufacturing facility in Mangalore, India, to meet growing automotive OEM demand in South Asia and ASEAN. These capital deployments signal a clear intent to align capacity with regional demand gravity while strengthening supply chain resilience. In parallel, pricing and formulation strategies are being recalibrated across the value chain, as detailed in the sections that follow.
Raw Material Pressure and Cost Structure Dynamics
Input cost trajectories have become a decisive factor in margin management and pricing architecture. Epoxy resin prices in April 2026 reached approximately 2.62 USD per kilogram in Northeast Asia, reflecting a year-over-year increase of 23 percent, while European benchmarks climbed to about 5.23 USD per kilogram, up 13 percent, under sustained global upward pressure from feedstock costs. The Middle East segment experienced an even sharper escalation, with resin prices surging nearly 32 percent between late 2025 and March 2026 as costs for Bisphenol A and Epichlorohydrin climbed. These movements are not isolated commodity fluctuations; they directly influence formulation economics, inventory strategy, and downstream price transmission.
DIC Corporation formally recognized these pressures by announcing sales price increases for epoxy resins and curing agents effective mid-April 2026, citing rising crude oil and petrochemical feedstock costs alongside Middle East tensions. The convergence of regional price divergences, feedstock sensitivity, and logistics complexity creates a landscape where static cost assumptions quickly erode competitiveness. Our report provides a structured framework for tracking these cost vectors, mapping regional arbitrage opportunities, and evaluating hedging or sourcing reconfiguration options without relying on simplistic average-cost narratives.
Regulatory and Trade Environment Considerations
Trade policy and antidumping frameworks add another layer of complexity to market planning. In 2025, the U.S. Department of Commerce issued final affirmative determinations in antidumping and countervailing duty investigations on epoxy resins originating from China, India, Korea, Taiwan, and Thailand. These determinations reshape the cost baseline for imported resin inputs and influence the relative attractiveness of domestic or alternative sourcing pathways. For manufacturers and converters that depend on cross-border resin flows, the implications extend beyond tariff calculations to include supplier qualification timelines, inventory buffer strategies, and contract renegotiation cycles. The study integrates these regulatory shifts into a broader risk-matrix approach, helping readers align procurement posture with compliance requirements and regional demand patterns.
Formulation and Application Architecture
The market's structural composition reflects a clear preference for single-component systems, which command a larger revenue share, while two-component formulations maintain a significant but smaller footprint. This distribution is not merely a technical preference; it carries implications for application efficiency, cure profiles, storage stability, and end-user handling requirements. In application terms, automotive demand represents the largest revenue pool, driven by the continued reliance on electrophoretic deposition for consistent film thickness, uniform coverage, and corrosion protection across complex metal geometries. Industrial machinery follows as a substantial secondary vertical, with appliances and other end-use categories contributing additional demand streams.
Regional revenue distribution further illustrates the market's geographic concentration, with Asia Pacific holding the largest share, followed by North America and Europe, while Latin America and the Middle East and Africa represent smaller but strategically important corridors. These regional profiles are shaped by local automotive production intensities, heavy equipment manufacturing bases, and varying regulatory expectations around corrosion protection and environmental performance. Rather than presenting static percentage splits, our analysis contextualizes these regional dynamics through capacity location decisions, OEM localization trends, and feedstock proximity advantages, enabling readers to interpret where growth is likely to materialize and why.
What the Study Delivers for 2026 Decision-Making
The full Epoxy Electrocoating Market report is structured to move beyond top-line forecasts and deliver operational intelligence that can be embedded directly into strategy, procurement, and commercial planning. The study includes a detailed segmentation analysis across formulation types and application verticals, with revenue trajectories, volume indicators, and relative share evolution that clarify where value is accumulating and where competitive intensity is rising. Regional assessments go beyond headline sizes to examine capacity footprints, demand drivers, and trade flow implications, providing a multi-dimensional view of market geography.
Competitive profiling extends to strategic positioning, capability differentiation, recent facility investments, and pricing behavior, allowing readers to benchmark their own portfolios against the actions of leading participants. The report also integrates raw material tracking, regulatory developments, and macroeconomic linkages into a cohesive dynamics section that explains how cost shocks, duty determinations, and capacity expansions interact to shape margin outcomes and market access. Scenario frameworks are included to test growth paths under different feedstock price environments, demand cadence assumptions, and regional policy shifts, giving planners a practical tool for contingency preparation.
For enterprise teams operating in 2026, the study is designed to answer several pressing questions: How should procurement strategies adapt to divergent regional resin pricing? Which application verticals are likely to drive incremental volume versus those where value growth will be margin-led? Where do capacity expansions and localization moves by major players alter competitive access? How do trade determinations influence sourcing flexibility and cost baselines? By addressing these questions with data-grounded analysis and forward-looking scenarios, the report provides a reference point for investment prioritization, commercial messaging, and risk calibration.
Strategic Implications and Forward Look
The epoxy electrocoating market is entering a phase where growth is real but increasingly conditional on how well organizations manage cost volatility, regional capacity shifts, and competitive concentration. The 4.5 percent CAGR projected through 2032 offers a credible expansion pathway, yet capturing disproportionate value will depend on formulation leadership, application-specific performance credentials, and the ability to navigate raw material and trade complexities. Companies that treat epoxy electrocoating as a strategic capability rather than a commodity input will be better positioned to secure OEM relationships, optimize total cost of ownership for end customers, and sustain margins amid fluctuating feedstock economics.
This preview has outlined the structural contours of the market, the competitive forces shaping it, and the operational dynamics that will define decision-making in 2026 and beyond. The complete study builds on this foundation with detailed segmentation revenue flows, regional capacity and demand mappings, competitive benchmarking, raw material tracking, and scenario-based planning tools. For leadership teams seeking to align strategy with the market's actual growth architecture, the full report provides the depth required to move from directional confidence to precise action.
Electrocoating Market
For detailed analysis of this topic, please visit the official page: Epoxy Electrocoating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com