

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive Image Signal Processor Market to Hit $8,800 Million by 2032 at 13.01% CAGR

Strategic Intelligence in the Automotive Image Signal Processor Market: A 2026 Decision Framework
Driving Vision Through Data: The PW Consulting Market Research Introduction
The automotive industry is currently undergoing one of the most significant technological shifts in its history, moving rapidly from mechanical dominance to software-defined, sensor-rich architectures. At the heart of this transformation lies the Image Signal Processor (ISP), the critical component responsible for converting raw sensor data into actionable visual intelligence. As vehicles evolve towards higher levels of autonomy and enhanced safety features, the demand for sophisticated image processing has never been more critical. PW Consulting is pleased to introduce our latest comprehensive study, the Worldwide Automotive Image Signal Processor Market research report, designed specifically to equip stakeholders with the strategic foresight required for navigating the 2026 landscape and beyond.
This report is not merely a collection of statistics; it is a strategic decision-making tool built upon rigorous primary and secondary research. Our analysis covers the historical trajectory from 2020 through the base year of 2025, while projecting market dynamics through the forecast period ending in 2032. For executives, investors, and product strategists, understanding the magnitude of this growth is the first step toward capitalizing on the opportunities within the semiconductor value chain. The data indicates a robust expansion trajectory, reflecting the increasing integration of cameras in various vehicle domains, from exterior sensing to interior monitoring.
Our objective with this publication is to provide a clear lens through which companies can assess their competitive positioning. The market has reached a inflection point where traditional growth drivers are being compounded by new regulatory requirements and technological breakthroughs in artificial intelligence. By synthesizing historical performance with future projections, this study offers a nuanced view of where capital should be allocated and which technological pathways are likely to yield the highest returns in the coming cycle.
Market Trajectory and Growth Catalysts
Understanding the scale of the opportunity is essential for long-term strategic planning. The automotive ISP market has demonstrated resilience and significant upward momentum over the past five years. From a baseline established in the early 2020s, the market has compounded steadily, driven by the adoption of Advanced Driver Assistance Systems (ADAS) and the gradual rollout of autonomous driving features. Our analysis projects that this momentum will accelerate, with the market expanding from recent valuations to reach substantial milestones by the end of the decade. The Compound Annual Growth Rate (CAGR) reflects a strong double-digit expansion, signaling a high-demand environment for ISP manufacturers and integrators.
Several key factors are underpinning this growth trajectory. First, the regulatory push for safety standards across major automotive markets is mandating more sophisticated camera systems. Second, the consumer demand for enhanced in-cabin experiences, including monitoring systems for driver distraction and occupant comfort, is opening new revenue streams for ISPs beyond traditional exterior viewing. Third, the technological arms race among original equipment manufacturers (OEMs) to deploy high-level autonomous features is increasing the pixel throughput and processing power requirements of these components.
Image Signal Processor And Vision Processor Market
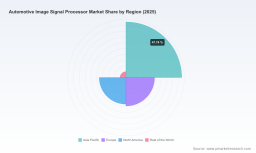
While the overall market size is compelling, the distribution of value across different segments tells a more complex story. The shift towards integrated solutions versus standalone components is reshaping supply chain dynamics. Similarly, regional variations in adoption rates and manufacturing capabilities influence where strategic partnerships are most viable. Our report dissects these macro trends without losing sight of the granular operational realities faced by industry players. We analyze how these macro forces translate into procurement strategies, production planning, and R&D focus areas for the upcoming fiscal years.
Product Architecture and Application Segments
The architecture of image signal processing solutions is diverging as application requirements become more specialized. The market is currently segmented by product type, primarily distinguishing between integrated ISPs and standalone units. Integrated ISPs, often embedded within larger system-on-chip (SoC) architectures, are gaining traction due to their ability to optimize space and power consumption within the vehicle. These solutions are particularly favored in applications where processing latency must be minimized, such as real-time obstacle detection. Conversely, standalone ISPs continue to hold significant value in scenarios requiring modular flexibility or where legacy architectures are still being serviced. The balance between these two types is shifting, and our report provides detailed insight into which configuration is favored across different vehicle tiers and price points.
Application segmentation further reveals where the highest value is being generated. ADAS and autonomous driving remain the dominant drivers of ISP demand. The need for high dynamic range (HDR), LED flicker mitigation, and low-light performance in safety-critical systems ensures that this segment commands a premium. Viewing cameras, including surround-view and rear-view systems, represent a stable and growing portion of the market, essential for regulatory compliance and basic vehicle functionality. However, a rapidly emerging segment is in-cabin monitoring. As regulations regarding driver monitoring systems (DMS) become stricter, the requirement for ISPs capable of processing interior camera feeds for gesture recognition and vital monitoring is creating a new frontier for growth.
The interplay between these segments is critical for suppliers. A product line that excels in ADAS may not be optimal for in-cabin applications, which have different power and thermal constraints. Our analysis maps these requirements against current product portfolios, helping companies identify gaps in their offerings. We examine how leading architectures are evolving to handle multi-camera inputs and higher resolutions, ensuring that the processing pipeline does not become a bottleneck as sensor technology advances. This section of the report serves as a technical benchmark for evaluating current capabilities against future market needs.
Competitive Landscape and Key Players
The competitive environment in the automotive ISP market is characterized by a mix of established semiconductor giants and specialized innovators. Concentration among the top players is significant, indicating a market where scale, technology leadership, and strategic partnerships dictate market share. The top three companies command a substantial portion of the market revenue, while the top five firms control the majority of the industry's value. This concentration suggests high barriers to entry and the importance of maintaining a robust roadmap to stay relevant.
Key companies shaping this landscape include onsemi, known for their dedicated automotive ISPs optimized for high-performance HDR CMOS image sensors. Their focus on ADAS and surround-view applications positions them strongly in the safety-critical segment. OmniVision Technologies competes aggressively with AI-enabled ASICs and companion processors that integrate NPU capabilities, catering to the growing need for edge intelligence within camera modules. STMicroelectronics continues to leverage its integrated vision and sensor technologies, particularly for ADAS and in-cabin monitoring, benefiting from a broad automotive portfolio.
Texas Instruments and NXP Semiconductors remain pivotal players, with TI supplying essential analog and digital solutions and NXP offering integrated ISPs within their i.MX series processors. Renesas Electronics contributes with vision processors like the V3H series, specifically targeted at ADAS perception. Notably, regional specialists are also making an impact. Nextchip Co., Ltd. in South Korea specializes in ADAS SoCs for L2+ to L3 autonomous driving, while VeriSilicon Microelectronics in China focuses on ISP IP series with rigorous functional safety certifications. Sony Semiconductor Solutions leads in the sensor side with innovations like the IMX828 featuring built-in MIPI A-PHY interfaces, often paired with ISP pipelines. Ambarella and Qualcomm round out the competitive field with computer vision SoCs and Snapdragon platforms that incorporate advanced image processing for connected vehicles.
Understanding the strategies of these players is vital. For instance, VeriSilicon recently achieved ISO 26262 ASIL-B and ASIL-D certifications for their second-generation ISP IP, highlighting the industry's focus on functional safety. Sony's announcement of the IMX828 in late 2025 underscores the trend towards higher bandwidth interfaces and HDR performance. These developments are not isolated; they are indicators of where the market is heading. Our report analyzes the recent activities, product launches, and strategic moves of these key entities to provide a clear picture of the competitive intensity and potential consolidation opportunities.
Industry Dynamics and Regulatory Impact
The operational environment for automotive ISPs is increasingly influenced by external dynamics ranging from supply chain constraints to regulatory mandates. In late 2025 and early 2026, the industry faced notable shifts. Average automotive semiconductor lead times lengthened amid rising demand for vision-related components, putting pressure on supply chain resilience. This lengthening of lead times requires manufacturers to adopt more cautious inventory strategies and strengthen relationships with foundries and packaging suppliers.
Regulatory factors are also reshaping the market. The emphasis on functional safety, exemplified by ISO 26262 certifications, is becoming a prerequisite for participation in high-value ADAS contracts. Components that cannot demonstrate compliance with safety integrity levels are increasingly being excluded from critical systems. Furthermore, geopolitical factors are influencing trade flows. Recent investigations and tariffs involving critical minerals and semiconductor products in the United States introduce potential cost volatility and supply chain rerouting considerations. These factors necessitate a agile approach to sourcing and manufacturing location decisions.
Additionally, broader industry analysis suggests that the complexity of image-signal processors within automotive SoCs is increasing. Driven by the need for AI accelerators and zonal architectures, the semiconductor content per vehicle is rising. This trend aligns with projections that automotive semiconductor demand will continue to grow at a double-digit CAGR through 2030. For ISPs specifically, this means that value is shifting towards solutions that can integrate more functionality, support higher data throughputs, and interface seamlessly with central vehicle computers. Our report evaluates how these dynamics impact pricing power, margin structures, and long-term contract negotiations.
Worldwide Automotive Image Signal Processor Market
Strategic Value for 2026 Decision Making
Why is this research critical for 2026 decision-making? The answer lies in the convergence of timing and technology. Companies entering or expanding in this market in 2026 must align their product development cycles with the rapid adoption curves of ADAS and autonomous features. Decisions made today regarding IP licensing, manufacturing partnerships, or product portfolio focus will determine competitiveness in 2028 and beyond. The data provided in this report allows stakeholders to model various scenarios, assessing risk and opportunity under different adoption rates and regulatory environments.
For investors, the market concentration data and growth projections offer a framework for evaluating potential returns and identifying companies with sustainable competitive advantages. For OEMs and Tier 1 suppliers, the segmentation analysis helps in specifying the right components for different vehicle platforms, balancing cost against performance requirements. For semiconductor manufacturers, the insights into regional demand and product type preferences inform capacity planning and R&D prioritization. The report serves as a single source of truth that aligns these diverse stakeholders around a common understanding of market realities.
Furthermore, the forward-looking nature of the forecast period allows companies to anticipate inflection points. Knowing when certain segments are expected to accelerate enables proactive rather than reactive strategy formulation. Whether it is preparing for the surge in in-cabin monitoring demands or positioning for the next generation of high-pixel-throughput sensors, timing is everything. PW Consulting's analysis removes the ambiguity from these projections, providing a validated basis for budget allocation and strategic planning.
Unlocking Full Market Intelligence
While this overview highlights the significant trends, competitive stakes, and macroeconomic drivers within the Worldwide Automotive Image Signal Processor Market, it represents only a fraction of the intelligence available in our full report. The strategic advantage lies in the details: the specific revenue splits across regions, the granular breakdown of application segments, and the deep-dive profiles of each key company's technology roadmap. To make fully informed decisions, stakeholders need access to the comprehensive data sets that underpin our high-level conclusions.
Our complete market research product offers detailed tables, extensive competitive benchmarking, and scenario-based forecasting that goes beyond the summaries provided here. We invite industry leaders, investors, and strategic planners to access the full Worldwide Automotive Image Signal Processor Market report. By doing so, you will gain the granular intelligence necessary to secure your position in this rapidly evolving sector. Visit our source webpage to download the full executive summary and acquire the detailed market intelligence needed to navigate the automotive semiconductor landscape of 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Image Signal Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com