
Blogs
5-Bromo-2,4-dichloropyrimidine Market: Why 6.31% CAGR Changes Asia Pacific Winners
By pmarketresearch, 2026-09-18
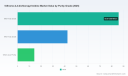
Strategic Trends and Commercial Opportunities in the Global 5-Bromo-2,4-dichloropyrimidine Market
Market Overview and Core Challenges
The global market for 5-Bromo-2,4-dichloropyrimidine has entered a phase of steady structural expansion, driven by its entrenched role as a critical heterocyclic building block in pharmaceutical and fine chemical value chains. Valued at approximately USD 142.5 million in 2025, the market has demonstrated consistent compounding growth since 2020, when it stood at USD 102.34 million. Projections indicate that this upward trajectory will persist through the end of the decade, with the market expected to surpass USD 200 million by 2031 and approach USD 218.69 million by 2032. This expansion translates to a compound annual growth rate of 6.31 percent across the 2026 to 2032 forecast window.
Such growth is neither accidental nor isolated. It reflects a broader industry pattern wherein specialized halogenated pyrimidine intermediates have become indispensable to modern drug discovery and process chemistry. The compound serves as a versatile electrophilic scaffold, enabling nucleophilic substitution and cross-coupling reactions that underpin the synthesis of kinase inhibitors, immunomodulators, and other targeted therapeutics. Parallel to pharmaceutical demand, academic and industrial laboratory research continues to provide a stable baseline of consumption, while niche applications in agrochemical synthesis add incremental volume.
Beneath the headline growth figures, however, the market faces structural friction that will define profitability and supply reliability over the next several years. The first challenge lies in raw material volatility and its downstream impact on pricing discipline. The synthesis of related chlorinated pyrimidine derivatives depends heavily on chlorination agents and precursor heterocycles that have experienced quarterly price swings exceeding 40 percent since 2022. These fluctuations force manufacturers into unpredictable cost structures, compress margins on standardized grades, and complicate long-term contract negotiations with downstream formulators.
The second challenge centers on regulatory classification and logistics complexity. The material is classified for transport as UN3261, a corrosive solid, acidic, organic, n.o.s., falling under Hazard Class 8, Packing Group III under DOT, IATA, and IMDG frameworks. This designation introduces mandatory compliance layers for packaging, labeling, carrier qualification, and cross-border documentation. For manufacturers and distributors operating across multiple jurisdictions, the cumulative administrative and operational burden restricts agility in scaling shipment volumes and increases the cost of market entry for smaller regional players.
A third pressure point is the clustering of commercial activity around a concentrated supplier base. The top three firms account for roughly 42 percent of market share, while the top five capture nearly 59 percent. Such concentration creates an environment where pricing transparency is limited, alternative sourcing paths are narrow, and supply disruptions at a single facility can ripple through downstream pipelines. At the same time, this structure incentivizes incumbents to protect margin by differentiating on purity consistency, documentation quality, and technical support, raising the barrier for new entrants who lack established quality systems or regulatory familiarity.
For business leaders, the implication is clear: the market is growing reliably, but growth alone does not guarantee operational stability or margin preservation. Firms that navigate raw material exposure, transport compliance, and supplier concentration with disciplined sourcing strategies and technical differentiation will be better positioned to convert volume expansion into sustainable commercial advantage.
Key Drivers of Market Change
Several interlocking forces are reshaping how 5-Bromo-2,4-dichloropyrimidine is produced, priced, and deployed across end-use sectors. Understanding these drivers is essential for anticipating where capacity, pricing power, and partnership opportunities will emerge.
Technological Innovation and Process Optimization
Advances in synthetic methodology and scale-up engineering are gradually reshaping the cost and quality profile of the compound. Manufacturers that have invested in continuous or semi-continuous chlorination and bromination pathways are achieving tighter control over impurity profiles, which directly supports the production of higher-purity grades demanded by pharmaceutical clients. At the same time, process intensification efforts are reducing batch-to-batch variability and improving yield reproducibility, which matters greatly for customers running multi-step syntheses where intermediate purity can influence downstream reaction efficiency.
Recent commercial listings and supplier updates illustrate this trajectory. In late 2025, multiple suppliers maintained or expanded offerings emphasizing 99 percent purity thresholds, while others continued to supply the 98 percent grade that remains a workhorse standard for many intermediate applications. The coexistence of these purity tiers reflects a market that is simultaneously optimizing for cost-effective scale and for the stricter analytical specifications required by regulated drug development programs. Suppliers that can reliably bridge both segments, without compromising documentation or lot consistency, are gaining preferential positioning in procurementreviews.
Policy and Regulatory Evolution
The regulatory backdrop is steadily maturing, albeit without introducing abrupt restrictions that would fundamentally constrain trade. In the United States, the compound is listed under the TSCA inventory, providing a recognized pathway for commercial handling and import. Within the European framework, the substance does not currently appear under specific Annex XIV authorization requirements or Annex XVII restrictions under REACH, which reduces immediate compliance friction for EU-facing supply chains. These conditions create a permissive but monitored environment where established manufacturers can operate with predictable regulatory overhead, provided they maintain up-to-date safety documentation and transport classification compliance.
This environment is not static. Updated Safety Data Sheets, such as those refreshed in late 2025 by major distributors, reaffirm the corrosive solid classification and emphasize ongoing commercial availability under hazard-aligned logistics protocols. The practical effect is a market where regulatory clarity supports continuity, but where any future tightening of classification, packaging mandates, or import documentation could quickly alter cost structures. Firms that proactively maintain compliance infrastructure and monitor jurisdictional updates will be better insulated against sudden operational shifts.
Demand-Side Shifts in Pharmaceutical and Research Workflows
Demand dynamics are being reshaped by the broader architecture of modern drug development and fine chemical synthesis. The compound's role as a trisubstituted pyrimidine precursor positions it squarely within the workflow of kinase inhibitor programs and other targeted therapy pipelines, where modular building blocks are repeatedly iterated across lead optimization and process development phases. As these pipelines expand and as development timelines compress, the demand for intermediates that offer predictable reactivity, well-characterized impurity profiles, and reliable lot availability increases correspondingly.
PW Consulting
Beyond drug development, the laboratory research segment continues to serve as a stable demand anchor. Academic groups, contract research organizations, and internal R&D teams rely on the intermediate for exploratory synthesis, method development, and small-scale feasibility studies. While this segment rarely drives the largest volume swings, it contributes to baseline consumption and supports the supply ecosystem that larger commercial buyers depend upon. A third, smaller demand stream emerges from agrochemical synthesis, where the same heterocyclic scaffold supports the construction of active ingredients and formulation intermediates. Though modest in relative size, this segment adds diversification to the demand base and can become more significant if crop protection portfolios expand their use of halogenated pyrimidine chemistry.
2-Amino-5-bromothiazole Monohydrobromide Market
Supply Chain and Cost Structure Dynamics
Cost structures remain highly sensitive to upstream chemical volatility. The dependence on pyrimidine derivatives and chlorination agents means that price swings in basic halogenation inputs propagate rapidly through the value chain. Since 2022, quarterly fluctuations in these inputs have exceeded 40 percent at times, creating an environment where static pricing models quickly become unsustainable. Suppliers have responded by adopting more flexible contract structures, hedging strategies where feasible, and closer integration with precursor suppliers to improve visibility into input availability and cost trends.
Logistics and handling costs form another layer of the supply chain equation. The corrosive solid classification requires specific packaging, carrier training, and documentation workflows that add cost at every transfer point. Companies that standardize these processes, invest in compliant packaging inventories, and maintain relationships with trained logistics partners can reduce per-unit handling premiums. Conversely, organizations that treat transport compliance as an afterthought often encounter delays, rework, and unexpected surcharges that erode margin.
Taken together, these drivers point to a market where competitive advantage is increasingly derived from process reliability, documentation rigor, and supply chain agility rather than from volume alone. Buyers are prioritizing partners who can demonstrate consistent purity, transparent lot records, and the operational capacity to manage regulated transport without disruption. Suppliers that align their capabilities with these expectations are capturing stronger commercial positioning even in a price-sensitive environment.
Competitive Landscape and Leading Strategies
The competitive environment for 5-Bromo-2,4-dichloropyrimidine is characterized by a mix of established fine chemical manufacturers, regional producers with integrated synthesis capabilities, and global scientific suppliers that bridge laboratory-scale and commercial-scale demand. Rather than competing solely on price, leading players differentiate through purity consistency, application-specific documentation, scale flexibility, and technical support that reduces friction for downstream users.
In India, several manufacturers have built commercial positions around the production of the intermediate for pharmaceutical applications. Jay Finechem, headquartered in Gujarat, is known for supplying the compound in powder form with a 98 percent assay, supporting drug development programs for medicines such as Ribociclib, Trilaciclib, and Palbociclib. Simson Pharma and Vandana Chem similarly serve domestic and international clients, emphasizing competitive quality and export-oriented logistics. These Indian-based producers benefit from established fine chemical manufacturing infrastructure, proximity to key precursor supply networks, and growing experience in serving regulated pharmaceutical supply chains. Their strategic positioning tends to center on reliable batch output, assay consistency, and the ability to support both intermediate production and downstream formulator requirements.
Across China, the landscape features manufacturers and suppliers that span research-grade and larger-scale commercial offerings. COLORKEM, based in Zhejiang, offers the compound as a pale yellow liquid pharmaceutical intermediate with content at or above 99 percent, packaged in standard bag sizes for chemical and pharmaceutical applications. BLD Pharmatech, in Shanghai, supplies the material primarily for research and development use in pharmaceutical and fine chemical synthesis, catering to teams that require well-characterized lots for exploratory and scale-up studies. AstaTech (Chengdu) Biopharmaceutical Corp. positions its offering around intermediate applications in nucleophilic substitution and cross-coupling reactions, emphasizing compatibility with trisubstituted pyrimidine synthesis workflows. In late 2025, additional commercial activity appeared from regional producers such as Henan Aochuang Chemical, which indicated supply capability at the ton scale for 98 percent purity material, and Shaanxi Dideu New Materials, which listed 99.0 percent purity material at industrial scale. These listings reflect a market in which Chinese suppliers are actively expanding both purity options and volume capacity to capture demand from cost-conscious development programs and production-scale buyers.
Global scientific distributors add a distinct layer to the competitive field. TCI America, operating under Tokyo Chemical Industry, supplies high-purity material at 97 percent or higher for laboratory and synthesis use across pharmaceutical and agrochemical applications. Thermo Fisher Scientific, including its Alfa Aesar portfolio, provides 98 percent material for chemical synthesis and intermediate applications, supported by broad distribution infrastructure and standardized quality documentation. Sigma-Aldrich, under Merck KGaA, offers 97 percent material as a halogenated pyrimidine intermediate for organic synthesis in pharmaceutical and agrochemical sectors. These firms leverage global reach, established procurement pathways, and strong technical support networks to serve customers who value availability, documentation completeness, and multi-region logistics more than localized price advantages.
Recent operational developments reinforce how these players are adapting. Updated safety documentation from Thermo Fisher Scientific in September 2025 confirmed the transport classification and reaffirmed ongoing commercial availability, signaling that major distributors continue to prioritize compliance clarity alongside supply continuity. Meanwhile, new listings and scale indications from regional producers in 2025 point to growing capacity and an intensifying focus on purity tiers that match specific buyer requirements. This dynamic suggests a market that is gradually bifurcating: one track emphasizing high-purity, well-documented material for regulated pharmaceutical workflows, and another emphasizing cost-competitive, scale-oriented supply for research and intermediate production where specifications are slightly less restrictive.
Strategically, the market concentration pattern reinforces the importance of differentiation. With the top three and top five suppliers holding substantial share, incumbents protect their positions by reducing buyer risk through lot traceability, analytical support, and responsive logistics. New entrants face a challenging path unless they bring clear advantages in purity control, regional proximity, or specialized application support. The most probable evolution in the near term is a combination of consolidation among smaller distributors seeking scale efficiencies and selective fragmentation as regional manufacturers expand capacity to capture demand from specific therapeutic or geographic segments.
For decision-makers evaluating supplier relationships, the practical takeaway is that competitive strength in this market is not measured by catalog breadth alone. It is reflected in the ability to deliver consistent assay results, maintain audit-ready documentation, manage regulated transport without disruption, and support the specific synthetic workflows of downstream users. Suppliers that build these capabilities systematically tend to secure longer-term procurement relationships and greater resilience against pricing pressure.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, the market for 5-Bromo-2,4-dichloropyrimidine is likely to be shaped by three interrelated trends, each carrying distinct commercial implications.
The first trend is a continued drift toward higher and more consistently documented purity tiers for pharmaceutical-facing supply. As drug development programs increasingly rely on well-characterized intermediates to reduce downstream variability and support regulatory submissions, buyers will place greater weight on lot-to-lot reproducibility, analytical certificates, and traceability. Suppliers that standardize high-purity production and can provide robust documentation packages will find expanding opportunities to serve regulated pipelines and command pricing that reflects reduced technical risk for their customers. A related opportunity lies in offering tiered product configurations, allowing buyers to select between 99 percent grades for sensitive synthetic steps and 98 percent grades for cost-sensitive stages without sacrificing quality assurance.
The second trend is the gradual regional rebalancing of supply and demand. Demand from pharmaceutical development and fine chemical synthesis is not uniformly distributed, and procurement teams are increasingly sensitive to lead times, transport compliance costs, and currency exposure. This creates room for regional manufacturers that can offer shorter logistics paths, localized technical support, and flexible batch sizes. At the same time, global scientific distributors will continue to play a crucial role for buyers who require multi-region availability and standardized quality systems. The commercial opportunity here lies in building supply networks that combine regional responsiveness with globally recognized documentation standards, rather than treating proximity and scale as mutually exclusive options.
The third trend involves ongoing sensitivity to input cost volatility and regulatory adaptation. Because precursor chlorination agents and pyrimidine derivatives remain prone to significant quarterly price movement, suppliers and buyers alike will need to adopt more dynamic contracting approaches and maintain deeper visibility into upstream conditions. On the regulatory side, while the current classification and inventory status support stable operations, any future adjustments to hazard packaging requirements, import documentation, or jurisdictional listings could shift cost structures quickly. Firms that invest in compliance readiness, packaging standardization, and proactive monitoring of regulatory updates will be better prepared to absorb such changes without losing service reliability.
The principal risks to watch include sustained input price swings that erode margin predictability, supply disruptions concentrated among a limited number of high-share producers, and potential regulatory changes that increase handling or documentation burdens. These risks do not undermine the market's growth trajectory, but they do raise the importance of portfolio diversification, supplier redundancy, and technical due diligence in procurement decisions.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to convert process reliability into differentiated commercial value. Investing in consistent purity output, robust analytical documentation, and compliant packaging inventories can reduce buyer-perceived risk and support longer-term contracts. Developing flexibility across purity tiers and scale options allows suppliers to serve both research-stage and production-stage customers without compromising quality standards. Where feasible, strengthening visibility into precursor availability and cost trends will improve pricing resilience amid volatile input markets.
Worldwide Bromoacetic Acid Market
For investors evaluating exposure to this segment, the emphasis should be on operational maturity and supply chain positioning rather than on volume growth alone. Suppliers with established quality systems, audit-ready documentation, and diversified customer bases are better equipped to maintain margin stability through input volatility and regulatory adjustments. Capacity expansion that is paired with documentation capability and logistics compliance offers a more durable value proposition than capacity growth in isolation.
For procurement teams and sourcing managers, the most effective approach is to evaluate suppliers on a combination of purity consistency, documentation completeness, transport compliance readiness, and technical support quality. Diversifying across regional and global partners can reduce exposure to single-source disruption while maintaining access to different scale and purity configurations. Establishing clear specification requirements, lot traceability expectations, and compliance documentation standards at the outset of a procurement relationship will reduce friction during scale-up and limit the risk of unexpected handling or logistics costs.
Detailed segmentation data, purity-grade dynamics, regional volume patterns, and company-level strategic profiles can help translate these observations into precise sourcing, investment, and capacity decisions. Readers seeking a deeper breakdown of market splits, competitive benchmarking, and forward-looking scenario analysis are encouraged to review the full study, which provides the granular data and structured frameworks needed to support enterprise-level planning.
For detailed analysis of this topic, please visit the official page: Worldwide 5-Bromo-2,4-dichloropyrimidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Signage Design Services Market: How 7.5% CAGR Redefines Revenue Trajectories to 2032
By pmarketresearch, 2026-09-18
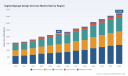
The Digital Signage Design Services Market: Navigating Growth Amid Structural Shifts
Market Overview and Core Challenges
The global digital signage design services market has demonstrated steady expansion over the past five years, growing from approximately $1.57 billion in 2020 to an estimated $2.25 billion in 2025. This trajectory reflects a compound annual growth rate of 7.5 percent, with forecasts projecting further acceleration through 2032 as organizations across sectors increasingly treat in-store and in-facility visual communication as a strategic capability rather than a decorative afterthought. The baseline revenue expansion, when mapped against evolving deployment patterns, points to a market that is maturing but far from saturated at the design and content layer. Hardware commoditization has lowered entry barriers for screen deployment, yet the value capture has progressively shifted toward creative strategy, motion design, interactive architecture, and content management integration—the very service components that determine whether a digital display resonates or simply occupies wall space.
Beneath these headline figures, three structural tensions are reshaping how service providers compete and how buyers evaluate formats. First, the industry is confronting a demographic and talent bottleneck in specialized design labor. A significant share of professional sign designers in developed markets is over fifty years old, intensifying talent scarcity and placing upward pressure on project costs and turnaround times. This demographic reality is colliding with demand for more sophisticated visual storytelling, interactive wayfinding, and multi-screen content orchestration, creating a supply-demand imbalance that favors firms with structured design operations or scalable creative outsourcing models.
Second, regulatory complexity is rising across wireless emissions, data privacy, workplace safety, and accessibility. Deployments that incorporate wireless components must navigate radio-frequency compliance, while interactive screens processing personal data face consent and minimization requirements under privacy frameworks. Workplace and public-facing displays are also subject to visibility and accessibility standards that influence both content placement and system architecture. These obligations are not merely legal checkboxes; they shape design workflows, content governance, and the commercial terms of service engagements, particularly for enterprises operating across multiple jurisdictions.
Third, the market is experiencing a functional split between commodity display installation and differentiated content design. As networks scale into hundreds or thousands of nodes, buyers increasingly expect design services to be tightly coupled with content strategy, template governance, and platform integration. Providers that only deliver visual assets without strategic planning or CMS alignment are seeing margin compression, while those that unify creative, technical, and operational capabilities are capturing more durable engagements. The challenge for decision-makers is distinguishing between providers that can produce compelling visuals and those that can sustain brand consistency, compliance, and performance across entire screen estates.
Key Drivers Shaping Market Dynamics
Technological Innovation and Content Sophistication
A defining driver of current growth is the convergence of advanced display technologies with more capable content creation and management workflows. LED formats, high-brightness outdoor panels, touch-enabled interfaces, and cloud-based CMS platforms have expanded the creative palette, but the real commercial impact comes from how design services translate these capabilities into coherent visual experiences. Providers are increasingly expected to deliver motion graphics, templated content kits, and interactive wayfinding that can be updated at scale without losing brand integrity. The ability to design once and deploy consistently across multiple locations has become a decisive competitive dimension, especially for retail chains, hospitality groups, and large corporate campuses.
Recent industry activity underscores this shift toward design-plus-management offerings. In early 2026, a major retail operator implemented a platform to control digital signage screens across more than 900 stores, integrating content design and centralized management into a single operational workflow. This kind of deployment signals that buyers are no longer purchasing isolated design projects; they are investing in repeatable content systems that reduce localized production burden while maintaining visual quality. As creative teams adopt more modular design approaches—templates, motion libraries, localized variants—the service market is being reshaped around scalability, governance, and rapid iteration rather than one-off bespoke production.
Policy and Regulatory Influence on Design Practice
Regulatory expectations are becoming embedded into design processes rather than treated as post-deployment contingencies. Wireless connectivity requirements, privacy obligations for interactive kiosks, workplace visibility standards, and accessibility guidelines all influence how content is structured, where screens are positioned, and what data flows are permissible. For international operators, the challenge is multiplied by uneven regulatory expectations across regions, which can affect template design, consent mechanisms, and compliance documentation.
This environment favors providers that build compliance into the design stage. Firms that offer ADA-aligned visual considerations, privacy-aware interactive design, and documentation supporting workplace safety visibility can reduce retrofit risk for clients and create stronger differentiation. At the same time, regulatory attention raises the importance of content governance: who can update what, how personalization is handled, and how audit trails are maintained. Design services are therefore evolving from aesthetic production toward governed visual communication systems, a transition that expands the scope of professional engagements and raises the strategic stakes for buyers selecting partners.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are a powerful force behind service demand. In retail and hospitality, customers increasingly expect dynamic, context-aware visuals that support navigation, promotions, and experience design. In corporate and education environments, digital displays serve internal communication, wayfinding, and brand reinforcement functions that must feel consistent with broader identity systems. Healthcare and transportation settings add another layer of complexity, where clarity, accessibility, and real-time information accuracy can directly affect user experience and operational outcomes.
PW Consulting Information & Electronics Research Center
These demand patterns are pushing buyers toward service models that combine strategy, visual design, and platform integration. A display without a content plan tends to underperform, while a well-orchestrated visual system can improve engagement, reduce staff workload, and support localized messaging at scale. The commercial implication is clear: design services are being evaluated less on isolated creative quality and more on their contribution to operational efficiency, brand consistency, and user experience across multiple touchpoints. This is why enterprises are gravitating toward providers with in-house creative teams, reusable content structures, and proven deployment track records.
Supply-Side and Cost Structure Considerations
On the supply side, the maturation of fabrication networks, installation capabilities, and outsourced design models is altering cost structures and delivery models. Large national networks can bundle design, production, and installation, while specialized outsourcing firms offer flexibility for concept development, LED layout planning, and compliance-oriented signage solutions. This combination expands access to design capacity but also increases the importance of vendor management, quality control, and coordination between creative and technical teams.
Labor scarcity and demographic concentration in the design workforce add another layer of cost pressure. As experienced designers retire and demand rises for more complex interactive and multi-screen work, firms that can institutionalize design assets, build reusable libraries, and integrate production with clear technical specifications are better positioned to manage cost and turnaround. For buyers, this means total project economics increasingly depend on how well design services are structured for repeatability and how effectively providers balance creative quality with operational discipline.
Worldwide Product Design Service Market
Competitive Landscape and Leading Strategies
The competitive field is populated by organizations with distinct strategic anchors. Some providers compete through end-to-end capability, pairing in-house creative teams with installation and management services to deliver branded visual experiences across retail and hospitality environments. Others emphasize software-enabled visual communication with dedicated design support, offering custom signage designs, content kits, templates, and interactive wayfinding for enterprise clients. A further cluster of players operates as national or regional production networks, specializing in custom design, fabrication, and installation for menus, directories, promotions, and dynamic displays. Alongside these, architectural and urban integration specialists focus on landmark-scale experiences, while outsourced design firms provide concept development, LED layouts, and compliance-aware signage solutions.
This diversity produces clear differentiation paths. End-to-end providers gain advantage from integrated delivery, where creative, technical, and operational responsibilities are coordinated under one relationship, reducing fragmentation for multi-site clients. Software-centric players leverage repeatable content structures and enterprise visual communication expertise, making them attractive to organizations that need governance across many screens. Production networks differentiate through scale, localized execution, and speed to install, which matters for time-sensitive rollouts or distributed locations. Architectural integrators command premium positioning by linking digital displays to physical environments and experiential design, a niche that can be highly valuable for landmark projects but less applicable to broad-based deployments.
The market is evolving through both consolidation and specialization. Larger operators are expanding service portfolios and partnership networks to cover more of the value chain, while niche specialists deepen expertise in areas such as interactive design, accessibility, or outdoor durability. At the same time, recent partnership activity shows how installation-focused players are layering in custom design integration to strengthen their offerings. For example, a major signage network partnered to support digital signage installations in hospital environments with tailored design integration, illustrating how healthcare deployments are pushing providers to combine technical reliability with context-sensitive creative work.
Strategic positioning is increasingly defined by three questions: can the provider unify design strategy with content management, can it scale creative output without losing consistency, and can it navigate regulatory and accessibility requirements as part of the design process? Firms that answer these convincingly are building moats around recurring content operations rather than one-off projects. Buyers, in turn, are rewarded for selecting partners based on delivery discipline, content governance, and the ability to adapt creative assets across locations and use cases.
Forward-Looking Trends for the Next Three to Five Years
Design-as-a-System Becomes the Standard
Over the next several years, design services are likely to be judged increasingly on systemization rather than isolated creative output. Expect broader adoption of templated motion libraries, localized content variants, and governance frameworks that let enterprises update large screen networks efficiently. This trend will create opportunities for providers that can deliver modular design assets, clear style rules, and integration with CMS platforms, while also increasing the value of partners who can train internal teams and manage content workflows over time.
Interactive and Data-Rich Experiences Will Expand, With Guardrails
Interactive wayfinding, touch-enabled directories, and personalization-enabled displays will continue to grow in high-traffic and service-oriented environments. However, privacy expectations and compliance requirements will shape how these experiences are designed, particularly where personal data is processed. The commercial opportunity lies in building interactive experiences that are compelling without over-collecting data, supported by consent design and transparent data handling. Providers that can balance engagement with compliance will be better positioned for enterprise and public-sector work.
Integration with Physical Environments and Multi-Channel Identity Will Deepen
Digital signage will increasingly be treated as part of a broader environmental and brand identity system, not a standalone medium. Architectural integration, lighting considerations, and coordination with broader communication channels will matter more as deployments seek to reinforce cohesive experiences across spaces. This creates opportunities for specialists who can bridge design, physical installation, and operational planning, but it also raises execution risk where coordination is weak. Projects that treat design, installation, and content management as separable silos are likely to face more rework, inconsistent results, and slower time to value.
Potential risks include talent constraints that slow creative delivery, regulatory changes that add compliance overhead, and price competition in commoditizing segments that pressure margins. Market participants that depend heavily on manual, bespoke workflows may find it harder to scale, while those that invest in reusable assets, structured processes, and integration-ready design will be better equipped to manage volatility.
Strategic Implications for Decision-Makers
For enterprises evaluating digital signage design services, the priority is to define the engagement around content systems rather than individual displays. This means specifying how strategy, visual design, localization, accessibility, and CMS integration will work together before scoping individual projects. Buyers should assess providers on repeatability, governance, and the ability to maintain brand consistency across multiple locations, not only on creative quality in isolation.
For investors and strategic planners, the most durable value appears to be linked to providers that combine creative capability with operational scale and integration-ready workflows. Businesses that can institutionalize design assets, support compliance-by-design practices, and deliver content across distributed networks are more likely to secure recurring engagements. Market observers should watch for consolidation among service providers, deeper partnerships between fabrication/installation networks and creative teams, and growing demand for interactive experiences that meet privacy and accessibility expectations.
For manufacturers and technology suppliers, the opportunity is to support design-led deployments with tools and specifications that make content creation, management, and compliance easier. Clearer technical standards, interoperability with common CMS platforms, and guidance on accessibility and visibility can help reduce friction between creative teams and installation operations. In a market where screens are increasingly commoditized, the differentiator is often how smoothly the surrounding design and management ecosystem functions.
Digital Signage Market
For all of these audiences, the strategic value lies in understanding where the market is heading before committing to large-scale deployments or partnership decisions. Detailed segmentation data, regional dynamics, end-user patterns, and provider-level benchmarks can sharpen planning significantly, especially when aligning investment or procurement choices with the likely trajectory of the market through the end of the decade and into the early 2030s.
For detailed analysis of this topic, please visit the official page: Digital Signage Design Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MMOEXP offers one of the most reliable solutions for purchasing game currency, items,accounts, and more. You can now use the exclusive discount code "east" to enjoy a 8% discount.
EA Sports FC 27 bringt wichtige Änderungen für die Defensive und legt dabei einen stärkeren Fokus auf manuelle Entscheidungen. Für Ultimate-Team-Spieler bedeutet das, dass gutes Stellungsspiel, richtiges Timing und kontrollierte Zweikämpfe noch wichtiger werden. Wer sein Team gezielt verbessern möchte, beschäftigt sich gleichzeitig mit dem Aufbau des Kaders und der effizienten Nutzung von FC 27 Coins .
Die neue defensive Ausrichtung verändert vor allem die Art und Weise, wie Spieler Situationen verteidigen. Automatische Bewegungen sollen weniger Einfluss auf bestimmte Spielsituationen haben, während die eigene Eingabe stärker über den Ausgang eines Zweikampfs entscheidet.
Manuelle Steuerung wird wichtiger
Eine der auffälligsten Änderungen betrifft die manuelle Kontrolle. Spieler müssen ihre Verteidiger genauer positionieren und stärker darauf achten, wann sie einen Zweikampf einleiten. Wer zu früh herausrückt, kann Räume öffnen und dem Gegner einfache Passwege ermöglichen.
Gleichzeitig bietet die manuelle Steuerung mehr Möglichkeiten, Angriffe aktiv zu unterbrechen. Durch geschicktes Wechseln zwischen Verteidigern können Passwege geschlossen und gefährliche Läufe früh erkannt werden. Besonders gegen Spieler, die häufig mit schnellen Richtungswechseln arbeiten, dürfte diese Kontrolle eine größere Rolle spielen.
Auch das Timing beim Tackling gewinnt an Bedeutung. Ein gut getimter Zweikampf kann einen Angriff sofort stoppen, während ein schlecht gesetzter Tackling-Versuch zu einem gefährlichen Konter führen kann.
Stellungsspiel entscheidet über viele Duelle
Die Änderungen machen nicht nur direkte Zweikämpfe wichtiger. Auch die Positionierung vor dem eigentlichen Duell ist entscheidend. Verteidiger sollten möglichst verhindern, dass Angreifer mit viel Tempo in den Strafraum kommen.
Spieler müssen deshalb lernen, Geduld zu bewahren. Statt ständig auf den Ball zu gehen, kann es effektiver sein, den Laufweg des Gegners zu kontrollieren und auf einen Fehler zu warten. Diese Herangehensweise verlangt mehr Aufmerksamkeit, kann aber gleichzeitig für stabilere Defensivaktionen sorgen.
Auswirkungen auf Ultimate Team
Die neuen Verteidigungsmechaniken können auch die Kaderplanung in Ultimate Team beeinflussen. Attribute wie Tempo, Defensivwerte, Physis und Beweglichkeit bleiben wichtig, doch die Fähigkeiten des Spielers am Controller gewinnen zusätzlich an Bedeutung.
Das könnte dazu führen, dass bestimmte Verteidiger je nach Spielstil unterschiedlich eingesetzt werden. Ein schneller Innenverteidiger kann beispielsweise besser geeignet sein, wenn die eigene Taktik eine hohe Abwehrlinie nutzt. Defensivstarke Spieler mit guter Positionierung können dagegen in kompakteren Systemen besonders nützlich sein.
Belohnungen gezielt nutzen
Neben den Gameplay-Änderungen bleiben Belohnungen ein wichtiger Bestandteil von FC 27. Durch Ziele, Saisonfortschritt und verschiedene Ultimate-Team-Aktivitäten können Spieler Packs, Spieler und weitere Ressourcen erhalten.
Wer seine Belohnungen sinnvoll einsetzt, kann seinen Kader Schritt für Schritt verbessern, ohne unnötige Ressourcen auszugeben. Gleichzeitig lohnt es sich, vor jeder Investition die eigenen Schwachstellen zu analysieren.
Fazit
Die Verteidigungsänderungen in FC 27 belohnen eine aktivere und bewusstere Spielweise. Manuelle Steuerung, gutes Stellungsspiel und präzises Timing werden wichtiger und können einen deutlichen Unterschied in engen Partien machen. Wer seinen Kader zusätzlich effizient aufbauen möchte, kann die Handelsplattform MMOExp nutzen. Mit dem Rabattcode „east“ erhalten Spieler dort 8 % Rabatt. Wer gezielt Ressourcen für den Aufbau seines Teams benötigt, kann sich auch über die Möglichkeit informieren, FC 27 Coins kaufen zu können.
Prostaglandins Market: Why 5.24% CAGR and Ophthalmology Demand Reshape 2032
By pmarketresearch, 2026-09-18
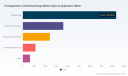
Strategic Trends and Commercial Opportunities in the Global Prostaglandins and Related Drugs Market
Market Overview and Core Challenges
The global market for prostaglandins and related drugs has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately $12.45 billion in 2020 to an estimated $16.17 billion in 2025. This trajectory reflects a compound annual growth rate of 5.24 percent through 2032, signaling a maturing yet still dynamic therapeutic segment. The market’s resilience stems from its entrenched role in managing chronic conditions where prostaglandin-based mechanisms deliver measurable clinical outcomes. Revenue generation is broadly distributed across advanced economies and emerging regions, with North America and Europe collectively accounting for a significant share of total sales, while Asia Pacific continues to capture incremental growth driven by expanding healthcare access and localized manufacturing capacity.
Despite the favorable top-line momentum, the industry faces structural headwinds that will shape competitive positioning in the coming years. First, the proliferation of generic alternatives following the patent expirations of major branded prostaglandin analogs between 2010 and 2020 has fundamentally altered pricing dynamics. While this has improved patient access and broadened prescription volumes, it has simultaneously compressed margins for originator manufacturers and intensified the need for cost-efficient production models. Second, the segment is experiencing heightened scrutiny around supply chain resilience, particularly for active pharmaceutical ingredients where synthesis complexity and regulatory compliance requirements create bottlenecks. Third, reimbursement pressures are reshaping commercial strategies, as evidence from historical spending data shows a shift in payer behavior—from a period where branded products dominated utilization to an environment where formulary restrictions and cost-containment policies demand clearer value differentiation.
Prostaglandin Market
For executives and investors, these dynamics point to a market where scale, intellectual property strategy, and manufacturing agility will separate long-term winners from passive participants. The growth trajectory remains intact, but capturing value now requires navigating a landscape where clinical differentiation, regulatory navigation, and supply chain integration matter as much as therapeutic efficacy.
Key Drivers of Market Evolution
Technological Innovation and Formulation Breakthroughs
Advancements in drug delivery and molecule engineering are redefining how prostaglandin therapies are administered and experienced by patients. The introduction of sustained-release formats, such as intracameral implants, illustrates a broader shift toward reducing treatment burden and improving adherence in chronic conditions like glaucoma. Regulatory milestones have validated these approaches, with approvals expanding the clinical utility of established molecular classes into new administration routes and patient populations. Beyond ophthalmology, the extension of prostaglandin-based therapies into areas like severe frostbite management demonstrates how legacy molecules can find renewed relevance when paired with innovative delivery mechanisms or new clinical indications. These developments create commercial pathways for companies that can successfully integrate formulation science with clinical evidence generation.
Regulatory Environment and Policy Dynamics
The regulatory landscape continues to shape market entry, pricing, and competitive intensity. Approval timelines and label expansions directly influence the commercial lifespan of branded products and the pace at which generics can capture market share. Recent regulatory actions have underscored a dual trend: agencies are encouraging therapeutic innovation through expedited pathways for unmet needs, while simultaneously maintaining rigorous standards that reward high-quality manufacturing and comprehensive clinical data. For manufacturers, this environment rewards early investment in regulatory strategy, robust quality systems, and proactive engagement with evolving safety and efficacy expectations. Policy shifts around formulary management and reimbursement benchmarks further incentivize companies to articulate clear value propositions that align with payer priorities.
Demand-Side Shifts and Clinical Utilization Patterns
Clinical demand is being reshaped by demographic trends and evolving treatment paradigms. The growing prevalence of chronic conditions requiring long-term prostaglandin therapy, particularly in ophthalmology and cardiovascular care, sustains baseline demand while creating opportunities for differentiated products that address adherence, tolerability, or convenience. At the same time, healthcare providers and payers are increasingly focused on total cost of care, favoring therapies that reduce follow-up burden, minimize adverse effects, or simplify administration. This behavior shift encourages manufacturers to invest in real-world evidence, patient support programs, and hybrid delivery models that align with the practical realities of chronic disease management. In parallel, emerging markets are expanding their healthcare footprints, creating incremental demand for both branded and generic prostaglandin products as diagnostic capacity and treatment access improve.
Supply Chain Dynamics and Cost Structure Pressures
The cost and reliability of prostaglandin manufacturing remain central to competitive positioning. Synthesis complexity, stringent quality requirements, and the need for specialized infrastructure create barriers that favor companies with vertically integrated or strategically partnered production capabilities. Recent capacity expansion announcements highlight how leading manufacturers are responding to anticipated demand growth by investing in dedicated facilities, process optimization, and regional production footprints. These investments are not merely scale plays; they are strategic hedges against supply disruptions, regulatory delays, and margin erosion from price competition. For buyers and downstream partners, this trend signals a market where supply reliability and quality consistency will increasingly influence sourcing decisions, particularly as demand for both branded and generic formulations continues to expand across therapeutic areas.
Competitive Landscape and Leading Strategies
The competitive ecosystem for prostaglandins and related drugs blends large global pharmaceutical companies with specialized active pharmaceutical ingredient manufacturers and generic-focused producers. Each group occupies a distinct strategic position, and the interplay between them is reshaping how value is created and captured across the supply chain.
Large multinational firms maintain strong commercial presence in high-value therapeutic areas, particularly ophthalmology, where prostaglandin analogs are well established for intraocular pressure management. These companies leverage extensive commercial infrastructure, established physician relationships, and brand recognition to sustain market relevance even as generic alternatives proliferate. Their differentiation often rests on formulation optimization, delivery device innovation, and integrated patient support ecosystems. Some also extend their reach through complementary portfolio acquisitions or division-level focus, ensuring that established molecules remain commercially viable through lifecycle management and combination strategies.
Specialized API manufacturers occupy a critical position in the value chain, particularly where synthesis complexity and regulatory rigor create meaningful barriers. Companies that have invested in fully integrated production sites or possess complete prostaglandin portfolios are positioned to serve both branded and generic customers with greater supply reliability and cost predictability. Strategic capacity expansion in regions that offer manufacturing efficiency and regulatory alignment reflects a long-term bet on sustained demand growth and the need for resilient sourcing. For these players, the value proposition is built on technical capability, production scale, and the ability to support downstream formulation partners with consistent quality.
Generic manufacturers have expanded access and intensified price competition, particularly following the wave of patent expirations that opened the market to multiple alternatives. Their strategy centers on regulatory agility, cost-efficient production, and the ability to launch equivalents across multiple dosage forms and markets. Recent approvals of generic prostaglandin ophthalmic solutions illustrate how generic entrants continue to broaden therapeutic access while reinforcing the importance of manufacturing quality and supply consistency in a crowded field. These companies often compete on distribution reach, formulary positioning, and operational efficiency, making them essential participants in the market’s overall growth dynamics.
Regional and mid-sized producers, including specialized firms in Asia and Europe, add further depth to the competitive landscape by focusing on intermediates, niche formulations, and local market requirements. Their presence supports broader supply diversification and can provide downstream partners with flexible sourcing options. At the same time, the market is showing signs of gradual consolidation pressure, as scale advantages in manufacturing, regulatory compliance, and commercial reach become increasingly valuable. New entrants face a steep path unless they bring clear differentiation—whether through novel delivery technologies, unique molecular variants, or highly specialized manufacturing expertise.
For decision-makers, the key takeaway is that competitive advantage in this market is no longer defined by a single molecule or therapy area. It is increasingly determined by the ability to integrate clinical differentiation, manufacturing reliability, regulatory foresight, and commercial execution into a coherent strategy. Companies that can align these elements will be best positioned to defend share in mature segments while capturing growth in evolving applications.
Future Trends and Strategic Outlook
Over the next three to five years, the prostaglandins and related drugs market is likely to be shaped by three reinforcing trends. First, formulation and delivery innovation will continue to create commercial differentiation, especially in chronic therapy areas where adherence and treatment burden are persistent challenges. Sustained-release systems, alternative administration routes, and device-drug combinations are expected to gain further traction as clinical evidence and payer acceptance mature. These advances open opportunities for companies that can demonstrate tangible improvements in patient outcomes and total cost of care.
Second, supply chain localization and capacity investment will become more prominent as manufacturers seek to reduce dependency on concentrated production networks and mitigate regulatory or logistical disruptions. Expect continued capital deployment in dedicated facilities, process intensification, and regional manufacturing footprints designed to support both branded and generic demand. This trend will reward suppliers that can offer predictable quality, scalable capacity, and transparent compliance records.
Third, pricing and reimbursement dynamics will keep pressure on undifferentiated products while rewarding therapies with clear clinical or economic value. As health systems refine formulary strategies and emphasize cost-effectiveness, the market will increasingly separate products that compete primarily on price from those that can justify positioning through superior delivery, tolerability, or evidence-based value arguments. This environment will favor strategic portfolio management, lifecycle planning, and early engagement with payer and provider stakeholders.
Potential uncertainties include the pace of new indication approvals, the trajectory of generic penetration in key markets, and the impact of regulatory changes on manufacturing requirements and launch timelines. Macroeconomic factors affecting raw material costs, capital availability, and healthcare spending patterns may also influence investment timing and margin expectations. Companies that monitor these variables closely and maintain flexible strategic plans will be better equipped to navigate shifts in demand and competitive intensity.
Decision-Maker Action Recommendations
For manufacturers, the priority is to strengthen the foundation that supports both margin defense and growth capture. Invest in formulation and delivery capabilities that differentiate offerings beyond molecule identity, and align manufacturing strategy with long-term demand signals rather than short-term volume fluctuations. Companies that can combine supply reliability with clear clinical or practical value will have greater leverage in formulary negotiations and partnership discussions.
For investors, focus on organizations that demonstrate durable competitive advantages in API production, regulatory execution, and commercial reach within prostaglandin-related therapy areas. Evaluate exposure to segments where generic pressure is balanced by differentiated delivery, where regional demand growth is supported by healthcare expansion, and where supply chain resilience translates into more predictable revenue streams. Portfolio positioning should account for both the steady-growth core and the higher-upside potential of novel delivery or expanded indications.
For procurement and sourcing leaders, evaluate suppliers not only on unit cost but on quality consistency, capacity visibility, and regulatory standing. In a market where price competition is intense and supply interruptions can carry significant clinical and commercial consequences, multi-source strategies and supplier qualification rigor can reduce risk while supporting continuity of care. Early engagement with manufacturers that are expanding capacity or modernizing production can also improve long-term negotiating positioning.
Worldwide Carboprost Tromethamine Market
Given the pace of regulatory change, generic entry dynamics, and evolving demand patterns, access to timely and granular market intelligence is essential for informed decision-making. Detailed segmentation data, company-level tracking, and scenario-based forecasts can help organizations refine strategy, anticipate competitive moves, and identify the most relevant opportunities across regions and therapeutic applications. For those seeking a deeper, structured view of the market’s trajectory and strategic implications, the full PW Consulting research report provides the detailed breakdowns and customized analysis needed to support execution at the operational and portfolio level.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Prostaglandins and Related Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Landscape Rock Market: 5.45% CAGR Fuels Reshaping Competition
By pmarketresearch, 2026-09-18
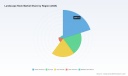
Global Landscape Rock Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide landscape rock market has established itself as a resilient component of the broader landscaping and construction materials sector. Valued at approximately 4,333 million USD in 2020, the market expanded to an estimated 5,650 million USD by 2025, reflecting consistent growth across diverse geographic and application segments. Forward projections indicate the market will reach 8,191 million USD by 2032, supported by a compound annual growth rate of 5.45 percent over the 2026–2032 forecast horizon. This trajectory underscores sustained demand for natural and processed stone materials in outdoor design, infrastructure development, and recreational space creation.
From a structural standpoint, the market exhibits moderate fragmentation. The top three companies collectively account for roughly 12.5 percent of total revenue, while the top five hold approximately 18.2 percent. Such concentration levels suggest that while major players maintain meaningful market share, the landscape remains open to specialized operators, regional distributors, and niche product innovators. The revenue distribution across regions reflects a mature base in North America, complemented by steady demand across Europe and the Asia Pacific, alongside emerging opportunities in Latin America and the Middle East and Africa. Application-wise, residential landscaping continues to represent the largest demand driver, followed by commercial infrastructure and public parks and recreational facilities. By product type, crushed granite and stone, river rock, lava rock, and boulders and decorative stones each serve distinct aesthetic and functional requirements across these end-use segments.
Despite the constructive growth outlook, the industry faces several structural challenges that will shape competitive dynamics over the coming years. First, environmental scrutiny and regulatory tightening around quarrying operations, land reclamation, and water usage are increasingly influencing site approvals and operational costs. Companies must navigate evolving local and state requirements while maintaining supply continuity, which can compress margins and delay expansion timelines. Second, the market's reliance on natural stone extraction creates inherent supply constraints. Geological availability, transportation logistics, and quarry permitting cycles introduce volatility in lead times and pricing, particularly for specialty or imported stone varieties. Third, the residential landscaping segment, while dominant, is sensitive to macroeconomic cycles, housing market fluctuations, and discretionary spending patterns. Shifts in consumer confidence or interest rate environments can quickly alter project pacing and material procurement behavior, requiring suppliers and distributors to maintain flexible inventory and pricing strategies.
These challenges are not insurmountable, but they demand proactive strategic positioning. Operators that invest in sustainable extraction practices, diversify product portfolios, and strengthen downstream distribution capabilities are better equipped to absorb regulatory and demand-side shocks. At the same time, the moderate concentration of the market leaves room for consolidation, partnership models, and targeted acquisitions that can enhance scale, geographic reach, and product differentiation.
Key Demand Drivers and Structural Shifts
Several interconnected forces are reshaping the landscape rock market, creating both pressure and opportunity for stakeholders across the value chain. Understanding these drivers is essential for anticipating where growth will concentrate and which capabilities will differentiate leaders from laggards.
Technological Innovation and Product Differentiation
Advances in crushing, screening, and finishing technologies have expanded the range of available stone profiles, enabling more consistent sizing, improved surface textures, and tailored color variations. Producers are increasingly leveraging precision processing to offer specialized aggregates that meet aesthetic and functional specifications for hardscaping, pool deck surrounds, vertical masonry, and decorative ground cover. In parallel, the adoption of eco-friendly extraction techniques and sustainable quarrying practices is gaining traction among natural stone producers seeking to minimize environmental impact while aligning with buyer expectations for responsibly sourced materials. These innovations are not merely operational improvements; they are becoming competitive differentiators that influence procurement decisions among landscape contractors, designers, and retail distributors.
A notable illustration of this trend is the introduction of premium imported natural stone lines designed for hardscape, pool deck, and vertical masonry applications. Such launches signal a broader industry movement toward higher-margin, design-forward product categories that cater to upscale residential and commercial projects. By emphasizing imported specialty stones and curated finishes, suppliers are capturing demand from buyers who prioritize visual appeal, durability, and project-specific performance over commodity-grade alternatives.
Policy and Regulatory Environment
Regulatory frameworks governing quarry operations, reclamation obligations, and water usage continue to evolve, particularly in regions where residential and commercial development intersect with environmentally sensitive areas. Aggregates and landscape materials face local and state requirements that shape permitting timelines, operational boundaries, and post-extraction land management. Companies that proactively integrate compliance into their operational planning—through responsible site design, water conservation measures, and reclamation commitments—can reduce approval friction and build stronger relationships with regulators and community stakeholders.
At the same time, the growing emphasis on sustainable sourcing is influencing procurement standards among larger contractors and commercial developers. Buyers are increasingly requesting documentation on extraction practices, environmental stewardship, and supply chain transparency. This shift is encouraging producers to adopt more formalized sustainability reporting and to differentiate their offerings based on responsible sourcing credentials, which can become a decisive factor in competitive bids and long-term supply agreements.
Demand-Side Behavior and End-Use Evolution
Consumer and enterprise behavior is shifting toward outdoor spaces that serve multiple functions: aesthetic enhancement, recreational use, and durable hardscaping. Residential landscaping remains the largest application driver, supported by home improvement activity, curb appeal investments, and the popularity of low-maintenance outdoor design. Commercial infrastructure demand is also sustained by urban redevelopment, hospitality projects, and mixed-use developments that incorporate landscaped courtyards, pedestrian pathways, and decorative stone elements. Public parks and recreational facilities contribute additional volume, particularly where municipalities invest in trail systems, green spaces, and community amenities.
Limestone Market
Within this demand environment, buyers are placing greater emphasis on coverage efficiency, material consistency, and installation practicality. For example, landscape rock ground cover is commonly evaluated by square footage coverage at specified depths, while cobble or rubble stone is assessed by coverage per ton. These practical considerations influence product selection and pricing sensitivity, encouraging suppliers to provide clear specifications and reliable volume guidance. The result is a market where technical performance and aesthetic value are increasingly intertwined, and where distributors that can articulate usage parameters gain an edge in customer conversations.
Supply Chain and Cost Structure Dynamics
Supply chain considerations are becoming more prominent as operators manage quarry output, transportation constraints, and inventory positioning across regional markets. North America remains a major market for landscape rock, supported by significant domestic quarrying in the United States and selective imports of specialty stones. This dual structure allows suppliers to balance cost efficiency with product variety, but it also requires careful coordination between extraction schedules, logistics capacity, and downstream fulfillment.
Cost structures are influenced by energy inputs, equipment maintenance, labor availability, and site-specific extraction conditions. In response, several operators are pursuing capacity expansion and operational optimization to improve throughput and reduce unit costs. Recent planning approvals for expanded quarry operations illustrate how companies are seeking to scale production footprints to meet projected demand while improving supply reliability. Such expansion decisions are often driven by the expectation that stronger demand visibility and improved operational scale will support margin stability through the forecast period.
Industry performance signals also point to cautious optimism among aggregates and stone operators. Steady performance in core operations, combined with positive outlooks for the near term, suggests that many producers are navigating current conditions with disciplined cost management and selective investment. This environment favors companies that can align capacity plans with demand signals, maintain inventory flexibility, and respond quickly to regional procurement shifts.
Worldwide Natural Stone Market
Competitive Landscape and Leading Strategies
The competitive landscape of the landscape rock market is characterized by a mix of global aggregates leaders, regional stone specialists, and focused decorative product suppliers. This diversity creates multiple pathways to competitive advantage, depending on whether a company competes on scale, product specialization, geographic coverage, or design-oriented branding.
PW Consulting
Global aggregates leaders such as Holcim, CRH plc, Vulcan Materials Company, Martin Marietta, and Heidelberg Materials bring extensive production capabilities, broad distribution networks, and deep experience in crushed stone and landscape rock supply for construction and landscaping projects. Their scale enables them to serve large commercial infrastructure programs, maintain consistent output across multiple regions, and invest in processing infrastructure that supports a wide range of product grades. For these companies, differentiation often comes from supply reliability, standard product breadth, and the ability to integrate landscape rock offerings within broader aggregates and building materials portfolios.
Regional and specialty players occupy a different strategic space. Companies such as Aggregates International, Polycor Inc., Kafka Granite LLC, RCP Block & Brick, Inc., Techo-Bloc, Yardco Rock & Stone, Euro Quarries, Minick Materials, Basalite Concrete Products, and Boral Limited compete by emphasizing curated decorative aggregates, natural stone quarrying expertise, hardscape product integration, and nationwide or regional delivery capabilities. Their portfolios often include pebbles, chippings, rockery, decomposed granite, flagstone, and complementary concrete or pavers, allowing them to address design-sensitive residential and commercial projects with a more tailored value proposition. For these operators, differentiation is frequently built on product variety, aesthetic positioning, sourcing flexibility, and service responsiveness.
Recent market developments highlight how companies are executing on these strategic paths. The launch of premium imported natural stone lines for hardscape, pool deck, and vertical masonry applications reflects a deliberate move toward higher-value product categories that align with upscale project requirements. At the same time, capacity expansion initiatives, such as planning approvals to significantly increase quarry acreage, demonstrate efforts to strengthen production scale and supply resilience. Alongside these moves, steady operational performance and constructive near-term outlooks among aggregates and stone operators indicate that disciplined execution remains central to navigating demand variability and cost pressures.
The market structure is evolving along several trends. Consolidation is likely to continue where larger players seek to expand regional coverage, acquire specialized product lines, or integrate downstream distribution. At the same time, fragmentation will persist in segments where local sourcing, decorative specialization, and customer intimacy matter most. New entrants and expanding distributors can gain traction by focusing on underserved geographies, importing distinctive stone varieties, or combining landscape rock with complementary hardscape products. The net effect is a competitive environment where scale and specialization are not mutually exclusive; rather, successful companies often blend both by operating efficient core production while cultivating differentiated product and service offerings.
Future Trends and Strategic Implications
Looking ahead over the next three to five years, several trends are likely to shape the direction of the landscape rock market and inform where commercial opportunities will emerge.
One key trend is the continued expansion of design-forward and specialty stone categories. As residential and commercial projects place greater emphasis on outdoor aesthetics, durable hardscaping, and multi-functional recreational spaces, demand for curated finishes, imported varieties, and application-specific products is expected to grow. This creates opportunities for suppliers that can reliably source, process, and distribute distinctive materials while providing clear guidance on coverage, installation, and performance. Companies that invest in product education, specification support, and visual merchandising will be better positioned to capture higher-margin demand.
A second trend is the increasing importance of sustainable sourcing and regulatory readiness as competitive factors. Buyers, contractors, and municipal purchasers are likely to place greater weight on responsible extraction practices, environmental documentation, and long-term site stewardship. Operators that formalize sustainability credentials, adopt eco-friendly extraction techniques, and maintain strong compliance records can use these attributes to strengthen bids, build customer trust, and reduce regulatory risk. This trend also favors partnerships and supply chain transparency, as downstream buyers seek assurance across the sourcing-to-delivery chain.
A third trend is the ongoing alignment of capacity and distribution with regional demand patterns. As housing activity, commercial development, and public space investment fluctuate across markets, suppliers will need to balance production scale with inventory agility. Capacity expansions that improve throughput and reduce lead times can strengthen market position, but they must be paired with demand forecasting and logistics coordination to avoid oversupply or underutilized assets. In this environment, companies that develop flexible distribution models, regional stock positioning, and responsive customer service will be more resilient to localized demand shifts.
These trends carry potential risks and uncertainties. Regulatory changes can alter permitting timelines and operating costs, particularly in areas where quarry expansion intersects with community or environmental concerns. Macroeconomic conditions may affect discretionary residential spending and the pace of commercial construction, creating variability in order flow. Supply disruptions, transportation constraints, and shifts in energy or input costs can also pressure margins. Companies should therefore treat growth planning as conditional on scenario awareness, maintaining flexibility in capacity commitments, product mix, and pricing strategy.
Actionable Guidance for Decision-Makers
For manufacturers and producers, the priority is to align processing capability and product breadth with the growing demand for specialty and design-oriented stone categories. Investing in finishing consistency, curated color and texture options, and clear usage specifications can help capture higher-value demand while supporting customer installation success. At the same time, strengthening sustainable sourcing practices and compliance documentation will increasingly serve as a baseline expectation rather than a differentiator alone.
For investors, the market's moderate concentration and diverse competitive pathways suggest value in evaluating both scaled aggregates operators and specialized decorative stone suppliers. Due diligence should focus on geographic exposure, capacity expansion plans, product mix toward higher-margin categories, and the ability to manage regulatory and supply chain risk. Companies with disciplined cost structures, flexible distribution, and credible sustainability positioning are likely to be better prepared for demand variability and evolving buyer standards.
For procurement teams and distributors, the emphasis should be on supplier reliability, specification clarity, and inventory responsiveness. Understanding coverage parameters, material consistency, and regional availability can reduce project risk and improve customer outcomes. Building relationships with suppliers that offer both dependable core products and distinctive specialty lines can provide a balanced portfolio that serves a wider range of residential, commercial, and public-sector projects.
Given the number of moving parts across regulation, demand cycles, product innovation, and competitive consolidation, timely access to detailed segment data, regional breakdowns, and company-level benchmarking can materially improve planning quality. For decision-makers seeking deeper segmentation, granular regional insights, and customized strategic recommendations, the full PW Consulting research report provides the supporting detail needed to translate these market-level trends into specific investment, sourcing, and growth decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Landscape Rock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Commercial Encryption Products Market: Why 13.5% CAGR and 15B Scale Redefine Security Strategy by 2032
By pmarketresearch, 2026-09-18
The Commercial Encryption Products Market: Strategic Trends and Commercial Opportunities
The commercial encryption products market has evolved from a niche cybersecurity concern into a foundational layer of digital infrastructure. By 2025, the market has reached an estimated 6.5 billion USD in revenue, with consistent compound annual growth of 13.5 percent projected through 2032. Over the five-year historical window from 2020 to 2025, revenue expanded by nearly 87 percent, reflecting a structural shift rather than a temporary surge. The trajectory ahead points to continued acceleration, with forecasts suggesting the market will exceed 15.7 billion USD by the end of the forecast period. This growth is not evenly distributed across product types or sectors, but the overall magnitude signals that encryption has moved from compliance-driven procurement to strategic investment.
Several characteristics define the current market landscape. The ecosystem remains moderately concentrated, with the top three players capturing roughly a third of total revenue and the top five accounting for just under 43 percent. This concentration leaves substantial room for specialization, regional differentiation, and niche innovation, particularly in segments where performance, assurance, and integration matter more than price. At the same time, the market faces a pivot point driven by certification transitions, quantum readiness expectations, and the growing mismatch between legacy architectures and cloud-native workloads.
Hardware Encryption Devices Market
Key Challenges and Inflection Points
One of the most consequential challenges is the regulatory transition from FIPS 140-2 to FIPS 140-3. The formal move of FIPS 140-2 certificates to a historical list in September 2026 forces commercial encryption products and the systems that embed them to adopt validated modules under the newer standard. For vendors, this is not a simple recertification exercise; it requires re-architecting validation footprints, aligning engineering roadmaps, and addressing procurement cycles that may stall until compliance is confirmed. For buyers, the risk is procurement inertia: legacy deployments that were once acceptable may face audit exposure or sourcing constraints, while new projects must specify FIPS 140-3 from the outset.
A second inflection point is the post-quantum cryptography transition. NIST finalized post-quantum standards in 2024, and CISA published product categories to support adoption in commercial technologies in early 2026. The market is not yet in full implementation mode, but the direction of travel is clear: organizations are beginning to inventory cryptographic dependencies, assess migration paths, and evaluate vendor roadmaps. The challenge is twofold. First, the technical complexity of hybrid deployments and crypto-agility introduces integration risk. Second, the absence of mature commercial tooling and testing frameworks means early movers must navigate uncertainty around interoperability, performance, and total cost of ownership.
A third challenge lies in workload dispersion. Encryption is no longer confined to perimeter networks or on-premises storage. Data protection requirements now span distributed cloud environments, hybrid identity architectures, edge devices, and payment ecosystems that must balance assurance with latency and throughput. Suppliers that cannot offer scalable key management, integration with cloud services, and modular assurance profiles will find themselves squeezed by both performance requirements and procurement expectations. The markets leading players are responding with certification breadth, cloud-optimized hardware, and software-centric data protection, but the structural tension between assurance depth and deployment agility remains unresolved.
Key Drivers Shaping Market Momentum
Market growth is being propelled by a convergence of technical, regulatory, and demand-side forces. The most visible driver is cryptographic assurance modernization. The shift toward FIPS 140-3 and the emergence of post-quantum standards are reshaping specification language and procurement requirements. Recent vendor activity makes this acceleration tangible. Utimaco achieved FIPS 140-3 Level 3 certification for its u.trust GP HSM Se-Series in May 2026, positioning the company as the only vendor with full FIPS 140-3 coverage across general-purpose and payment HSM portfolios. In December 2025, Thales secured NATO Secret classification for its Luna Network HSM 7 alongside FIPS 140-3 Level 3 validation. These milestones illustrate how high-assurance certification is becoming a competitive differentiator, especially in environments where data sensitivity spans commercial, government, and defense-adjacent use cases.
Demand-side behavior is changing in parallel. Enterprise data protection strategies are shifting from perimeter-based controls to pervasive, identity-aware encryption integrated with broader data security platforms. Regulatory exposure in financial services, healthcare, and public-sector operations continues to raise the baseline for key management and data-at-rest protection. At the same time, business leaders are pressing for faster deployment cycles, cloud-native integration, and reduced operational friction. The result is a market that values not only cryptographic strength but also manageability. Certification becomes a proxy for trust, and trust becomes a procurement gate.
Supply-side dynamics are increasingly shaped by cloud adoption and partnership models. Hardware security modules are no longer treated as standalone appliances in every context. Cloud-optimized HSM families are being selected to support managed cloud HSM services, extending encryption capabilities into elastic environments while maintaining key isolation. Marvell's LiquidSecurity HSM family, chosen by Microsoft for Azure Cloud HSM services in August 2025, reflects this pattern. The broader implication is that encryption infrastructure is being embedded into platform ecosystems, not simply layered as an independent product. For commercial encryption providers, this opens opportunities in integration design, attestation, and managed key services, but it also requires tighter alignment with cloud vendor roadmaps and operational expectations.
Emerging Influences Across the Ecosystem
Three additional dynamics are reinforcing these drivers. First, crypto-agility is moving from a technical aspiration to a procurement criterion. Buyers are increasingly interested in architectures that can adapt to evolving algorithms without wholesale replacement, especially as post-quantum migrations are planned. Second, product certification breadth is expanding beyond traditional enterprise and financial use cases into IoT and connectivity domains. The April 2026 announcement of FIPS 140-3 validation for cryptographic modules on Digi Accelerated Linux-based IoT and connectivity solutions signals that assurance requirements are reaching edge and embedded environments where security has historically been harder to standardize. Third, geopolitical and sector-specific assurance needs are creating differentiated demand. Classification achievements such as NATO Secret for select HSM products illustrate that high-assurance commercial encryption can unlock adjacent markets where data sensitivity and supply-chain trust are paramount.
PW Consulting Information & Electronics Research Center
Together, these drivers are pushing the market toward a more layered structure: certified hardware for high-assurance root operations, software and platform capabilities for data protection and key lifecycle management, and cloud-integrated services for scalability. Growth will be determined not only by how many organizations buy encryption products, but by how many can absorb them into workflows without compromising performance, compliance, or operational continuity.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a handful of established players with strong certification portfolios and a growing emphasis on integration with enterprise and cloud ecosystems. Thales Group maintains a broad commercial encryption and key management position through Luna Network HSMs, payShield payment HSMs, and CipherTrust data security solutions, with recent validation activity reinforcing its high-assurance credentials. Utimaco has concentrated on full-portfolio FIPS 140-3 coverage across general-purpose and payment HSMs, a differentiating posture in markets where procurement teams want a single, consistently validated vendor footprint. Entrust continues to anchor its commercial position in nShield HSMs for key protection, code signing, and enterprise encryption, appealing to organizations that value high-assurance key use cases within broader identity and data protection strategies.
Homomorphic Encryption Market
Futurex occupies a manufacturing-centric positioning with FIPS 140-2 Level 3 and PCI HSM validated products produced in the United States, an advantage in contexts where supply-chain provenance and domestic manufacturing are evaluation factors. IBM brings encryption software, Guardium data protection, and HSM offerings into the enterprise commercial data protection conversation, leveraging platform adjacencies and data security integration. Microsoft competes in a different layer of the stack, with Azure Key Vault and encryption services that incorporate HSM-backed key management for cloud data protection, effectively embedding encryption into a broader cloud platform. Marvell contributes cloud-optimized HSMs, notably through its selection for Azure Cloud HSM services, aligning hardware capability with hyperscale deployment requirements.
Strategic Positioning and Differentiation
Across these players, differentiation is emerging along several axes. Certification scope is one of the most visible. Vendors that can demonstrate consistent FIPS 140-3 validation, payment HSM validation, or elevated classification may secure preference in regulated environments where audit confidence is directly tied to specification language. Product breadth is another axis: players offering both general-purpose and payment HSMs, or hardware combined with software data protection, can address multiple procurement categories within a single relationship. Integration capability is becoming equally important. The ability to connect key management to cloud services, enterprise identity, and data security platforms reduces operational friction and strengthens the value proposition beyond raw cryptographic assurance.
Manufacturing origin and supply-chain narrative also matter in specific segments. Domestic manufacturing, transparent validation histories, and clear product category alignment can influence procurement decisions in government-adjacent, critical infrastructure, and payment environments. At the same time, cloud-native deployments are rewarding providers that can offer modular, scalable hardware or managed services that fit into elastic architectures rather than rigid appliance models.
Structural Evolution in the Market
The market is likely to evolve through both consolidation and niche differentiation. Larger platforms with broad data security, identity, and cloud ecosystems may expand their encryption footprint through product integration or selected partnerships. At the same time, specialized vendors with focused certification portfolios, strong payment or HSM credentials, and clear supply-chain value can thrive by serving high-assurance segments that are less price-elastic. New entrants are unlikely to displace incumbents through pure scale, but they may carve out positions in specific use cases such as cloud-optimized key services, modular assurance for hybrid deployments, or crypto-agility tooling that simplifies transition planning. The real contest will be over specification influence: vendors that help buyers translate compliance requirements into operational architectures will shape demand more than those that compete solely on feature parity.
Future Trends to Watch
Over the next three to five years, three trends are likely to shape the commercial encryption market most directly. First, FIPS 140-3 compliance will become a default procurement baseline rather than a differentiator, and the competitive advantage will shift toward breadth, speed of validation, and the ability to support hybrid and cloud-native deployments. Vendors with completed portfolios and clear migration support will gain preference in regulated sectors, while late movers risk exclusion from specification lists.
Second, post-quantum readiness will move from policy direction to operational planning. Migration inventories, crypto-agility architectures, and hybrid key management approaches will increasingly appear in enterprise and public-sector roadmaps. Commercial opportunity will emerge for providers that can simplify transition paths, support hybrid modes, and offer clear documentation and testing for algorithm flexibility. The associated risk is fragmentation: without common deployment patterns or interoperability expectations, early implementations may require expensive integration work and create vendor lock-in concerns.
Third, encryption will continue to converge with platform services. Managed cloud HSM, integrated key protection, and data security platforms will become the primary consumption model for a growing share of commercial workloads. This trend favors players that can embed security into workflows and reduce operational overhead, but it also raises questions about long-term control of cryptographic assets, audit visibility, and portability across environments. The opportunity lies in architectures that preserve assurance while making protection easier to consume; the risk lies in over-reliance on opaque or tightly coupled services that complicate governance.
Strategic Actions for Decision-Makers
For manufacturers and product vendors, the near-term priority is to align certification roadmaps with procurement reality. Completing FIPS 140-3 validation, clarifying payment and general-purpose coverage, and communicating migration support can influence specification outcomes in regulated demand channels. Vendors should also invest in integration and cloud compatibility, because assurance alone is unlikely to win deals where operational fit is weak. Differentiation should be expressed through portfolio consistency, deployment flexibility, and clear guidance for post-quantum transition planning.
For investors and strategic partners, the most informative signals are certification milestones, ecosystem partnerships, and evidence of adoption in cloud or platform services. Companies that combine validated hardware with usable key management and data protection integration are better positioned to capture recurring commercial demand than those competing primarily on price. Portfolio exposure should be assessed not only by product footprint but by the ability to serve regulated, high-assurance, and cloud-scale segments simultaneously.
For procurement and security leaders, the practical move is to treat encryption as a lifecycle decision rather than a point purchase. Early specification of FIPS 140-3 requirements, evaluation of crypto-agility options, and review of vendor support for post-quantum transition planning will reduce downstream risk. Buyers should also assess integration fit with existing cloud, identity, and data security environments to avoid new operational bottlenecks. Where demand is complex or region-specific, detailed segment intelligence can shorten evaluation cycles and improve specification accuracy. The broader market dynamics, segment differentiation, and vendor-level developments can be explored in depth through a complete market study that provides the detailed segmentation, competitive tracking, and scenario-based guidance needed for tailored planning.
For detailed analysis of this topic, please visit the official page: Commercial Encryption Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tonsil Cancer Treatment Market: Why the $996M Base & 6.42% CAGR Upend Strategy
By pmarketresearch, 2026-09-18
Tonsil Cancer Treatment Market: Strategic Shifts & Commercial Opportunities (2025-2032)
The Current Market Landscape and Core Challenges
The global market for tonsil cancer treatment is undergoing a significant structural transformation, driven by evolving therapeutic paradigms, shifting demographic patterns, and a maturing pharmaceutical ecosystem. Valued at approximately 1,000 million USD in the 2025 base year, the market has demonstrated consistent expansion, with historical growth trajectories reflecting increased diagnostic awareness, refined staging protocols, and broader access to advanced oncology interventions. Forecasts indicate sustained momentum through the end of the decade, supported by a steady compound annual growth rate and clear upward trajectory in total revenue. The market’s expansion is not merely a function of population growth or incidence rates; it reflects a fundamental recalibration of how oropharyngeal and tonsil malignancies are approached clinically, commercially, and financially.
Beneath these aggregate figures, several structural tensions are reshaping competitive priorities. First, pricing resilience and reimbursement uncertainty remain central concerns across most mature healthcare systems. Oncology portfolios increasingly rely on on-patent therapies that command premium pricing, yet the lifecycle economics of pharmaceutical products are well understood by payers and health technology assessment bodies. Once patent protection expires, generic and biosimilar entrants typically trigger rapid price compression, and procurement frameworks are increasingly designed to steer utilization toward lower-cost alternatives through tiered cost-sharing mechanisms. For manufacturers and care providers alike, this creates a narrow window to demonstrate differentiated clinical value, secure formulary positioning, and build durable reimbursement narratives before margin erosion accelerates.
Second, the regulatory and trade environment has introduced new supply chain and operational contingencies. Recent policy shifts have altered how pharmaceutical imports are evaluated, particularly for branded and patented products. Manufacturers without active domestic production commitments face heightened cost exposure and potential access friction in certain key markets. This development is prompting strategic reassessment of manufacturing footprints, logistics planning, and portfolio localization strategies, especially for companies whose tonsil cancer or broader head and neck oncology offerings depend on cross-border supply networks.
Third, clinical adoption pathways are becoming more nuanced as treatment algorithms move beyond one-size-fits-all cytotoxic regimens. The convergence of immunotherapy, targeted biologics, and conditionally active antibody-drug conjugates is changing the standard of care conversation, but integration into real-world clinical practice depends on biomarker stratification, multidisciplinary coordination, and institutional readiness. Healthcare systems and specialty centers must navigate the balance between innovation adoption and operational feasibility, particularly when newer modalities require specialized administration, monitoring, or patient selection criteria.
Collectively, these dynamics define a market that is expanding, but not uniformly. Growth is increasingly concentrated among players who can align product development with reimbursement strategy, adapt supply chain architectures to policy volatility, and support clinical adoption with robust evidence generation. The competitive battlefield is shifting from simple therapeutic availability toward value demonstration, access optimization, and integration readiness.
Key Drivers Shaping Market Trajectory
Several interlocking forces are accelerating change within the tonsil cancer treatment landscape. Understanding their interaction is essential for anticipating where commercial value will accumulate and which capabilities will separate resilient organizations from reactive ones.
Therapeutic Innovation and Biomarker-Aligned Oncology
The most consequential driver is the ongoing evolution of treatment architecture for head and neck malignancies, including tonsil and oropharyngeal disease. Immunotherapy has established itself as a core pillar in recurrent, metastatic, and increasingly perioperative contexts. Rather than replacing established modalities, the prevailing model is one of integration: checkpoint inhibitors and targeted biologics are being positioned alongside surgery, radiation, and chemotherapy in ways that aim to improve outcomes while moderating toxicity. This shift is particularly relevant in HPV-associated disease, where biological characteristics create opportunities for more selective targeting and refined patient stratification.
Recent regulatory milestones have reinforced this direction. The approval of pembrolizumab for perioperative use in resectable locally advanced head and neck squamous cell carcinoma, including PD-L1-positive tumors, marked a meaningful expansion of immunotherapy utility beyond later-stage settings. The therapeutic relevance extends to tonsil cancer where disease biology and staging overlap substantially with broader oropharyngeal indications. Simultaneously, conditionally active biologics and antibody-drug conjugates are advancing through late-stage development with a focus on HPV-positive populations. Alignment between developers and regulators on pivotal trial design indicates growing confidence in differentiated mechanisms of action, particularly where conventional treatment pathways leave residual unmet need.
PW Consulting
This innovation trajectory changes the commercial calculus in two ways. First, it raises the importance of companion diagnostics, biomarker testing infrastructure, and pathology workflow integration. Second, it increases the premium on clinical evidence that goes beyond median endpoints to address durability, quality of life, and toxicity management, all of which influence formulary decisions and provider adoption.
Policy, Regulation, and Access Frameworks
Regulatory and reimbursement dynamics are not merely compliance considerations; they are strategic determinants of market access and revenue durability. The 2025 approval expansion for perioperative immunotherapy underscored how regulatory decisions can reshape treatment intent, moving certain modalities earlier in the care continuum and altering competitive positioning across therapy classes. At the same time, the broader pricing environment emphasizes lifecycle management. Payers are increasingly attentive to value demonstration, and procurement structures are designed to encourage substitution when exclusivity lapses. This creates pressure on manufacturers to plan for the full product arc, including post-patent positioning, differentiated formulations, and combination strategies that may extend commercial relevance.
Trade policy adds another layer of complexity. Import-related measures that affect branded and patented pharmaceutical products can alter landed costs, supply continuity, and market entry timing. Companies with significant exposure to cross-border distribution are being forced to evaluate whether localized production, regional stocking strategies, or alternative sourcing models are warranted. This is especially salient for players whose tonsil cancer portfolios intersect with broader head and neck oncology franchises and whose manufacturing decisions affect multiple indications simultaneously.
Demand-Side Evolution in Care Delivery
Patient and provider behavior is shifting as clinical education improves and multidisciplinary care models mature. Awareness of HPV-associated oropharyngeal disease has increased attention to early presentation, staging accuracy, and risk stratification. At the same time, treatment decisions are increasingly made by coordinated teams rather than single-specialty decision makers. This favors therapies that fit cleanly into established surgical, radiation, and medical oncology workflows while minimizing disruption to patient throughput.
Demand is also being shaped by expectations around tolerability and functional outcomes. In cancers affecting the head and neck region, treatment burden can have pronounced effects on swallowing, speech, nutrition, and overall quality of life. Interventions that can preserve efficacy while reducing acute or long-term toxicity gain traction not only in clinical discussions but also in patient preference and provider referral patterns. Consequently, the market increasingly rewards solutions that couple clinical performance with manageable administration and supportive care integration.
Cost Structures and Competitive Realities
Cost dynamics are being redefined by several factors: the concentration of spending on newer on-patent therapies, the operational costs associated with advanced treatment administration, and the financial pressure on care sites to manage episode-related resource use. Hospital settings continue to represent the largest end-user segment, reflecting the complexity of surgical and multidisciplinary management. Specialty clinics and ambulatory surgical centers play a growing role where treatment pathways allow for shorter recovery times, streamlined administration, or outpatient-compatible protocols.
Mapping below outlines the core drivers and their commercial implications.
Worldwide Canine Mammary Tumor Treatment Market
- Therapeutic innovation : Expands addressable use cases, increases reliance on biomarker infrastructure, and raises evidence standards for adoption.
- Regulatory and reimbursement shifts : Accelerates earlier-line integration for some modalities, intensifies lifecycle pricing pressure, and strengthens the need for differentiated value narratives.
- Demand-side behavior : Favors multidisciplinary compatibility, tolerability, and functional outcomes, influencing referral patterns and site selection.
- Cost and supply dynamics : Encourages manufacturing localization, portfolio resilience planning, and reimbursement-aligned procurement strategies.
Competitive Landscape and Leading Strategies
The competitive environment in tonsil cancer treatment is defined by a mix of large oncology franchises, targeted biotech developers, and supportive-care participants, all operating within a moderately concentrated market. A handful of firms account for a substantial share of revenues, and CR3 and CR5 concentration indicators reflect the structural advantage held by companies with established immunotherapy platforms, broad commercialization capabilities, and integrated oncology portfolios. Concentration does not imply stagnation, however. In fact, the current phase is characterized by deliberate differentiation, where scale is necessary but not sufficient, and where pipeline novelty, regulatory timing, and access strategy increasingly determine relative positioning.
Among the most prominent participants, Merck & Co. has reinforced its position through a high-profile regulatory milestone for perioperative pembrolizumab in resectable locally advanced head and neck squamous cell carcinoma, including PD-L1-positive disease. The move is strategically significant because it broadens the immunotherapy conversation earlier in the treatment journey, where patient populations are larger and clinical decision-making is more highly coordinated. This positioning supports the company’s broader oncology narrative by demonstrating applicability across the care continuum rather than restricting relevance to later-line settings.
Bristol Myers Squibb continues to leverage nivolumab as an established immunotherapy option for recurrent and metastatic disease. Its strategic advantage lies in clinical familiarity, integration within existing treatment algorithms, and the durability of evidence built over prior adoption cycles. In a market where provider comfort and institutional protocols influence prescribing, such entrenched positioning can serve as a stable foundation even as newer modalities emerge.
Eli Lilly and AstraZeneca contribute distinct value propositions within the broader head and neck oncology ecosystem. Lilly’s involvement spans supportive agents and pipeline candidates relevant to squamous cell carcinomas, reflecting an interest in both direct treatment and the surrounding care architecture. AstraZeneca’s emphasis on durvalumab and combination-oriented research illustrates the industry’s appetite for regimen-level innovation, where the opportunity is not simply a single agent but a coordinated therapeutic sequence or combination that may improve outcomes in defined patient subsets.
Roche’s cetuximab remains relevant in combination with radiation or chemotherapy for advanced disease, including oropharyngeal cases. Its continued role reflects the persistence of targeted anti-EGFR strategies in selected settings and the practical reality that established biologics can retain clinical utility even as the innovation frontier advances. Sanofi’s oncology portfolio elements and supportive care contributions similarly underscore the importance of surrounding therapies that help manage complex cases and improve treatment tolerability.
The most notable competitive shift, however, comes from specialized developers pursuing biologically selective approaches. BioAtla’s conditionally active antibody-drug conjugate is advancing toward pivotal development in HPV-positive oropharyngeal disease, with regulatory alignment supporting potential accelerated pathways. This type of asset is strategically important because it targets a biologically defined subgroup and represents a move toward conditional activity design, where therapeutic action is intended to be more selective in the tumor environment. If clinical outcomes confirm the promise of such approaches, the commercial impact could include tighter biomarker-linked adoption, new partnering dynamics, and heightened value assessment requirements from payers and providers alike.
PDS Biotechnology’s HPV-focused clinical program reflects a parallel trend: vaccine-based and immune-priming strategies aimed at populations with viral-driven disease biology. This approach complements the broader momentum around HPV-associated oropharyngeal cancers and signals continued interest in modalities that address etiology as well as tumor burden. The presence of such programs in the competitive landscape suggests that future differentiation will increasingly depend on biology-driven targeting and regimen-level evidence rather than class-level presence alone.
Several structural trends are shaping how this landscape evolves.
- Integration over isolation : Companies that can position therapies within multidisciplinary pathways, including surgery, radiation, and supportive care, are likely to gain stronger adoption footholds.
- Biomarker-driven segmentation : HPV status, PD-L1 expression, and other molecular markers are becoming central to treatment selection, raising the stakes for diagnostic partnerships and evidence generation.
- Lifecycle and access planning : As exclusivity timelines shape pricing trajectories, leaders are preparing for generic and biosimilar pressure by building differentiated indications, combination strategies, and access narratives early.
- Manufacturing and geopolitical readiness : Trade and import-related contingencies are pushing firms to evaluate domestic production options and supply chain resilience as part of commercial strategy, not just operational logistics.
- Clinical trial leadership as influence : Academic and clinical centers that shape pivotal studies can influence adoption standards, guideline inclusion, and the credibility of new regimens, which indirectly affects competitive outcomes.
The competitive field is therefore moving toward a hybrid structure: large players maintain scale, breadth, and established relationships, while focused innovators compete on biological precision, trial design, and potential accelerated regulatory pathways. Over time, the most successful organizations will likely be those that can combine scientific differentiation with reimbursement fluency and real-world implementation support.
Future Trends and Market Outlook (2026–2032)
Looking ahead, three trends are likely to shape the next phase of market development. The first is the continued migration of immunotherapy and targeted modalities into earlier lines of care where clinically appropriate. This does not eliminate surgery, radiation, or chemotherapy; rather, it reframes them within more personalized sequences. For commercial players, this trend expands the scope of strategic planning beyond late-stage rescue therapy and into perioperative and consolidation contexts, where patient volume, treatment duration, and combination economics can be materially different.
Cancer Treatment Drugs Market
The second trend is the growing importance of biomarker and diagnostic ecosystems. As therapeutic selection becomes more dependent on HPV status, PD-L1 expression, and potentially other molecular features, the value of reliable testing, clear reporting, and coordinated pathology workflows will increase. This creates opportunities not only for diagnostic providers and companion test developers, but also for therapy manufacturers that can demonstrate how biomarker-guided use improves outcomes, reduces unnecessary toxicity, and strengthens reimbursement justification. Organizations that treat diagnosis as an integral part of the commercial model, rather than a separate transaction, will be better positioned to secure durable adoption.
The third trend is institutional adaptation to cost, access, and supply pressures. Healthcare systems and specialty sites will continue to optimize care delivery around tolerability, throughput, and total episode cost. At the same time, manufacturers will need to manage lifecycle risk more explicitly, anticipating biosimilar and generic entry, trade-related cost impacts, and the need for localized or regionally resilient supply. The likely outcome is a market in which financial and operational resilience become as important as clinical innovation. Products and programs that can navigate access complexity, support site-level efficiency, and maintain continuity under policy volatility will have a structural advantage.
Potential risks and uncertainties remain. Clinical development in biomarker-selected populations can be promising but also fragile, with regulatory and reimbursement outcomes depending on the strength and generalizability of trial results. Pricing pressure may intensify if healthcare budgets face renewed constraints or if payers become more assertive in value-based contracting. Trade and manufacturing policy could also create uneven access conditions across regions, complicating global launch strategies and potentially favoring companies with more flexible operational footprints. Finally, the pace of guideline adoption and multidisciplinary integration may vary by setting, meaning that the same clinical advancement can translate into different commercial outcomes depending on local care infrastructure.
Strategic Implications for Decision Makers
For executives and investors navigating this market, several priorities stand out.
For Manufacturers and Developers
Invest in biomarker-aligned development and evidence generation that supports earlier-line use where appropriate. Build reimbursement narratives that connect clinical differentiation with real-world value, including toxicity reduction, functional outcomes, and treatment sequencing. Evaluate manufacturing and supply chain localization proactively, particularly if portfolio exposure crosses multiple oncology indications and import-related cost risks are material.
For Investors
Focus on assets and companies with clear biomarker strategy, strong regulatory alignment, and credible lifecycle plans. Differentiate between broad franchise stability and innovation-driven optionality; both can be valuable, but they carry different risk profiles. Pay attention to supply chain readiness and access positioning, since commercial success increasingly depends on execution beyond clinical efficacy alone.
For Procurement and Care Providers
Prioritize therapies and service models that integrate efficiently into multidisciplinary workflows, support predictable utilization patterns, and align with site-level cost management. Build internal capability for biomarker-informed decision-making and evaluate total episode impact rather than unit price in isolation. Where possible, align contracting strategies with anticipated lifecycle changes, including the transition from branded exclusivity to lower-cost alternatives.
The tonsil cancer treatment market is expanding within a landscape defined by therapeutic innovation, biomarker-driven segmentation, access complexity, and supply-side recalibration. Organizations that understand these interconnections will be better equipped to allocate capital, shape pipelines, and plan for the commercial realities of the next several years. For teams seeking deeper segmentation data, company-level profiling, and tailored scenario planning across regions and therapy classes, detailed research resources are available for further exploration.
For detailed analysis of this topic, please visit the official page: Worldwide Tonsil Cancer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Scar Treatment Supplies Market: Why 10% CAGR and 48.95 Billion in 2032 Matter
By pmarketresearch, 2026-09-18
Worldwide Scar Treatment Supplies Market: Strategic Trends and Commercial Opportunities
1. Market Landscape and Core Challenges
The worldwide market for scar treatment supplies has demonstrated sustained expansion over the past five years, reaching an estimated valuation of approximately 25.1 billion USD in the base year 2025. Historical trajectories from 2020 through 2025 reveal a consistent upward climb, reflecting growing clinical acceptance and broader consumer awareness of scar management solutions. Forward projections for the period 2026 to 2032 indicate that this momentum will continue, with the sector anticipated to approach 49 billion USD by the end of the forecast window. This evolution corresponds to a compound annual growth rate of roughly 10.0 percent, signaling a mature yet still accelerating demand environment. The scale and velocity of growth suggest that scar care has transitioned from a niche wound care adjunct to a distinct commercial category with its own supply chains, regulatory pathways, and competitive dynamics.
Scar Tape Market
Despite the favorable headline numbers, the industry is navigating a set of structural challenges that will shape competitive outcomes over the next several years. The first challenge lies in the fragmentation of product classifications and quality expectations across regions. Medical-grade silicone sheets, hydrogels, topical gels, compression garments, and adhesive tapes each occupy different regulatory and clinical positioning, which complicates market entry, manufacturing standardization, and cross-border distribution. Companies must balance the need for broad product portfolios against the operational burden of maintaining consistent quality and documentation across multiple device categories and therapeutic claims.
A second challenge stems from the tension between clinical efficacy and consumer accessibility. Scar treatment supplies serve a dual audience: healthcare professionals managing post-surgical, burn, and trauma outcomes, and consumers seeking non-invasive options for aesthetic or comfort-related concerns. This duality creates divergent purchasing behaviors, price sensitivities, and expectations around evidence. Suppliers that rely primarily on clinical credibility may find growth constrained if they cannot translate that credibility into user-friendly packaging, clear usage instructions, and retail or e-commerce visibility. Conversely, products positioned primarily for convenience risk scrutiny if clinical differentiation is perceived as thin.
A third challenge is the pressure on margin structures as the market matures. With a meaningful portion of revenue concentrated among a limited number of established players, smaller manufacturers and new entrants face rising costs for materials, regulatory compliance, and channel access. At the same time, larger organizations are increasingly looking to consolidate capabilities, streamline product lines, and push for value-based pricing. The result is a market where scale, regulatory fluency, and brand trust increasingly determine who can protect profitability while still expanding share.
2. Key Drivers of Market Change
Technological innovation remains one of the most powerful forces reshaping scar treatment supplies. Advances in silicone formulation, adhesion engineering, and barrier performance have improved the practical usability of sheets and gels, making them easier to apply, more comfortable for extended wear, and more reliable across different skin types and scar ages. Products that combine occlusion and hydration in a way that supports flattening, softening, and fading of raised scars have become central to both prophylactic and treatment-oriented use. The broader shift toward medical-grade materials that can be used on new and older scars—from surgery, burns, and trauma—has expanded the addressable use cases and encouraged product refinement rather than simple commodity competition.
Scar Treatment Market
Regulatory and policy dynamics are also acting as a major driver, particularly as classification expectations tighten in key markets. In the United States, silicone gel sheeting and hydrogel products for scar management are commonly regulated as Class I medical devices, with many products exempt from premarket notification but still subject to establishment registration and general controls. This framework lowers the procedural barrier for certain entrants while still demanding disciplined quality systems. In the European Union, the environment has moved toward more rigorous conformity assessment for a subset of scar and wound care products, with select gel and wound care items achieving Class IIb medical device certification under the Medical Device Regulation. Such developments elevate the importance of regulatory readiness, post-market surveillance, and documented safety and performance, especially for companies seeking to scale across multiple jurisdictions.
Demand-side change is accelerating the market as well. Clinicians and patients increasingly view scar management as a standard part of post-procedure care rather than an optional afterthought, especially following surgical interventions, burn recovery, and trauma-related healing. At the same time, the consumer side of the market is becoming more informed and more proactive, with growing interest in non-invasive options that can reduce itch, discomfort, and visible prominence. This dual demand expansion is pushing suppliers to develop offerings that satisfy professional procurement requirements while remaining accessible enough for direct-to-consumer and retail channels. The result is a broader product spectrum, from physician-exclusive lines to over-the-counter topical solutions, each targeting a different point in the care journey.
Supply chain and cost considerations are exerting a more subtle but persistent influence. Manufacturers of silicone sheets, gels, compression garments, and adhesive tapes must manage material availability, production consistency, and packaging requirements while responding to shifting channel expectations. The growing emphasis on branded and locally distributed portfolios has encouraged some companies to invest in manufacturing reliability and formulation consistency as differentiators, rather than competing primarily on price. At the same time, operations that can align procurement, regulatory documentation, and distribution logistics are better positioned to withstand volatility and maintain service levels for both clinical and consumer customers.
3. Competitive Landscape and Leading Strategies
The competitive field in scar treatment supplies is defined by a mix of established multinational players and specialized manufacturers, each pursuing a distinct route to differentiation. Several large organizations anchor their positions through well-known silicone sheeting and gel products designed for the management of hypertrophic and keloid scars. Smith & Nephew, for example, emphasizes self-adhesive silicone gel sheets intended to soften, flatten, and fade new and old red or raised scars arising from surgery, burns, and trauma. Mölnlycke Health Care takes a related but technically distinct approach with self-adherent soft silicone dressings built around a proprietary skin-friendly adhesive concept, supporting both prevention and treatment on old and new scars, including prophylactic use on closed wounds. These product narratives highlight how incumbents use clinical familiarity, application convenience, and prophylactic positioning to reinforce repeat usage and professional trust.
Specialist manufacturers are competing by sharpening the technical story around their materials. Bio Med Sciences focuses on silicone-based scar management products that incorporate a patented technology blending silicone with Teflon-like properties, offering adhesive gel sheets in clear, fabric, and foam variants for the prevention and reduction of hypertrophic and keloid scars. Biodermis and Newmedical Technology similarly concentrate on silicone-based sheets and gels for post-surgical and trauma-related scar reduction, while Enaltus markets a widely recognized silicone gel for topical treatment aimed at reducing the appearance of raised scars. This concentration on material science and application specificity allows smaller firms to compete on perceived performance and clinical fit rather than scale alone.
Other participants are expanding the therapeutic palette beyond traditional silicone sheeting. Sonoma Pharmaceuticals has built a presence around hypochlorous acid-based scar gels that aim to manage scars by reducing itch, pain, and appearance while supporting wound healing. Perrigo and Merz Pharmaceuticals contribute to the broader topical and dermatology-oriented side of the category, with Perrigo focusing on over-the-counter and branded scar treatment offerings through its portfolio, and Merz positioning topical scar solutions within a wider dermatology context for aesthetic and medical management. Scar Heal, operating under a physician-focused brand identity, offers silicone scar gels and sheets including exclusive lines for scar refinement. Together, these players illustrate a market where differentiation is being built through both material-based claims and broader care-pathway positioning.
Recent regulatory activity underscores how competitive positioning is increasingly tied to compliance capability as well as product performance. Sonoma Pharmaceuticals, for instance, completed the transition of its Epicyn scar gel and related items to EU Medical Device Regulation Class IIb certification for wound care, scar, and atopic dermatitis treatments in late 2024. Moves like this signal thatEU market access and credibility can depend on more advanced conformity assessment for certain product types, which in turn affects who can scale efficiently in that region. At the same time, the generally lighter regulatory pathway for many silicone hydrogel and gel sheeting products under FDA product codes continues to support a diverse set of entrants in the U.S., even as establishment registration and general controls remain baseline expectations.
PW Consulting
Looking at the broader evolution of the landscape, consolidation and portfolio rationalization appear likely to intensify. Larger organizations may pursue acquisitions or internal streamlining to reduce overlap, strengthen channel access, and build more coherent brand architectures across medical and consumer segments. At the same time, fragmentation is likely to persist in specialized niches where formulation, adhesion properties, comfort, and physician relationships create defensible positions. New entrants will probably continue to appear, but their success will increasingly depend on regulatory readiness, evidence-backed claims, and the ability to distribute through channels that match their target audience. The market is therefore moving toward a pattern where scale, compliance, and brand trust reinforce one another rather than operating as separate competitive dimensions.
4. Future Trends and Commercial Implications
Over the next three to five years, one likely trend is the continued sharpening of product differentiation around material performance and user experience. As clinicians and consumers compare options more systematically, products that offer easier application, better adhesion control, improved comfort over longer wear periods, and consistent outcomes across scar types will gain advantage. This creates commercial opportunities for manufacturers that invest in formulation refinement, packaging that supports adherence, and clear guidance for both prophylactic and treatment use. It also raises the stakes for suppliers whose products are perceived as interchangeable, since price competition alone is unlikely to sustain margins in a growing but increasingly discerning market.
A second trend is the deepening of regulatory stratification across regions and product types. While some categories will continue to benefit from lighter premarket requirements, others will face more demanding conformity, documentation, and post-market expectations. This uneven landscape creates opportunities for companies that build regulatory competence as a core capability rather than a back-office function. Firms that can navigate device classification, maintain robust quality systems, and adapt product claims to local expectations will be better positioned to expand internationally and to present themselves as lower-risk partners for distributors and clinical buyers. The unpredictability lies in how quickly regulators may adjust expectations and how consistently those adjustments are applied across product variants.
A third trend is the growth of hybrid distribution models that blend professional channels with consumer access. As scar care becomes more embedded in post-procedure routines and more visible in retail and online channels, companies will need to manage the tension between clinical credibility and consumer convenience. This opens opportunities for portfolios that are structured by use case—prophylaxis after surgery or trauma, management of hypertrophic and keloid scars, and consumer-focused topical solutions—while preserving consistent quality standards. The risk is brand dilution or channel conflict if product lines are not clearly differentiated by audience, evidence level, and intended use. Companies that can maintain disciplined segmentation while still reaching multiple purchasing paths are more likely to capture growth without eroding trust.
5. Strategic Options for Decision-Makers
Manufacturers should treat regulatory readiness, material consistency, and channel fit as interconnected priorities rather than isolated functions. Investing in formulation and adhesion performance can support differentiation, but that advantage only translates into share if the product is positioned clearly for its intended use and supported by documentation that matches the expectations of the markets served. Companies expanding across regions may benefit from sequencing their regulatory strategy, prioritizing markets where their product classification and quality systems align most naturally with local requirements before scaling into more demanding environments.
For investors, the key question is whether a company’s growth is backed by defensible differentiation or by broadly commoditized supply. Businesses with strong formulation expertise, recognizable clinical use narratives, and the ability to meet evolving device-classification expectations are better placed to sustain margins as the market expands. Caution is warranted where expansion depends mainly on volume without corresponding improvements in compliance, brand trust, or channel access, since these are the areas where competitive pressure is most likely to compress returns.
For procurement and supply chain leaders, the priority is to balance availability, quality assurance, and category fit when selecting suppliers. Evaluating manufacturers on the basis of regulatory status, product consistency, and suitability for specific scar types and care settings can reduce risk while supporting better outcomes. It also helps to structure sourcing around clearly defined use cases, so that procurement decisions reflect whether the need is prophylaxis, ongoing management of raised scars, or consumer-oriented topical support.
For organizations that need a more granular view of segment dynamics, regional splits, and company-level positioning, a detailed research report can provide the segmentation breakdowns, competitive profiles, and scenario analysis needed to translate these strategic themes into specific plans. The broader market trajectory suggests that those who act early on regulatory preparation, product differentiation, and channel strategy will be better placed to capture the next phase of growth in scar treatment supplies.
For detailed analysis of this topic, please visit the official page: Worldwide Scar Treatment Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Educational and Training Software Market: Why 15.12% CAGR Reshapes Strategy
By pmarketresearch, 2026-09-18
Navigating the EdTech Inflection Point: Strategic Trends in the Educational and Training Software Market
Market Landscape and Core Challenges
The global educational and training software market has firmly entered a phase of accelerated expansion. Revenue climbed from approximately 175.4 billion USD in 2020 to 355.6 billion USD by 2025, reflecting sustained institutional adoption and shifting learning paradigms. Projections indicate the market will continue compounding at a 15.12 percent CAGR through 2032, reaching an estimated 952.84 billion USD. This trajectory is not merely a post-pandemic normalization but a structural reallocation of how organizations invest in knowledge delivery, skill development, and academic infrastructure.
Cloud-based deployment has become the dominant architecture, reflecting broader enterprise preferences for scalability, remote accessibility, and reduced on-premise maintenance overhead. The sector is broadly distributed across K-12 education, higher education, and corporate training, with each segment driving distinct procurement cycles, compliance requirements, and user experience expectations. In terms of application, learning management systems, student information systems, assessment and testing software, and content creation and simulation tools occupy significant portions of the value chain. Geographic adoption remains led by North America, followed by Europe and Asia Pacific, while Latin America and the Middle East and Africa represent faster-growing but still earlier-stage commercialization environments.
Despite this momentum, the market faces three structural challenges that will shape competitive outcomes over the next decade. First, integration fragmentation continues to burden end users. Institutions and enterprises frequently operate disjointed platforms for administration, instruction, assessment, and corporate skill tracking. Without interoperable data standards, organizations struggle to create unified learner profiles, measure continuous competency development, or automate cross-platform workflows. This friction raises total cost of ownership and slows the realization of analytics-driven decision making.
Second, data privacy and AI governance are becoming decisive procurement filters. Educational software now routinely processes sensitive demographic, performance, and behavioral data. Simultaneously, generative AI capabilities are embedded into tutoring, assessment design, content summarization, and administrative automation. Buyers are increasingly scrutinizing model transparency, data retention practices, bias mitigation, and compliance with emerging regulatory frameworks. Vendors that cannot articulate clear governance positions risk exclusion from RFPs, particularly in public sector and higher education procurement.
Third, the market is reaching a saturation inflection in mature segments. Base-level learning management and content delivery tools are becoming table stakes, pressuring vendors to differentiate through outcomes rather than feature lists. Buyers are asking harder questions about whether platforms demonstrably improve completion rates, skill transfer, instructor efficiency, or workforce readiness. This shift rewards vendors that can connect software deployment to measurable organizational impact, while exposing those that rely on perception-based marketing or fragmented point solutions.
For executives and investors, the implication is clear. Growth alone will not guarantee durable advantage. The winners will be organizations that navigate interoperability demands, embed responsible AI into product design, and prove value through outcome metrics rather than platform breadth alone.
Key Drivers Reshaping Demand and Value Creation
Four interconnected forces are driving the market’s next phase of expansion, each reshaping how software is designed, sold, and valued.
Technology Innovation and AI-Infused Learning Workflows
Generative AI has moved from experimental feature to core product architecture. Platforms are now integrating AI-assisted lesson planning, adaptive tutoring, automated rubric generation, multilingual content localization, and intelligent summarization of dense learning materials. These capabilities reduce the manual workload of educators and corporate trainers while enabling more personalized learning paths at scale. The shift is most visible in tools that support test preparation, workplace compliance training, and skills-based upskilling, where rapid content iteration and individualized pacing create tangible efficiency gains.
Equally important is the move toward AI-supported instruction rather than AI replacement. Educational institutions and employers are exploring tools that augment human facilitation, provide real-time feedback, and help managers identify skill gaps earlier in the learning journey. This balanced positioning is becoming a design principle for platforms seeking wide adoption across risk-averse and pedagogy-sensitive environments.
Policy, Regulation, and Institutional Standardization
Regulatory and policy environments are increasingly shaping procurement behavior. Public agencies and multilateral organizations are publishing guidance on responsible AI use in education, emphasizing transparency, age-appropriate design, and safeguards around student data. In parallel, regional frameworks are beginning to classify certain AI applications as higher-risk, particularly where biometric or emotion-recognition technologies intersect with learning environments. These developments do not slow adoption outright, but they do raise the bar for compliance, documentation, and vendor accountability.
At the same time, policy-driven workforce initiatives are expanding demand for accessible training tools. Government-backed literacy and AI readiness programs are surfacing as new adoption channels, especially when delivered through lightweight, mobile-friendly, or text-based formats that can reach workers outside traditional classroom settings. Such initiatives create downstream demand for content authoring, assessment, and tracking capabilities that can plug into broader skills infrastructure.
Demand-Side Shifts in Learning Behavior and Workforce Expectations
Learner expectations are changing faster than many legacy platforms can accommodate. Students, professionals, and managers increasingly expect seamless mobile experiences, modular microlearning, and visible connections between training and career progression. In corporate environments, learning is no longer treated as a separate HR function but as part of continuous performance enablement. This is driving demand for platforms that connect learning activity to role readiness, internal mobility, and compliance tracking.
In academic settings, there is growing emphasis on hybrid instruction models, credit-bearing digital credentials, and tools that reduce administrative load without compromising instructional quality. The line between formal education and professional training is blurring, encouraging platforms that can serve both contexts with consistent identity, assessment, and reporting experiences.
Education Software Market
Cost Structure and Deployment Economics
Economic pressures are reinforcing cloud-first adoption while also changing how organizations justify software spend. Budget holders want platforms that lower IT maintenance burdens, scale across campuses or enterprise units, and reduce content production costs through reusable templates, automated localization, and AI-assisted authoring. The economics of content creation are especially relevant in fast-moving technical fields where courseware can become outdated quickly. Vendors that shorten content update cycles and enable non-specialist staff to maintain materials are gaining an operational advantage.
At the same time, the cost of switching is rising as programs deepen their dependency on integrated ecosystems. Once a platform becomes the system of record for enrollment, assessment, or compliance, migration becomes politically and operationally difficult. This dynamic is strengthening retention for incumbents with broad deployment footprints, while making it harder for new entrants to displace established workflows without a clearly superior value proposition.
Competitive Landscape and Leading Strategies
The market remains comparatively fragmented at the top, with no single vendor holding dominant share. Industry concentration is moderate, with the top three players accounting for roughly 19.45 percent of revenue and the top five reaching about 29.8 percent. This structure leaves substantial room for differentiation, niche specialization, and regional expansion, but it also intensifies pressure on vendors to define a sharp strategic position rather than compete across every segment simultaneously.
Customer Support Training Software Market
Several strategic archetypes are emerging among leading players. Broad online learning platforms continue to scale by pairing content breadth with credentialing and professional signaling. Their advantage lies in audience reach, employer partnerships, and the ability to connect learning to career outcomes. Gamified and mobile-first learning apps occupy a different position, using engagement mechanics to lower barriers to entry and expand into adjacent subjects beyond their original focus. Their growth increasingly depends on converting casual users into sustained learning habits and leveraging platform ecosystems for cross-subject expansion.
Learning management system providers remain central to institutional adoption, competing on usability, integration depth, and support for diverse teaching and training models. Their differentiation often comes from how well they serve blended environments, simplify instructor workflows, and connect with student information or assessment systems. In parallel, corporate and skills-focused platforms compete on personalized learning paths, compliance coverage, leadership development, and technology skills curricula. These vendors are positioning learning as an operational capability rather than a one-off training event.
Large technology providers are layering educational capabilities onto existing productivity and cloud ecosystems. Their strategy typically emphasizes AI-enabled tools, identity and collaboration infrastructure, and low-friction adoption through familiar interfaces. By embedding learning assistance, content summarization, and classroom or workforce support tools into broader software environments, they aim to reduce switching costs and increase platform stickiness. Eu-based and multi-regional regulatory considerations are also shaping how these providers design data handling and AI features for education use cases.
Recent product and program activity illustrates how quickly the landscape is evolving. Major providers have launched educator-focused programs that bundle AI-supported teaching tools, content creation features, and improved access controls for instructional workflows. Other vendors have expanded personalized learning journeys and acquired AI content capabilities to speed creation and adaptation of training materials. In parallel, public-sector workforce initiatives are pairing free AI literacy resources with accessible delivery formats, expanding the reach of digital training beyond traditional buyers. The OECD’s recent exploration of generative AI design principles in education further underscores the growing expectation that learning tools should be effective, transparent, and context-aware.
The competitive trend points toward both consolidation and specialization. Larger platforms are likely to pursue integrations that cover identity, content, assessment, analytics, and administrative workflows in a more unified stack. At the same time, specialized providers will continue to thrive by solving narrow problems exceptionally well, such as high-stakes assessment, simulation-based training, language acquisition, or compliance-heavy corporate programs. New entrants are most likely to succeed where they can address underserved segments, offer superior UX for specific user groups, or provide interoperable tools that reduce integration burdens for existing ecosystems.
Future Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to define where value concentrates. First, AI will become a standard layer across learning workflows, but differentiation will shift from “having AI” to “using AI responsibly and effectively.” Platforms that demonstrate measurable improvements in instructor efficiency, learner completion, and assessment quality will command stronger positioning than those that merely showcase automation features. Commercial opportunities will arise for vendors that can package AI capabilities as trustworthy, auditable, and aligned with institutional governance requirements.
Second, interoperability and unified learner data will become strategic purchasing criteria. Buyers will increasingly favor solutions that can exchange data cleanly across administrative, instructional, and workforce systems. This creates openings for middleware, analytics layers, and platforms designed with open integration as a core architectural choice. Companies that reduce the integration tax for schools, universities, and enterprises will be better placed to expand within accounts and cross-sell adjacent modules.
Third, the boundary between education and workforce training will keep eroding, especially in skills-based hiring and internal mobility programs. Organizations will look for tools that support continuous credentialing, competency mapping, and scenario-based simulation. This trend favors platforms that can serve both academic and corporate audiences with adaptable content models and reporting frameworks. There is also opportunity in lightweight, high-reach training formats that support large-scale literacy and upskilling initiatives, especially where accessibility and low friction matter more than feature density.
Risks remain significant. Regulatory uncertainty around AI in education could alter procurement requirements or limit certain use cases, particularly where sensitive data or high-stakes decisions are involved. Overreliance on automation may trigger pushback if learners or instructors perceive quality degradation or excessive surveillance. Macroeconomic pressure could also compress discretionary budgets, making outcome proof and total cost of ownership more important than novelty. Vendors and buyers alike will need to balance innovation with governance, integration, and measurable impact.
Strategic Actions for Decision-Makers
For platform builders and product leaders, the priority is to design for interoperability and governance from the start. Products should make it easy to exchange learner data, support modular content creation, and provide transparent controls for AI-assisted features. Differentiation should be anchored in workflows that reduce instructor or administrator burden while improving learning outcomes, not simply in the presence of advanced features.
For investors, due diligence should focus on retention economics, integration depth, and evidence of outcome-based value. The most durable opportunities are likely to sit in segments where software becomes embedded in daily operations, compliance, or credentialing, rather than in discretionary point tools. It is also important to assess how prepared portfolio companies are for evolving AI regulation and data-handling expectations, since these factors will increasingly influence procurement velocity.
For procurement and strategy teams, selection criteria should expand beyond feature checklists. Evaluations should include data portability, integration effort, AI governance documentation, and the vendor’s ability to demonstrate measurable improvements in efficiency or learner performance. Pilots should be structured to test whether a platform can reduce administrative load, support personalized learning or training paths, and fit within broader systems already in use.
Given the speed of product launches, regulatory updates, and adoption shifts across regions and sectors, high-level market narratives are no longer sufficient for planning. Decision-makers benefit from detailed segmentation data, company-level benchmarking, and scenario analysis that connects technology roadmaps with procurement realities. Those seeking a fuller view of segmentation dynamics, regional demand patterns, and vendor positioning can use the complete PW Consulting market research report to inform investment, product, and procurement decisions with greater precision.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Educational and Training Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Ultra Low Temperature Freezers Medical Market: 5.42% CAGR Redefining Growth
By pmarketresearch, 2026-09-18
Global Ultra Low Temperature Freezers for Medical Market: Strategic Shifts and Commercial Pathways
The Worldwide Ultra Low Temperature Freezers for Medical Market has entered a phase of measured but meaningful expansion. Valued at approximately USD 915.0 Million in 2025, the market is projected to reach USD 1,324.0 Million by 2032, translating to a steady CAGR of 5.42 percent across the 2026–2032 forecast horizon. The trajectory from 2020 through 2025 reflects a compounding pattern of procurement normalization, biobank infrastructure build-outs, and sustained clinical sample preservation needs. What was once a niche laboratory equipment category has matured into a strategically critical component of healthcare logistics, pharmaceutical cold-chain operations, and biomedical research ecosystems. The growth curve is no longer driven purely by volume expansion; it is increasingly shaped by performance expectations, regulatory compliance, and total cost of ownership considerations.
Despite the clear upward trajectory, the sector faces structural inflection points that will separate value creators from commoditized players. First, energy intensity remains a stubborn operational burden. Legacy -86°C units draw substantial power over extended operating cycles, and hospitals, research facilities, and biobanks are increasingly auditing lifecycle operating costs rather than focusing solely on upfront capital expenditure. Second, regulatory scrutiny has tightened considerably. Equipment used to store vaccines, human cells, tissues, and high-value pharmaceutical products is now evaluated through stricter quality management, validation, and certification frameworks, raising the compliance burden for manufacturers and buyers alike. Third, the market is moving away from one-size-fits-all procurement toward application-specific configurations. Clinical environments demand robust temperature stability and rapid recovery, biobanks prioritize long-duration sample integrity and footprint optimization, while pharmaceutical and biotech operators focus on traceability, audit readiness, and integration with broader quality systems. These converging pressures are redefining what “competitive” means in this equipment category.
Key Demand Drivers Reshaping the Market
Technological Innovation and Performance Differentiation
Technological advancement is no longer a secondary feature; it is becoming a primary purchasing criterion. Manufacturers are deploying dual-cooling architectures, improved insulation materials, and smarter temperature management logic to reduce energy consumption while preserving sample safety. The emphasis has shifted from simply achieving low setpoints to delivering consistent temperature uniformity, faster recovery after door openings, and lower failure risk during extended unattended operation. Energy-efficient models that meaningfully cut daily power draw are gaining preference in hospital and laboratory modernization programs, particularly where facilities are under pressure to align equipment upgrades with broader sustainability and operating-cost targets. The practical implication for buyers is clear: total cost of ownership now outweighs sticker price in multi-year planning, and manufacturers that can quantify energy savings alongside reliability metrics are earning stronger consideration.
Regulatory and Compliance Evolution as a Market Filter
The regulatory environment is reshaping both product design and procurement decision-making. In the European Union, ultra-low temperature freezers intended for medical use are regulated as Class IIa medical devices under EU MDR, requiring compliance frameworks that support the storage of vaccines, human cells, and tissues. Meanwhile, the FDA’s new Quality Management System Regulation, which became effective in early 2026, has introduced additional validation expectations for equipment used to store high-value medical and pharmaceutical products. These developments are elevating the importance of documented quality systems, traceable manufacturing practices, and certified performance validation. For manufacturers, this means compliance capability is now a competitive moat rather than a baseline expectation. For procurement teams, it means vendor selection must increasingly account for certification status, validation support, and ongoing quality management discipline, especially in regulated clinical and biobanking environments.
Demand-Side Shifts in Healthcare and Life Sciences Operations
Demand is being reshaped by how biological materials are generated, stored, and utilized across the healthcare and life sciences value chain. Biobanking activity continues to expand as research programs, translational medicine initiatives, and population-scale sample collections require secure long-term preservation. Hospitals and clinics are reinforcing specimen storage practices for diagnostics, therapeutic workflows, and blood product management. Pharmaceutical and biotech organizations are investing in controlled storage environments that support development pipelines, stability programs, and clinical material handling. At the same time, organizations are seeking equipment that integrates more smoothly into quality operations, offering clearer documentation, reliable alarm pathways, and configurations aligned with specific storage profiles. The result is a more sophisticated buyer mindset: procurement decisions are increasingly tied to operational resilience, sample integrity risk reduction, and alignment with institutional quality standards.
Supply Chain and Cost Structure Realignment
Cost structures across the sector are being influenced by component availability, manufacturing scale, logistics complexity, and the premium associated with certified medical-grade production. Suppliers that maintain disciplined quality management systems, including ISO 13485 alongside ISO 9001, are better positioned to serve clinical and biobanking customers who require consistent process control and auditable manufacturing practices. At the same time, energy efficiency has become a leverage point for cost optimization, since operating expense over a freezer’s service life can dominate ownership economics. This has encouraged a broader reassessment of procurement timing, fleet replacement cycles, and regional sourcing strategies. For companies evaluating market entry or expansion, the opportunity lies not only in hardware specification but also in delivering verifiable efficiency gains, dependable after-sales support, and compliance-ready documentation that reduces friction for regulated buyers.
Medical Refrigerator Market
Competitive Landscape and Strategic Positioning
Incumbent Strengths and Differentiation Playbooks
The market is moderately concentrated, with leading players competing on reliability, compliance readiness, application fit, and energy performance rather than price alone. Thermo Fisher Scientific maintains a broad commercial footprint and a comprehensive ULT portfolio that emphasizes temperature stability, energy efficiency, and compliance-oriented design for medical, pharmaceutical, and biobanking use. PHC Corporation, including its PHCbi brand, has built recognition around dual-cooling technology and dependable long-term storage for biological samples, vaccines, and medical specimens, with recent launches reinforcing energy-efficient variants for research and clinical environments. Eppendorf continues to emphasize precise temperature control and sample safety for life sciences laboratories, while Haier Biomedical has expanded its presence with energy-efficient ULT models designed for hospital and clinical certification requirements. Helmer Scientific focuses on medical-grade storage for sensitive biological materials, blood products, and pharmaceuticals, and B Medical Systems has positioned itself around EU MDR Class IIa certification for vaccines, human cells, tissues, and laboratory samples. Other participants, including Arctiko, Stirling Ultracold, NuAire, So-Low, Labcold, BINDER, LAUDA, Corepoint Scientific, and Accucold, contribute further specialization across laboratory, blood bank, and healthcare storage applications.
Competitive Dynamics and Market Evolution
The competitive landscape is evolving along three interrelated directions. First, differentiation is increasingly anchored in verifiable efficiency and regulatory readiness. Products that can demonstrate lower energy consumption, robust temperature recovery, and clear certification alignment are gaining salience with buyers managing both operating budgets and compliance obligations. Second, the market is showing signs of both consolidation and fragmentation depending on segment and region. Larger incumbents leverage scale, service networks, and portfolio breadth to defend positions in high-volume clinical and biobanking channels, while smaller or regionally focused manufacturers compete through specialized configurations, responsive support, and tailored application solutions. Third, new entrants and product innovations are pressuring incumbents to keep advancing efficiency and usability. Recent launches such as PHC Corporation of North America’s TwinGuard ECO series illustrate how dual-cooling technology and enhanced energy performance are being used to reinforce long-term sample protection for medical and pharmaceutical facilities. The broader implication is that competitive advantage will increasingly depend on the ability to combine dependable cooling performance with compliance support, energy economics, and service reliability.
Forward Outlook: Trends Shaping the Next 3–5 Years
Efficiency as a Default Requirement, Not a Premium Feature
Over the next several years, energy-efficient ULT freezers are likely to shift from preferred options to baseline expectations in hospital, laboratory, and biobank procurement. As operating cost pressure persists and sustainability considerations become more embedded in facility planning, models that substantially reduce daily energy use will be favored in fleet upgrades and replacement cycles. The commercial opportunity lies in equipment that can deliver measurable efficiency gains without compromising temperature stability or sample protection. Manufacturers and distributors that can provide transparent performance comparisons and lifecycle cost framing will be better positioned to influence purchasing decisions.
Regulatory Compliance as a Defining Purchase Criterion
Compliance expectations will continue to deepen as quality management requirements and medical-device classification frameworks become more familiar to procurement and quality teams. Buyers will increasingly expect documented validation support, certified manufacturing practices, and equipment designed to fit into regulated storage workflows for vaccines, cells, tissues, and pharmaceutical materials. This trend creates a dual opportunity: manufacturers that invest early in certification readiness, quality system alignment, and validation documentation can command stronger procurement credibility, while buyers that align equipment selection with compliance pathways can reduce downstream audit and operational risk.
PW Consulting
Application-Specific Solutions and Regional Diversification
Demand will continue to diverge by use case, with biobanks, hospitals and clinics, pharmaceutical and biotech companies, and academic research institutes each prioritizing different performance attributes. Biobanks will emphasize long-term sample integrity and storage density, clinical settings will prioritize dependable temperature control and service responsiveness, and pharmaceutical and biotech users will focus on quality-system compatibility and traceability. Regionally, growth is likely to remain broad-based, with North America, Europe, and Asia Pacific each presenting distinct procurement rhythms, regulatory nuances, and infrastructure needs. The strategic opportunity is to move beyond generic product positioning and align offerings with the operational realities of each application and geography. The main uncertainty is the pace and consistency of regulatory interpretation across markets, which could affect product requirements, validation expectations, and time-to-market for new models.
Strategic Implications for Decision-Makers
For Manufacturers and Suppliers
Product strategy should balance performance credibility with compliance readiness and operating economics. Prioritize demonstrable energy efficiency, temperature stability, and service support, while ensuring that quality management and certification pathways are clearly articulated for regulated customers. Differentiation will increasingly come from how well a product fits into clinical, biobanking, or pharmaceutical workflows, not just from nominal cooling specifications.
For Investors and Strategic Partners
Investment attention should focus on companies with defensible compliance positions, efficiency-driven product roadmaps, and credible service and support models. The most durable value creation is likely to come from players that can combine reliable hardware with documentation, validation support, and total cost of ownership advantages that resonate with regulated buyers. Market growth is steady, but share gains will depend on execution in compliance, efficiency, and application alignment.
Ultra-low Temperature Freezers Market
For Procurement and Operations Leaders
Procurement decisions should evaluate ULT freezers through a lifecycle lens, weighing energy consumption, temperature reliability, certification status, validation support, and service responsiveness alongside initial capital cost. Aligning equipment selection with the intended application—clinical storage, biobanking, pharmaceutical handling, or research—will reduce operational friction and improve long-term sample integrity risk management. Requesting performance data, compliance documentation, and efficiency comparisons should become standard practice in vendor evaluation.
For organizations seeking deeper segmentation, regional procurement dynamics, and customized strategic recommendations, the full PW Consulting market analysis provides expanded data and targeted guidance across market size trajectories, competitive positioning, and application-specific demand patterns.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra Low Temperature Freezers for Medical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com