
Blogs
Hydrogen Sulfide Scavengers Market: Inside the 3.44% CAGR Upside to 2032
By pmarketresearch, 2026-09-21
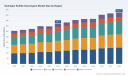
The Hydrogen Sulfide Scavengers Market: Navigating Growth, Regulation, and Chemical Innovation
Hydrogen sulfide remains one of the most persistent operational and safety hazards across oil and gas production, gas processing, and wastewater treatment. The compounds corrosive nature, toxicity, and tendency to form metal sulfides make its control a non-negotiable requirement for compliant and efficient operations. Against this backdrop, the global market for hydrogen sulfide scavengers has settled into a measured but steady growth trajectory, expanding from approximately 305 million USD in 2020 to an estimated 370.5 million USD in 2025, with projections reaching roughly 472 million USD by 2032. The implied compound annual growth rate of 3.44 percent over the 2025 to 2032 forecast window reflects a market that is maturing rather than exploding, driven less by explosive volume demand and more by regulatory tightening, operational optimization, and incremental chemical innovation.
For executives and investors, the central takeaway is that this is not a high-growth novelty segment but a stable, regulation-anchored specialty chemicals market with meaningful margin potential for players who can differentiate on performance, safety, and total cost of ownership. The challenge lies in recognizing where the growth pockets are forming, which product architectures are gaining ground, and how leading suppliers are repositioning themselves in a landscape marked by fragmented demand, supply chain friction, and increasingly stringent emission controls.
Market Structure and Core Challenges
The market's evolution over the 2020 to 2025 period tells a story of resilience amid volatility. Revenue growth from 305.21 million USD in 2020 to 347.92 million USD in 2023, followed by a modest contraction to 346.36 million USD in 2024 before rebounding to 370.5 million USD in 2025, underscores how external shocks can temporarily disrupt even essential chemical supply chains. That 2024 dip, while relatively small in percentage terms, signals the market's sensitivity to raw material availability and pricing, particularly for triazine-based formulations that dominate high-volume applications. The rebound in 2025 suggests that demand fundamentals remain intact and that operators are unwilling to delay H2S control investments given the safety and compliance stakes involved.
Several structural challenges define the current inflection point. First, raw material dependency and supply chain vulnerability continue to shape pricing dynamics and product availability. The market relies heavily on precursor chemicals such as ethylene oxide and related intermediates for triazine-based scavengers. A plant incident in 2023 triggered shortages and price increases for these formulations, a disruption that rippled through procurement cycles well into 2025. This fragility has forced operators and suppliers alike to reconsider single-source dependencies and to evaluate alternative chemistries that can reduce exposure to precursor volatility.
Second, regulatory fragmentation across regions creates a complex compliance environment. In the United States, the Toxic Substances Control Act and related EPA and OSHA mandates increase the compliance burden for facilities handling sour streams, while Bureau of Safety and Environmental Enforcement rules under 30 CFR 250.490 require operators on the U.S. Outer Continental Shelf to maintain H2S scavengers on facilities and deploy them upon detection. In Europe, Directive 2016/2284 sets emission limits that drive H2S control requirements across industrial applications. In the Middle East and Africa, GSO ISO 8819:2013 provides regional standards for H2S treatment processes. These overlapping requirements mean that a one-size-fits-all product strategy is rarely sufficient; suppliers must navigate differing thresholds, testing protocols, and documentation expectations across jurisdictions.
Third, the market must balance performance against cost and environmental considerations. Traditional triazine-based scavengers offer effective H2S removal but can generate sludge, introduce nitrogen-containing byproducts, and carry higher handling costs in certain applications. The industry is increasingly asking whether alternative chemistries can deliver comparable or superior performance with reduced waste, lower corrosion risk, or easier integration into existing processes. This tension between proven reliability and the desire for cleaner, more efficient solutions is reshaping product selection criteria at the operational level.
The Demand Side: Where Growth Is Concentrated
H2S scavenging demand is anchored by three core application areas: oil industry operations, gas industry processing, and wastewater treatment. These segments collectively represent the bulk of market volume, with oil and gas applications historically dominating due to the prevalence of sour production streams and the high cost of downtime or safety incidents when H2S is not adequately controlled. Gas processing facilities face similar pressures, particularly where sales gas must meet pipeline specifications that impose strict H2S limits. Wastewater treatment represents a growing adjacent demand source, where H2S control intersects with odor management, corrosion prevention, and regulatory compliance for industrial and municipal effluent handling.
What ties these applications together is not just the presence of H2S but the operational consequences of failing to manage it. In production environments, H2S contributes to sulfide stress cracking, iron sulfide scale formation, and equipment fouling, all of which increase maintenance costs and reduce throughput. In gas transmission, failure to meet pipeline specifications can result in rejected volumes, fines, or the need for costly downstream cleanup. In water systems, H2S generates odors, accelerates corrosion in concrete and metal infrastructure, and poses worker safety risks in confined spaces. These cost and risk drivers ensure that H2S scavenging remains a priority even in capital-constrained cycles, because the alternative is often more expensive in the long run.
The market segmentation by type reflects a meaningful split between regenerative and non-regenerative approaches. Non-regenerative scavengers, which react with H2S to form stable compounds that are then disposed of or treated downstream, account for a larger share of current demand. Regenerative systems, which capture and release H2S for subsequent processing or reuse, appeal in contexts where continuous treatment, waste minimization, or resource recovery is prioritized. The relative balance between these two architectures is not static; it shifts with application requirements, operating economics, and the availability of disposal or recycling pathways.
Key Drivers Shaping the Market
Several forces are converging to shape the next phase of market development. Understanding these drivers is essential for identifying where investment, product development, and commercial strategy should be directed.
Technological Innovation and Performance Differentiation
Product innovation is moving beyond generic H2S removal toward application-specific formulations that address multiple operational pain points simultaneously. Recent product introductions illustrate this trajectory. In June 2025, Clariant introduced SCAVTREAT 1173, a gas phase hydrogen sulfide scavenger, expanding its portfolio for gaseous streams. The following month, the company released SCAVTREAT 13964, an H2S scavenger based on glycol derivatives in organic solvents, signaling a push toward alternative chemical architectures that may offer advantages in selectivity, handling, or compatibility with specific process conditions. These releases reflect a broader industry pattern: suppliers are investing in targeted formulations rather than relying solely on established triazine platforms.
Baker Hughes has similarly emphasized performance validation and cost reduction through real-world case studies. In July 2025, the company published a case study demonstrating that its PETROSWEET H2S scavenger reduced H2S levels in sales gas by 60 percent, enabling the operator to meet pipeline specifications and increase production revenue. In May 2025, a separate case study highlighted how the same product cut treatment costs in multiple contact tower applications. These examples underscore a shift in how suppliers justify value: not merely by stating that a product removes H2S, but by quantifying the downstream impact on revenue, compliance, and operating expense.
SLB contributed its own performance narrative in June 2025, releasing a case study on subsea injection of a proprietary H2S scavenger that reduced schmoo deposits and significantly lowered cost. This application highlights the growing relevance of H2S control in subsea and offshore environments, where access constraints, safety considerations, and deposit management create unique challenges. The ability to inject scavengers subsea and achieve measurable deposit reduction points to a niche where specialized formulations and delivery methods can command premium positioning.
Regulatory Pressure as a Structural Demand Driver
Regulation is not merely a compliance checkbox; it is a persistent demand anchor that shapes procurement behavior, product specification, and geographic prioritization. The U.S. regulatory framework, encompassing TSCA and EPA/OSHA mandates, increases the baseline requirement for effective H2S control across production and processing facilities. BSEE rules add a layer of operational obligation for offshore facilities, making scavenger availability and deployment a regulatory expectation rather than an optional best practice. In Europe, emission limits under Directive 2016/2284 sustain demand for H2S control across industrial applications, while GSO ISO 8819:2013 provides a regional standard that influences procurement specifications in the Middle East and Africa.
Hydrogen Sulfide Removal Market
For suppliers, this regulatory patchwork creates both opportunity and complexity. Products that can demonstrate compliance with multiple regional standards, provide robust documentation, and offer consistent performance across varying H2S concentrations and flow conditions gain a competitive advantage. Conversely, suppliers that treat regulation as a secondary concern risk losing specification share to competitors who position their products explicitly around compliance assurance and audit readiness.
Supply Chain Realities and the Push for Alternatives
The 2023 plant incident that disrupted ethylene oxide and related precursor supplies exposed a structural vulnerability in the triazine-based scavenger supply chain. The resulting shortages and price increases in 2025 reinforced the need for diversification, whether through alternative chemistries, multi-source procurement, or reformulated products that reduce dependency on constrained intermediates. This dynamic is accelerating interest in non-triazine options, including nitrogen-free formulations and glycol-derivative-based scavengers, as operators and suppliers seek to insulate operations from single-point failures in the raw material chain.
Cost structure evolution is also influenced by the total cost of treatment, not just the price per unit of scavenger. Factors such as dosing efficiency, sludge generation, corrosion impact, handling requirements, and waste disposal costs all contribute to the economic equation. Products that reduce overall treatment burden, even at a higher unit price, can win on total cost of ownership. This is particularly relevant in applications where downtime, equipment damage, or compliance penalties carry heavy financial consequences.
Competitive Landscape and Strategic Positioning
The hydrogen sulfide scavengers market is moderately concentrated, with the top three companies holding approximately 27.5 percent of revenue and the top five reaching roughly 39.8 percent. This concentration level indicates a market where leading players command meaningful share but where a long tail of specialized and regional suppliers retains relevance, particularly in niche applications, local service requirements, and cost-sensitive segments. The presence of large energy service and chemical companies alongside focused specialty chemical firms creates a dynamic where competition plays out across multiple dimensions: technical performance, application expertise, regulatory support, supply reliability, and total cost of ownership.
Baker Hughes and SLB, both headquartered in Houston, represent the energy services end of the spectrum. Baker Hughes has built its offering around PETROSWEET and SULFIX H2S scavenger solutions targeting crude oil, intermediates, refined products, and processing systems. Its recent case study activity emphasizes measurable outcomes—H2S reduction to meet pipeline specs, treatment cost reductions in contact towers, and subsea deposit control—positioning its products around demonstrated operational value rather than chemistry alone. SLB's liquid H2S scavenger portfolio includes triazine and nitrogen-free options for sour production streams, corrosion control, and HSE hazard management. Its subsea case study reinforces a strategy centered on solving hard-to-reach, high-consequence applications where performance and safety integration are paramount.
Clariant, based in Muttenz, Switzerland, brings a specialty chemicals perspective through its SCAVTREAT line, which addresses hydrogen sulfide, iron sulfide, sulfide scale, and oxygen control in gases and liquids. The 2025 introductions of SCAVTREAT 1173 and SCAVTREAT 13964 illustrate a focus on expanding the application envelope and exploring alternative chemical bases, such as glycol derivatives in organic solvents. This approach positions Clariant as a player investing in formulation breadth and application flexibility, appealing to operators seeking tailored solutions for specific gas or liquid streams.
Merichem Company, also headquartered in Houston, occupies a distinct position with its regenerable H2S scavengers via LO-CAT and EcoTreat technologies for sour gas streams. Regenerable systems appeal where continuous treatment, waste reduction, or resource recovery economics justify the higher complexity and capital considerations. This positions Merichem in a segment where lifecycle economics and sustainability considerations can outweigh lower upfront simplicity.
Other notable participants include SUEZ in Paris, with chemical solutions for H2S removal in water treatment and industrial applications; NuGenTec in the United States, offering triazine-based and non-triazine formulations; Dorf-Ketal in Mundra, Gujarat, India, with its MAXSCAV line for refinery and petrochemical process chemicals; Halliburton in Houston, providing production chemicals and H2S treatment solutions for oil and gas operations; Arkema in Colombes, France, with specialty chemicals and solutions for H2S control; ChemTreat in Glen Allen, Virginia, focusing on water treatment chemicals including H2S scavengers; Caradan Chemicals International in the United States, with H2S scavenger products for oil and gas applications; Paqell in the Netherlands, offering chemical solutions for H2S scavenging in industrial settings; and Nalco Water in Naperville, Illinois, with water treatment and H2S control products. This breadth of participants reflects a market where application specialization, regional presence, and service capabilities often matter as much as chemistry alone.
The competitive landscape is evolving along several axes. Consolidation pressure exists, particularly as larger energy service and chemical companies seek to strengthen their production chemicals portfolios and capture cross-selling opportunities across drilling, completion, production, and processing services. At the same time, fragmentation persists because H2S scavenging requirements vary widely by geography, application, H2S concentration, flow conditions, and regulatory context. New entrants and regional specialists can find room by focusing on underserved applications, localized service, or alternative chemistries that address specific pain points such as nitrogen-free requirements, reduced sludge generation, or improved compatibility with particular process environments.
Forward Trends and Commercial Implications
Looking ahead to the 2026 to 2032 window, several trends are likely to shape market direction and commercial opportunity.
PW Consulting Automotive & Machinery Research Center
Trend One: Performance Validation Becomes a Competitive Mandate
As operators face tighter margins and heightened compliance scrutiny, the ability to quantify the impact of H2S scavenging on revenue protection, cost reduction, and safety outcomes will increasingly differentiate suppliers. Case studies, field data, and application-specific performance benchmarks will move from marketing support to core competitive assets. Suppliers that invest in rigorous validation, transparent reporting, and customer-specific economic modeling will be better positioned to defend specification share and justify premium positioning. For buyers, this trend means that product selection will increasingly hinge on demonstrated outcomes in comparable applications rather than on generic claims.
Mma Triazine H2S Scavengers Market
Trend Two: Chemistry Diversification Accelerates in Response to Supply and Regulation
The precursor disruptions affecting triazine-based scavengers, combined with evolving regulatory expectations around waste, emissions, and handling, will continue to drive interest in alternative chemistries. Nitrogen-free formulations, glycol-derivative-based options, and regenerative systems are likely to gain traction in segments where their performance, safety, or waste profile aligns with operator priorities. This diversification does not imply the obsolescence of established chemistries; triazine-based products remain effective and widely used. Rather, it expands the decision space, giving operators more options to match chemistry to application constraints and risk tolerance. Suppliers that can offer a balanced portfolio, supported by clear guidance on when each chemistry is appropriate, will capture more specification opportunities across a wider range of conditions.
Trend Three: Application Expansion Beyond Traditional Oil and Gas Core
While oil and gas production and gas processing remain the dominant demand centers, adjacent applications in wastewater treatment, industrial effluent handling, and subsea or offshore operations are likely to contribute a growing share of demand. In water treatment, H2S control intersects with odor management, infrastructure protection, and regulatory compliance, creating opportunities for chemistries and delivery methods tailored to aqueous environments. In subsea and offshore settings, the combination of access difficulty, safety criticality, and deposit management creates niche demand for specialized injection and performance assurance approaches. These application expansions do not require a wholesale shift in market structure; they represent incremental growth pockets where focused product development and application expertise can yield disproportionate returns.
Potential risks and uncertainties temper this outlook. Raw material volatility could recur if precursor supply chains remain fragile, affecting pricing and availability for certain chemistries. Regulatory divergence across regions could increase compliance costs and complicate product standardization, particularly for multinational operators managing assets across multiple jurisdictions. Economic cycles in oil and gas investment could influence the pace of new project development and the willingness to adopt newer or more expensive chemistries, even when long-term benefits are clear. Finally, the performance claims surrounding alternative chemistries will need to withstand field validation; products that overpromise on H2S removal, corrosion control, or waste reduction risk reputational damage and specification loss if real-world results fall short.
Strategic Implications for Decision-Makers
For manufacturers and suppliers, the imperative is to build portfolios and capabilities that align with where value is being created. This means investing in application-specific formulation development, expanding evidence-based validation programs, and ensuring that product lines cover both established and emerging chemistry options. Suppliers should also evaluate supply chain resilience, including multi-source sourcing for critical precursors and formulation flexibility that can adapt to raw material constraints. Differentiation will increasingly come from the ability to reduce total treatment cost and risk, not just from the chemistry itself.
For investors, the market offers a profile of steady, regulation-anchored demand with selective pockets of faster growth tied to application expansion and chemistry innovation. The moderate concentration level suggests that market leadership is attainable but not guaranteed, and that success depends on execution in product development, service, and commercial positioning rather than on scale alone. Due diligence should focus on demonstration of field-validated performance, exposure to alternative chemistries and regenerative options, geographic and application diversification, and supply chain robustness. Companies that can show measurable impact on customer revenue, compliance, and operating cost will command stronger competitive positions and more resilient demand.
For procurement and operations leaders, the priority is to move beyond unit price comparisons and evaluate total cost of ownership across dosing efficiency, sludge and waste handling, corrosion impact, handling safety, and compliance documentation. Specification decisions should incorporate application-specific performance data, supplier validation records, and supply reliability considerations, particularly given past precursor disruptions. Where possible, operators should maintain flexibility in chemistry selection, allowing them to adapt to supply conditions, regulatory changes, and evolving operational requirements without compromising H2S control.
The hydrogen sulfide scavengers market is at a point where steady growth, regulatory anchoring, and chemical innovation intersect. Understanding the nuances of product architecture, application economics, and competitive positioning is essential for capturing value in this segment. For those seeking deeper segmentation data, company-level benchmarks, and customized scenario analysis to inform specific investment or procurement decisions, comprehensive market research reports provide the detailed intelligence needed to move from strategic direction to execution.
For detailed analysis of this topic, please visit the official page: Hydrogen Sulfide Scavengers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wheel Flange Lubrication System Market: Why 4.46% CAGR Redefines Track Performance
By pmarketresearch, 2026-09-21
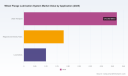
Global Wheel Flange Lubrication System Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Steady Growth Anchored in Infrastructure Modernization
The global wheel flange lubrication system market has transitioned from a specialized niche to a critical component of railway maintenance ecosystems. Valued at USD 0.56 billion in 2020, the market has followed a consistent upward trajectory, reaching approximately USD 0.70 billion by 2025. Projections through 2032 indicate continued expansion, with the market expected to reach USD 0.95 billion by the end of the forecast period, supported by a compound annual growth rate of 4.46%. This trajectory reflects a maturing but still evolving landscape where reliability, environmental compliance, and lifecycle cost optimization drive procurement decisions across transport operators and infrastructure managers.
The market structure remains concentrated, with the top three and top five players collectively commanding roughly 70% of global revenue. This concentration suggests entrenched relationships with rolling stock manufacturers, railway operators, and municipal transit authorities, while simultaneously leaving meaningful room for differentiated challengers who can address specific operational pain points. Geographically, demand is distributed across multiple regions, with mature markets in North America and Europe maintaining steady procurement cycles and emerging infrastructure programs in Asia Pacific, Latin America, and the Middle East and Africa contributing incremental growth. The application mix is anchored by urban transport networks, which represent the largest share of deployments, followed by regional and intercity trains and locomotive operations. By system type, wayside configurations account for the majority of installations, while on-board solutions occupy a smaller but strategically important segment tied to fleet flexibility and space-constrained platforms.
This growth is not accidental. It reflects a broader shift in railway operations from reactive maintenance toward predictive, condition-based, and environmentally conscious asset management. The market’s trajectory through 2032 will be shaped less by raw volume expansion and more by the ability of stakeholders to align lubrication technologies with evolving compliance standards, operational reliability targets, and total cost of ownership expectations.
Critical Challenges and Industry Inflection Points
The market faces a set of intertwined challenges that are reshaping procurement behavior and technology selection. First, the operational trade-off between lubrication effectiveness and contamination risk continues to force operators to reconsider liquid versus solid delivery architectures. Recent industry publications have highlighted shunt failure issues caused by excess oil from liquid wheel flange lubrication systems in metro applications, underscoring how over-application or poorly managed dispersion can create downstream reliability problems. This has reignited operator scrutiny around dosing precision, delivery placement, and the operational footprint of lubricant residues on track infrastructure.
Second, regulatory and environmental constraints are tightening the boundaries of acceptable lubricant selection. Equipment standards such as EN 15427-1-1:2022 specify requirements for equipment used to apply lubricant to the interface between the wheel flange and the gauge face of the rail, which pushes suppliers to align hardware design, nozzle performance, and application controls with recognized engineering expectations. Beyond equipment specifications, environmental permitting and lubricant discharge limits in certain jurisdictions restrict lubricant types and affect a meaningful portion of trial sites reported by operators. These constraints are not theoretical; they influence procurement timelines, site approvals, and the willingness of operators to adopt new chemistries without localized validation.
Third, material and design choices are increasingly scrutinized through a lifecycle lens. Modern wheel flange lubrication systems are often built on a polymer matrix with dry solid lubricant integrated, a configuration that reflects the broader industry shift toward reduced residue, simplified maintenance, and lower contamination risk. However, performance consistency across varying rail profiles, weather conditions, and traffic densities remains a recurring operational challenge. Suppliers that can demonstrate repeatable friction reduction, controlled wear characteristics, and compatibility with different rail and wheel materials will have a distinct advantage in a market where operators increasingly evaluate solutions across multi-year service life rather than initial capex.
PW Consulting
These challenges do not signal stagnation. Instead, they mark an inflection point where the winning offerings will be those that balance application precision, environmental acceptability, and maintenance-friendly design rather than those that simply maximize lubricant volume or hardware complexity.
Core Drivers Shaping Market Direction
Several interconnected forces are accelerating change in wheel flange lubrication system demand and purchasing behavior.
Technological innovation is pushing the category beyond mechanical dispensing toward controlled delivery, material science advancement, and more predictable friction management. Patented application techniques and specialized material formulations are being used to improve lubrication consistency while reducing excess spread. Dry solid lubricant approaches, particularly carbon-based products designed to lower friction and wear without heavy residue, are gaining traction where operators seek to reduce cleaning cycles and minimize track contamination. At the same time, on-board and wayside architectures are being refined to address specific operating environments, from high-frequency urban tram networks to heavier regional and intercity services. The result is a more segmented technology landscape in which performance claims must be validated under real track conditions, not just in laboratory settings.
Policy and regulatory dynamics are simultaneously shaping the market by narrowing lubricant choices and increasing documentation expectations. Newer equipment requirements and evolving environmental expectations are making compliance an integral part of procurement rather than an afterthought. The growing proportion of biodegradable and low-VOC lubricant selections in new contracts signals that sustainability considerations are moving from peripheral interest to active evaluation criteria. This shift does not eliminate performance requirements, but it does raise the bar for solution providers: lubricant formulations and delivery systems must now demonstrate operational value alongside environmental acceptability.
Demand-side behavior is also changing. Urban transport authorities and regional operators are increasingly focused on service continuity, reduced wheel and rail wear, and lower maintenance burden. These priorities are especially relevant where network utilization is high and downtime carries significant operational and financial consequences. Procurement teams are therefore weighing lubrication systems not only against upfront cost, but also against expected service intervals, ease of refilling or replacement, and the ability to reduce unplanned interventions. In that context, lubrication solutions that simplify field service and deliver consistent performance can justify premium positioning even in cost-sensitive environments.
Supply chain and cost structure considerations add another layer of influence. Material availability, carbon-based feedstock characteristics, polymer matrix design, and manufacturing scalability all influence both product performance and commercial resilience. As operators become more sensitive to total cost of ownership, suppliers that can manage material sourcing, maintain formulation consistency, and support service networks with predictable lead times are better positioned to secure long-term contracts. Cost compression alone is unlikely to drive purchasing decisions in this segment; reliability, compliance, and serviceability typically carry more weight in operational evaluations.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a blend of established multinational suppliers, specialized lubrication manufacturers, and material-focused innovators. Large incumbents tend to leverage broad railway portfolios, global service reach, and longstanding relationships with rolling stock and infrastructure stakeholders. This scale advantage supports system integration, cross-platform compatibility, and the ability to offer both wayside and on-board configurations within a single supplier relationship. For operators seeking consolidation of supply and standardized maintenance practices, these players remain natural first stops in the evaluation process.
At the same time, differentiated specialists are competing through technology specificity and application expertise. Companies promoting patented delivery methods are positioning around precision, reduced waste, and performance consistency in targeted use cases. Suppliers of carbon-based dry lubricants are emphasizing friction reduction and wear mitigation with a focus on lower contamination and simplified field handling. Others are promoting solid lubricant sticks, applicators, and corrosion-resistant designs tailored for metro, tram, and industrial railway environments where residue control and durability are especially important. This specialization matters because wheel flange lubrication is inherently site-sensitive; a solution that performs well in one operating environment may require adaptation in another.
Recent developments indicate a market that is active but selective. Industry participation in technology exhibitions and targeted case study publications suggests continued emphasis on demonstration, validation, and operator education. Showcasing lubrication technologies at sector events helps suppliers reach transit authorities, maintenance teams, and engineering decision-makers who evaluate solutions based on compatibility with existing infrastructure and anticipated service impact. At the same time, published case discussions around excess oil and shunt-related issues reinforce the market’s sensitivity to over-application and contamination, pushing the conversation toward controlled delivery and cleaner interface management.
The competitive landscape is likely to evolve through a mix of consolidation and targeted entry rather than uniform convergence. Consolidation may continue where scale, service coverage, and system integration create durable advantages. Fragmentation may persist where niche performance, regional compliance needs, or specific material advantages allow focused players to win meaningful contracts. New entrants will need to demonstrate more than equipment availability; they will need to show credible validation, operator-relevant service support, and alignment with environmental and reliability expectations. For incumbents, the challenge is to avoid over-reliance on portfolio breadth alone and to maintain compelling product-level differentiation as procurement teams become more sophisticated about lifecycle performance.
Forward-Looking Trends: 2026 to 2032
Several trends are likely to define commercial direction over the next several years.
Trend 1: Controlled delivery and residue-sensitive architectures will gain preference. As operators confront the operational consequences of over-application and track contamination, demand will increasingly favor systems that emphasize dosing accuracy, targeted placement, and cleaner interface management. This trend supports both dry solid and refined liquid approaches, but only where performance can be demonstrated without creating secondary maintenance burdens. Commercial opportunity lies in solutions that reduce cleaning frequency, improve consistency across varying traffic conditions, and simplify operator procedures. The risk is that overly aggressive claims about “cleaner” systems will be challenged if field validation does not match controlled-environment expectations.
Trend 2: Environmental acceptability will become a core procurement filter, not a secondary consideration. With biodegradable and low-VOC options representing a growing share of new contract selections and environmental permitting constraints affecting a notable portion of trial activity, sustainability criteria will play a larger role in vendor shortlists. Solutions that align with local discharge expectations, demonstrate reduced environmental footprint, and maintain mechanical performance will be better positioned for broader adoption. The commercial upside is clear for suppliers that can provide compliant chemistries, application hardware, and documentation support in a single value proposition. The uncertainty lies in regulatory variation across jurisdictions, which may require region-specific validation and slow standardization of lubricant preferences.
Trend 3: Lifecycle value and service integration will increasingly outweigh initial hardware cost. Operators managing dense urban networks and publicly accountable transport systems are likely to evaluate lubrication systems through total cost of ownership, including maintenance labor, refilling logistics, wear reduction, and downtime avoidance. This creates opportunities for suppliers that bundle application reliability with field service support, predictable consumable supply, and design choices that simplify inspection and replenishment. Over the next few years, contracts may increasingly reward proven serviceability and operational consistency. The risk is that supply chain volatility, material availability, or inconsistent manufacturing quality can undermine the expected lifecycle benefits and erode buyer confidence.
Automatic Lubrication Systems Market
Strategic Implications for Decision-Makers
For manufacturers and technology suppliers, the priority is to align product development with the market’s shifting evaluation criteria. Differentiation is strongest when it directly addresses application precision, residue management, and environmental compliance without sacrificing reliable friction control. Investments in validation documentation, pilot-scale demonstrations, and region-specific lubricant compatibility can improve credibility with operators and engineering teams. Supplier strategies that depend solely on hardware presence or legacy relationships are more vulnerable to competitors offering cleaner, more controllable, and more service-friendly solutions.
For investors and strategic partners, the attractive value lies in capabilities that strengthen lifecycle value and compliance readiness rather than in volume expansion alone. Technology positions tied to controlled delivery, dry solid formulations, and durable consumable designs may offer more defensible differentiation in a market where contamination risk and environmental constraints are rising in importance. Equally important is the operational side: distribution, service readiness, and the ability to support trial-to-scale transitions can determine whether a promising product translates into durable contract wins. Due diligence should account for regional regulatory variation and the potential need for localized validation before widespread adoption.
For procurement teams and transport operators, the most effective approach is to evaluate lubrication systems through a combined lens of reliability, compliance, and maintenance burden. Specifying solutions based only on upfront price can increase exposure to repeat application issues, cleaning requirements, and downstream infrastructure concerns. Where possible, procurement should incorporate trial data, operator-relevant performance metrics, and supplier support capabilities into the decision process, especially for urban networks and high-utilization services where downtime carries significant operational cost. Balancing equipment standards alignment with lubricant selection criteria can also reduce approval friction and improve long-term contract stability.
Railway Grease Market
As the market moves toward 2032, the differentiating questions will not be limited to whether a system can apply lubricant, but whether it can do so with controlled dispersion, compliant chemistry, and maintenance-friendly execution across the intended operating environment. Organizations that secure detailed segment-level insight, region-specific regulatory context, and supplier-by-supplier positioning will be better equipped to time investments, refine specifications, and target the most commercially relevant opportunities.
For detailed analysis of this topic, please visit the official page: Wheel Flange Lubrication System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
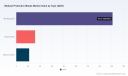
Medical Protective Masks Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for medical protective masks has entered a new phase of structural maturation, transitioning from crisis-driven demand to a more predictable, compliance-shaped growth trajectory. With a 2025 revenue baseline of 215.0 million USD and a projected compound annual growth rate of 6.95 percent through 2032, the sector is expanding toward a 344.8 million USD valuation by the end of the forecast window. The historical arc from 2020 through 2025 reveals a market that absorbed unprecedented shocks, stabilized around renewed procurement rhythms, and is now being reshaped by regulatory recalibration, regional capacity realignment, and shifting end-user expectations. For executives, investors, and procurement leaders, the central question has moved beyond whether demand will persist to how value will be captured in a market where certification status, domestic sourcing preferences, and performance standardization increasingly dictate commercial outcomes.
N95 Grade Medical Protective Masks Market
Market Landscape and Core Challenges
The revenue progression from 2020 to 2025 establishes a baseline of steady expansion, with annual figures moving from 163.15 million USD to 215.0 million USD. The forecast path to 2032 indicates continued upward movement, though the growth profile is not linear. Acceleration in the near term is supported by renewed institutional purchasing and updated performance expectations, while longer-term expansion depends on how quickly manufacturers can align production with evolving compliance frameworks and how procurement systems integrate new domestic sourcing incentives. The market remains moderately fragmented. The combined share of the three largest participants sits at 24.6 percent, while the top five account for 26.2 percent. This concentration pattern signals that scale alone does not confer decisive dominance. Instead, competitive advantage is increasingly tied to certification portfolios, regulatory responsiveness, and the ability to maintain consistent supply to healthcare and institutional buyers who prioritize reliable compliance over pure price competition.
Several structural challenges are redefining how participants operate. The first is regulatory volatility around approval frameworks. Recent actions by NIOSH, including the voluntary rescission of multiple approvals for major respirator manufacturers, have introduced uncertainty into product line continuity and inventory planning. For manufacturers, this creates a need to treat certification status as a dynamic asset rather than a static credential. For procurement teams, it complicates long-term sourcing commitments and raises the importance of supplier diversification. The second challenge lies in the tension between global cost optimization and emerging domestic procurement preferences. Policy signals, including CMS proposals to maintain equitable adjustment authority for domestic N95 respirator costs and a January 2026 advance notice of proposed rulemaking seeking input on incentivizing domestic procurement of personal protective equipment, indicate a directional shift toward supply chain localization. Companies that rely heavily on centralized overseas production without regional backup capacity may face margin pressure or eligibility constraints in certain procurement channels. The third challenge is standardization reform. The introduction of EN 14683:2025, which specifies updated construction, design, performance requirements, and test methods for medical face masks, raises the bar for product consistency and documentation. While stronger standards improve end-user confidence and interoperability across procurement systems, they also increase compliance costs and can slow product launches for manufacturers that have not invested in testing infrastructure and quality system upgrades.
Key Drivers Shaping Market Trajectory
The market's direction is being shaped by four interlocking forces: technology and design innovation, regulatory and policy evolution, demand-side behavior changes, and supply chain cost structure realignment. Each driver carries distinct implications for commercial strategy.
Technology and Performance Innovation
Product differentiation is increasingly anchored in filtration consistency, fit optimization, and material durability rather than basic barrier functionality. N95 respirators remain the largest product category, reflecting sustained preference for higher filtration performance in clinical and high-exposure environments. At the same time, manufacturers are expanding surgical N95 variants and ASTM-aligned surgical masks to address settings where both fluid resistance and respiratory protection are required. Recent commercial activity illustrates how companies are using product breadth and certification coverage to strengthen positioning. Makrite's participation in Tool Japan 2025 highlighted a strategy of showcasing N95, surgical, and KN95/FFP2 variants together, reinforcing a portfolio approach that aligns with procurement teams seeking single-source compatibility across multiple use cases. Harley Commodity's emphasis on surgical N95 models with adjustable head straps reflects attention to fit and wearer compliance, factors that increasingly influence repeat purchasing decisions in healthcare environments. For businesses, the strategic implication is clear: performance claims must be backed by active approvals and demonstrable test alignment, and product roadmaps should anticipate overlaps between respirator and surgical mask requirements as institutions consolidate purchasing categories.
Regulatory and Policy Environment
Policy frameworks are moving from emergency-era flexibility toward more structured oversight and procurement incentives. FDA draft guidance for FY2025 on enforcement discretion policy for premarket and other requirements for NIOSH-approved air purifying respirators signals an effort to clarify how compliance expectations will be applied in routine market conditions. NIOSH's conformity assessment activity, including the September 2025 voluntary rescission of approvals for multiple major manufacturers, underscores that approval status can change quickly and that manufacturers must maintain rigorous quality system discipline. On the procurement side, CMS proposals related to equitable adjustment authority for domestic N95 respirator costs and the January 2026 advance notice of proposed rulemaking on domestic PPE procurement incentives point toward financial and policy mechanisms that may favor domestic production in certain purchasing pathways. These developments do not erase global supply chains, but they introduce a new layer of strategic planning. Companies that can demonstrate stable approval status, transparent compliance documentation, and flexible sourcing options will be better positioned to navigate both regulatory scrutiny and procurement preference shifts.
PW Consulting
Demand-Side Behavior and Institutional Purchasing
End-user behavior has shifted from reactive stockpiling to more disciplined, specification-driven purchasing. Healthcare remains the dominant application arena, reflecting continued emphasis on staff protection, infection control protocols, and standardized procurement in clinical settings. Industrial and other application segments contribute meaningful demand, but the commercial center of gravity remains in environments where compliance documentation, batch traceability, and performance consistency are non-negotiable. Procurement teams are increasingly evaluating suppliers on the stability of their approval portfolios and the resilience of their supply commitments rather than on short-term price advantages alone. This shift favors manufacturers that can provide clear certification status, predictable lead times, and product lines that match multiple procurement specifications. It also creates an opening for intermediaries and verification-focused organizations that help buyers navigate approval status, sourcing authenticity, and specification matching. Project N95's role in vetting, sourcing, and distributing respirators from approved manufacturers reflects a broader market need for trusted validation pathways, especially when procurement decisions must balance speed, compliance, and supply assurance.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by the interaction of raw material availability, manufacturing geography, and compliance-related operating costs. Domestic capacity expansion is one visible response to supply assurance concerns and procurement preference signals. 3M's opening of a new N95 respirator manufacturing facility in North Carolina in March 2025 illustrates a strategic move to increase domestic production capacity for medical protective masks, reducing dependence on distant supply nodes and improving responsiveness to regional demand fluctuations. At the same time, manufacturers with strong positions in Asian production networks are pursuing market-facing visibility and certification breadth to maintain competitiveness. The broader cost picture is not simply about labor arbitrage; it is increasingly about the total cost of maintaining approval status, meeting updated standards, and satisfying procurement rules that may favor localized supply. Businesses that treat supply chain design as a compliance and responsiveness issue, rather than purely a cost-minimization exercise, are more likely to sustain margin stability through regulatory and demand shocks.
Competitive Landscape and Leading Strategies
The competitive field combines established multinational manufacturers, specialized respirator producers, and sourcing and verification platforms that help institutional buyers navigate approval and authenticity concerns. Leading participants are pursuing distinct strategic positions that reflect their manufacturing base, certification coverage, and go-to-market focus.
Several U.S.-based manufacturers hold active NIOSH approvals and emphasize respirator product lines with surgical variants. 3M Company produces N95 respirators including surgical variants and the 9205+ Aura series, and has reinforced its domestic production posture through new facility investment. Honeywell International Inc. manufactures N95 respirators and surgical N95 variants while maintaining active NIOSH approvals, positioning around recognizable brand trust and institutional procurement familiarity. Kimberly-Clark Corporation produces N95 respirators and surgical masks with active NIOSH approvals, leveraging broader health and hygiene commercial infrastructure to support distribution and buyer relationships. DemeTech Corporation manufactures N95 respirators and surgical masks with ASTM Level 3 compliance and holds active NIOSH approvals, emphasizing specification alignment for higher-barrier surgical use cases. These players share a common strategic thread: maintaining active approvals, expanding or protecting domestic capacity where advantageous, and aligning product lines with procurement categories that value both respiratory protection and fluid-resistance performance.
International manufacturers are competing through certification breadth, model variety, and regional market presence. Makrite produces surgical N95 respirators, ASTM Level 1-3 surgical masks, and KN95/FFP2 variants, with active NIOSH, CE, and other certifications. Its exhibition activity at Tool Japan 2025 reflects a market-facing strategy that emphasizes cross-variant availability and direct engagement with procurement and distribution channels. Harley Commodity produces surgical N95 respirators with adjustable head straps and holds active NIOSH approvals and FDA clearance, focusing on fit-oriented design and compliance documentation that supports institutional purchasing requirements. These companies illustrate how non-domestic producers can remain relevant by combining certification coverage with product features that address wearability, specification range, and channel visibility.
A separate but important part of the landscape is occupied by verification and distribution intermediaries such as Project N95, which vets, sources, and distributes N95 respirators and KN95 masks from approved manufacturers. This model addresses a persistent market need: buyers want to reduce the risk of sourcing non-conforming products and need practical pathways to approved supply. The presence of such organizations indicates that trust and verification are becoming more valuable as compliance scrutiny intensifies and procurement teams seek to reduce administrative and product-risk burdens.
The market structure is evolving along three directions. First, consolidation pressure exists where scale, approval maintenance, and distribution reach create advantages, particularly in healthcare procurement where supplier reliability is heavily weighted. Second, differentiation is increasing among manufacturers that can combine approval stability with product features such as fit adjustment, surgical compatibility, or multi-standard coverage. Third, new-entry and intermediary activity is likely to persist where verification, sourcing transparency, and regulatory navigation offer commercial value. The overall effect is a market that rewards compliance discipline and supply reliability as much as production volume.
Future Trends and Commercial Opportunities
Looking toward the next three to five years, several trends are likely to shape commercial outcomes. The first is a more formal separation between emergency-surge purchasing and routine procurement. As policy frameworks settle into structured oversight and domestic sourcing incentives, buyers will likely standardize around suppliers that can demonstrate steady approval status, consistent documentation, and resilient supply. This creates opportunity for manufacturers that invest early in quality system robustness, approval maintenance, and transparent communication about certification status. It also raises the importance of portfolio planning so that product offerings match the specifications most likely to be required in routine healthcare and institutional purchasing.
The second trend is the widening role of standards and verification as commercial differentiators. Updated mask performance standards and ongoing conformity assessment activity increase the value of demonstrable compliance. Companies that can align product design, testing, and documentation with current requirements will face fewer market-access frictions and will be better positioned to serve buyers who must justify purchasing decisions through compliance evidence. Verification-focused intermediaries and platform models may also gain stature as buyers look for reduced-risk sourcing pathways, especially when approval status or product origin must be confirmed quickly.
The third trend is geographic and supply chain reconfiguration. Domestic capacity investments and procurement incentive signals suggest that regional supply resilience will become a more important part of commercial positioning. This does not mean global production will disappear, but it does mean that dual-sourcing strategies, regional backup capacity, and procurement-channel alignment will matter more than in the pre-2020 era. Businesses that can offer supply flexibility while maintaining approval integrity will be better placed to capture demand from buyers who are balancing cost, compliance, and continuity.
These trends carry commercial opportunities for different players. Manufacturers can pursue portfolio breadth that covers respirator and surgical needs, invest in approval maintenance and testing alignment, and develop supply-chain flexibility that supports both domestic and export channels. Investors can focus on companies with stable certification positions, credible compliance infrastructure, and credible pathways to benefit from domestic procurement preference shifts. Procurement organizations can reduce risk by prioritizing suppliers with transparent approval status, diversified sourcing options, and documentation that supports audit and compliance requirements. At the same time, uncertainty remains. Approval rescissions, evolving enforcement discretion guidance, and changes in reimbursement or procurement incentive rules can alter competitive positioning quickly. Businesses should therefore treat compliance status and sourcing flexibility as living strategic assets rather than fixed advantages.
Medical Face Masks Market
Strategic Actions for Decision-Makers
For manufacturers, the priority is to treat certification and compliance as core commercial infrastructure. Maintaining active approvals, aligning products with current standards, and communicating approval status clearly can reduce market-access risk and improve buyer confidence. Portfolio planning should anticipate overlap between respirator and surgical mask requirements, since many institutional buyers prefer suppliers that can serve multiple specifications without fragmenting the supply base. Supply chain design should incorporate regional flexibility where possible, both to respond to procurement preference signals and to improve continuity during disruption. Companies that combine technical credibility with supply resilience are more likely to secure recurring institutional demand.
For investors, due diligence should place significant weight on approval stability, quality system maturity, and exposure to regulatory or procurement shifts. Revenue growth potential is important, but in a market where approval status can change and compliance costs can rise, the durability of a company's certification portfolio and its ability to maintain supply under scrutiny may be equally decisive. Preference should be given to businesses that demonstrate clear compliance documentation, diversified product coverage, and realistic pathways to benefit from domestic sourcing incentives without overconcentrating risk in a single channel or geography.
For procurement leaders and institutional buyers, the strategic imperative is to move from transactional sourcing to supply assurance planning. That means evaluating suppliers on approval continuity, documentation transparency, and the ability to provide consistent product across respirator and surgical categories where needed. Diversification of approved sources, attention to standard updates such as EN 14683:2025, and alignment with procurement incentives that may favor domestic supply can reduce both compliance and continuity risk. Verification support from trusted intermediaries can also help reduce the administrative burden of confirming approval status and product authenticity.
Detailed segmentation data, company-level benchmarking, and scenario-based procurement guidance can materially improve the speed and quality of these decisions. The broader market trajectory is clear enough to justify strategic action, but the value of any specific move depends on precise figures, approval-status mapping, and procurement-context nuance that vary by region, application, and buyer type. Readers seeking deeper segmentation detail, competitive benchmarking, and customized sourcing or investment implications can access the full PW Consulting market research report for comprehensive data and tailored analysis supporting the strategic directions outlined here.
For detailed analysis of this topic, please visit the official page: Medical Protective Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dock Levelers Market CAGR 5.7%: What's Fueling the $257.5M Growth to 2032
By pmarketresearch, 2026-09-21
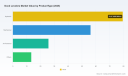
Dock Levelers Market: Strategic Trends and Commercial Opportunities Through 2032
The dock leveler market sits at a critical intersection of logistics infrastructure, workplace safety, and material handling efficiency. As loading docks remain the primary interface between indoor storage and external transportation networks, the equipment that bridges this gap has evolved from a purely mechanical accessory to a regulated, performance-driven component of facility design. Market trajectories over the past half-decade and projections through the end of the decade point to steady expansion, but the growth is neither uniform nor automatic. Stakeholders who understand the shifting technological baselines, regulatory tightening, and end-user operating models will be better positioned to capture margin, market share, or strategic acquisition value.
Market Snapshot and Core Challenges
The dock levelers market has demonstrated consistent expansion from 2020 through 2025, with a base-year valuation that reflects decades of incremental modernization across warehousing and industrial facilities. Over the historical period, revenue climbed steadily as replacement cycles, new construction, and retrofitting activity combined to sustain demand. Looking ahead through 2032, the market is projected to maintain a compound annual growth rate of 5.7%, translating into a meaningful uplift in cumulative revenue over the forecast window. This trajectory reflects a maturing industry where baseline demand is supported by broad infrastructure needs, but incremental growth is increasingly tied to specification upgrades, safety compliance, and regional industrialization patterns.
A few structural realities define the market's current posture. First, concentration is moderate rather than dominant. The top three players hold roughly a third of aggregate revenue, while the top five account for just under two-fifths. This leaves substantial room for specialized manufacturers, regional specialists, and channel-focused integrators to compete without requiring massive scale. Second, the market's expansion is uneven across product architectures and end-use contexts, with hydraulic solutions commanding the largest revenue share, mechanical systems retaining strong relevance where cost and simplicity matter, and air-powered or niche variants serving more targeted applications. Logistics and warehousing facilities represent the largest end-user base, while manufacturing and retail environments contribute meaningful but differentiated demand profiles. Regional patterns are similarly differentiated, with Asia Pacific capturing the largest absolute revenue contribution, followed by Europe and North America, while Latin America and the Middle East and Africa reflect smaller but strategically important footprints.
- The industry is navigating a transition from commoditized hardware sales to specification-driven, compliance-aligned installations.
- Replacement and retrofit activity is becoming a larger share of demand as existing dock infrastructure ages in developed markets.
- Price competition in mechanical and entry-level hydraulic segments pressures OEMs to differentiate through durability, service, and compliance credentials rather than unit cost alone.
Key Drivers Reshaping the Market
Technology Innovation and Performance Baselines
Product architecture continues to be the most visible driver of market differentiation. Hydraulic dock levelers remain the dominant revenue category, favored for their lifting capacity, operator convenience, and adaptability to a wide range of truck bed height variations. At the same time, recent product launches illustrate how even established categories are being refined. In mid-2025, new hydraulic dock leveler models were introduced by major brands, signaling a market-wide push toward installer-friendly features, standardized performance benchmarks, and more predictable maintenance characteristics. Mechanical systems retain competitive advantages in environments where electrical infrastructure is limited or where lower acquisition cost is prioritized. Air-powered and specialty variants address narrower use cases but benefit from ongoing improvements in actuation reliability and sealing performance.
PW Consulting Automotive & Machinery Research Center
Material choices also matter more than they did in earlier cycles. High-strength steel and notched plate constructions have become central to dock leveler build specifications, reinforcing structural resilience under repeated loading cycles and harsh operating conditions. These material and design choices are not merely engineering details; they directly influence service life, downtime frequency, and total cost of ownership, which increasingly drive specification decisions by facility managers and engineering teams.
Regulatory and Standards Environment
Regulatory pressure is accelerating the shift toward certified, safety-oriented equipment. Standards such as ANSI MH30.1-2022 provide uniform design and testing guidelines for dock leveling devices, giving facility owners, integrators, and insurers a clearer baseline for specification and procurement. In practice, this means dock levelers are increasingly evaluated not just on load capacity but on conformance to recognized testing protocols, energy-saving behaviors, and integration with broader dock safety systems. Stricter workplace safety expectations under OSHA and related compliance frameworks further encourage adoption of equipment that demonstrably reduces exposure to loading dock hazards, including trailer creep, unintended movement, and edge-of-dock incidents.
This regulatory environment creates a dual effect. For buyers, it adds weight to the case for higher-specification, certified products rather than bare-minimum hardware. For manufacturers, it raises the bar for product documentation, testing rigor, and installer support, but also strengthens the value proposition of equipment that can be presented as compliant by design rather than by retrofit.
Demand-Side Shifts in Operations and Building Use
The way facilities operate is reshaping equipment requirements. Modern logistics and warehousing facilities increasingly emphasize throughput, dock utilization, and labor efficiency. Dock levelers that integrate cleanly with door operators, vehicle restraints, and traffic flow design are more attractive because they reduce installation friction and improve day-to-day uptime. In retail and distribution settings, frequent trailer turnover and variable vehicle heights make consistency and ease of use especially important. Meanwhile, manufacturing environments often place higher structural and duty-cycle demands on levelers, reinforcing demand for heavy-duty configurations and robust material builds.
Operational expectations are also shifting the conversation around energy and safety. Facilities are more attentive to dock sealing, air infiltration, and the interaction between levelers and dock doors, not only for operational comfort but for energy performance and compliance. Equipment that contributes to safer trailer engagement and reduces incidental energy loss has a stronger narrative in specifications, particularly in organizations with formalized safety programs and sustainability targets.
Supply Chain and Cost Structure Dynamics
Input costs, lead times, and manufacturing location strategies continue to influence competitive positioning. Steel-based construction remains central to dock leveler production, and commodity dynamics can affect margin structure and pricing flexibility across the value chain. Manufacturers with stable supply arrangements, efficient fabrication workflows, and strong domestic production footprints can respond more predictably to demand fluctuations. Integration within larger industrial equipment groups also shapes market behavior, as corporate ownership can provide access to broader distribution channels, cross-selling opportunities, and more structured aftermarket service networks.
Loading Dock Equipment Market
At the same time, the market remains accessible enough that regional manufacturers and specialized brands can compete effectively, especially where local installation ecosystems, service responsiveness, and application-specific expertise matter more than global scale. This balance helps sustain innovation and optionality, but it also means pricing and positioning can vary noticeably across geographies and customer segments.
Competitive Landscape and Strategic Positioning
The competitive set is anchored by established manufacturers with distinct positioning across product breadth, application focus, and ownership structure. Some players have built reputations around hydraulic, air-powered, mechanical, and edge-of-dock portfolios, often emphasizing domestic manufacturing and broad availability. Others differentiate through vertical-storing concepts, dock lifts, or applications tailored to retail and distribution clients at scale. A subset of manufacturers focuses on edge-of-dock levelers and complementary material handling equipment, appealing to facilities that prioritize simpler mechanical solutions or specific installation constraints. There are also brands known for advanced safety and energy-saving features, which align with the compliance and operational-efficiency themes increasingly valued by facility owners.
A notable competitive development is the pattern of product refinement rather than radical category disruption. Recent mid-2025 introductions of new hydraulic dock leveler models from major brands illustrate the direction of travel: improved installer features, clearer certification alignment, and more defined model families. This suggests competition is increasingly won through specification support, service reliability, and product clarity as much as through raw hardware performance.
Hydraulic Dock Leveler Market
- OEMs with broad product ranges can capture more fixture points across multiple facility types and replacement cycles.
- Manufacturers emphasizing safety certifications, energy performance, and installer-friendly design can command stronger positioning in compliance-conscious procurement processes.
- Companies with strong retail, warehousing, or industrial customer relationships benefit from repeat specification influence and visibility into end-user operating requirements.
- Regional manufacturers and niche specialists can compete by focusing on service speed, application customization, and local integration partnerships rather than attempting to match global breadth.
The industry is also experiencing gradual consolidation and channel maturation rather than abrupt market disruption. Larger industrial groups can leverage broader portfolios and service networks, while specialized brands retain relevance where they solve particular installation or application problems well. New entrants face a meaningful barrier in installation expertise, compliance documentation, and aftermarket support, which means credible growth often comes through acquisition, channel expansion, or focused geographic and application specialization. The result is a landscape where scale, differentiation, and service capability each matter, and no single dimension is sufficient on its own.
Outlook: Three Trend Lines to Watch Through 2032
Compliance and specification intensity will keep rising
Dock levelers are increasingly specified as part of a broader safety and performance package rather than as standalone hardware. As standards and workplace safety expectations continue to sharpen, procurement processes are likely to place greater weight on certification alignment, testing documentation, and compatibility with dock safety systems. This favors manufacturers that can make compliance easy to verify and installers that can demonstrate consistent execution. The commercial implication is that equipment which can be presented as compliant by design will have stronger stickiness in repeat business and replacement cycles, while bare-minimum offerings may face growing pressure in specification-led environments.
Performance differentiation will shift toward total cost of ownership and uptime
As the market expands at a moderate pace, competitive advantage will depend less on headline price and more on uptime, serviceability, and durability over the installed life of the equipment. Energy interaction, mechanical reliability, ease of maintenance, and reduced downtime during installation or service will increasingly drive purchasing decisions, especially in high-utilization logistics and manufacturing environments. This trend opens room for products that balance hydraulic performance with practical installer and maintenance considerations, and for brands that can support facilities with reliable service networks and clear specification guidance.
Regional demand will remain uneven but strategically significant
While the largest absolute revenue contributions are expected from regions with advanced logistics infrastructure and substantial industrial activity, growth opportunities will differ by market maturity. In developed markets, replacement, modernization, and safety-driven retrofitting are likely to be important growth engines. In developing and industrializing regions, new facility construction and expanding distribution networks can support incremental demand, though pricing sensitivity and specification expectations may vary. Firms that can navigate these differences through appropriate product mix, local support, and application-specific positioning will be better placed to convert regional opportunity into durable revenue.
These trends are not risk-free. Regulatory interpretation can shift, and standards may evolve in ways that change specification requirements. Supply chain volatility in steel and fabricated components can affect cost structures and lead times, particularly if demand accelerates faster than capacity adjustments. In addition, the market's moderate concentration means competitive responses can be swift in price-sensitive segments, which can compress returns for manufacturers that fail to differentiate clearly. Operators should therefore treat growth as achievable but contingent on product clarity, compliance readiness, service capacity, and regional execution.
Actionable Guidance for Decision Makers
For manufacturers and brand leaders
- Strengthen specification support around recent product introductions by emphasizing installer features, certification alignment, and maintenance predictability, not just load capacity or product range.
- Invest in service and aftermarket capability as a differentiator, since uptime and response quality increasingly influence repeat specification in logistics and manufacturing environments.
- Develop clear product narratives for compliance and energy interaction where relevant, so that facilities can justify selection on safety, performance, and operating cost rather than initial purchase price alone.
For investors and strategic acquirers
- Focus on businesses with durable specification relationships, recurring replacement demand, and the ability to support compliance-led procurement rather than purely transactional hardware sales.
- Evaluate exposure to service revenue, retrofit activity, and regional installation ecosystems, since these often shape margin stability more than new-unit volume alone.
- Watch for consolidation patterns that could combine portfolio breadth, distribution reach, and service scale, especially where corporate ownership can accelerate cross-selling and operational efficiency.
For procurement and facility decision makers
- Treat dock leveler selection as part of a broader dock safety and operational-performance decision, coordinating with door systems, vehicle restraint strategies, and facility traffic design to reduce installation friction and improve long-term uptime.
- Use standards alignment and documented testing as a practical filter in specification, especially where safety programs, insurance expectations, or compliance responsibilities are significant.
- Balance acquisition cost against total cost of ownership by evaluating durability, maintenance requirements, installer support, and compatibility with existing dock infrastructure before finalizing specifications.
The market's next several years will reward participants who can connect product performance to operational outcomes, compliance expectations, and regional realities. Detailed segmentation data, company-level financial signals, regulatory timelines, and application-specific demand patterns can sharpen these decisions considerably, and that level of granularity is where a focused market study adds the most value. Readers looking for deeper breakdowns across product types, end users, regional dynamics, and competitive detail can use the insights here as a starting point for a more comprehensive review of the full report and supporting data.
For detailed analysis of this topic, please visit the official page: Dock Levelers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beyond 4.12% CAGR: Unpacking the Real Drivers of the Chlorinated Paraffin Market’s 2032 Trajectory
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Chlorinated Paraffin Market
Market Snapshot and Critical Inflection Points
The chlorinated paraffin market has demonstrated steady expansion over the 2020–2025 period, reaching approximately 2,075 million USD in 2025, up from 1,725 million USD five years earlier. The trajectory reflects consistent demand growth across downstream industrial sectors, supported by the material's versatile role as a secondary plasticizer, extreme-pressure additive, and flame retardant. Looking ahead to the forecast horizon through 2032, the market is projected to grow at a compound annual growth rate of 4.12 percent, rising toward 2,753 million USD by the final year of the outlook period. This expansion rate points to a market that is maturing but not stagnant, with growth increasingly dependent on selectivity in applications and regions rather than broad-based volume increases.
Several structural features of the current market warrant close attention from decision-makers. Market concentration data indicates that the top three players collectively command roughly 45 percent of global revenue, while the top five reach approximately 68 percent. This concentration level implies that a limited number of established producers hold significant sway over pricing dynamics, capacity allocation, and product standardization. At the same time, the long-tail presence of regional and specialty manufacturers creates a fragmented periphery where niche positioning remains viable. For new entrants or expanding players, this landscape presents a dual reality: barrier to scale are real, but fragmentation leaves room for targeted moves in specific value chains or geographies.
Beyond concentration patterns, the industry is navigating three critical inflection points that will define the next phase of growth. The first is the regulatory recalibration around chlorinated paraffin categories. Medium-chain chlorinated paraffins have been listed under Annex A of the Stockholm Convention for elimination from production and use in the European Union, marking a decisive shift in the treatment of this segment within one of the world's most influential chemical markets. Short-chain variants remain under restricted conditions in the United States, with the Environmental Protection Agency continuing risk management processes under TSCA. These regulatory developments are not uniformly global in timing or scope, but they create a patchwork of compliance obligations that complicate sourcing strategies, product specifications, and market access planning.
The second inflection point lies in raw material cost volatility and its transmission through the value chain. Feedstock costs for paraffin wax rose noticeably in the fourth quarter of 2025, pushing Northeast Asia chlorinated paraffin prices to approximately 0.66 USD per kilogram. The increase was supported by firmer upstream paraffin wax and chlorine feedstock costs that raised production expenses for manufacturers in the region. However, this cost pressure was followed by a reversal in early 2026, when heightened environmental scrutiny on chlorinated paraffins dampened downstream consumption activity in Northeast Asia, contributing to a price decline to roughly 0.60 USD per kilogram. This sequence illustrates how quickly the market can swing between cost-driven price increases and demand-driven corrections, especially in regions where regulatory sentiment and end-user confidence are closely intertwined.
The third inflection point is capacity expansion in response to perceived demand resilience. In June 2025, Lords Chloro Alkali Limited announced an expansion of its chlorinated paraffin wax production capacity from 50 tonnes per day to 100 tonnes per day at its Rajasthan facility. The move was positioned to meet rising demand from plastics, rubber, coatings, and metalworking industries. Such expansions signal that producers see durable application pull, particularly in markets where alternatives face performance or cost limitations. Yet, capacity additions also raise questions about whether incremental supply will outpace demand growth in certain segments, particularly if regulatory constraints or substitution dynamics narrower the addressable market faster than anticipated.
Core Drivers Shaping Market Trajectory
The market's direction is being shaped by a combination of technological, regulatory, demand-side, and supply-side forces. Understanding how these drivers interact is essential for anticipating where growth will be most concentrated and where risk will accumulate.
Technological Innovation and Product Differentiation
Innovation in chlorinated paraffins is increasingly focused on performance stability, application specificity, and compatibility with evolving downstream formulations. Manufacturers are working to improve the consistency of chlorination levels, reduce impurity profiles, and develop stabilized or sulphochlorinated variants that perform reliably under the thermal and mechanical stresses of modern processing. These enhancements matter because downstream users in plastics compounding, rubber formulation, and metalworking fluids are under pressure to meet tighter performance specifications while managing material costs. Products that can deliver better dispersion, lower volatility, or improved resistance to degradation under processing conditions offer a tangible value proposition beyond price alone.
Paraffin Wax Market
At the same time, innovation is also occurring in the broader materials context, where alternatives such as non-chlorinated plasticizers, phosphate-based flame retardants, and bio-derived additives are gaining ground in certain applications. This dynamic pushes chlorinated paraffin producers to sharpen their technical positioning rather than compete solely on volume. Those that can demonstrate superior performance in specific use cases, such as extreme-pressure lubrication under high load or flame retardancy in PVC compounds where regulatory acceptance remains more favorable, are better equipped to defend share and command premium positioning.
Policy and Regulatory Environment
The regulatory environment is perhaps the most consequential driver shaping near-term strategy. The listing of medium-chain chlorinated paraffins under the Stockholm Convention's Annex A for elimination in the European Union represents a significant policy shift. It signals that jurisdictions with strong environmental governance are willing to target specific chlorinated paraffin categories even as other segments remain in use. This layered regulatory approach creates a complex operating environment where product classification, chain of custody, and end-use declaration become increasingly important for market access.
In parallel, short-chain chlorinated paraffins continue to face restrictions in the United States under TSCA, with the EPA maintaining ongoing risk management activities. While the regulatory treatment differs between regions and categories, the broader trajectory points toward greater scrutiny of chlorinated compounds, especially where persistence, bioaccumulation, or toxicological concerns are raised. For businesses, the implication is not that the entire market is under uniform threat, but that regulatory exposure varies by chain length, geography, and application. Companies that rely on a single product category or a narrow geographic footprint face heightened vulnerability if regulations shift in their core markets.
Demand-Side Shifts in End-Use Industries
Downstream demand is evolving as end-use industries balance performance requirements, cost pressures, and sustainability expectations. In plastics and rubber, chlorinated paraffins continue to serve as cost-effective secondary plasticizers and processing aids, particularly where PVC formulations require flexibility and flame retardancy without resorting to higher-cost alternatives. The metalworking fluids and lubricants segment remains important as well, given the material's established role as an extreme-pressure additive that reduces friction and wear under demanding operating conditions. These applications benefit from well-understood performance characteristics and long-standing formulation familiarity among end users.
However, demand patterns are also being influenced by end-users' increasing attention to regulatory compliance and supply chain transparency. Buyers in coatings, adhesives, and industrial lubricants are more likely to request documentation regarding product classification, regional compliance status, and handling requirements. This creates an advantage for suppliers that can provide clear technical data sheets, compliance statements, and application-specific guidance. Conversely, suppliers that cannot respond to these information demands risk losing visibility in customer qualification processes, particularly in regions where regulatory and procurement standards are tightening.
Chlorinated Polyolefin Market
Supply Chain and Cost Structure Dynamics
The cost structure of chlorinated paraffin production is closely linked to the availability and pricing of paraffin wax and chlorine feedstocks. When feedstock costs rise, producers face pressure to pass through increases or absorb them in margin compression. The late-2025 price movement in Northeast Asia, driven by firmer upstream costs, shows how quickly feedstock conditions can affect realized pricing. The subsequent early-2026 decline, tied to reduced downstream consumption under environmental scrutiny, illustrates that cost-side pressures do not automatically translate into sustained price gains if demand sentiment weakens.
Supply chain considerations also extend to logistics, regional production footprint, and the ability to serve customers with consistent quality and timing. Producers with integrated or proximate feedstock access, flexible operational setups, and well-distributed customer service networks are better positioned to manage cost volatility and maintain reliability. In contrast, producers that depend heavily on long-distance feedstock flows or operate in regions with pronounced regulatory uncertainty may find it harder to compete on both cost and availability. As capacity expansions come online, the balance between localized supply advantages and global price convergence will become an important strategic variable.
Competitive Landscape and Leading Strategies
The competitive environment in chlorinated paraffins is characterized by a mix of large established producers, regional specialists, and application-focused manufacturers. The leading companies have built their positions not simply on scale, but on product range breadth, application know-how, and the ability to serve specific verticals with tailored formulations.
Dover Chemical Corporation, based in Dover, Ohio, has focused on liquid chlorinated alkanes and other chlorinated paraffins under the Paroil® brand, with emphasis on medium- and long-chain products used as plasticizers, flame retardants, and extreme-pressure additives in metalworking fluids and lubricants. This application-oriented framing allows the company to align its offerings with the operational needs of lubricant and metalworking fluid formulators, where extreme-pressure performance and additive compatibility are critical. INEOS Chlor, operating from Runcorn in the United Kingdom, offers the Cereclor range of medium- and long-chain chlorinated paraffins for similar end uses, reinforcing the importance of long-standing product lines in lubricants, metalworking fluids, and polymer applications. The presence of multiple global players emphasizing medium- and long-chain variants reflects a strategic preference for segments where regulatory exposure and performance acceptance can be more manageable than in the short-chain category.
PW Consulting Chemical & Energy Research Center
Caffaro Industrie S.p.A., headquartered in Torviscosa, Italy, produces Cloparin®, Cloparol®, and Cloparten® chlorinated paraffins covering normal, stabilized, and sulphochlorinated variants for plastics, metalworking, and tanning applications. The breadth of product types and application coverage demonstrates a strategy centered on serving multiple industries with differentiated formulations. JSC Kaustik, one of the larger Russian producers, manufactures a wide portfolio of chlorinated paraffin waxes, including CP-30, CP-52, CP-250, CP-418, and CP-470A, used as secondary plasticizers in PVC compounds and other polymers. This scale and product range underscore the significance of regional production hubs that can serve polymer compounding markets with cost-competitive and specification-diverse offerings.
Aditya Birla Chemicals, based in Mumbai, India, operates as an integrated producer of chlorinated paraffins within a broader specialty chemicals portfolio, targeting plastics, rubber, and flame-retardant applications. Integration within a larger chemicals platform can provide feedstock linkages, financial scale, and market access advantages. LEUNA-Tenside GmbH, Altair Chimica SpA, and Química del Cinca S.A. add further regional depth, each supplying chlorinated paraffins and related chemistries for lubricants, metalworking fluids, polymer compounds, rubber, and plastics. Their presence highlights the role of European and Mediterranean-based manufacturers in meeting regional demand with application-specific products and technical support.
In Asia and other growth regions, KLJ Group in Mumbai and NCP Chlorchem (Pty) Ltd in Port Elizabeth, South Africa, illustrate the continued importance of producers positioned to serve industrial chemical markets with flame retardants, plasticizers, lubricants, and metalworking fluid applications. These companies benefit from proximity to end-use industries and the ability to respond to regional demand patterns, though they also face the same feedstock and regulatory considerations as larger global players.
The competitive landscape is evolving along several axes. First, consolidation pressure exists at the top of the market, where larger players with broader product portfolios and stronger technical service capabilities can capture share from smaller competitors that lack differentiation. Second, regional divergence is increasing, as regulatory differences and feedstock availability create distinct competitive conditions in Europe, North America, Asia Pacific, Latin America, and Africa. Third, new entrants and expanding producers, such as the capacity increase announced by Lords Chloro Alkali Limited, are betting on demand growth in plastics, rubber, coatings, and metalworking sectors. Whether such moves translate into durable share gains will depend on how well new capacity aligns with the segments that remain most commercially viable under evolving regulation.
Leading strategists in this market tend to focus on three differentiators. The first is application-specific value delivery, where products are positioned not as generic commodities but as solutions for extreme-pressure lubrication, PVC plasticization, or flame retardancy in specified formulations. The second is regulatory readiness, including the ability to classify products accurately, provide compliance documentation, and guide customers through regional requirements. The third is supply reliability and feedstock management, which becomes increasingly important as cost volatility and capacity changes reshape the competitive balance. Companies that combine these strengths are better placed to navigate a market where growth is uneven and regulatory interpretation varies by jurisdiction.
Forward-Looking Trends and Commercial Opportunities
Looking toward the next three to five years, several trends are likely to shape where opportunity concentrates and where risk accumulates. These trends are not independent; they interact with feedstock costs, regulatory developments, and end-use demand in ways that will determine which segments outperform.
Shift Toward Medium- and Long-Chain Positioning
The trend toward greater regulatory scrutiny of certain chlorinated paraffin categories is likely to reinforce a strategic shift toward medium- and long-chain products in markets where these variants retain clearer acceptance. This does not mean short-chain products will disappear across all geographies, but it does suggest that commercial emphasis will increasingly tilt toward segments with more favorable regulatory profiles and established performance roles in metalworking fluids, lubricants, and selected polymer applications. For producers and investors, the opportunity lies in strengthening product lines, technical documentation, and application support for these categories, while carefully managing exposure to categories facing elimination or restriction in key markets.
Regional Divergence and Market Fragmentation
Regulatory and cost conditions are unlikely to move uniformly across regions. Divergence between Europe, North America, Asia Pacific, and other regions will create pockets of opportunity where demand remains robust and regulatory pathways are clearer. Asia Pacific, as a large and diverse region, will continue to be significant, but the pace and direction of growth may vary by country and by application as environmental scrutiny and feedstock conditions evolve. This fragmentation rewards companies that build regional competencies, adapt formulations to local requirements, and maintain flexible sourcing and distribution networks. It also creates risks for businesses that assume a single global strategy will work across all markets without adjustment.
Performance-Led Differentiation Over Pure Volume Competition
As feedstock costs fluctuate and regulatory expectations rise, competition on price alone becomes riskier and less sustainable. The trend is toward performance-led differentiation, where suppliers compete on functional benefits such as extreme-pressure performance, stability under processing conditions, compatibility with complex formulations, and support for customer compliance needs. This shift opens commercial opportunities for companies that invest in technical service, application testing, and formulation guidance. It also suggests that customers will increasingly reward suppliers who reduce uncertainty in the qualification process, particularly in industries where downtime, rework, or compliance failures carry significant cost.
These trends carry potential risks. If capacity expansions outpace demand growth in specific segments, price competition could intensify and compress margins. If regulatory measures extend to additional categories or tighten in important end-use markets, demand could shift faster than producers can adapt. If alternative materials improve in cost-performance balance, substitution pressure could erode share in applications that have historically relied on chlorinated paraffins. Monitoring these risks requires close attention to feedstock pricing, regulatory timelines, and downstream formulation trends, rather than relying on aggregate market growth figures alone.
Actionable Guidance for Decision-Makers
Different roles within the market face distinct strategic priorities, but all benefit from clearer visibility into where growth is durable and where exposure is rising. The following recommendations are intended to help manufacturers, investors, and procurement teams orient their decisions in a market that is steady in aggregate but uneven in detail.
-
For manufacturers and producers, prioritize application-specific positioning and regulatory readiness. Develop clear documentation and technical support for medium- and long-chain products where regulatory acceptance is more favorable, and ensure that product classification and compliance statements are precise enough to support customer qualification in multiple regions. Evaluate whether capacity expansion plans align with segments that retain demand momentum under current regulatory trajectories, rather than relying on broad volume growth assumptions. Feedstock sourcing and regional production footprint should be reviewed for resilience against cost volatility and logistics disruption.
-
For investors and strategic planners, focus on differentiation quality rather than headline market size. The market's projected growth trajectory is positive, but value creation will likely accrue to players that can defend application niches, manage regulatory complexity, and maintain cost discipline. Assess exposure by chain length, geography, and end-use, and weigh the risk of substitution and regulatory tightening in specific segments. When evaluating expansion or consolidation moves, consider whether the target's competitive advantage rests on product range breadth, technical service capability, feedstock integration, or regional market access, because these factors will determine durability in a fragmented and evolving landscape.
-
For procurement and supply chain leaders, treat supplier selection as a risk-management decision as much as a cost decision. Request product classification clarity, regional compliance status, and application-specific performance data, especially for uses subject to tighter regulatory or quality requirements. Diversify sourcing where possible to reduce reliance on a single region or supplier type, and monitor feedstock-driven price movements and demand sentiment shifts that can affect availability and cost over short time horizons. Building stronger technical dialogue with suppliers can also improve formulation stability and reduce the risk of qualification delays.
The chlorinated paraffin market is at a point where aggregate growth is meaningful but not sufficient to guide detailed decisions. Chain-length dynamics, regulatory divergence, feedstock volatility, and application-specific demand are shaping a landscape in which strategic positioning matters more than ever. There is substantial value in accessing more granular data on regional demand patterns, segment-level revenue splits, competitive capacity moves, and regulatory timelines, particularly for teams making sourcing, expansion, or investment choices with multi-year consequences. For those seeking deeper segmentation, scenario analysis, and customized recommendations, a more detailed research resource can provide the level of specificity needed to move from broad market awareness to executable strategy.
For detailed analysis of this topic, please visit the official page: Chlorinated Paraffin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sodium Chlorite Market: Why 5.49% CAGR and Water Treatment Demand Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Sodium Chlorite Market
Sodium chlorite has steadily moved from a niche chemical intermediate to a critical enabler of modern water disinfection, industrial bleaching, and food safety processes. The market’s trajectory over the past five years reflects a broader shift toward safer disinfectants, stricter water quality mandates, and the need for reliable on-site generation chemistry. With a market valued at USD 231.3 million in 2025 and an expected climb to USD 335.9 million by 2032, the sector is expanding at a compound annual growth rate of 5.49 percent. This growth is neither accidental nor purely cyclical; it is being shaped by a combination of regulatory momentum, technological maturation, and supply-side restructuring that together create distinct strategic entry points for manufacturers, investors, and procurement leaders.
Sodium Hypochlorite Market
Behind the headline figures lies a market that is structurally bifurcated. Industrial and technical grade chemistry continues to dominate volume, driven by pulp and paper processing, textile bleaching, and large-scale disinfection systems. Food grade and potable water compliant grades, while smaller in total revenue, command higher regulatory scrutiny and often stronger pricing power where certified supply is constrained. The geographic distribution of demand further complicates the picture, with mature water infrastructure markets in Europe and North America anchoring steady consumption, while Asia Pacific reflects faster capacity additions and shifting industrial footprints. Rather than treating the market as a single block, executives should view it as a set of interconnected demand pockets, each with its own regulatory cadence, certification requirements, and supply reliability expectations.
Core Challenges and Inflection Points
The sodium chlorite market is entering a phase where growth is no longer guaranteed by end-use expansion alone. Several structural challenges are reshaping how value is created and captured.
- Raw material and energy volatility is pressuring cost structures. The electrochemical production of sodium chlorite is closely linked to sodium chlorate pricing and electricity costs. As chlorate prices have moved sharply in key production hubs, downstream manufacturers face more unpredictable input economics, which complicates long-term pricing agreements and margin planning.
- Regulatory and certification friction is raising the barrier to supply. Drinking water quality standards, NSF/ANSI certifications, and municipal approval processes are becoming more stringent and more visible. Suppliers that cannot demonstrate compliant grades, traceable manufacturing, and robust quality documentation are increasingly shut out of high-value water treatment contracts.
- Capacity realignment is creating both risk and opportunity. The industry is witnessing selective closures and targeted expansions rather than broad-based build-outs. Some producers are narrowing their chlor-alkali portfolios, while others are adding sodium chlorite-specific capacity to serve faster-growing disinfection and water treatment demand. This uneven landscape is redrawing regional availability and competitive dynamics.
These challenges matter because they alter the competitive logic of the market. Sodium chlorite is not a commodity in practice; it is a regulated, application-specific chemical where reliability, certification, and technical support often matter as much as unit price. The inflection point is that buyers and suppliers alike can no longer rely on static supply assumptions. Strategic decisions now need to account for input cost exposure, certification readiness, and the willingness of leading producers to invest in compliant capacity where demand is most regulated and most durable.
Key Drivers Shaping the Market
Technological Innovation and On-Site Generation
One of the most important demand engines for sodium chlorite is its role in chlorine dioxide generation systems. On-site generation offers water utilities and industrial operators a way to produce disinfectant close to the point of use, reducing storage risks and improving operational flexibility. This application model favors sodium chlorite suppliers that can provide consistent grades, reliable logistics, and technical integration support rather than competing solely on bulk pricing.
Technological progress is also improving the usability and safety profile of sodium chlorite in industrial settings. Better handling protocols, more standardized dosing practices, and improved compatibility with downstream generation equipment are reducing operational friction. For end users, this translates into lower total cost of ownership even when chemical prices rise. For suppliers, it opens the door to value-added positioning: certified product lines, application guidance, and dependable supply continuity become differentiators rather than extras.
Recent capacity moves by established producers underscore this shift. Expanding sodium chlorite production to support water treatment utilities adopting chlorine dioxide disinfection systems signals that manufacturers see durable demand tied to infrastructure modernization and disinfection upgrades. That kind of investment is rarely made in response to short-term price spikes; it reflects confidence in a structural application trend.
PW Consulting
Policy, Regulation, and Certification as Demand Catalysts
Regulation is not merely a constraint in this market; it is a demand shaper. Stricter drinking water quality expectations, evolving disinfection byproduct management, and municipal procurement standards are pushing utilities toward disinfectants and generation chemistries that meet higher compliance thresholds. Sodium chlorite’s relevance in potable water treatment depends heavily on certification and documented compliance, which means regulatory momentum can directly translate into incremental demand for approved grades.
Certification renewal and expansion are concrete indicators of how regulatory alignment supports commercial access. Renewed NSF/ANSI/CAN 60 certification for expanded product lines used in municipal drinking water treatment reinforces a supplier’s ability to participate in regulated water markets. In practice, these certifications function as market access credentials. They reduce procurement risk for utilities, shorten approval cycles, and increase theStrategic Trends and Commercial Opportunities in the Sodium Chlorite Market strategic value of the supplier relationship. For market participants, the implication is clear: regulatory readiness is becoming a competitive asset, not a compliance overhead.
Demand-Side Shifts in Industrial and Municipal Users
End-user behavior is changing in ways that favor reliability and service depth. Water utilities and industrial buyers are increasingly focused on supply resilience, especially where disinfection systems are integrated into critical operations. This is not simply about finding the lowest price per metric ton; it is about minimizing downtime, avoiding qualification delays, and ensuring that the chemical supplied matches the exact specifications required by generation equipment and end-use standards.
In parallel, industrial users in pulp, paper, and textiles continue to rely on sodium chlorite for bleaching and disinfection, but their purchasing logic is becoming more sophisticated. Mills and manufacturers are weighing chemical consistency, inventory buffers, and the operational impact of switching grades. Where sodium chlorite can deliver predictable performance with fewer process adjustments, it earns a stronger place in the input mix. That dynamic benefits suppliers that can prove consistency across batches and provide application-level support.
Supply Chain and Cost Structure Realignment
The supply side is undergoing a quieter but equally important transformation. Sodium chlorite economics are sensitive to upstream chlor-alkali dynamics, energy costs, and plant utilization decisions. Electricity cost volatility has already surfaced as a material factor in chlorate pricing, and because chlorate is a key input for chlorite production, the effect cascades downstream. This means cost leadership is increasingly tied to energy efficiency, plant location, and input procurement strategy rather than to scale alone.
At the same time, producers are making deliberate portfolio choices. Some are closing loosely aligned operations to streamline their chlor-alkali footprint. Others are expanding sodium chlorite capacity in regions where water treatment demand and regulatory compliance create stronger revenue visibility. The net effect is a market in which supply security is being re-evaluated. Buyers may need to qualify multiple sources, and suppliers may need to decide where to commit capital to compliant, cost-efficient capacity. This realignment creates opportunities for producers that can combine regulatory credibility with disciplined cost management.
Competitive Landscape and Leading Strategies
The competitive field in sodium chlorite is concentrated but not uniform. With a CR3 near 31.9 percent and a CR5 near 42.5 percent, the market has meaningful incumbency advantages, yet there is still room for differentiation based on grade specialization, regional presence, certification strength, and technical service. The leading companies illustrate several distinct strategic postures.
- ERCO Worldwide has positioned itself as a leading supplier of bulk sodium chlorite for on-site chlorine dioxide generation across water treatment, food safety, and industrial disinfection. Its recent production capacity expansion in North America and its decision to close sodium chlorate operations at a Manitoba site both point to a focused strategy: concentrate resources on higher-value chlorite-related demand while simplifying the broader portfolio. This suggests a company optimizing for application relevance and supply prioritization rather than trying to compete across every chlor-alkali segment.
- International Dioxcide is known as the largest producer and distributor of bulk sodium chlorite in North America under its ERCOPure™ brand, with strong EPA and ANSI/NSF credentials. Its strategic advantage lies in scale within a regulated geography, combined with the certifications that unlock municipal and industrial water applications. In a market where compliance documentation can be as decisive as price, this positioning is commercially powerful.
- OxyChem stands out as the only U.S. producer of sodium chlorite, manufacturing Purox S and OxyChlorite grades at its Wichita facility for water treatment and disinfection. Its recent NSF/ANSI/CAN 60 certification renewal for an expanded product line reinforces domestic supply credibility for municipal drinking water use. The “only U.S. producer” positioning gives it a structural role in domestic supply continuity discussions, which can be especially valuable where local content, logistics, and approval timelines matter.
- Ercros operates as the largest European manufacturer of sodium chlorite, with multiple production plants and grades tailored for potable and industrial water treatment. Its regional scale in Europe positions it well for markets where water infrastructure compliance and industrial disinfection demand intersect. In a region with mature regulatory expectations, a locally anchored supply base with multiple plants can provide resilience and responsiveness that distant suppliers struggle to match.
- Osaka Soda Co., Ltd. reflects a different application emphasis, with significant production tied to textile bleaching, disinfecting detergents, fabric softeners, and broader industrial uses. Its strategy illustrates how sodium chlorite demand can be diversified beyond water treatment into consumer-adjacent and industrial chemical applications. This diversification can cushion exposure to any single regulatory cycle while requiring strong application expertise and consistent grade control.
These profiles show that leadership in sodium chlorite is not defined solely by tonnage. It is increasingly defined by the ability to secure regulated market access, maintain supply reliability, and align capacity with the most defensible demand pockets. The competitive landscape is likely to keep evolving through selective expansion, portfolio narrowing, and continued emphasis on certification and technical support. New entrants will face the practical hurdle of establishing compliance credibility and supply trust, while existing players may compete more intensely on service, availability, and regional coverage than on headline price alone.
Future Trends and Commercial Implications
Trend 1: Regulated Water Treatment Demand Will Remain the Strongest Structural Anchor
Over the next three to five years, sodium chlorite demand tied to water treatment and disinfection is likely to remain the most durable growth engine. Municipal and industrial users continue to modernize disinfection practices, and compliance-driven procurement tends to be less elastic than price-driven procurement. The commercial implication is that suppliers with certified, application-ready products will have more resilient demand than those competing only in less regulated segments. For buyers, the opportunity lies in locking in reliable supply partnerships before certification cycles or capacity constraints tighten availability.
A related risk is that regulatory intensity can also increase compliance costs and delay new supply qualification. If certification requirements become more demanding or if approval timelines lengthen, the market may reward established, already-approved suppliers even more. That would reinforce concentration among players with strong compliance infrastructure and reduce the speed at which new capacity can be commercially absorbed.
Trend 2: Cost and Energy Dynamics Will Separate Efficient Producers from the Rest
Electricity cost volatility and chlorate pricing will continue to shape the economics of sodium chlorite production. In this environment, the winners are likely to be producers that can manage input exposure, optimize electrochemical efficiency, and choose plant footprints that balance logistics with energy economics. This is not just a margin issue; it is a strategic survivability issue. Producers with weaker cost structures may face difficult choices between shrinking margins, portfolio narrowing, or exiting less competitive segments.
For investors and corporate strategists, the practical implication is to evaluate sodium chlorite opportunities through a cost-structure lens as much as through demand projections. Capacity announcements are useful signals, but they only translate into durable advantage if they are paired with energy efficiency, input procurement discipline, and the ability to serve regulated demand without excessive cost penalties.
Trend 3: Regional Supply Realignment Will Create Localized Opportunities and Vulnerabilities
The market is moving toward a more regionally uneven supply picture. Some areas will see capacity additions driven by water treatment demand and regulatory compliance, while others may experience tighter availability due to portfolio streamlining or plant rationalization. This creates a dual dynamic: regional suppliers with compliant capacity can gain bargaining power and customer loyalty, while buyers in constrained regions may need to diversify sources or accept higher logistical complexity to secure supply.
In practical terms, this trend favors strategies that emphasize regional reliability, qualified backup supply, and strong customer technical support. It also suggests that procurement teams should revisit supply continuity assumptions, especially for critical applications where disruption carries operational or compliance consequences. The market is not necessarily becoming more global in a uniform sense; it is becoming more sensitive to where compliant capacity is located and how easily it can be accessed.
Strategic Recommendations for Decision-Makers
For Manufacturers and Producers
- Prioritize certification and compliance readiness as a commercial asset. In regulated water and food-related applications, approved grades and documented quality systems often determine market access more directly than marginal price differences.
- Reassess portfolio fit in light of input cost volatility. Where sodium chlorite aligns with stronger demand visibility and better cost discipline, capacity and service investment are more likely to generate durable returns than broad, undifferentiated expansion.
- Strengthen application-level support. Suppliers that help customers integrate sodium chlorite into chlorine dioxide generation, bleaching, or disinfection processes can build stickier relationships and reduce price-only competition.
For Investors
- Focus on compliance-linked demand rather than aggregate volume growth alone. Segments tied to water treatment, municipal disinfection, and certified grades tend to offer more predictable commercial logic when regulatory scrutiny is rising.
- Evaluate energy and input exposure carefully. Sodium chlorite economics are sensitive to electricity costs and chlorate pricing, so production advantage increasingly depends on cost structure and plant efficiency, not simply scale.
- Watch for capacity realignment signals. Selective expansions and closures can reshape regional availability and competitive positioning, creating both acquisition/distress opportunities and supply risk warnings.
For Procurement and End-User Buyers
- Treat supply reliability and certification as primary selection criteria, especially for critical water treatment and disinfection applications. Price optimization should not come at the expense of qualified, consistent supply.
- Qualify backup sources where operational continuity is important. Regional supply realignment can create localized tightness, and multiple qualified suppliers can reduce exposure to single-source disruption.
- Align specification and inventory strategy with application requirements. Consistent grade specifications, clear handling protocols, and appropriate buffer stock can lower operational risk and improve total cost outcomes over time.
The sodium chlorite market is entering a phase where success depends less on treating the chemical as a generic bulk input and more on managing it as a regulated, application-specific enabler. Demand linked to water treatment, disinfection, and certified grades is likely to remain the most resilient core, while cost dynamics, energy volatility, and regional capacity choices will determine who can serve that demand profitably and reliably. For executives and investors, the most valuable next step is to move from broad market awareness to a sharper understanding of grade-level demand, regulatory access, regional supply positioning, and the cost structures behind competing producers. Detailed segmentation data, company-level capacity context, and tailored scenario analysis can make those decisions far more precise, especially in a market where compliance and supply continuity increasingly define commercial advantage.
Sodium Chlorate Market
For detailed analysis of this topic, please visit the official page: Sodium Chlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High Carbon Bearing Steel Market: Why 6.4% CAGR Redefines 2032 Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the High Carbon Bearing Steel Market
The high carbon bearing steel market has evolved from a steady industrial commodity segment into a strategically critical materials market shaped by precision engineering demands, regulatory tightening, and shifting end-use requirements. Valued at approximately USD 146.55 million in 2025, the market reflects a consistent growth trajectory from its 2020 base of roughly USD 109.55 million, with a forecast extending through 2032 that points to a compound annual growth rate of 6.4 percent. This expansion is not merely a function of broader industrial output; it signals a structural realignment in how bearing steels are specified, manufactured, and integrated into downstream products. As companies navigate tighter performance tolerances, sustainability mandates, and raw material volatility, the market is increasingly rewarding players who can couple metallurgical precision with supply chain resilience.
Market Snapshot and Structural Challenges
The market's size and growth profile underscore a segment that is expanding at a pace above many traditional specialty steel categories, yet it remains highly concentrated. A handful of producers command the majority of share, reflecting the technical barriers to entry, capital intensity of advanced melting and refining processes, and the long qualification cycles required by demanding end users. Revenue streams are distributed across multiple product forms, with bearing steel bars representing the dominant configuration, while plates, wire, tubes, and rods serve more specialized or volume-sensitive applications. Demand is anchored by several sectors, with automotive and industrial machinery forming the core consumption base, while aerospace, railway, and marine applications contribute incremental but increasingly strategic growth.
Key Challenges and Inflection Points
Three interlocking challenges are reshaping competitive dynamics and forcing strategic recalibration.
- Raw material and energy cost volatility: High carbon bearing steel production is highly sensitive to input price swings. Iron ore fluctuations alone have been shown to impact total production costs by up to 32 percent annually, while chromium costs vary by roughly 27 percent year over year. Energy represents another substantial burden, accounting for 20 to 25 percent of manufacturing expenses, with recent electricity price increases of about 18 percent adding pressure to margins and pricing stability.
- Regulatory and specification upgrades: Domestic mills in key regions are facing tighter cleanliness and inclusion standards that effectively require ladle furnace and vacuum degassing investments. In China, regulatory revisions have mandated cleanliness benchmarks aligned with recognized international bearing specifications, compressing the gap between domestic capability and global-tier performance. These changes raise capital requirements and accelerate the differentiation between mills that can meet advanced specifications and those that cannot.
- Demand fragmentation and qualification cycles: End-use sectors are increasingly requiring higher consistency, cleanliness, and traceable performance. Automotive powertrain designs, industrial machinery under higher cycle loads, and aerospace components all impose more stringent metallurgical expectations. At the same time, qualification timelines remain long, which limits how quickly new entrants can access premium segments and reinforces the advantage of established relationships and documented reliability.
For decision makers, these challenges translate into a simple but demanding reality: scale alone is insufficient. The winners will be those who combine cost discipline with technical capability, secure predictable input strategies, and align product development with the specifications that end users are rapidly institutionalizing.
Core Drivers of Market Change
Technological Innovation in Melting and Refining
Advances in secondary refining are central to the market's trajectory. Vacuum degassing and controlled ladle furnace treatments are no longer optional enhancements for premium bearing steel; they are becoming baseline requirements to manage inclusion content, control carbon and chromium distributions, and ensure consistent hardness and fatigue performance. Mills that have integrated these processes are better positioned to serve automotive and aerospace segments where failure risk is unacceptable and cleanliness tolerances are increasingly narrow. This technological shift also creates a natural filter in the competitive landscape: producers with modernized assets can capture higher-value orders, while those relying on older process chains face margin compression and reduced access to specification-driven demand.
Policy and Regulatory Tightening
Regulatory evolution is accelerating both capability upgrades and market realignment. The push toward cleanliness standards that mirror global bearing specifications is compelling domestic producers to invest in advanced refining, which in turn raises the bar for what qualifies as a competitive offering. Beyond product specifications, environmental and energy policies are reshaping operating economics. Energy cost trends, emissions considerations, and efficiency mandates are pushing producers to evaluate furnace optimization, process heat recovery, and more precise control over melting cycles. For companies operating across jurisdictions, regulatory divergence can become both a risk and an opportunity: early compliance and documentation can shorten sourcing approvals, while lagging capability can restrict market access.
Demand-Side Shifts Toward Reliability and Service Life
End users are increasingly prioritizing bearing steels that support longer service life, reduced maintenance intervals, and predictable performance under variable loads and speeds. Automotive manufacturers are seeking materials that can withstand higher rotational speeds and temperature variations while maintaining dimensional stability. Industrial machinery operators are under pressure to improve uptime and reduce total cost of ownership, which favors materials with consistent cleanliness and superior fatigue behavior. In aerospace and railway applications, where reliability is paramount, the demand for tighter control over microstructure and inclusion content is further reinforcing the move toward higher-specification grades. This demand-side evolution is not simply about volume growth; it is about a shift toward value-accretive specifications that reward technical differentiation and stable supply.
Supply Chain and Cost Structure Realignment
Raw material volatility and energy cost pressures are driving a rethinking of procurement and production strategies. Because iron ore and chromium price movements can materially affect total costs, producers are increasingly evaluating long-term contracting, alternative sourcing, and inventory buffering strategies to protect margins. At the same time, energy intensity is prompting attention to process efficiency and plant-level optimization. This environment favors organizations that can integrate metallurgical capability with disciplined procurement and operational flexibility, especially as end users seek suppliers who can offer stable pricing, documented quality, and continuity of supply in an unpredictable input environment.
Competitive Landscape and Leading Strategies
The market's concentrated structure reflects the technical and capital requirements of producing high-quality bearing steel at scale. Leading players are differentiating themselves through a combination of metallurgical specialization, application-targeted development, and selective capacity or product expansion. The result is a landscape where competitive advantage is increasingly tied to specification readiness, process control, and the ability to serve demanding end markets without compromising consistency.
Strategic Positioning Among Key Players
Several companies illustrate distinct paths to differentiation. Specialist steelmakers focused on high-tech engineering grades are building reputation and backlog in automotive and industrial bearing applications by offering dedicated high carbon bearing steel grades with tight tolerances and proven reliability. In Japan, producers with integrated portfolios and strong aerospace and industrial bearing focus are expanding capacity or refining product lines to capture premium demand, signaling a deliberate move toward higher-value applications. In China, major producers are leveraging environmentally conscious production methods and broadening their processed bearing steel offerings for industrial machinery, while others are expanding product ranges to address industrial performance requirements more comprehensively. These strategies point to a broader pattern: successful participants are aligning product development with the most specification-sensitive applications, investing in process capability, and using application-focused portfolios to build switching costs and customer loyalty.
Recent Developments as Strategic Signals
Recent company actions underscore where value is being sought. Capacity expansion directed at aerospace demand reflects the premium that highly controlled bearing steel commands in sectors where failure risk is unacceptable and documentation is rigorous. New product launches targeting industrial machinery indicate an effort to broaden exposure to high-performance applications while building on existing commercial relationships. Taken together, these moves suggest a market in which growth is increasingly captured by producers that can move beyond generic supply and into application-engineered solutions with verified performance.
Market Structure Evolution
The market is likely to see continued consolidation among producers that can fund advanced refining, maintain consistent quality, and serve demanding applications, while smaller or less-equipped mills may face pressure to specialize, partner, or exit higher-specification segments. New entry remains challenging due to qualification cycles and capital intensity, but targeted partnerships, subcontracting, and niche product development can provide pathways for specialized players. For buyers, this environment rewards diversification of qualified suppliers where feasible, combined with deeper collaboration with preferred producers to secure consistency, lead times, and specification alignment.
PW Consulting
Future Outlook: Trends and Commercial Implications
Trend One: Specification Upgrading as the New Baseline
Over the next three to five years, cleanliness and inclusion control are expected to become standard expectations across more applications, not just aerospace or premium automotive niches. Mills that have already invested in advanced refining will be able to serve a wider range of orders with minimal additional reconfiguration, while others will face rising obsolescence risk for legacy process chains. The commercial opportunity lies in aligning product portfolios with the specifications that procurement and engineering teams are institutionalizing, and in building the documentation and traceability that accelerate sourcing decisions.
High Strength Steel Market
Trend Two: Cost and Supply Resilience as a Competitive Moat
Given the sensitivity of production costs to iron ore, chromium, and energy prices, companies that can stabilize input exposure and optimize energy use will be better positioned to offer reliable pricing and continuity. This is likely to become a differentiator in bids and long-term supply agreements, especially for industrial machinery and railway applications where procurement teams value predictability. The strategic play is to combine technical quality with procurement and operational discipline, turning cost resilience into a repeatable advantage rather than a temporary buffer.
Bearing Steel Market
Trend Three: Application-Linked Product Development
As end-use requirements become more segmented, generic bearing steel offerings will increasingly give way to grades developed with specific application profiles in mind. The most attractive opportunities will be in segments where performance improvements translate directly into measurable gains: reduced wear, extended service intervals, higher load capacity, or better stability under variable conditions. Producers and suppliers that can co-develop grades with end users, supported by consistent process control and documented test data, are likely to capture stronger positioning and more defensible margins.
Risks and Uncertainties
The outlook is not without risk. Continued raw material and energy volatility could erode margins for producers without hedging or efficiency strategies. Regulatory divergence across regions may complicate global supply strategies and increase compliance costs. Qualification lead times and documentation burdens may slow the ability of new or upgraded players to access premium segments. Finally, demand patterns in automotive and industrial machinery can shift with broader economic cycles, influencing order timing and inventory behavior. Navigating these uncertainties will require a balance of technical readiness, supply discipline, and relationship depth.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to ensure that process capability matches the specifications that buyers are increasingly demanding. Investments in secondary refining, process control, and quality documentation are not optional enhancements; they are becoming prerequisites for access to higher-value orders and longer-term agreements. Manufacturers should also evaluate procurement and energy strategies as part of a holistic competitive plan, since input volatility can quickly undermine the benefits of technical differentiation. Aligning product development with application profiles and maintaining close dialogue with key customers can help convert specification readiness into repeat business.
For investors, the market rewards companies that combine metallurgical capability with disciplined cost management and clear application focus. Asset quality, specification breadth, and the ability to serve demanding segments are indicators of resilience and pricing power, while exposure to volatile input markets and legacy process chains can create disproportionate risk. Monitoring capacity actions, product launches, and regulatory-driven upgrades can provide early signals about which players are likely to expand their share of premium demand versus those that may face margin pressure.
For procurement and sourcing leaders, the emphasis should be on qualifying suppliers not only for price but for specification compliance, consistency, and supply continuity.Diversification of qualified sources can reduce concentration risk, while deeper collaboration with preferred producers can secure better alignment on lead times, cleanliness requirements, and documentation standards. In a market where cost volatility and specification upgrades are reshaping supply options, a procurement strategy that values technical reliability alongside price will be better positioned to protect downstream performance and total cost of ownership.
The high carbon bearing steel market is entering a phase where technical precision, regulatory compliance, and supply resilience converge to define competitive advantage. Detailed segmentation data, regional dynamics, and company-level development timelines can sharpen these strategic choices further, providing the granularity needed to prioritize investments, qualify suppliers, and time market entries with greater confidence.
For detailed analysis of this topic, please visit the official page: High Carbon Bearing Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Fireplaces Market: Why 7.5% CAGR & $22 Billion Demand Reshape the Industry
By pmarketresearch, 2026-09-21
The Electric Fireplaces Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot: Growth Trajectory and Structural Realities
The electric fireplaces market has transitioned from a niche heating alternative to a mainstream design and comfort solution, with total industry revenue expanding from 8.98 billion USD in 2020 to an estimated 13.37 billion USD in 2025. The sector is projected to sustain a compound annual growth rate of 7.45 percent across the 2026 to 2032 horizon, reaching approximately 22.05 billion USD by the end of the forecast period. This acceleration is not merely a function of raw demand but reflects a maturation in product engineering, shifting consumer preferences toward low-emission home environments, and broader architectural trends that favor flexible, installation-light ambiance solutions.
Beneath the headline growth figures lies a market structure characterized by moderate fragmentation and steady competitive pressure. The industry operates with a measured degree of concentration, where the top three players collectively account for roughly 25.5 percent of revenue and the top five reach approximately 31.8 percent. This concentration pattern signals a landscape where scale advantages matter, but differentiation through technology, design, and channel strategy remains decisive. Incumbents have secured footholds through product ecosystems, while regional distribution networks and specialty retail partnerships continue to shape market access.
The current environment also presents distinct challenges that temper uninterrupted expansion. First, the market must navigate a complexity-heavy regulatory landscape, particularly around electrical safety certification and energy-efficiency expectations in key regions. Compliance requirements add cost and development time, especially for manufacturers expanding across jurisdictions with differing standards. Second, consumer expectations around realism and convenience have evolved rapidly. Early-generation LED flame effects and basic heating elements no longer satisfy buyers seeking multi-dimensional visuals, app-based control, and integration with broader smart-home environments. Firms that lag on experience design risk margin erosion as price-sensitive segments commoditize. Third, the market faces periodic tension between premium feature-rich offerings and the need for accessible price points in volume-driven channels. Balancing engineering sophistication with manufacturing efficiency will remain a persistent strategic test.
Core Drivers: What Is Powering the Next Phase of Growth
Technology Innovation as a Baseline Expectation
Product differentiation increasingly centers on how convincingly a unit replicates the visual depth and atmospheric effect of a traditional fireplace while maintaining energy efficiency and ease of installation. Recent product cycles have accelerated this trajectory. In October 2025, Modern Flames introduced the Orion v2 Virtual LCD Electric Fireplace, establishing a reference point for multi-dimensional flame technology that competitors are now pressured to match or extend. By February 2026, Escea broadened its holographic electric fireplace range, extending from compact configurations to full-wall installations up to two meters wide, reflecting the market's appetite for architectural-scale solutions. These developments underscore a shift from discrete appliance thinking toward integrated design elements that function as focal points in both new builds and retrofit projects.
Electric Blankets Market
The competitive implication is clear: visual quality, controllability, and modular form factors are becoming table stakes rather than optional enhancements. Manufacturers investing in proprietary flame rendering, layered lighting, and interchangeable cabinet styles are better positioned to defend pricing and build repeat purchase relationships across multiple property renovations or hospitality rollouts.
Regulatory and Standards Frameworks Reshaping Product Architecture
Regulatory direction is not simply a compliance burden; it is actively influencing product form factors and feature sets. In Europe, Ecodesign-type requirements are steering manufacturers toward electronic thermostats and open-window detection capabilities, thereby embedding efficiency logic into everyday operation. Across North America, adherence to UL 1278 and CSA C22.2 No. 46 standards governs evaluation of electric shock risk, fire hazards, insulation integrity, and mechanical stability, while CE marking and the EN 60335-1/EN 60335-2-30 framework set general household electrical safety expectations for products sold in the European Economic Area. These frameworks push firms to formalize testing protocols, document performance claims, and design for lower risk profiles.
For commercial strategy, regulatory alignment can become a differentiator when framed as assurance rather than obligation. Clear certification narratives, transparent energy-use characteristics, and demonstrable safety engineering help procurement teams, specifiers, and insurers reduce perceived risk. Companies that anticipate regional requirements early can avoid rework and accelerate time to market for cross-border rollouts.
Demand-Side Shifts Toward Low-Installation, High-Aesthetic Value
Demand patterns increasingly favor solutions that deliver ambiance and supplemental heat without the structural burden of gas lines, flue requirements, or major masonry work. Residential buyers are seeking room-scale comfort that complements existing decor, while commercial operators look for lobby, hospitality, and dining environments where fireplace presence can be installed with predictable lead times and lower on-site labor risk. This preference is especially relevant in urban housing where wall-cavity constraints and rental turnover make permanent installations less practical.
The result is a market that rewards flexibility in mounting style, finish options, and control interfaces. Products that support wall-mounted, built-in, and freestanding configurations within a coherent design language can better serve mixed customer bases. Additionally, the growth of short-term rentals, boutique hospitality, and refreshed commercial interiors creates incremental demand for repeatable, visually consistent installations that can be deployed across multiple sites.
Cost Structure and Supply Chain Considerations
Suppliers are balancing the cost of advanced display components, heating elements, and control electronics against the need for competitive pricing in volume channels. LED and LCD subassemblies, tempered glass, and smart-home connectivity modules all carry distinct cost and availability profiles. Firms that modularize core platforms can reuse enclosures, electronics architectures, and firmware across multiple product families, improving gross margins and reducing engineering duplication. At the same time, distribution dynamics matter: specialty retailers, e-commerce platforms, and trade specifier channels each demand different packaging, documentation, and service commitments. Companies that align supply planning with channel-specific expectations typically manage inventory risk more effectively and maintain stronger shelf and digital presence.
Competitive Landscape: Positioning, Differentiation, and Evolution
The market's mid-concentration structure allows both scale players and design-focused specialists to thrive, provided they hold a clear strategic position. Modern Flames has built recognition around virtual LCD flame technology and a broad catalog spanning Orion, Redstone, Spectrum, and Landscape Pro series, with app-based control and realistic effects anchoring its value proposition. Its October 2025 launch of the Orion v2 signals a focus on raising the visual benchmark and sustaining a technology-forward narrative. Amantii emphasizes holographic and multi-view flame technologies, extending into contemporary wall-mount and heater offerings; its participation at HPBExpo 2026 in New Orleans with Signature MultiView Holo and other design-forward models illustrates a channel and audience strategy aimed at specification-driven buyers and design-conscious retailers.
Touchstone Home Products has expanded its footprint through recessed, insert, wall-mount, linear, and three-sided smart electric fireplaces that integrate with Alexa and Google ecosystems. Its approach reflects a pragmatic balance between installation variety and smart-home readiness, appealing to buyers who want integration without sacrificing flexibility. SimpliFire contributes a modern and traditional portfolio featuring Digital Spark technology and outdoor-capable series, demonstrating that weather-resistant or seasonal-use designs can open adjacent demand pools. Dimplex, often recognized as a North American leader in electric fireplaces and heaters, maintains breadth across lines such as Revillusion, Ignite Aspire, and water vapor models, leveraging scale and multi-technology depth to address both residential and commercial applications. Napoleon rounds out the competitive set with electric fireplace inserts, built-ins, and linear models including Element and Luminex series, targeting clean, contemporary installations that suit specifiers seeking integrated architectural looks.
Electric Fan Market
Strategically, the leading firms are pursuing differentiation along three intersecting axes. The first is visual authenticity and technological novelty, where advanced flame rendering and holographic-style effects justify premium positioning. The second is installation and format versatility, allowing a single brand to address retrofit, new-build, and commercial use cases without fragmenting the brand identity. The third is ecosystem integration, where app control, voice assistant compatibility, and programmable modes transform a fireplace from a static appliance into an adaptable room system. Companies that combine two or more of these strengths tend to achieve stronger margin profiles and greater resilience when one demand channel softens.
Looking ahead, the competitive structure is likely to evolve through selective consolidation, channel partnerships, and deliberate entry by firms with adjacent competencies in lighting, heating, or smart-home integration. Pure price-based entry will remain challenging given certification costs and the difficulty of matching visual quality at scale. Instead, new entrants will probably appear through niche formats, regional distribution advantages, or targeted partnerships with fixture and interior brands. Incumbents that strengthen service networks, expand finish libraries, and keep firmware upgrade paths open will be better placed to retain specifier and repeat buyer loyalty.
Outlook 2026 to 2032: Three Strategic Trends to Watch
First, the market will increasingly treat electric fireplaces as part of a broader interior systems category rather than a standalone heating accessory. This means closer convergence with architectural lighting, room control platforms, and modular wall systems. Opportunities will arise for bundled specification packages in hospitality and multi-unit residential projects, where standardized visuals and control logic reduce installation complexity and improve consistency across locations. The commercial upside is meaningful: repeat deployment across sites can create predictable revenue streams and strengthen relationships with design firms and general contractors.
Second, advanced visual technologies will continue to diffuse from premium tiers into mid-range products, gradually resetting baseline expectations. Holographic-style rendering, layered flame effects, and refined color-temperature control are likely to become more widely available as component costs stabilize and manufacturing processes mature. For manufacturers, the strategic task is to introduce tiered feature sets that preserve premium margins while expanding addressable volume. For buyers, the opportunity lies in selecting platforms with upgradeable control electronics and accessory compatibility, enabling room designs to evolve over time without full replacement.
Third, regional regulatory divergence will increasingly shape product roadmaps and geographic rollout priorities. European efficiency-oriented features, North American safety certification norms, and varying marking requirements across additional jurisdictions will encourage more modular compliance strategies. Firms that build adaptable internal architectures and maintain clear documentation trails can expand faster with lower rework risk. The corresponding uncertainty is that regulatory shifts or new energy policy instruments may alter relative attractiveness across regions, making near-term investment timing and channel selection more sensitive to local policy signals.
PW Consulting Health Care Research Center
Actionable Guidance for Decision Makers
For Manufacturers and Brand Owners
- Treat platform modularity as a strategic asset. Designing shared electronics, enclosure options, and software layers across wall-mounted, built-in, and freestanding variants can reduce development cost, accelerate line extensions, and improve margin consistency.
- Invest in visual and control differentiation that can be communicated to specifiers and consumers. Certifications and safety narratives should be presented as trust signals that support premium positioning rather than as minimum obligations.
- Plan channel strategy around customer job-to-be-done. Specialty retail, e-commerce, and trade specification channels require different packaging, documentation, and service levels; aligning supply and marketing to each channel improves cash efficiency and brand coherence.
For Investors and Capital Allocators
- Evaluate exposure not only by unit volume but by the durability of technological and design moats. Companies with proprietary flame-rendering methods, modular platforms, and strong smart-home integration typically have better pricing power and repeat purchase potential.
- Monitor regulatory readiness as a quality indicator. Firms with well-documented certification processes and adaptable compliance architectures are better positioned to expand across regions without unexpected delays or cost overruns.
- Seek segments where installation-light, high-aesthetic solutions align with structural demand, such as hospitality refresh cycles, urban residential retrofits, and multi-site commercial interiors. These contexts can support recurring procurement relationships rather than one-off transactions.
For Procurement Teams, Specifiers, and Channel Partners
- Prioritize platforms that balance visual goals with serviceability and upgrade paths. Selection criteria should include control ecosystem compatibility, finish flexibility, and the supplier's ability to support multiple installation types within consistent design language.
- Use certification and efficiency documentation to streamline specification and reduce downstream risk. Clear standards compliance and transparent operating characteristics help align procurement, facilities, and design stakeholders.
- Engage early with suppliers on multi-site or program-based deployments. Coordinating finish options, control settings, and installation requirements in advance can reduce on-site variability and improve portfolio-wide consistency.
The electric fireplaces market is moving into a phase where technology maturity, regulatory alignment, and design integration jointly determine competitive outcomes. For organizations operating in or adjacent to this space, timely and granular intelligence on product roadmaps, regional requirements, and channel dynamics can materially improve investment timing and resource allocation. Detailed segmentation data, company-level profiles, and region-specific trend analysis can support more precise planning and scenario evaluation. For that level of coverage, including deeper breakdowns of format, application, and regional dynamics, interested readers can consult the full PW Consulting market report and related advisory materials.
For detailed analysis of this topic, please visit the official page: Electric Fireplaces Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Engineered Wooden Flooring Market 2026: Why 7% CAGR Signals a Structural Shift in Global Resale Value
By pmarketresearch, 2026-09-21
Navigating the Engineered Wooden Flooring Market: Strategic Trends and Commercial Opportunities Through 2032
The engineered wooden flooring market has moved from a niche alternative to traditional solid hardwood into a mainstream specification across residential, commercial, and hospitality projects. With a base-year valuation of $215.0 million in 2025 and a projected trajectory reaching $344.79 million by 2032, the sector is expanding at a compound annual growth rate of 6.98%. This growth is not merely a function of population or housing starts; it reflects a structural shift in how developers, architects, and homeowners evaluate durability, dimensional stability, sustainability, and total cost of ownership. The historical arc from $153.44 million in 2020 to the current baseline underscores a market that has consistently outpaced broader flooring segments, driven by product maturation and broader acceptance in demanding environments.
For executive teams, investors, and procurement leaders, the numbers tell only part of the story. The real strategic question is how to position within a market that is simultaneously consolidating around scale players, fragmenting through specialized product innovation, and confronting a rapidly shifting regulatory and cost environment. The period from 2026 through 2032 will reward firms that can align product roadmaps with specification trends, manage tariff and supply chain volatility, and communicate verifiable performance advantages to architects, contractors, and end users.
Laminate Flooring Market
Market Status and Core Challenges
The engineered wooden flooring market operates at a crossroads of growth and complexity. Revenue has climbed steadily from $158.68 million in 2021 through $179.78 million in 2022, $186.76 million in 2023, and $204.56 million in 2024, before reaching the 2025 baseline. The forecast window projects continued acceleration, with figures moving from $225.53 million in 2026 to $249.32 million in 2027, $258.33 million in 2028, $272.59 million in 2029, $296.86 million in 2030, $329.9 million in 2031, and $344.79 million in 2032. This trajectory signals a market that is scaling but also increasingly sensitive to macroeconomic, regulatory, and competitive dynamics.
Fragmented Competition with Moderate Concentration
Market concentration remains relatively low, with the top three players accounting for approximately 24.6% of revenue and the top five reaching about 26.2%. This structure indicates a competitive landscape where scale advantages exist but do not dominate, leaving space for specialized manufacturers, regional brands, and product-led disruptors. The moderate concentration also means that pricing power is distributed, and differentiation increasingly depends on performance claims, warranty structures, finish technology, and specification support rather than volume alone.
Key Challenges and Inflection Points
Several structural challenges are reshaping how companies compete and how buyers evaluate engineered wooden flooring:
- Regulatory and tariff volatility: The trade environment has become a defining variable. Reciprocal tariffs of up to 20% on imported engineered wood flooring and related hardwood/plywood from key origins took effect in October 2025, altering cost structures and sourcing strategies. Complementing this, a preliminary affirmative determination in the antidumping investigation on hardwood and decorative plywood imports from China was issued in January 2026, adding further uncertainty to cross-border supply chains. While earlier Section 232 measures on wood products initially excluded engineered wood flooring, subsequent reciprocal measures have closed part of that gap, creating a more complex compliance and cost landscape.
- Material and chemical compliance pressures: Formaldehyde emission limits continue to push manufacturers toward low-VOC and zero-emission resins. This is not a marginal compliance issue; it affects formulation choices, supplier selection, production line adaptation, and marketing claims. Companies that can verify low-emission performance and communicate it credibly gain an edge in specification-driven segments, while those slower to adapt face rising compliance costs and potential reputational risk.
- Differentiation in a maturing product category: As engineered wooden flooring becomes more commonplace, buyers increasingly compare technical attributes—scratch resistance, dimensional stability, waterproof or water-resistant variants, plank dimensions, and finish durability—rather than treating the category as a generic alternative. This raises the bar for product development and specification support, and it compresses margins for undifferentiated offerings.
Key Drivers of Market Change
The market's expansion is being pulled by a combination of technology, regulation, demand-side behavior, and supply chain economics. These forces interact in ways that create both opportunities and constraints for different business models.
Technology Innovation and Performance Breakthroughs
Product innovation is shifting from aesthetic replication toward verifiable performance. Acrylic-infused engineered wood flooring, for example, is engineered for superior scratch resistance, dimensional stability, and carbon reduction, directly addressing long-standing concerns about wear in high-traffic residential and commercial settings. Tarkett's pure natural engineered wood flooring lines emphasize durable, recyclable hardwood construction, aligning performance with sustainability narratives that resonate with specification teams and environmentally conscious buyers. Mullican Flooring's Eloquence engineered oak collection, launched in April 2025, features an aluminum-oxide finish and a 50-year warranty, signaling a push toward longer-life positioning and confidence-based marketing. AHF Products' Bruce-engineered hardwood extends similar logic with up to 50-year residential warranties and prefinished protective coatings, reinforcing durability as a commercial message. Meanwhile, Mohawk's TecWood and other engineered hardwood lines with factory-finished options, waterproof variants, and wide-plank configurations illustrate how product portfolios are broadening to meet diverse installation environments and design preferences.
These innovations matter because they change the value proposition. When scratch resistance, stability, and finish longevity are demonstrable, engineered wooden flooring competes more effectively against luxury vinyl and other resilient alternatives in spaces where wood aesthetics are desired but traditional solid hardwood is impractical. For manufacturers, the implication is clear: R&D and finish technology are becoming core differentiators, not support functions.
Policy and Regulatory Environment
Regulation is no longer a background condition; it is an active driver of product design and sourcing strategy. Formaldehyde emission limits are accelerating adoption of low-VOC and zero-emission resins across North American manufacturers, as reflected in recent industry outlook commentary. This shift influences raw material procurement, production processes, and certification pathways. At the same time, trade measures are reshaping cost structures. The reciprocal tariffs that began in October 2025 and the January 2026 preliminary determination in the antidumping investigation on Chinese hardwood and decorative plywood imports create a dual pressure: costs for certain imported inputs or finished goods may rise, while domestic and allied-source supply chains gain relative attractiveness.
For businesses, the regulatory driver cuts both ways. It raises the cost of non-compliance and the complexity of sourcing, but it also creates opportunities for manufacturers that can document compliance, secure relevant certifications, and offer supply chain transparency. Mohawk Flooring's October 2025 NWFA/NOFMA certification for engineered wood flooring products is a concrete example of how industry recognition can reinforce credibility in a compliance-sensitive environment.
Demand-Side Shifts in Consumer and Business Behavior
Demand is being reshaped by changing expectations around aesthetics, durability, and sustainability. Residential applications continue to represent the largest share of market value, reflecting homeowners' preference for wood aesthetics combined with the practical advantages of engineered construction in environments where moisture, subfloor conditions, or installation speed matter. Commercial and hospitality segments, while smaller in relative terms, are influenced by different dynamics: specification criteria, lifecycle cost, maintenance requirements, and brand alignment with sustainability goals.
In practice, this means specification teams and procurement groups are weighing more than initial price. They are increasingly attentive to finish warranties, dimensional stability claims, maintenance regimes, and environmental profiles. The growth in wide-plank configurations, matte and satin finishes, and extra-long boards—seen across several leading collections—indicates that design preferences are evolving toward larger, more contemporary formats that still rely on engineered construction for stability. For suppliers, this demands closer engagement with specifiers and a clearer articulation of how product attributes translate into installation and maintenance benefits.
Supply Chain and Cost Structure Changes
Tariffs, antidumping actions, and resin compliance requirements are collectively reshaping cost structures. Imported engineered wood flooring and related substrates face higher effective costs under reciprocal measures, while domestic and allied-source alternatives may benefit from relative price competitiveness and lower compliance friction. At the same time, the shift toward low-VOC and zero-emission resins can alter input costs and require production adjustments, affecting both margins and time-to-market for reformulated products.
Supply chain resilience is becoming a strategic priority. Companies that diversify sourcing, secure reliable substrate supplies, and invest in factory-finished capabilities can reduce exposure to import volatility and improve delivery predictability. For investors and executives, the key is to view cost structure not as a static input but as a dynamic variable shaped by trade policy, chemical regulations, and manufacturing geography.
Competitive Landscape and Leading Strategies
The competitive field combines established scale players with specialized manufacturers and regional brands, each pursuing different levers of differentiation. The market's moderate concentration leaves room for multiplewinning positions, but sustaining them requires clear strategic focus.
Strategic Positioning and Differentiators Among Leading Companies
Several patterns emerge when examining how leading firms position their engineered wooden flooring offerings:
- Performance and warranty leadership: Mullican Flooring and AHF Products emphasize long-duration warranties and advanced finishes, using durability claims to justify premium positioning and build specifier confidence. Mullican's Eloquence collection, with its aluminum-oxide finish and 50-year warranty, exemplifies a durability-first narrative.
- Water resistance and format expansion: Mohawk Industries extends its portfolio with waterproof variants, factory-finished options, and wide-plank configurations, targeting environments where moisture and contemporary design preferences intersect. This broadens the addressable use cases beyond traditional dry interiors.
- Sustainability and material purity: Tarkett's pure natural engineered wood flooring lines focus on durable, recyclable hardwood construction, aligning with specification trends that value recyclability and material transparency. This positions the brand in projects where environmental messaging is part of the value proposition.
- Finish aesthetics and board dimensions: Shaw Industries Group's core engineered hardwood collections feature matte and satin finishes, extra-long boards, and sustainable options, reflecting a design-driven approach that meets evolving 인테리어 preferences while maintaining performance credibility.
- Certification and compliance credibility: Mohawk Flooring's NWFA/NOFMA certification achievement in October 2025 illustrates how industry recognition can reinforce trust in a market where performance claims and compliance are under greater scrutiny.
- Specialized engineered profiles: Mercier Wood Flooring's engineered 1/2-inch and 3/4-inch hard maple and oak planks in collections such as Idol and Legend, and Nydree Flooring's acrylic-infused engineered wood flooring with superior scratch resistance, dimensional stability, and carbon reduction, show how specialized formulations and dimensions can carve out distinct positions.
Evolution of the Competitive Structure
The market is not trending toward a single dominant model. Instead, it is evolving through a combination of consolidation at the top, specialization in the middle, and continued entry from focused newcomers. Scale players leverage breadth, distribution, and specification support to defend share, while specialized manufacturers compete on technical attributes, finish technology, and targeted applications. Regional brands and niche entrants can thrive by focusing on particular wood species, plank dimensions, finish systems, or sustainability credentials that resonate with local specification communities.
This structure suggests that competitive advantage will increasingly come from the ability to combine product performance with credible certification, reliable supply, and strong specifier engagement. Price competition alone is unlikely to sustain differentiation in a market where buyers are comparing warranties, emission profiles, and installation practicality alongside aesthetics.
Future Trends and Commercial Opportunities (2026–2032)
Looking ahead, several trends are likely to shape how the market grows and where opportunities emerge. These are not speculative narratives; they are grounded in current product directions, regulatory signals, and the observed trajectory of market size through 2032.
Trend 1: Performance-Led Differentiation Will Become the Default Expectation
As engineered wooden flooring becomes more widely specified, buyers will increasingly expect demonstrable performance rather than categorical claims. Scratch resistance, dimensional stability, finish longevity, and moisture handling will move from nice-to-have attributes to baseline evaluation criteria. Commercial opportunity lies in developing and communicating verifiable test data, offering meaningful warranties, and aligning finish technologies with real-world use cases. The risk is that product claims outpace substantiation, which can erode trust and invite scrutiny from specifiers and regulators.
LVT Flooring Market
Trend 2: Regulatory and Trade Dynamics Will Continue to Reshape Sourcing and Cost
The combination of emission limits, reciprocal tariffs, and antidumping measures indicates that trade and compliance will remain central variables. Companies that build diversified, resilient sourcing strategies and maintain clear compliance documentation will be better positioned to manage cost swings and specification requirements. Commercial opportunity exists for manufacturers that can offer stable supply, transparent compliance, and competitive total cost despite import pressures. The uncertainty lies in the potential for further trade measures and the pace at which emission standards tighten, both of which can alter cost structures and product roadmaps.
Trend 3: Design Formats and Sustainability Narratives Will Co-Drive Specification
The movement toward wider planks, longer boards, and matte or satin finishes reflects a design evolution that engineered construction is well suited to support. Simultaneously, sustainability considerations—recyclable construction, low-emission resins, carbon reduction claims—are becoming part of specification decisions in commercial and hospitality projects. Commercial opportunity lies in product lines that marry contemporary formats with credible environmental profiles and durable finishes. The risk is greenwashing or overstatement; buyers and specifiers are increasingly adept at distinguishing substantiated claims from marketing language.
Implications for Commercial Opportunity
Taken together, these trends point to several opportunity spaces. Manufacturers can capture share by investing in finish and infusion technologies that improve durability and stability, then communicating those benefits through warranties and certification. Distributors and retailers can differentiate through specifier education, installation support, and clear guidance on where engineered wooden flooring outperforms alternatives. Investors can look for companies with defensible product technology, credible compliance posture, and flexible sourcing strategies that can absorb trade volatility. Across all roles, the ability to connect product attributes to real installation and maintenance outcomes will be a critical value driver.
Strategic Actions for Decision-Makers
Different roles in the value chain face distinct priorities, but all benefit from a disciplined approach to product, compliance, and specification strategy.
PW Consulting
For Manufacturers and Brand Leaders
- Prioritize finish and material technologies that deliver measurable improvements in scratch resistance, dimensional stability, and moisture handling, and back them with meaningful warranties and third-party recognition where appropriate.
- Strengthen compliance documentation and low-emission formulations to meet tightening formaldehyde and VOC expectations, turning compliance into a specification advantage rather than a cost center.
- Diversify sourcing and manufacturing footprints to reduce exposure to import tariffs and antidumping actions, while maintaining cost competitiveness and delivery reliability.
For Investors and Capital Allocators
- Evaluate target companies on the strength of their product differentiation, warranty structures, certification posture, and ability to manage trade and compliance risk, not solely on revenue growth.
- Favor businesses with flexible supply chains and clear positioning in performance or sustainability, as these attributes are better placed to withstand regulatory and tariff volatility.
- Monitor consolidation patterns and specialization trends to identify where scale advantages are accruing and where niche leaders may be attractive acquisition or partnership candidates.
For Procurement and Specification Teams
- Evaluate engineered wooden flooring options against total lifecycle criteria—durability, maintenance, emission compliance, warranty support, and installation practicality—rather than initial unit cost alone.
- Seek suppliers that provide verifiable performance data, relevant certifications, and clear guidance on suitable applications, especially where moisture, traffic, or subfloor conditions are concerns.
- Build sourcing flexibility to account for tariff and compliance shifts, and prioritize suppliers with transparent supply chains and stable delivery records.
Conclusion
The engineered wooden flooring market is expanding along a clear growth path, but the nature of that growth is changing. Value is shifting from category acceptance to performance substantiation, from price competition to differentiated finish and material technologies, and from static sourcing to resilient, compliance-aware supply chains. The period from 2026 through 2032 will reward organizations that can align product innovation with specification realities, navigate trade and regulatory dynamics, and communicate credible, verifiable advantages to buyers and specifiers.
For leaders seeking deeper segment-level detail, granular competitive benchmarks, and tailored strategic recommendations, PW Consulting's full report on the engineered wooden flooring market provides the structured data and scenario analysis needed to move from insight to execution.
For detailed analysis of this topic, please visit the official page: Engineered Wooden Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LV and MV Switchgear Market: Why the 6.98% CAGR Reshapes Global Competition
By pmarketresearch, 2026-09-21
LV and MV Switchgear Market: Strategic Trends and Commercial Opportunities
The global LV and MV switchgear market has entered a phase of sustained expansion, reaching an estimated USD 21.5 billion in revenue in 2025 and projected to surpass USD 34.4 billion by 2032. This trajectory reflects a compound annual growth rate of approximately 7 percent across the 2026-2032 forecast period, accelerating from a 2020 baseline of USD 16.3 billion. The growth is not merely a function of incremental demand but a structural realignment driven by electrification, grid modernization, and regulatory shifts that are rewriting procurement requirements and technology roadmaps. For executives navigating capital allocation, product portfolios, or supply chain strategy, the market signals a transition from commoditized equipment sales to solution-oriented, digitally integrated power distribution ecosystems.
Understanding where value is being created requires looking beyond headline revenue figures. The market is dispersing across multiple layers: voltage class, application vertical, and geography all shape competitive positioning, but the underlying dynamics are converging around three themes. First, environmental mandates are forcing a rapid redesign of medium-voltage architectures. Second, digital connectivity has moved from a differentiator to a baseline expectation across both low-voltage and medium-voltage segments. Third, raw material volatility and manufacturing capacity constraints are reshaping margin structures and accelerating regionalization of supply chains. These forces are redistributing advantage among established multinationals, specialized niche players, and agile regional manufacturers.
Metal-Clad Switchgear Market
Market Landscape: Scale, Structure, and Structural Tension
Macro Trajectory and Concentration Dynamics
The market's growth path from 2020 through 2025 demonstrates resilience against macroeconomic headwinds, with revenue climbing steadily despite supply chain disruptions and inflationary pressures. The forecast period extends this momentum, with projections indicating acceleration in the latter half of the decade as utility capital programs mature and industrial electrification ramps up. Importantly, the market remains moderately fragmented. The top three players account for roughly 24.6 percent of total revenue, while the top five reach approximately 26.2 percent. This concentration level suggests a market where scale advantages exist but are not insurmountable, and where differentiated technology, regional service networks, and specification-winning capabilities can sustain profitable positions for focused competitors.
Three Defining Challenges
The industry is navigating a set of intersecting pressures that qualify any straightforward growth narrative. First, environmental regulation is compressing product lifecycles. The prohibition on new SF6-filled medium-voltage switchgear at or below 24 kV, effective from January 2026 under EU Regulation (EU) 2024/573, has shifted procurement specifications and capital planning timelines. Public procurement notices on the EU TED portal now reference SF6-free solutions in grid reinforcement projects, meaning manufacturers and system integrators must align product roadmaps with compliance deadlines that are already in force. This transition is not simply a substitution exercise; it requires revalidation of insulation performance, thermal management, and field service protocols, adding complexity to project execution.
Second, raw material costs are eroding margin predictability. Copper traded between USD 8,400 and USD 9,500 per ton during 2024-2025, while CRGO steel surpassed USD 3,000 per ton. These input pressures cut low-voltage OEM margins by up to four percentage points in some periods. Simultaneously, prices for aluminum mill shapes and primary and secondary nonferrous metals rose more than 25 percent over the past year, affecting enclosures, busbars, and structural components. The cumulative effect is that cost pass-through is uneven across regions and customer contracts, making pricing strategy and inventory management more strategic than operational.
Third, the market is experiencing a bifurcation between volume-driven standardization and value-driven customization. End-users in industrial and utility segments increasingly demand digitally connected equipment that integrates with monitoring, protection, and asset management platforms. At the same time, price sensitivity persists in commercially oriented segments where standardization is the norm. Winning in this environment requires clear segmentation of product architecture, production processes, and service models, because the economic logic of a commodity-style feeder panel differs fundamentally from that of a smart, configurable substation assembly.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Architecture
Environmental Regulation as a Technology Accelerant
Regulatory pressure is no longer a compliance cost center; it is reshaping the innovation pipeline. The EU's prohibition on SF6-filled medium-voltage switchgear up to 24 kV has catalyzed commercial momentum for SF6-free alternatives, including dry air, vacuum, and clean air insulation technologies. Schneider Electric's AirSeT portfolio exemplifies this shift, positioning SF6-free medium-voltage solutions with digital connectivity as a response to both regulatory directionality and customer sustainability targets. The same regulatory environment is forcing board-level decisions on urban substation modernization, as upgrade programs now must account for SF6-free specifications that alter project timelines, specification processes, and capital planning assumptions.
Beyond Europe, regulatory and policy signals are aligning with decarbonization and grid resilience goals. Utilities and large industrials are under increasing scrutiny to reduce greenhouse gas footprints, and switchgear selection is becoming a visible component of Scope 1 and Scope 2 reporting. This creates a commercial advantage for manufacturers that can offer verified SF6-free solutions with documented performance, because procurement teams need defensible specifications that withstand both internal sustainability reviews and external stakeholder expectations.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Digital Connectivity as a Value Multiplier
Digitalization has moved from a premium add-on to a structural requirement across both low-voltage and medium-voltage segments. Smart switchgear with embedded sensing, condition monitoring, and communication interfaces enables predictive maintenance, faster fault isolation, and integration into broader grid management platforms. Schneider Electric's introduction of the FeederSeT smart, compact, and digitally connected low-voltage switchgear range for indoor and outdoor applications illustrates how manufacturers are embedding connectivity into core product lines rather than treating it as a separate SKU. For utilities and industrials, the value proposition extends beyond reliability: digital switchgear reduces downtime, improves asset utilization, and supports lifecycle cost optimization, which matters as labor constraints and skilled technician shortages become more acute.
The commercial implication is that differentiation is shifting from physical protection performance alone to data-enabled service models. Manufacturers that can combine robust hardware with analytics, remote visibility, and integration with customer energy management systems are capturing higher value-share and deeper customer relationships. This trend also raises the barrier for entrants that lack software, data architecture, and service delivery capabilities.
Demand-Side Shifts: Electrification and Grid Modernization
Demand growth is being shaped by two reinforcing currents. On the utility and infrastructure side, grid reinforcement programs, renewable integration, and electrification of transport and heating are driving medium-voltage expansion. Mitsubishi Electric's order for 84 kV dry air insulated switchgear from Kansai Transmission and Distribution in Japan reflects how high-voltage, SF6-free solutions are entering mainstream transmission and distribution modernization programs. On the industrial side, reshoring, data center expansion, and electrification of process heat are increasing power distribution density, which in turn drives demand for compact, reliable, and digitally manageable switchgear.
For commercial and residential applications, the pattern is more heterogeneous. Some regions are experiencing steady replacement and upgrade cycles, while others see demand tied to building electrification and local grid constraints. The common thread is that end-users increasingly evaluate switchgear not only on protection performance but also on footprint, maintainability, and compatibility with digital energy management strategies. This shifts the purchasing dynamic from lowest-capital-cost to total-cost-of-ownership considerations, which favors suppliers with strong engineering support and lifecycle service offerings.
Supply Chain and Cost Structure Reconfiguration
The supply chain environment is prompting strategic recalibration. Input cost volatility, combined with the need for specialized insulation materials and digital components, is pushing manufacturers toward longer-term supplier agreements, dual-sourcing, and regional production footprints. Hitachi Energy's announcement of a USD 1 billion investment in transformer and grid equipment manufacturing with a new factory in Virginia signals how major players are committing to domestic capacity expansion in response to demand growth and supply chain resilience priorities. For the broader LV and MV switchgear ecosystem, such capacity investments indicate a multi-year ramp in manufacturing capability, but also a lag between investment announcements and commercially available incremental capacity, which can sustain pricing tension in the near term.
At the same time, component availability for digital subsystems, including sensors, communication modules, and control electronics, introduces dependency on semiconductor and electronics supply dynamics that differ from traditional electromechanical supply chains. Manufacturers that integrate these capabilities internally or through tightly managed partnerships gain flexibility, while those dependent on fragmented supplier bases face more variable lead times and quality risk.
Competitive Landscape: Positioning, Differentiation, and Structural Evolution
Strategic Positioning Among Leading Players
The competitive set spans global multinationals with broad power distribution portfolios and specialized manufacturers with focused application expertise. Siemens AG emphasizes a comprehensive medium-voltage power distribution portfolio anchored in smart grid capabilities, vacuum technology, and 24 kV ratings serving utilities and industrial applications, positioning reliability and system integration as core themes. Schneider Electric pairs a smart low-voltage FeederSeT range with SF6-free AirSeT medium-voltage solutions, using digital connectivity and regulatory alignment to appeal to customers managing both operational performance and sustainability obligations. ABB Ltd. maintains a broad medium and low-voltage equipment manufacturing footprint, including digital switchgear and regional production capabilities, with an emphasis on power distribution breadth and engineering integration. Eaton Corporation focuses on custom low and medium-voltage solutions for industrial, commercial, and utility power distribution, leveraging application engineering and configuration flexibility. Mitsubishi Electric's 84 kV dry air insulated and SF6-free solutions highlight a focus on grid modernization and renewable integration with high-voltage technology differentiation.
On the specialized side, Enercon Power provides custom-designed low and medium-voltage switchgear up to 15 kV with UL891 and UL1558 certification, serving on-site industrial and defense applications where specification precision and certification rigor matter. RESA Power and BCS Switchgear address markets that value remanufactured and custom new equipment, offering metal-clad, metal-enclosed, and pad-mounted styles across voltage ranges up to 38 kV, appealing to cost-conscious buyers who still require performance and reliability. LS Electric Co., Ltd. targets optimized medium-voltage switchgear for primary and secondary distribution across industrial, commercial, and residential applications, while Liyond provides medium-voltage switchgear solutions including GIS, KYN, RMU, and other configurations, competing on configurable product breadth and regional service reach.
Differentiation and Competitive Wedges
Several strategic wedges are shaping competitive outcomes. One is regulatory-ready SF6-free performance. As SF6 restrictions tighten and procurement specifications reference SF6-free requirements, manufacturers with validated alternatives and established certification paths are positioned to win specification decisions earlier in project cycles. A second wedge is digital service integration. Suppliers that offer not just connected hardware but also interoperable data formats, remote diagnostics, and preventive maintenance programs are building switching costs and recurring value streams. A third wedge is application-specific customization and certification. In industrial, defense, and specialized utility contexts, the ability to deliver UL-certified, code-compliant, and site-specific designs with reliable lead times creates a defensible niche that broad-line competitors may under-serve.
A fourth, often underappreciated, wedge is supply assurance. In a period of input cost volatility and capacity ramp-up, customers are assigning premium value to suppliers that can commit to delivery, maintain inventory buffers, and provide transparent lead-time visibility. This favors players with disciplined operations, multi-site manufacturing, and strong supplier relationships, and it is particularly relevant for large projects where delays carry significant penalty and reputational risk.
Structural Evolution: Consolidation, Fragmentation, and New Entrants
The market's moderate concentration suggests room for targeted consolidation, particularly in remanufacturing, specialty customization, and regional service segments where scale Economics are less dominant than technical capability and customer relationships. At the same time, fragmentation persists because application diversity and local code requirements sustain demand for smaller, agile suppliers that can respond quickly to niche specifications. New entrants are most likely to emerge where digital-native approaches, modular product platforms, or regional manufacturing models can offer meaningful cost or responsiveness advantages, but their success will depend on navigating certification, field validation, and service infrastructure requirements that are difficult to replicate quickly.
A plausible evolution path is a barbell structure: large multinationals expanding their integrated smart and SF6-free portfolios while consolidating service and aftermarket channels, and a layer of specialized manufacturers strengthening positions in high-specification industrial, defense, and regional utility applications where customization and certification expertise command premium economics. The middle ground of undifferentiated commodity switchgear faces the greatest pressure from input cost volatility, digital expectations, and regulatory-driven redesign cycles.
Future Trends and Commercial Implications
Trend One: SF6-Free Medium-Voltage Becomes Specification Default
Over the next three to five years, SF6-free solutions will move from an environmentally motivated alternative to a default consideration for medium-voltage switchgear at or below 24 kV in regulated markets, with influence extending to procurement specifications in other regions through multinational customer policies and utility sustainability commitments. The commercial opportunity lies in developing validated product lines, supporting documentation, and field service capabilities that reduce specification risk for customers. The uncertainty is whether alternative insulation technologies can achieve cost parity at scale and whether project timelines can absorb revalidation and training requirements without delaying capital programs.
Trend Two: Digital Integration Drives Recurring Value and Switching Costs
Digital connectivity will increasingly be treated as part of the core product architecture rather than an accessory. Expect broader adoption of condition monitoring, remote diagnostics, and integration with energy and asset management platforms, particularly in industrial and utility settings where downtime costs and labor constraints are acute. Manufacturers that build interoperable data layers and service offerings can capture higher-margin recurring revenue and deepen customer lock-in. The risk is that digital fragmentation and cybersecurity requirements raise integration complexity, and that customers demand open standards that reduce the proprietary advantage of any single supplier.
Trend Three: Regionalization and Capacity Investment Redraw Supply Economics
Capacity investments and supply chain regionalization will reshape lead times, cost structures, and competitive geography over the forecast period. Large manufacturing commitments signal a multi-year expansion cycle, but near-term supply tightness may persist in specific components and regions, sustaining pricing tension for commoditized segments while allowing premium economics for differentiated, certified, and digitally enabled products. The opportunity is for manufacturers and integrators that can combine regional supply assurance with specification-winning technology and service. The uncertainty is whether macroeconomic conditions, trade policy, or raw material disruptions could alter the pace of capacity realization and whether demand growth in certain verticals might outpace available qualified capacity.
Strategic Implications for Decision Makers
For Manufacturers and Product Leaders
Align product roadmaps explicitly with SF6-free requirements and digital connectivity expectations. Treat regulatory deadlines and customer sustainability specifications as design constraints from the outset rather than late-stage adaptations. Prioritize validated insulation alternatives, certification completeness, and field service readiness, because specification wins increasingly depend on defensible performance documentation and compliance clarity. In parallel, structure product architectures to separate high-volume standardized lines from configurable, digitally enabled offerings so that margin structures and production processes match the economic logic of each segment.
- Invest in SF6-free validation, certification pathways, and lifecycle documentation to reduce customer specification risk.
- Build interoperable digital service capabilities, including remote monitoring, predictive maintenance, and data integration, as part of the core offering rather than an add-on.
- Segment manufacturing and pricing strategies to protect margins against raw material volatility while preserving competitiveness in standardized segments.
For Investors and Capital Allocators
Focus on firms with clear differentiation in SF6-free technology, digital service integration, and application-specific customization, rather than relying solely on scale. The moderate market concentration implies that targeted capabilities can sustain strong positioning, but the same dynamics are compressing margins in undifferentiated commodity segments. Evaluate exposure to regulatory-driven demand acceleration, regional capacity expansion, and recurring service revenue potential, while scrutinizing raw material sensitivity, certification risk, and lead-time reliability.
- Differentiate between scale advantages and capability advantages; in a moderately fragmented market, technology and service differentiation can generate premium economics.
- Assess exposure to regulatory tailwinds and digital service monetization, and weigh these against input cost sensitivity and supply chain concentration risk.
- Watch for consolidation opportunities in remanufacturing, specialty customization, and regional service where technical capability and customer relationships matter more than commodity scale.
For Procurement and Supply Chain Leaders
Treat switchgear selection as a total-cost-of-ownership decision shaped by regulatory compliance, digital integration, service availability, and supply assurance. Specification processes should account for SF6-free requirements, lead-time reliability, and compatibility with energy and asset management platforms, because these factors increasingly determine operational resilience and lifecycle cost. Where projects span multiple regulatory jurisdictions or involve multinational operations, standardize specifications around future-proofed architectures to reduce rework and re-procurement risk later in the project lifecycle.
PW Consulting
- Embed SF6-free and digital connectivity requirements early in specification and evaluation criteria to avoid late-stage redesigns and timeline disruptions.
- Prioritize suppliers with transparent lead times, regional supply assurance, and certified performance documentation, particularly for critical industrial and utility projects.
- Evaluate total lifecycle economics, including maintenance, downtime risk, and data integration, rather than focusing solely on upfront capital cost.
Positioning for the Next Phase of Value Creation
The LV and MV switchgear market is transitioning from a hardware-centric equipment market to a solution-oriented domain where regulatory compliance, digital service, and supply assurance differentiate winners. Revenue growth to the mid-2030s reflects real structural demand, but value capture will favor those who can navigate SF6-free transition timelines, integrate digital capabilities into core product architecture, and manage the margin impact of raw material volatility through disciplined segmentation and supply strategy. For manufacturers, investors, and procurement leaders, the immediate task is to align decision frameworks with these dynamics rather than treating them as peripheral concerns. More detailed segmentation data, regional demand breakdowns, and company-level competitive assessments can sharpen execution planning, and readers seeking that level of granularity can explore the full PW Consulting research report for comprehensive figures and tailored strategic recommendations.
For detailed analysis of this topic, please visit the official page: LV and MV Switchgear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com