

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Dock Levelers Market CAGR 5.7%: What's Fueling the $257.5M Growth to 2032

Dock Levelers Market: Strategic Trends and Commercial Opportunities Through 2032
The dock leveler market sits at a critical intersection of logistics infrastructure, workplace safety, and material handling efficiency. As loading docks remain the primary interface between indoor storage and external transportation networks, the equipment that bridges this gap has evolved from a purely mechanical accessory to a regulated, performance-driven component of facility design. Market trajectories over the past half-decade and projections through the end of the decade point to steady expansion, but the growth is neither uniform nor automatic. Stakeholders who understand the shifting technological baselines, regulatory tightening, and end-user operating models will be better positioned to capture margin, market share, or strategic acquisition value.
Market Snapshot and Core Challenges
The dock levelers market has demonstrated consistent expansion from 2020 through 2025, with a base-year valuation that reflects decades of incremental modernization across warehousing and industrial facilities. Over the historical period, revenue climbed steadily as replacement cycles, new construction, and retrofitting activity combined to sustain demand. Looking ahead through 2032, the market is projected to maintain a compound annual growth rate of 5.7%, translating into a meaningful uplift in cumulative revenue over the forecast window. This trajectory reflects a maturing industry where baseline demand is supported by broad infrastructure needs, but incremental growth is increasingly tied to specification upgrades, safety compliance, and regional industrialization patterns.
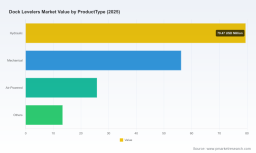
A few structural realities define the market's current posture. First, concentration is moderate rather than dominant. The top three players hold roughly a third of aggregate revenue, while the top five account for just under two-fifths. This leaves substantial room for specialized manufacturers, regional specialists, and channel-focused integrators to compete without requiring massive scale. Second, the market's expansion is uneven across product architectures and end-use contexts, with hydraulic solutions commanding the largest revenue share, mechanical systems retaining strong relevance where cost and simplicity matter, and air-powered or niche variants serving more targeted applications. Logistics and warehousing facilities represent the largest end-user base, while manufacturing and retail environments contribute meaningful but differentiated demand profiles. Regional patterns are similarly differentiated, with Asia Pacific capturing the largest absolute revenue contribution, followed by Europe and North America, while Latin America and the Middle East and Africa reflect smaller but strategically important footprints.
- The industry is navigating a transition from commoditized hardware sales to specification-driven, compliance-aligned installations.
- Replacement and retrofit activity is becoming a larger share of demand as existing dock infrastructure ages in developed markets.
- Price competition in mechanical and entry-level hydraulic segments pressures OEMs to differentiate through durability, service, and compliance credentials rather than unit cost alone.
Key Drivers Reshaping the Market
Technology Innovation and Performance Baselines
Product architecture continues to be the most visible driver of market differentiation. Hydraulic dock levelers remain the dominant revenue category, favored for their lifting capacity, operator convenience, and adaptability to a wide range of truck bed height variations. At the same time, recent product launches illustrate how even established categories are being refined. In mid-2025, new hydraulic dock leveler models were introduced by major brands, signaling a market-wide push toward installer-friendly features, standardized performance benchmarks, and more predictable maintenance characteristics. Mechanical systems retain competitive advantages in environments where electrical infrastructure is limited or where lower acquisition cost is prioritized. Air-powered and specialty variants address narrower use cases but benefit from ongoing improvements in actuation reliability and sealing performance.
PW Consulting Automotive & Machinery Research Center
Material choices also matter more than they did in earlier cycles. High-strength steel and notched plate constructions have become central to dock leveler build specifications, reinforcing structural resilience under repeated loading cycles and harsh operating conditions. These material and design choices are not merely engineering details; they directly influence service life, downtime frequency, and total cost of ownership, which increasingly drive specification decisions by facility managers and engineering teams.
Regulatory and Standards Environment
Regulatory pressure is accelerating the shift toward certified, safety-oriented equipment. Standards such as ANSI MH30.1-2022 provide uniform design and testing guidelines for dock leveling devices, giving facility owners, integrators, and insurers a clearer baseline for specification and procurement. In practice, this means dock levelers are increasingly evaluated not just on load capacity but on conformance to recognized testing protocols, energy-saving behaviors, and integration with broader dock safety systems. Stricter workplace safety expectations under OSHA and related compliance frameworks further encourage adoption of equipment that demonstrably reduces exposure to loading dock hazards, including trailer creep, unintended movement, and edge-of-dock incidents.
This regulatory environment creates a dual effect. For buyers, it adds weight to the case for higher-specification, certified products rather than bare-minimum hardware. For manufacturers, it raises the bar for product documentation, testing rigor, and installer support, but also strengthens the value proposition of equipment that can be presented as compliant by design rather than by retrofit.
Demand-Side Shifts in Operations and Building Use
The way facilities operate is reshaping equipment requirements. Modern logistics and warehousing facilities increasingly emphasize throughput, dock utilization, and labor efficiency. Dock levelers that integrate cleanly with door operators, vehicle restraints, and traffic flow design are more attractive because they reduce installation friction and improve day-to-day uptime. In retail and distribution settings, frequent trailer turnover and variable vehicle heights make consistency and ease of use especially important. Meanwhile, manufacturing environments often place higher structural and duty-cycle demands on levelers, reinforcing demand for heavy-duty configurations and robust material builds.
Operational expectations are also shifting the conversation around energy and safety. Facilities are more attentive to dock sealing, air infiltration, and the interaction between levelers and dock doors, not only for operational comfort but for energy performance and compliance. Equipment that contributes to safer trailer engagement and reduces incidental energy loss has a stronger narrative in specifications, particularly in organizations with formalized safety programs and sustainability targets.
Supply Chain and Cost Structure Dynamics
Input costs, lead times, and manufacturing location strategies continue to influence competitive positioning. Steel-based construction remains central to dock leveler production, and commodity dynamics can affect margin structure and pricing flexibility across the value chain. Manufacturers with stable supply arrangements, efficient fabrication workflows, and strong domestic production footprints can respond more predictably to demand fluctuations. Integration within larger industrial equipment groups also shapes market behavior, as corporate ownership can provide access to broader distribution channels, cross-selling opportunities, and more structured aftermarket service networks.
Loading Dock Equipment Market
At the same time, the market remains accessible enough that regional manufacturers and specialized brands can compete effectively, especially where local installation ecosystems, service responsiveness, and application-specific expertise matter more than global scale. This balance helps sustain innovation and optionality, but it also means pricing and positioning can vary noticeably across geographies and customer segments.
Competitive Landscape and Strategic Positioning
The competitive set is anchored by established manufacturers with distinct positioning across product breadth, application focus, and ownership structure. Some players have built reputations around hydraulic, air-powered, mechanical, and edge-of-dock portfolios, often emphasizing domestic manufacturing and broad availability. Others differentiate through vertical-storing concepts, dock lifts, or applications tailored to retail and distribution clients at scale. A subset of manufacturers focuses on edge-of-dock levelers and complementary material handling equipment, appealing to facilities that prioritize simpler mechanical solutions or specific installation constraints. There are also brands known for advanced safety and energy-saving features, which align with the compliance and operational-efficiency themes increasingly valued by facility owners.
A notable competitive development is the pattern of product refinement rather than radical category disruption. Recent mid-2025 introductions of new hydraulic dock leveler models from major brands illustrate the direction of travel: improved installer features, clearer certification alignment, and more defined model families. This suggests competition is increasingly won through specification support, service reliability, and product clarity as much as through raw hardware performance.
Hydraulic Dock Leveler Market
- OEMs with broad product ranges can capture more fixture points across multiple facility types and replacement cycles.
- Manufacturers emphasizing safety certifications, energy performance, and installer-friendly design can command stronger positioning in compliance-conscious procurement processes.
- Companies with strong retail, warehousing, or industrial customer relationships benefit from repeat specification influence and visibility into end-user operating requirements.
- Regional manufacturers and niche specialists can compete by focusing on service speed, application customization, and local integration partnerships rather than attempting to match global breadth.
The industry is also experiencing gradual consolidation and channel maturation rather than abrupt market disruption. Larger industrial groups can leverage broader portfolios and service networks, while specialized brands retain relevance where they solve particular installation or application problems well. New entrants face a meaningful barrier in installation expertise, compliance documentation, and aftermarket support, which means credible growth often comes through acquisition, channel expansion, or focused geographic and application specialization. The result is a landscape where scale, differentiation, and service capability each matter, and no single dimension is sufficient on its own.
Outlook: Three Trend Lines to Watch Through 2032
Compliance and specification intensity will keep rising
Dock levelers are increasingly specified as part of a broader safety and performance package rather than as standalone hardware. As standards and workplace safety expectations continue to sharpen, procurement processes are likely to place greater weight on certification alignment, testing documentation, and compatibility with dock safety systems. This favors manufacturers that can make compliance easy to verify and installers that can demonstrate consistent execution. The commercial implication is that equipment which can be presented as compliant by design will have stronger stickiness in repeat business and replacement cycles, while bare-minimum offerings may face growing pressure in specification-led environments.
Performance differentiation will shift toward total cost of ownership and uptime
As the market expands at a moderate pace, competitive advantage will depend less on headline price and more on uptime, serviceability, and durability over the installed life of the equipment. Energy interaction, mechanical reliability, ease of maintenance, and reduced downtime during installation or service will increasingly drive purchasing decisions, especially in high-utilization logistics and manufacturing environments. This trend opens room for products that balance hydraulic performance with practical installer and maintenance considerations, and for brands that can support facilities with reliable service networks and clear specification guidance.
Regional demand will remain uneven but strategically significant
While the largest absolute revenue contributions are expected from regions with advanced logistics infrastructure and substantial industrial activity, growth opportunities will differ by market maturity. In developed markets, replacement, modernization, and safety-driven retrofitting are likely to be important growth engines. In developing and industrializing regions, new facility construction and expanding distribution networks can support incremental demand, though pricing sensitivity and specification expectations may vary. Firms that can navigate these differences through appropriate product mix, local support, and application-specific positioning will be better placed to convert regional opportunity into durable revenue.
These trends are not risk-free. Regulatory interpretation can shift, and standards may evolve in ways that change specification requirements. Supply chain volatility in steel and fabricated components can affect cost structures and lead times, particularly if demand accelerates faster than capacity adjustments. In addition, the market's moderate concentration means competitive responses can be swift in price-sensitive segments, which can compress returns for manufacturers that fail to differentiate clearly. Operators should therefore treat growth as achievable but contingent on product clarity, compliance readiness, service capacity, and regional execution.
Actionable Guidance for Decision Makers
For manufacturers and brand leaders
- Strengthen specification support around recent product introductions by emphasizing installer features, certification alignment, and maintenance predictability, not just load capacity or product range.
- Invest in service and aftermarket capability as a differentiator, since uptime and response quality increasingly influence repeat specification in logistics and manufacturing environments.
- Develop clear product narratives for compliance and energy interaction where relevant, so that facilities can justify selection on safety, performance, and operating cost rather than initial purchase price alone.
For investors and strategic acquirers
- Focus on businesses with durable specification relationships, recurring replacement demand, and the ability to support compliance-led procurement rather than purely transactional hardware sales.
- Evaluate exposure to service revenue, retrofit activity, and regional installation ecosystems, since these often shape margin stability more than new-unit volume alone.
- Watch for consolidation patterns that could combine portfolio breadth, distribution reach, and service scale, especially where corporate ownership can accelerate cross-selling and operational efficiency.
For procurement and facility decision makers
- Treat dock leveler selection as part of a broader dock safety and operational-performance decision, coordinating with door systems, vehicle restraint strategies, and facility traffic design to reduce installation friction and improve long-term uptime.
- Use standards alignment and documented testing as a practical filter in specification, especially where safety programs, insurance expectations, or compliance responsibilities are significant.
- Balance acquisition cost against total cost of ownership by evaluating durability, maintenance requirements, installer support, and compatibility with existing dock infrastructure before finalizing specifications.
The market's next several years will reward participants who can connect product performance to operational outcomes, compliance expectations, and regional realities. Detailed segmentation data, company-level financial signals, regulatory timelines, and application-specific demand patterns can sharpen these decisions considerably, and that level of granularity is where a focused market study adds the most value. Readers looking for deeper breakdowns across product types, end users, regional dynamics, and competitive detail can use the insights here as a starting point for a more comprehensive review of the full report and supporting data.
For detailed analysis of this topic, please visit the official page: Dock Levelers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com