

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electric Fireplaces Market: Why 7.5% CAGR & $22 Billion Demand Reshape the Industry

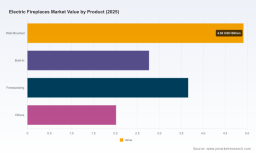
The Electric Fireplaces Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot: Growth Trajectory and Structural Realities
The electric fireplaces market has transitioned from a niche heating alternative to a mainstream design and comfort solution, with total industry revenue expanding from 8.98 billion USD in 2020 to an estimated 13.37 billion USD in 2025. The sector is projected to sustain a compound annual growth rate of 7.45 percent across the 2026 to 2032 horizon, reaching approximately 22.05 billion USD by the end of the forecast period. This acceleration is not merely a function of raw demand but reflects a maturation in product engineering, shifting consumer preferences toward low-emission home environments, and broader architectural trends that favor flexible, installation-light ambiance solutions.
Beneath the headline growth figures lies a market structure characterized by moderate fragmentation and steady competitive pressure. The industry operates with a measured degree of concentration, where the top three players collectively account for roughly 25.5 percent of revenue and the top five reach approximately 31.8 percent. This concentration pattern signals a landscape where scale advantages matter, but differentiation through technology, design, and channel strategy remains decisive. Incumbents have secured footholds through product ecosystems, while regional distribution networks and specialty retail partnerships continue to shape market access.
The current environment also presents distinct challenges that temper uninterrupted expansion. First, the market must navigate a complexity-heavy regulatory landscape, particularly around electrical safety certification and energy-efficiency expectations in key regions. Compliance requirements add cost and development time, especially for manufacturers expanding across jurisdictions with differing standards. Second, consumer expectations around realism and convenience have evolved rapidly. Early-generation LED flame effects and basic heating elements no longer satisfy buyers seeking multi-dimensional visuals, app-based control, and integration with broader smart-home environments. Firms that lag on experience design risk margin erosion as price-sensitive segments commoditize. Third, the market faces periodic tension between premium feature-rich offerings and the need for accessible price points in volume-driven channels. Balancing engineering sophistication with manufacturing efficiency will remain a persistent strategic test.
Core Drivers: What Is Powering the Next Phase of Growth
Technology Innovation as a Baseline Expectation
Product differentiation increasingly centers on how convincingly a unit replicates the visual depth and atmospheric effect of a traditional fireplace while maintaining energy efficiency and ease of installation. Recent product cycles have accelerated this trajectory. In October 2025, Modern Flames introduced the Orion v2 Virtual LCD Electric Fireplace, establishing a reference point for multi-dimensional flame technology that competitors are now pressured to match or extend. By February 2026, Escea broadened its holographic electric fireplace range, extending from compact configurations to full-wall installations up to two meters wide, reflecting the market's appetite for architectural-scale solutions. These developments underscore a shift from discrete appliance thinking toward integrated design elements that function as focal points in both new builds and retrofit projects.
Electric Blankets Market
The competitive implication is clear: visual quality, controllability, and modular form factors are becoming table stakes rather than optional enhancements. Manufacturers investing in proprietary flame rendering, layered lighting, and interchangeable cabinet styles are better positioned to defend pricing and build repeat purchase relationships across multiple property renovations or hospitality rollouts.
Regulatory and Standards Frameworks Reshaping Product Architecture
Regulatory direction is not simply a compliance burden; it is actively influencing product form factors and feature sets. In Europe, Ecodesign-type requirements are steering manufacturers toward electronic thermostats and open-window detection capabilities, thereby embedding efficiency logic into everyday operation. Across North America, adherence to UL 1278 and CSA C22.2 No. 46 standards governs evaluation of electric shock risk, fire hazards, insulation integrity, and mechanical stability, while CE marking and the EN 60335-1/EN 60335-2-30 framework set general household electrical safety expectations for products sold in the European Economic Area. These frameworks push firms to formalize testing protocols, document performance claims, and design for lower risk profiles.
For commercial strategy, regulatory alignment can become a differentiator when framed as assurance rather than obligation. Clear certification narratives, transparent energy-use characteristics, and demonstrable safety engineering help procurement teams, specifiers, and insurers reduce perceived risk. Companies that anticipate regional requirements early can avoid rework and accelerate time to market for cross-border rollouts.
Demand-Side Shifts Toward Low-Installation, High-Aesthetic Value
Demand patterns increasingly favor solutions that deliver ambiance and supplemental heat without the structural burden of gas lines, flue requirements, or major masonry work. Residential buyers are seeking room-scale comfort that complements existing decor, while commercial operators look for lobby, hospitality, and dining environments where fireplace presence can be installed with predictable lead times and lower on-site labor risk. This preference is especially relevant in urban housing where wall-cavity constraints and rental turnover make permanent installations less practical.
The result is a market that rewards flexibility in mounting style, finish options, and control interfaces. Products that support wall-mounted, built-in, and freestanding configurations within a coherent design language can better serve mixed customer bases. Additionally, the growth of short-term rentals, boutique hospitality, and refreshed commercial interiors creates incremental demand for repeatable, visually consistent installations that can be deployed across multiple sites.
Cost Structure and Supply Chain Considerations
Suppliers are balancing the cost of advanced display components, heating elements, and control electronics against the need for competitive pricing in volume channels. LED and LCD subassemblies, tempered glass, and smart-home connectivity modules all carry distinct cost and availability profiles. Firms that modularize core platforms can reuse enclosures, electronics architectures, and firmware across multiple product families, improving gross margins and reducing engineering duplication. At the same time, distribution dynamics matter: specialty retailers, e-commerce platforms, and trade specifier channels each demand different packaging, documentation, and service commitments. Companies that align supply planning with channel-specific expectations typically manage inventory risk more effectively and maintain stronger shelf and digital presence.
Competitive Landscape: Positioning, Differentiation, and Evolution
The market's mid-concentration structure allows both scale players and design-focused specialists to thrive, provided they hold a clear strategic position. Modern Flames has built recognition around virtual LCD flame technology and a broad catalog spanning Orion, Redstone, Spectrum, and Landscape Pro series, with app-based control and realistic effects anchoring its value proposition. Its October 2025 launch of the Orion v2 signals a focus on raising the visual benchmark and sustaining a technology-forward narrative. Amantii emphasizes holographic and multi-view flame technologies, extending into contemporary wall-mount and heater offerings; its participation at HPBExpo 2026 in New Orleans with Signature MultiView Holo and other design-forward models illustrates a channel and audience strategy aimed at specification-driven buyers and design-conscious retailers.
Touchstone Home Products has expanded its footprint through recessed, insert, wall-mount, linear, and three-sided smart electric fireplaces that integrate with Alexa and Google ecosystems. Its approach reflects a pragmatic balance between installation variety and smart-home readiness, appealing to buyers who want integration without sacrificing flexibility. SimpliFire contributes a modern and traditional portfolio featuring Digital Spark technology and outdoor-capable series, demonstrating that weather-resistant or seasonal-use designs can open adjacent demand pools. Dimplex, often recognized as a North American leader in electric fireplaces and heaters, maintains breadth across lines such as Revillusion, Ignite Aspire, and water vapor models, leveraging scale and multi-technology depth to address both residential and commercial applications. Napoleon rounds out the competitive set with electric fireplace inserts, built-ins, and linear models including Element and Luminex series, targeting clean, contemporary installations that suit specifiers seeking integrated architectural looks.
Electric Fan Market
Strategically, the leading firms are pursuing differentiation along three intersecting axes. The first is visual authenticity and technological novelty, where advanced flame rendering and holographic-style effects justify premium positioning. The second is installation and format versatility, allowing a single brand to address retrofit, new-build, and commercial use cases without fragmenting the brand identity. The third is ecosystem integration, where app control, voice assistant compatibility, and programmable modes transform a fireplace from a static appliance into an adaptable room system. Companies that combine two or more of these strengths tend to achieve stronger margin profiles and greater resilience when one demand channel softens.
Looking ahead, the competitive structure is likely to evolve through selective consolidation, channel partnerships, and deliberate entry by firms with adjacent competencies in lighting, heating, or smart-home integration. Pure price-based entry will remain challenging given certification costs and the difficulty of matching visual quality at scale. Instead, new entrants will probably appear through niche formats, regional distribution advantages, or targeted partnerships with fixture and interior brands. Incumbents that strengthen service networks, expand finish libraries, and keep firmware upgrade paths open will be better placed to retain specifier and repeat buyer loyalty.
Outlook 2026 to 2032: Three Strategic Trends to Watch
First, the market will increasingly treat electric fireplaces as part of a broader interior systems category rather than a standalone heating accessory. This means closer convergence with architectural lighting, room control platforms, and modular wall systems. Opportunities will arise for bundled specification packages in hospitality and multi-unit residential projects, where standardized visuals and control logic reduce installation complexity and improve consistency across locations. The commercial upside is meaningful: repeat deployment across sites can create predictable revenue streams and strengthen relationships with design firms and general contractors.
Second, advanced visual technologies will continue to diffuse from premium tiers into mid-range products, gradually resetting baseline expectations. Holographic-style rendering, layered flame effects, and refined color-temperature control are likely to become more widely available as component costs stabilize and manufacturing processes mature. For manufacturers, the strategic task is to introduce tiered feature sets that preserve premium margins while expanding addressable volume. For buyers, the opportunity lies in selecting platforms with upgradeable control electronics and accessory compatibility, enabling room designs to evolve over time without full replacement.
Third, regional regulatory divergence will increasingly shape product roadmaps and geographic rollout priorities. European efficiency-oriented features, North American safety certification norms, and varying marking requirements across additional jurisdictions will encourage more modular compliance strategies. Firms that build adaptable internal architectures and maintain clear documentation trails can expand faster with lower rework risk. The corresponding uncertainty is that regulatory shifts or new energy policy instruments may alter relative attractiveness across regions, making near-term investment timing and channel selection more sensitive to local policy signals.
PW Consulting Health Care Research Center
Actionable Guidance for Decision Makers
For Manufacturers and Brand Owners
- Treat platform modularity as a strategic asset. Designing shared electronics, enclosure options, and software layers across wall-mounted, built-in, and freestanding variants can reduce development cost, accelerate line extensions, and improve margin consistency.
- Invest in visual and control differentiation that can be communicated to specifiers and consumers. Certifications and safety narratives should be presented as trust signals that support premium positioning rather than as minimum obligations.
- Plan channel strategy around customer job-to-be-done. Specialty retail, e-commerce, and trade specification channels require different packaging, documentation, and service levels; aligning supply and marketing to each channel improves cash efficiency and brand coherence.
For Investors and Capital Allocators
- Evaluate exposure not only by unit volume but by the durability of technological and design moats. Companies with proprietary flame-rendering methods, modular platforms, and strong smart-home integration typically have better pricing power and repeat purchase potential.
- Monitor regulatory readiness as a quality indicator. Firms with well-documented certification processes and adaptable compliance architectures are better positioned to expand across regions without unexpected delays or cost overruns.
- Seek segments where installation-light, high-aesthetic solutions align with structural demand, such as hospitality refresh cycles, urban residential retrofits, and multi-site commercial interiors. These contexts can support recurring procurement relationships rather than one-off transactions.
For Procurement Teams, Specifiers, and Channel Partners
- Prioritize platforms that balance visual goals with serviceability and upgrade paths. Selection criteria should include control ecosystem compatibility, finish flexibility, and the supplier's ability to support multiple installation types within consistent design language.
- Use certification and efficiency documentation to streamline specification and reduce downstream risk. Clear standards compliance and transparent operating characteristics help align procurement, facilities, and design stakeholders.
- Engage early with suppliers on multi-site or program-based deployments. Coordinating finish options, control settings, and installation requirements in advance can reduce on-site variability and improve portfolio-wide consistency.
The electric fireplaces market is moving into a phase where technology maturity, regulatory alignment, and design integration jointly determine competitive outcomes. For organizations operating in or adjacent to this space, timely and granular intelligence on product roadmaps, regional requirements, and channel dynamics can materially improve investment timing and resource allocation. Detailed segmentation data, company-level profiles, and region-specific trend analysis can support more precise planning and scenario evaluation. For that level of coverage, including deeper breakdowns of format, application, and regional dynamics, interested readers can consult the full PW Consulting market report and related advisory materials.
For detailed analysis of this topic, please visit the official page: Electric Fireplaces Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com